Bay Area Market

Greater Bay Area market update

 
The Big Story
Quick Take:
  • Affordability remains a concern across the country despite lower interest rates compared to this time last year.
  • New homes are being added to the market, with the US seeing a 4.21% year-over-year increase in the number of new listings in February.
  • Inventory is getting back to healthier levels as we see backlogs begin to build across the country.
 
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
 
 
Affordability continues to be an issue nationwide
One of the headline issues in the real estate industry over the past few years has been, of course, the affordability (or rather the unaffordability) of homes. Unfortunately for new buyers, and more specifically first time home-buyers, this issue looks like it will persist throughout 2025. Mortgage rates remain comparatively high, and home prices largely have not given back their pandemic-era gains.
 
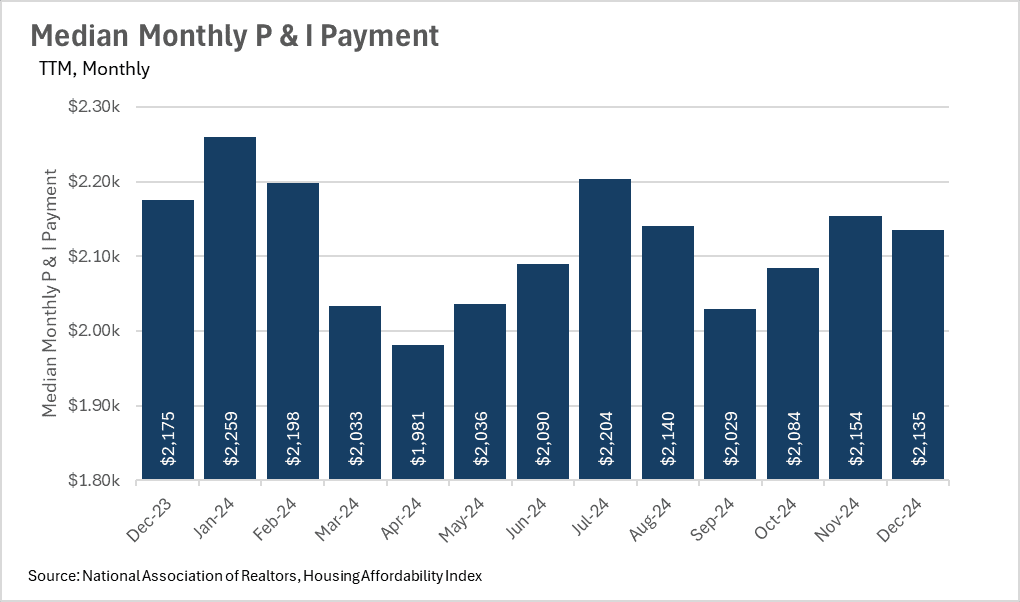
This has, of course, made the dreams of homeownership difficult to achieve for countless people around the country. With the median monthly principal and interest payment exceeding $2,100 per month on a nationwide level, people are struggling to afford the purchase of a new home!
New homes are starting to hit the market again
Fortunately for the market, there are plenty of new homes hitting the market though. While there are countless people sitting on the sidelines, waiting for lower interest rates to sell their current home and buy a new one, some of these holdouts are giving up and listing their homes. The writing seems to be on the wall, meaning more and more people are giving up on the thought that we will see lower interest rates in the short term, causing them to list their homes.
 
This has resulted in a pleasant jump in new home listings, despite us being at the tail end of the slow season. In the month of february, we saw more than 353,000 homes hit the market nationwide. This represents a 4.21% increase on a year-over-year basis, and an 8.15% increase on a month-over-month basis!
Inventories are beginning to build, offering more options for buyers
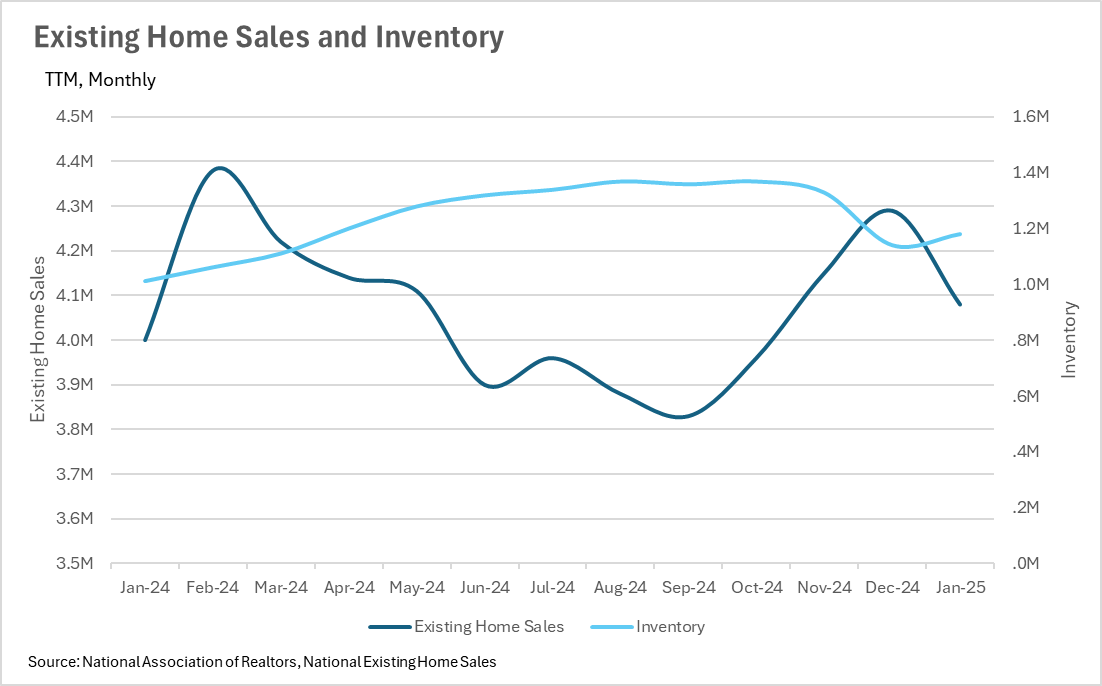
Since we are seeing new inventory hit the market and a steady level of demand, this is causing inventories to build, which is a great sign for those looking to enter the market! In the month of January, there were 1,180,000 homes listed on the market, representing a 16.83% increase on a year-over-year basis and a 3.51% increase on a month-over-month basis. At the same time, we’re seeing demand stagnate a bit, with 4,080,000 homes sold in January, representing a 2% increase when compared to last year and a 4.9% decrease when compared to last month!
 
Although a top-tier property will likely end up in a bidding war, no matter if it’s in Kansas City or Calabasas, this increase in inventory could mean that there are some deals to be had on listings that sit on the market for a few weeks.
 
While there are areas that deviate from the national trends, this is generally what's happening nationwide. Below, you'll find a local lowdown that provides you with the in-depth coverage of your area that you need. We will continue to monitor the housing market and overall economy to help guide you in buying or selling your home.
Big Story Data
Line chart compares existing home sales and inventory monthly from January 2024 through January 2025.
Line chart of Federal Reserve mortgage-backed securities holdings, peaking near $2.7 trillion in 2022.
Bar chart of monthly median principal and interest payments, peaking at $2,259 in January 2024 and ending at $2,135 in December.
Chart of monthly median home sale prices and 30-year mortgage rates, January 2024 to January 2025.
Line chart of monthly U.S. new listings from 2018 to 2025, with recurring peaks and sharp seasonal declines.
The Local Lowdown
Quick Take:
  • Silicon Valley continues to experience strong price growth, while East Bay home prices have stagnated due to rising inventory.
  • Inventory shortages persist in the North Bay, while San Francisco faces declining listings, particularly in the single-family home market.
  • Single-family homes remain in high demand across the region, but condos in many areas are seeing weaker competition.
  • Sellers maintain an advantage in most markets, though buyers have opportunities in Napa and San Francisco’s condo market.
 
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Silicon Valley and North Bay See Price Growth, While East Bay Stalls
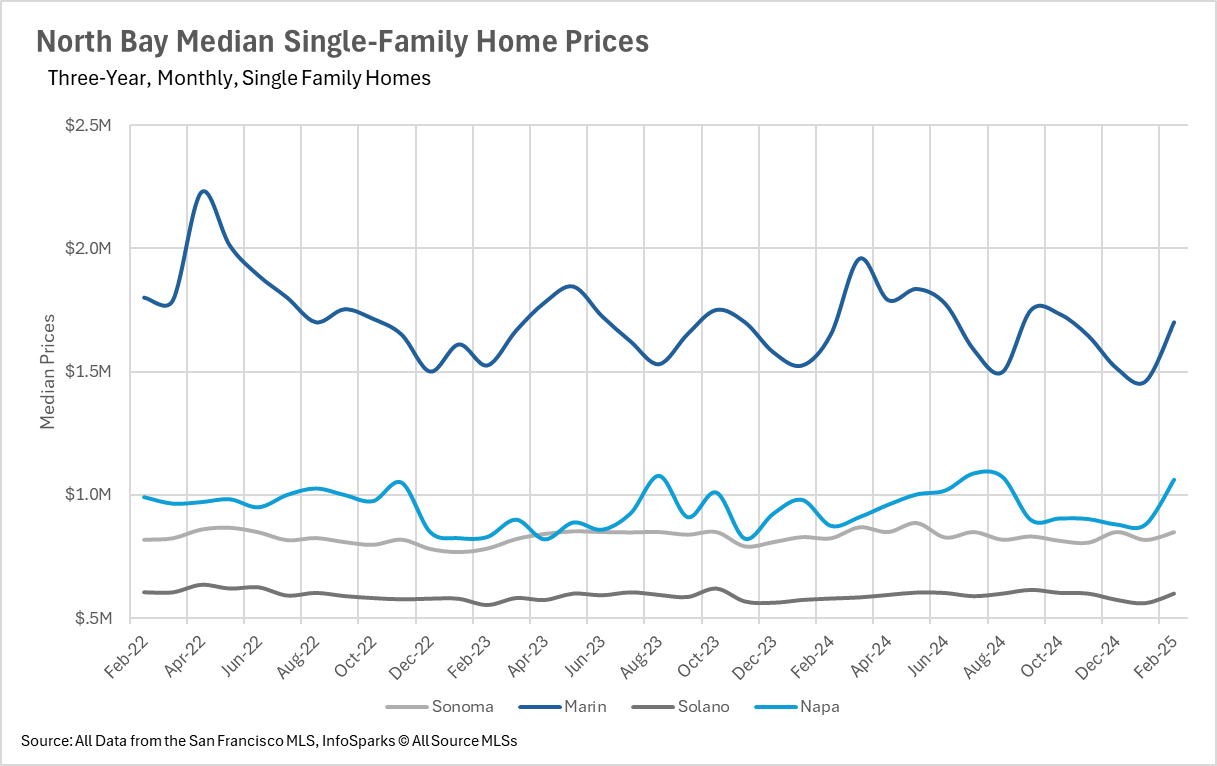
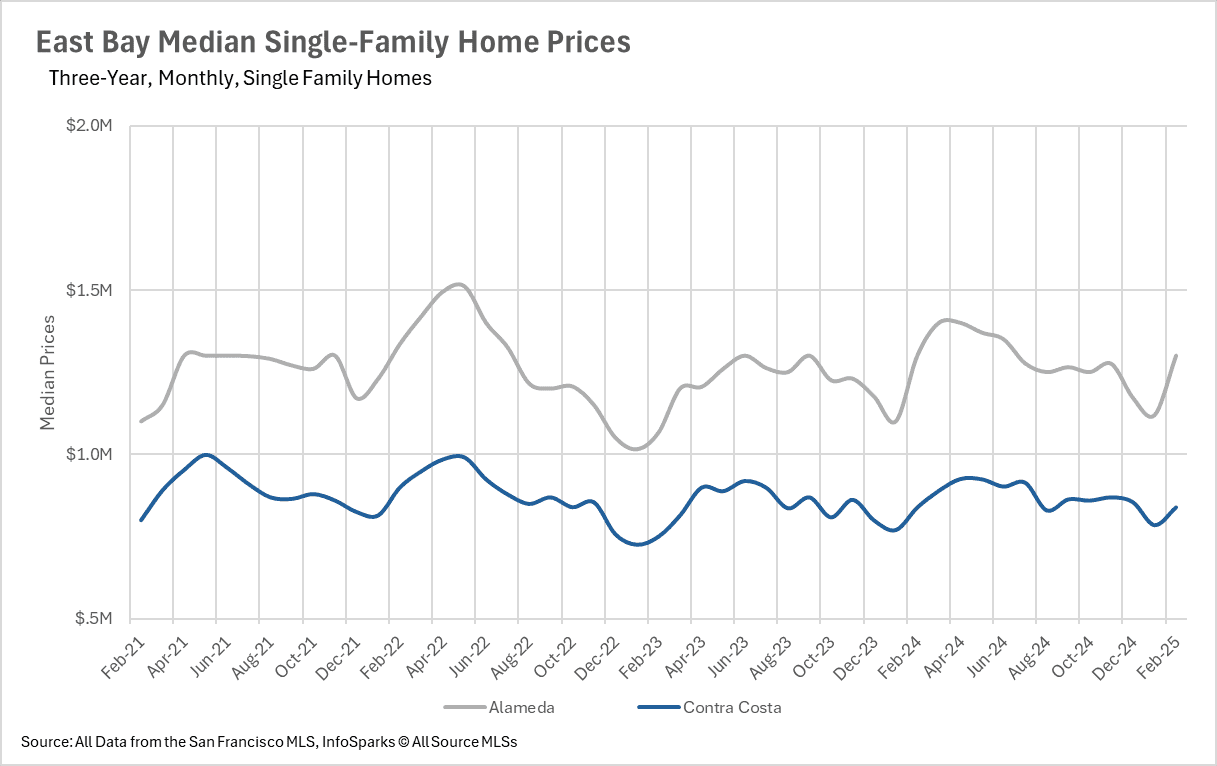
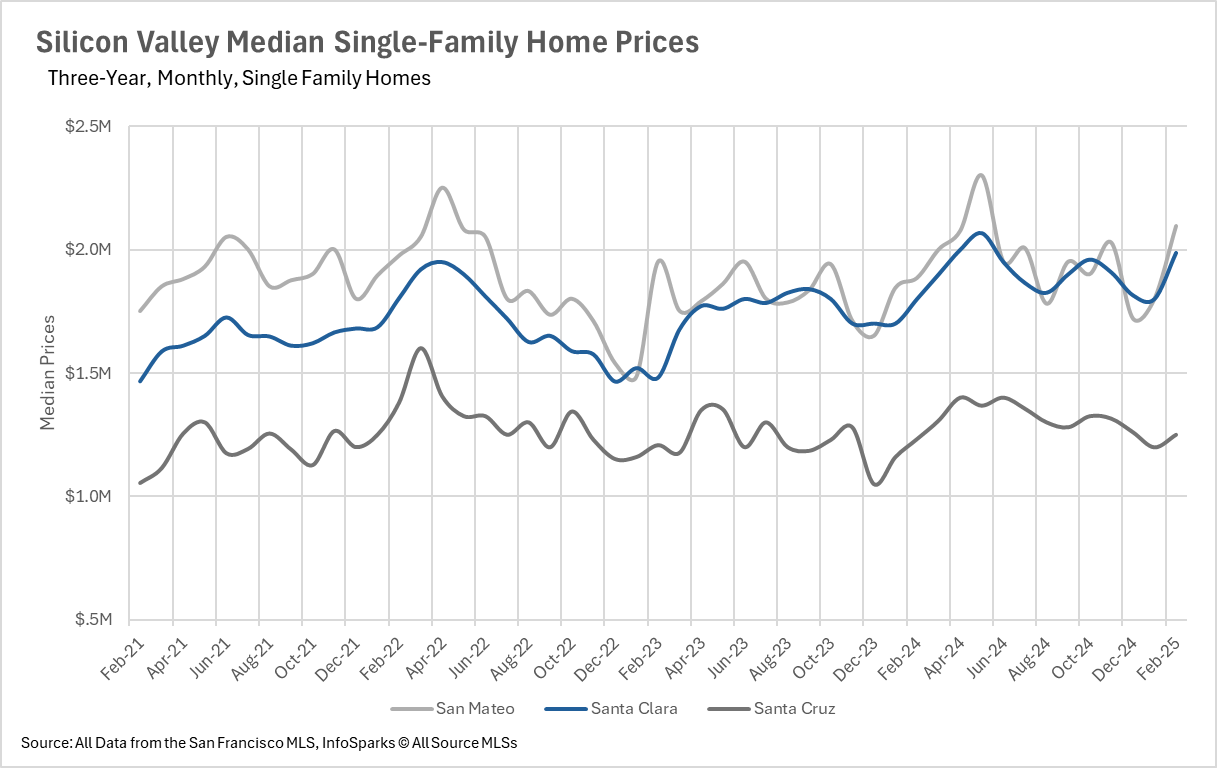
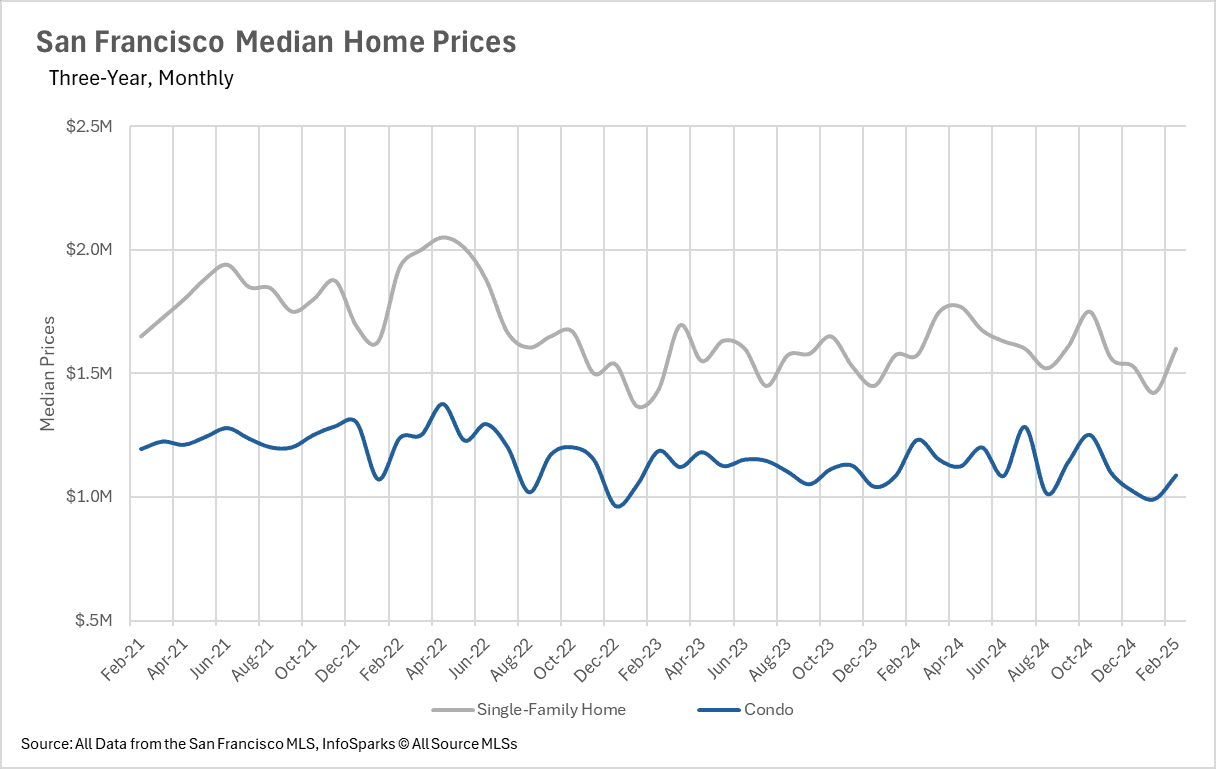
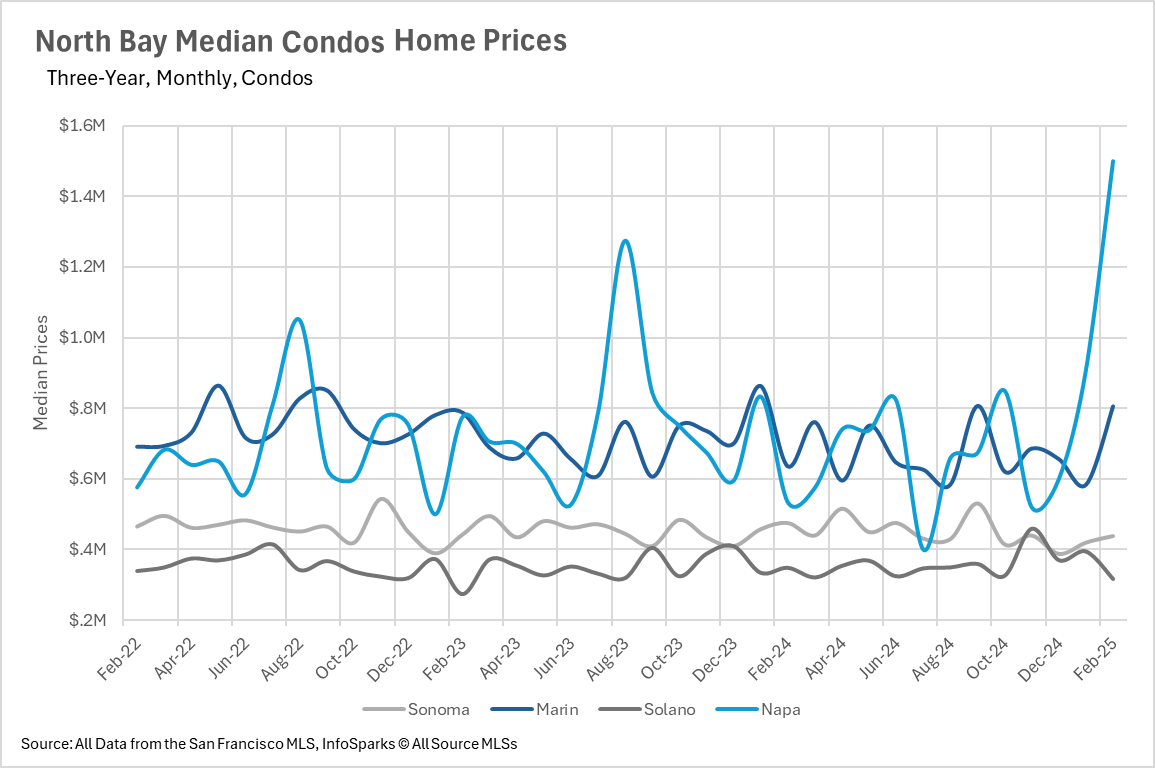
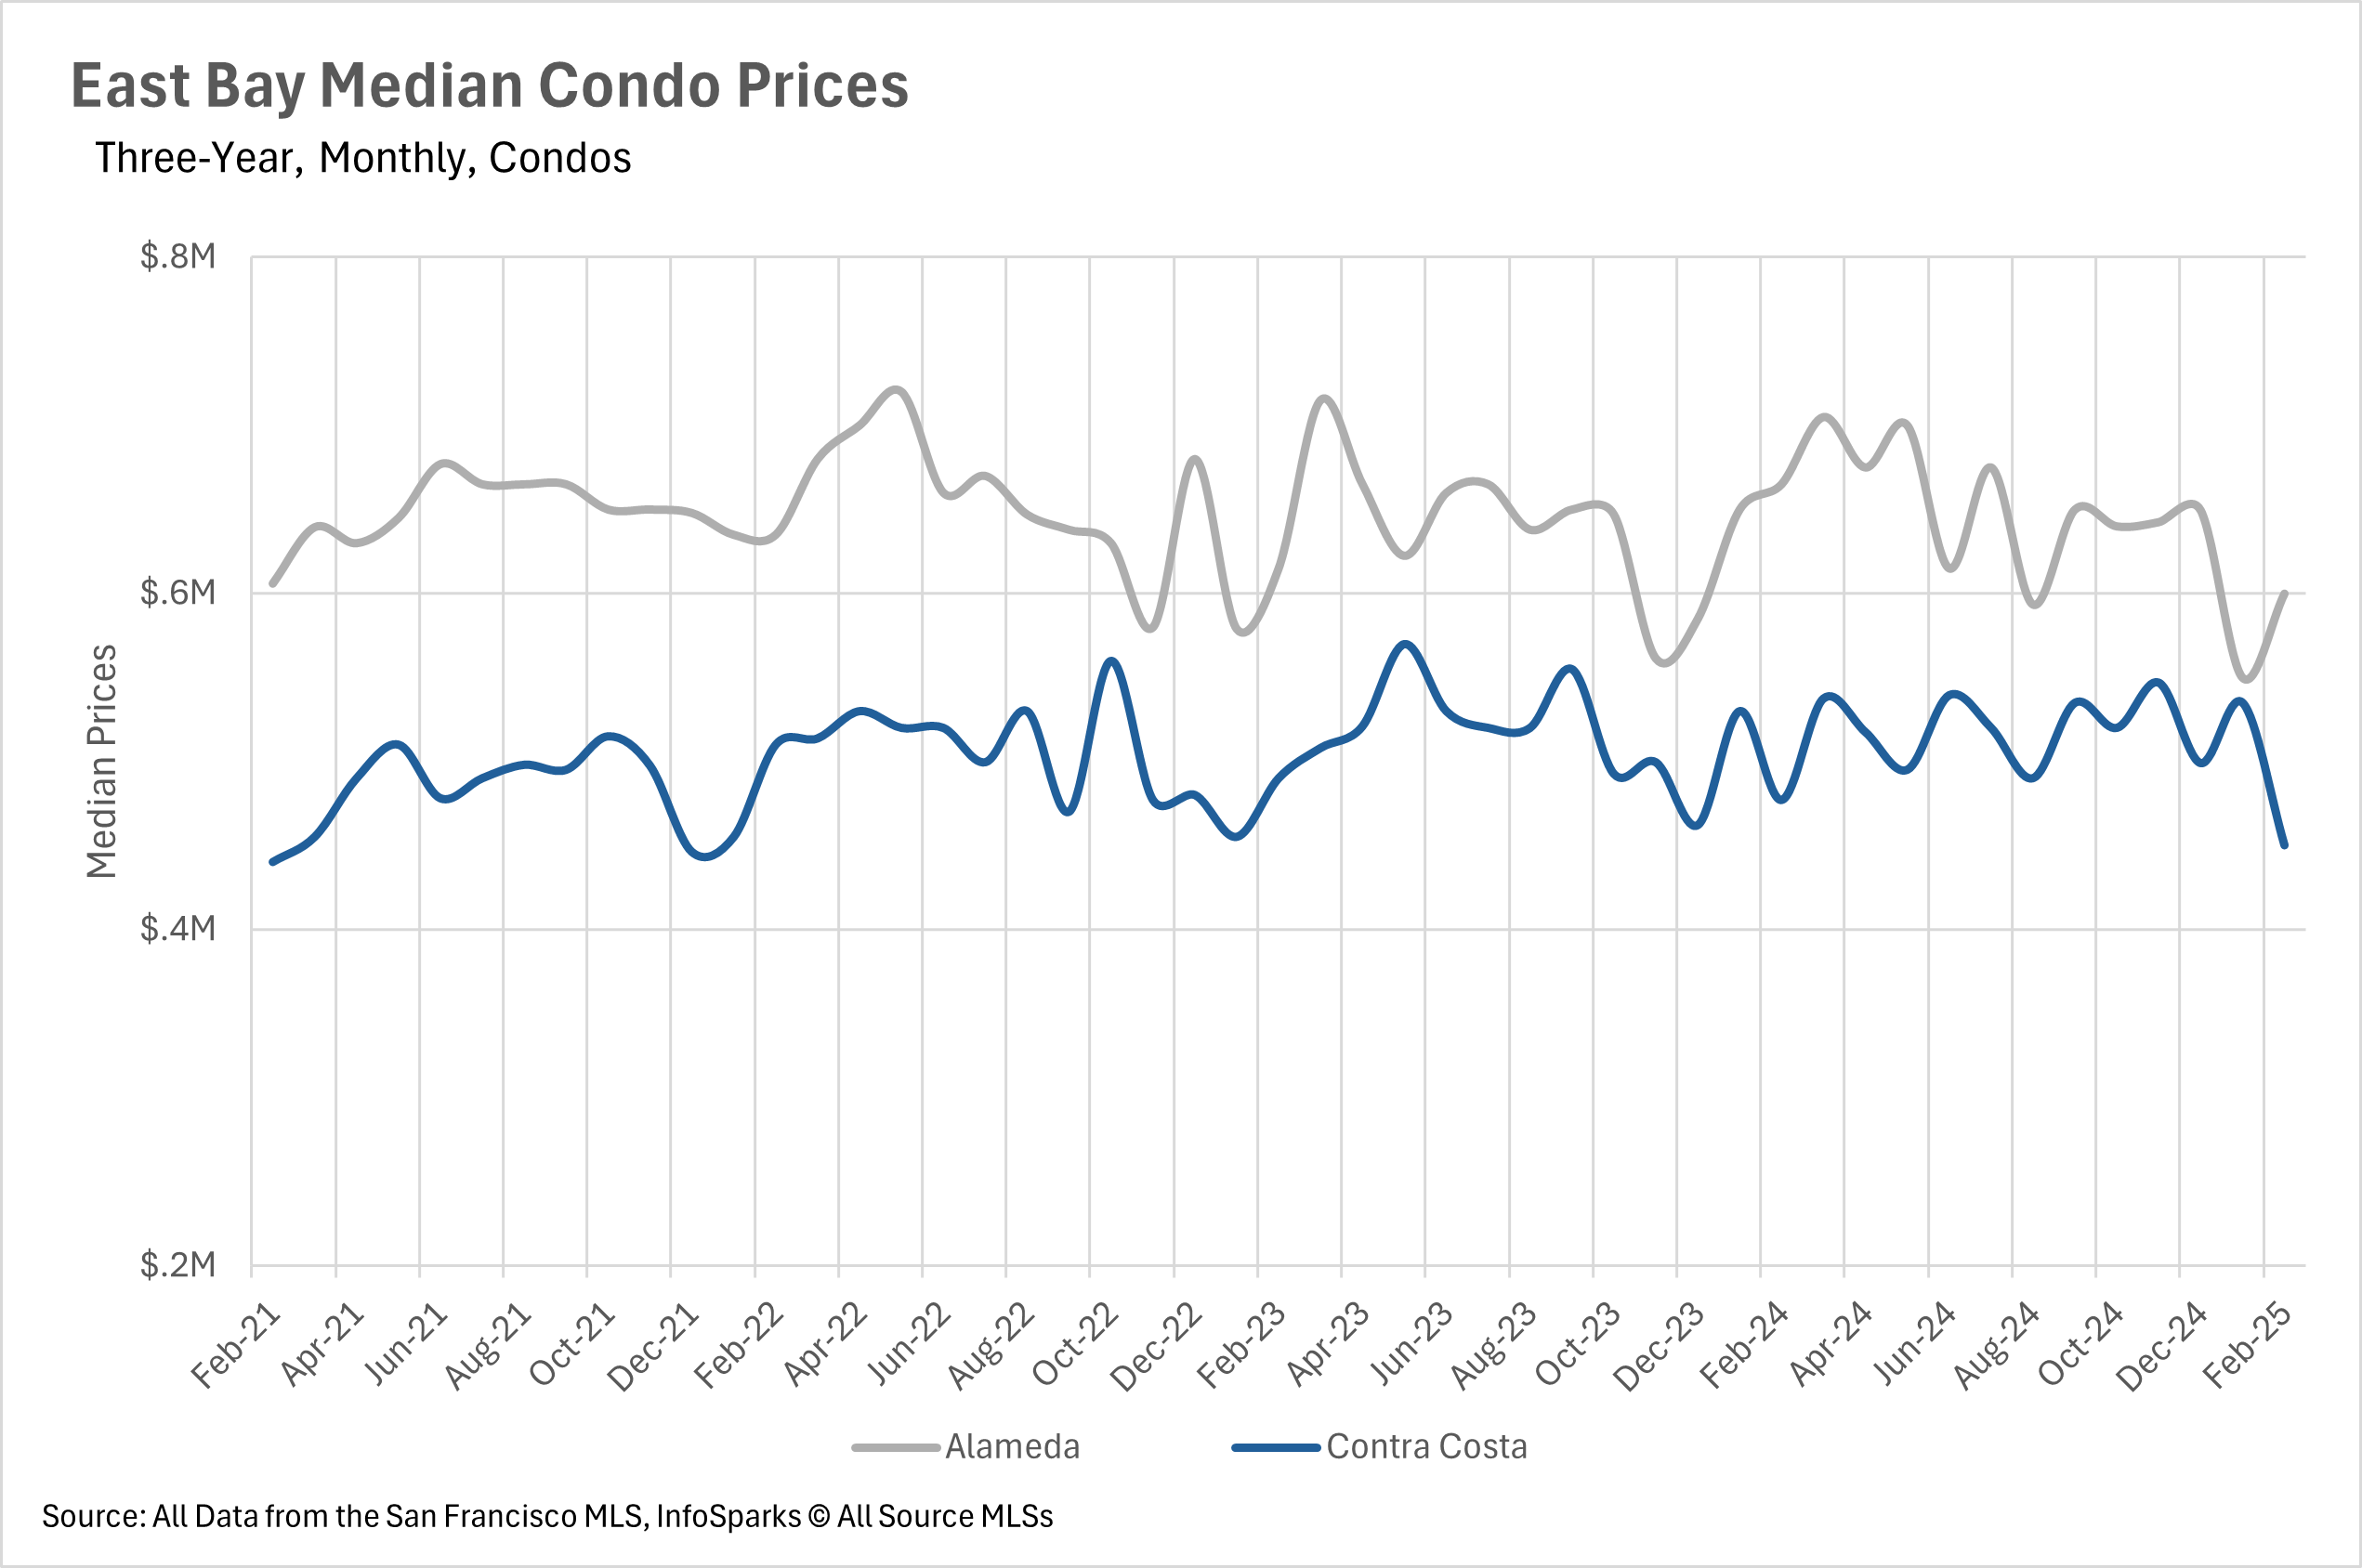
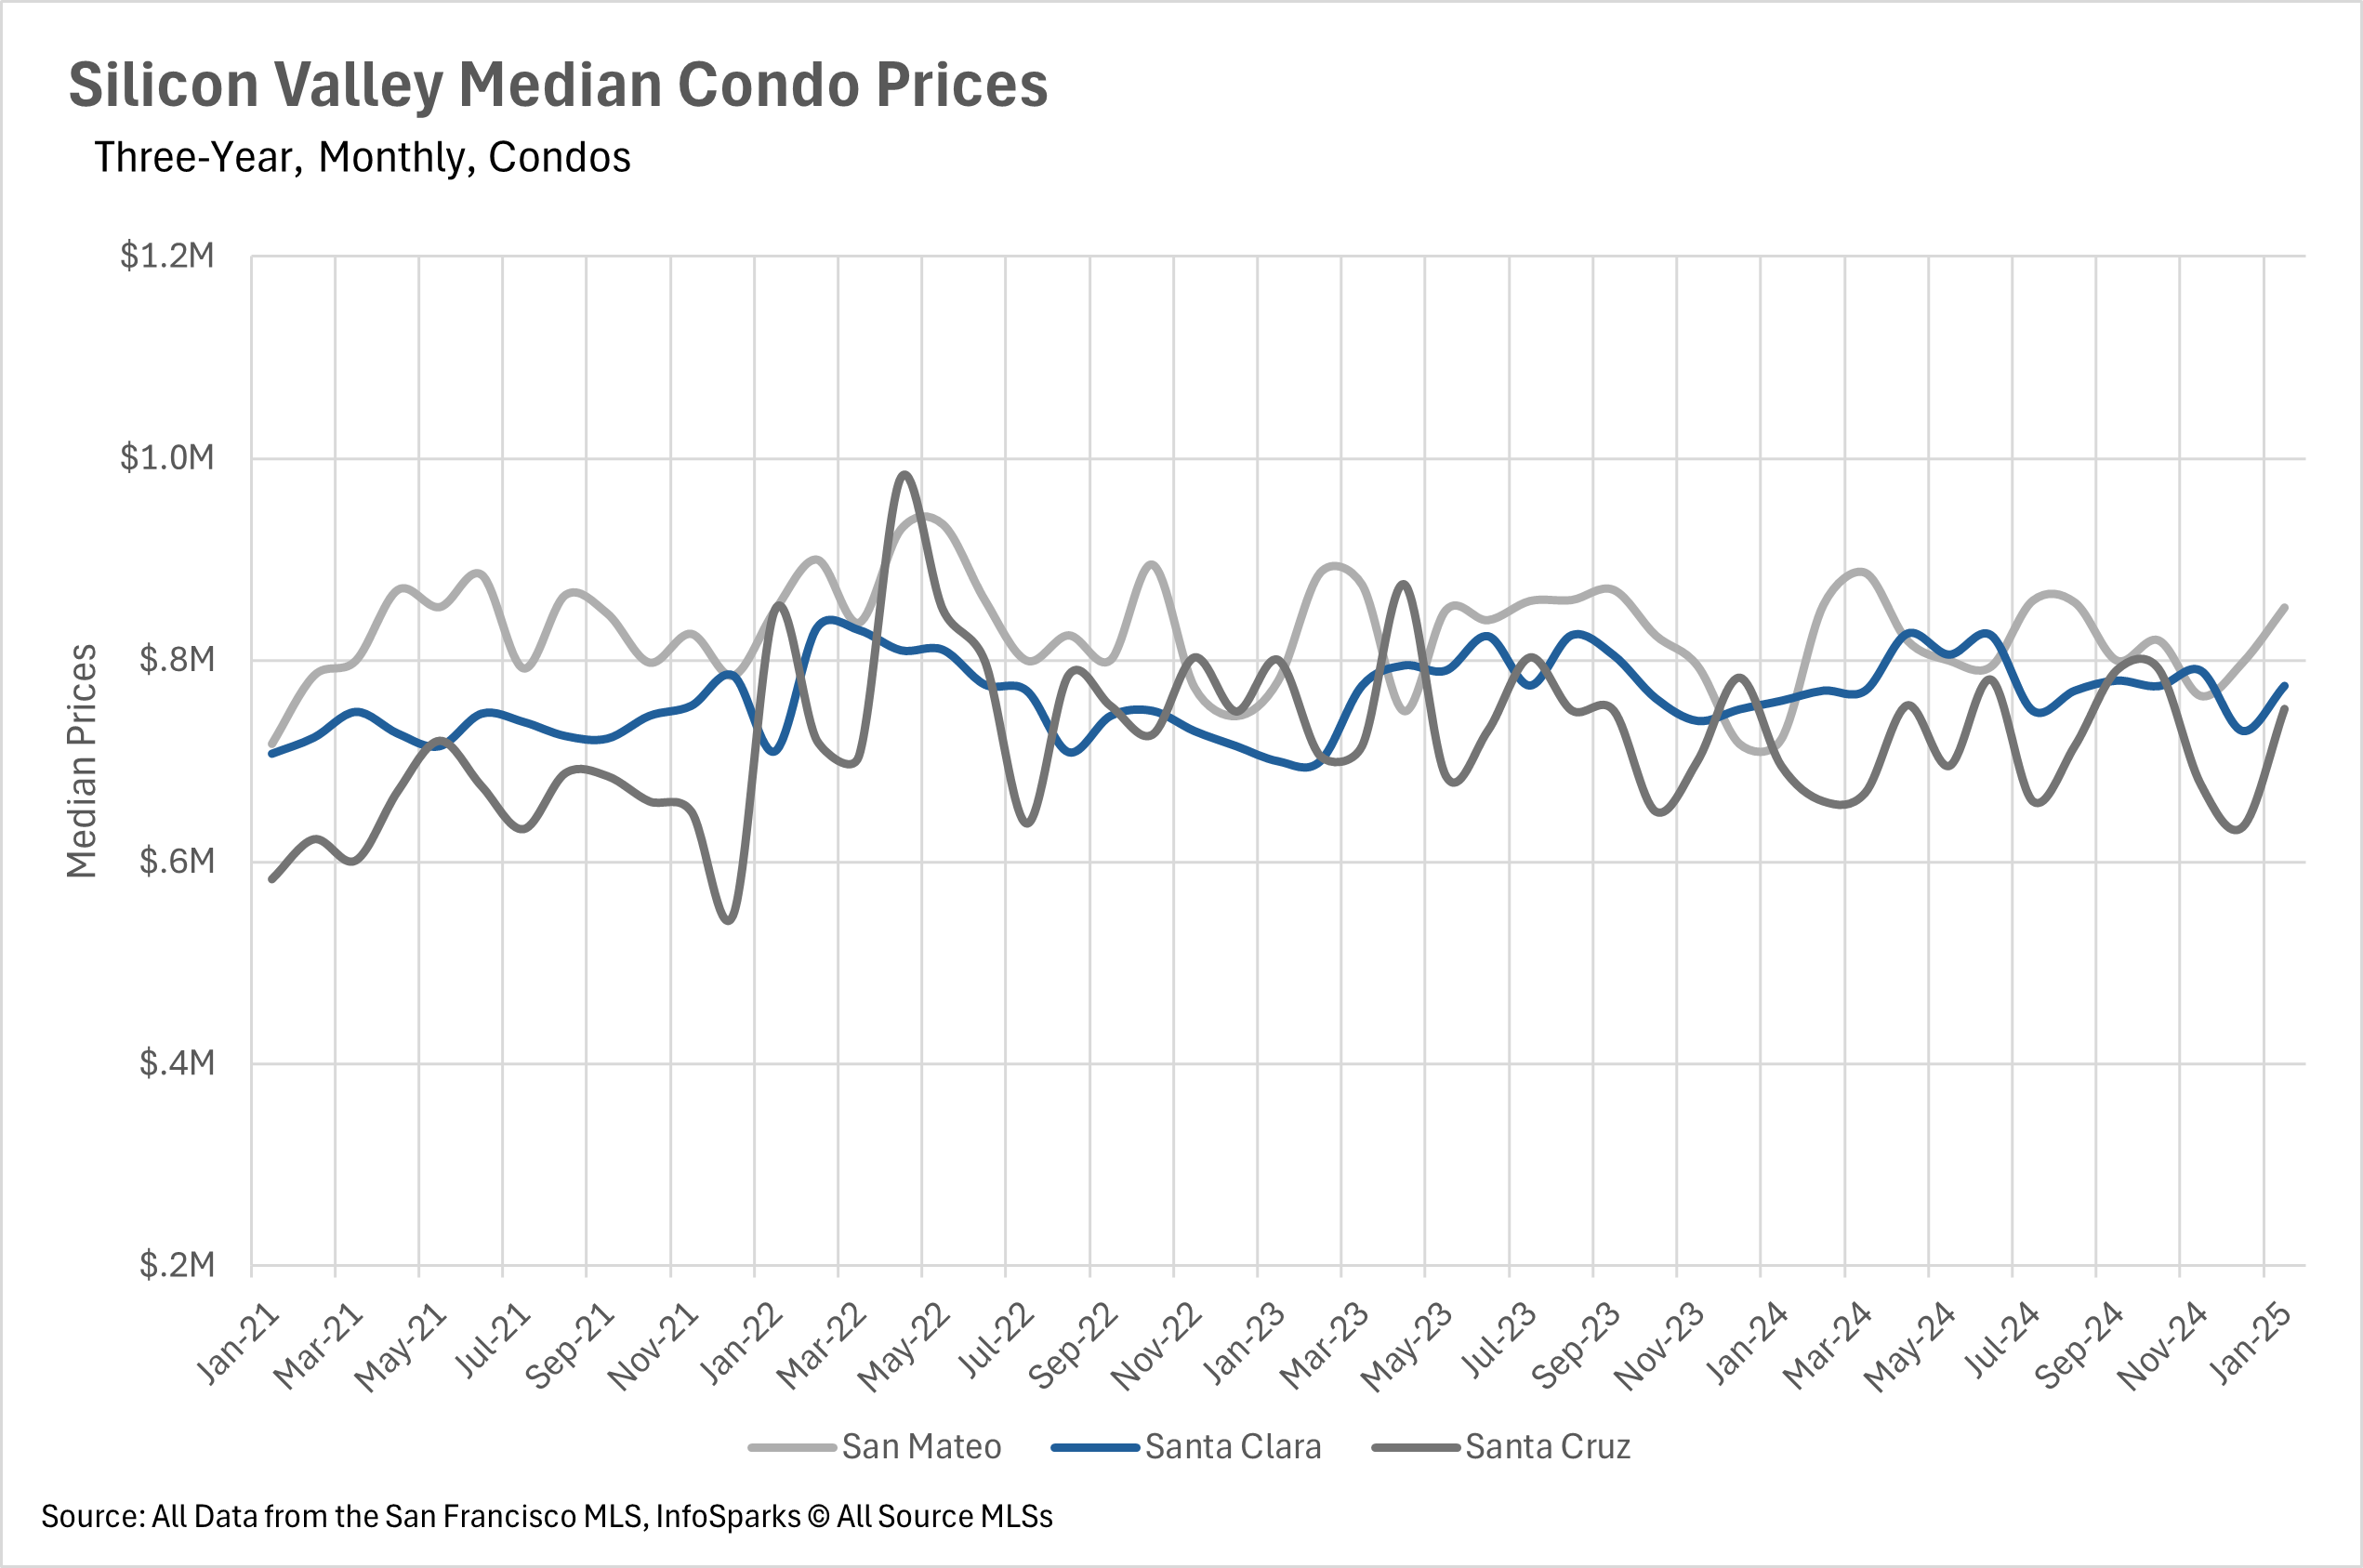
The Bay Area real estate market is showing clear contrasts between its regions. Silicon Valley remains one of the strongest markets, with median sale prices in San Mateo and Santa Clara counties rising over 10% year-over-year. North Bay also experienced price appreciation, with Napa County standing out at over 21% growth. However, the East Bay market is leveling off due to a surge in inventory, and while single-family home prices have held steady, condos have taken a notable dip. Meanwhile, San Francisco’s home prices continue to fluctuate around their two-year average, as inventory levels and demand move in sync.
Inventory Trends Vary Across the Bay Area
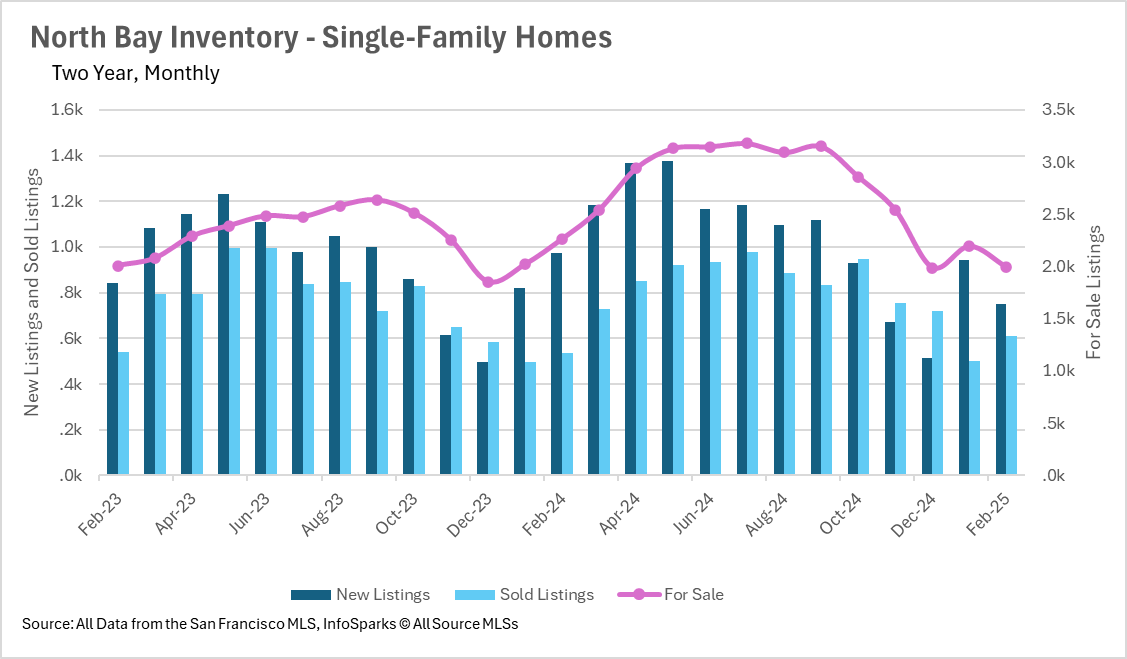
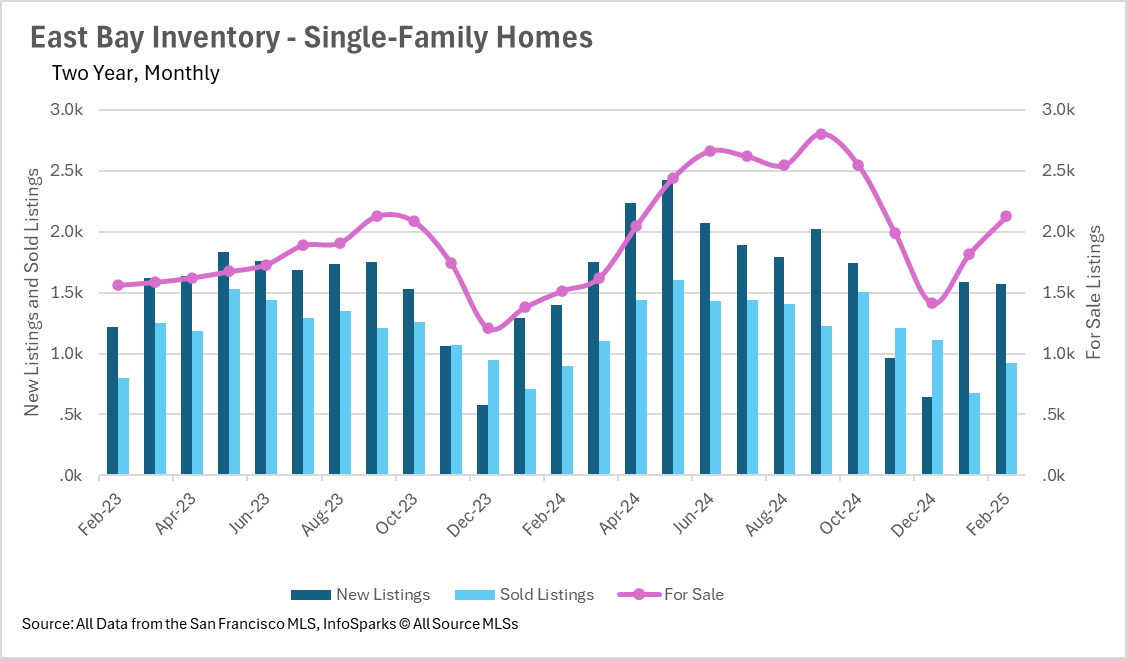
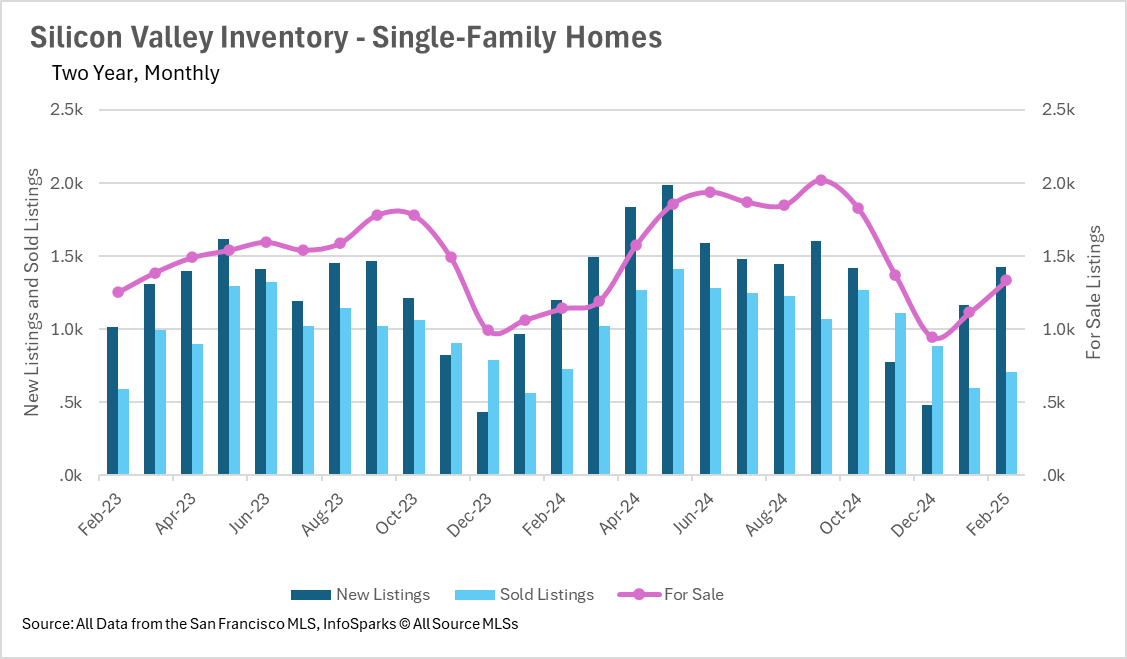
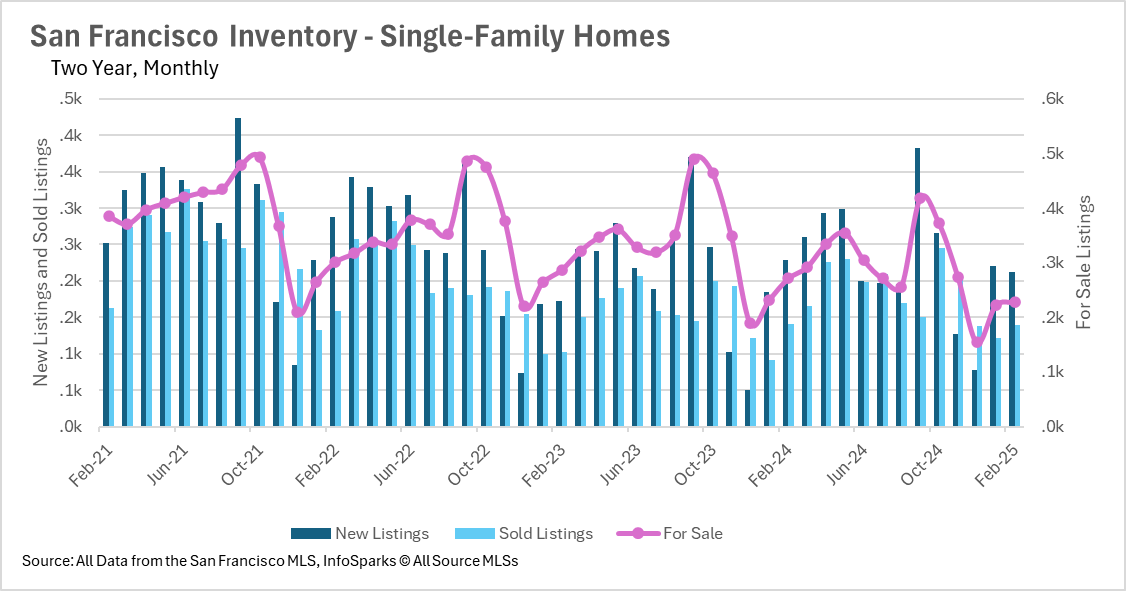
Inventory trends across the Bay Area are mixed. Silicon Valley saw a significant increase in available listings, with active inventory rising more than 16% compared to last year. The East Bay experienced an even more dramatic shift, with inventory up 40% year-over-year. In contrast, the North Bay is facing a supply shortage, with single-family home listings down over 12% annually, leading to continued competition among buyers. San Francisco presents a unique challenge, as its inventory continues to shrink, particularly in the single-family home market, where listings declined nearly 16% over the past year.
Homes Are Selling Quickly—But Not Everywhere
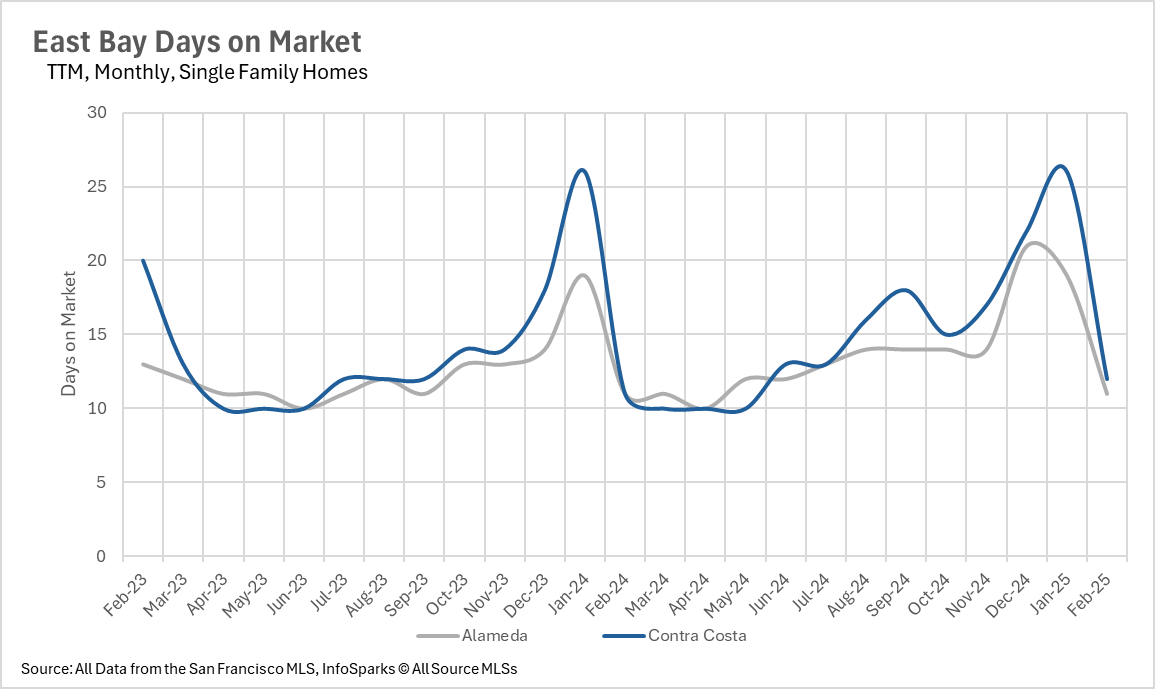
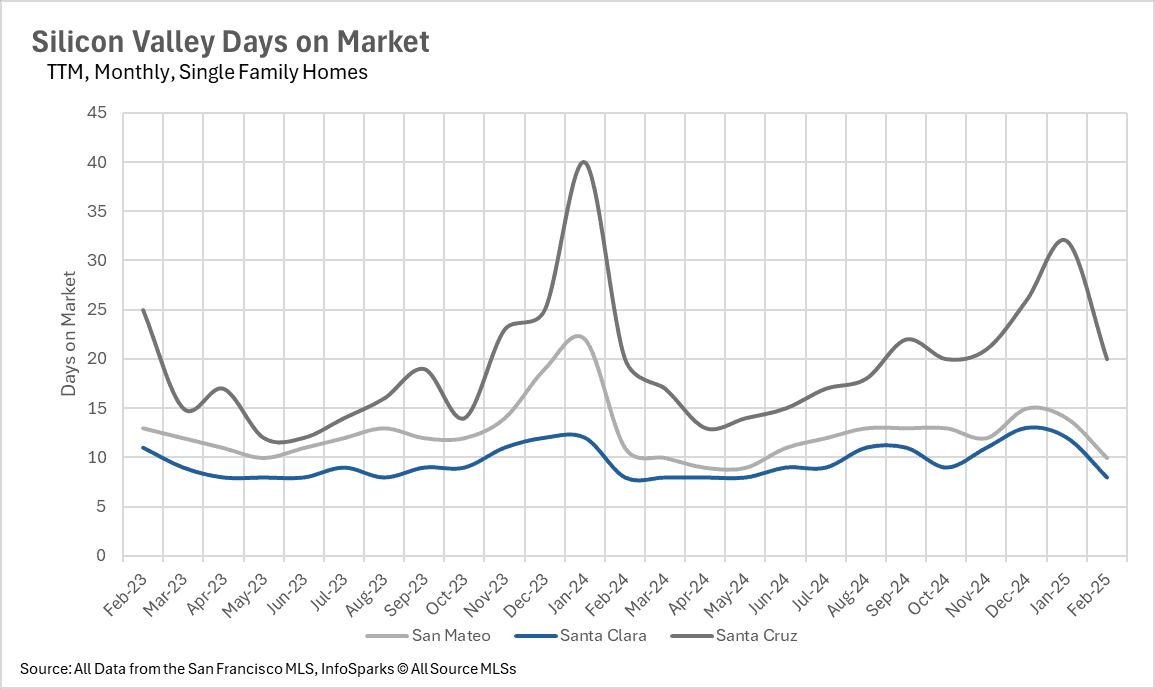
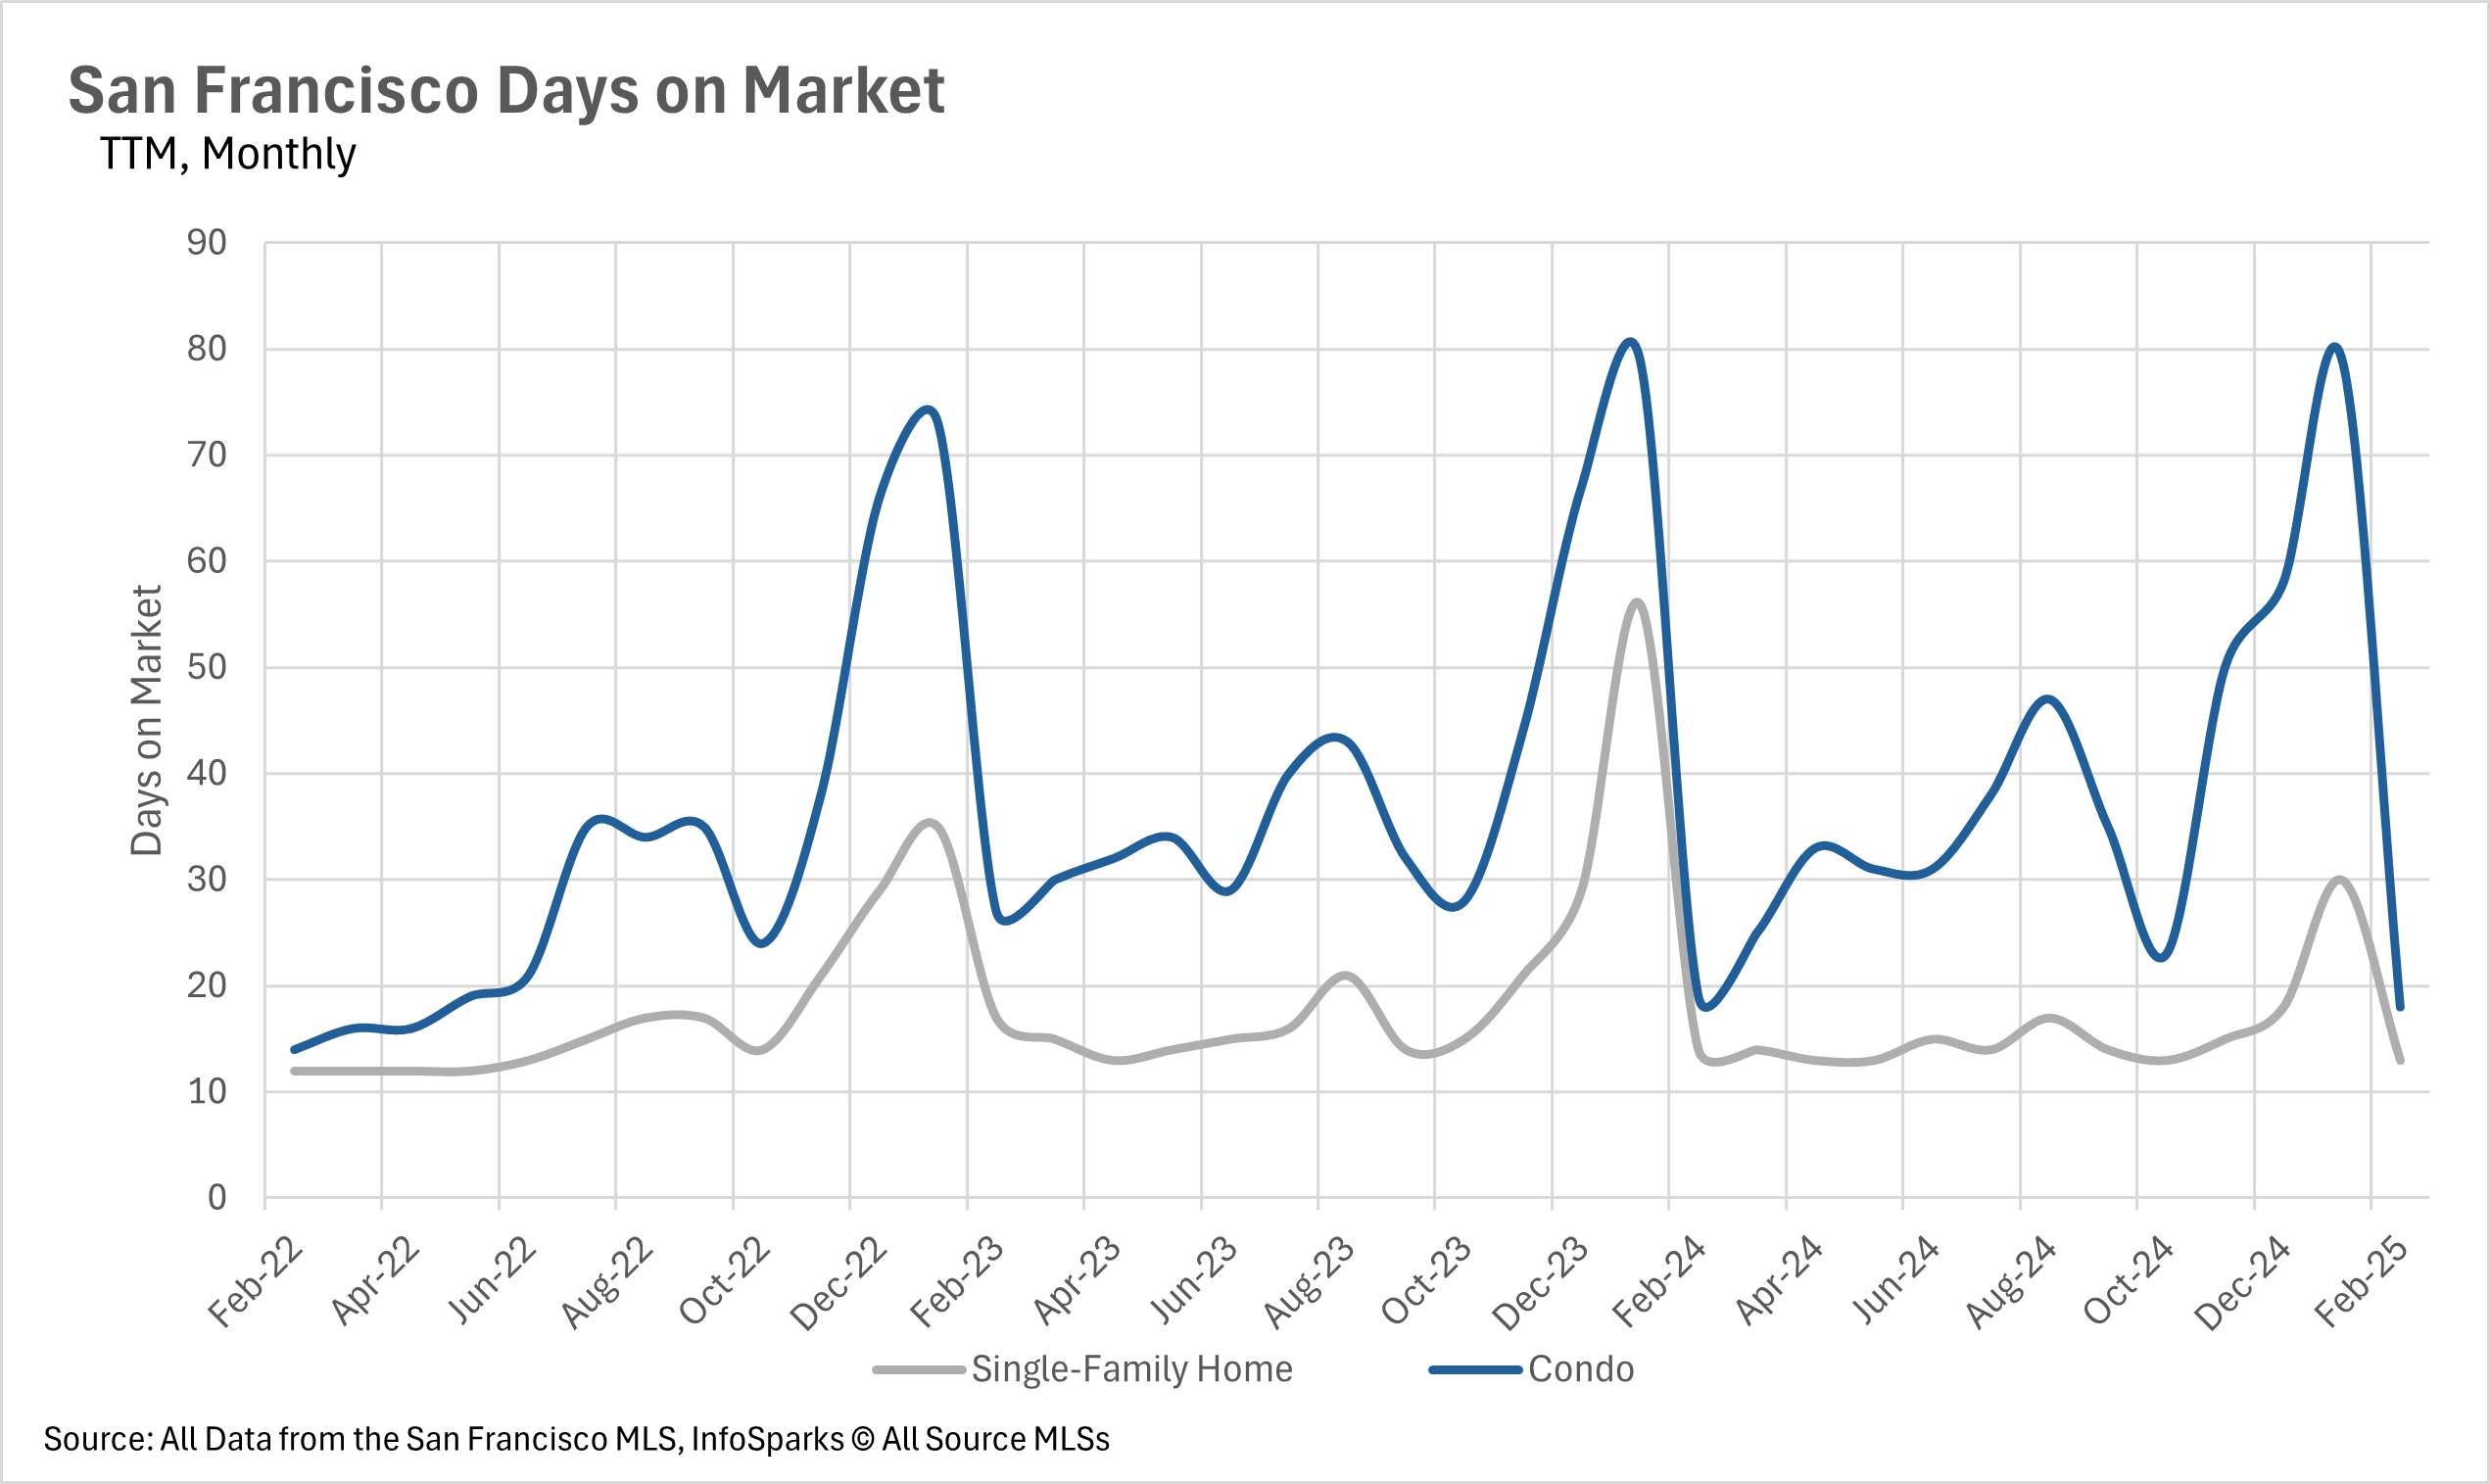
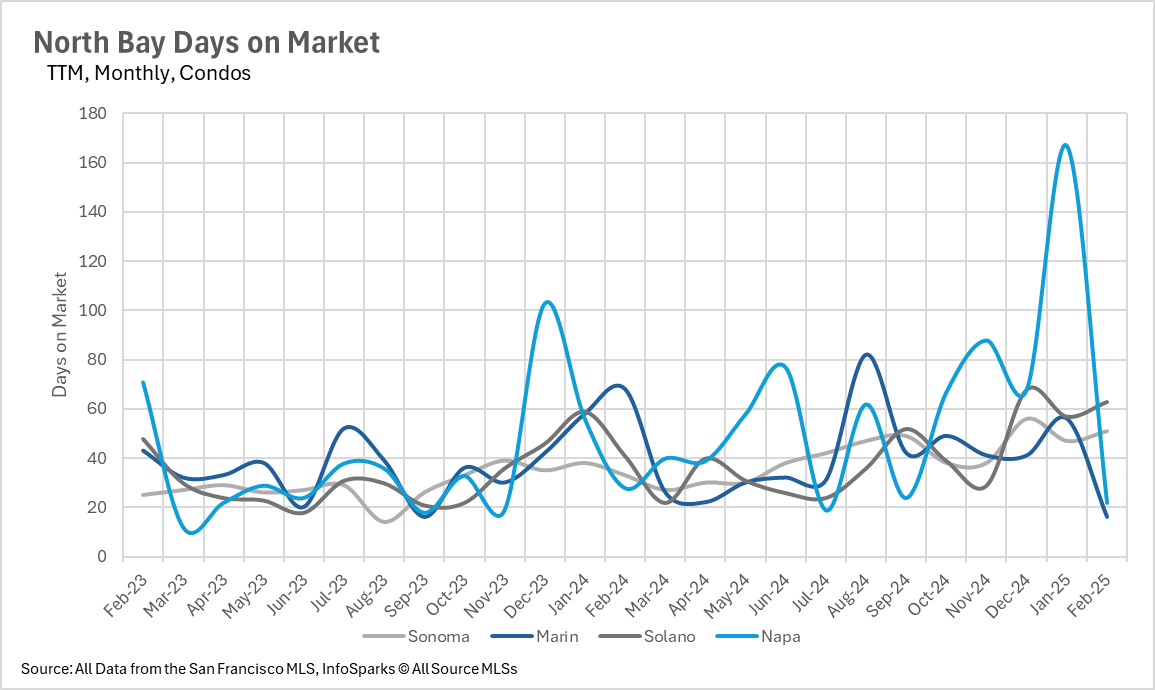
Despite varying inventory trends, homes in many parts of the Bay Area continue to sell quickly. In Silicon Valley, the average listing in Santa Clara County lasts just 8 days on the market, showing intense demand. Even in the East Bay, where inventory has surged, homes are still moving at a steady pace. The North Bay also remains highly competitive, with listings spending fewer days on the market in most counties—except for Napa, where homes are taking nearly twice as long to sell compared to last year. San Francisco remains split, as single-family homes sell at a premium, while condos linger longer on the market.
Seller’s Market Holds Firm, Except in Select Areas
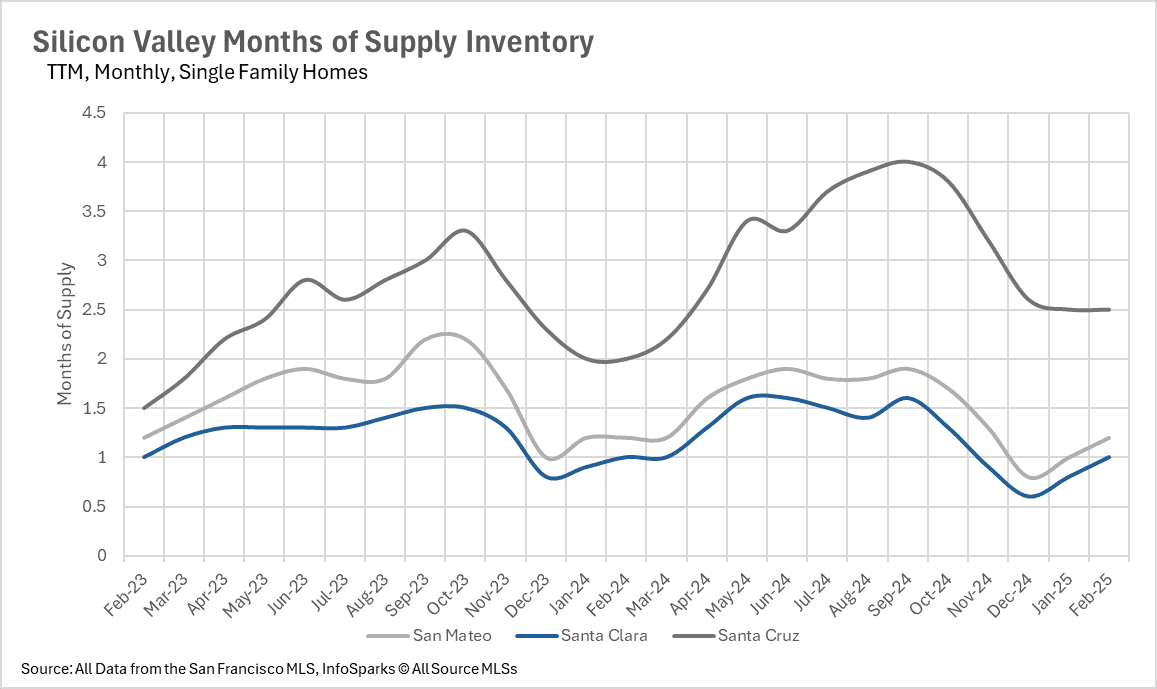
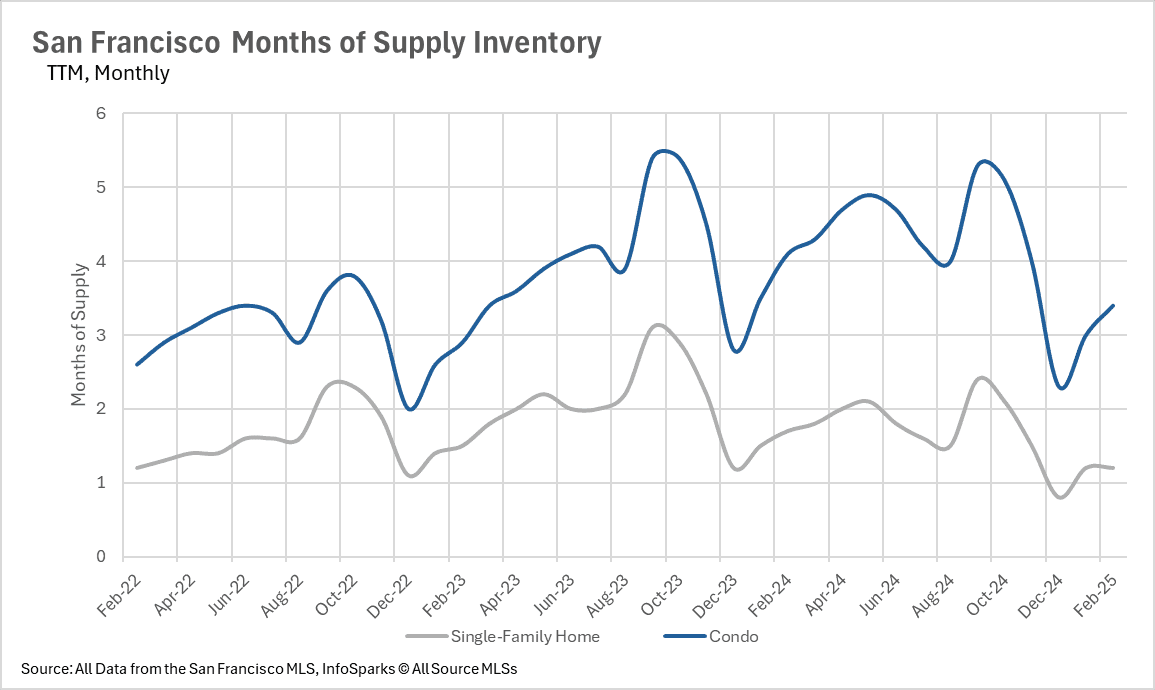
Most of the Bay Area remains a strong seller’s market, particularly in Silicon Valley, where months of supply inventory (MSI) remains well below the three-month threshold that defines a balanced market. The East Bay also continues to favor sellers, though its rapidly growing inventory could shift that dynamic. In the North Bay, Napa is the only county that leans toward a buyer’s market, with nearly five months of supply available. San Francisco remains divided—sellers hold the upper hand in the single-family home market, where inventory is tight, but condo buyers have more negotiating power with over three months of supply available.
Local Lowdown Data
Line chart of monthly North Bay single-family home prices by county, February 2022 to February 2025.
Line chart comparing monthly median single-family home prices in Alameda and Contra Costa counties, February 2021–February 2025.
Chart of monthly Silicon Valley single-family home prices by county from February 2021 to February 2025.
Chart of San Francisco median home prices, comparing single-family homes and condos from February 2021 to February 2025.
Chart of North Bay county condo prices, with Napa ending in a sharp rise near $1.5 million.
Line chart comparing monthly median condo prices in Alameda and Contra Costa counties from 2021 to 2025.
Chart of monthly median condo prices in San Mateo, Santa Clara, and Santa Cruz counties from 2021 to 2025.
Chart of North Bay single-family home listings, with new and sold listings and homes for sale, February 2023–February 2025.
Chart of East Bay single-family home listings and homes for sale, monthly from February 2023 to February 2025.
Silicon Valley single-family home inventory chart, with monthly new listings, sold listings, and homes for sale, February 2023–February 2025.
Chart of San Francisco single-family home inventory, showing monthly listings and homes for sale from 2021 to 2025.
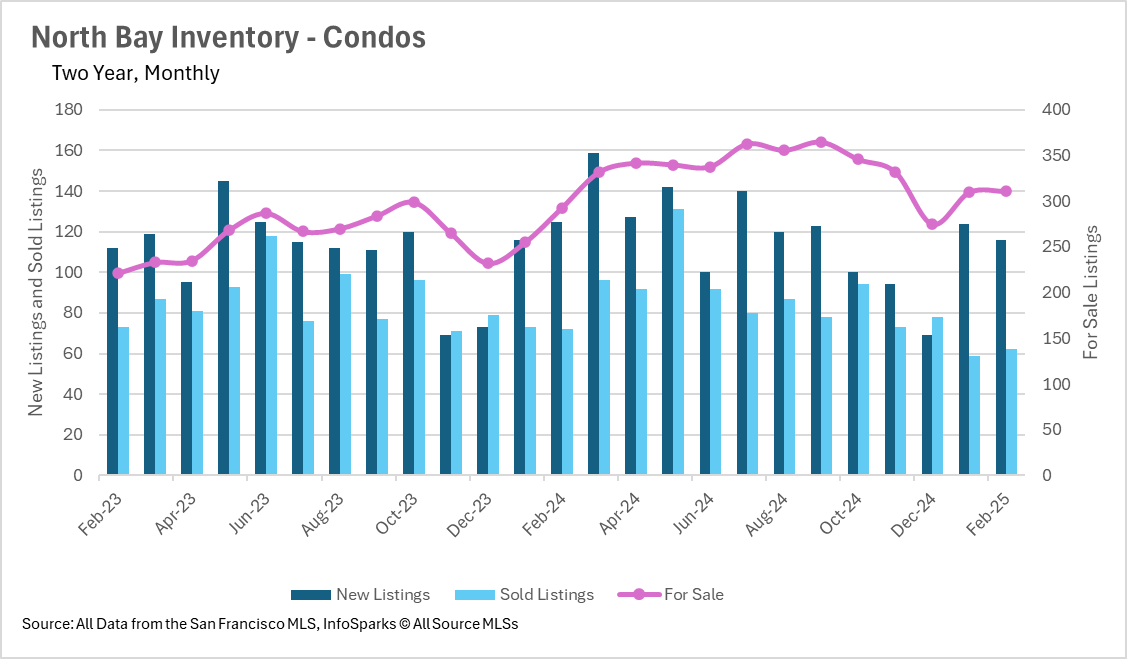
Chart of North Bay condo new listings, sold listings, and inventory for sale, February 2023–February 2025.
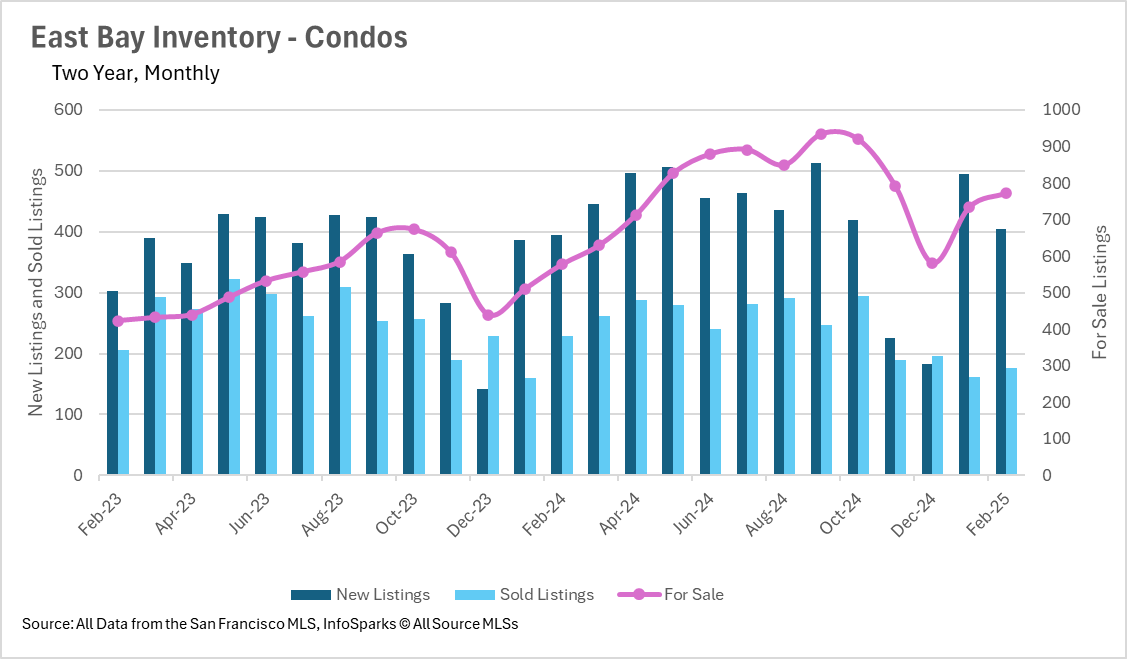
East Bay condo inventory chart showing monthly new listings, sold listings, and homes for sale, 2023–2025.
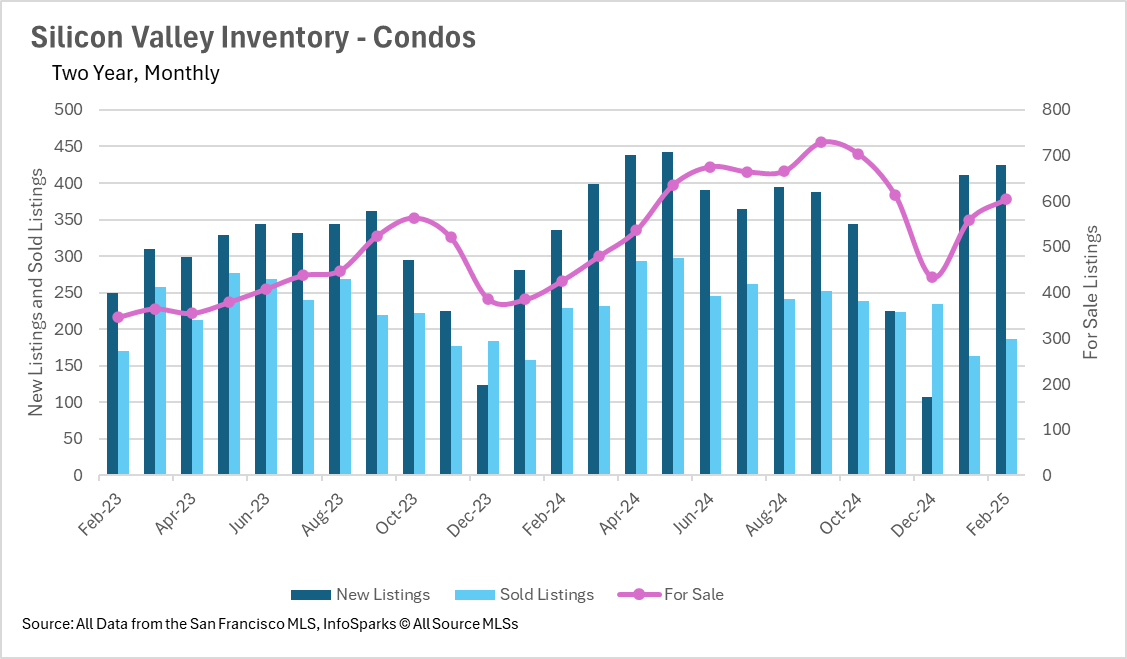
Chart of monthly Silicon Valley condo new listings, sold listings, and inventory from February 2023 to February 2025.
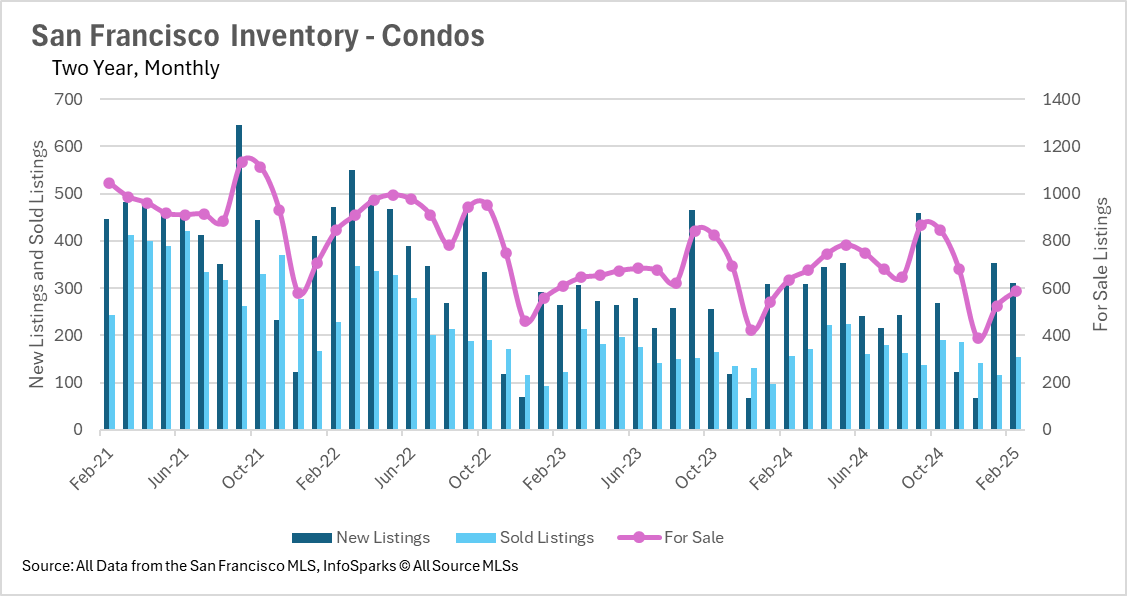
Chart of San Francisco condo listings, showing monthly new and sold listings and inventory for sale from 2021 to 2025.
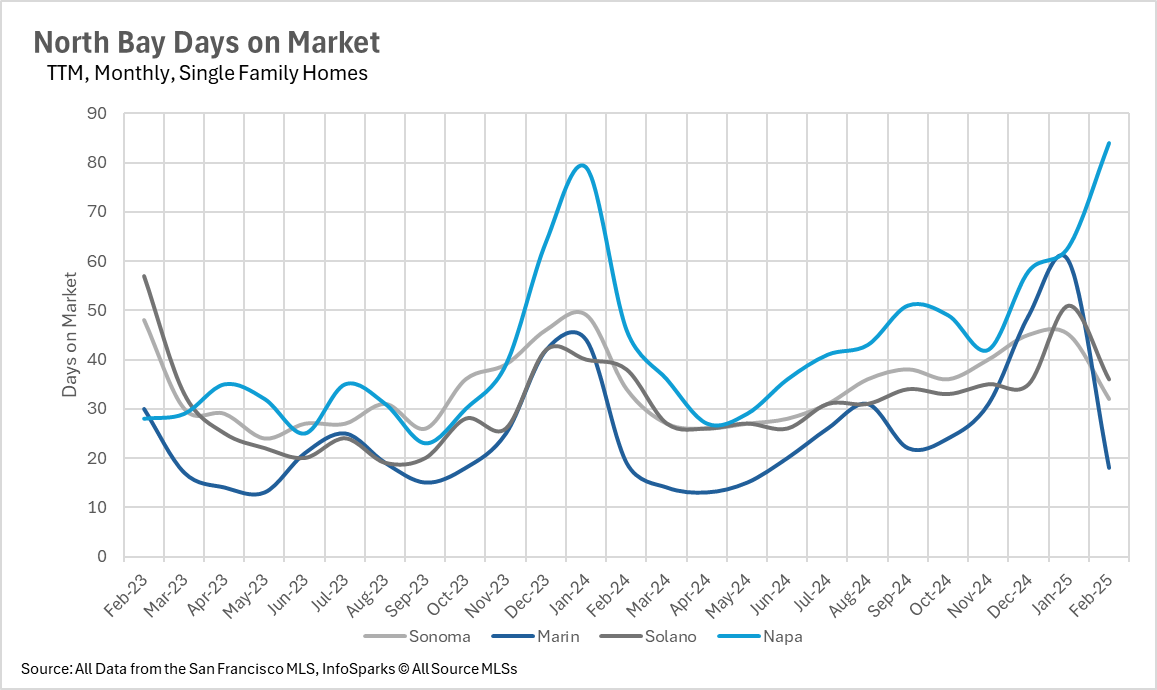
Line chart of North Bay single-family home days on market by county, February 2023 to February 2025; Napa ends highest.
Chart of monthly East Bay days on market, comparing Alameda and Contra Costa from February 2023 to February 2025.
Chart of Silicon Valley days on market, comparing San Mateo, Santa Clara, and Santa Cruz from February 2023 to February 2025.
San Francisco days-on-market chart comparing single-family homes and condos from February 2022 to February 2025.
North Bay condo days-on-market chart, February 2023–February 2025, comparing Sonoma, Marin, Solano, and Napa.
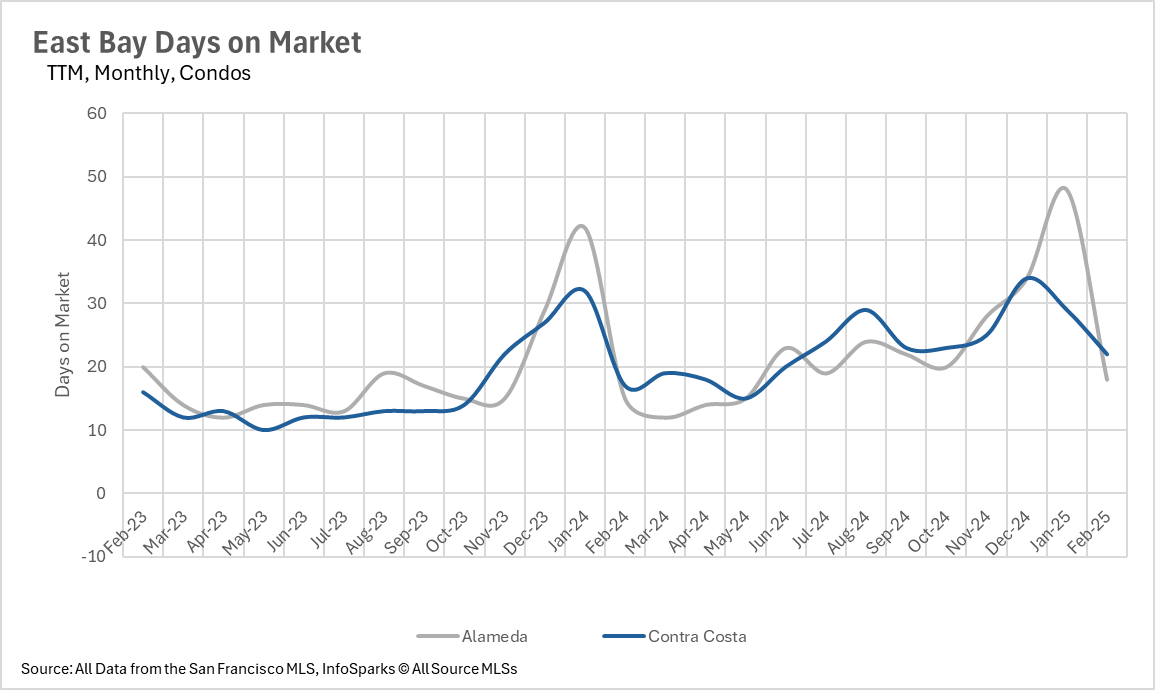
Line chart comparing monthly days on market for Alameda and Contra Costa condos, February 2023 to February 2025.
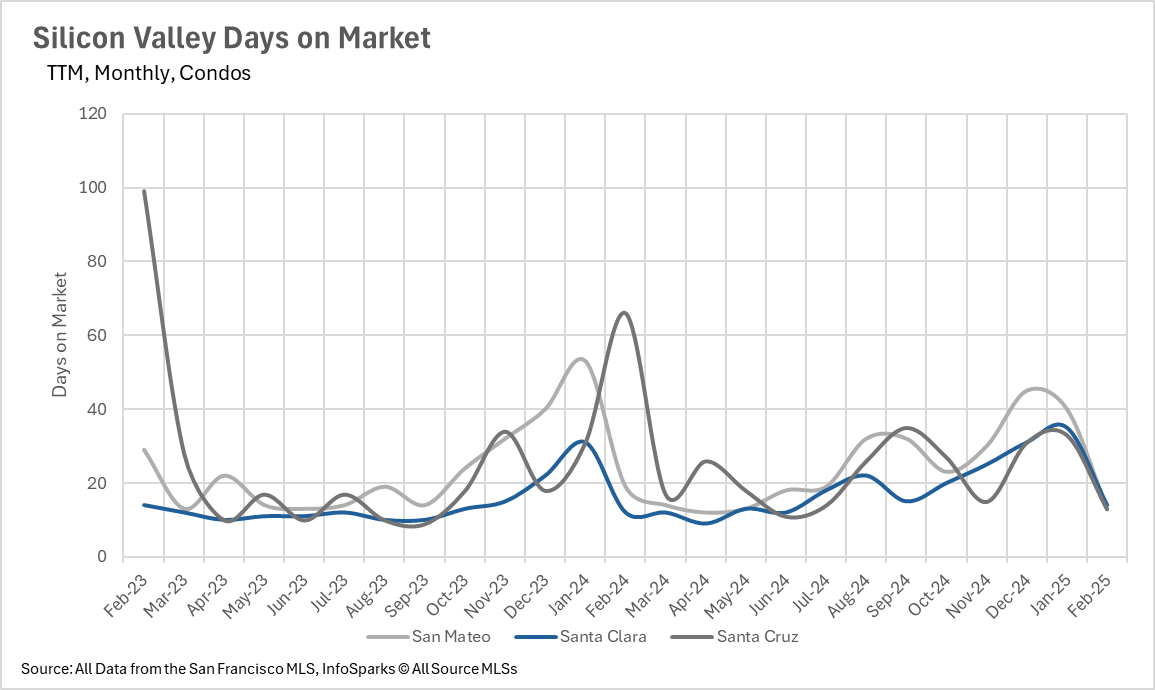
Line chart compares monthly condo days on market in three Silicon Valley areas, February 2023–February 2025.
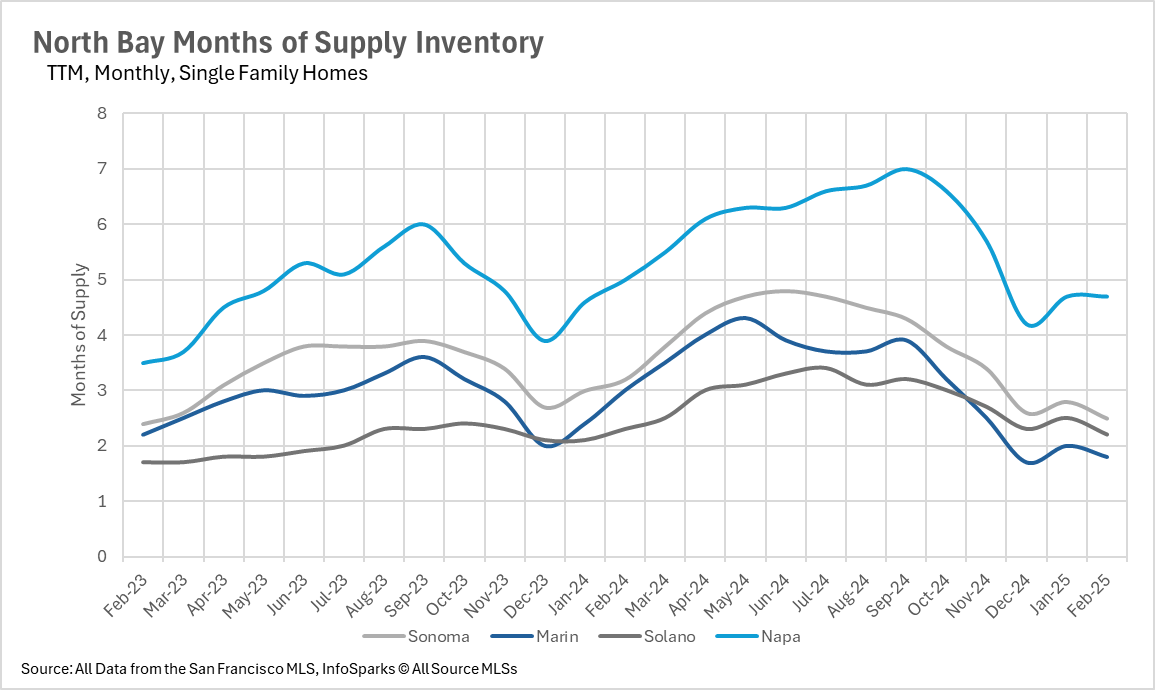
Line chart of North Bay single-family home supply by county, February 2023 to February 2025; Napa stays highest.
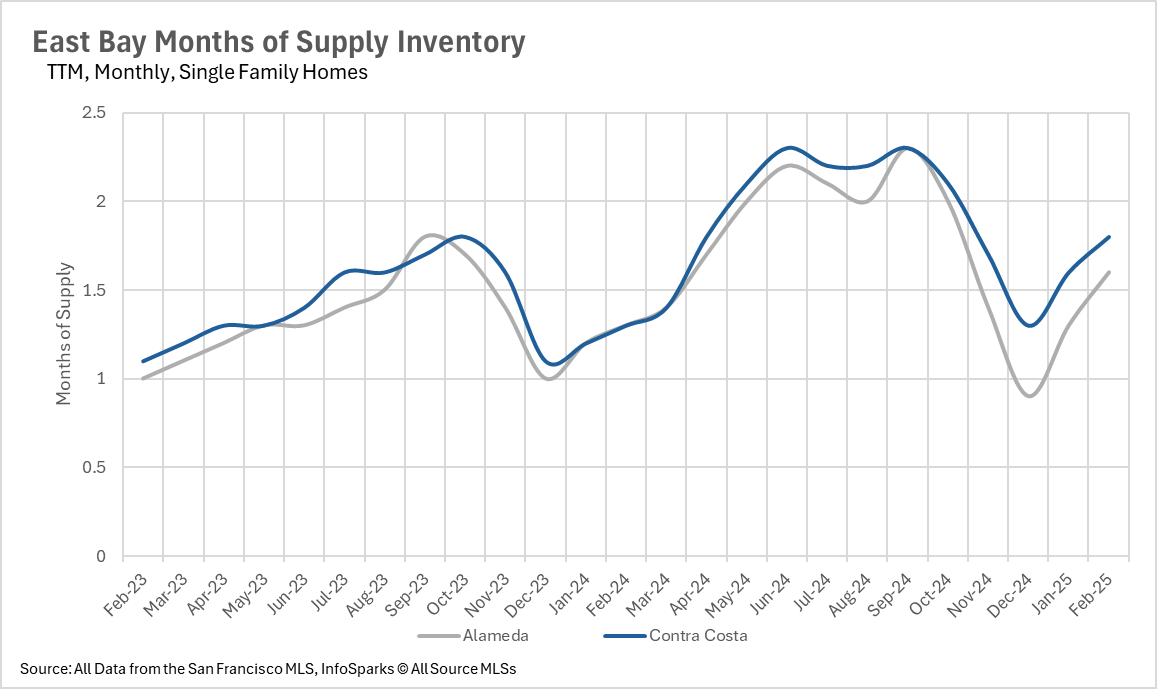
East Bay months-of-supply inventory chart comparing Alameda and Contra Costa from February 2023 to February 2025.
Line chart comparing monthly single-family home supply in San Mateo, Santa Clara, and Santa Cruz, February 2023–February 2025.
Chart comparing San Francisco condo and single-family home months of supply from February 2022 to February 2025.

ActivePipe Message ID: 3244562

Let’s Talk

You’ve got questions and we can’t wait to answer them.