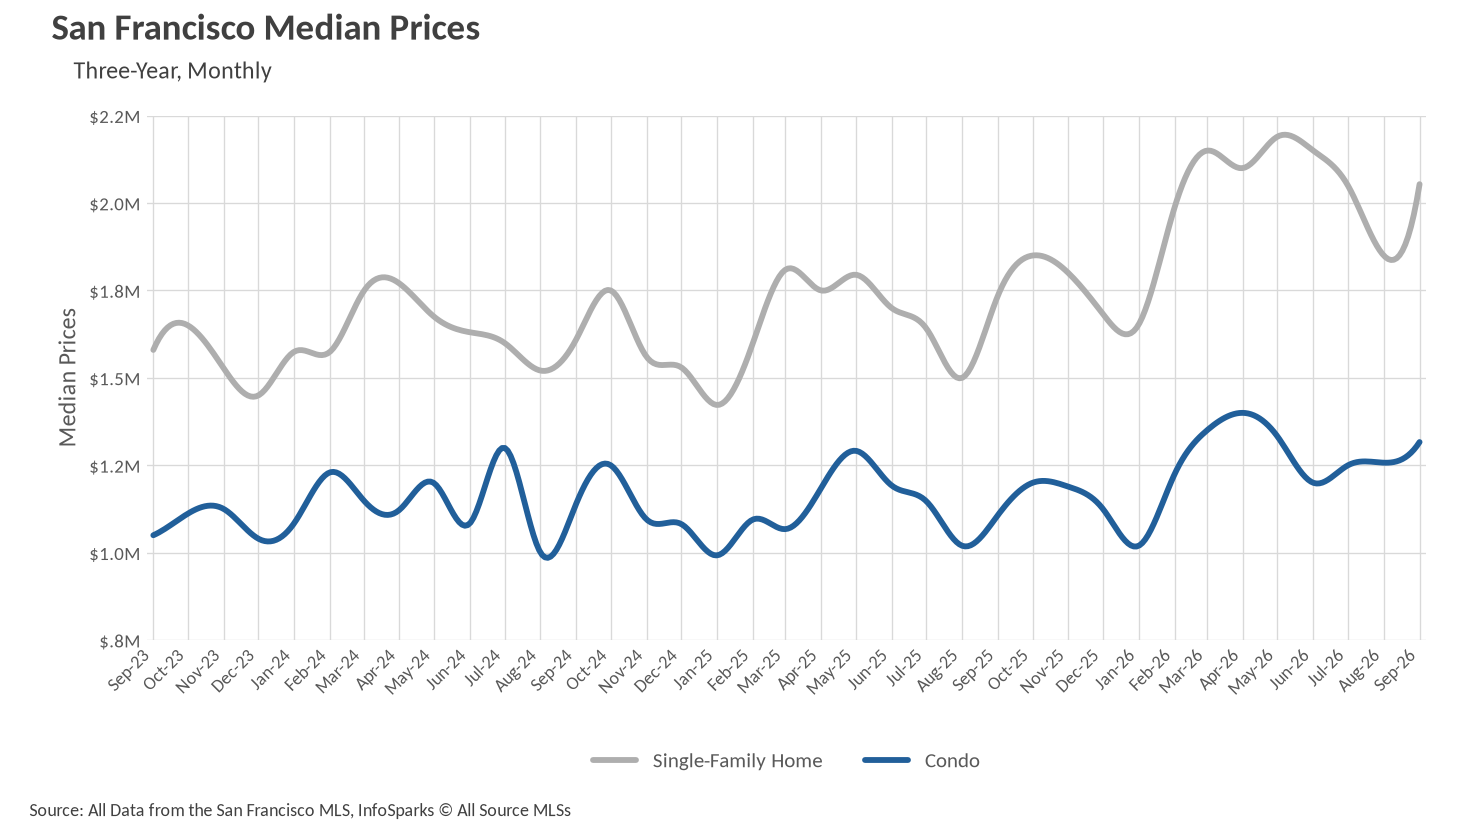
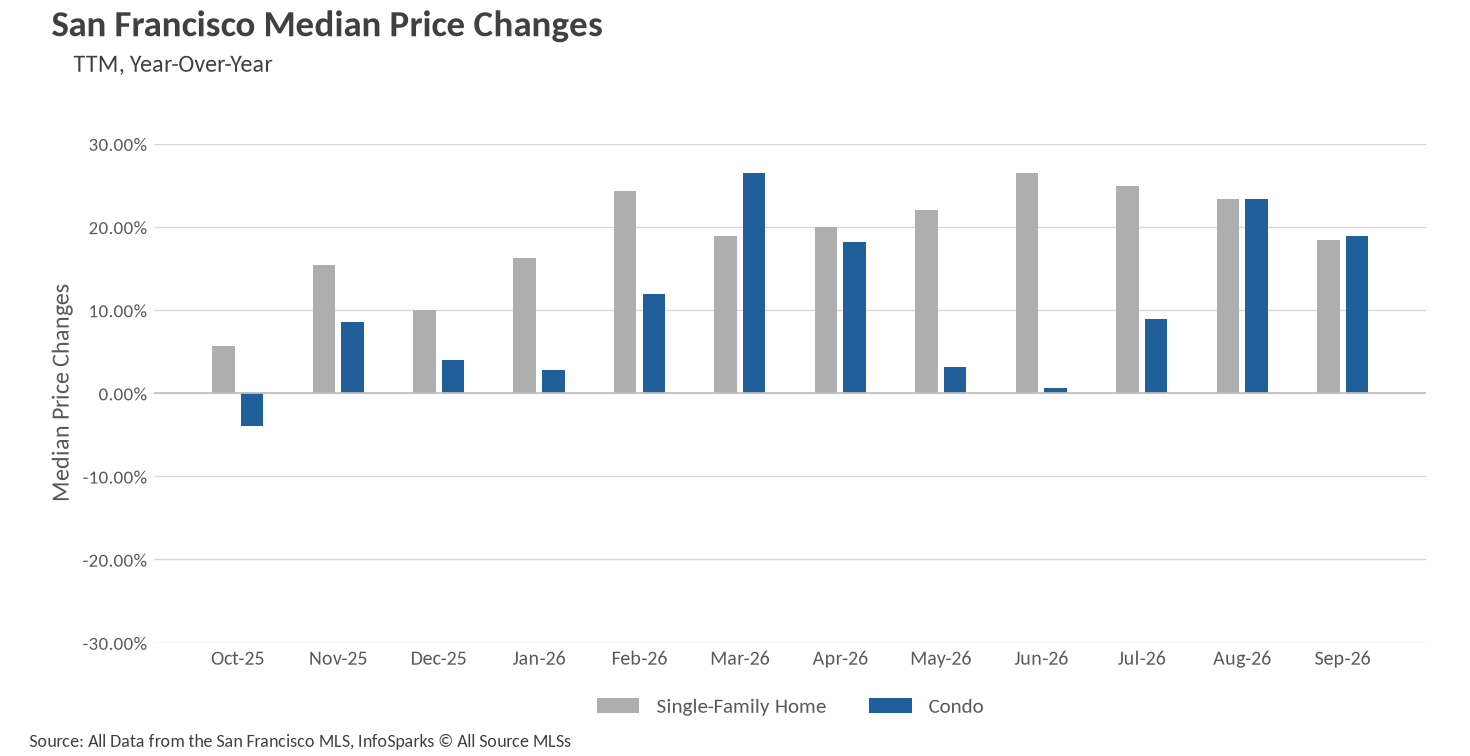Single-family median sale price jumped back above $2 million in September, finishing 18.4% higher than a year ago at $2,054,000.
San Francisco Market Update

Big Story Data

The Local Lowdown
Quick Take:
  • The single-family median sale price jumped back above $2 million in September, finishing 18.4% higher than a year ago at $2,054,000.
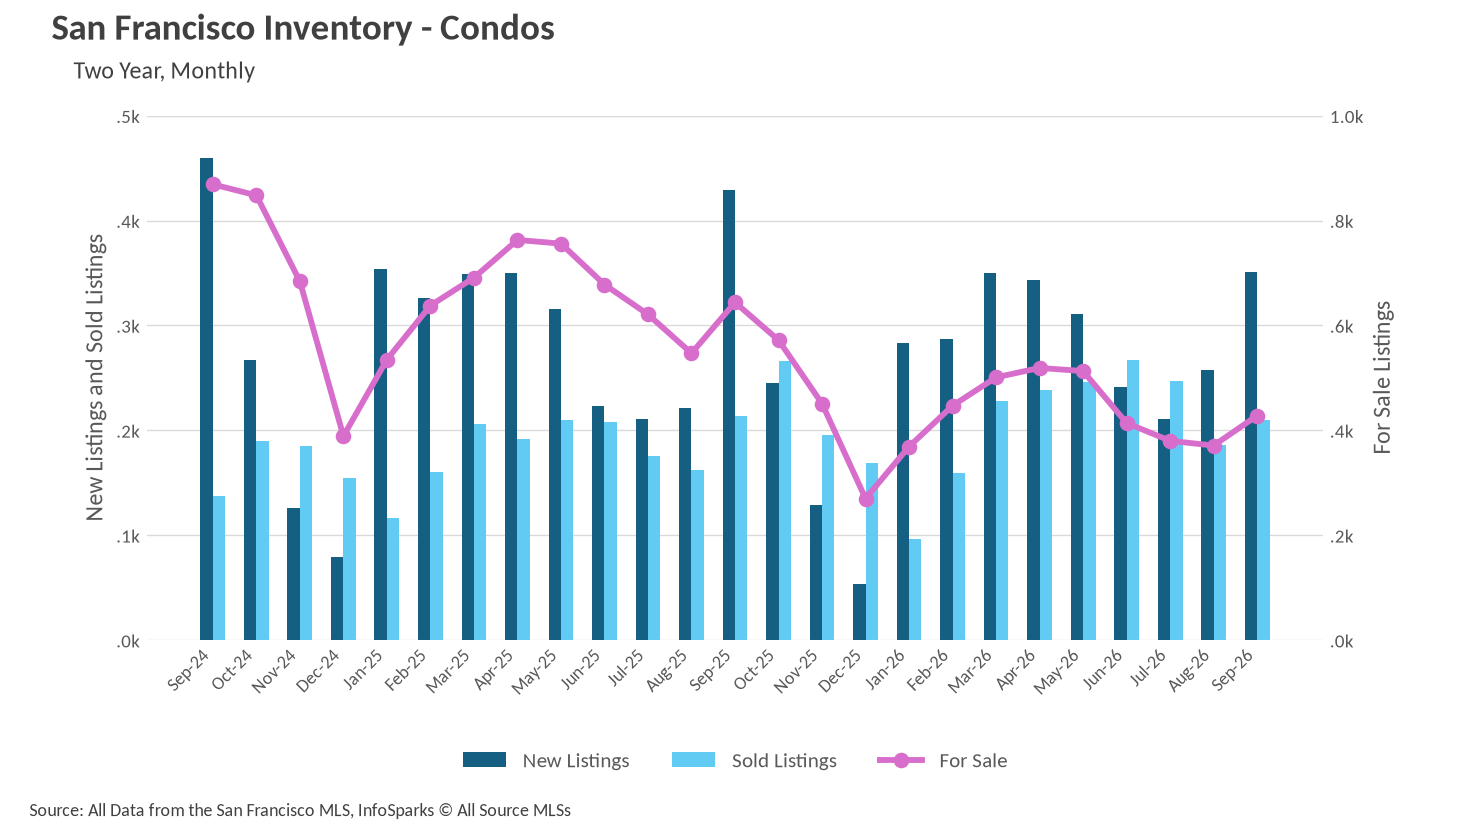
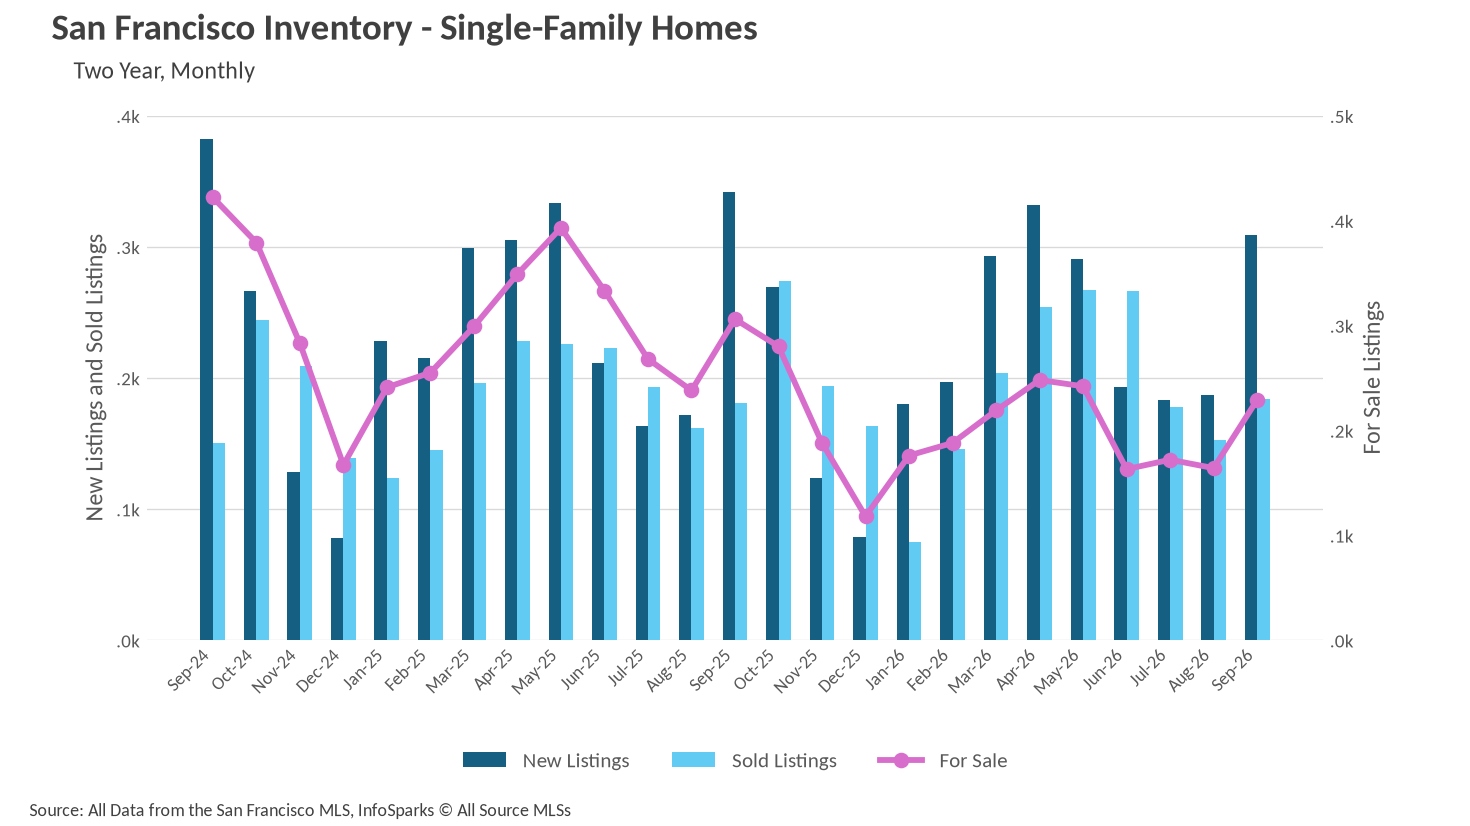
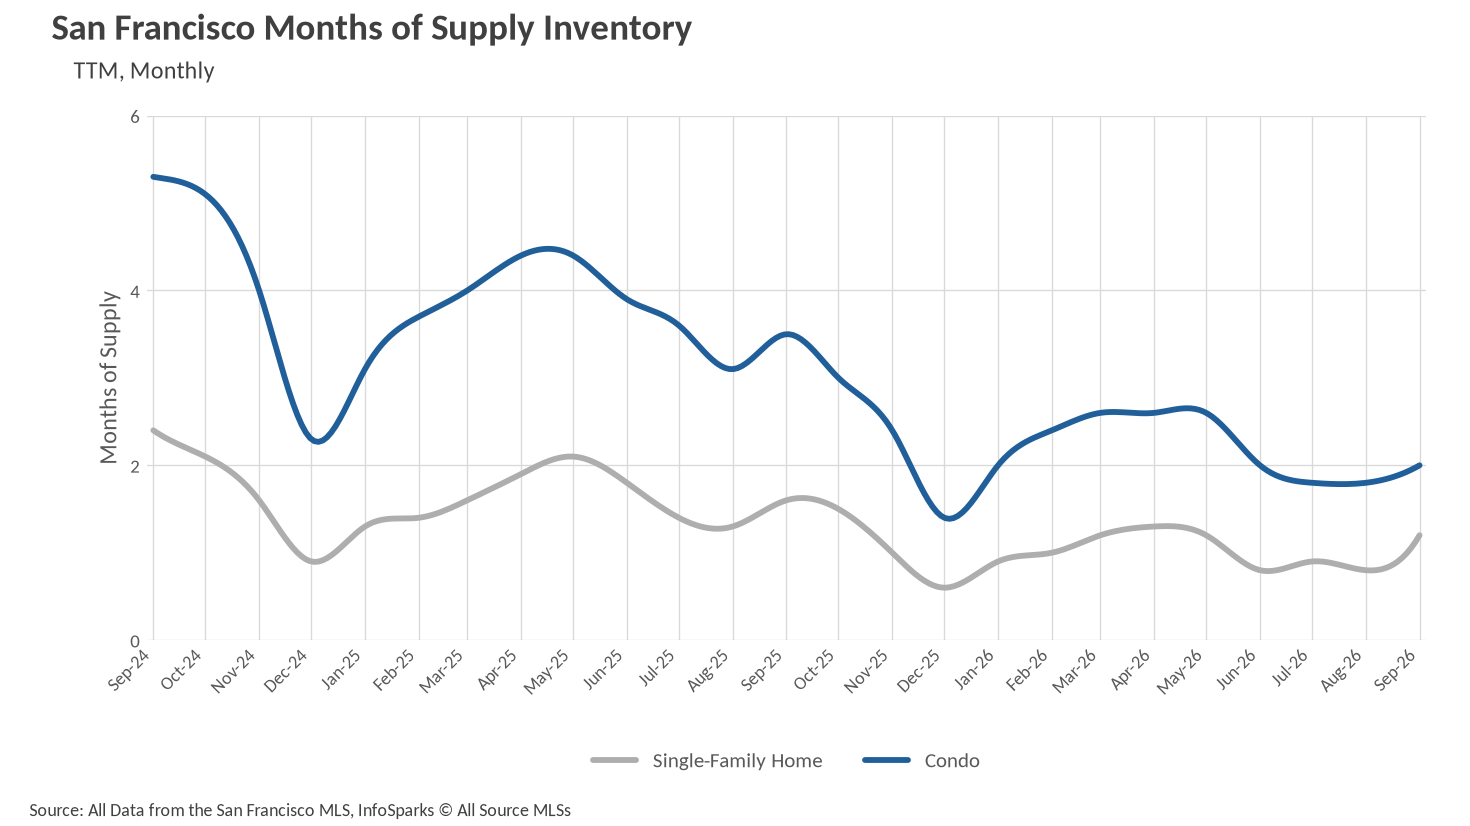
  • Inventory rebounded seasonally from the summer lows but remains far below last year, with single-family listings down roughly 25% and condo listings down nearly 34% year-over-year.
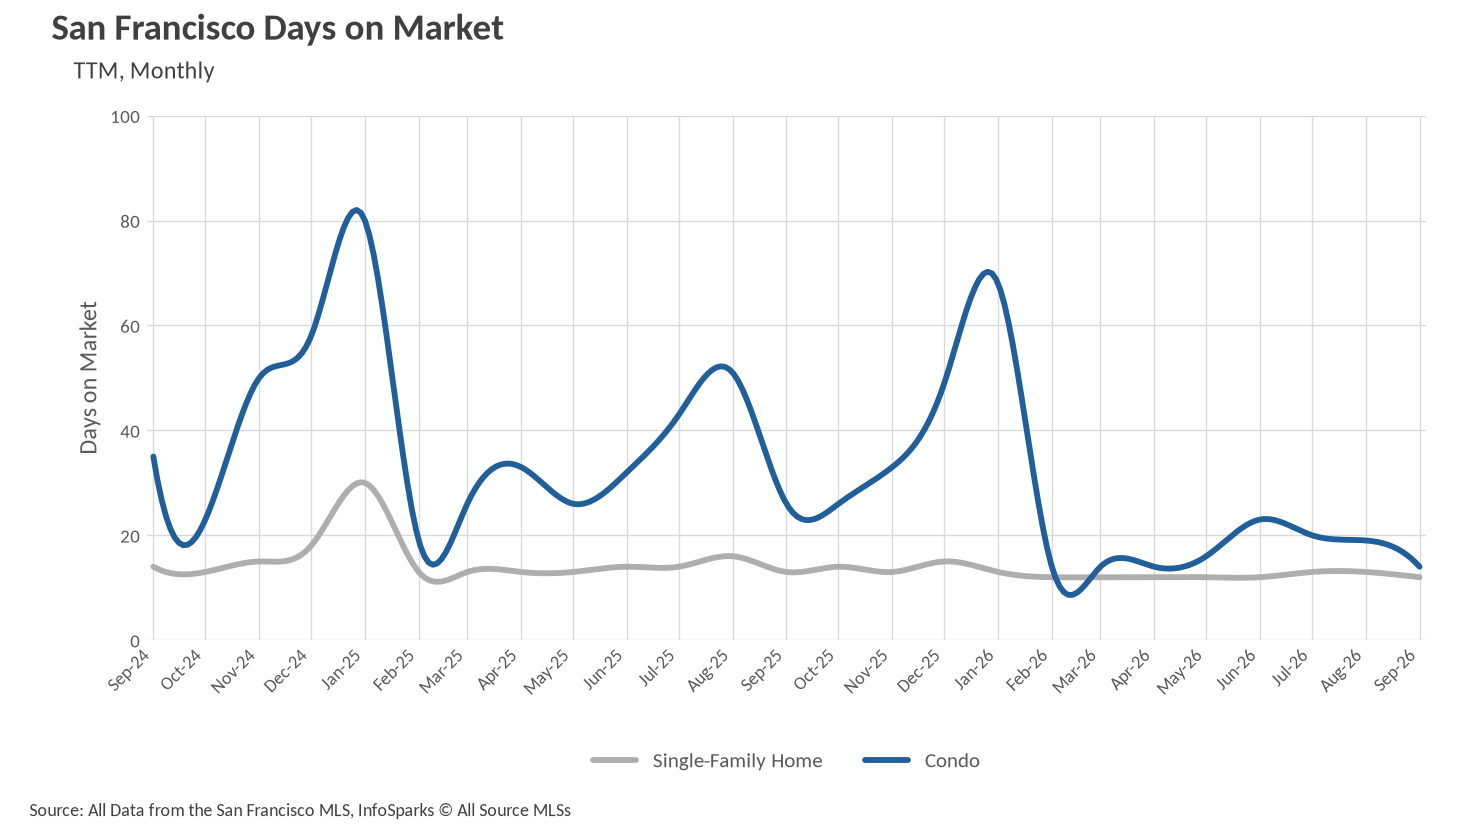
  • Single-family homes continue to sell in 12 days, while condos have accelerated dramatically to just 14 days, down from 26 days last September.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.

Prices rebound after a soft August, and bidding premiums hit record high
August looked like a breather for San Francisco's single-family market, with the median falling to $1,850,000, but September erased that dip in a hurry. The median sale price climbed 11.03% month-over-month to $2,054,000, putting it 18.39% above the $1,735,000 recorded in September 2025. That keeps the single-family market firmly in the $2 million-plus range it has occupied for most of 2026, a level that was simply not part of the conversation at this time last year.

The condo market turned in an equally impressive annual gain. At $1,316,500, the median condo price rose 18.87% from last September's $1,107,500 and added 4.69% from August. Condos have now posted three consecutive monthly increases after cooling off from the April peak of $1,400,000.

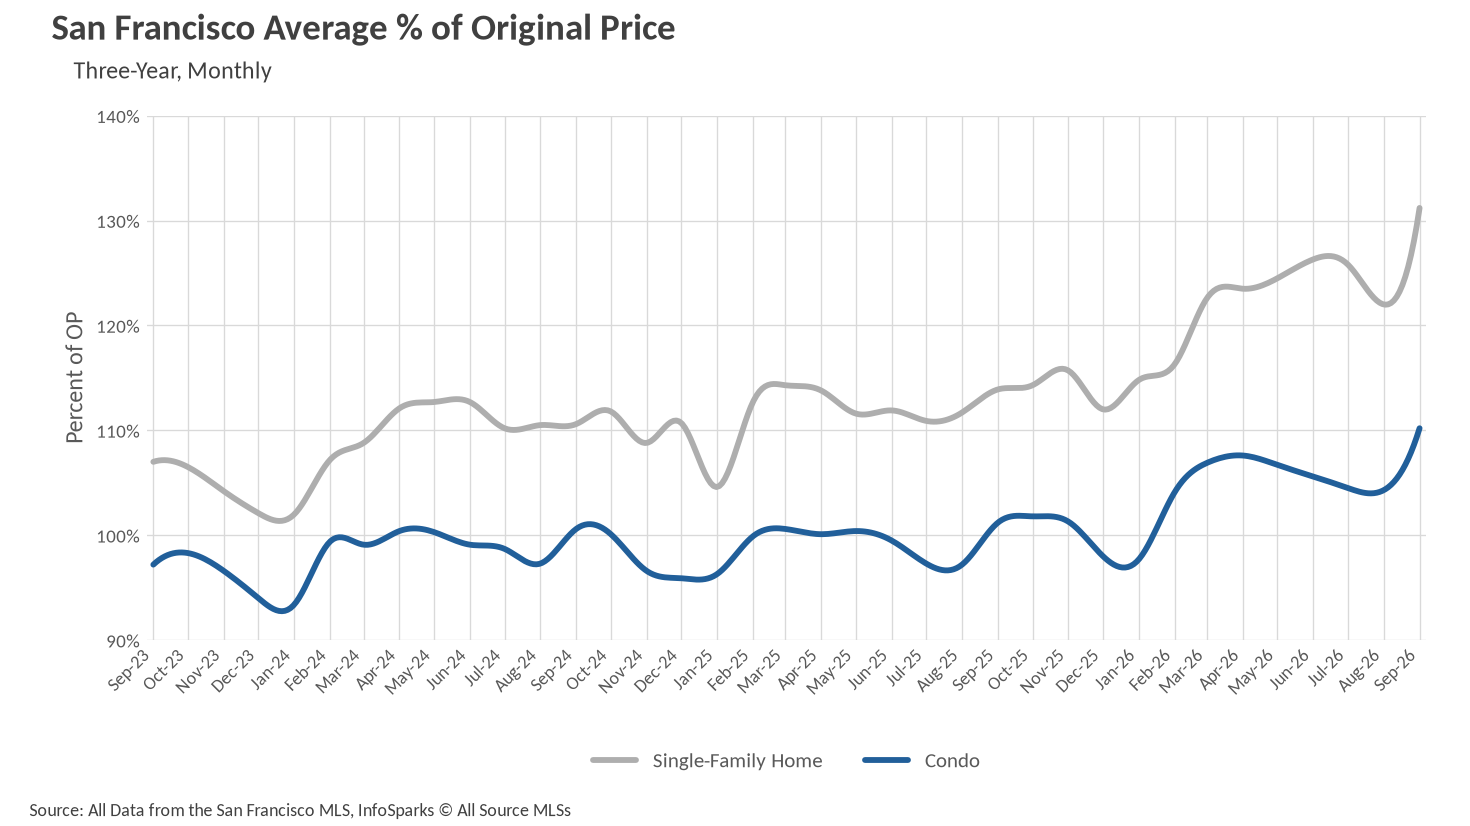
The more telling story may be what buyers are paying relative to list price. Single-family homes sold for an average of 31% above original asking price in September, the highest figure anywhere in this three-year data set and up from 14% a year ago. Condos sold for 10% over original price, also a record for this series and a sharp move from the 1% premium recorded last September. Competition is not just steady, it is intensifying.

Fall listings arrive, but the shelf is still half empty
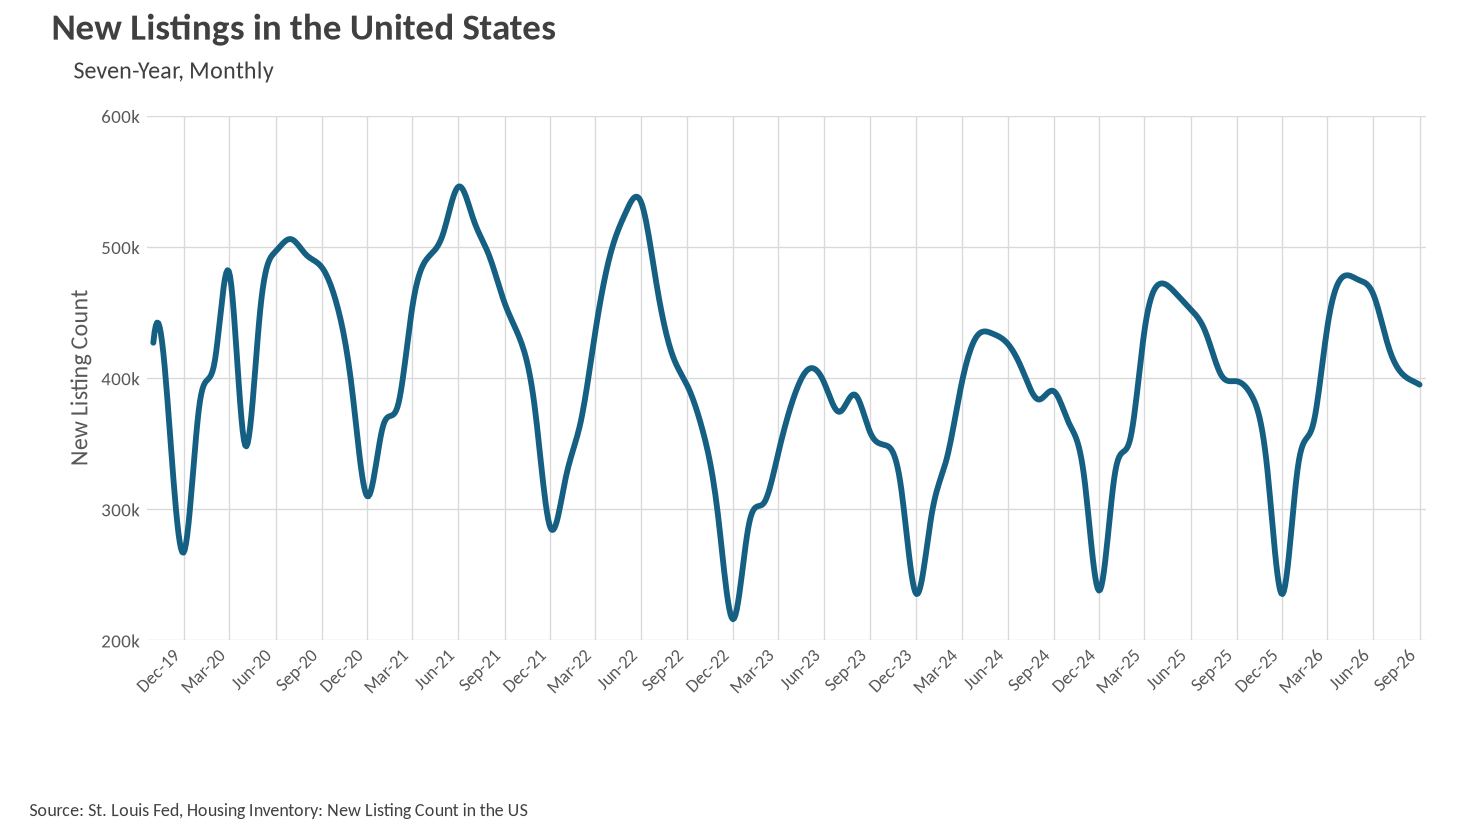
September delivered the seasonal restocking that San Francisco's market has been waiting for all summer. There were 229 single-family homes for sale at the end of the month, up 39.63% from August's 164 and the highest count since April. Sellers brought 309 new single-family listings to market, a healthy jump from 187 in August.

The problem is that this rebound still leaves the market well behind where it was a year ago. Last September there were 306 single-family homes for sale, meaning the current count represents a 25.16% year-over-year decline. New listings were also down 9.65% from the 342 brought to market in September 2025, even as sold listings held essentially flat at 184 versus 181. In other words, demand has held its ground while supply has thinned.

Condos tell a similar story with a steeper decline. There were 428 condos for sale in September, up 15.36% from August's 371 but down 33.54% from the 644 available last September. New condo listings came in at 351, an 18.18% drop from 429 a year ago, while 210 condos sold compared with 214 last September. Across both property types, roughly 650 homes were available citywide at the end of September, against about 950 at the same point in 2025.

Condos close the speed gap with single-family homes
Single-family homes continue to move about as fast as they physically can. The average home sold in 12 days in September, down 7.69% from 13 days last September and consistent with the 12 to 13 day range that has held every month since February.

The condo market is where the real change has occurred. Condos sold in an average of just 14 days, a 46.15% improvement from the 26 days recorded in September 2025 and down from 19 days in August. That matches the fastest pace in this data set, equaling the 14-day readings from February through April. For context, condos spent 49 days on market in December 2025 and 68 days in January 2026. The segment that once gave buyers room to deliberate now moves nearly as quickly as the single-family market.
San Francisco remains a decisive seller's market across both property types
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.

San Francisco sits well below that three-month benchmark on both fronts. Single-family inventory stands at 1.2 months of supply, up from 0.8 months in August as fall listings arrived but still 25% below the 1.6 months recorded last September. The condo market carries 2.0 months of supply, essentially flat with August's 1.8 months but down 42.86% from 3.5 months a year ago. That condo figure is particularly notable, because as recently as last spring the segment was running above four months and sat squarely in buyers' market territory. It has since crossed decisively onto the sellers' side of the ledger. With record-setting sale-to-list premiums, two-week marketing times, and supply running a quarter to a third below last year in both segments, sellers retain the upper hand heading into the final months of 2026.

Local Lowdown Data

ActivePipe Message ID: 4125736

Let’s Talk

You’ve got questions and we can’t wait to answer them.