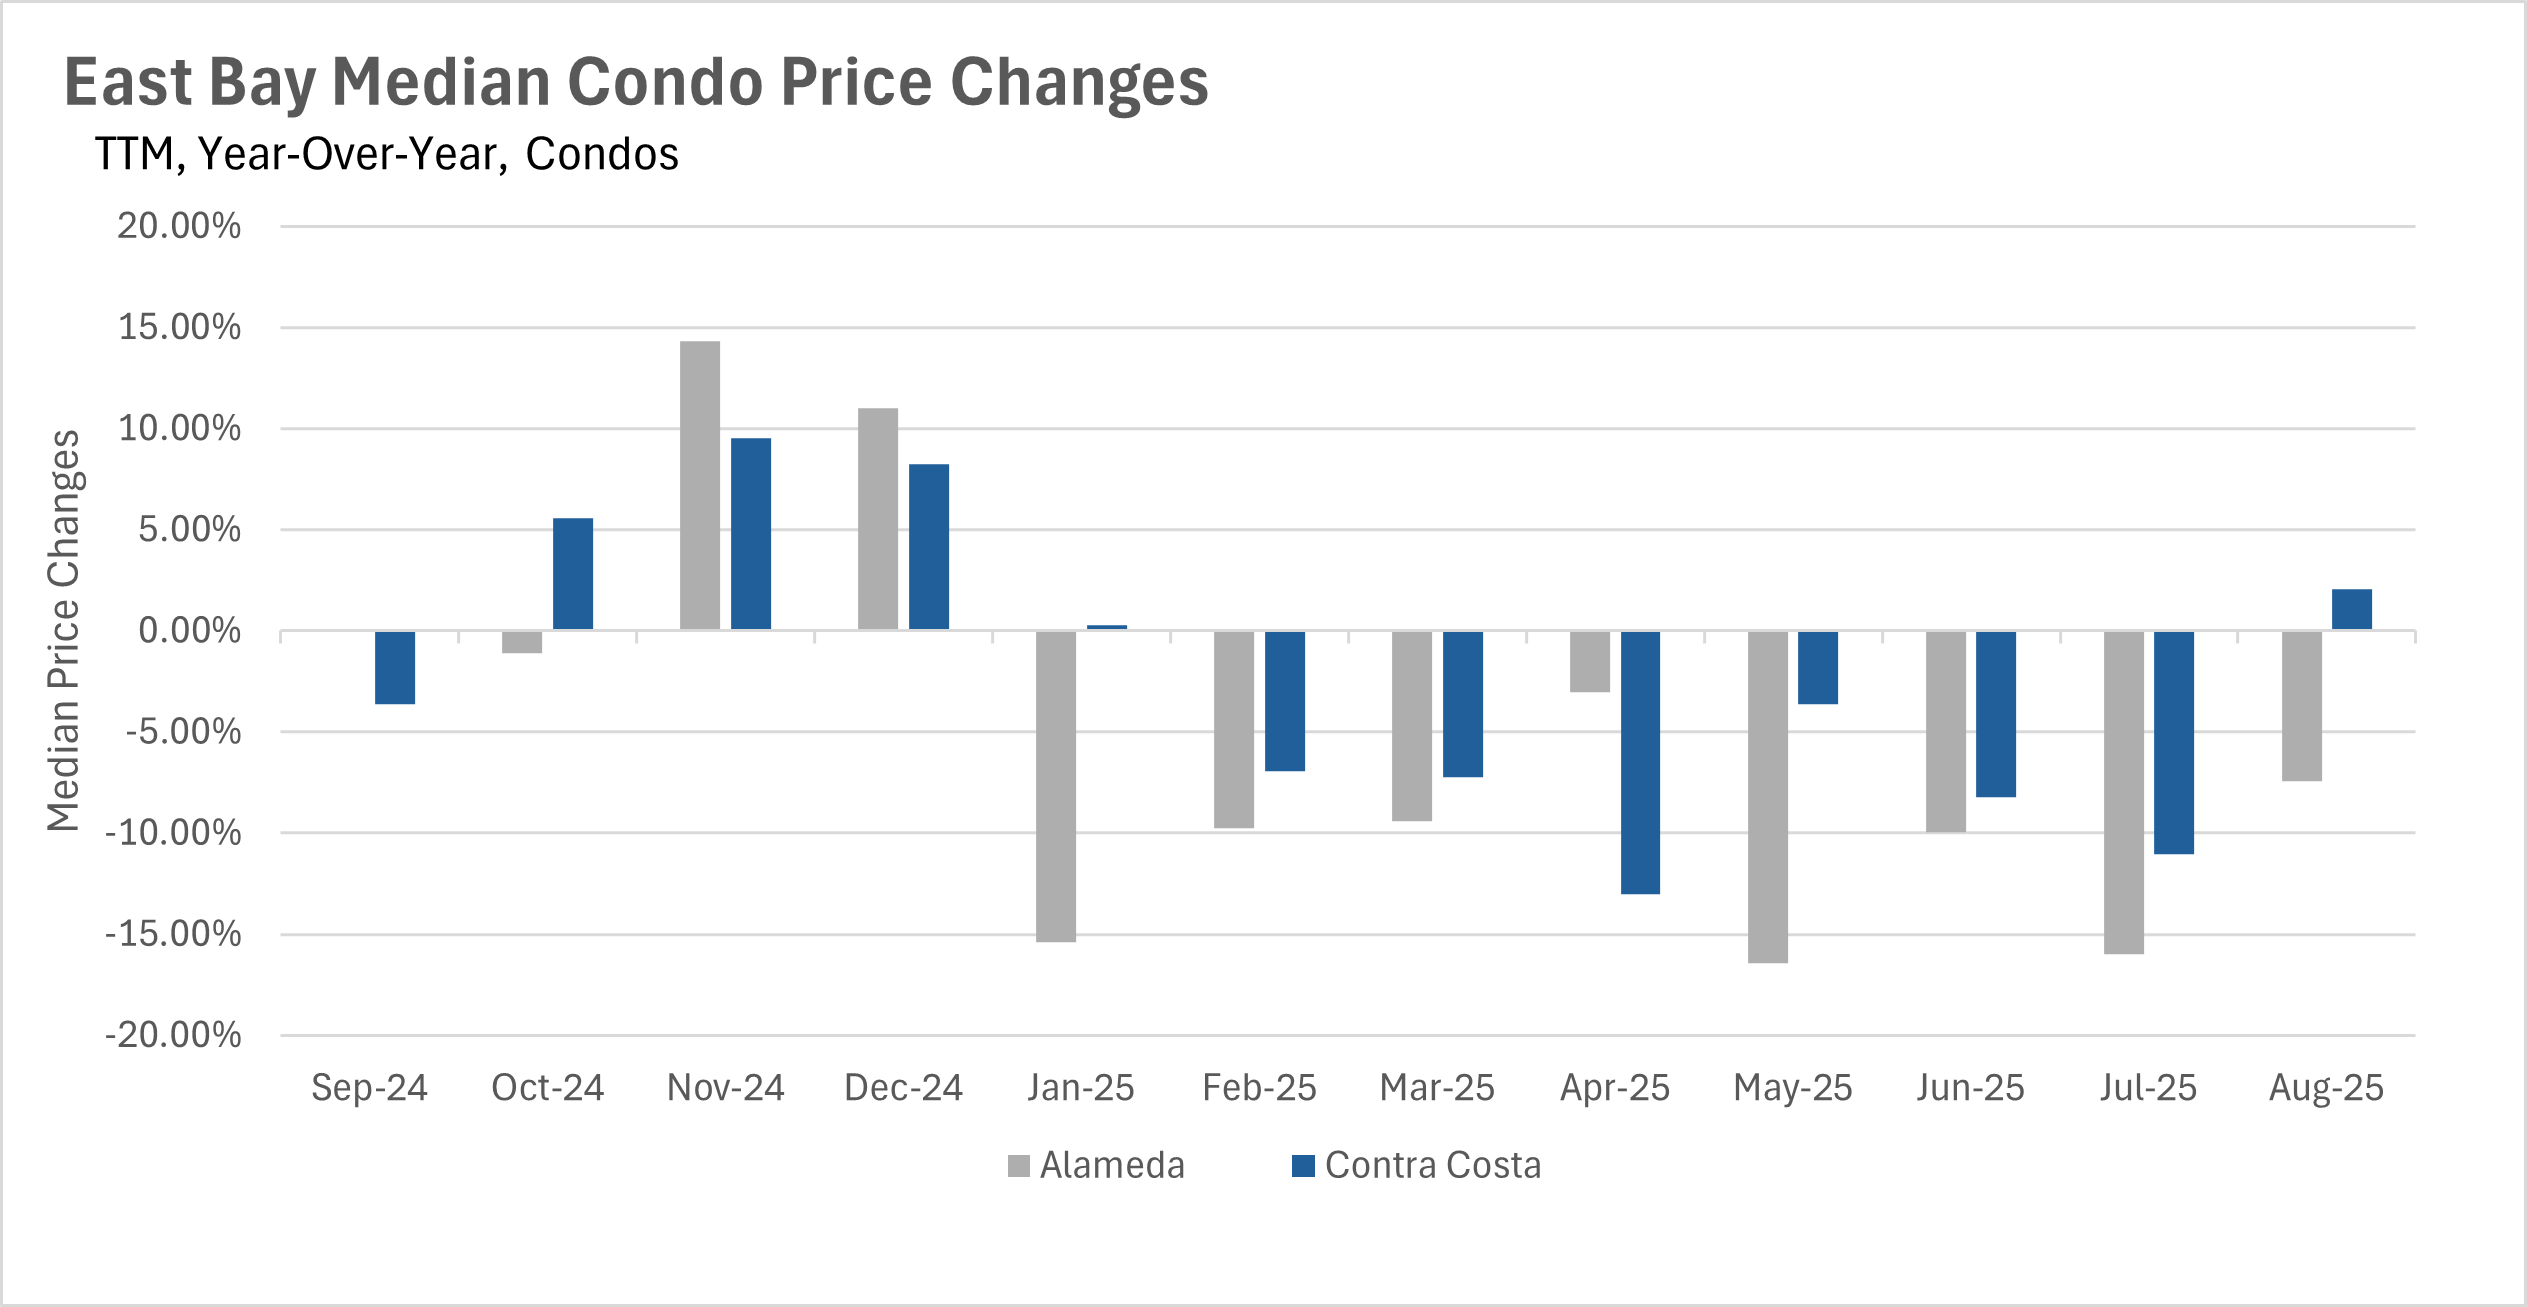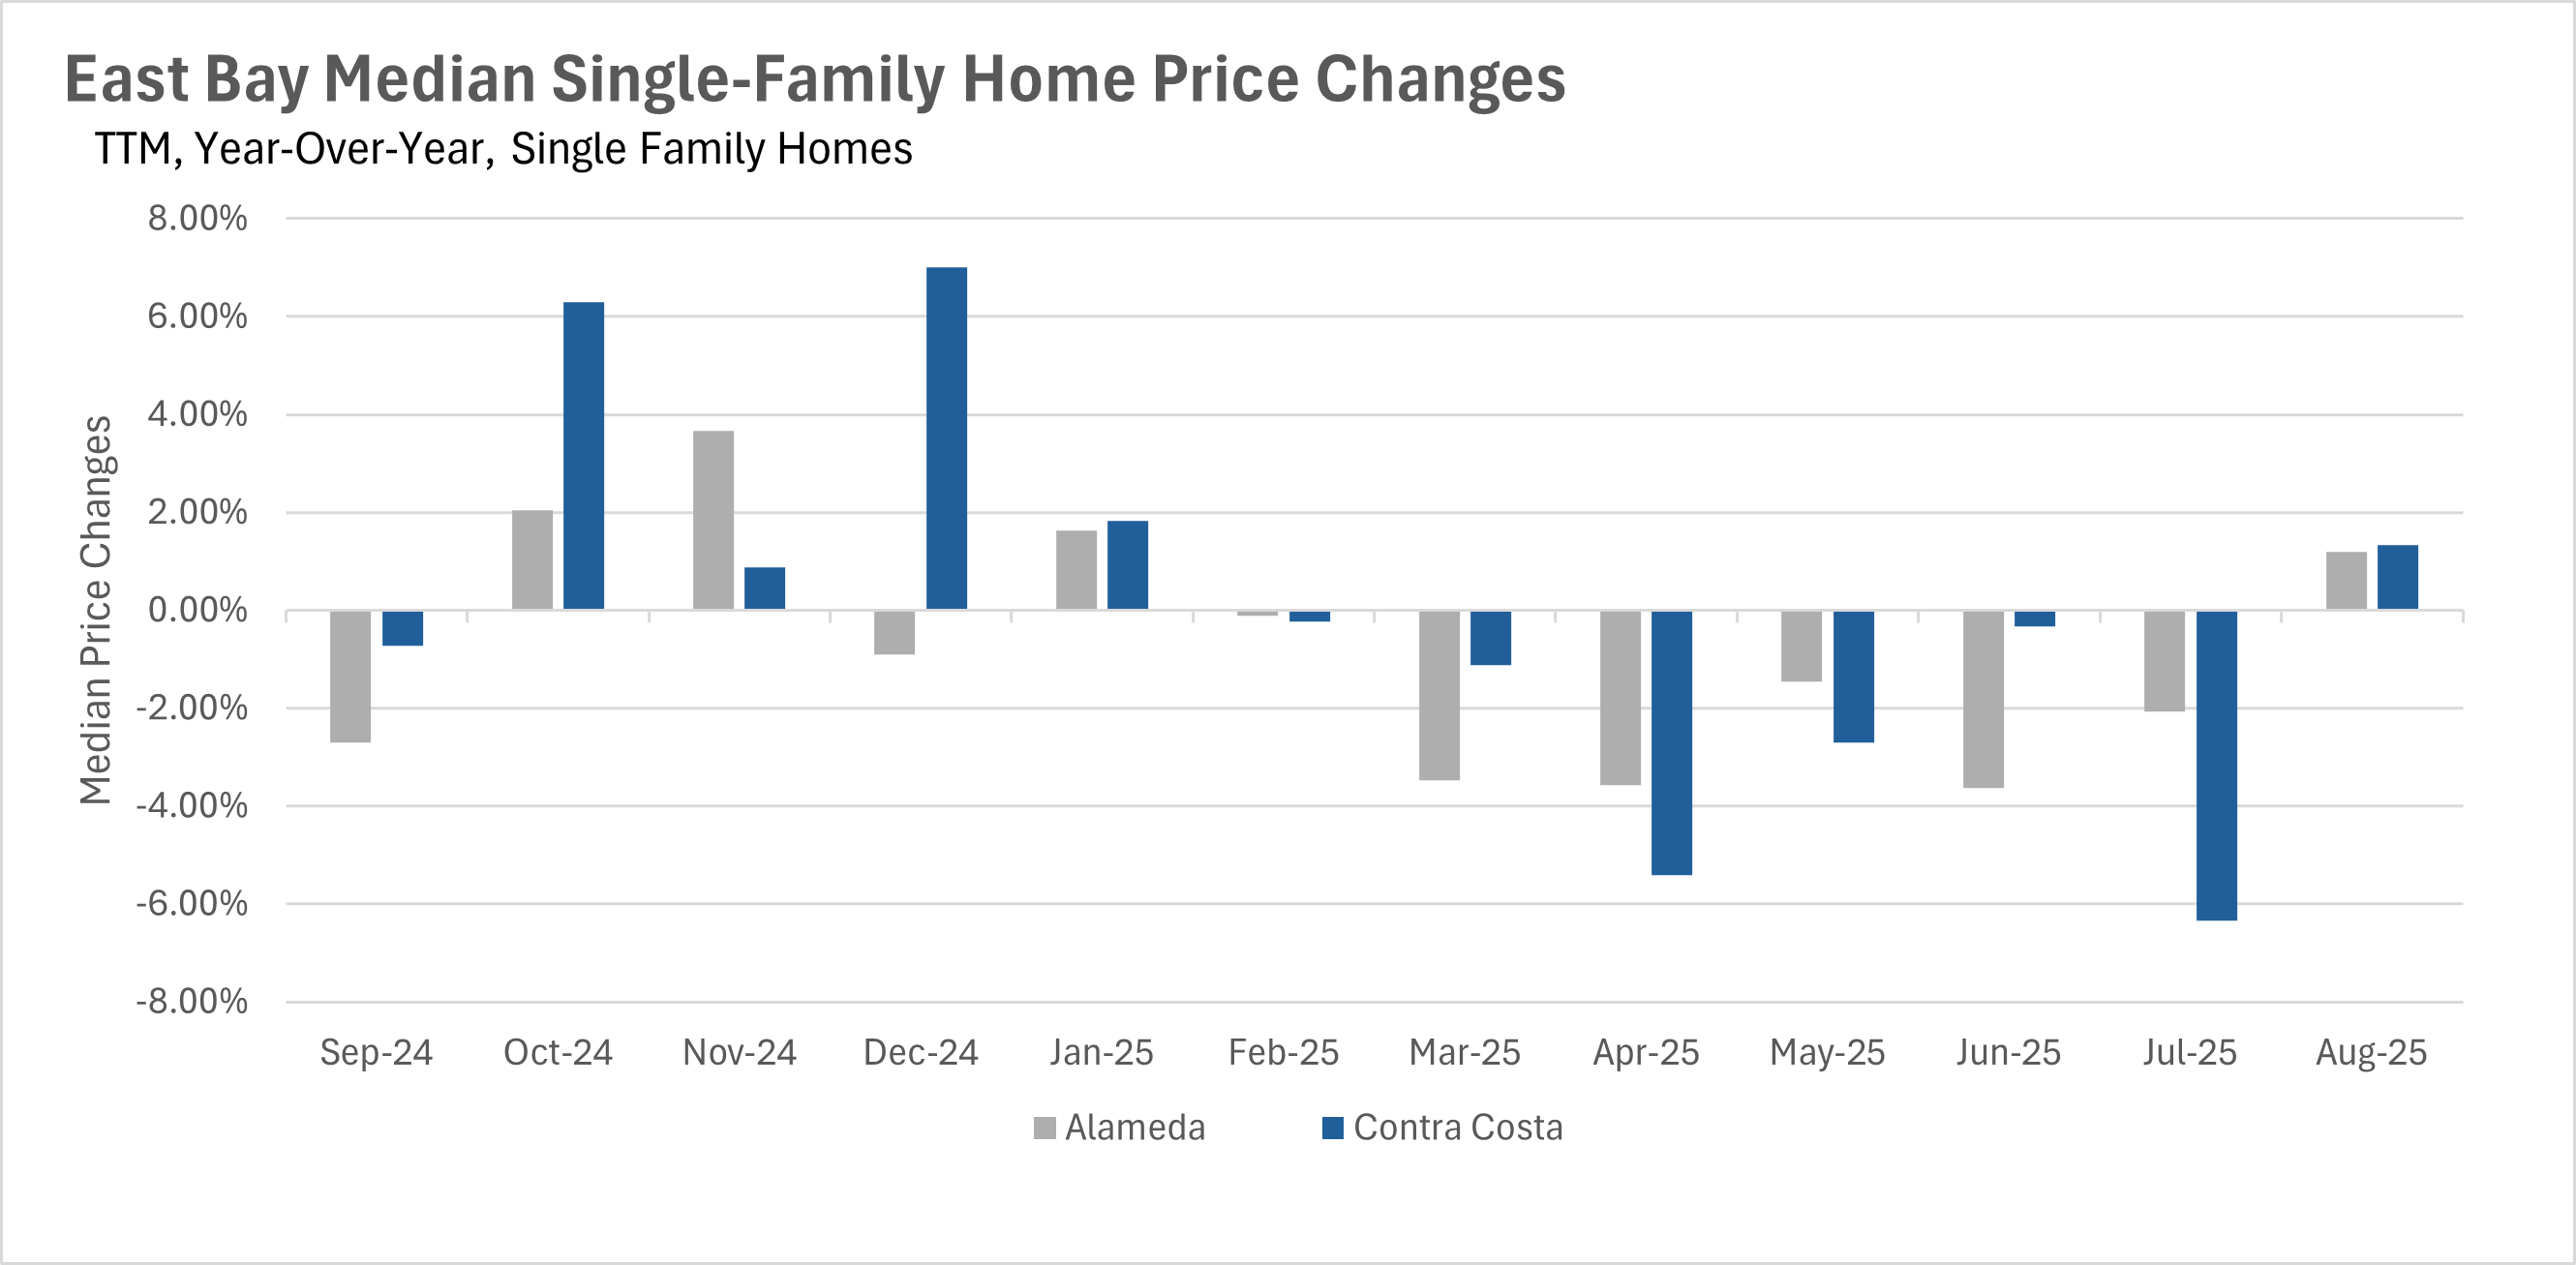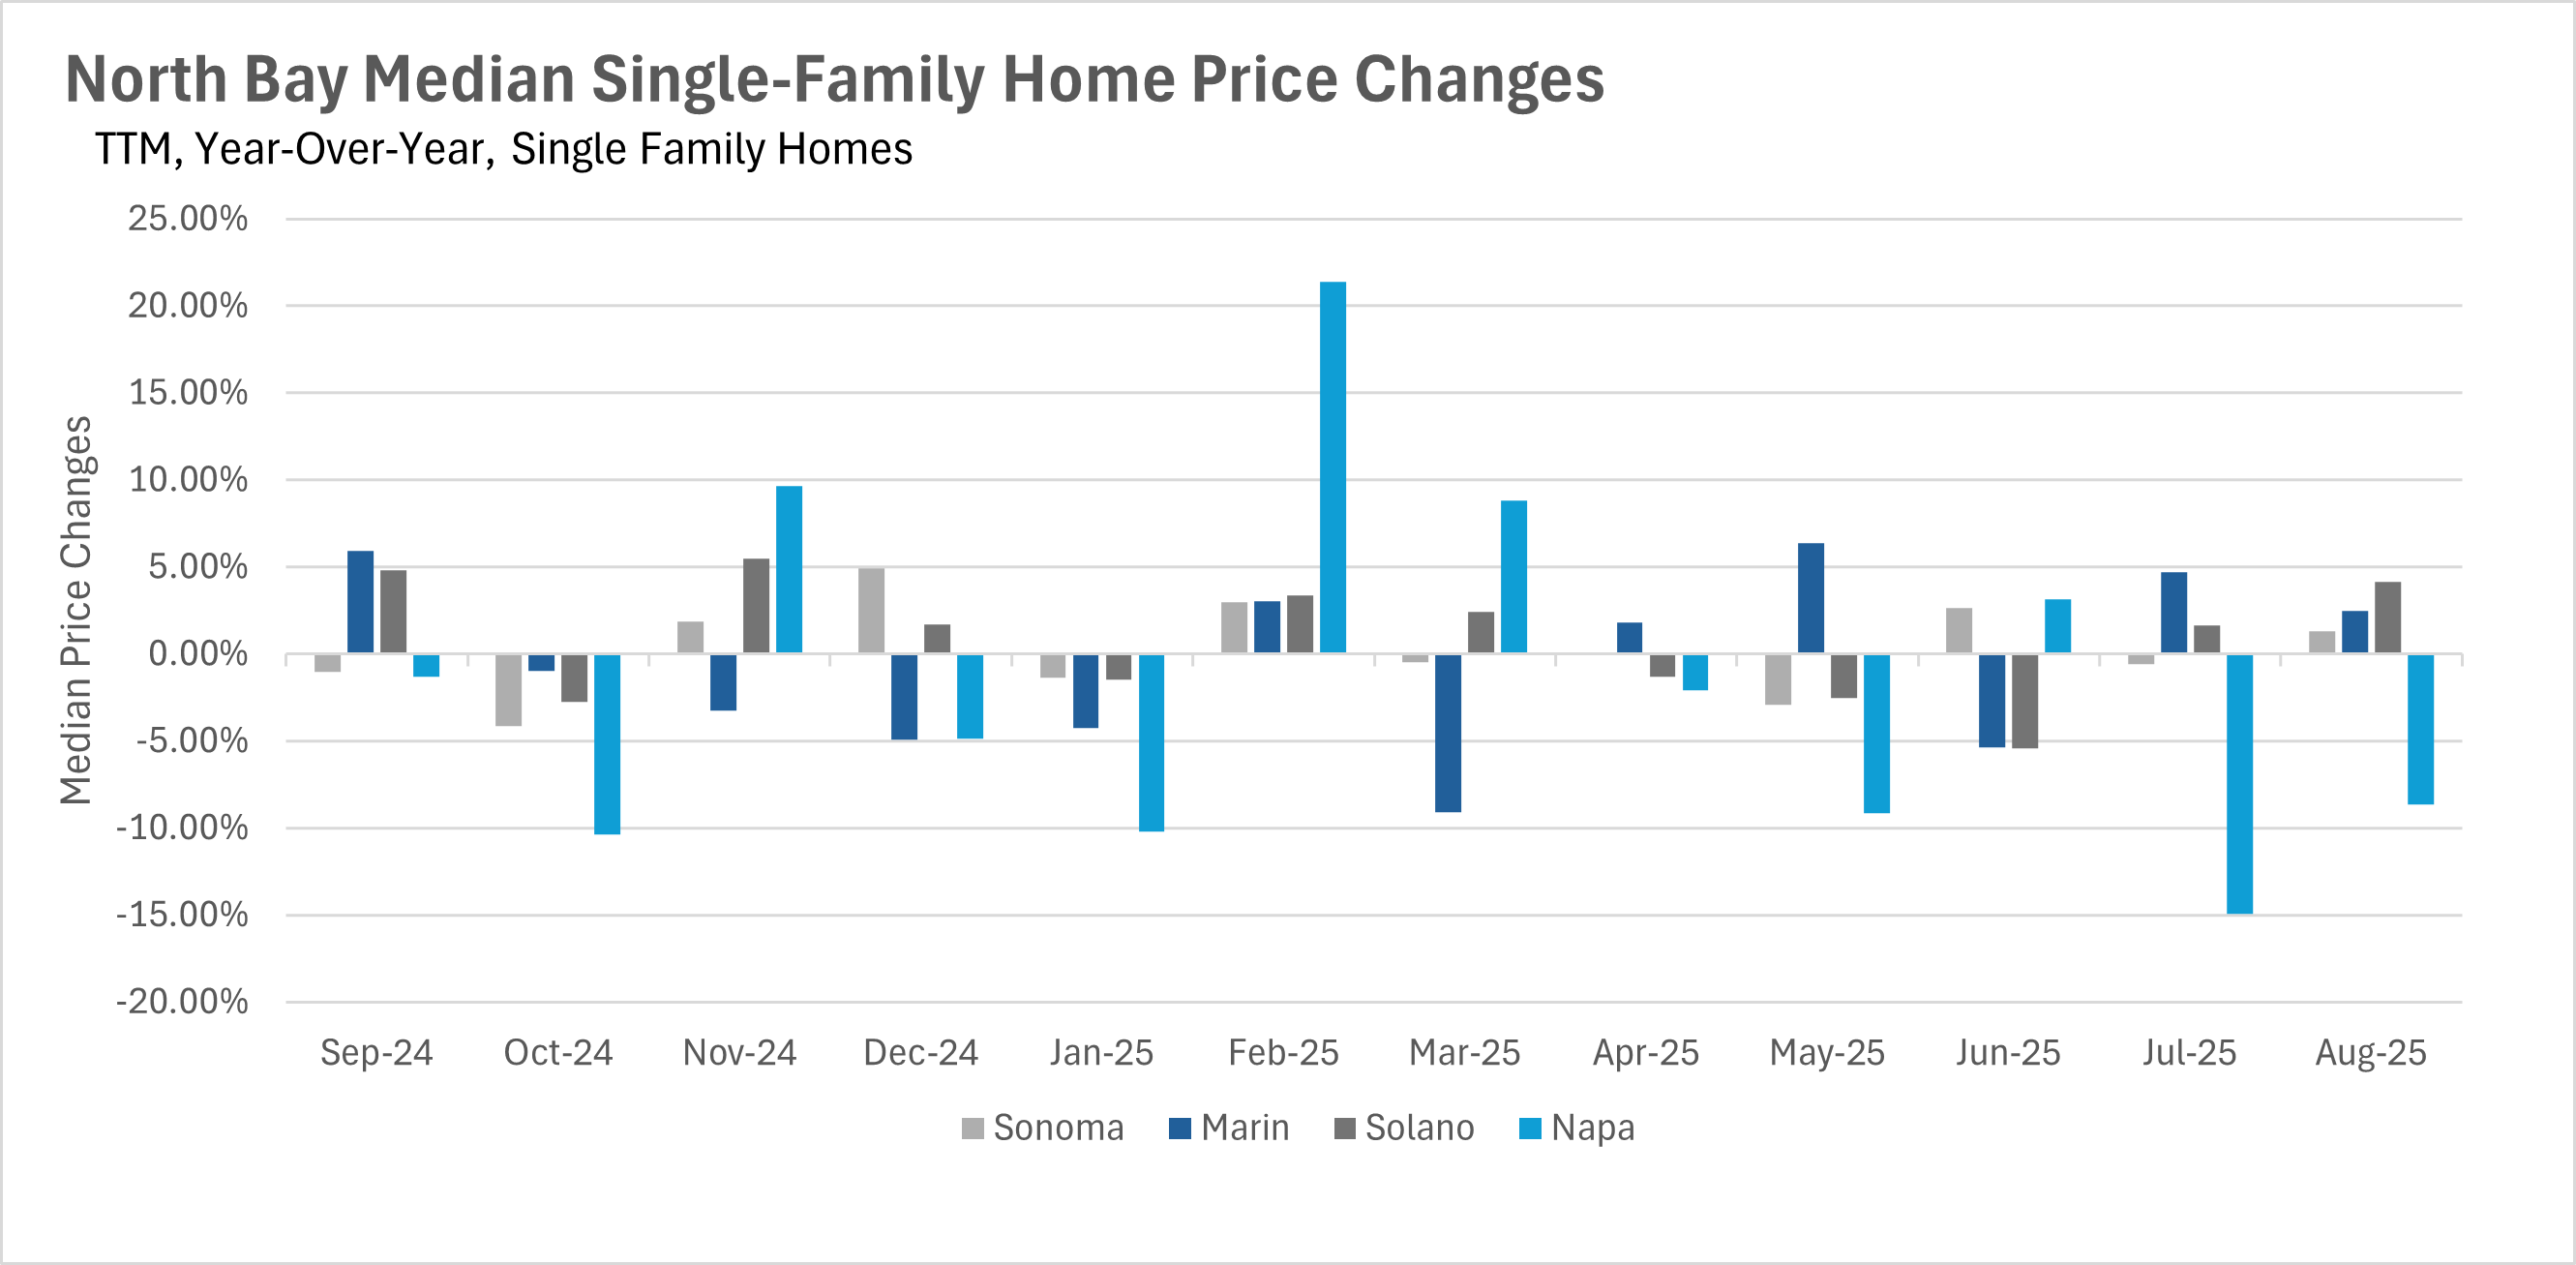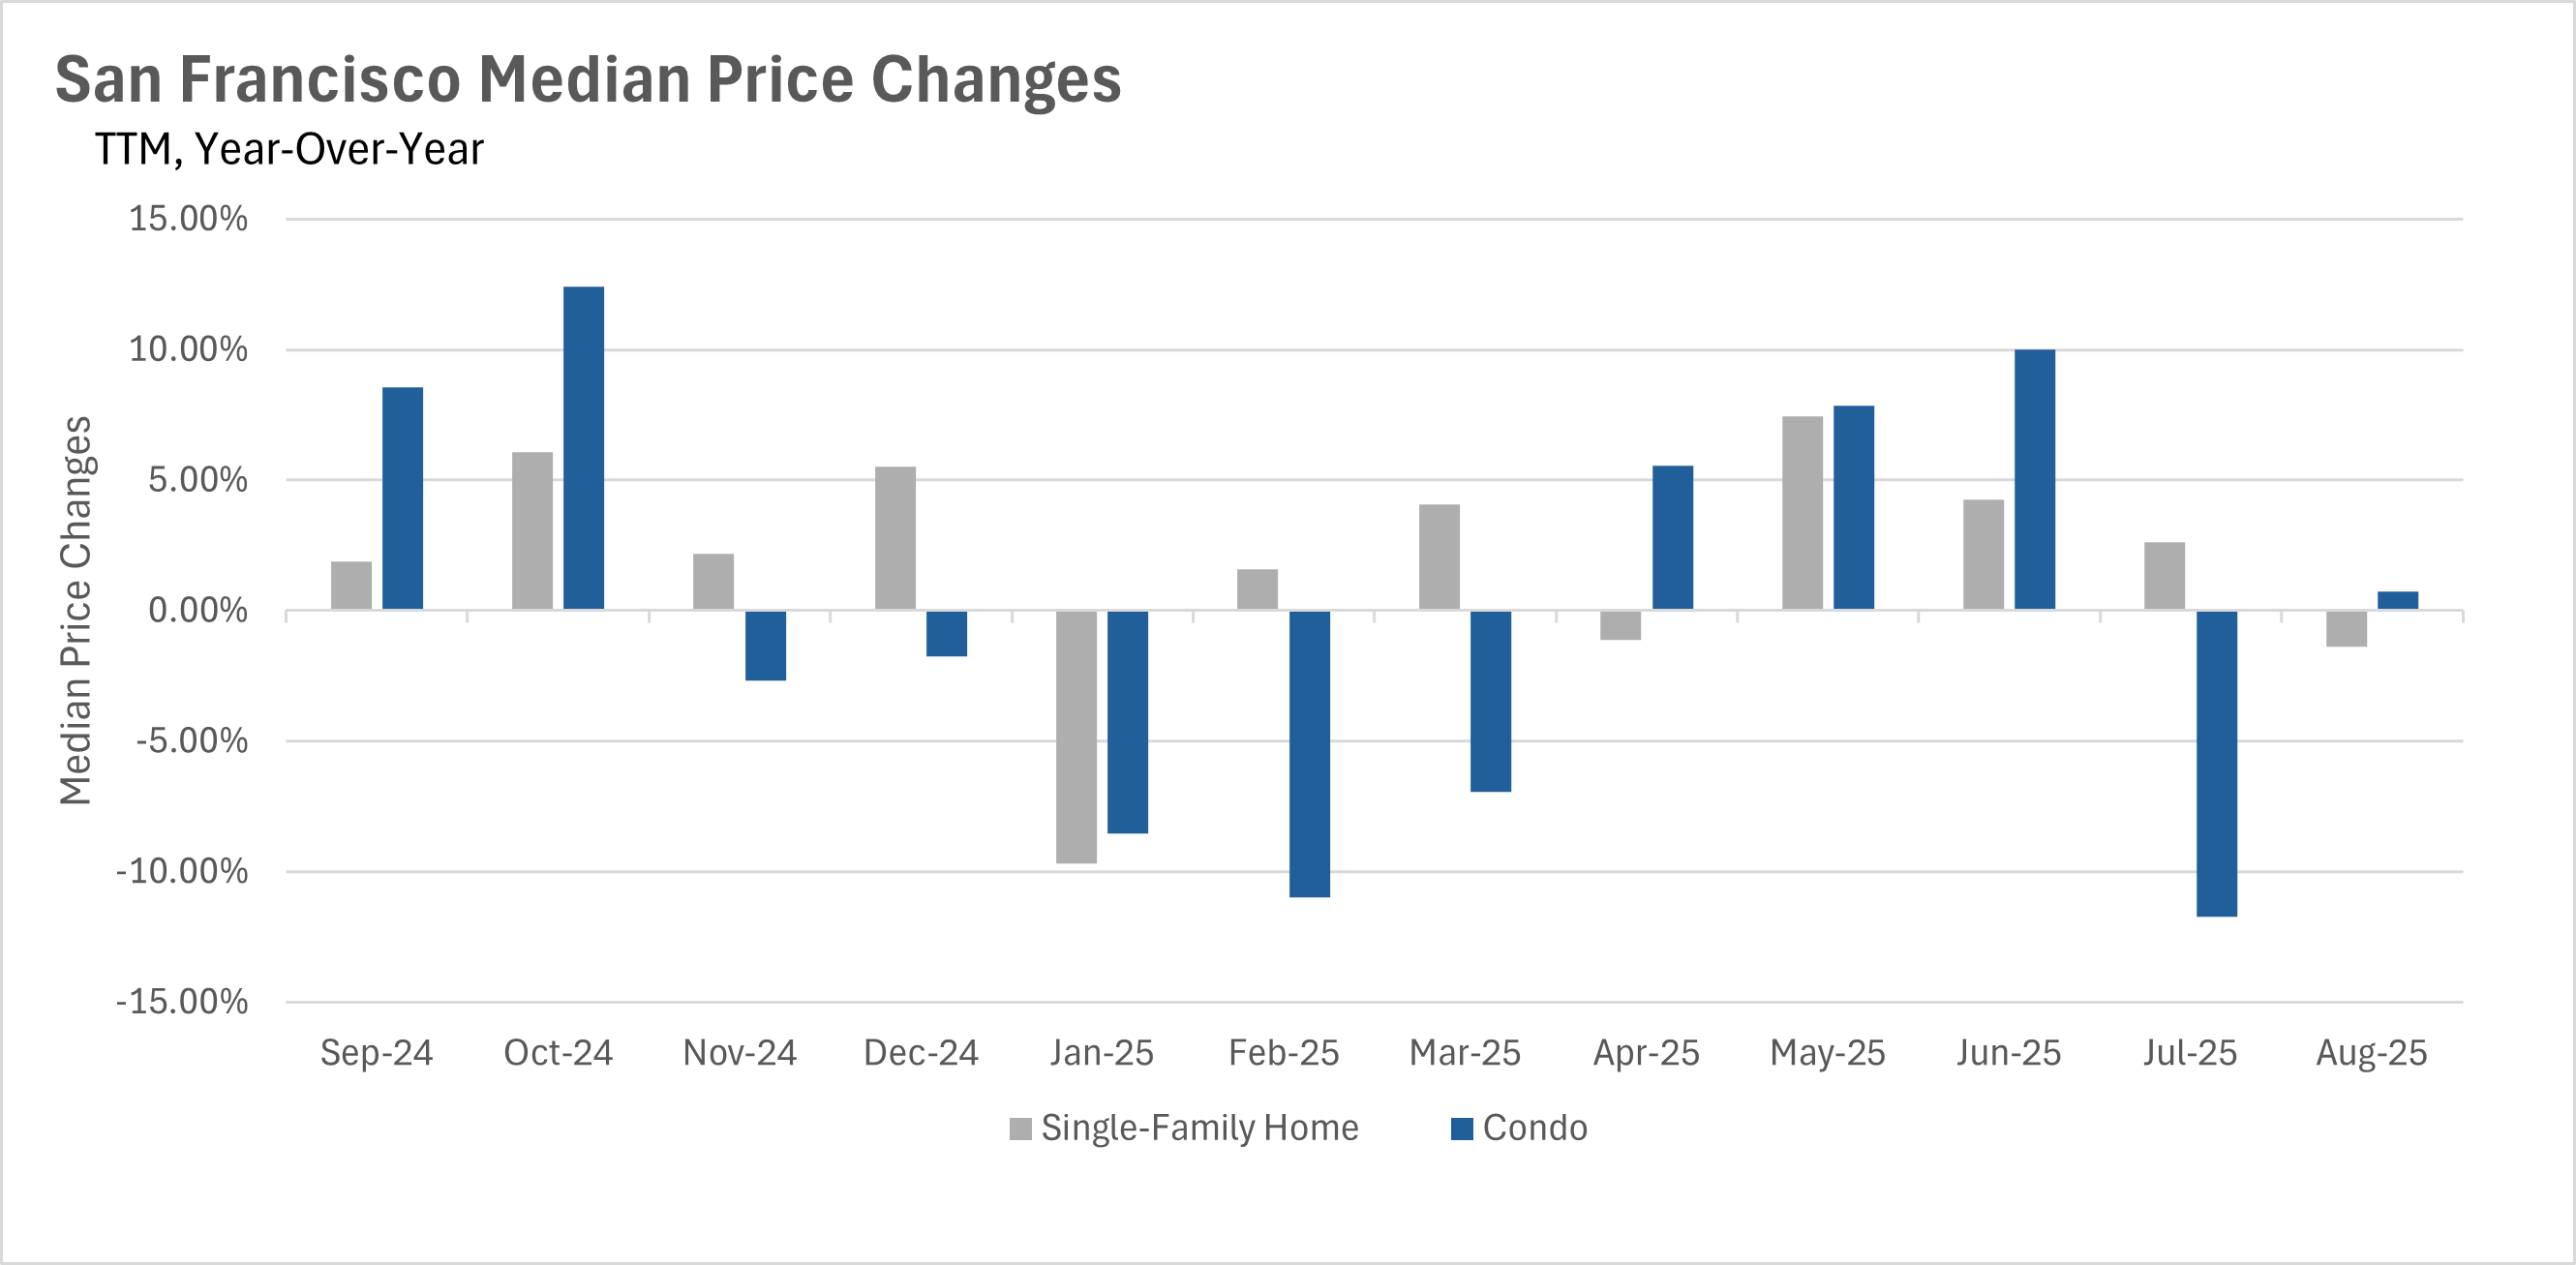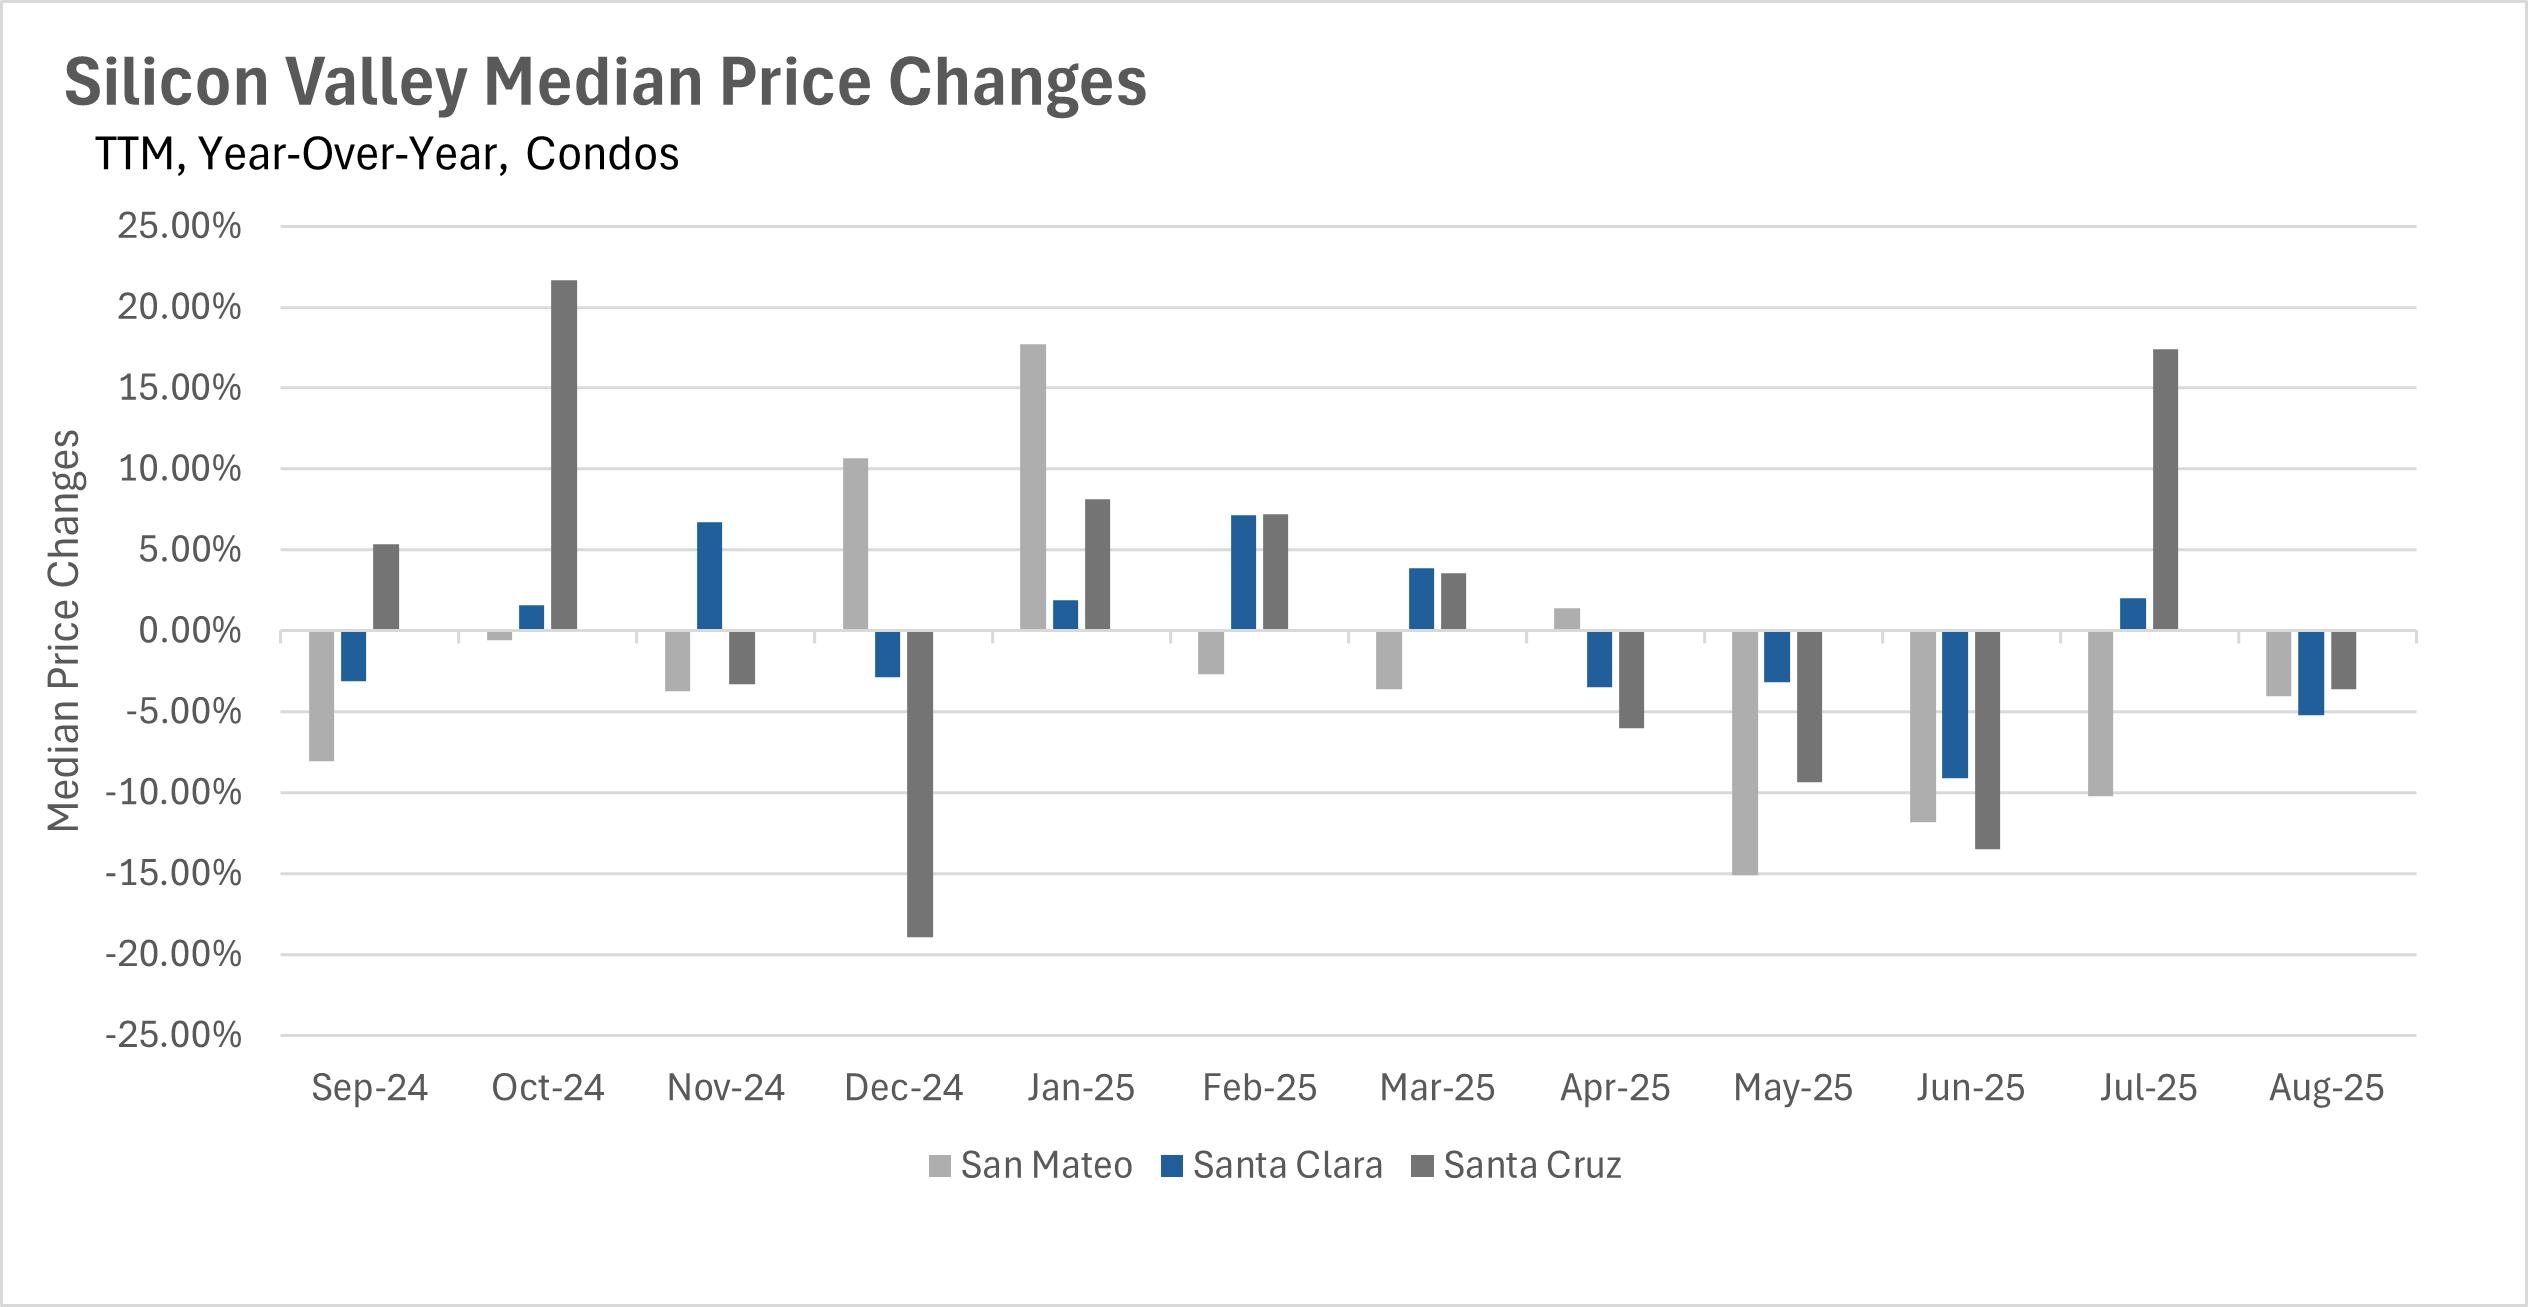Existing home sales remain slightly higher than they...
Greater Bay Area market update


The Big Story
Quick Take:
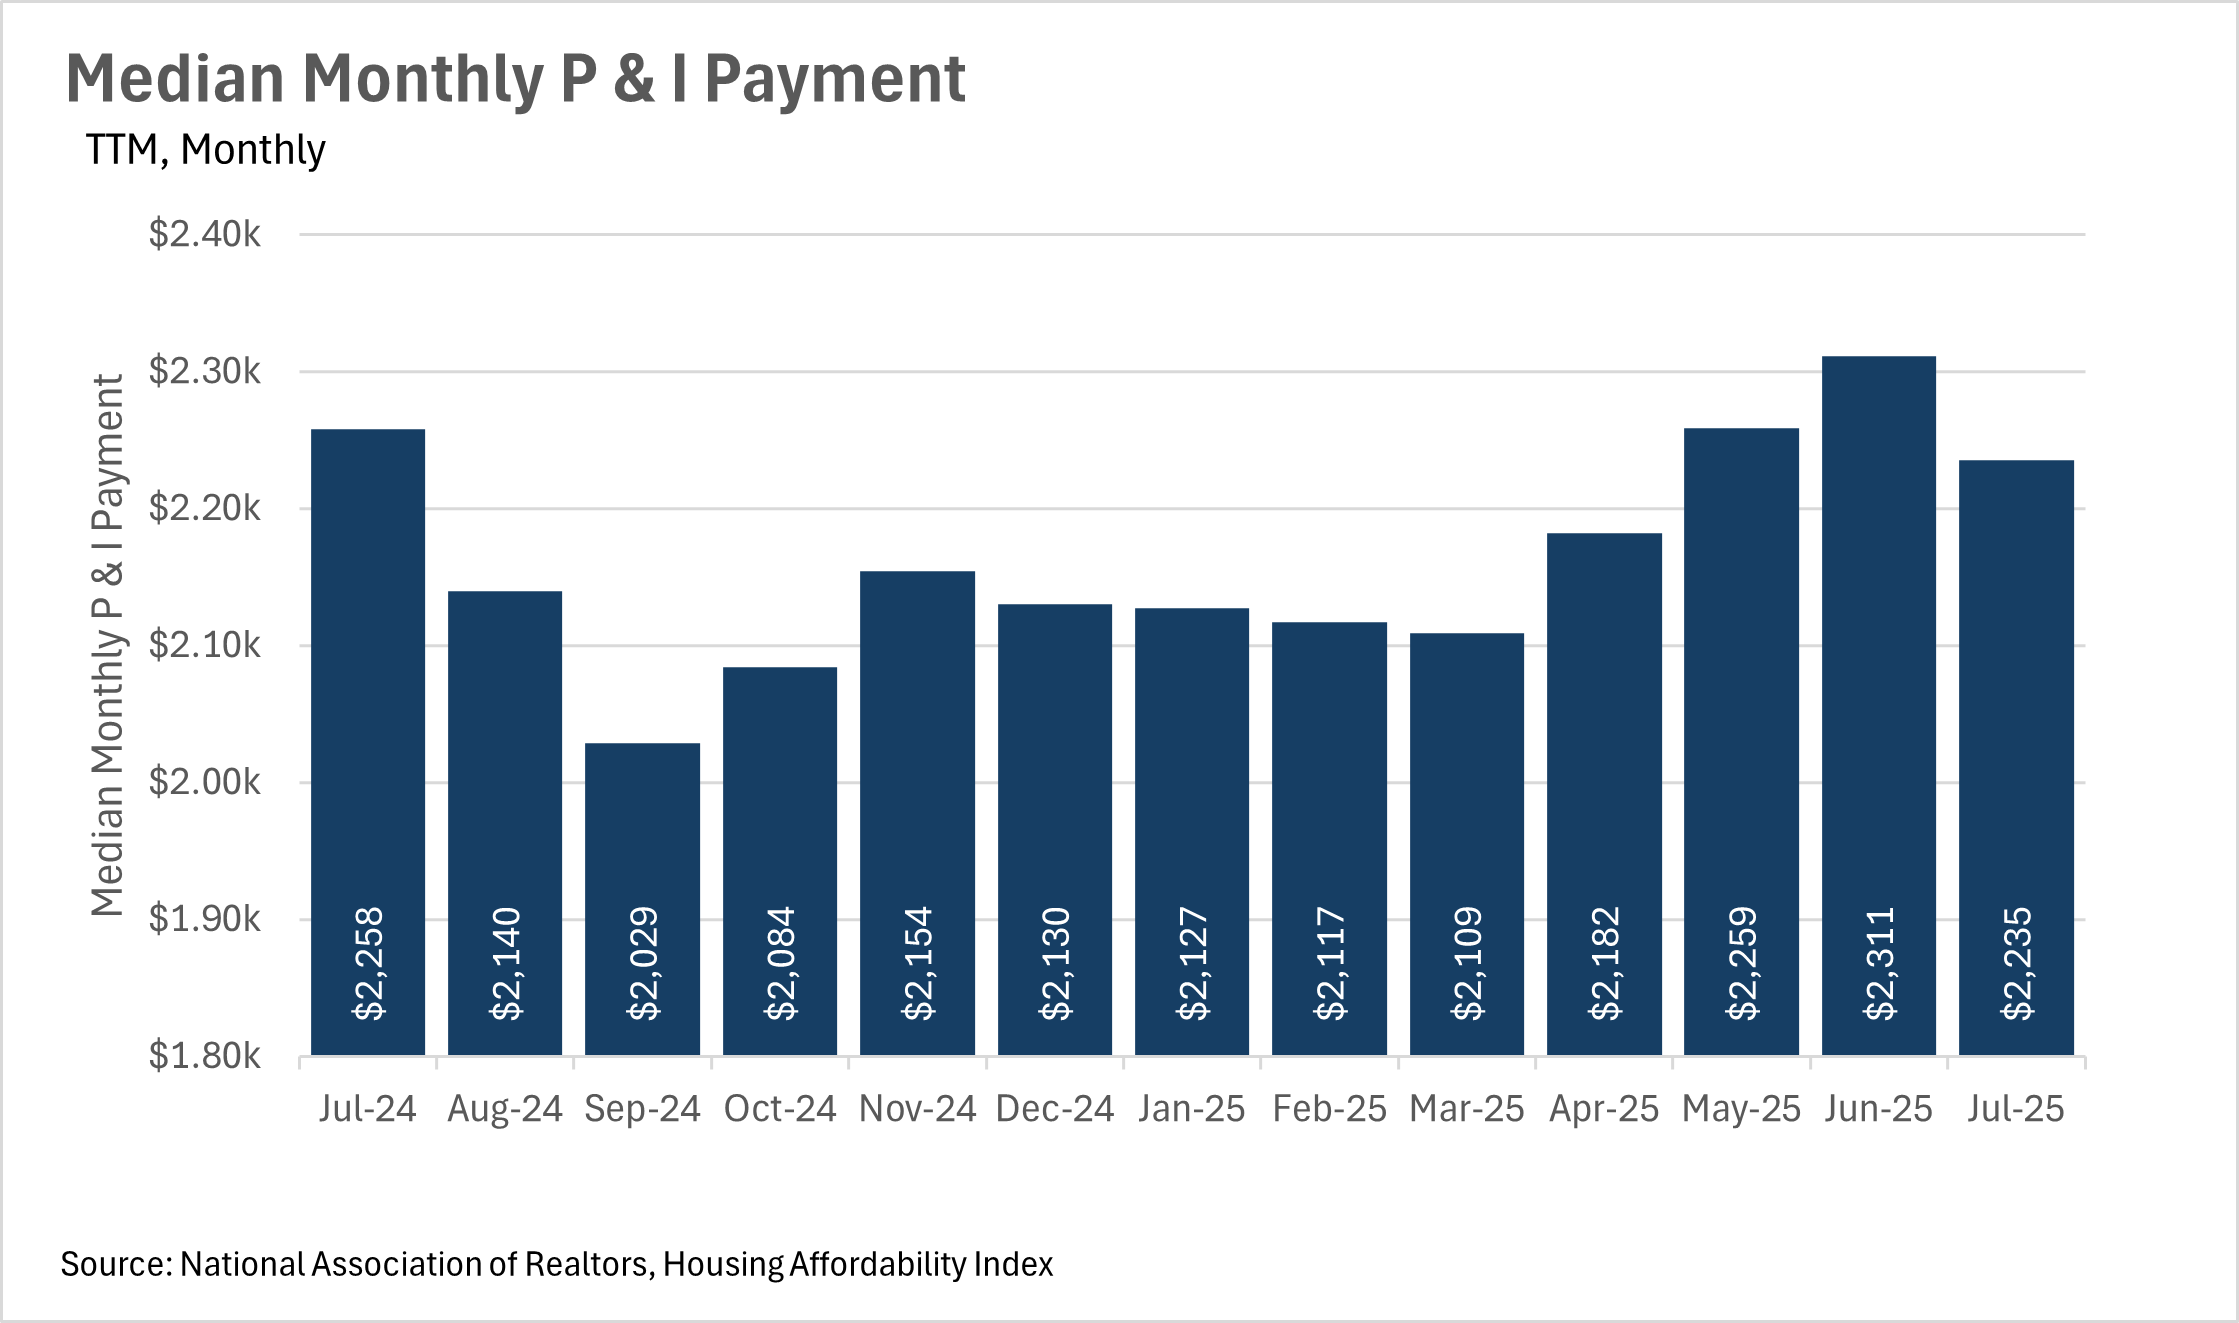
  • Median monthly principal and interest payments remain near the highest levels we’ve seen in the past year.
  • Mortgage rates have begun to drop, as we near the highly anticipated rate cut from the Federal Reserve.
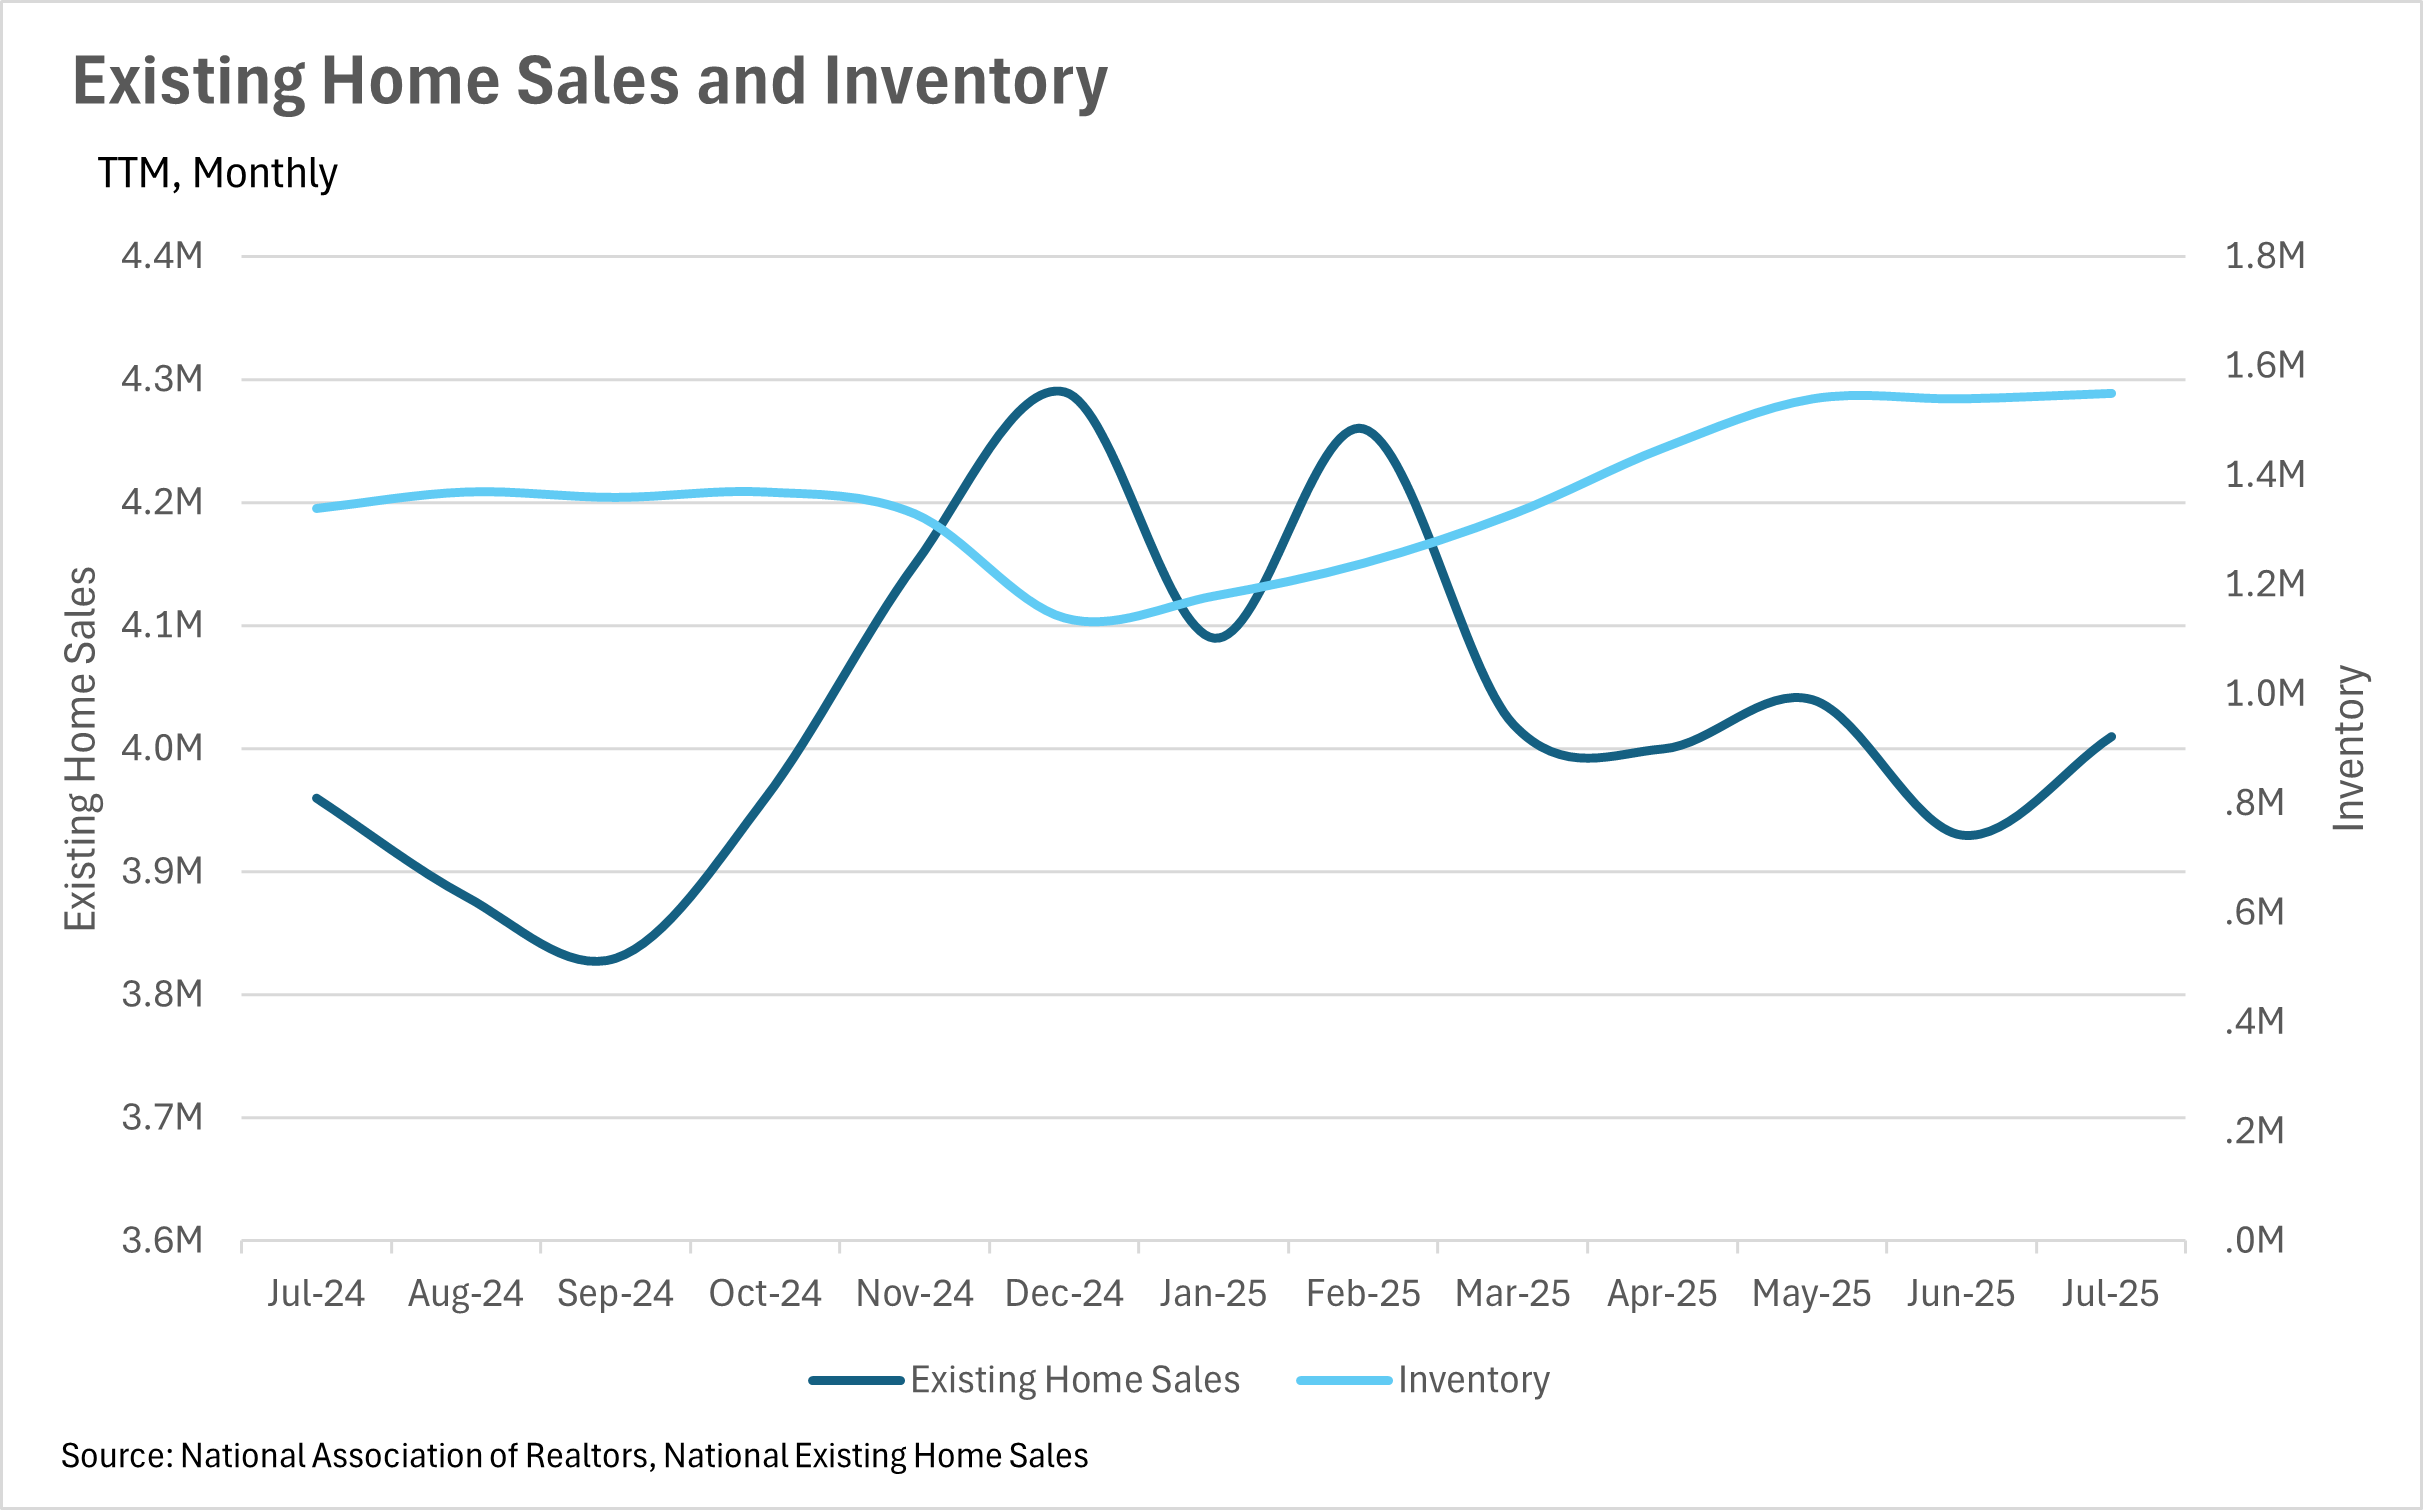
  • Existing home sales remain slightly higher than they were last year, while we observe nearly a 16% year-over-year increase in available inventory.
  • We may see rates start to drop sooner rather than later!
 
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
 
Median monthly payments remain high, for now
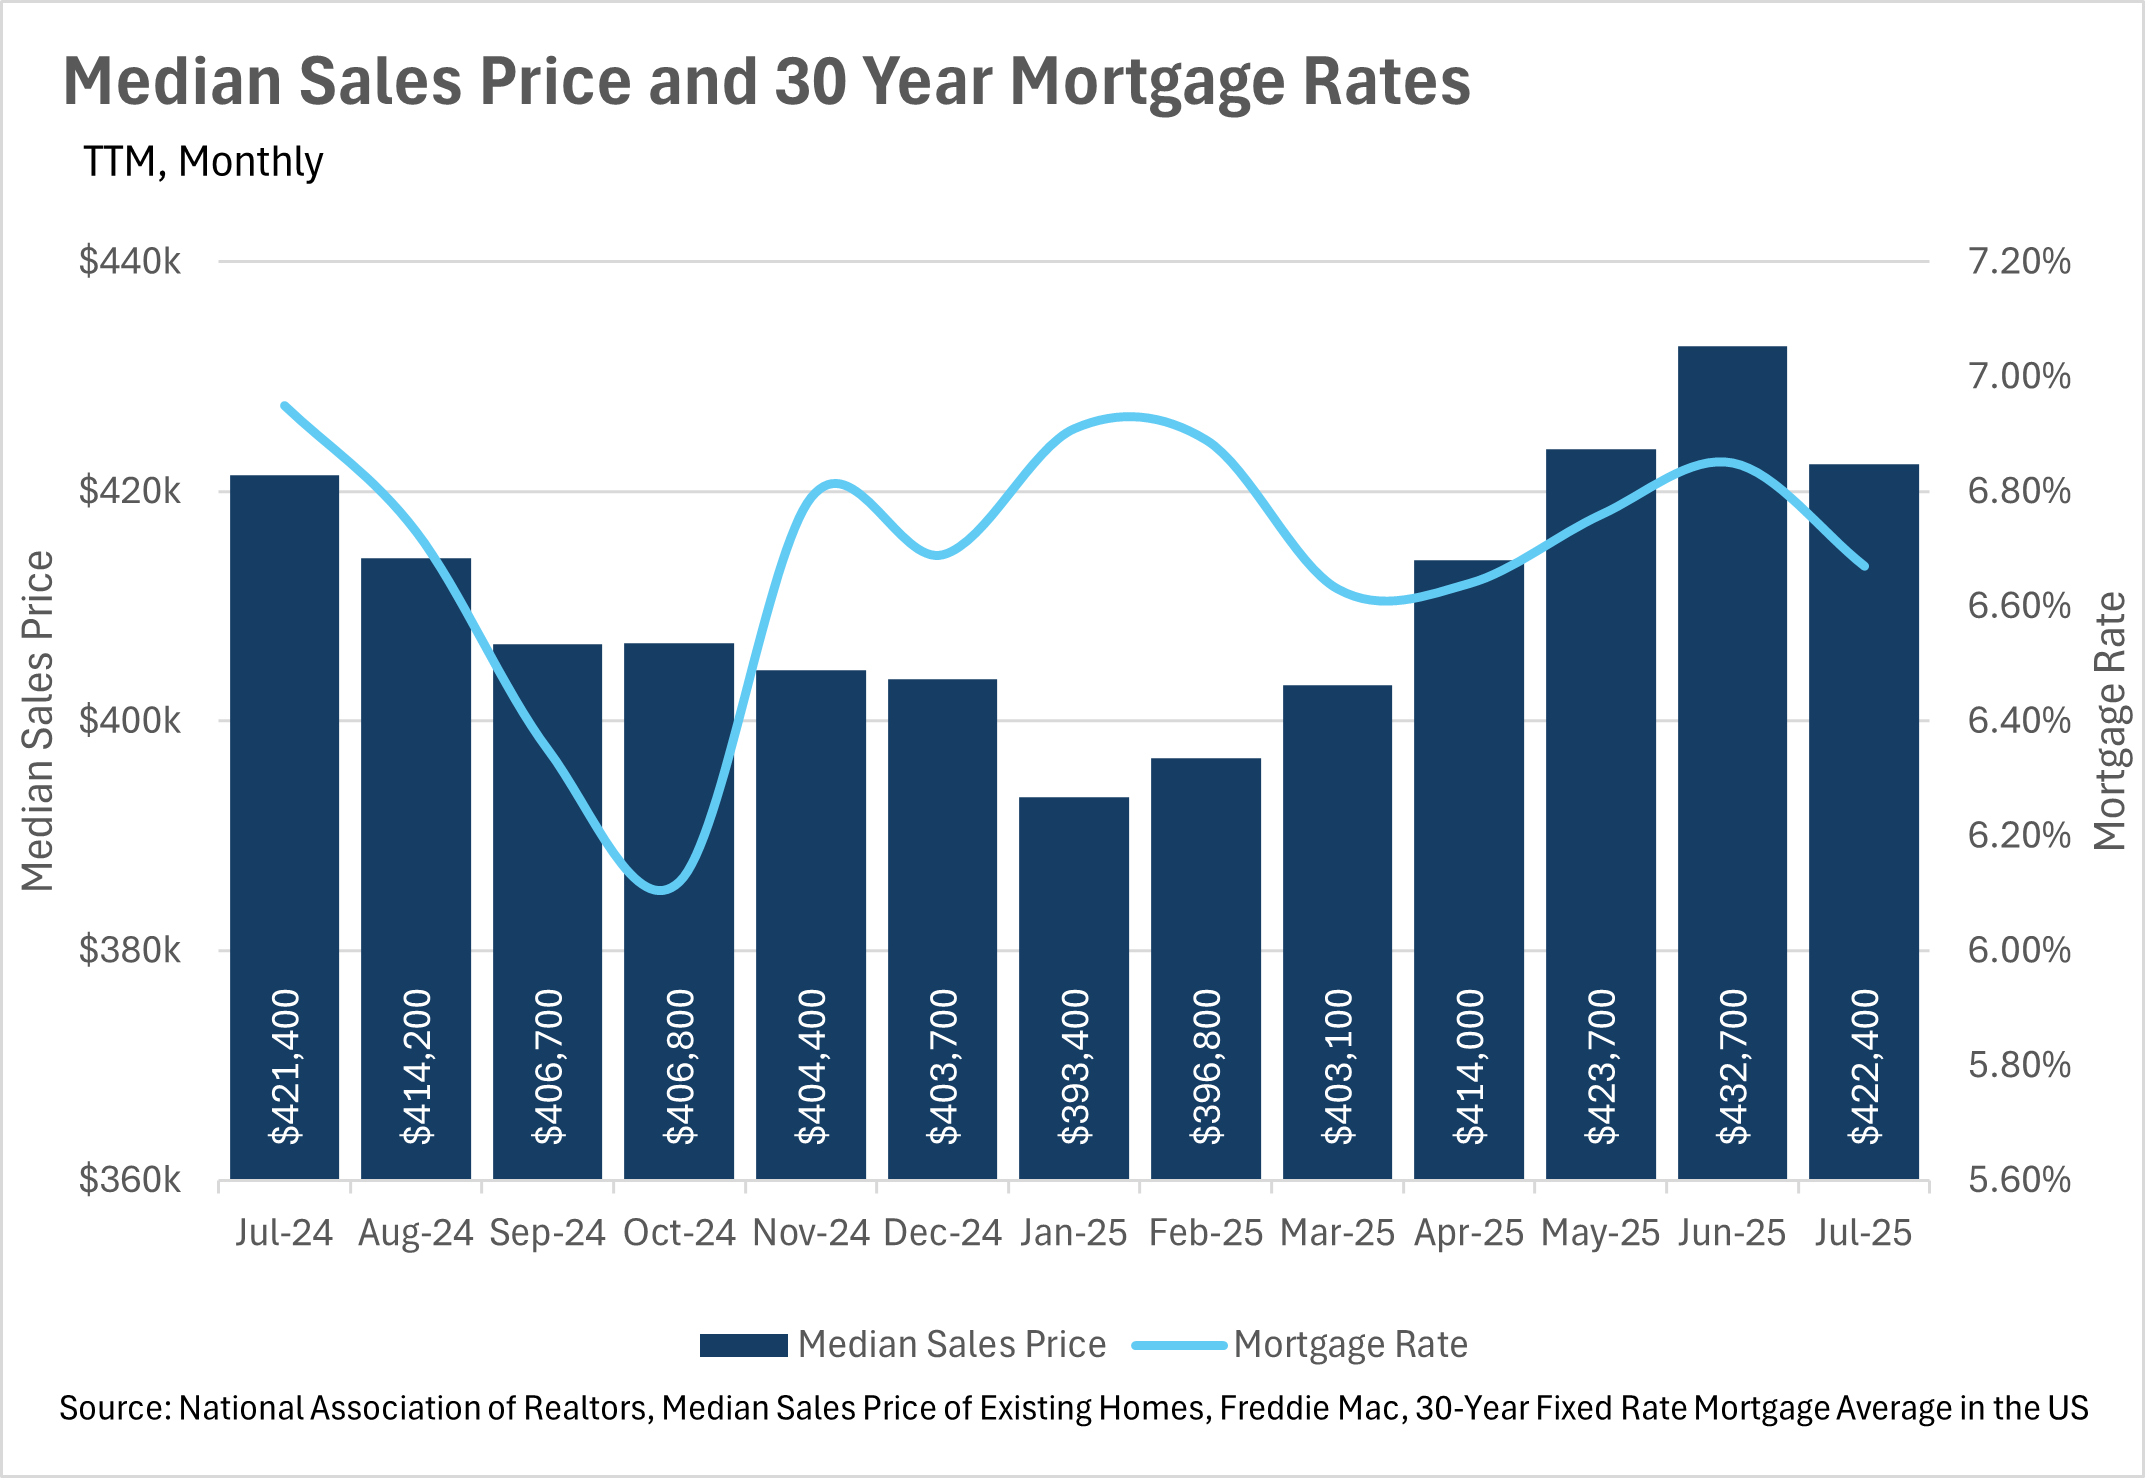
At $2,235 per month in principal and interest payments for the median homeowner, housing costs are near the highest points we’ve seen in the last year. As we all know, this is driven primarily by the fact that interest rates have remained high for quite some time, and home prices have not fallen by much over the past few years. However, existing homeowners might be able to save some money in the coming years/months, as Federal Reserve Chairman Jerome Powell mentioned in his speech at Jackson Hole that the Fed is keen on cutting rates in the near term. This, of course, would translate into lower P&I payments for new and existing homeowners alike.
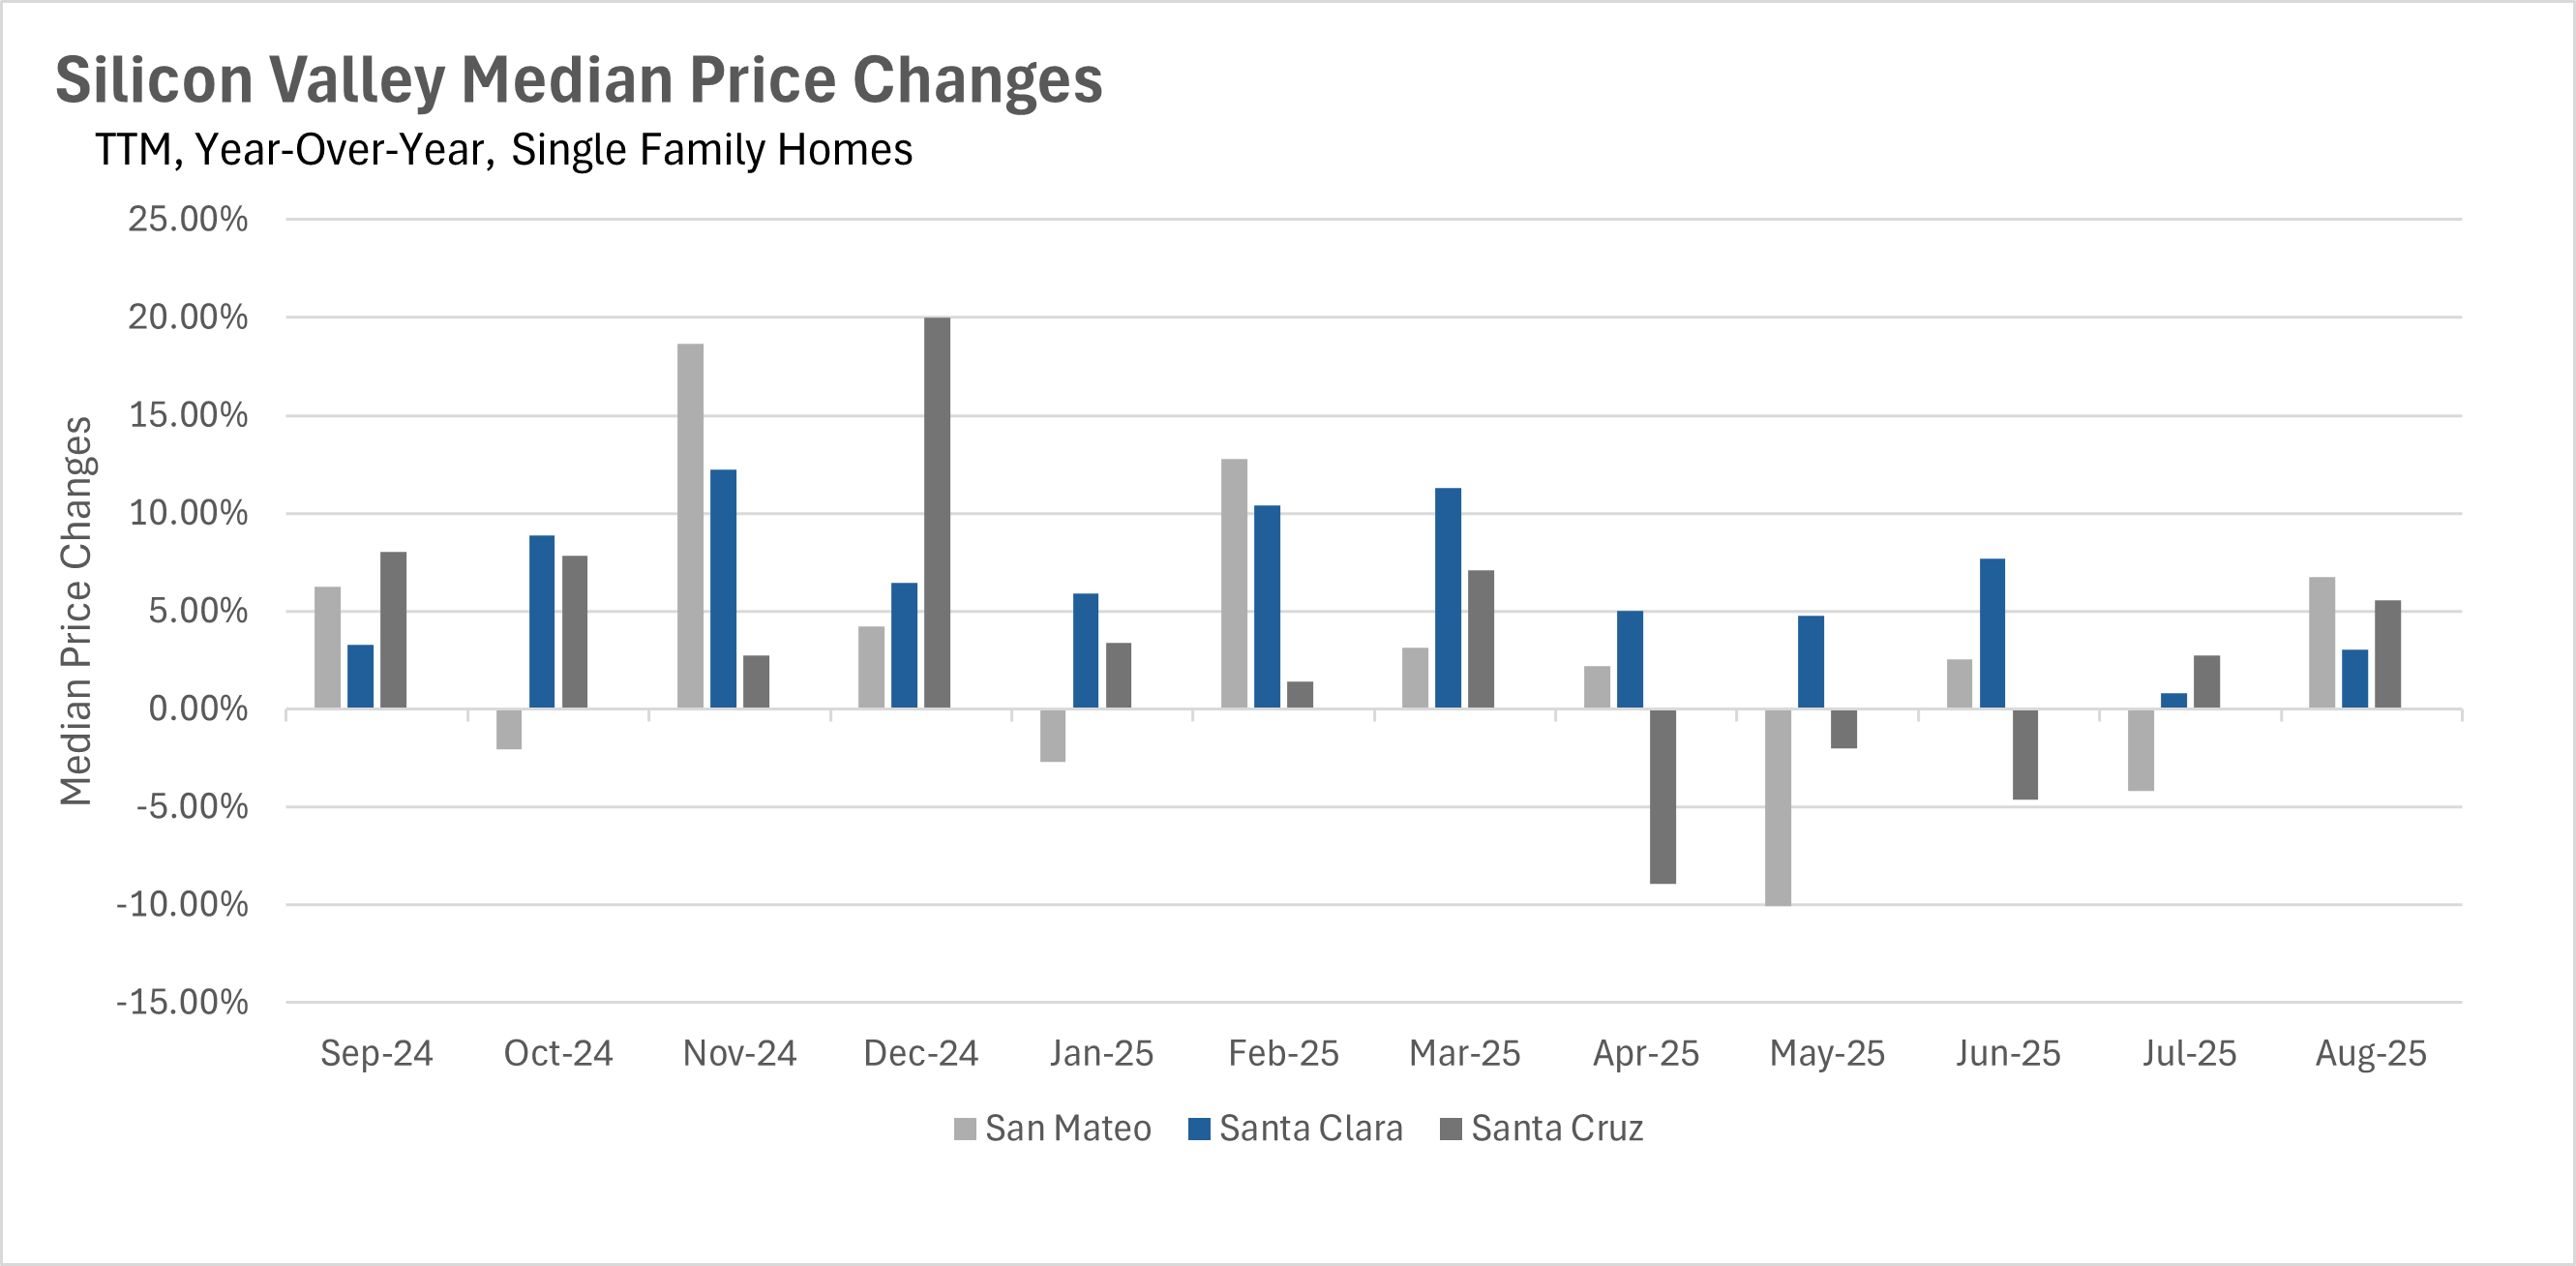
 
Are there rate cuts on the horizon?
As we mentioned in the previous section, the Fed Chairman mentioned in a speech at Jackson Hole that we’re likely to see cuts to the federal funds rate in the not-so-distant future, which would, of course, be great for the largely stagnant housing market that we’ve been in recent months/years. For prospective buyers, now might be a great time to lock in a great home at a relatively low price. If real estate values perform the same way as the last time we saw substantial decreases to mortgage rates, now might be an opportune time to lock in a home before values surge, then refinance once rates have bottomed out!
Mortgage rates have already started to decrease a bit
Although mortgage rates were in the mid to high-6% range throughout July and August, they’ve started to come down since the Fed Chairman’s speech. At the time of writing this newsletter, the average mortgage rate was 6.35%, according to Freddie Mac. Although this likely represents the market pricing in the rate cut before it even happens, if the Fed is entering a rate-cutting cycle, then there will be more rate cuts to come. If you want to keep an eye on where mortgage rates are going, then it’s particularly important to pay attention to any commentary out of the Fed, as well as economic data that’s published surrounding employment and inflation, as the mandate of the Fed is to control inflation and promote healthy employment.
Inventories are relatively high right now, but we might see that change in the near future
Over the course of the past few months, we’ve seen inventories remain at an elevated level on a year-over-year basis. However, with the recent drop in interest rates and the prospect of lower interest rates in the near-term future, we might see some of the built-up inventory begin to move, as housing becomes more affordable. Over the coming months, it’ll be important to pay attention to inventory levels, as they’re often leading indicators of price movements over time!
 
It’s important to note, though, that all of this is just what we’re seeing at a national level. To learn more about your local market, be sure to check out the Local Lowdown below:
Big Story Data
Line chart of existing home sales and inventory from July 2024 to July 2025; inventory rises as sales fluctuate.
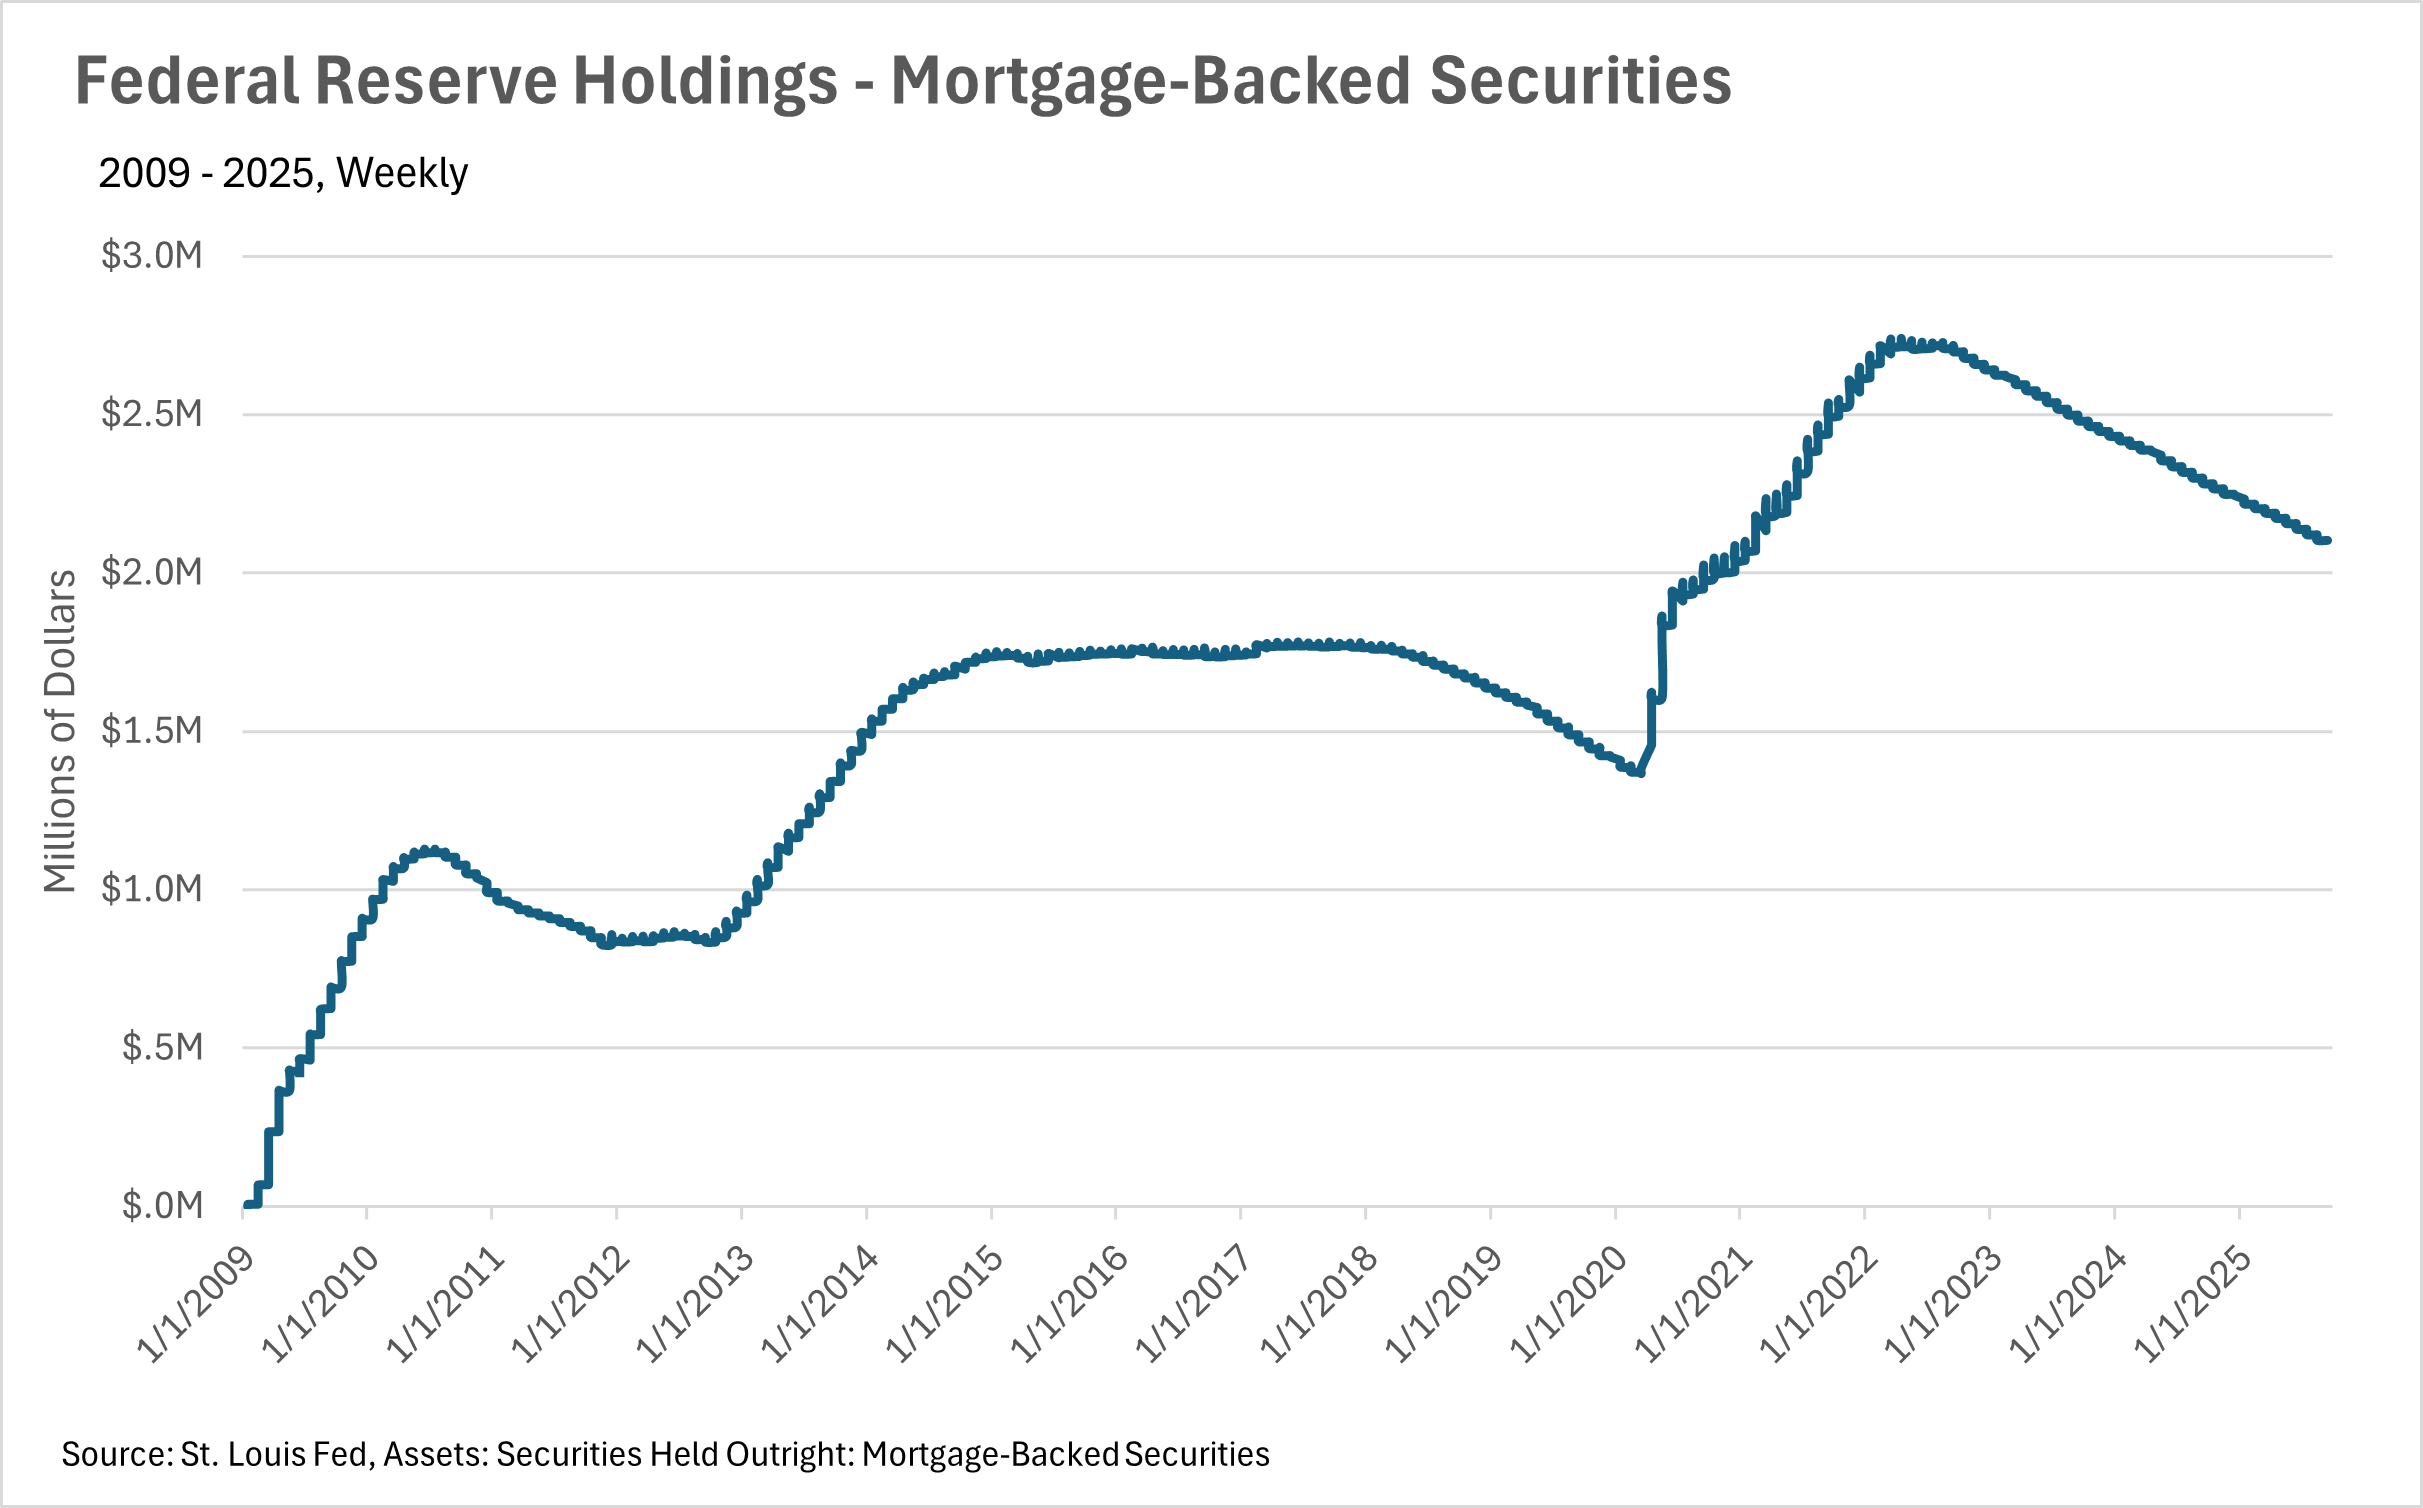
Chart of Federal Reserve mortgage-backed securities holdings, peaking in 2022 before declining through 2025.
Bar chart of median monthly principal and interest payments from July 2024 to July 2025.
Chart of monthly U.S. home sale prices and mortgage rates, July 2024–July 2025; prices peak in June 2025.
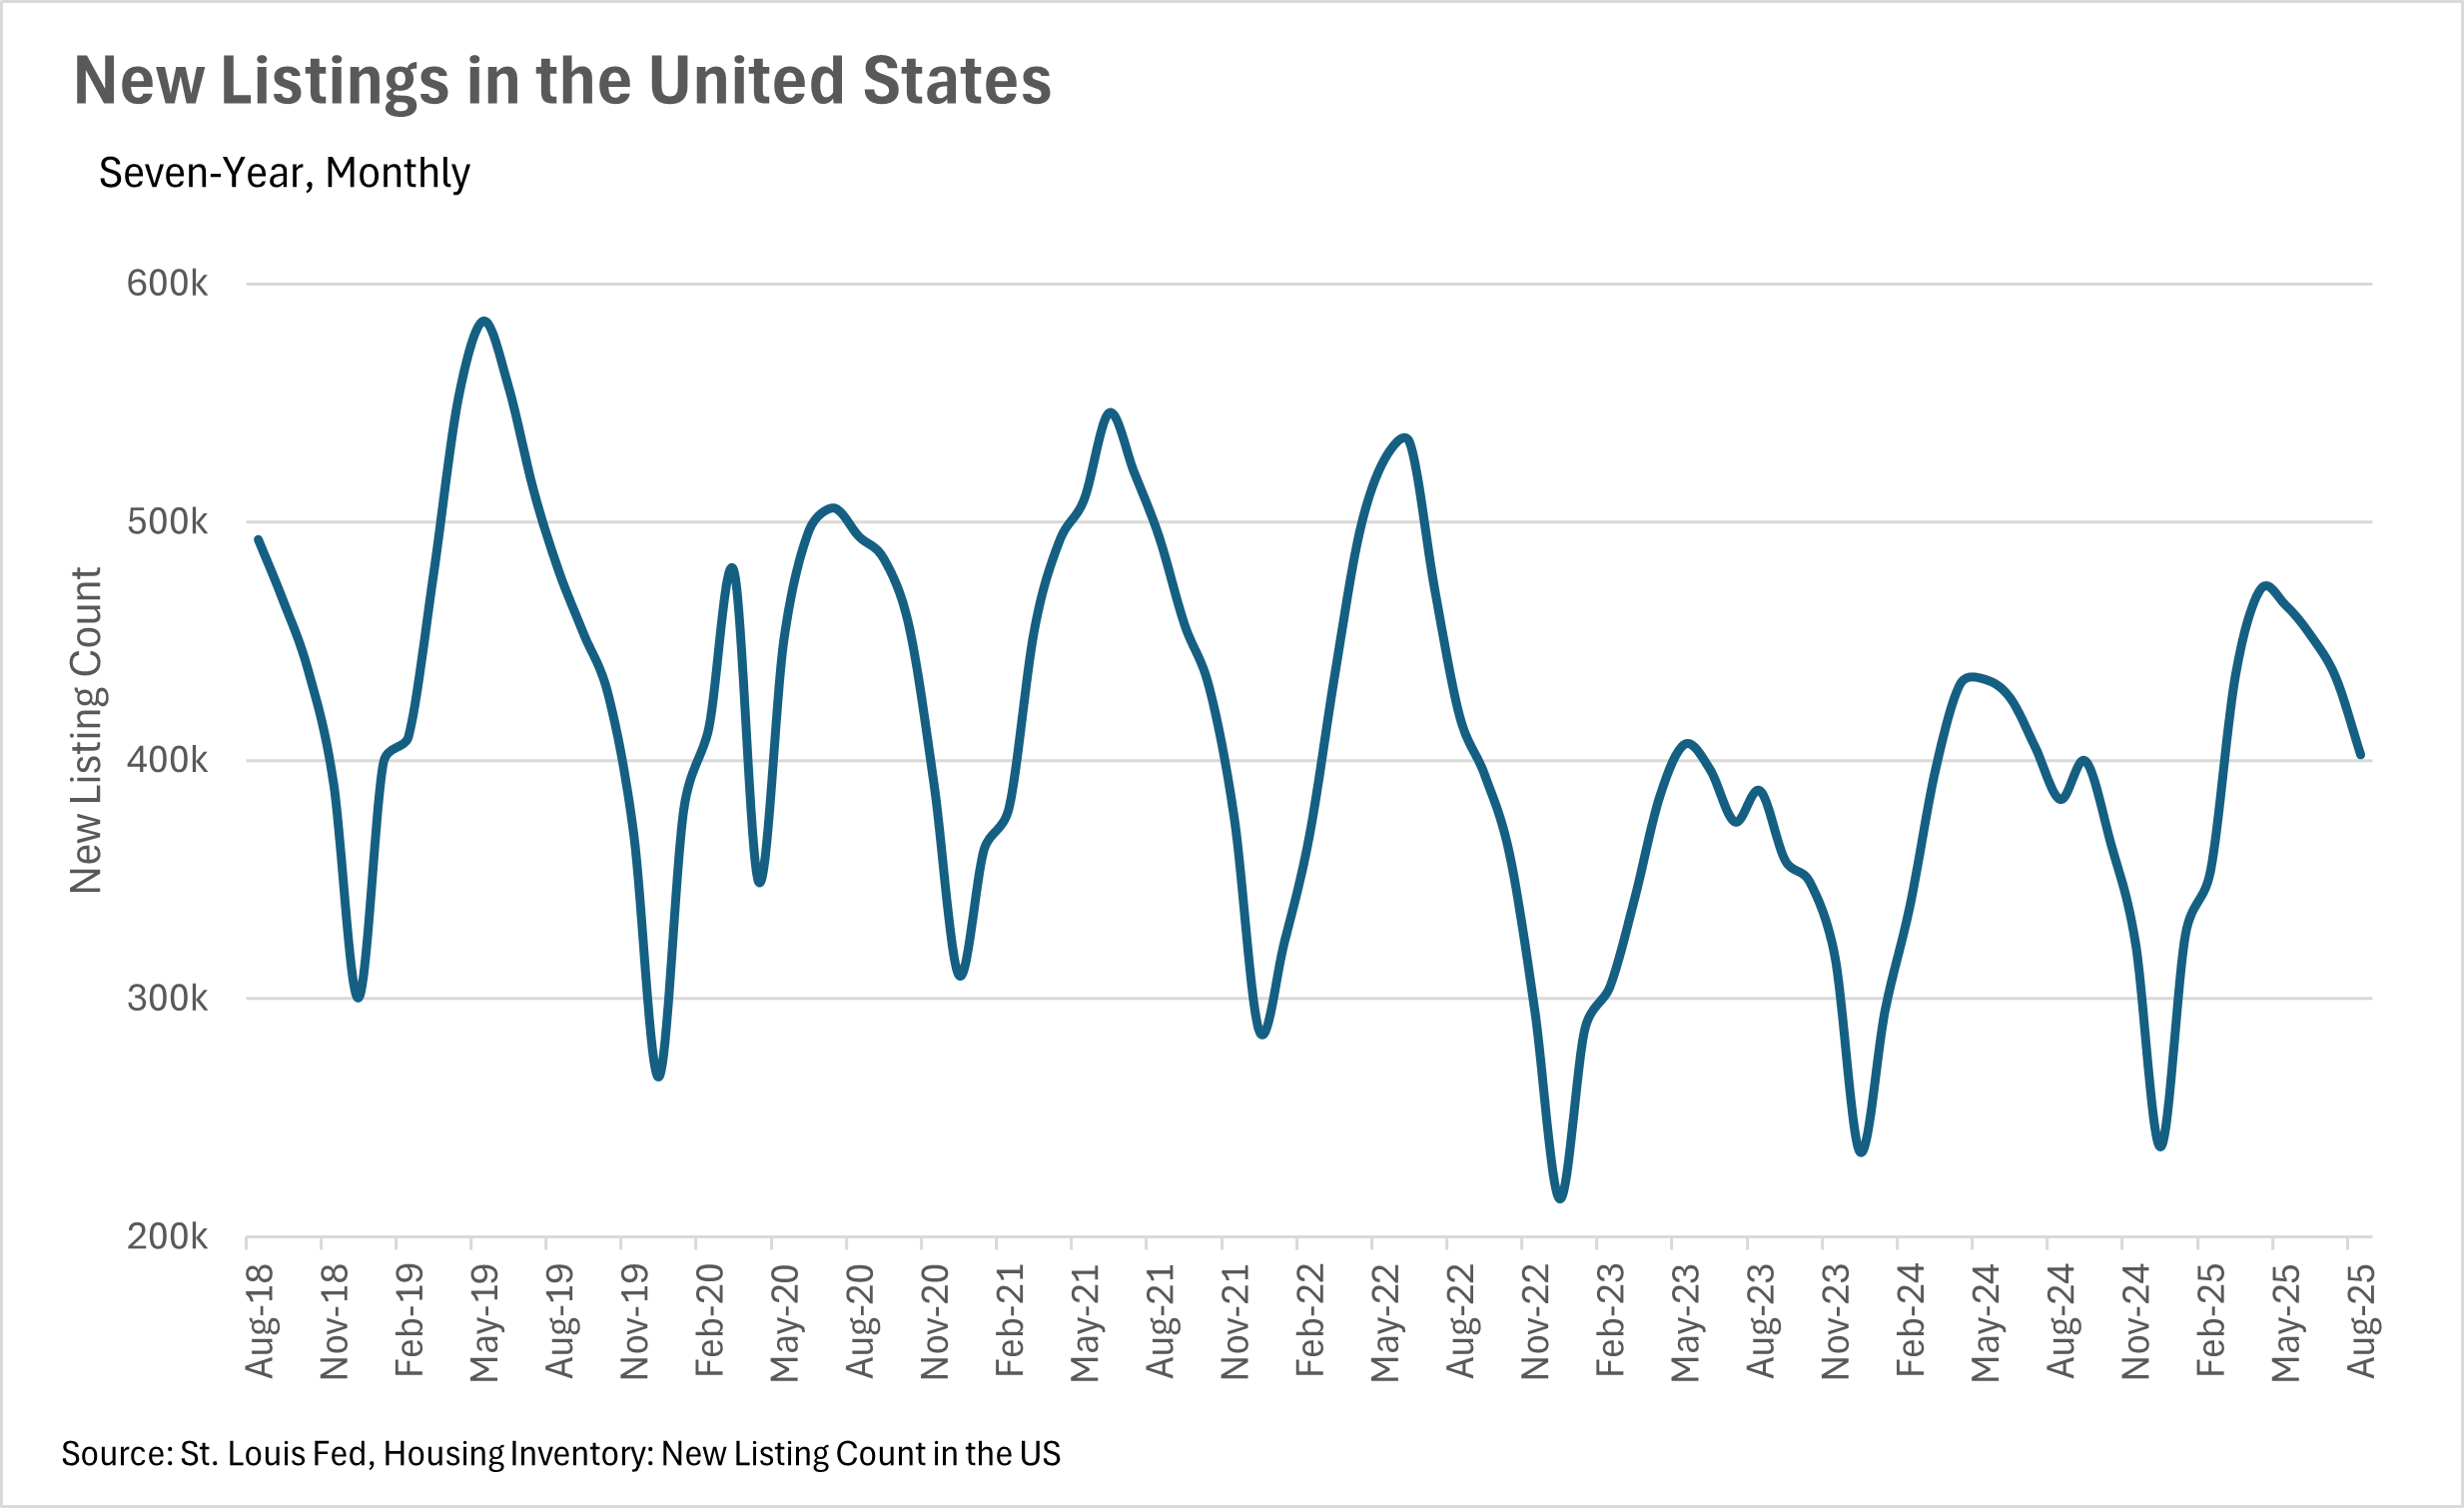
Line chart of U.S. new listings from August 2018 to August 2025, with recurring seasonal peaks and troughs.
The Local Lowdown
Quick Take:
  • August marked a turning point for Bay Area real estate, with single-family home prices rebounding in most regions while condo markets continue to struggle with volatility and declines.
  • Inventory levels are normalizing across the region after summer peaks, with San Francisco reaching some of the lowest supply levels ever recorded while other areas remain elevated year-over-year.
  • Despite inventory normalization, listings are spending significantly more time on market throughout most of the Bay Area, reflecting increased buyer selectivity.
  • Market dynamics strongly favor single-family homes over condos, with San Francisco becoming a dual seller's market while other regions maintain the traditional split between property types.
 
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Single-family home prices rebound while condo markets remain volatile
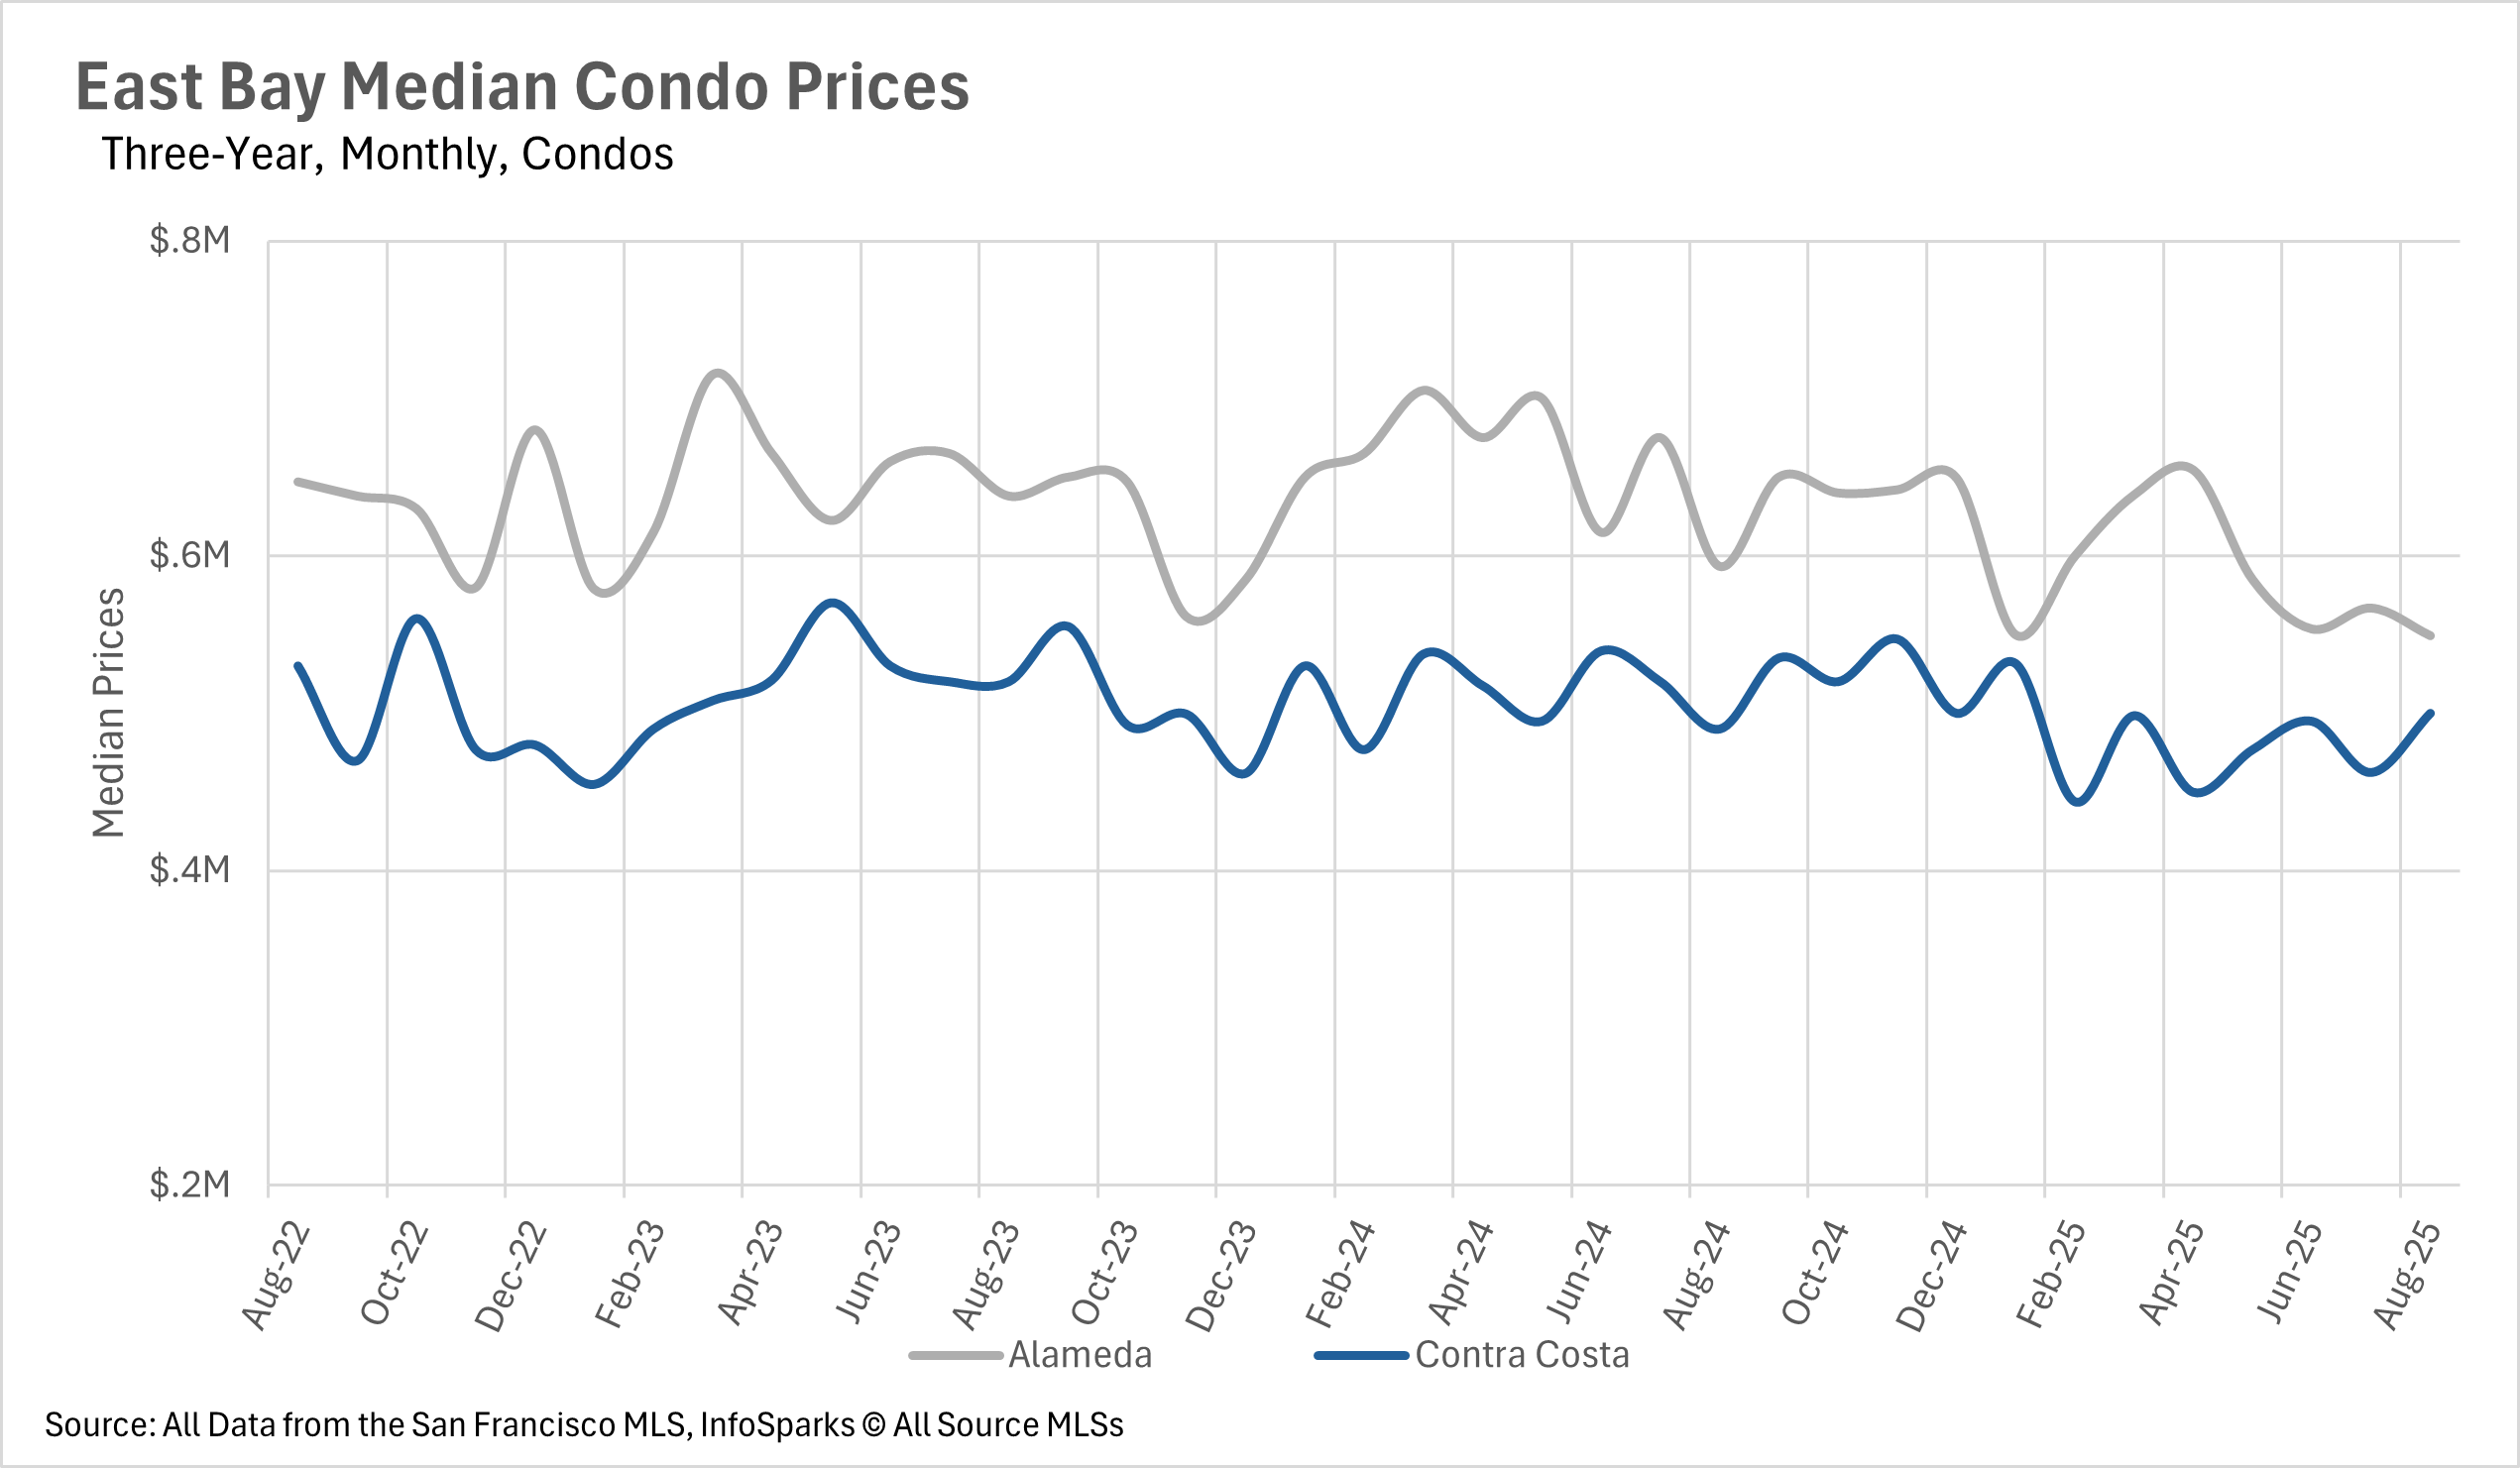
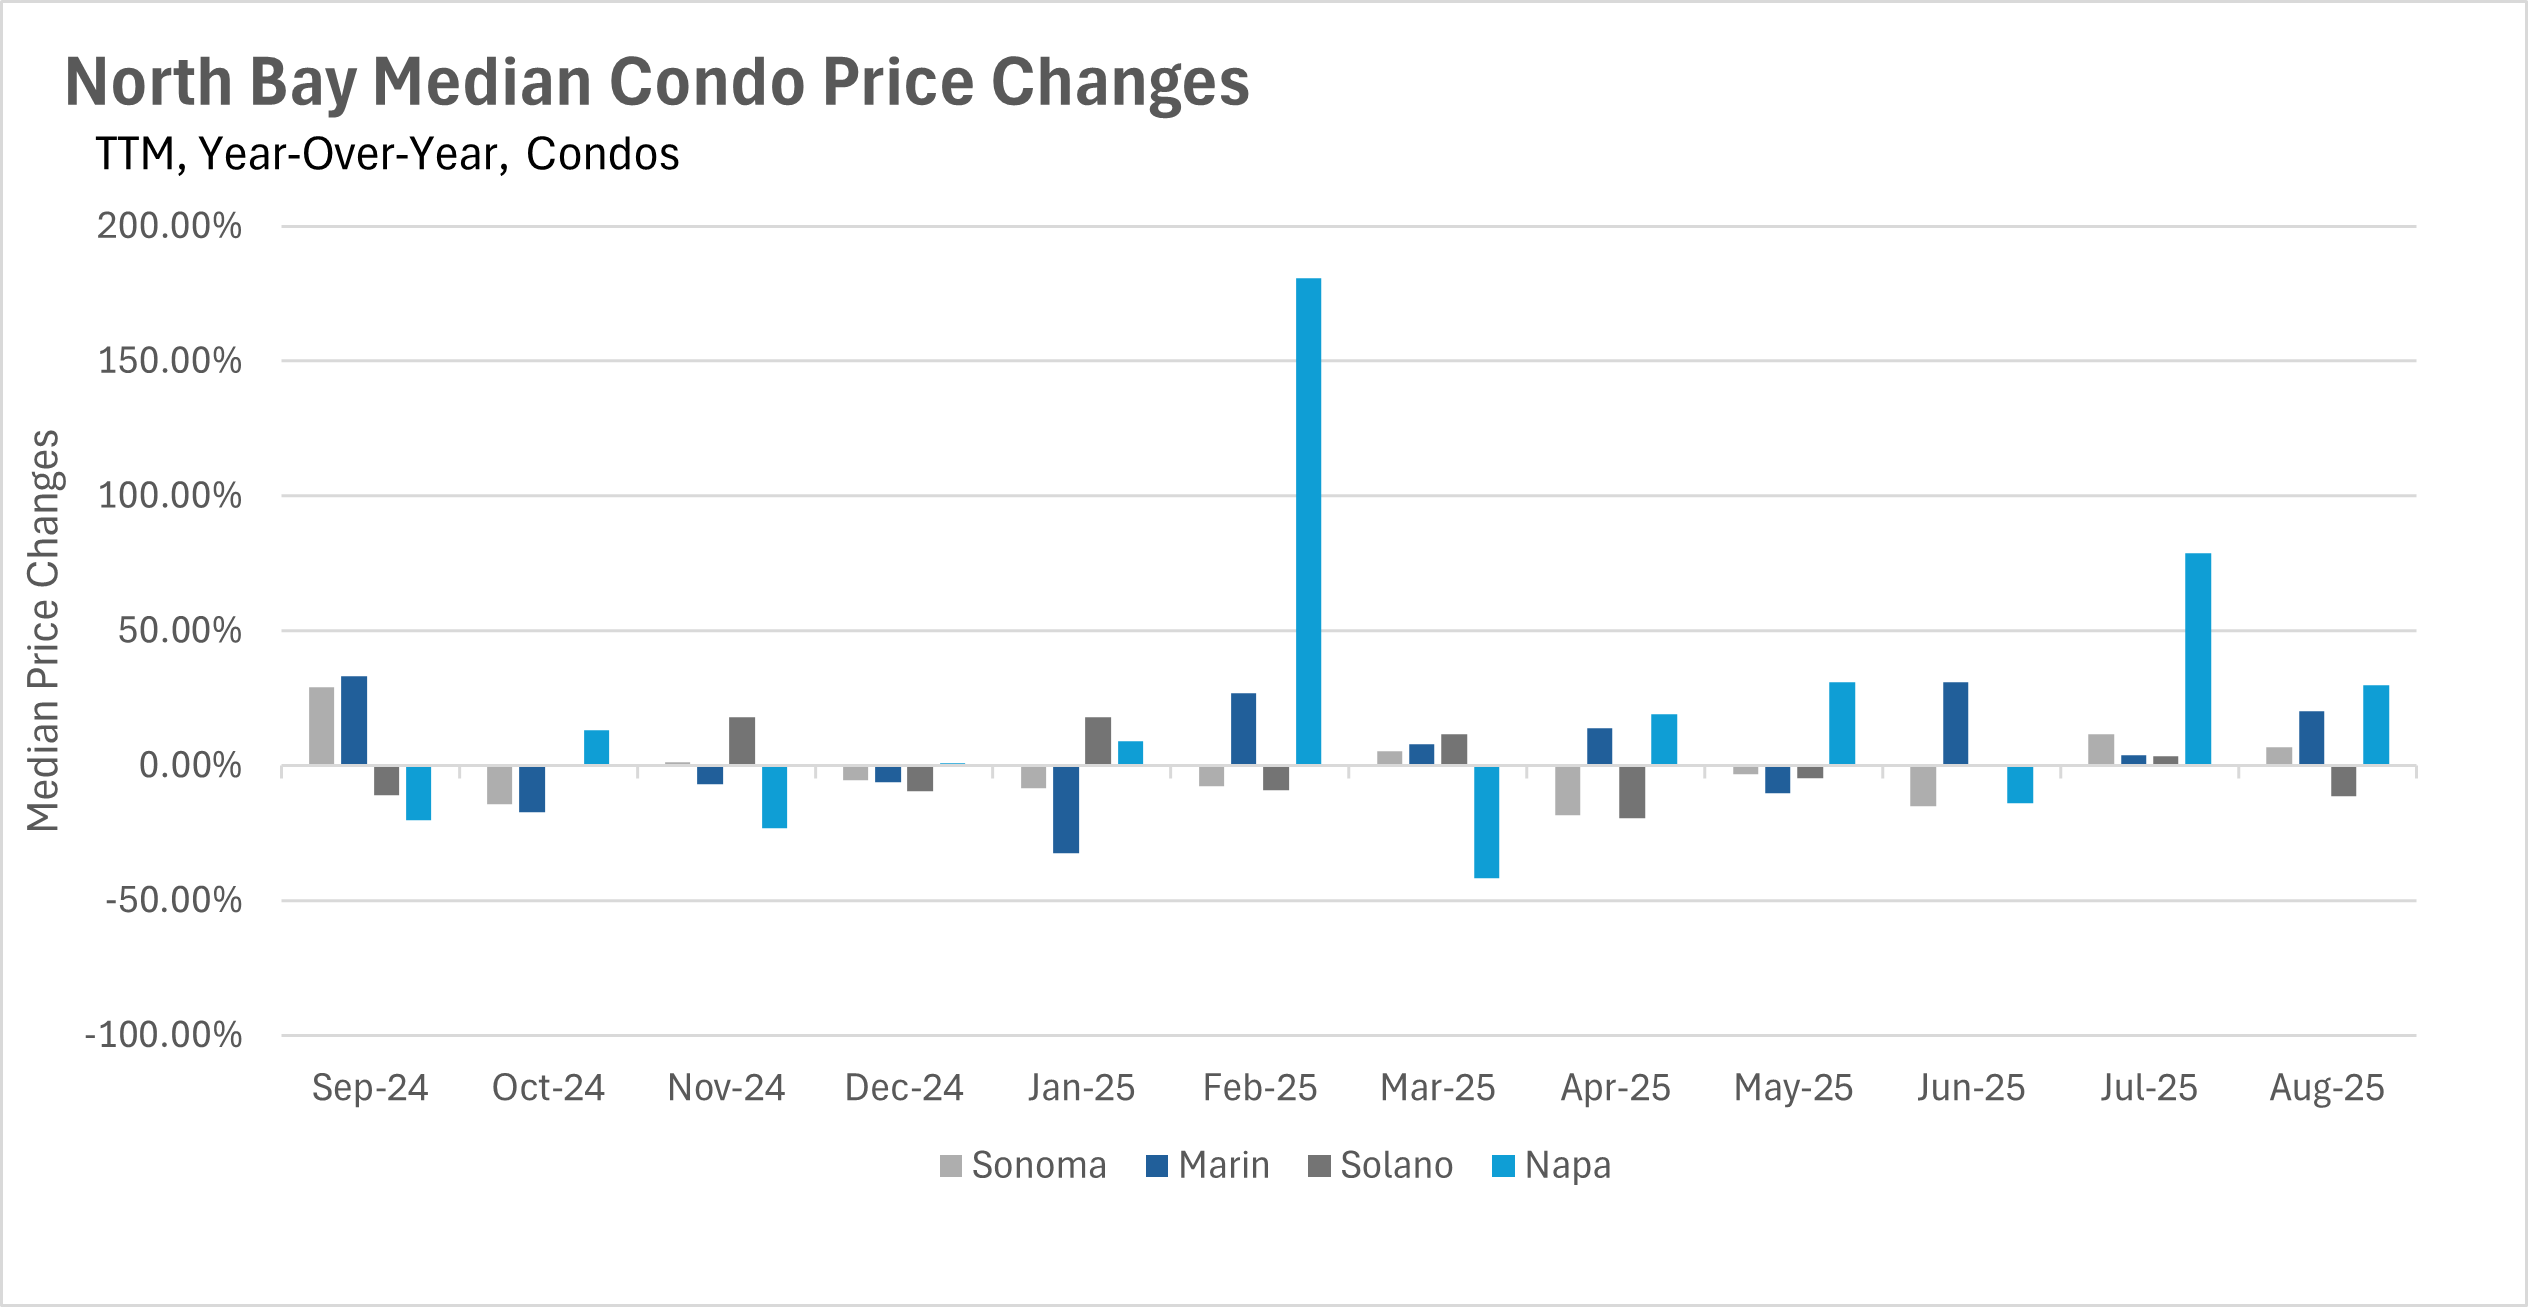
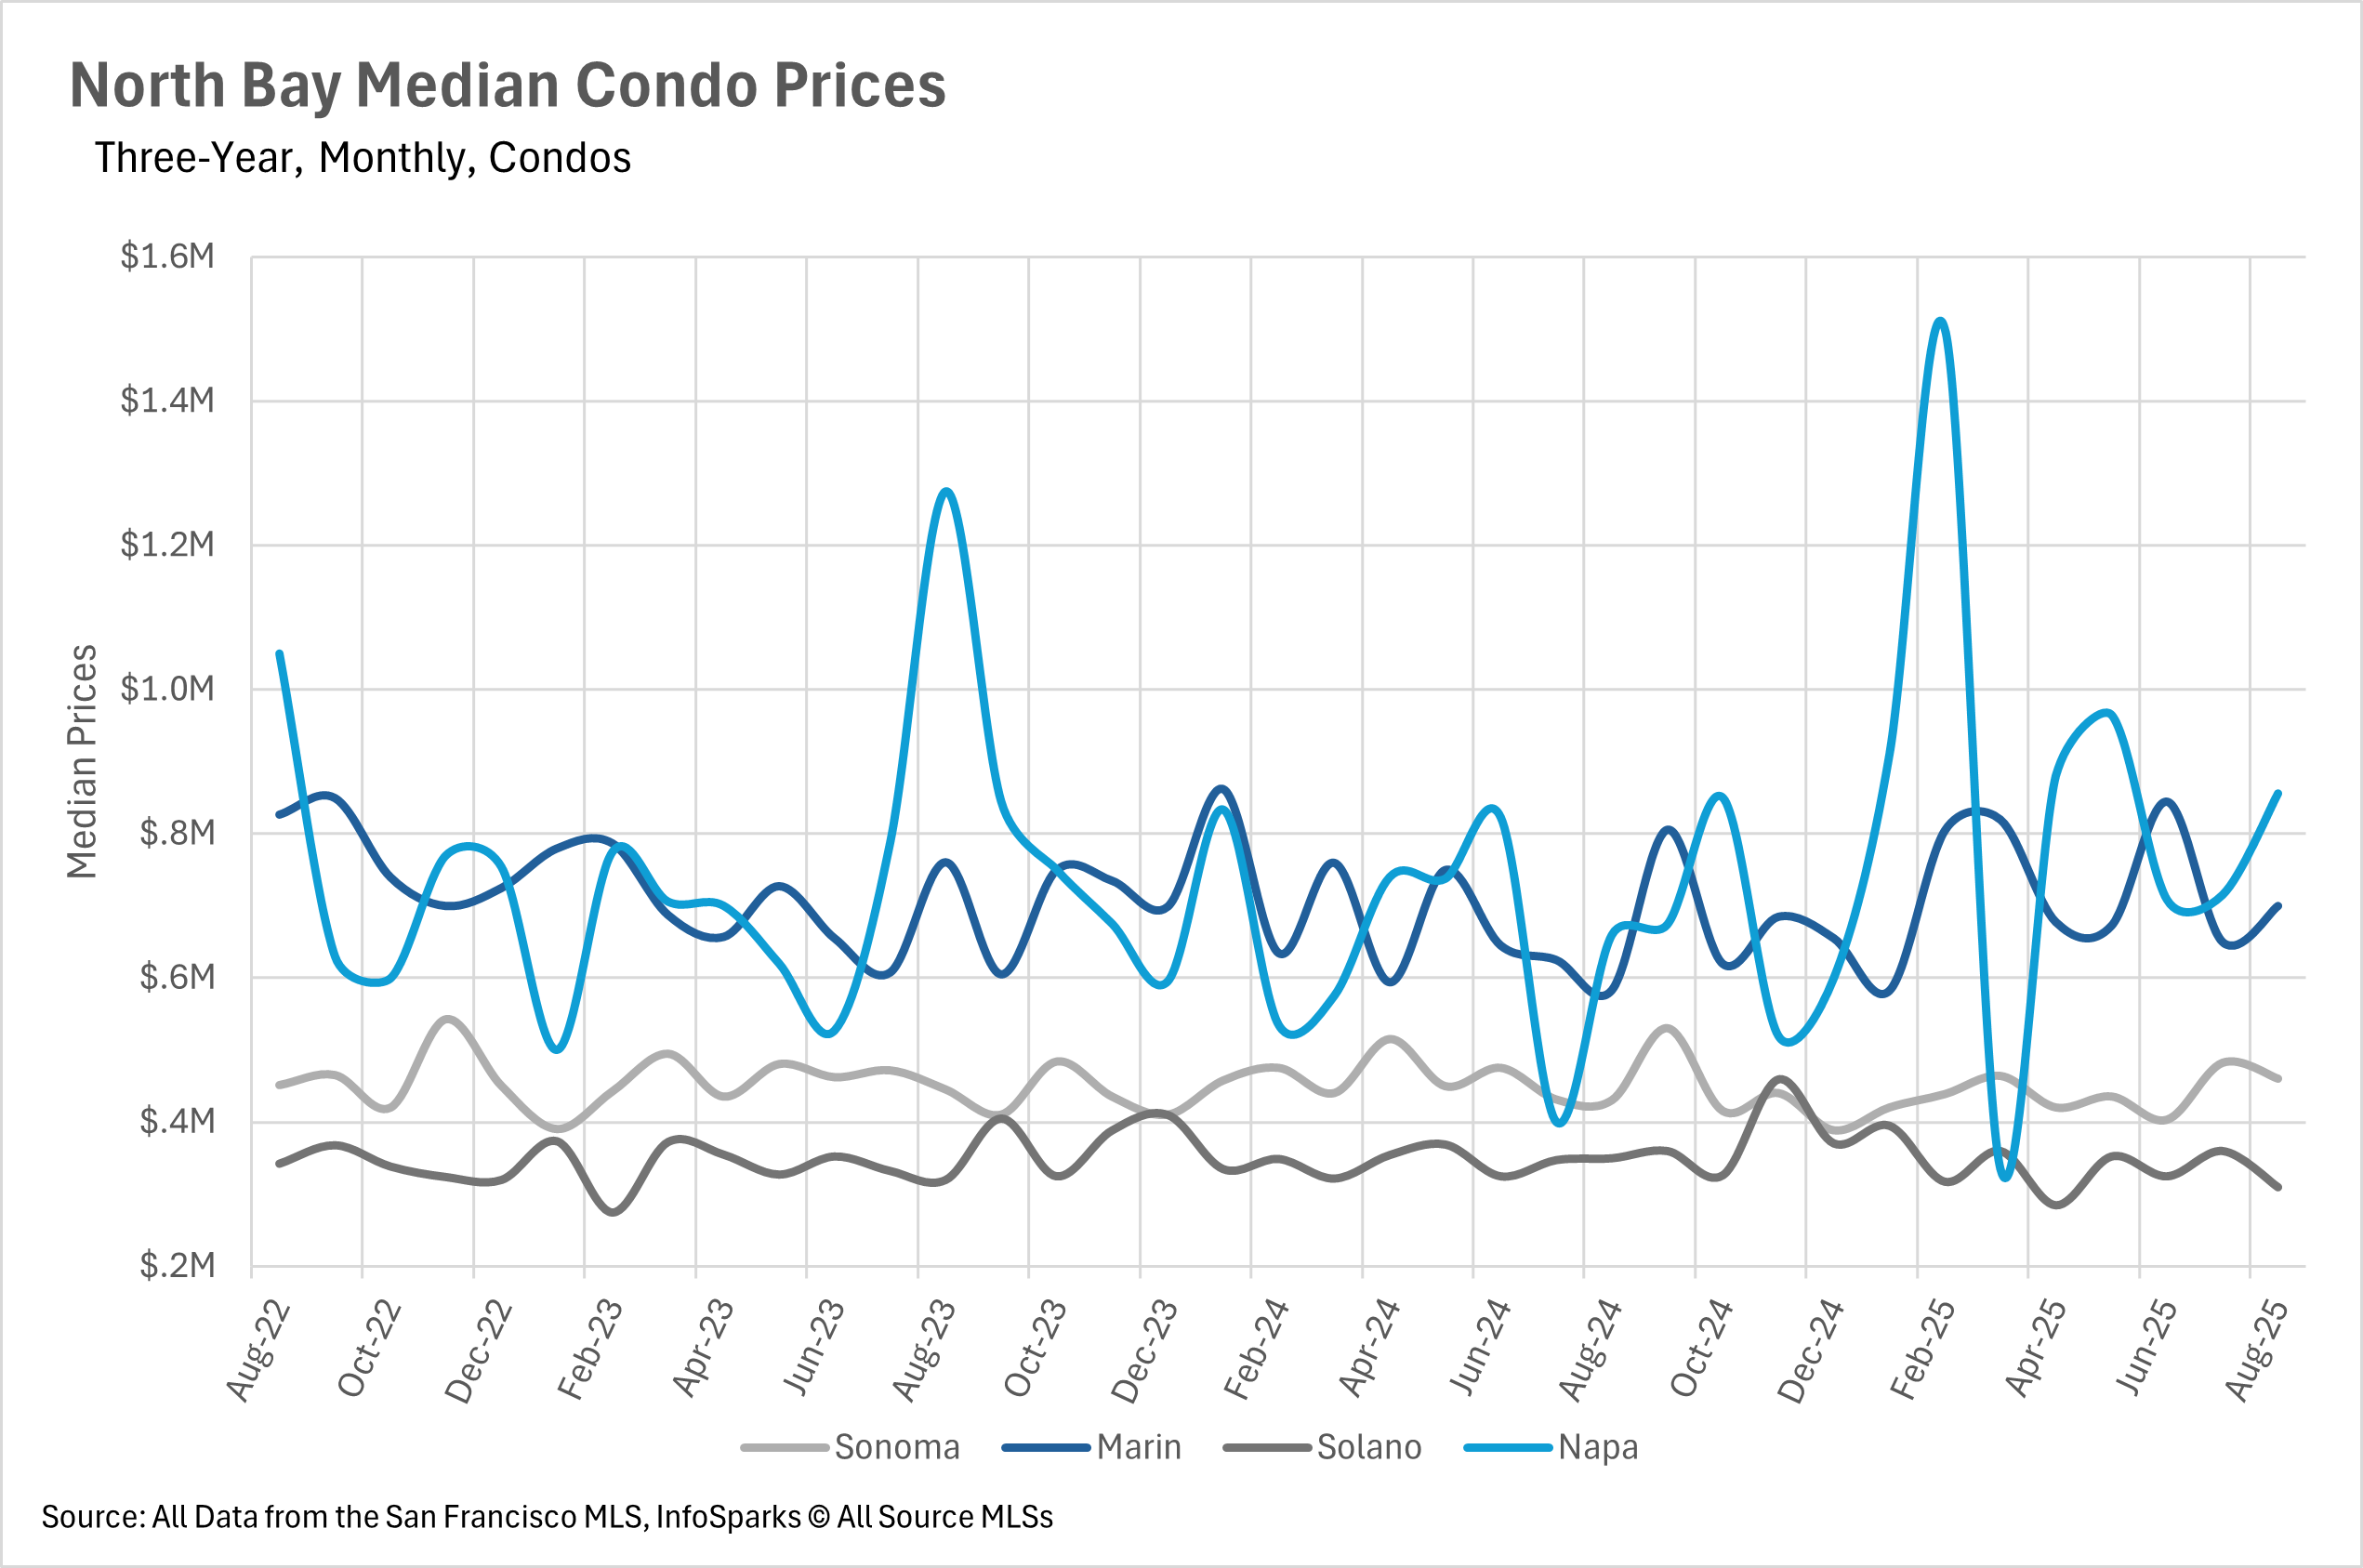
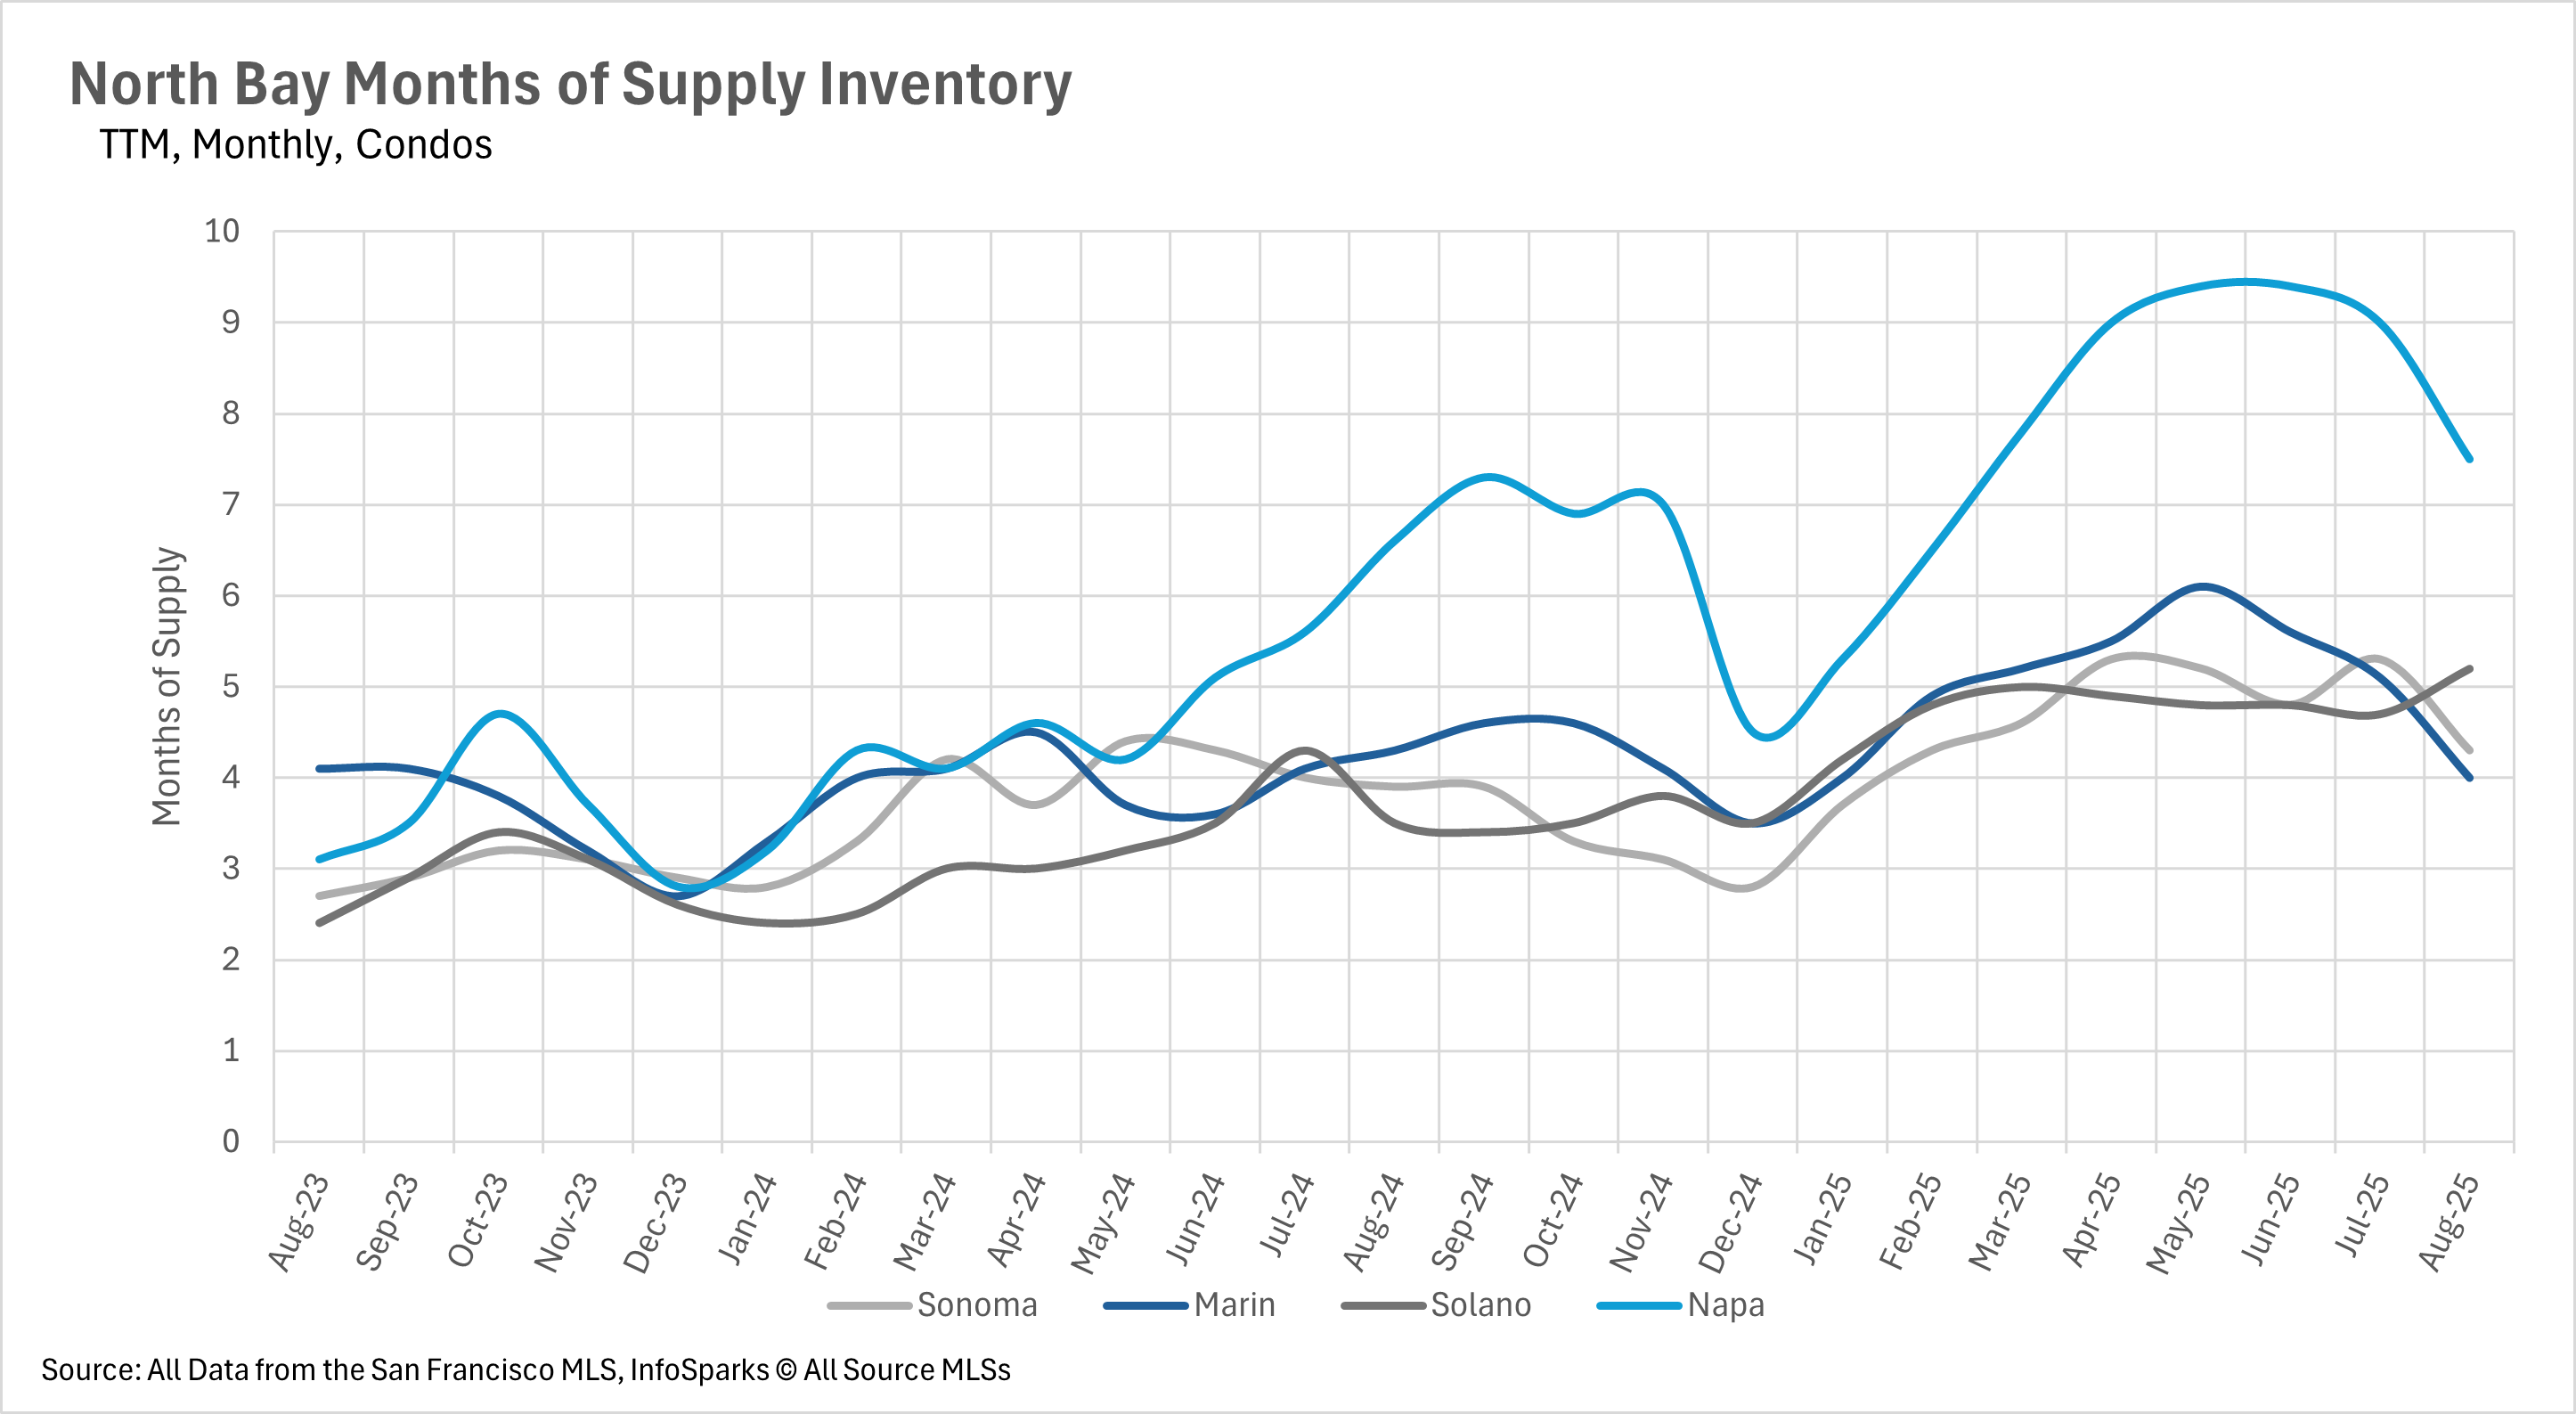
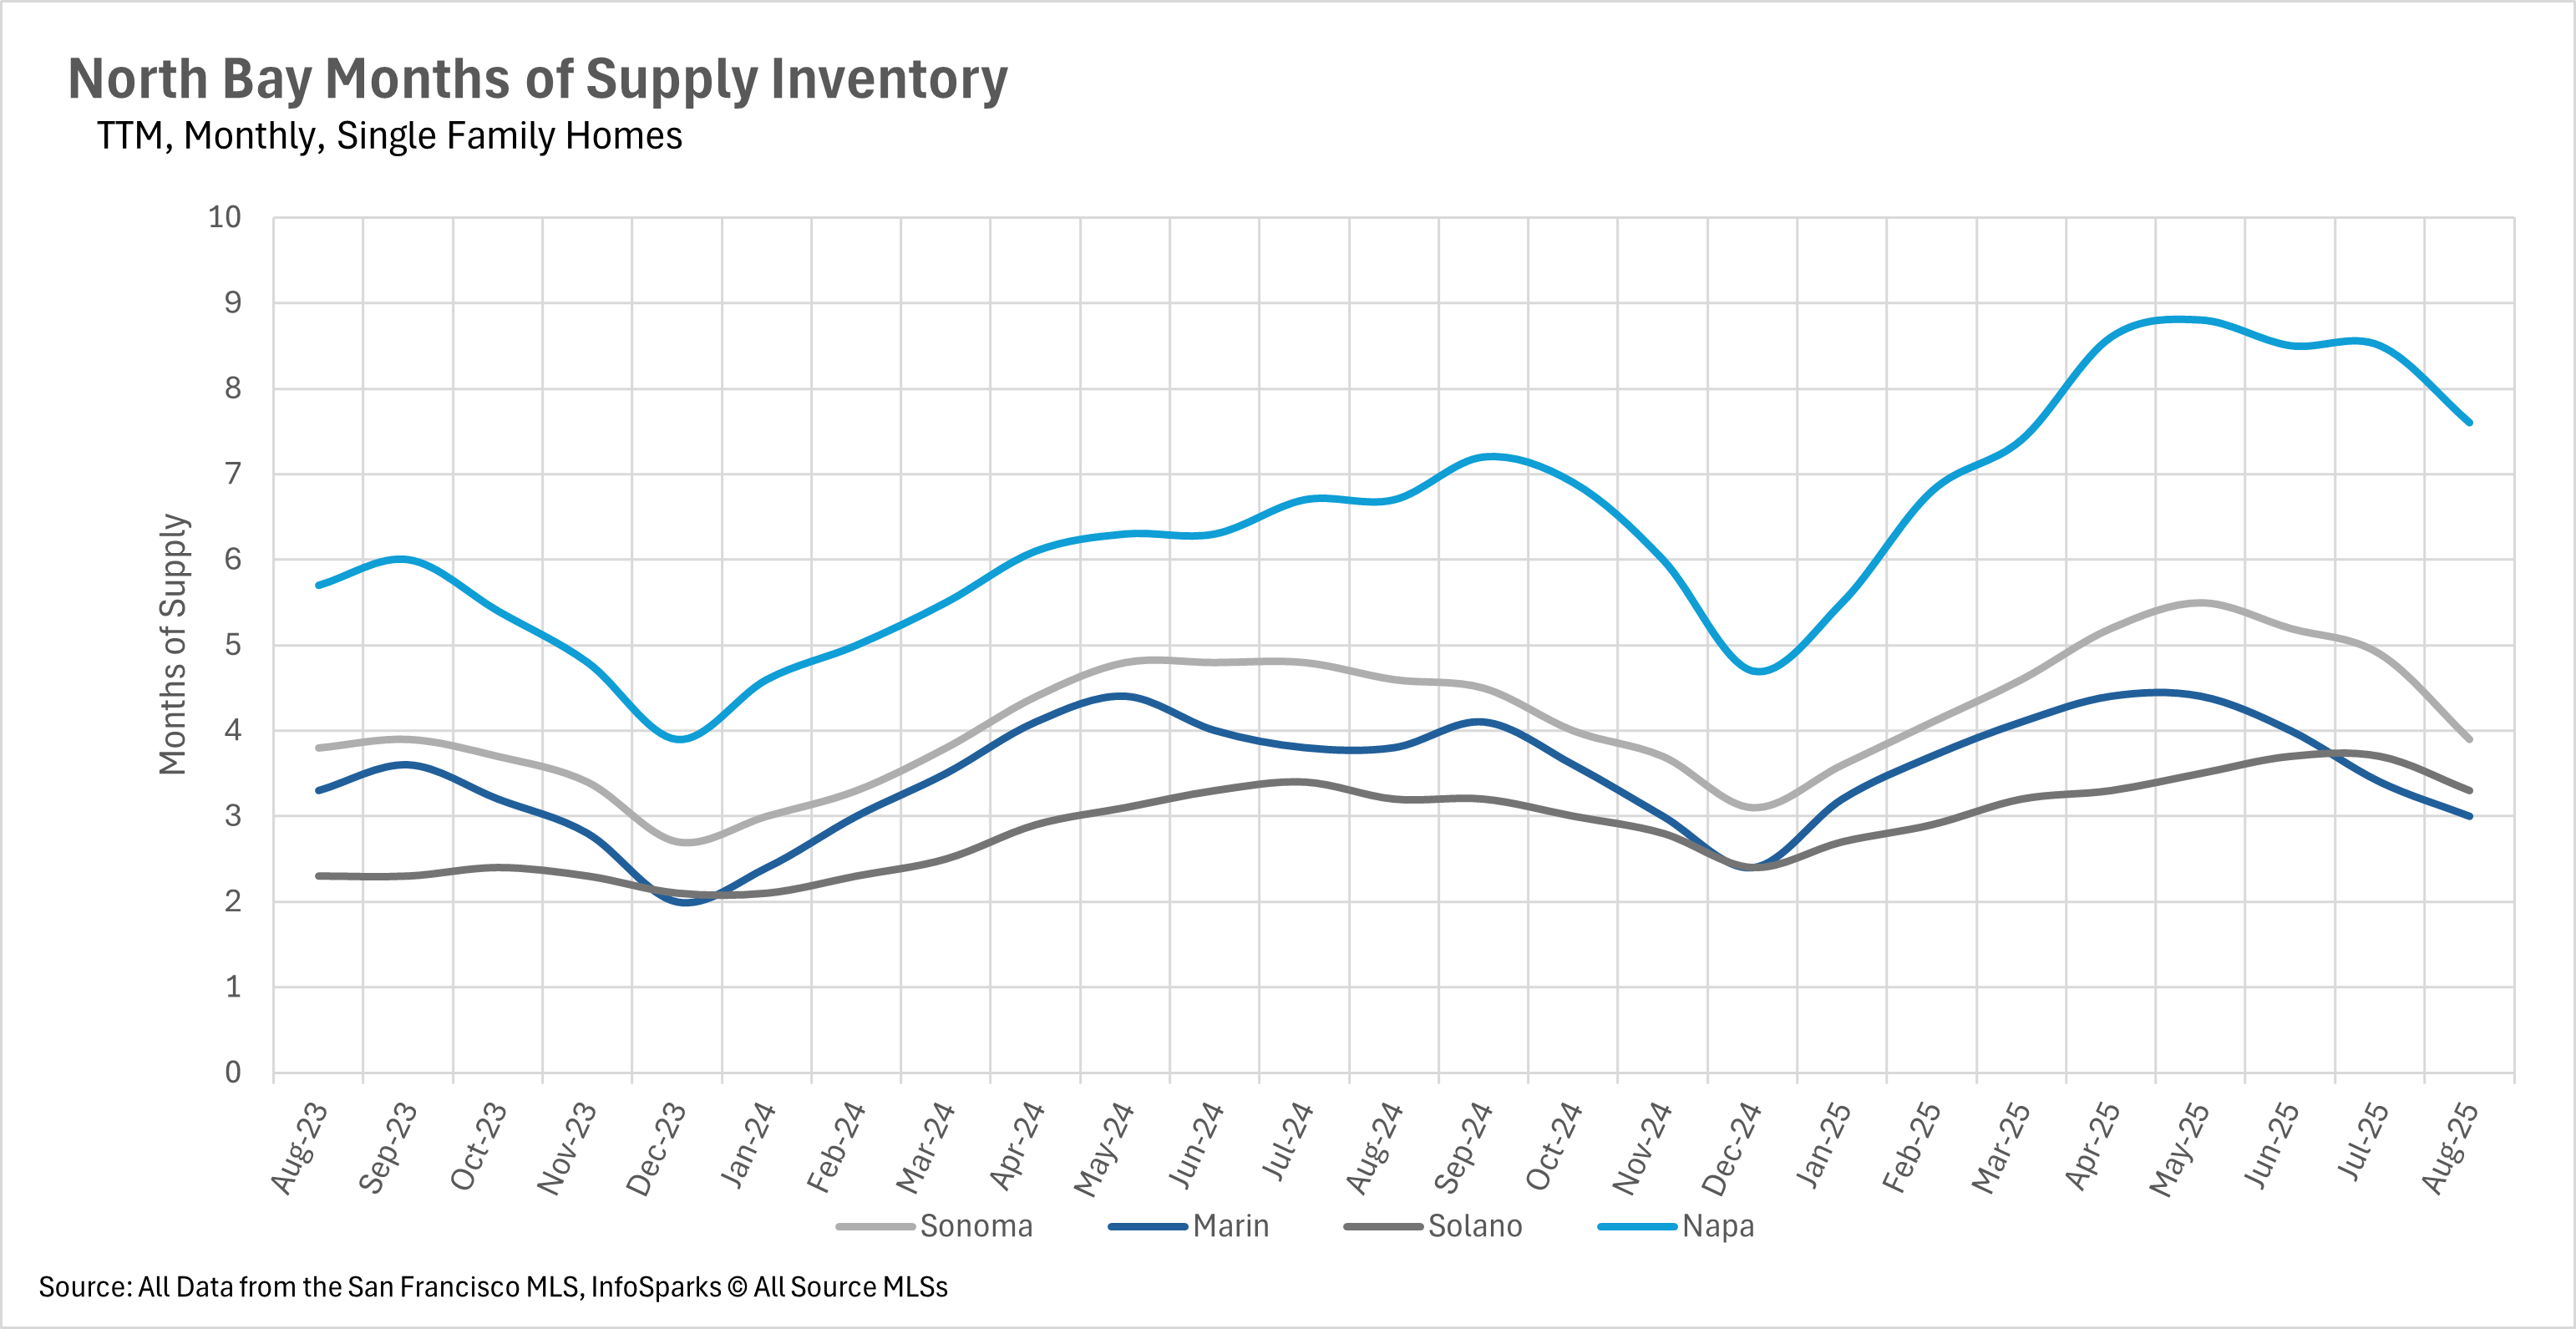
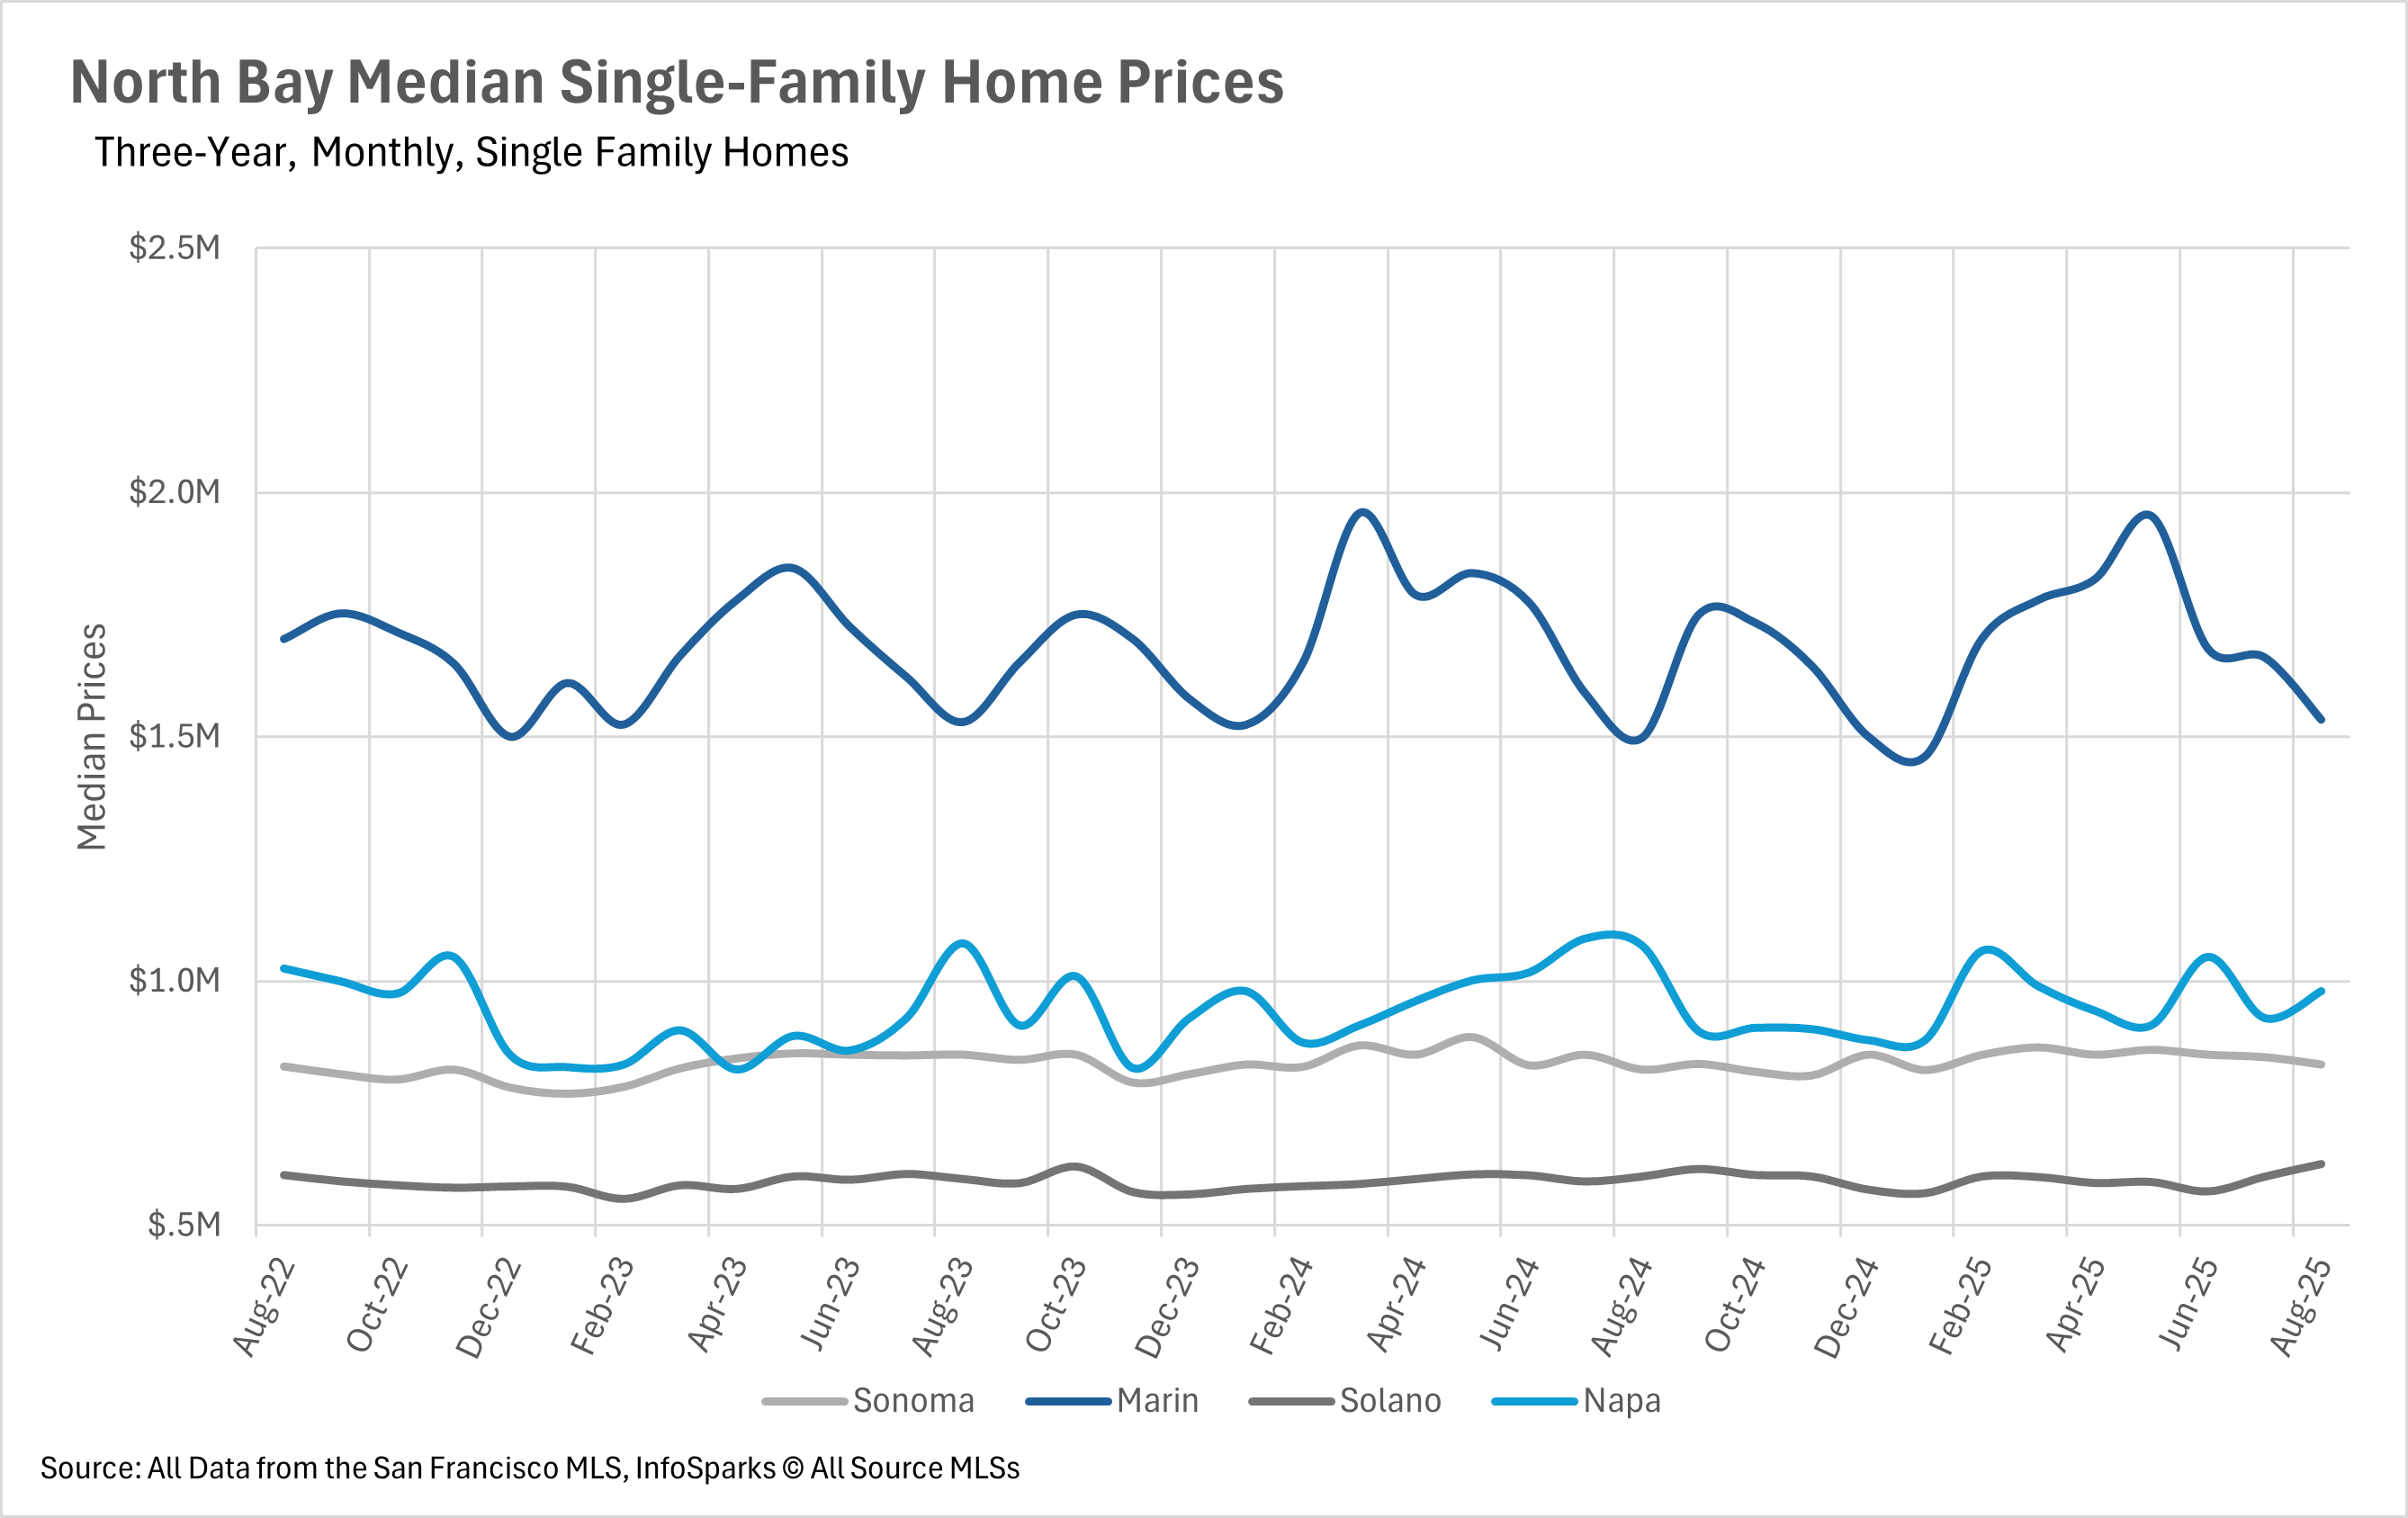
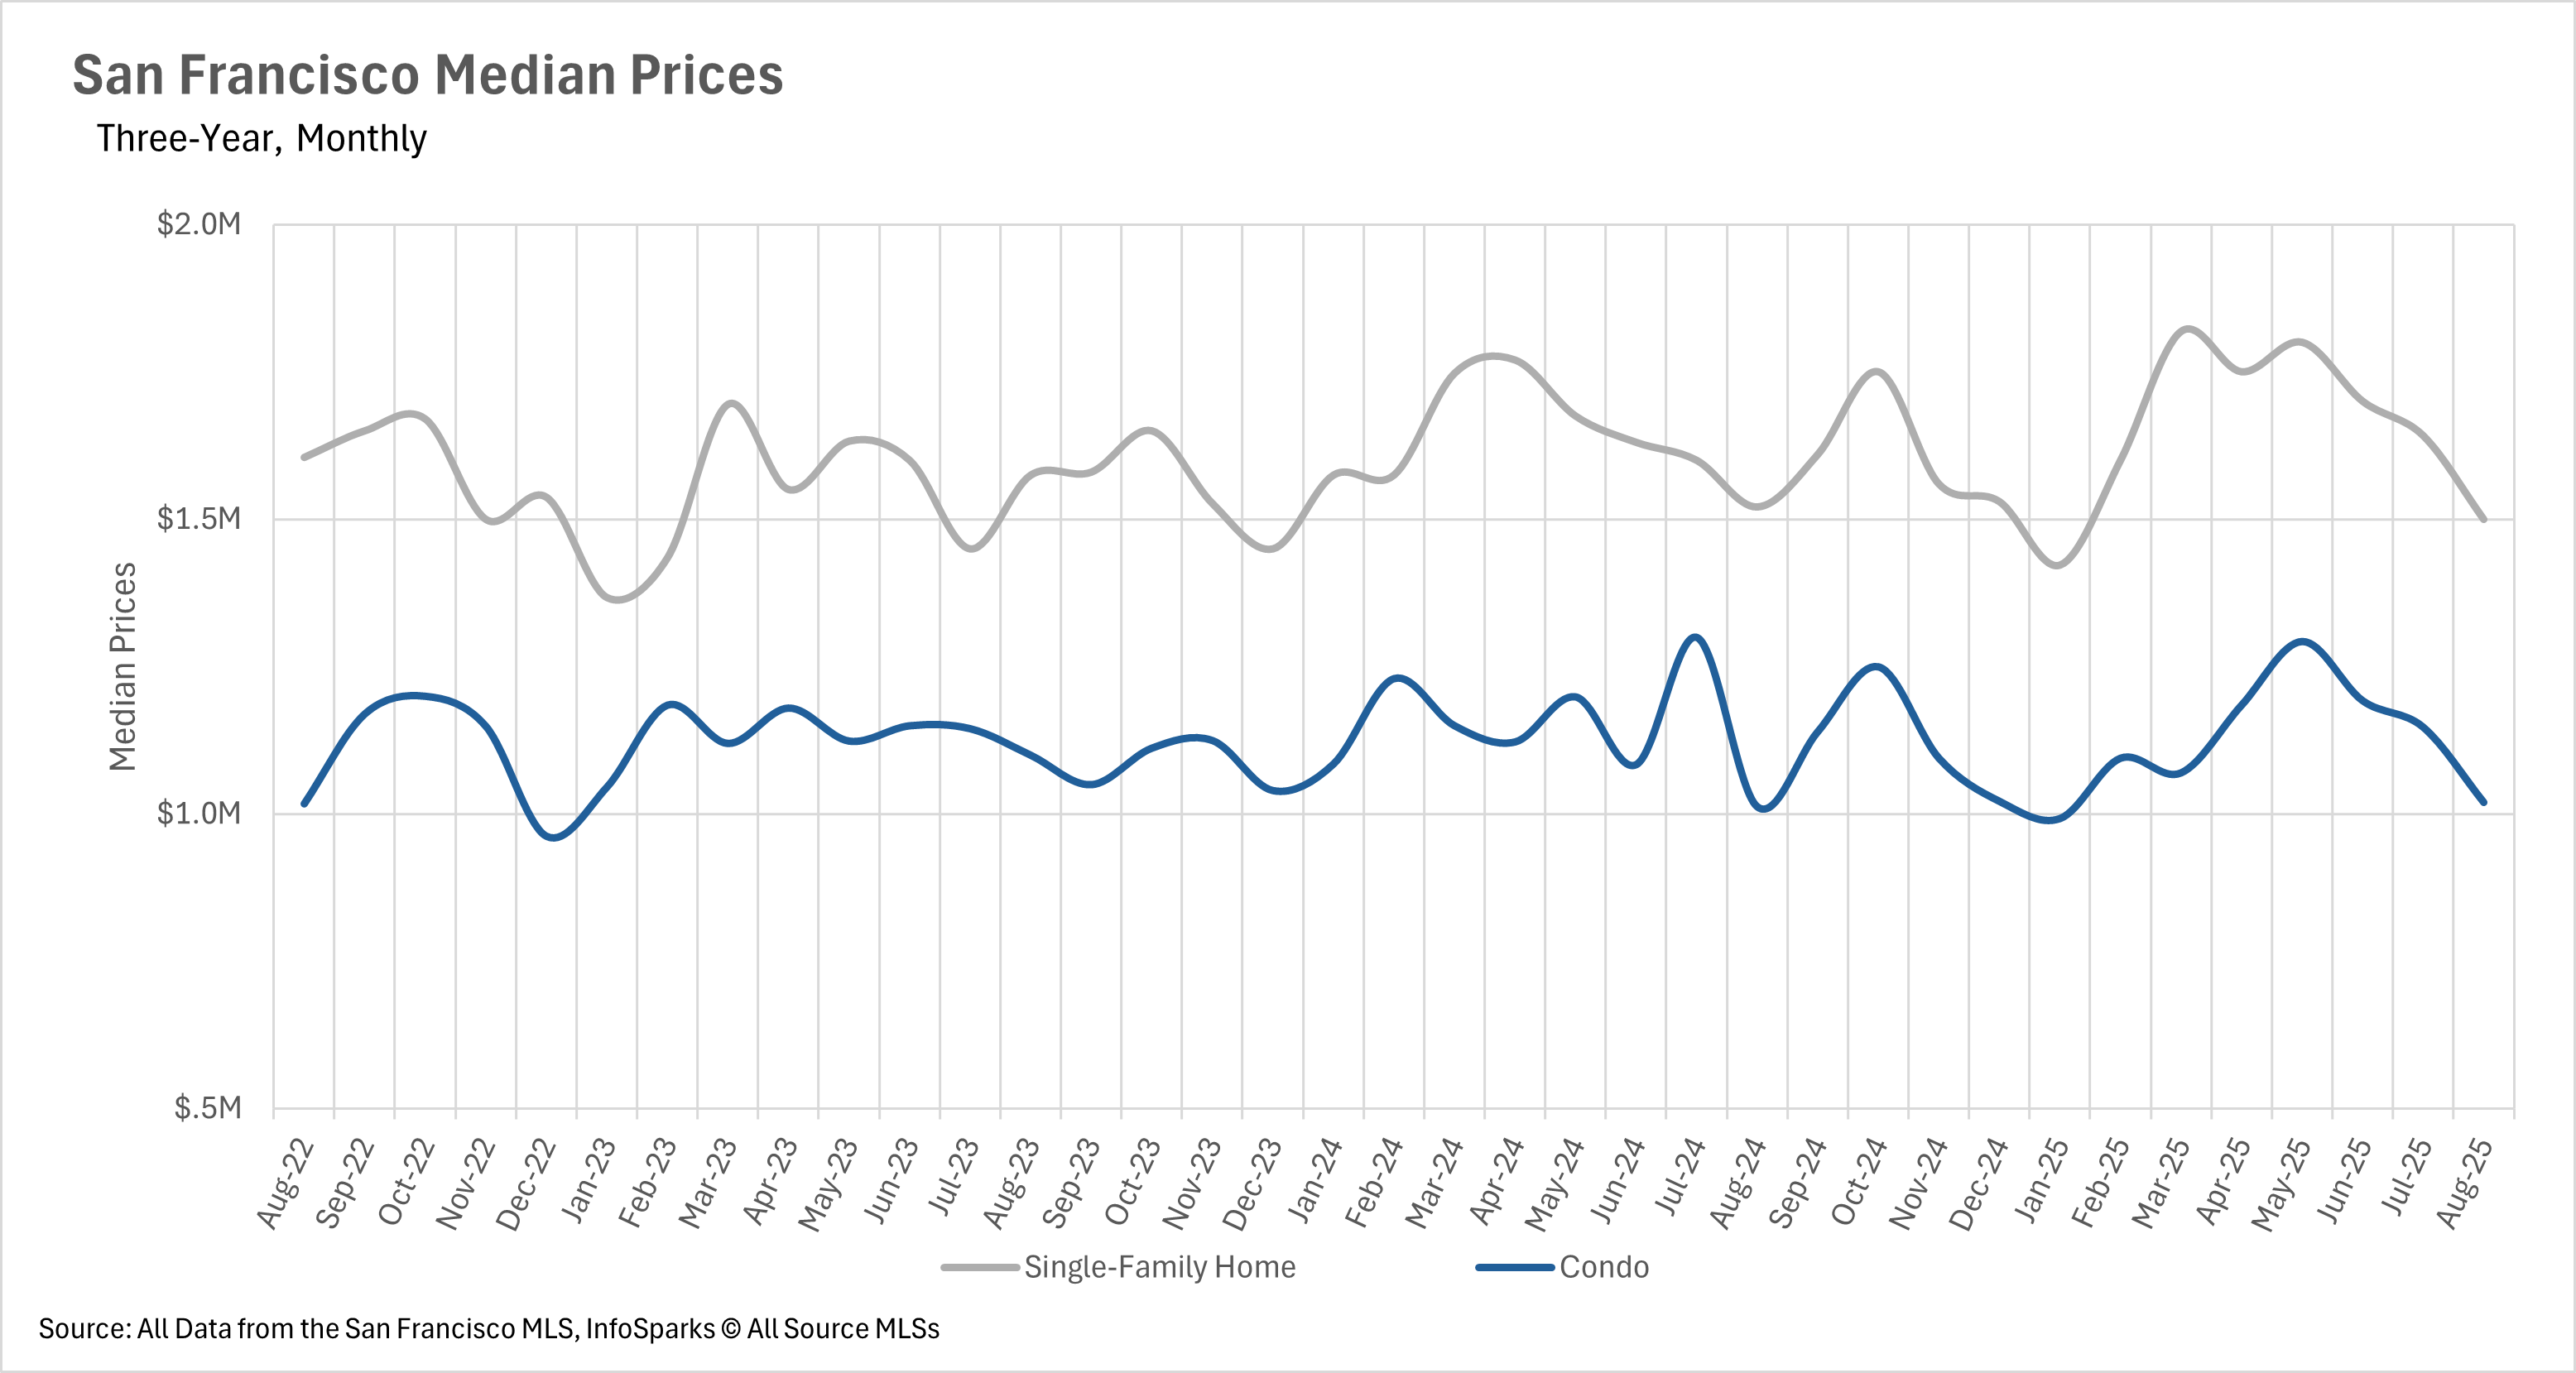
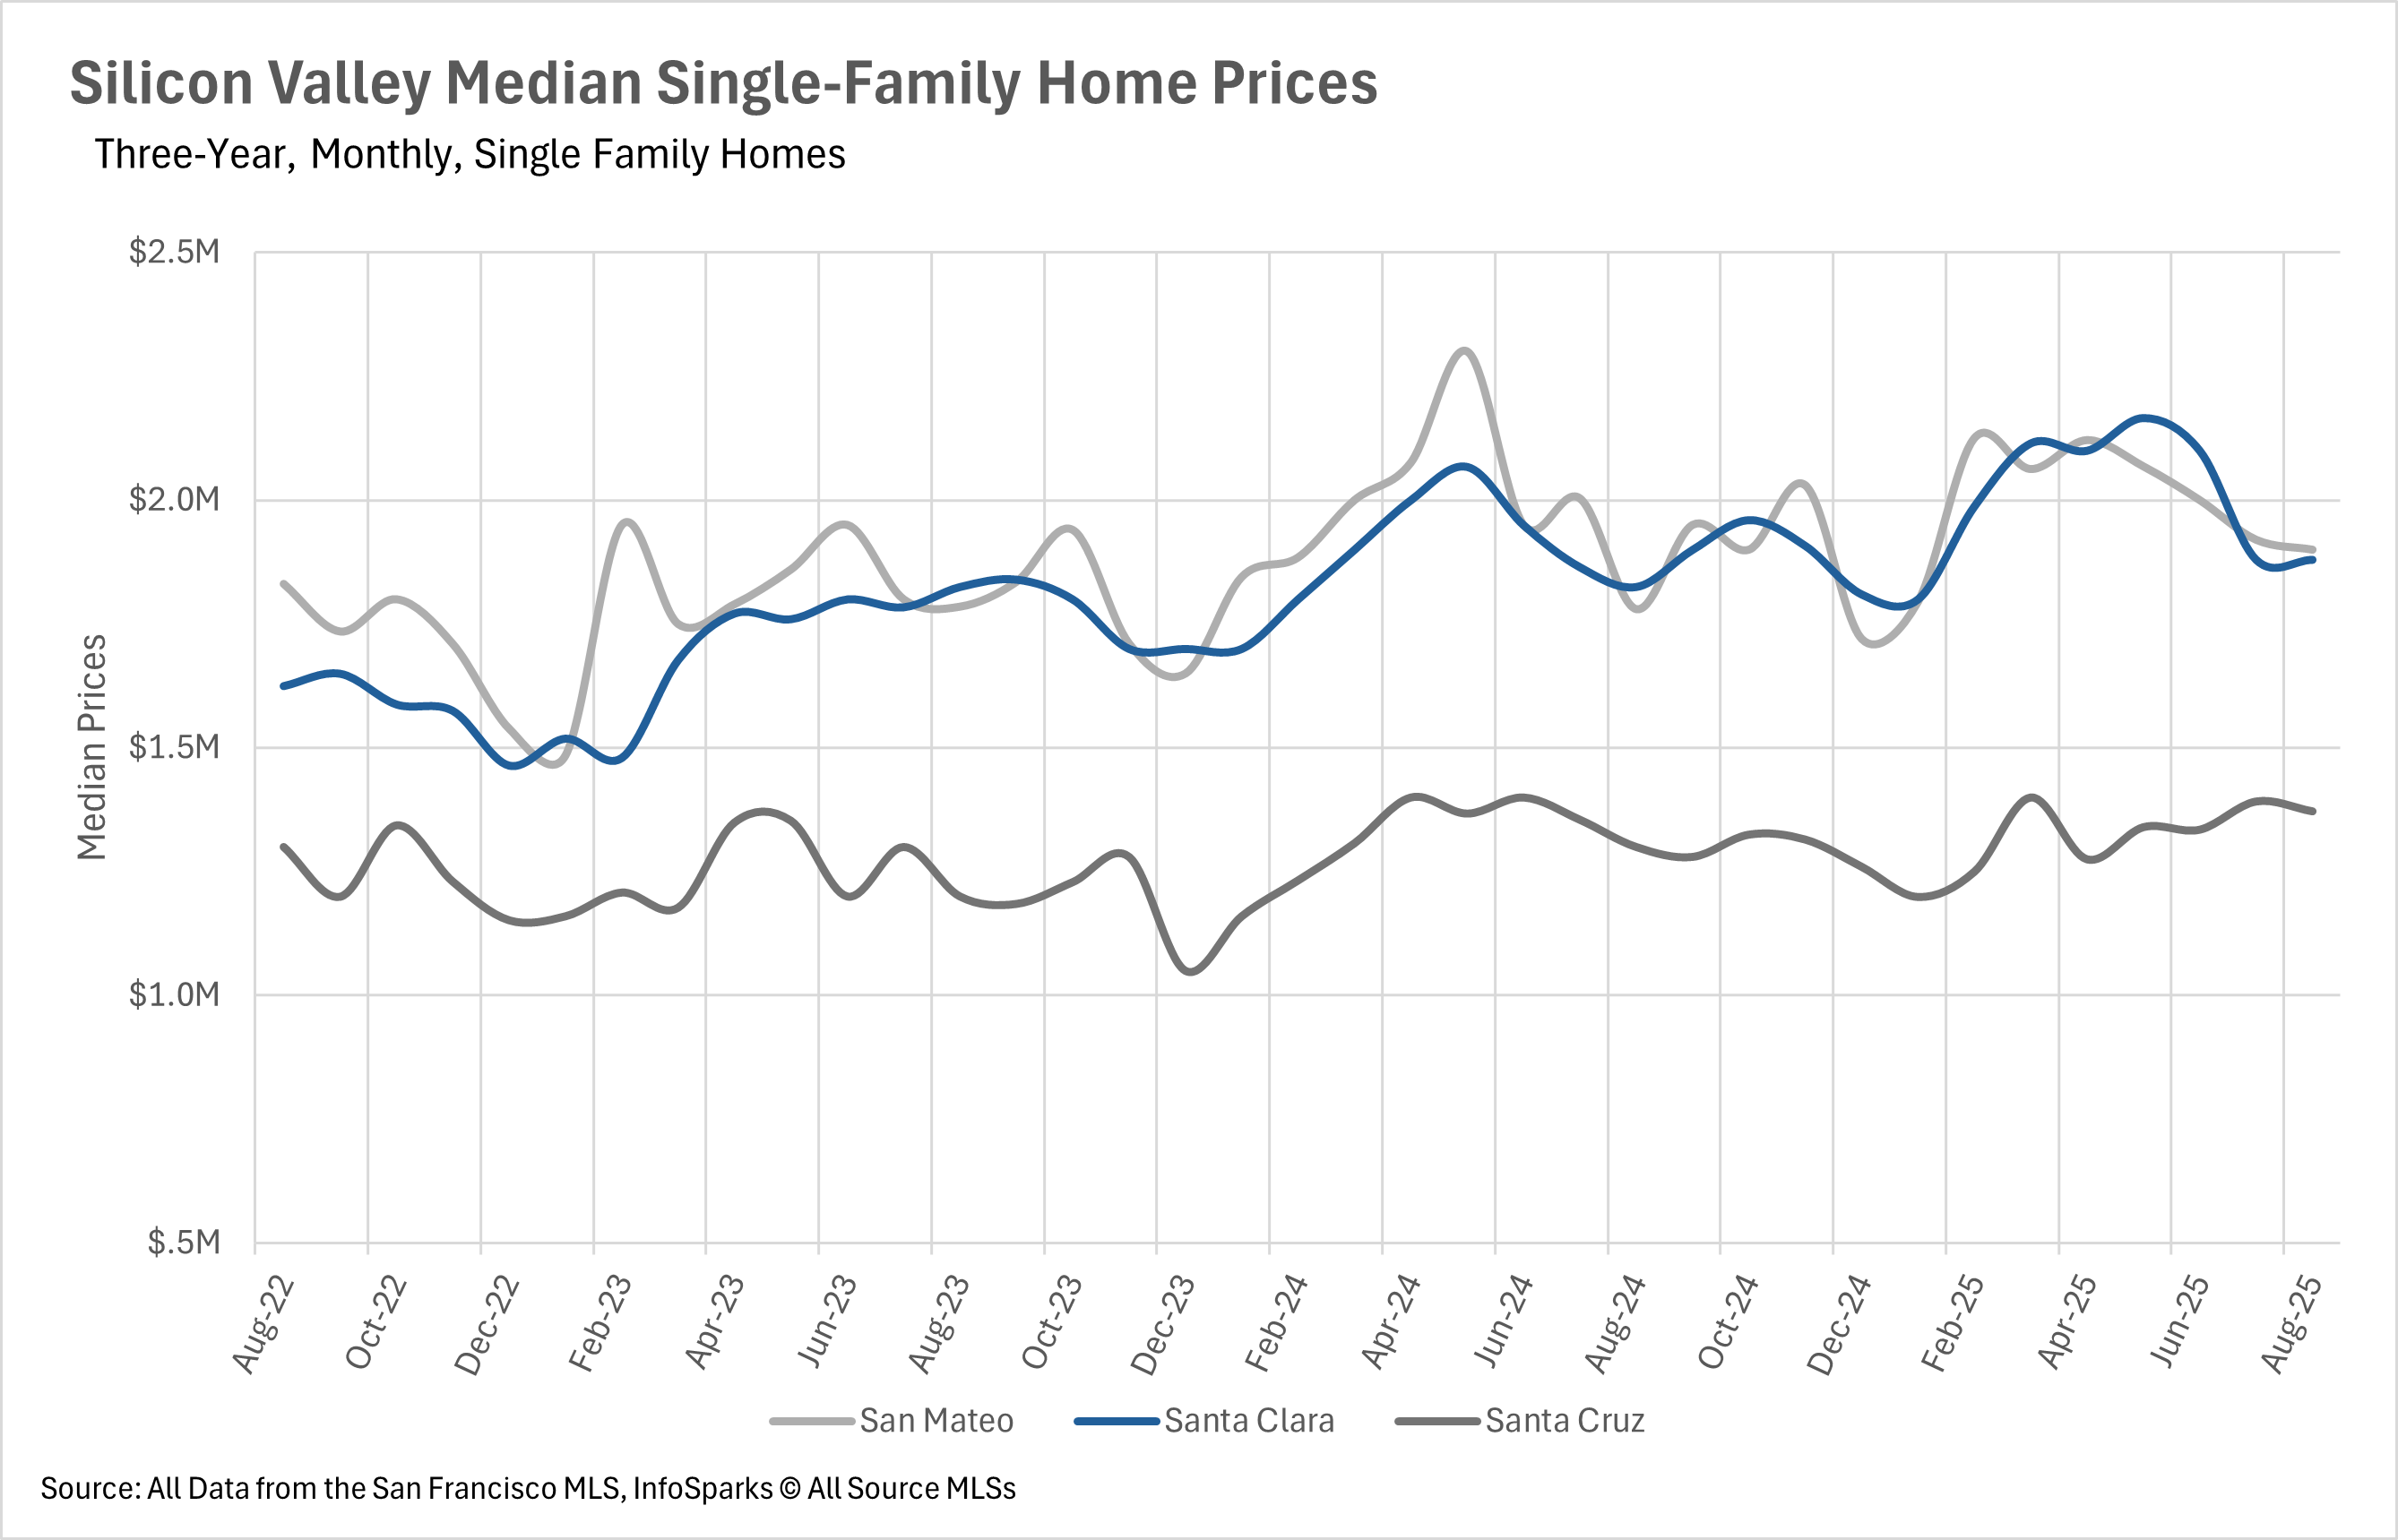
August showcased a remarkable turnaround for Bay Area single-family home markets after months of uncertainty. Silicon Valley led the recovery with price appreciation across all counties for the first time in four months - San Mateo County surged 6.74%, Santa Cruz gained 5.54%, and Santa Clara increased 3.01% year-over-year. The East Bay also returned to positive territory for the first time in six months, with Alameda and Contra Costa Counties posting modest gains of 1.20% and 1.33% respectively. The North Bay showed strong performance in most areas, with Solano County up 4.17%, Marin County gaining 2.47%, and Sonoma County rising 1.29%, though Napa County experienced a significant 8.67% decline. San Francisco displayed unusual stability with single-family homes down just 1.38% and condos up a modest 0.74% - a stark contrast to its typical volatility. However, condo markets throughout the region continued to face headwinds, with Silicon Valley experiencing broad declines ranging from 3.64% in Santa Cruz to 5.20% in Santa Clara County. The East Bay's condo market remained mixed, with Contra Costa County up 2.04% but Alameda County down 7.41%. North Bay condos showed extreme volatility, with dramatic increases in Napa (29.76%), Marin (20.07%), and Sonoma (6.98%) Counties, while Solano County declined 11.43%.
Inventory normalization accelerates with San Francisco reaching historic lows
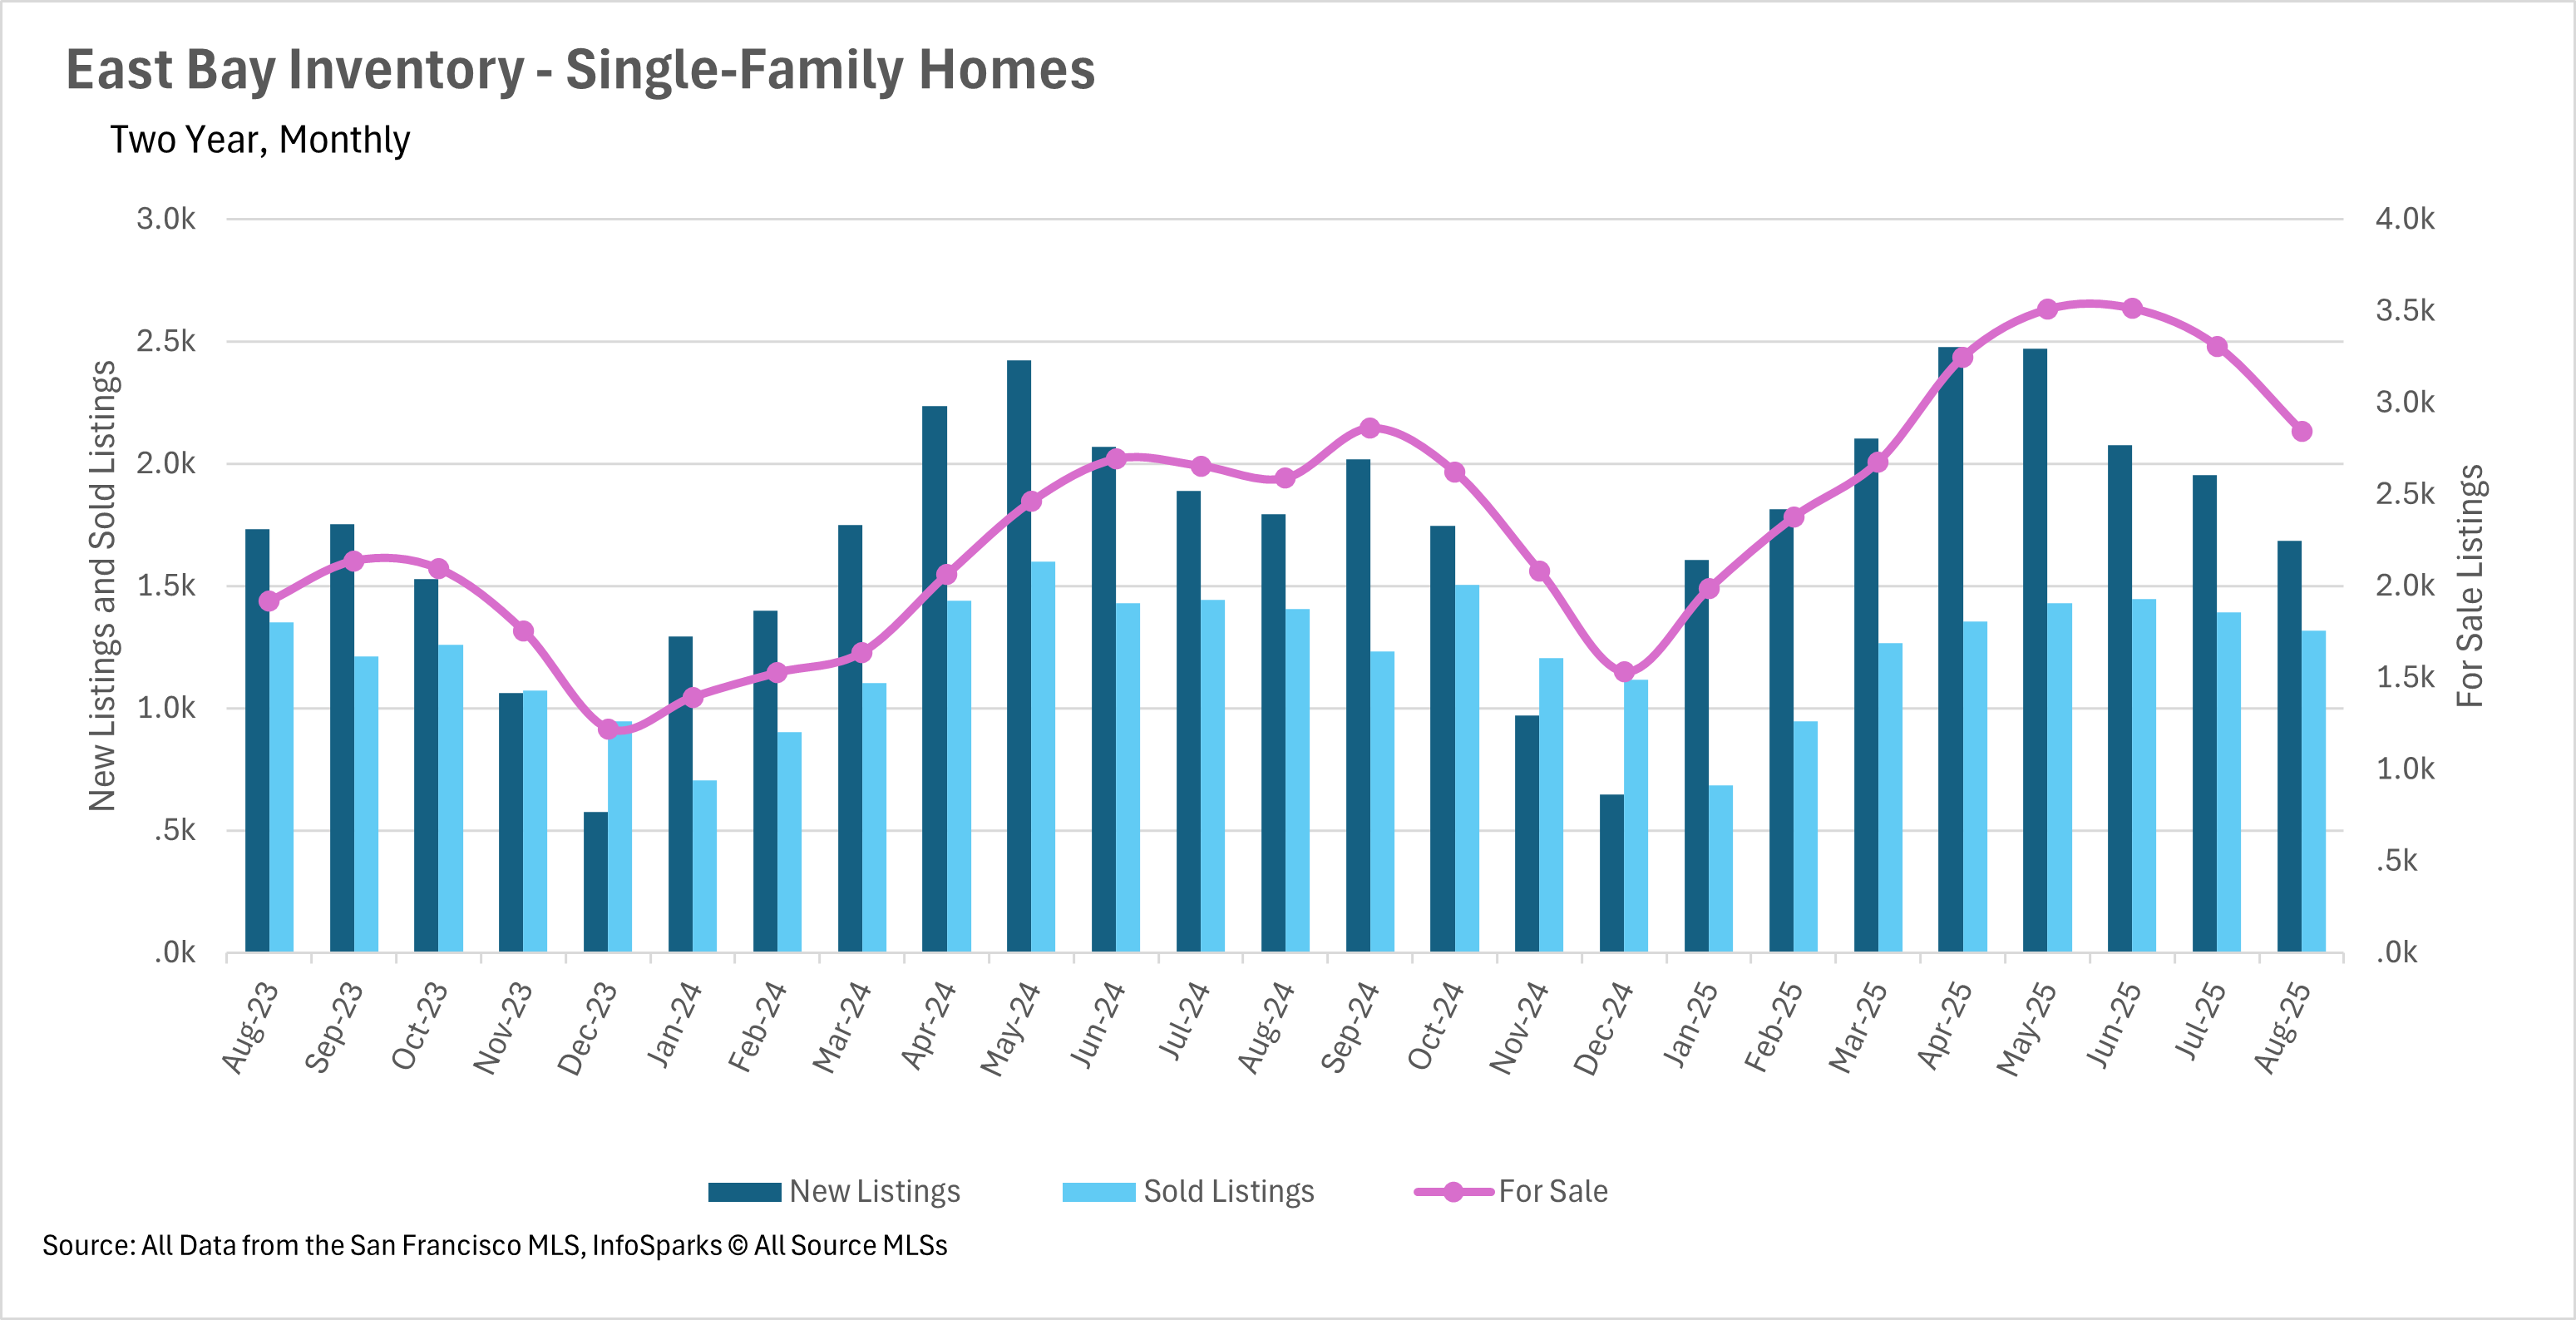
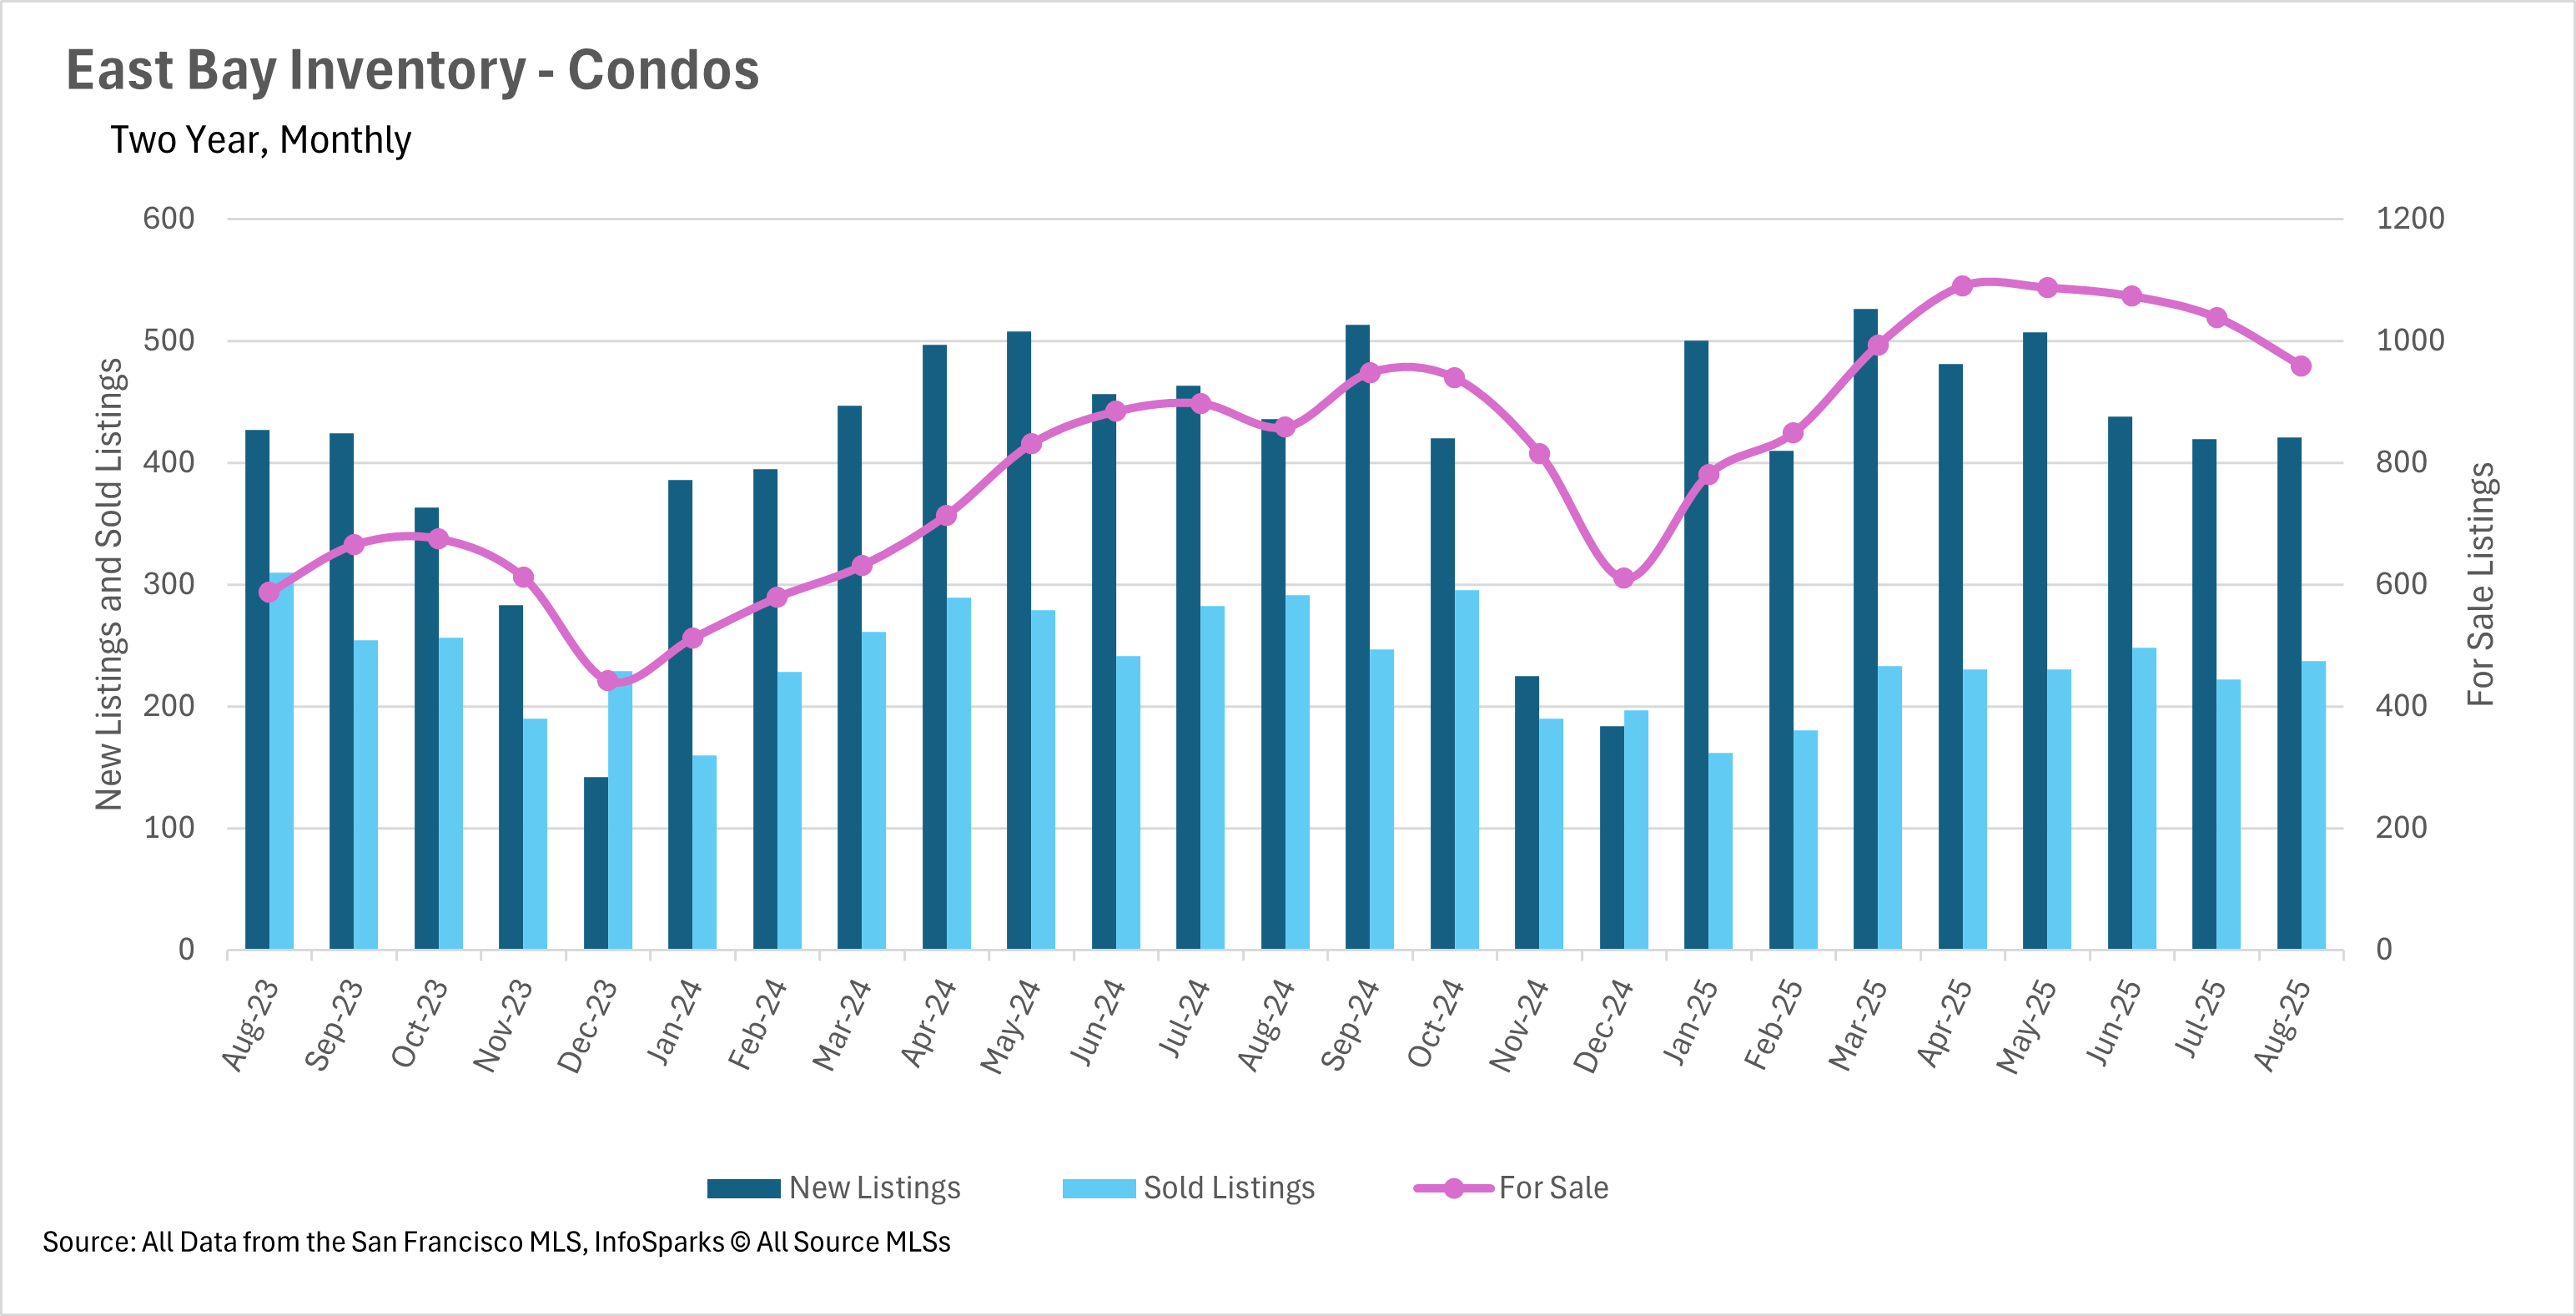
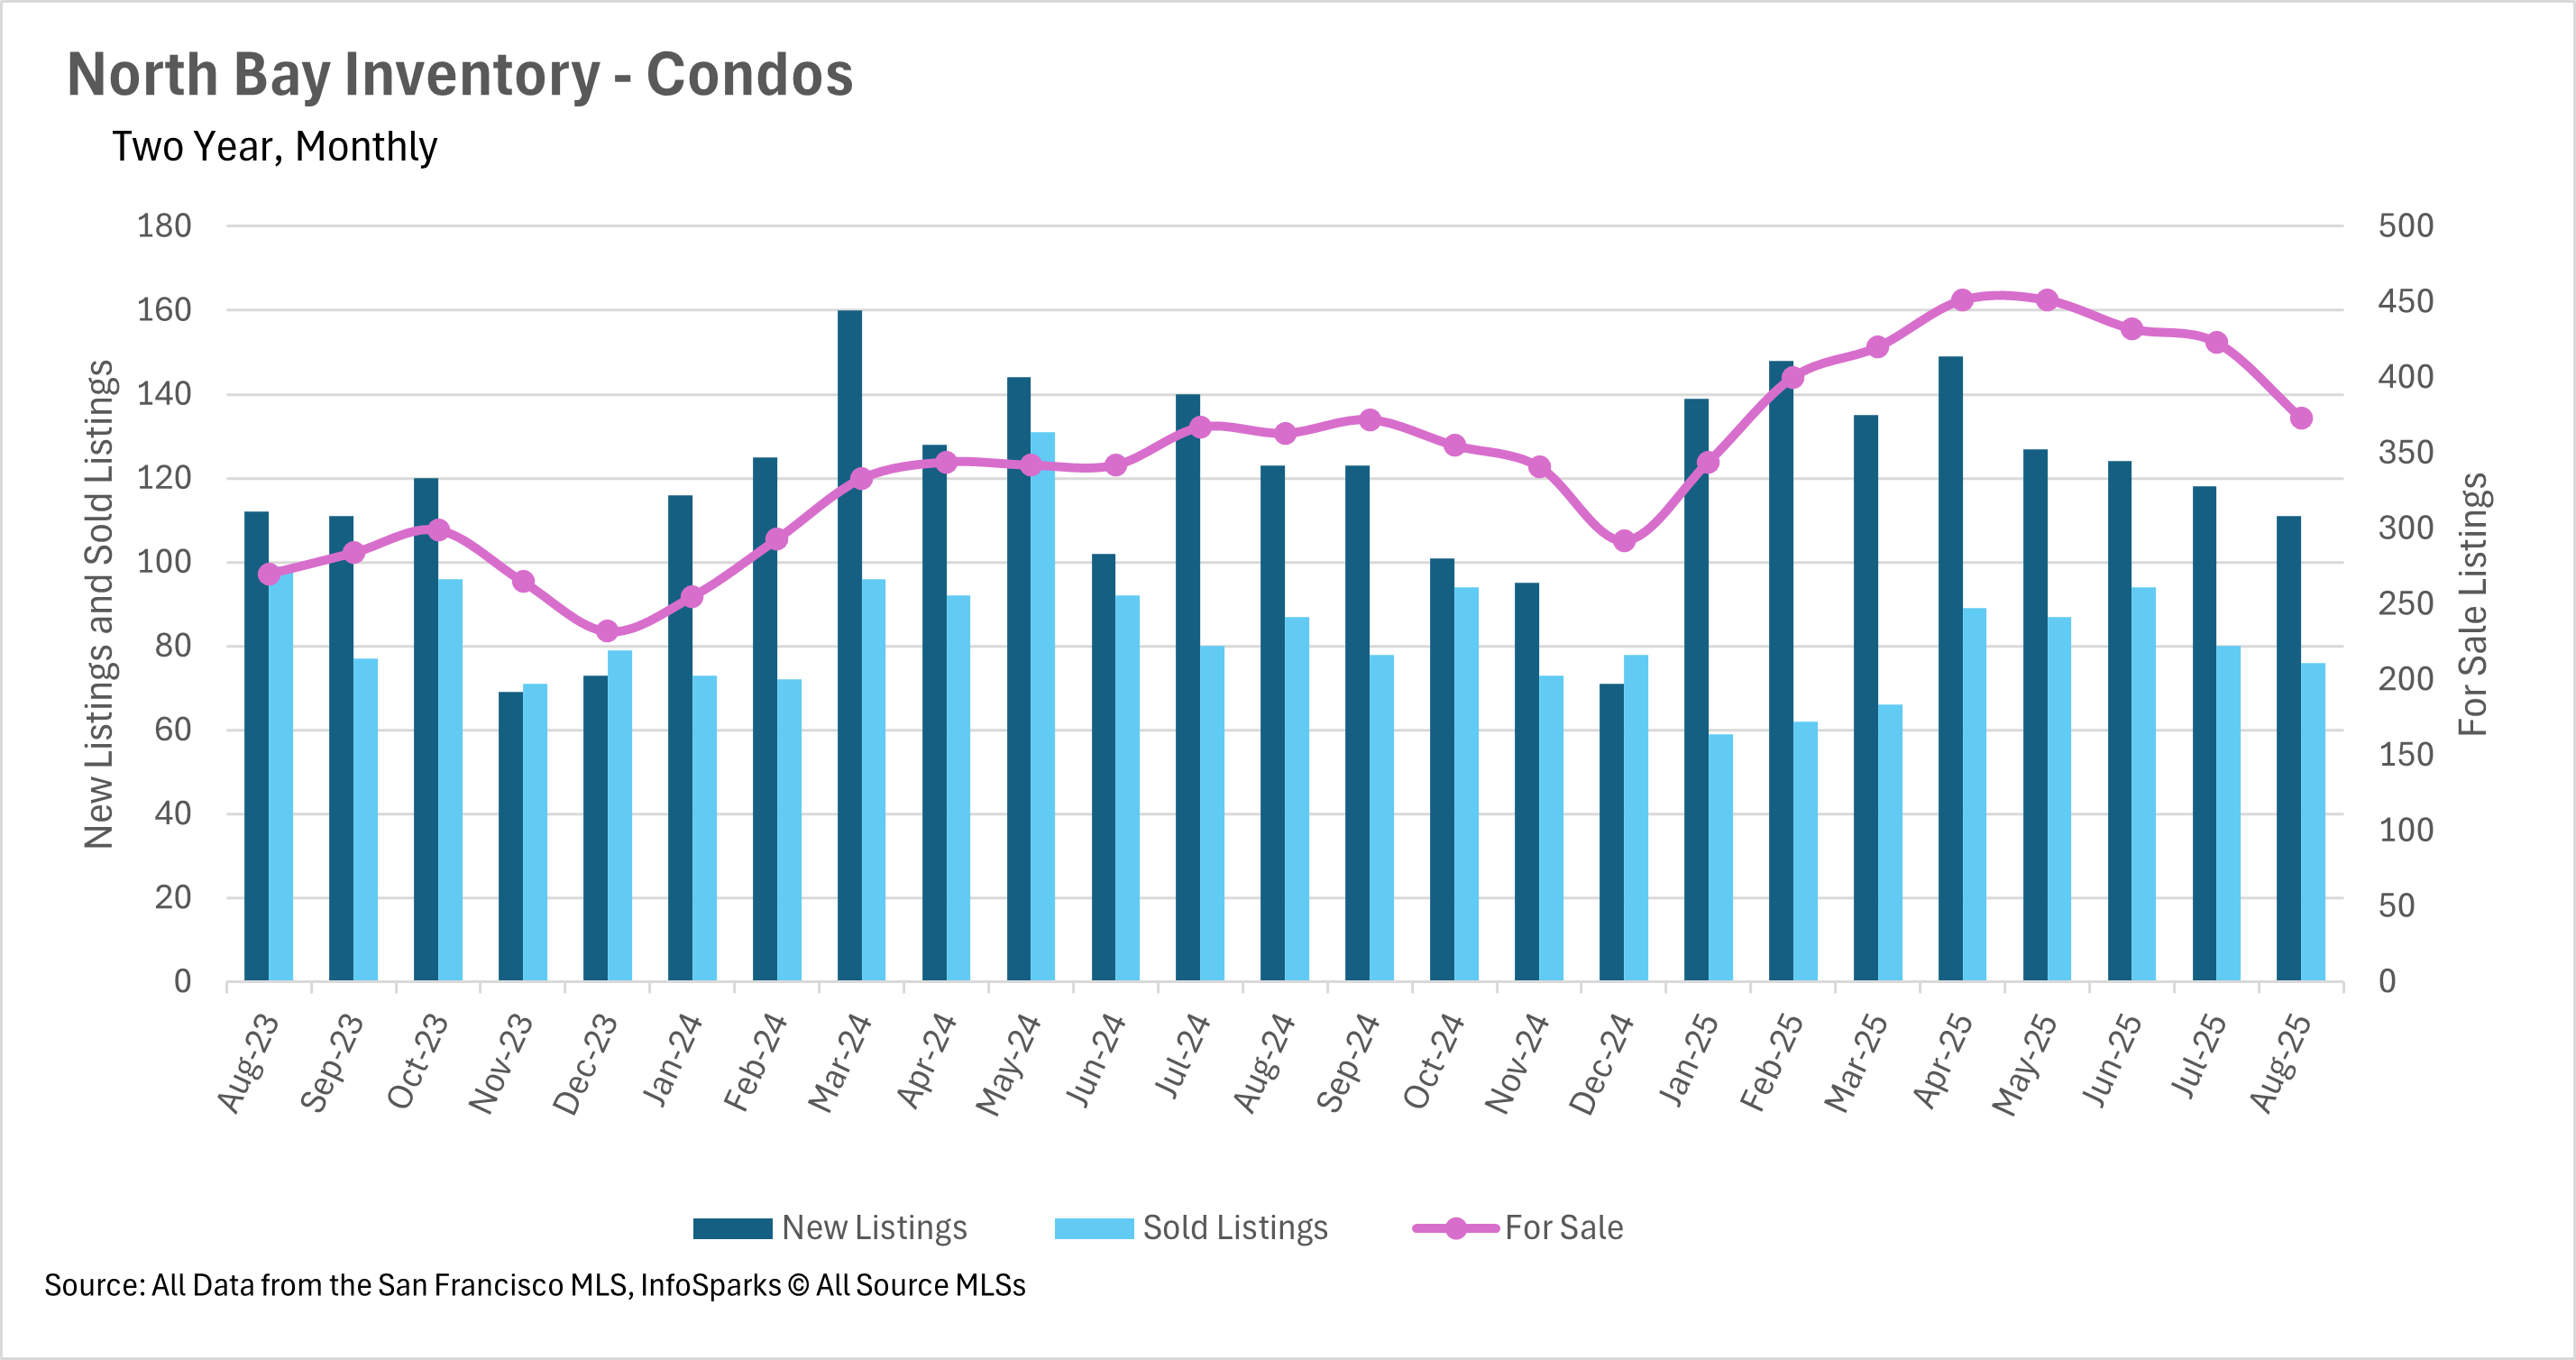
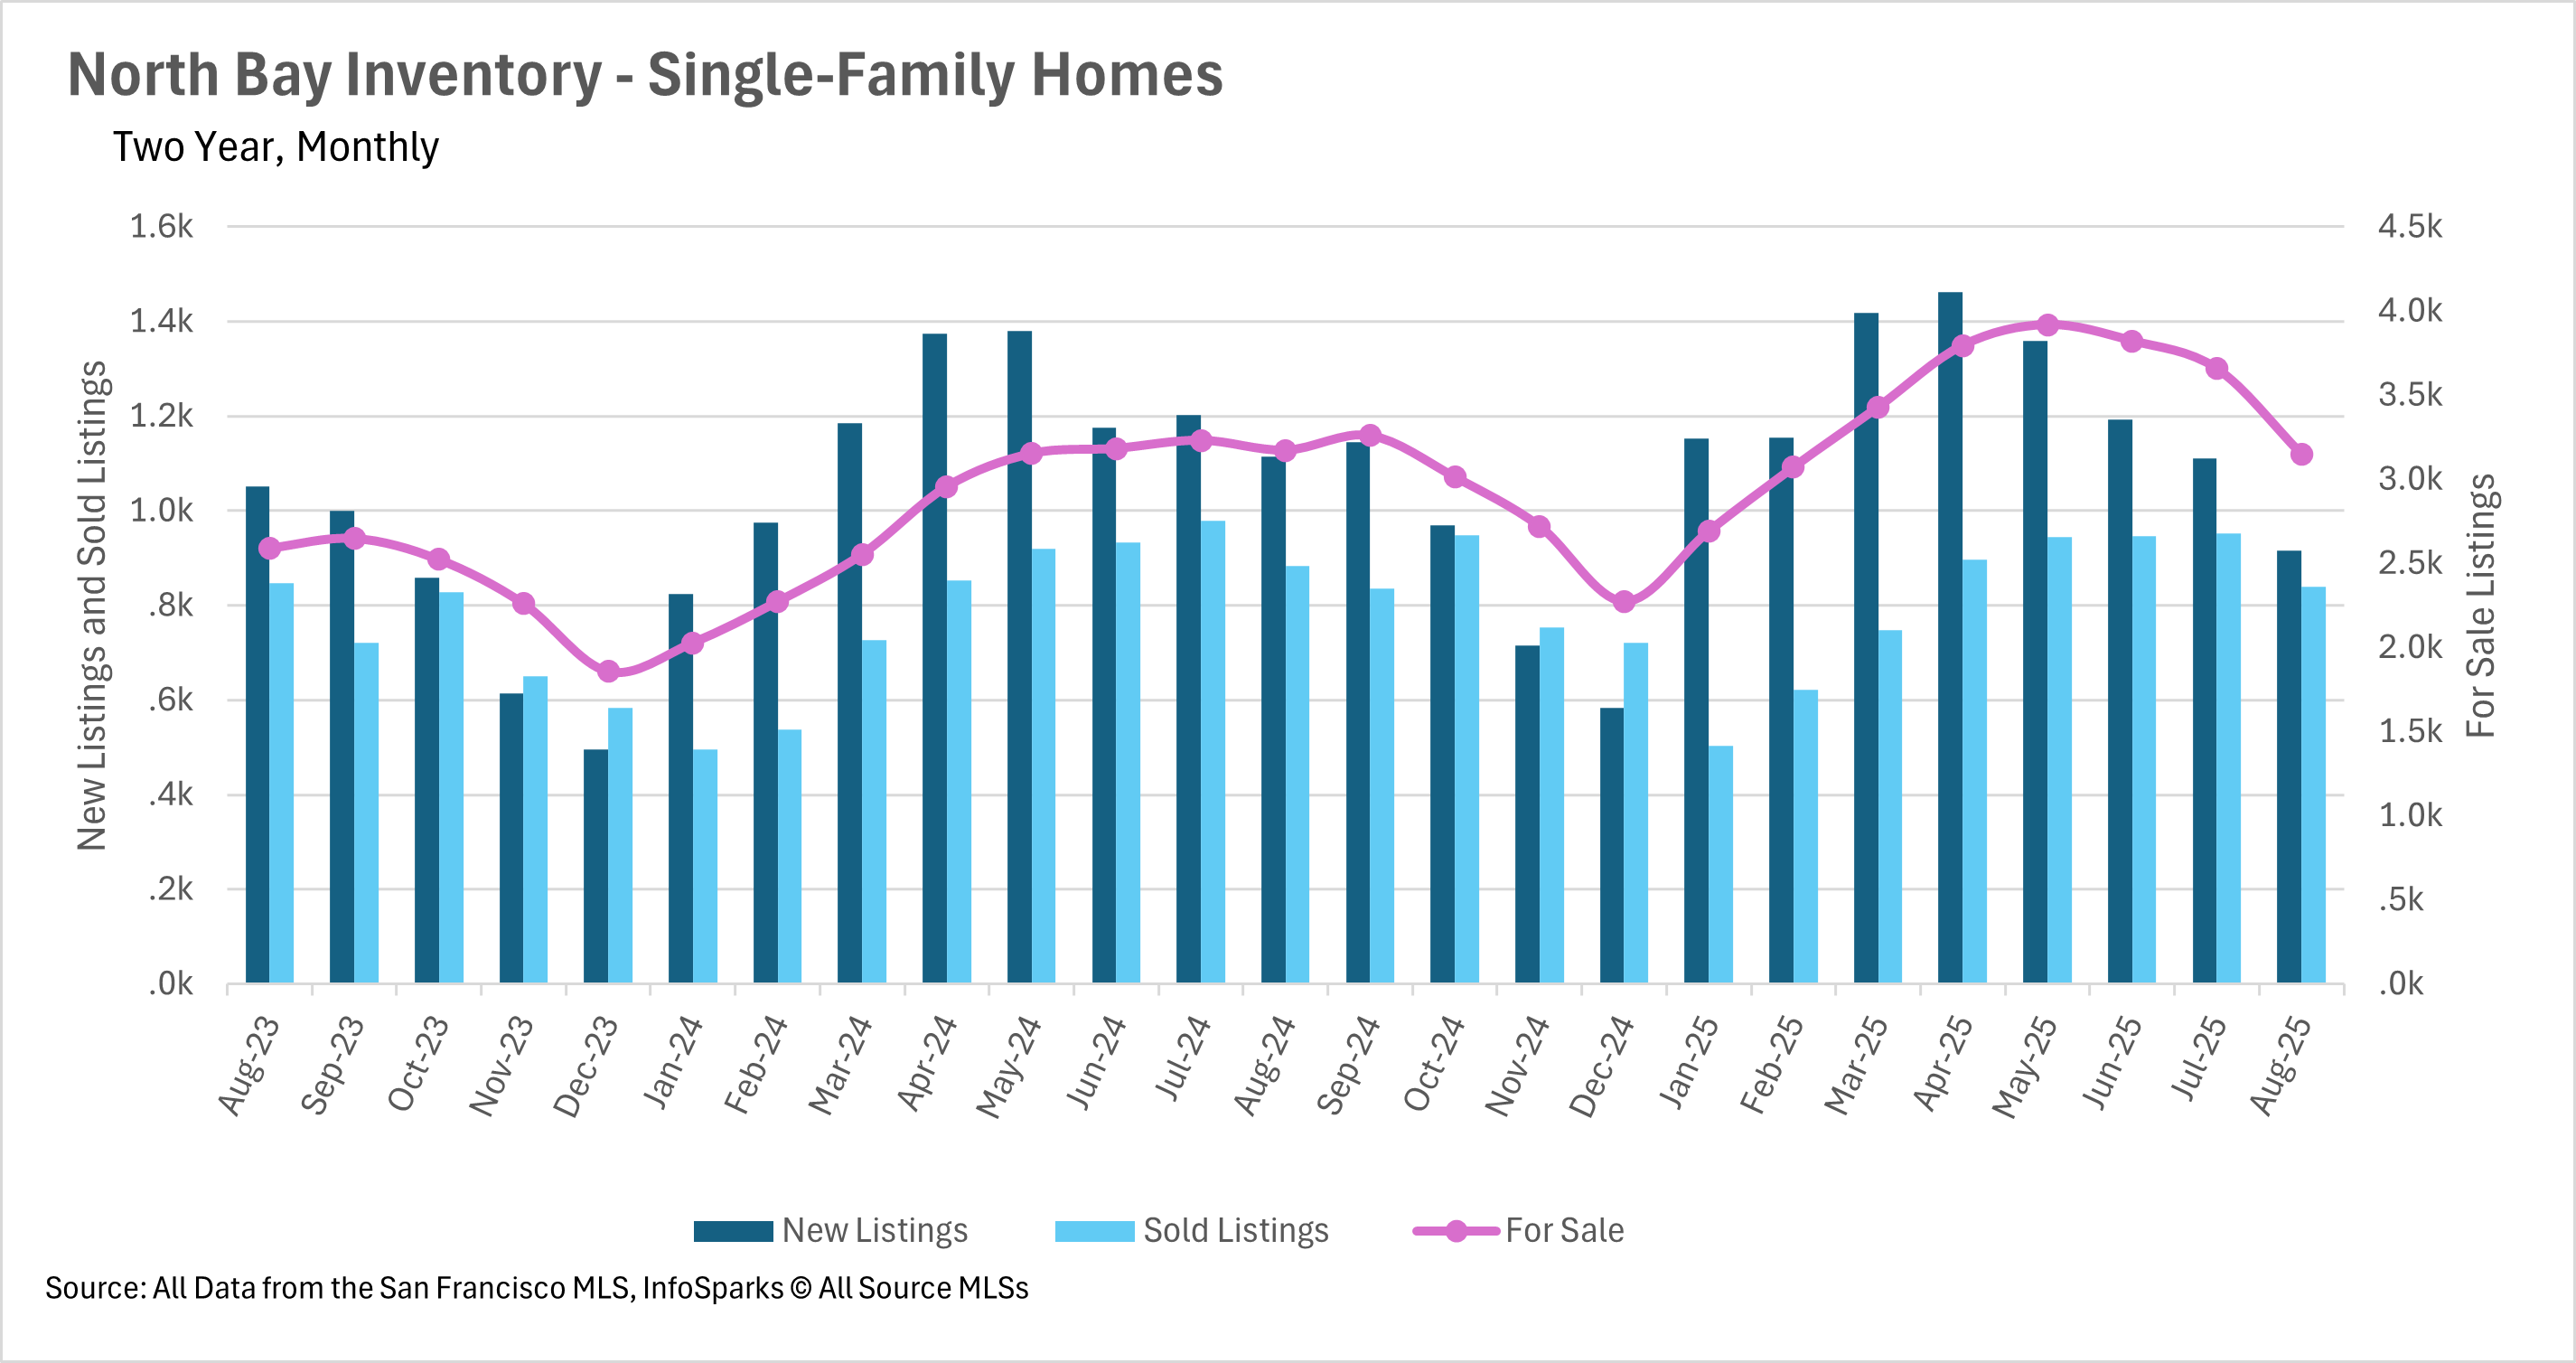
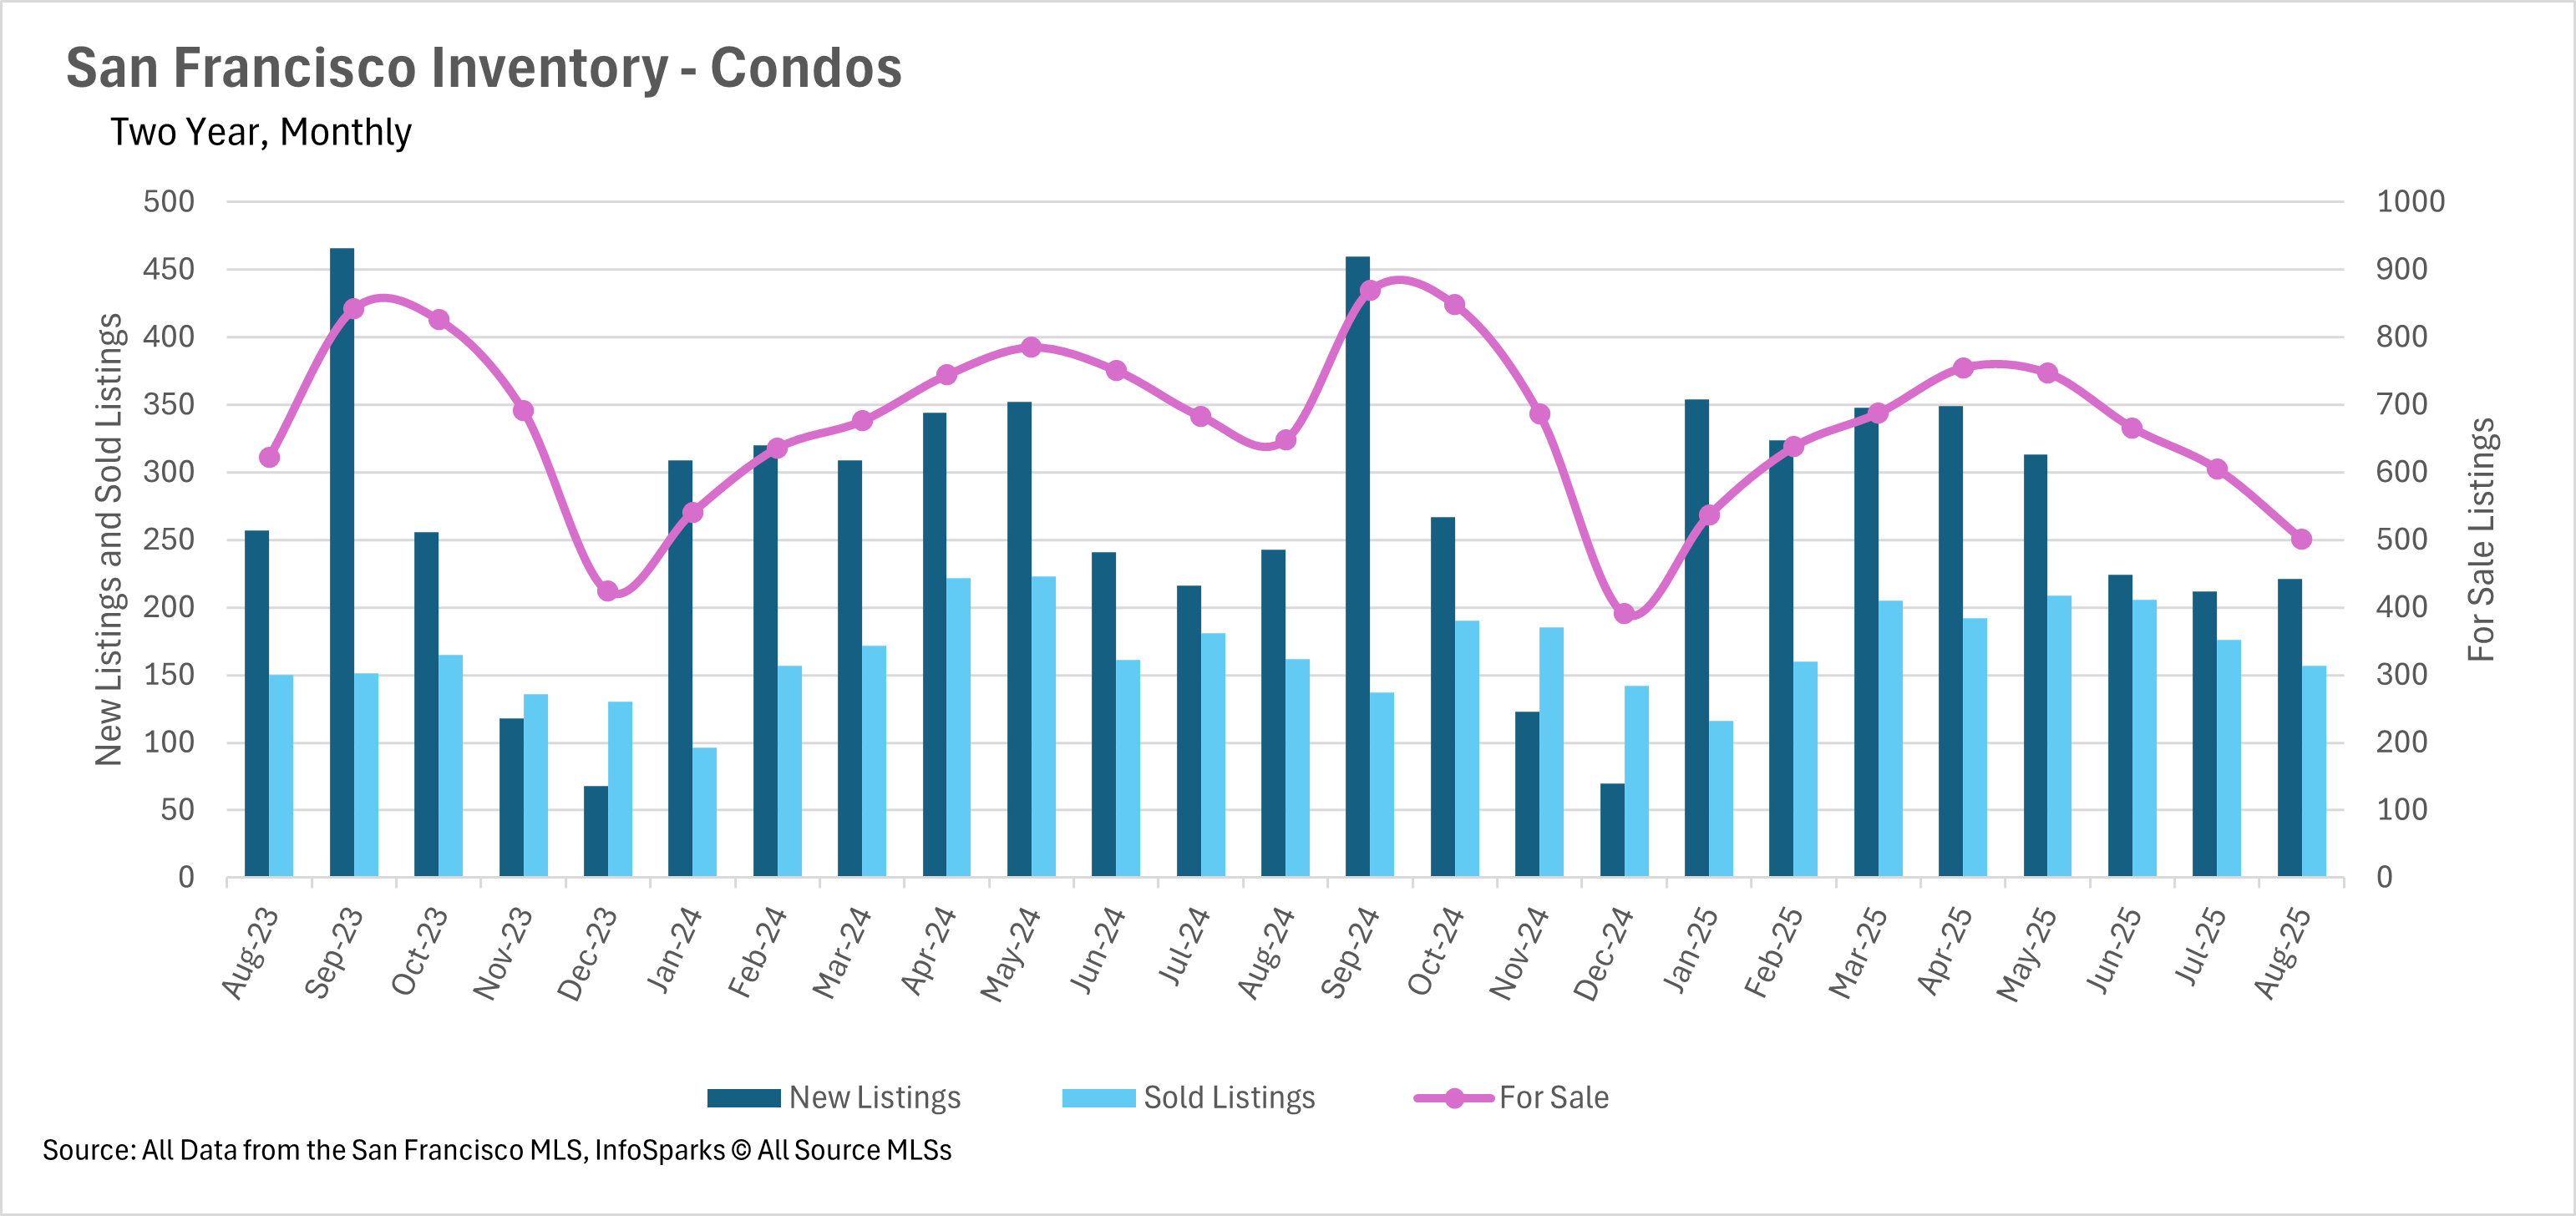
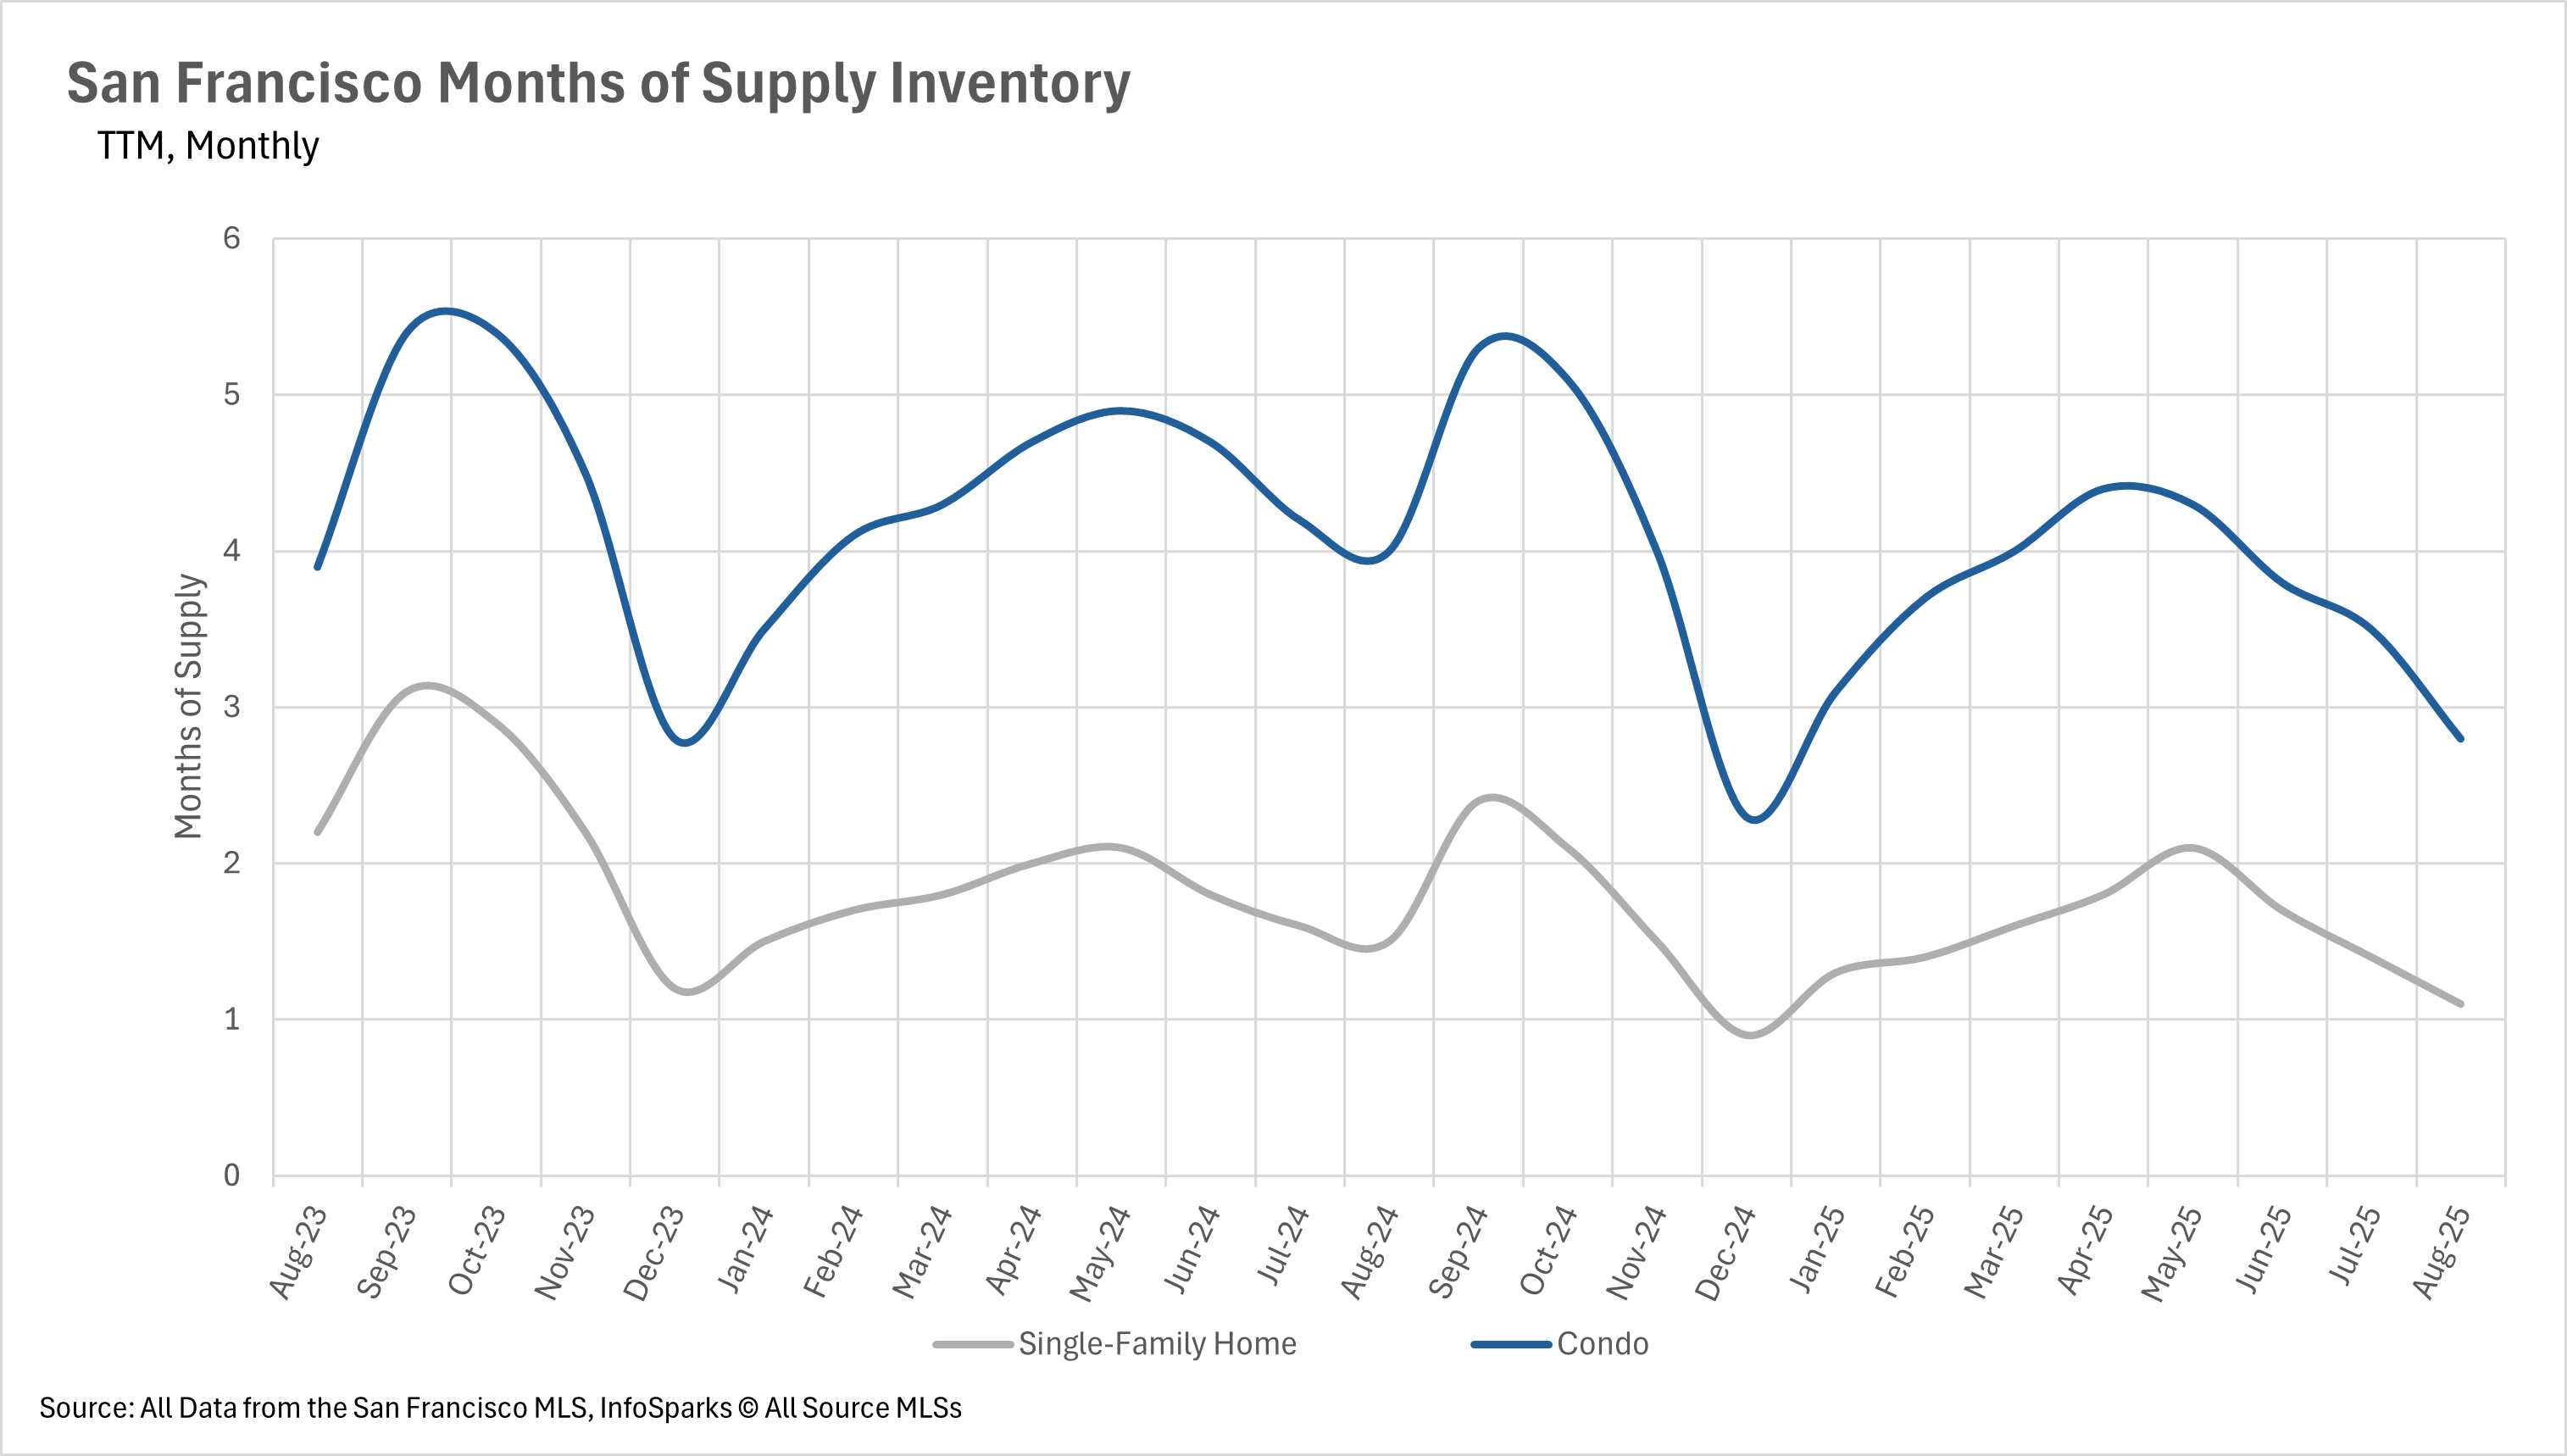
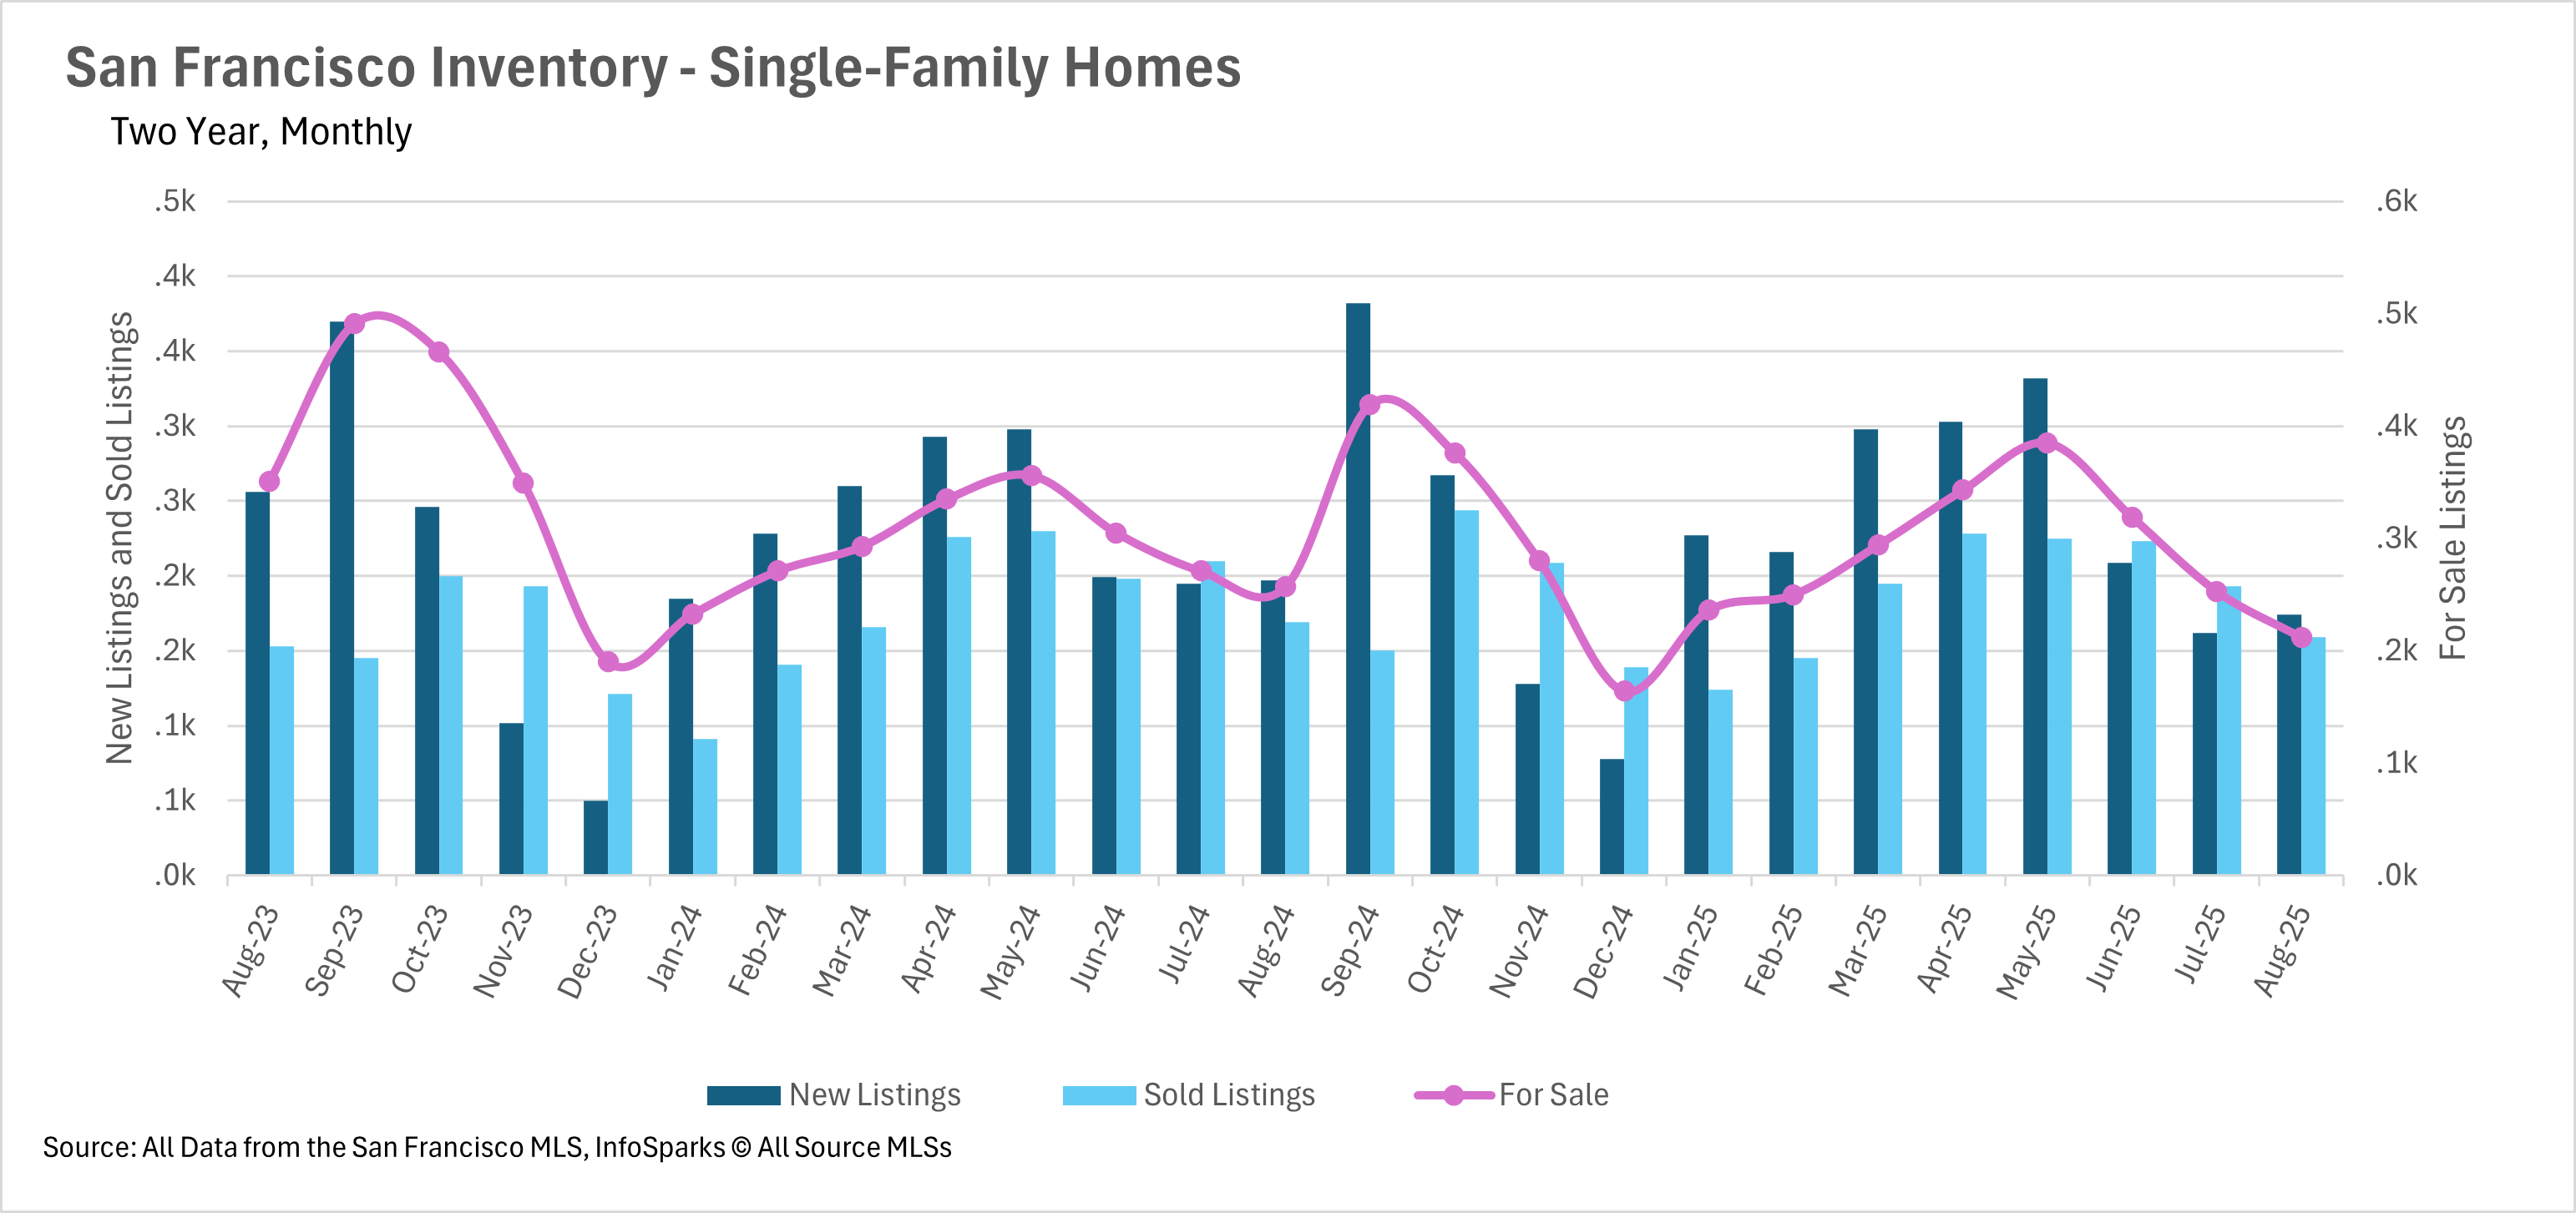
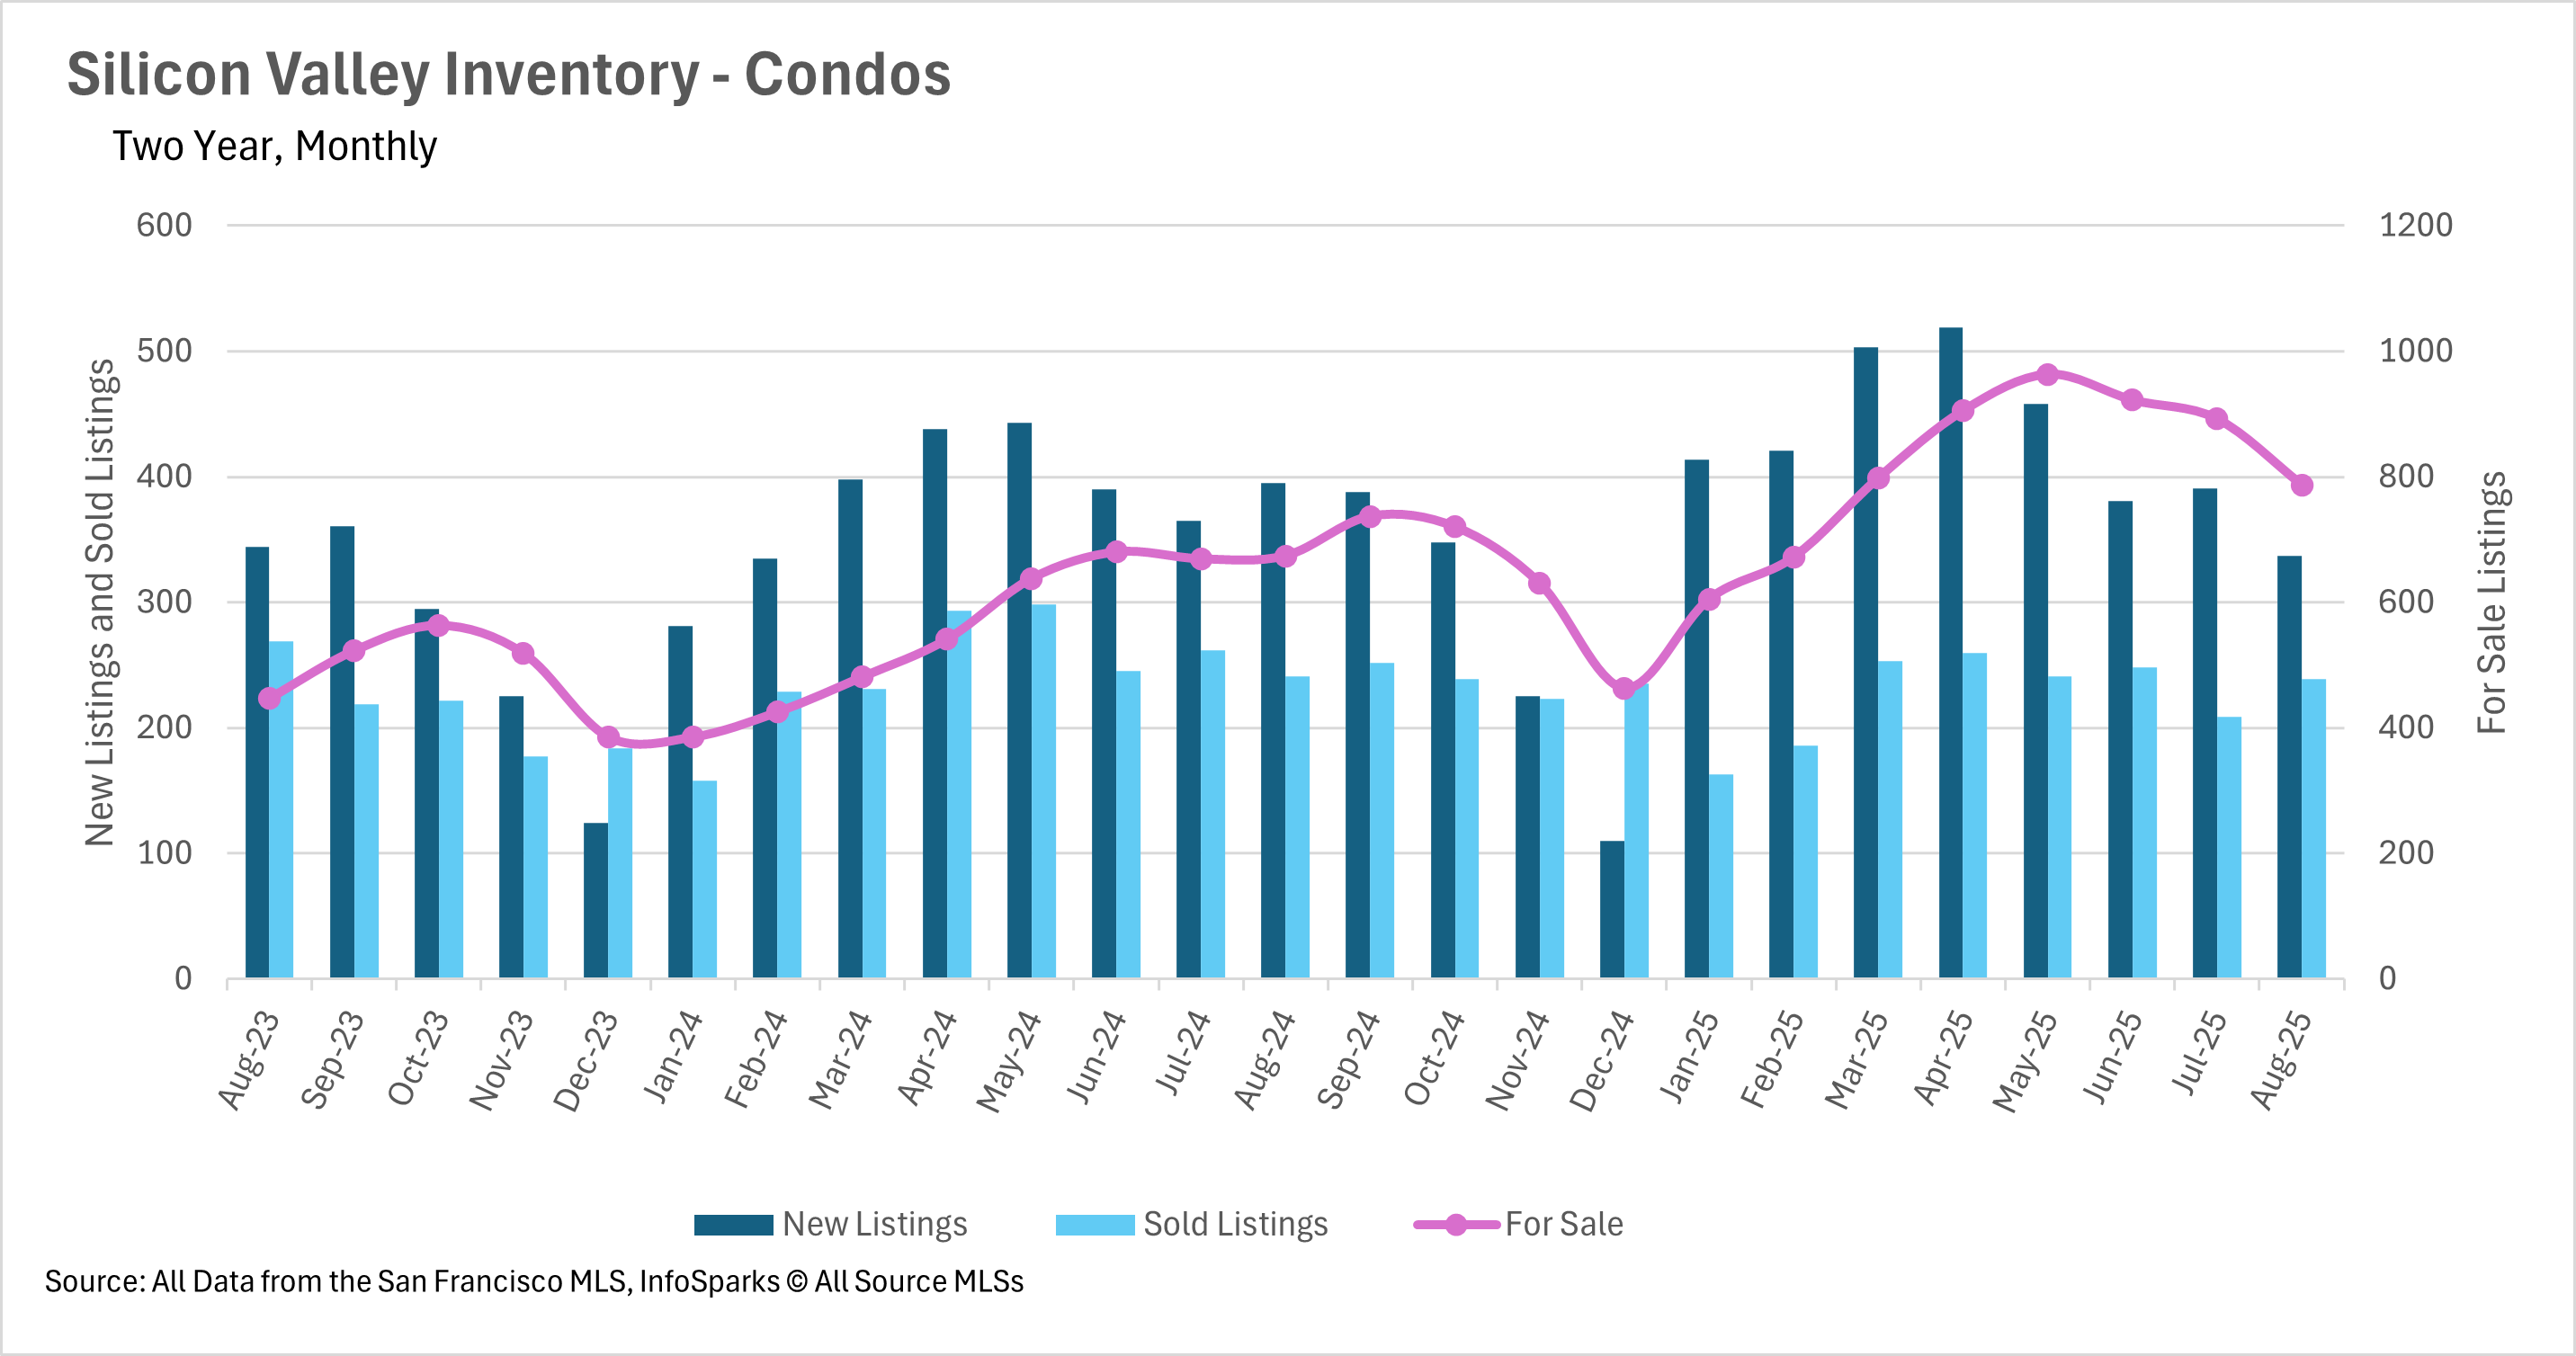
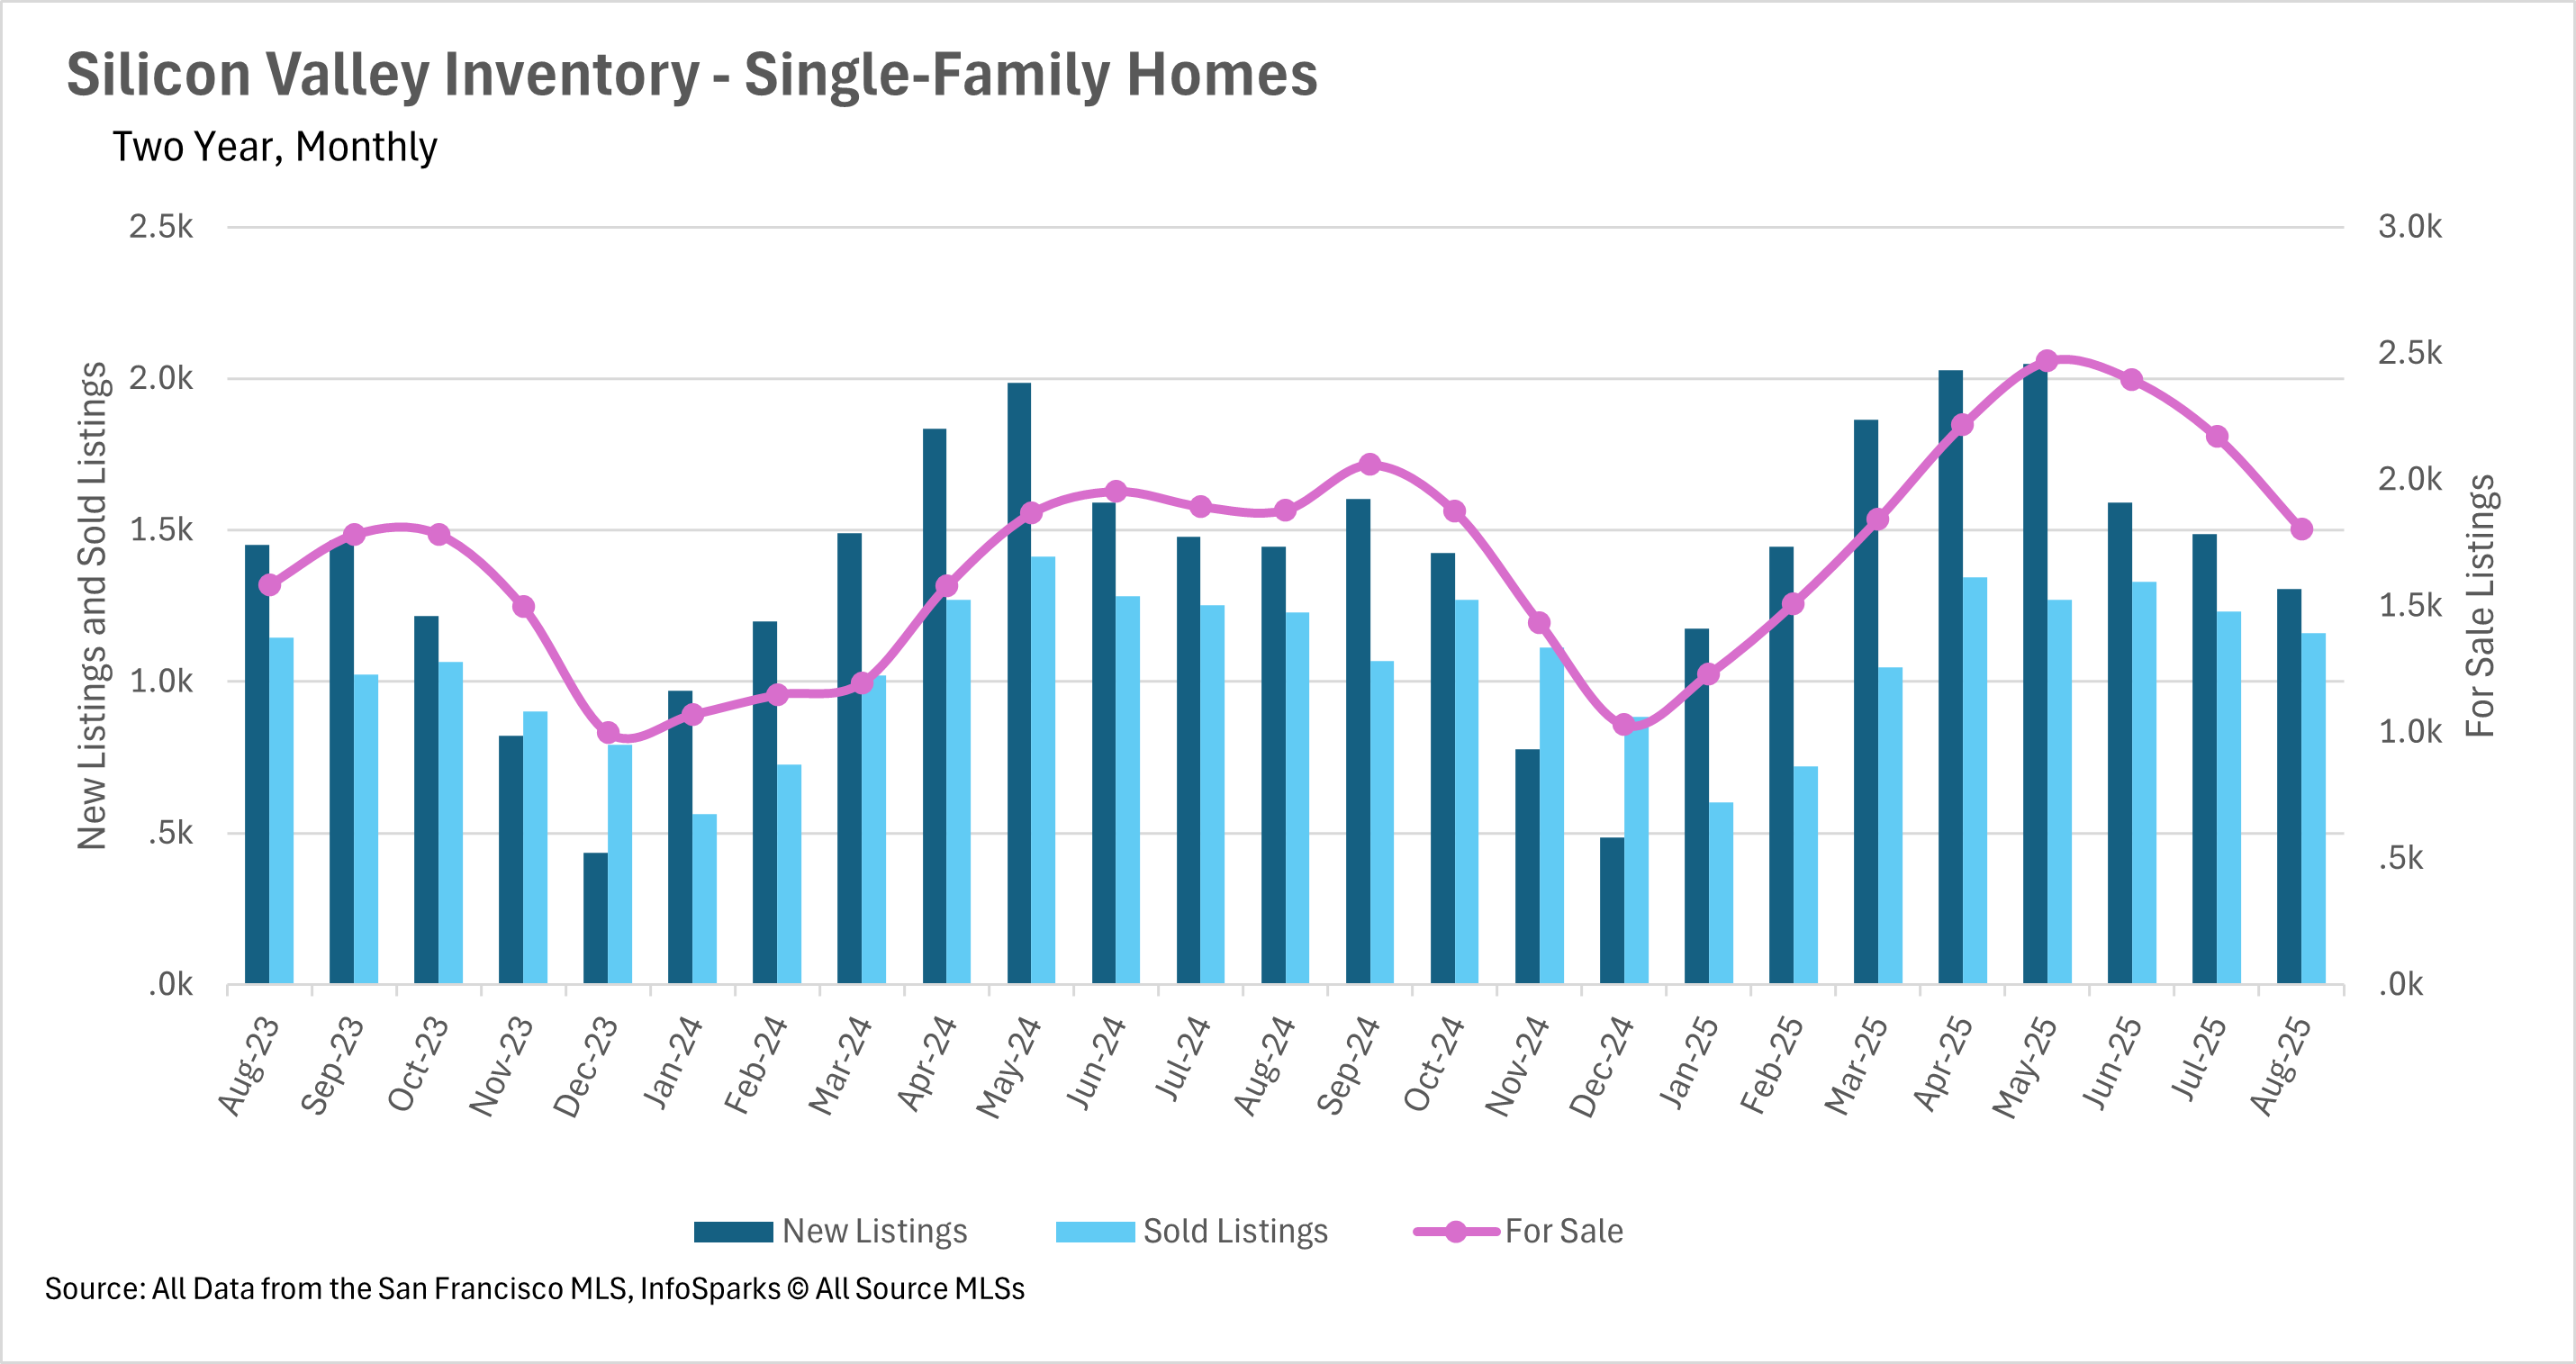
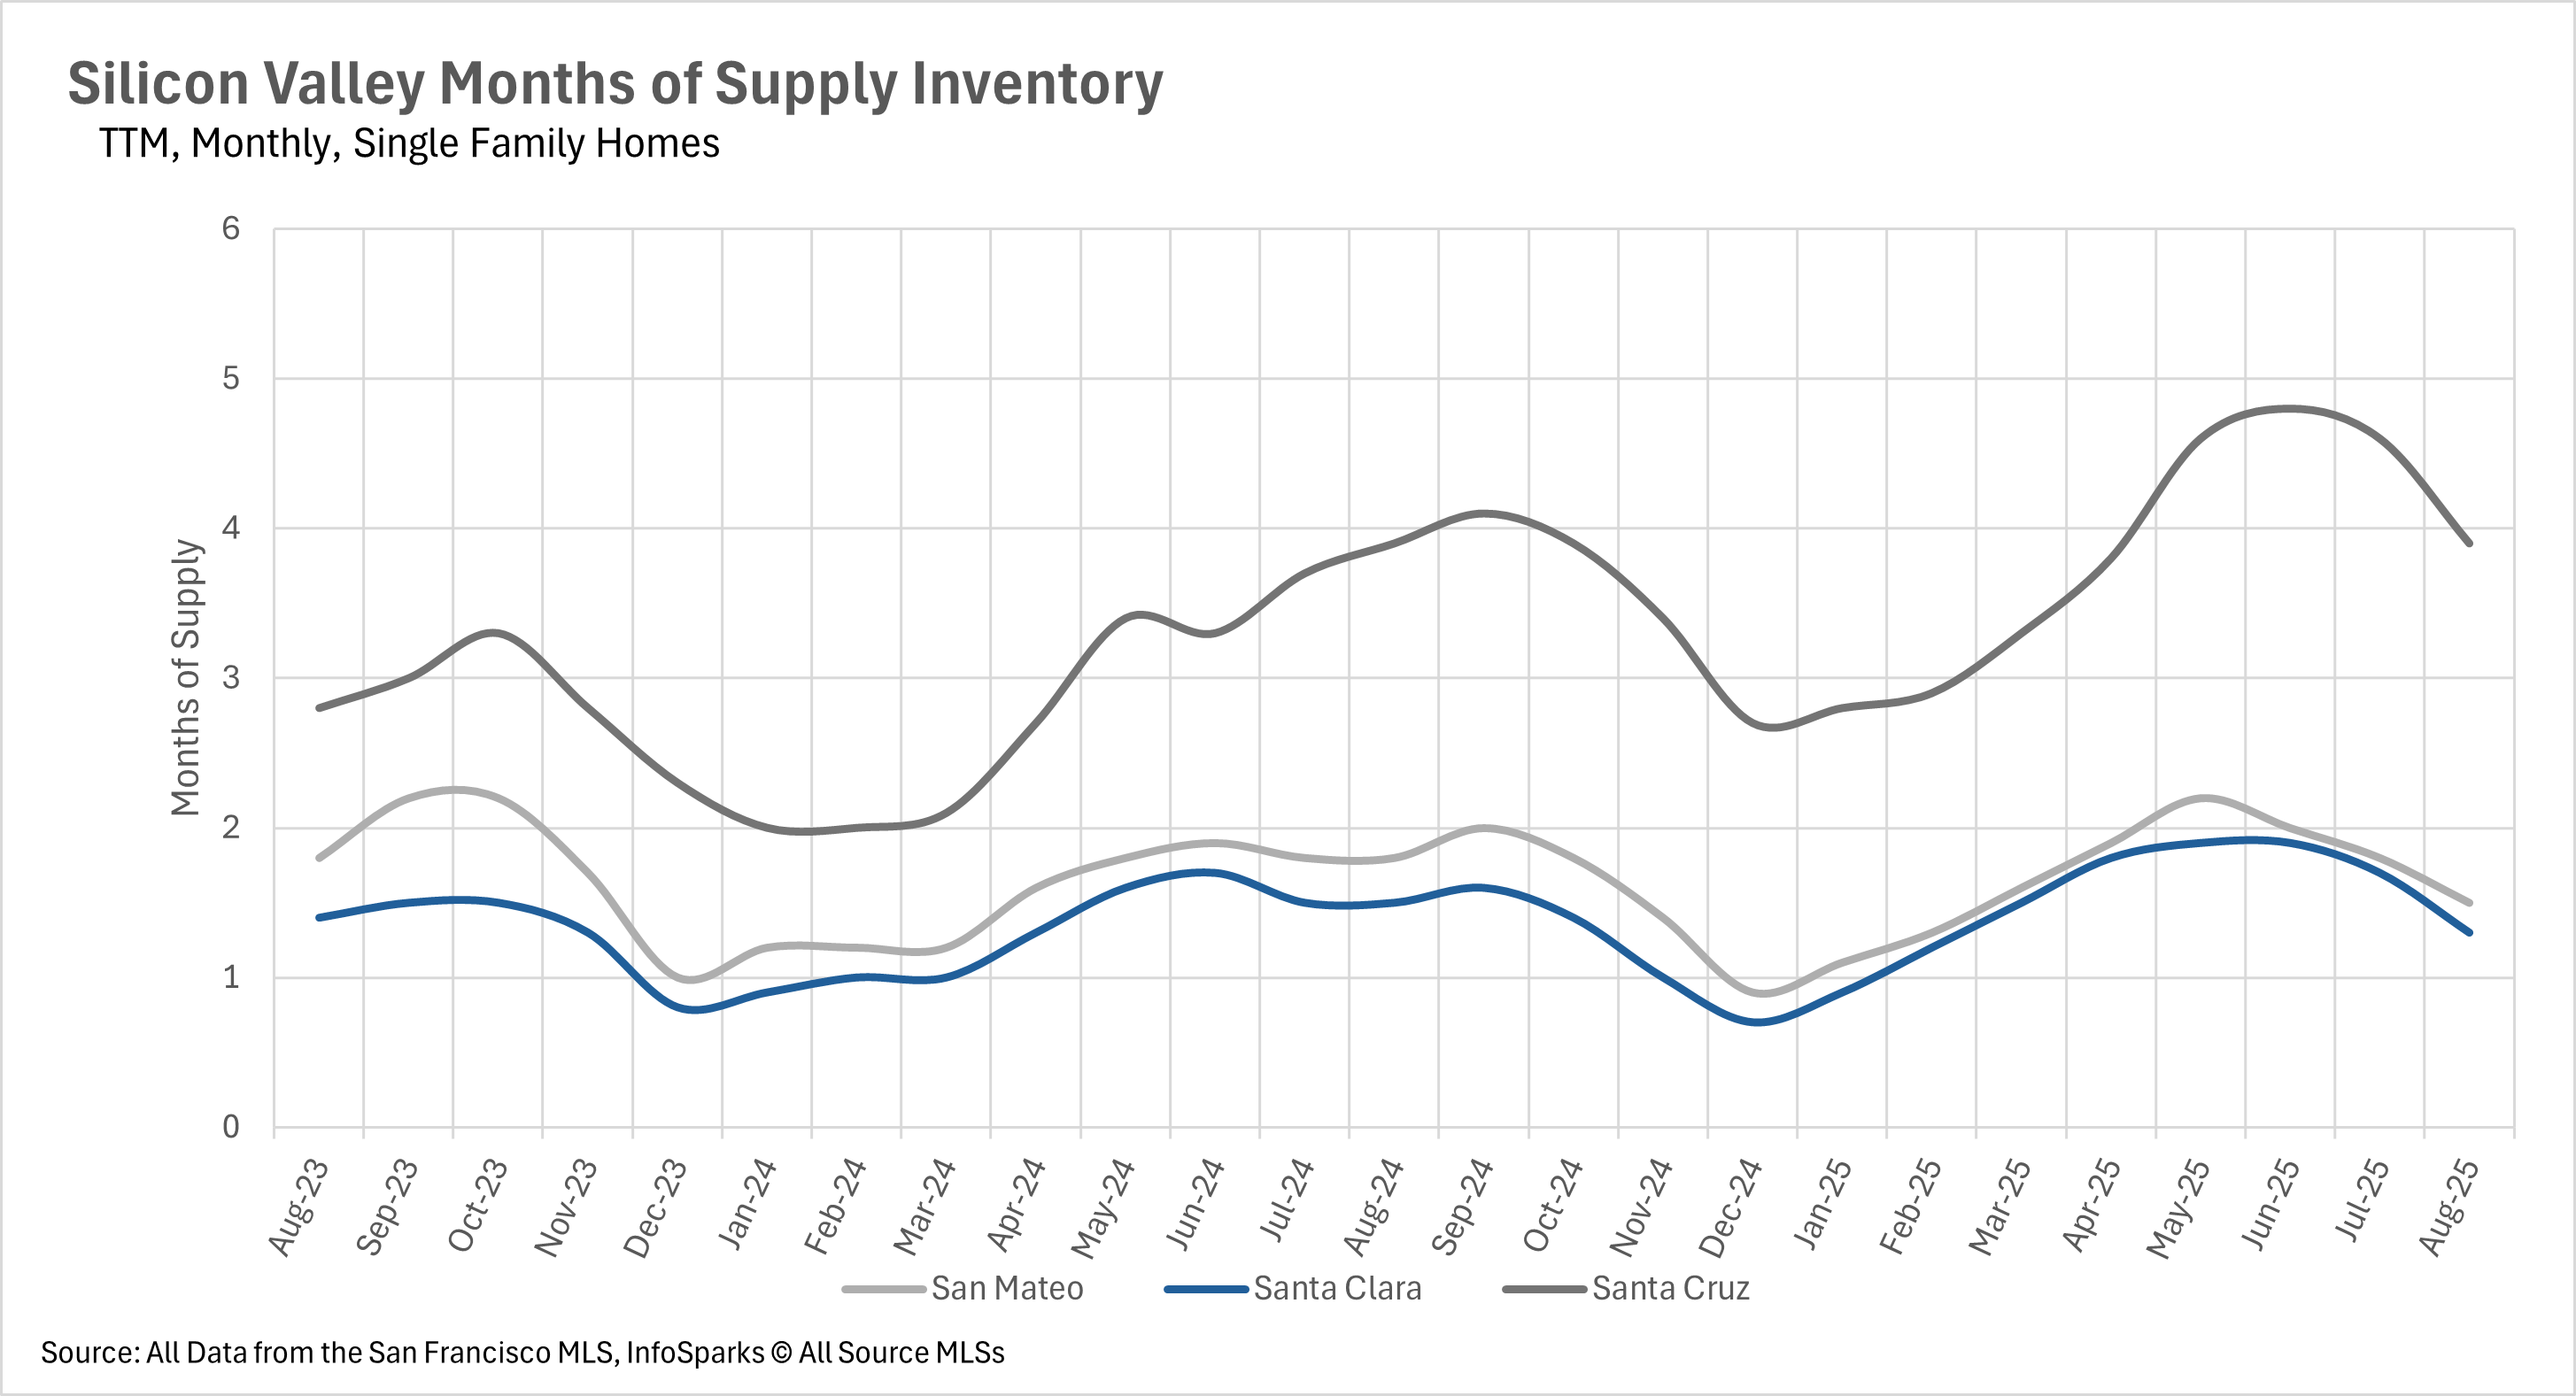
August marked a significant shift in Bay Area inventory dynamics, with most regions continuing the normalization process that began in the summer. San Francisco reached unprecedented territory with both single-family homes and condos achieving seller's market status - single-family inventory dropped to just 1.1 months of supply while condos fell to 2.8 months, representing the lowest levels ever recorded in the area. Single-family inventory declined 17.51% year-over-year, while condo inventory dropped 22.69%. Silicon Valley made a dramatic reversal, with single-family home inventory actually falling 4.04% below last year's levels for the first time in months, though condo inventory remained elevated at 16.77% above last year's levels - still a significant improvement from prior months. The North Bay showed the most balanced inventory picture, with single-family homes down just 0.73% year-over-year and condos up a modest 2.75%, indicating near-normalization. The East Bay, while still elevated, continued its downward trajectory with single-family inventory at 9.97% above last year and condos at 11.67% - substantial decreases from peak levels. Notably, most regions experienced fewer new listings hitting the market year-over-year, suggesting seller hesitancy rather than increased buyer absorption as the primary driver of inventory declines.
Days on market increase despite inventory improvements
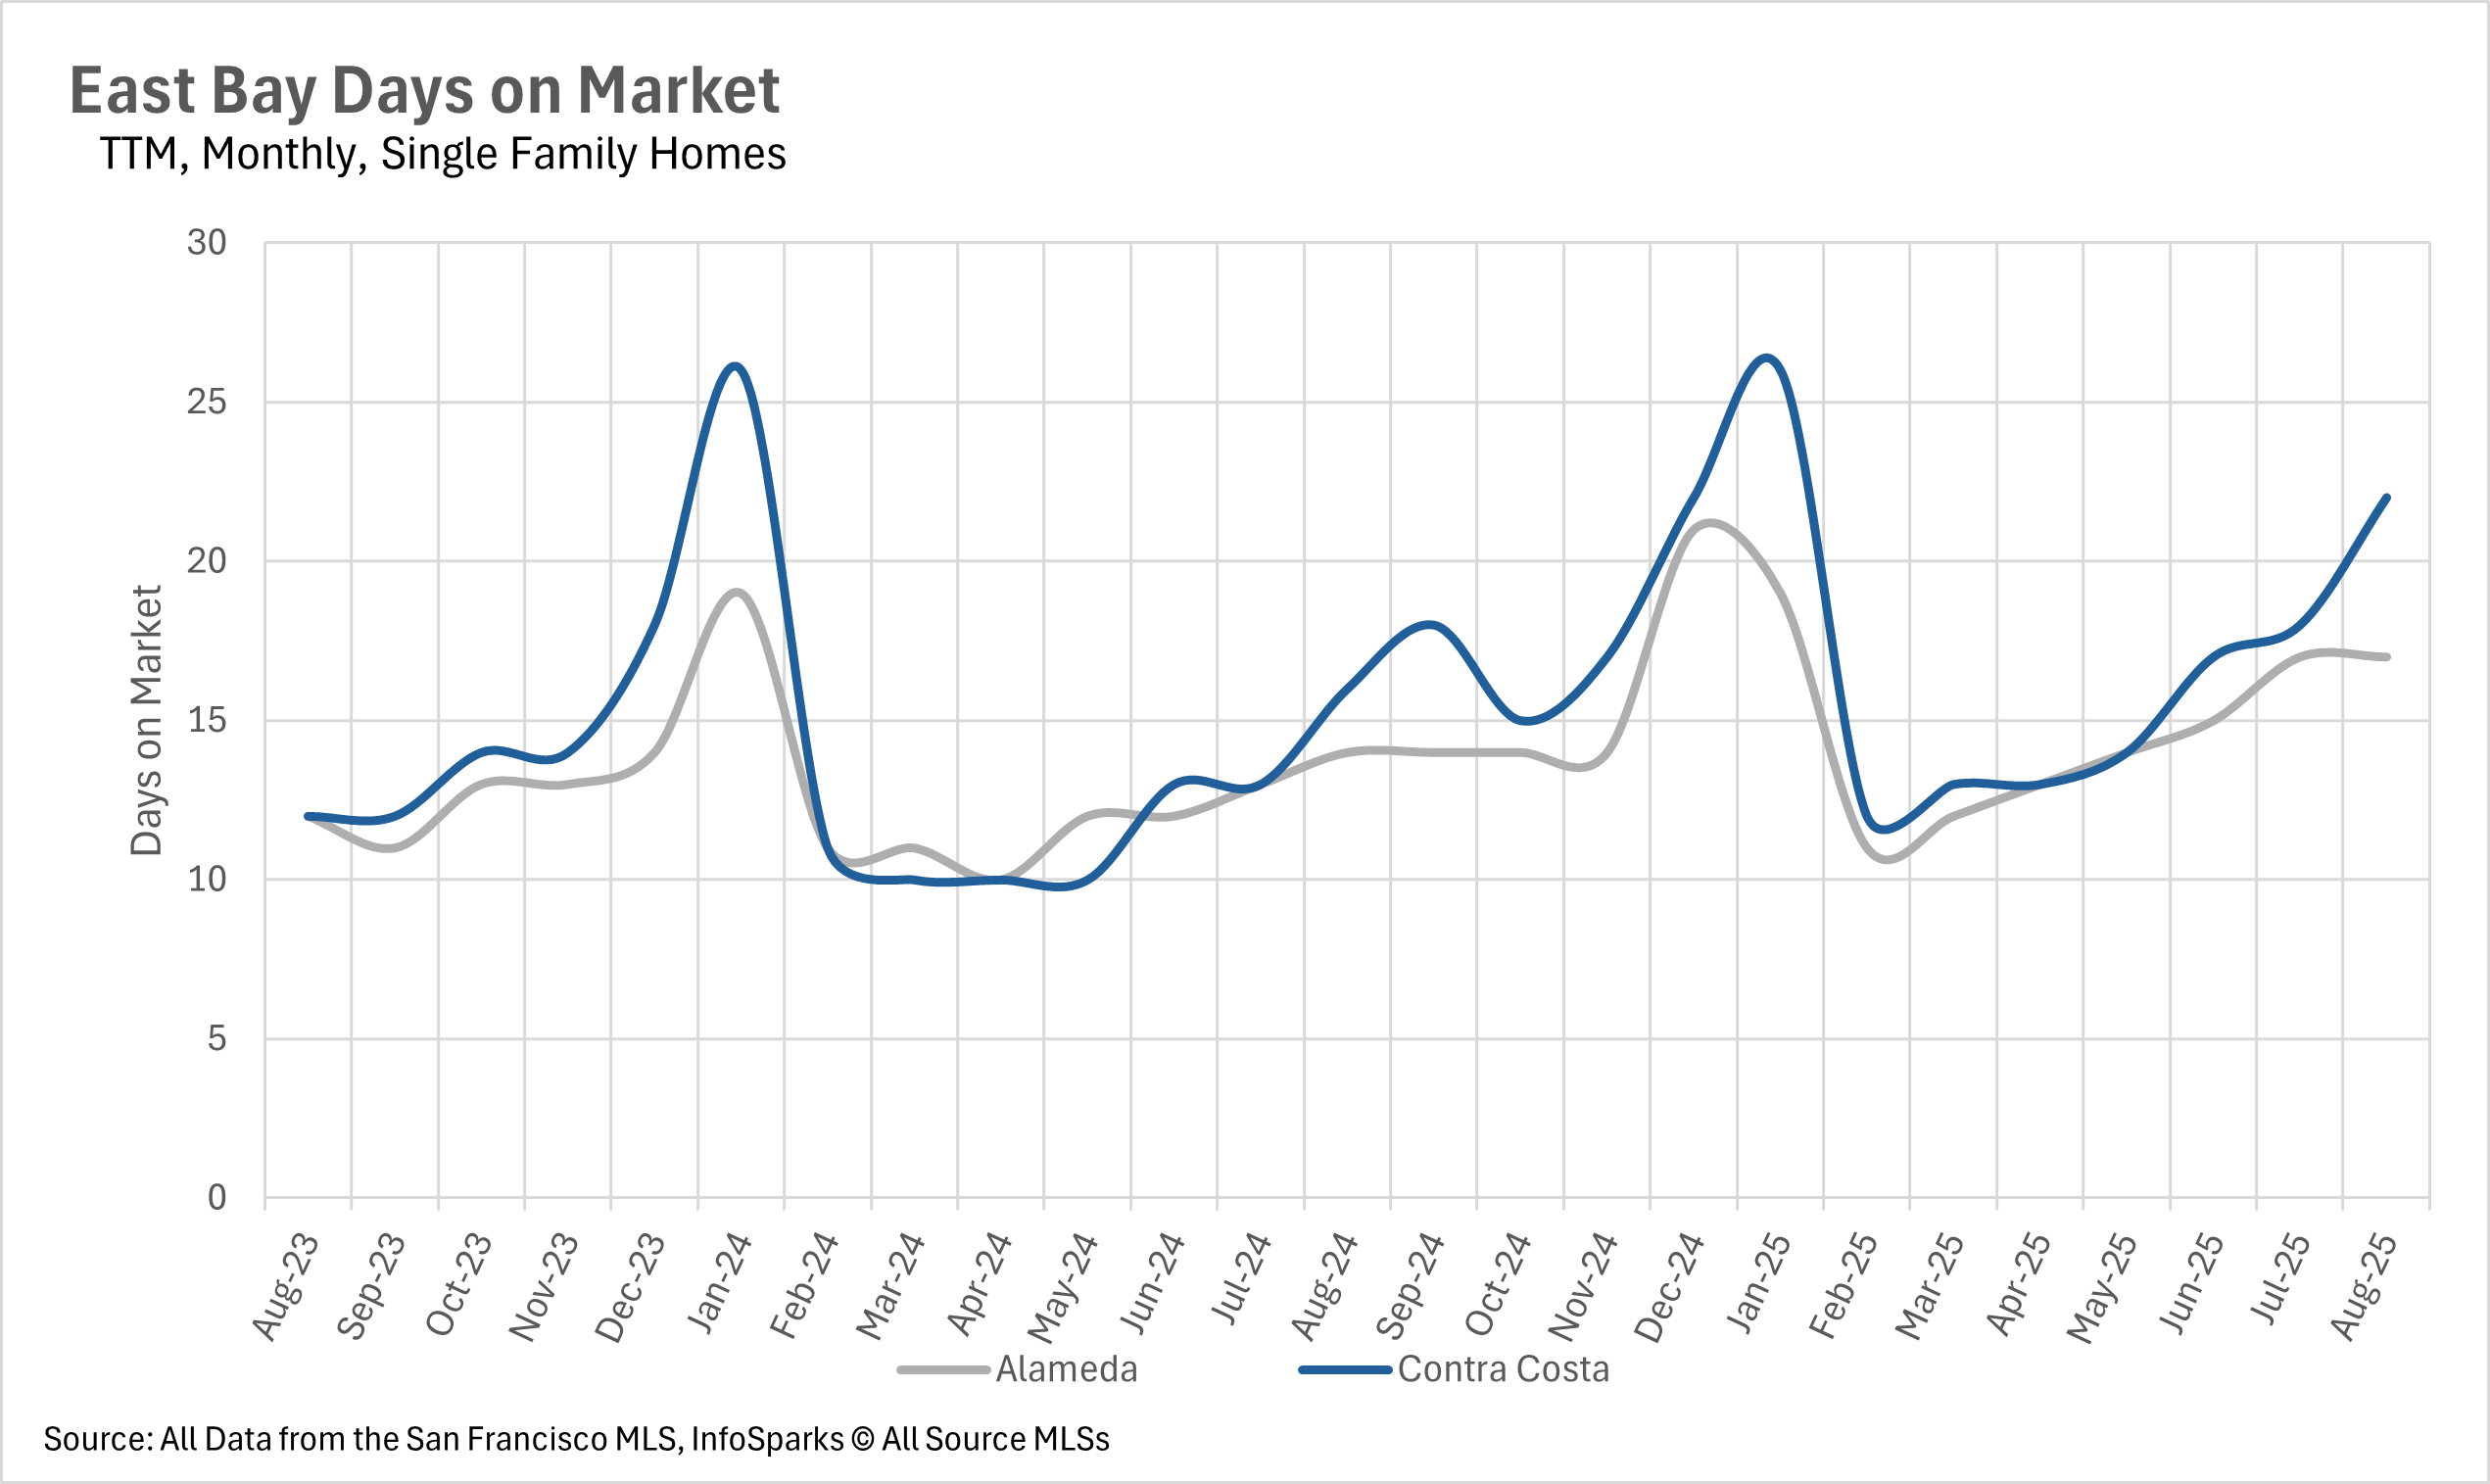
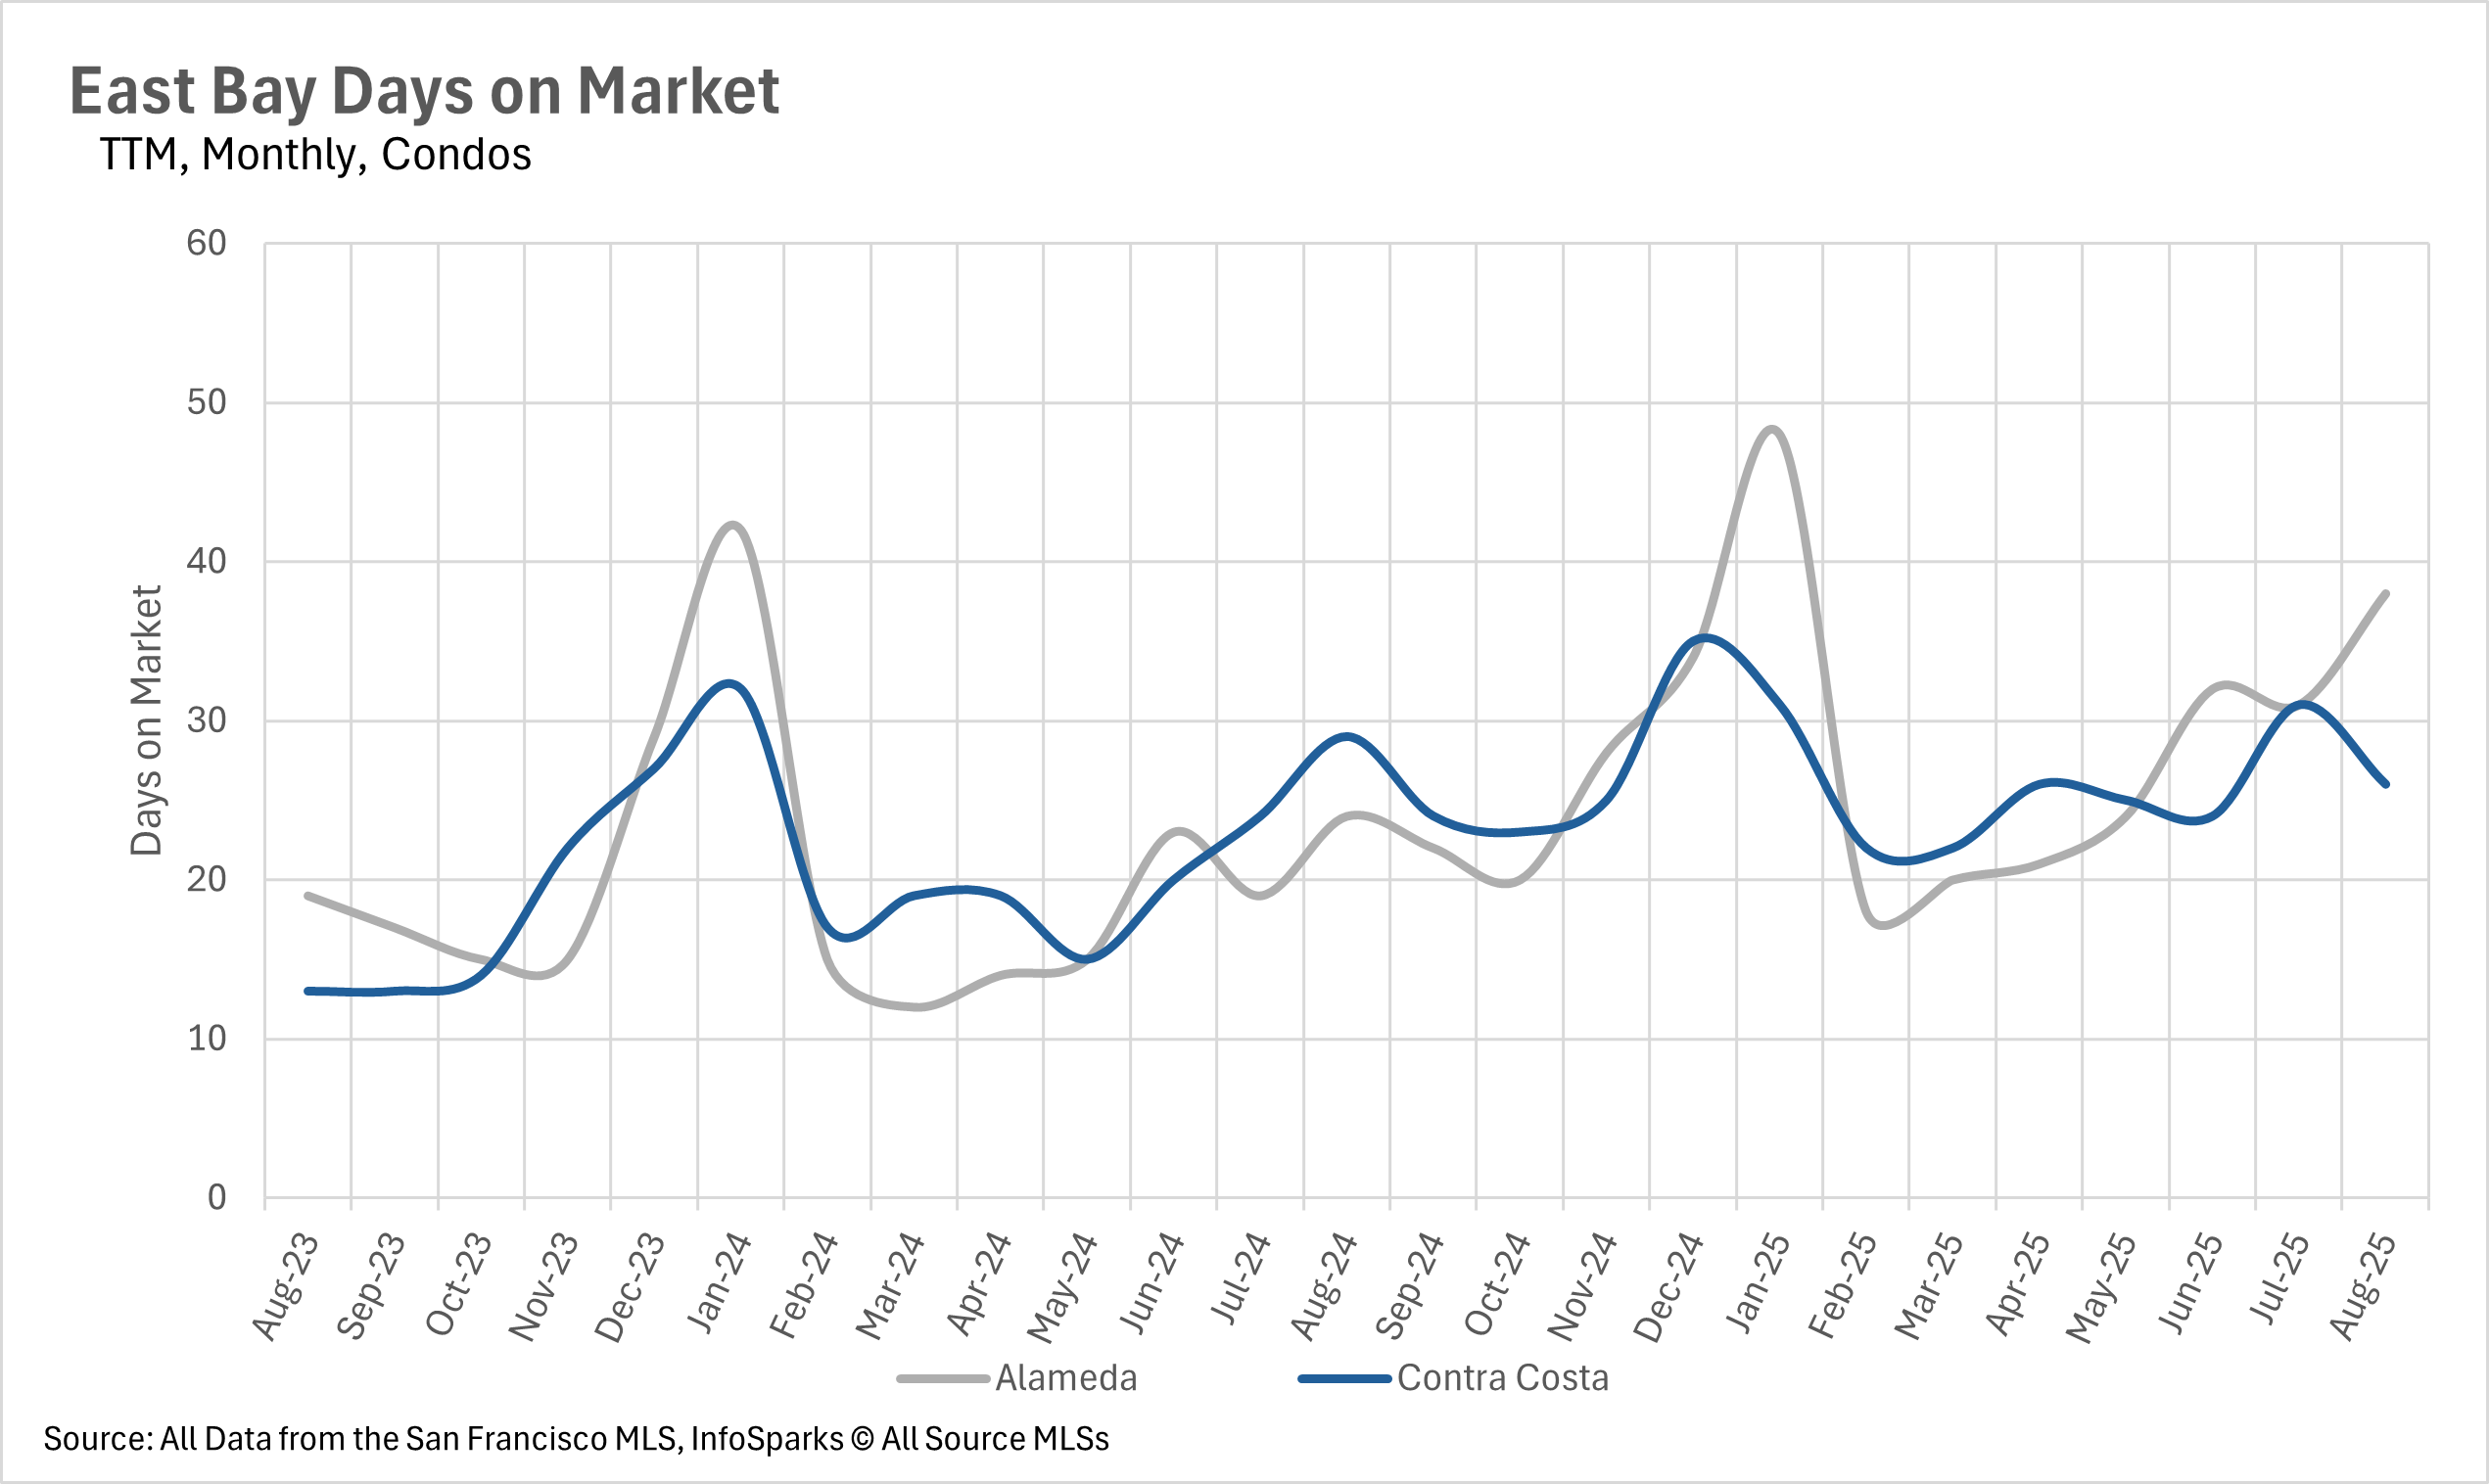
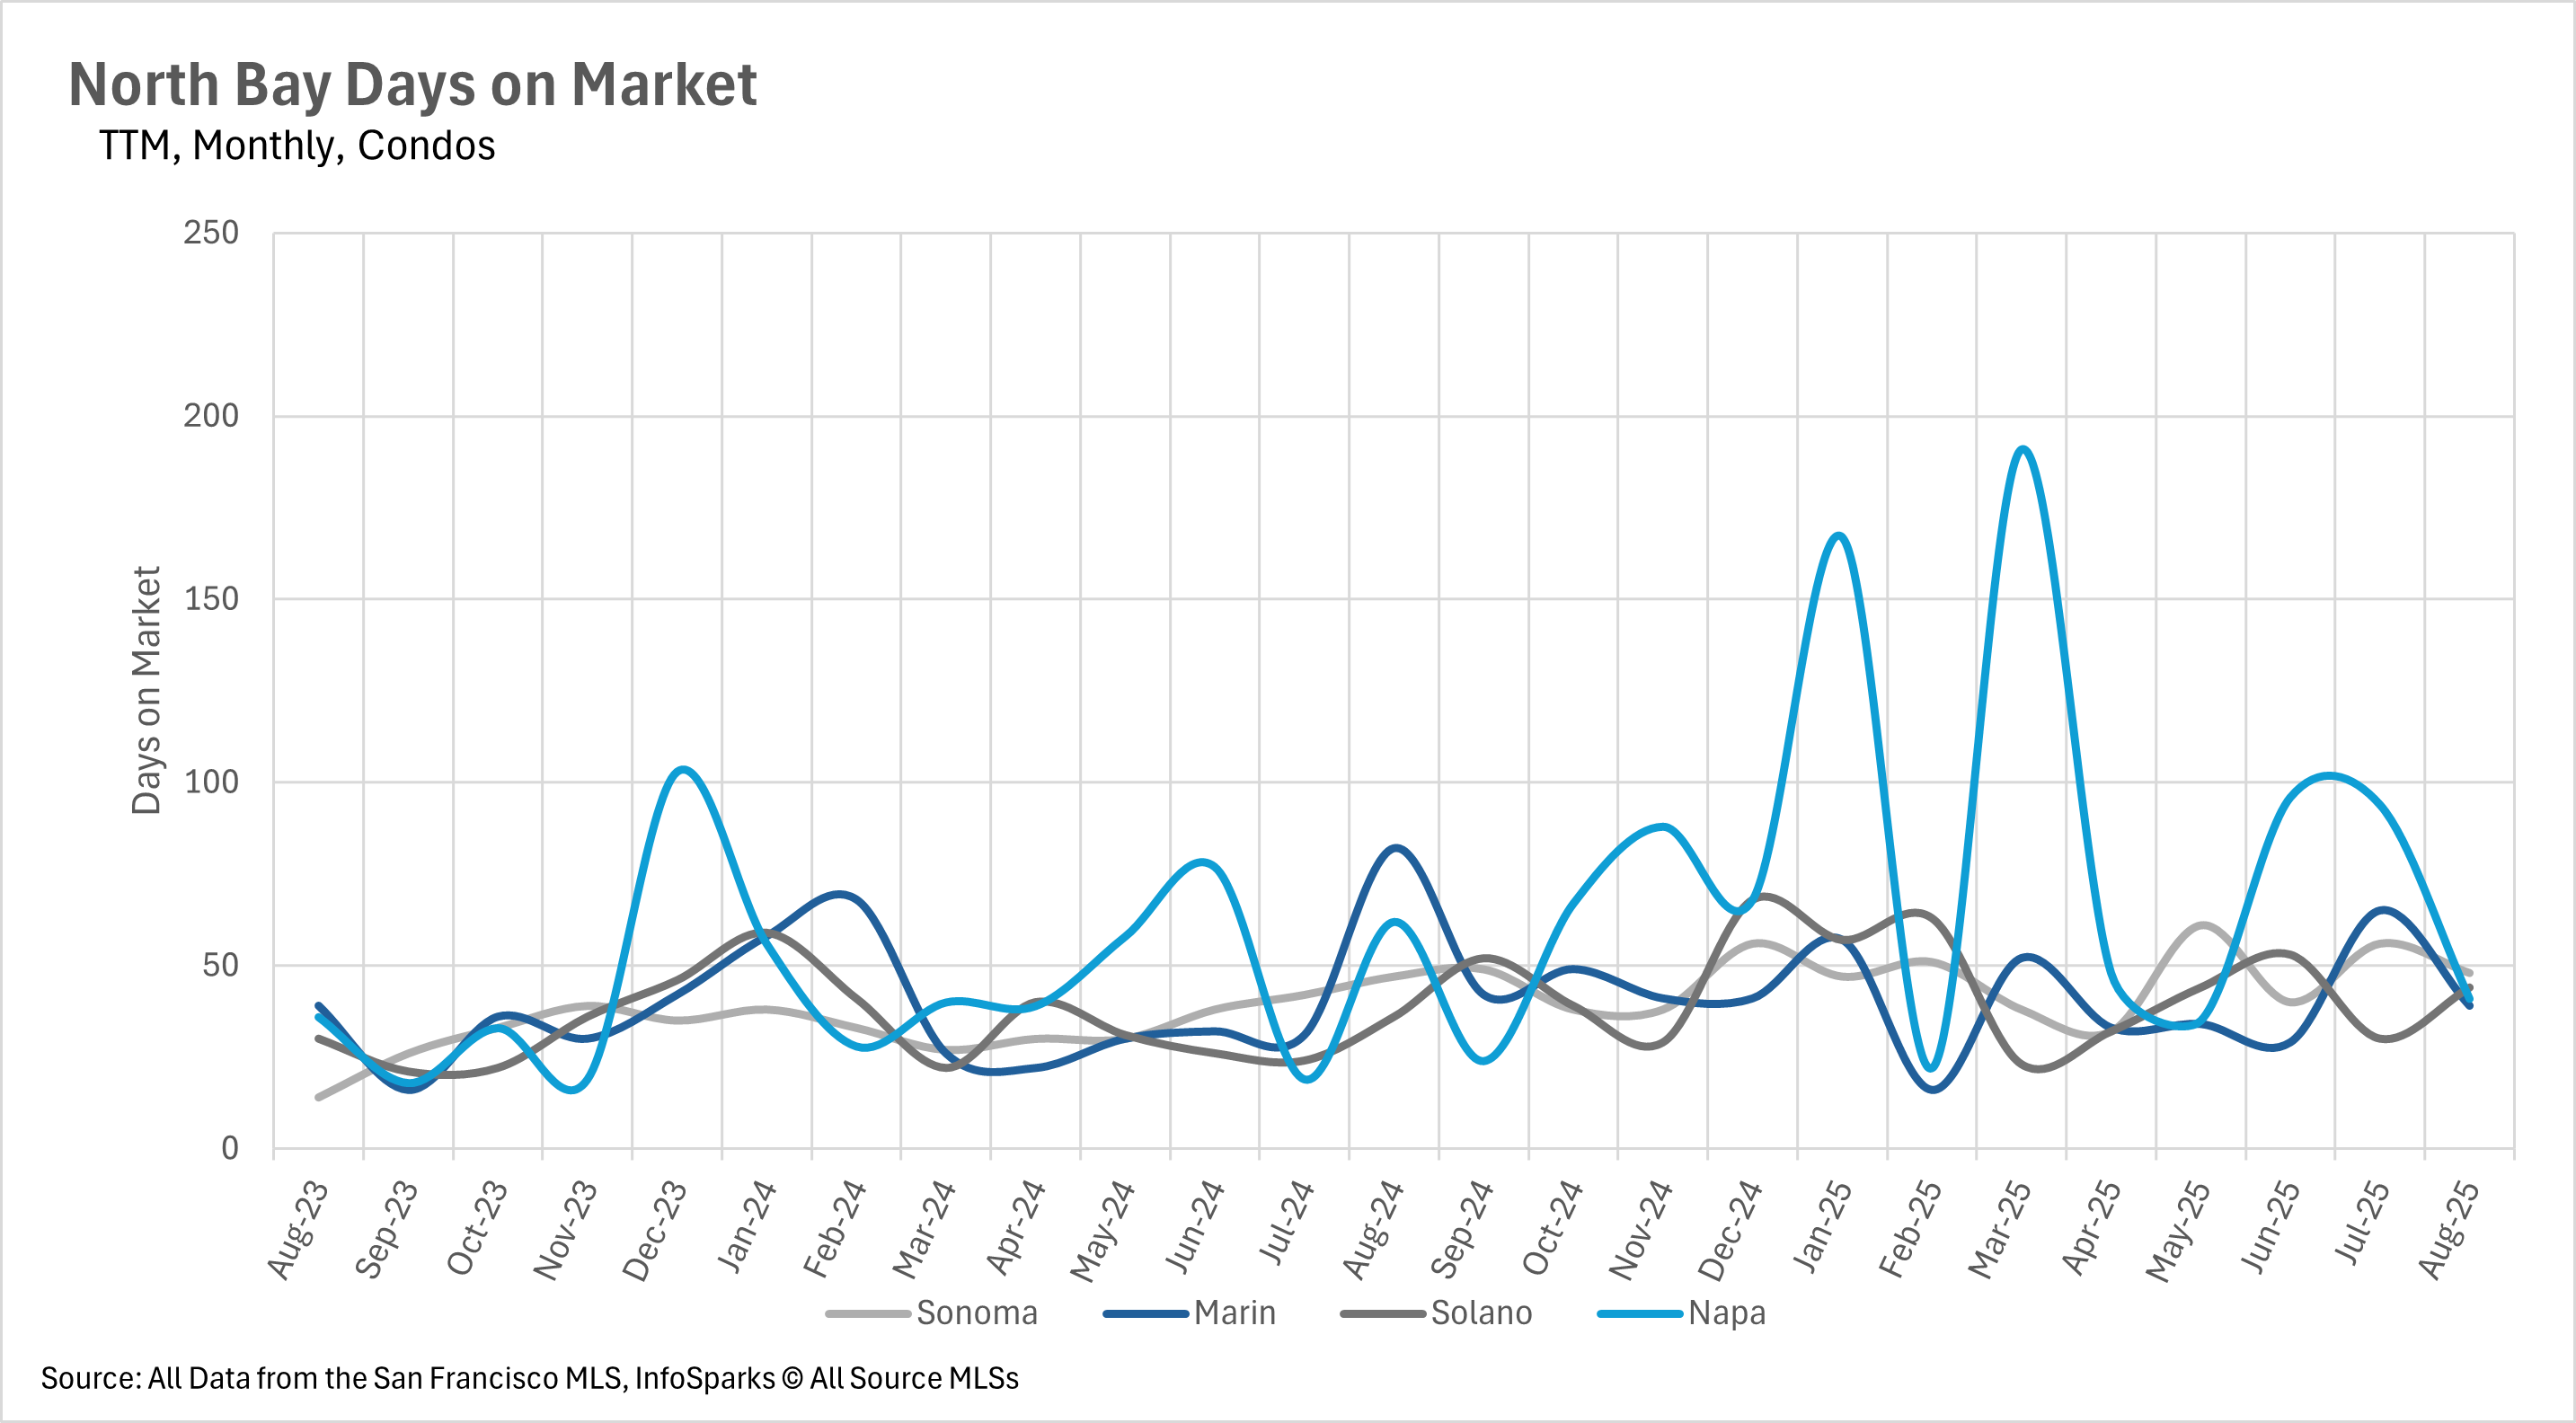
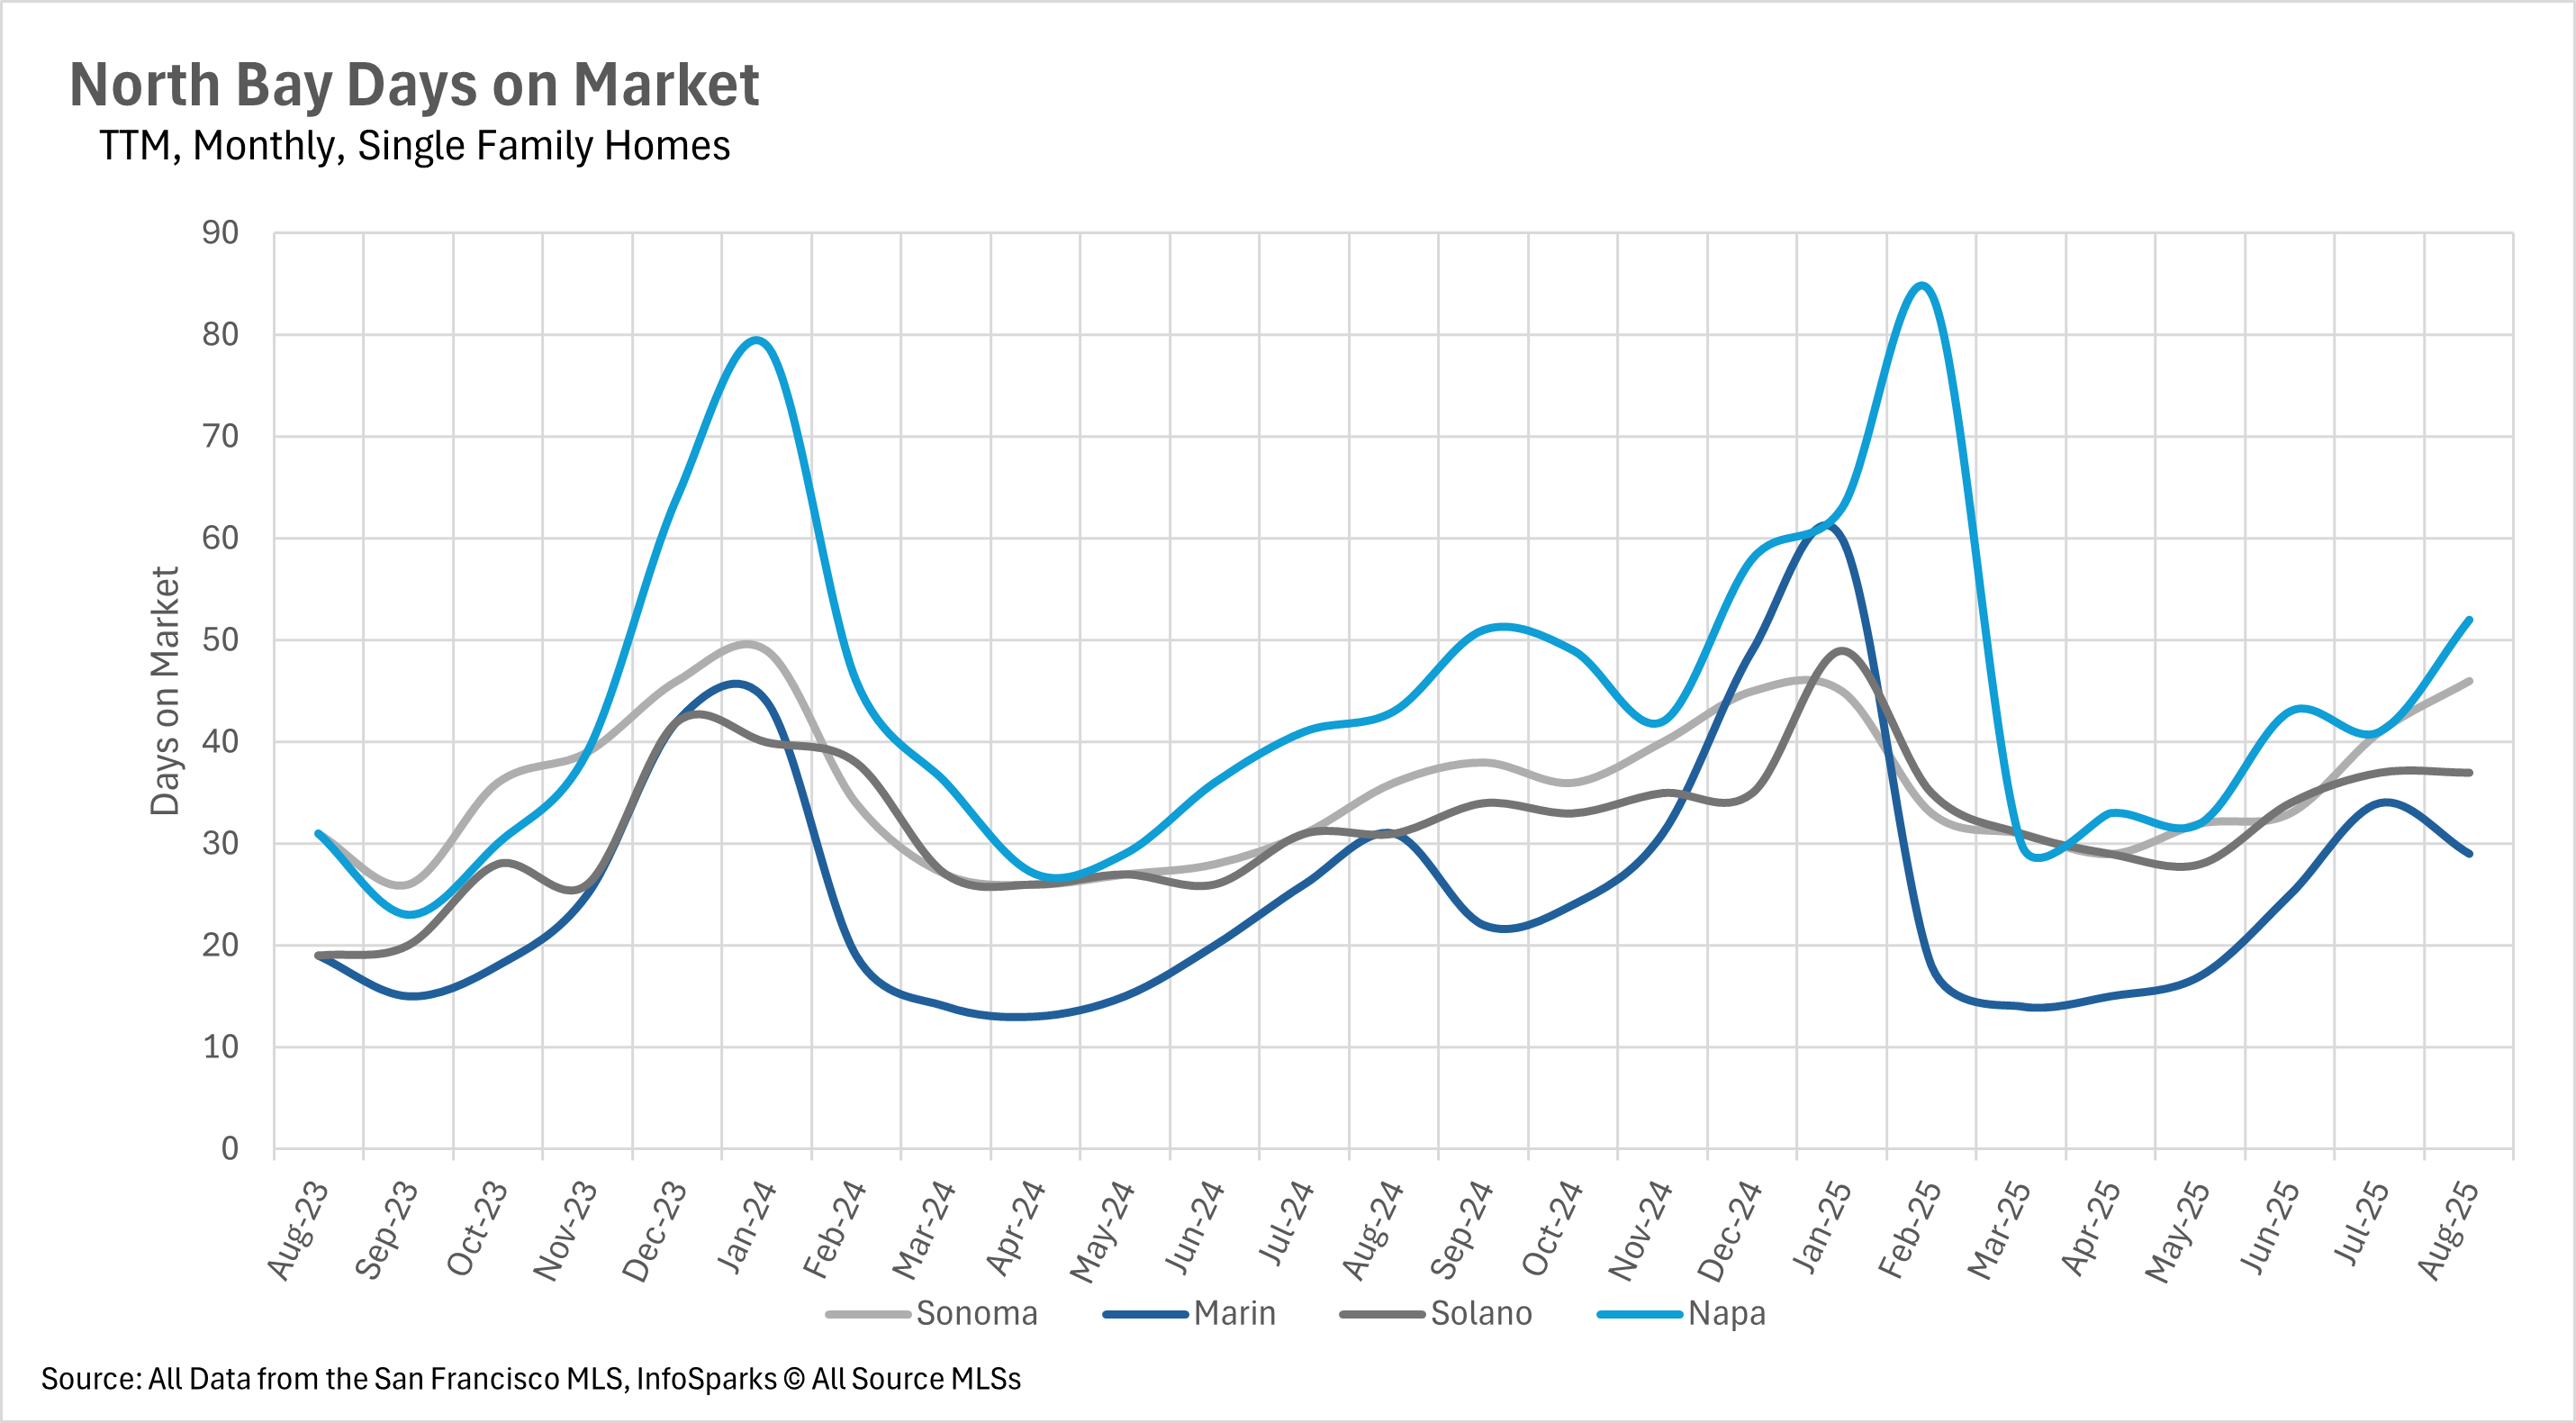
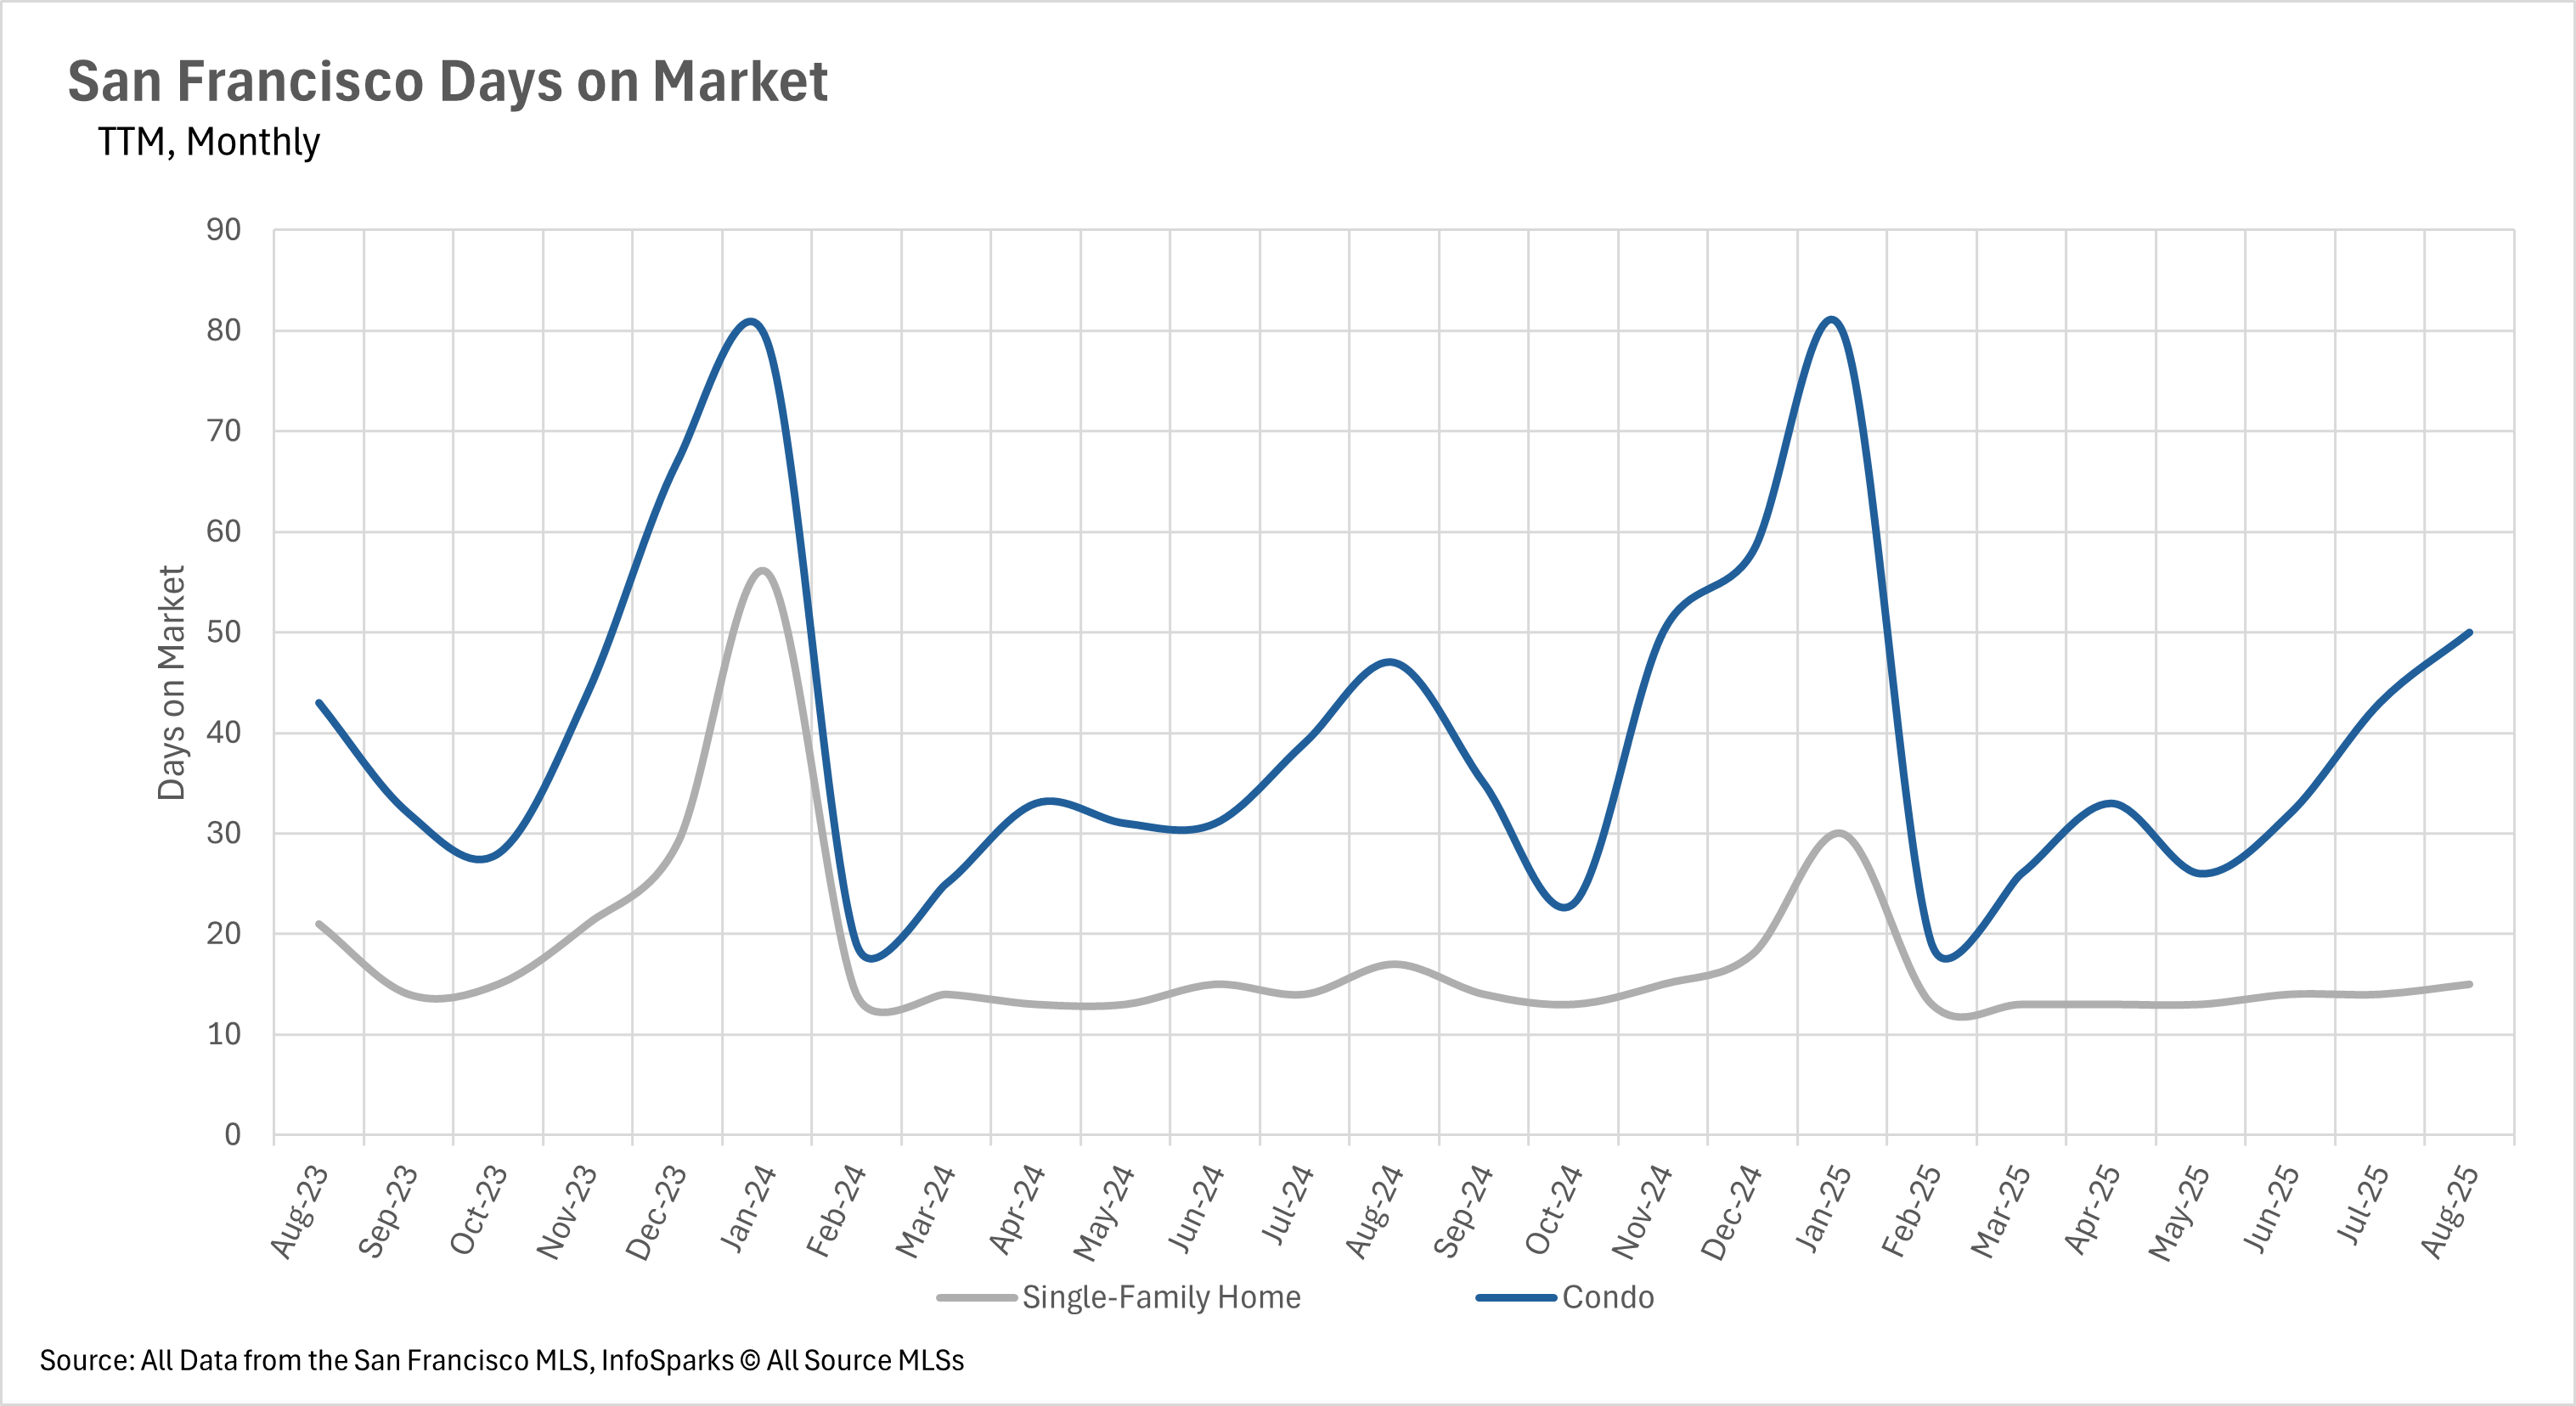
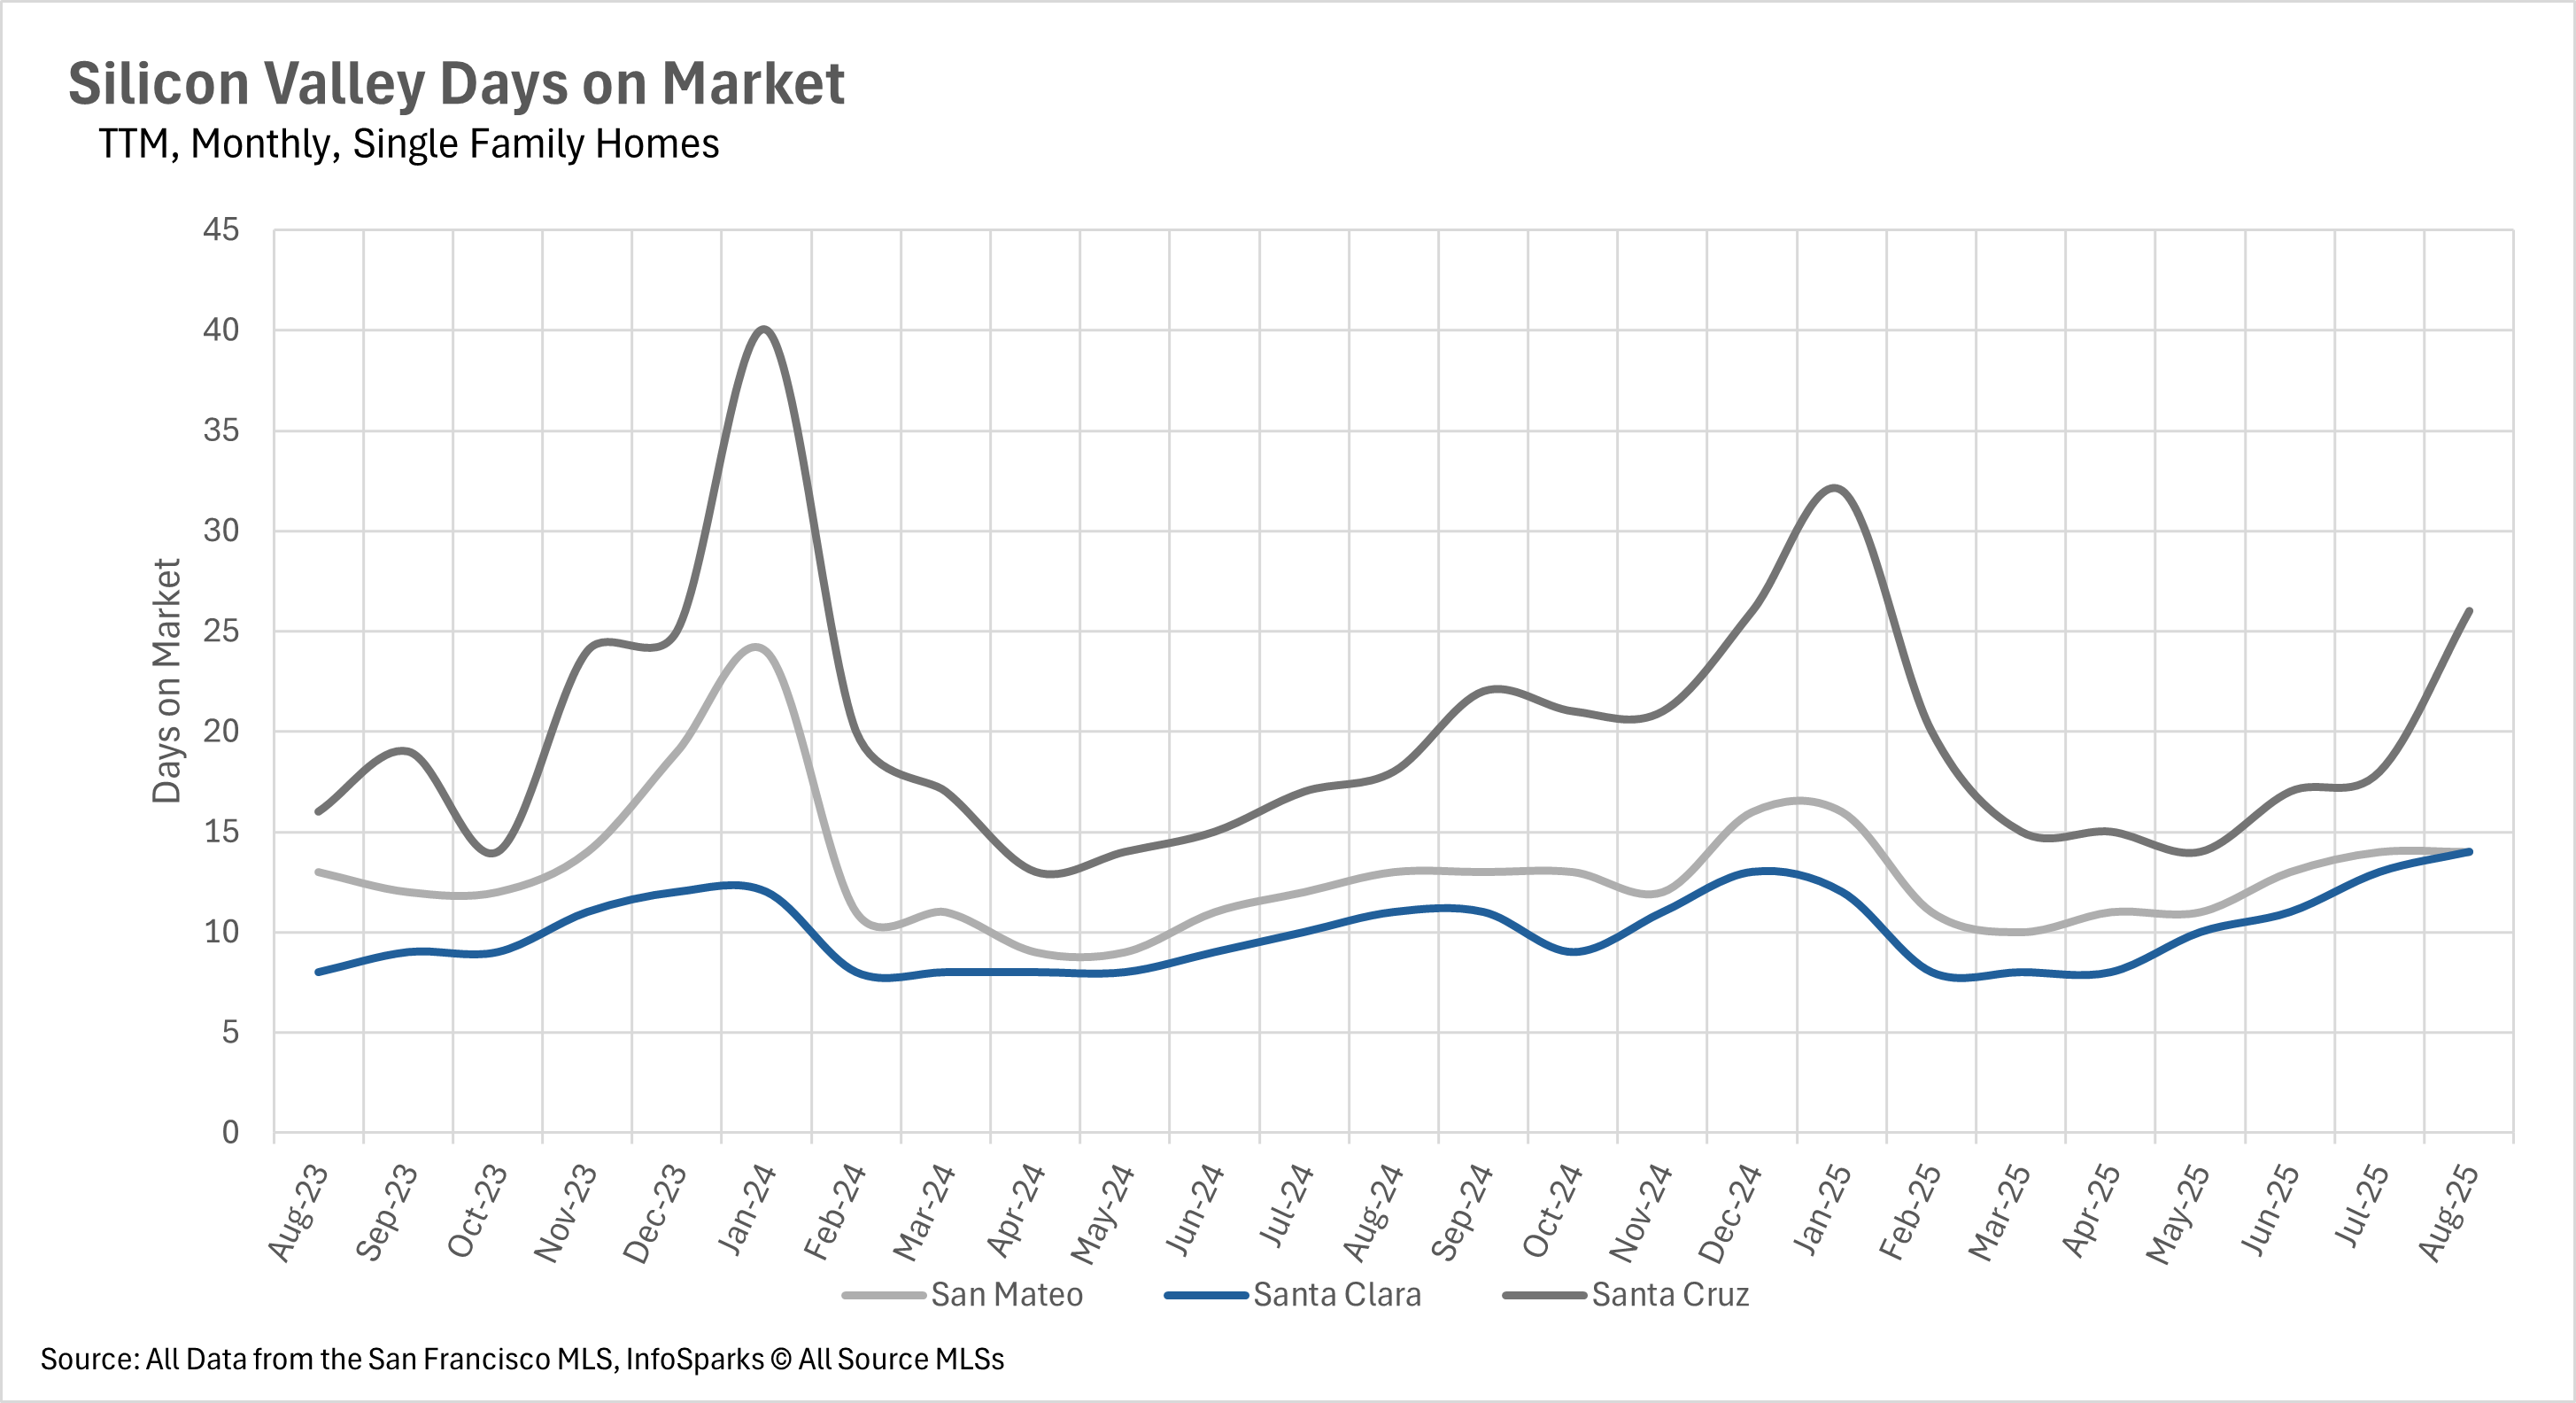
One of August's most notable trends was the continued increase in time on market across most Bay Area regions, despite improving inventory conditions. The North Bay showed the most dramatic increases, with single-family homes spending 27.78% more time on the market in Sonoma County and approximately 20% longer in Solano and Napa Counties, though Marin County bucked the trend with a 6.45% decrease. The East Bay demonstrated significant variations by property type and county, with single-family homes spending 21.43% more time on market in Alameda County and 37.50% more in Contra Costa County, while condo market times showed mixed results - Alameda condos spent 58.33% more time on market while Contra Costa condos actually decreased by 10.34%. Silicon Valley maintained relatively quick movement for single-family homes despite percentage increases, with absolute times remaining at just 14 days in San Mateo and Santa Clara Counties and 26 days in Santa Cruz County. San Francisco showed the most interesting pattern, with single-family homes remaining incredibly fast at just 15 days while condos increased to 50 days (up 6.38% year-over-year). These patterns suggest that while inventory levels are improving, buyer behavior has fundamentally shifted toward increased selectivity and deliberation.
Property type trumps geography in market dynamics
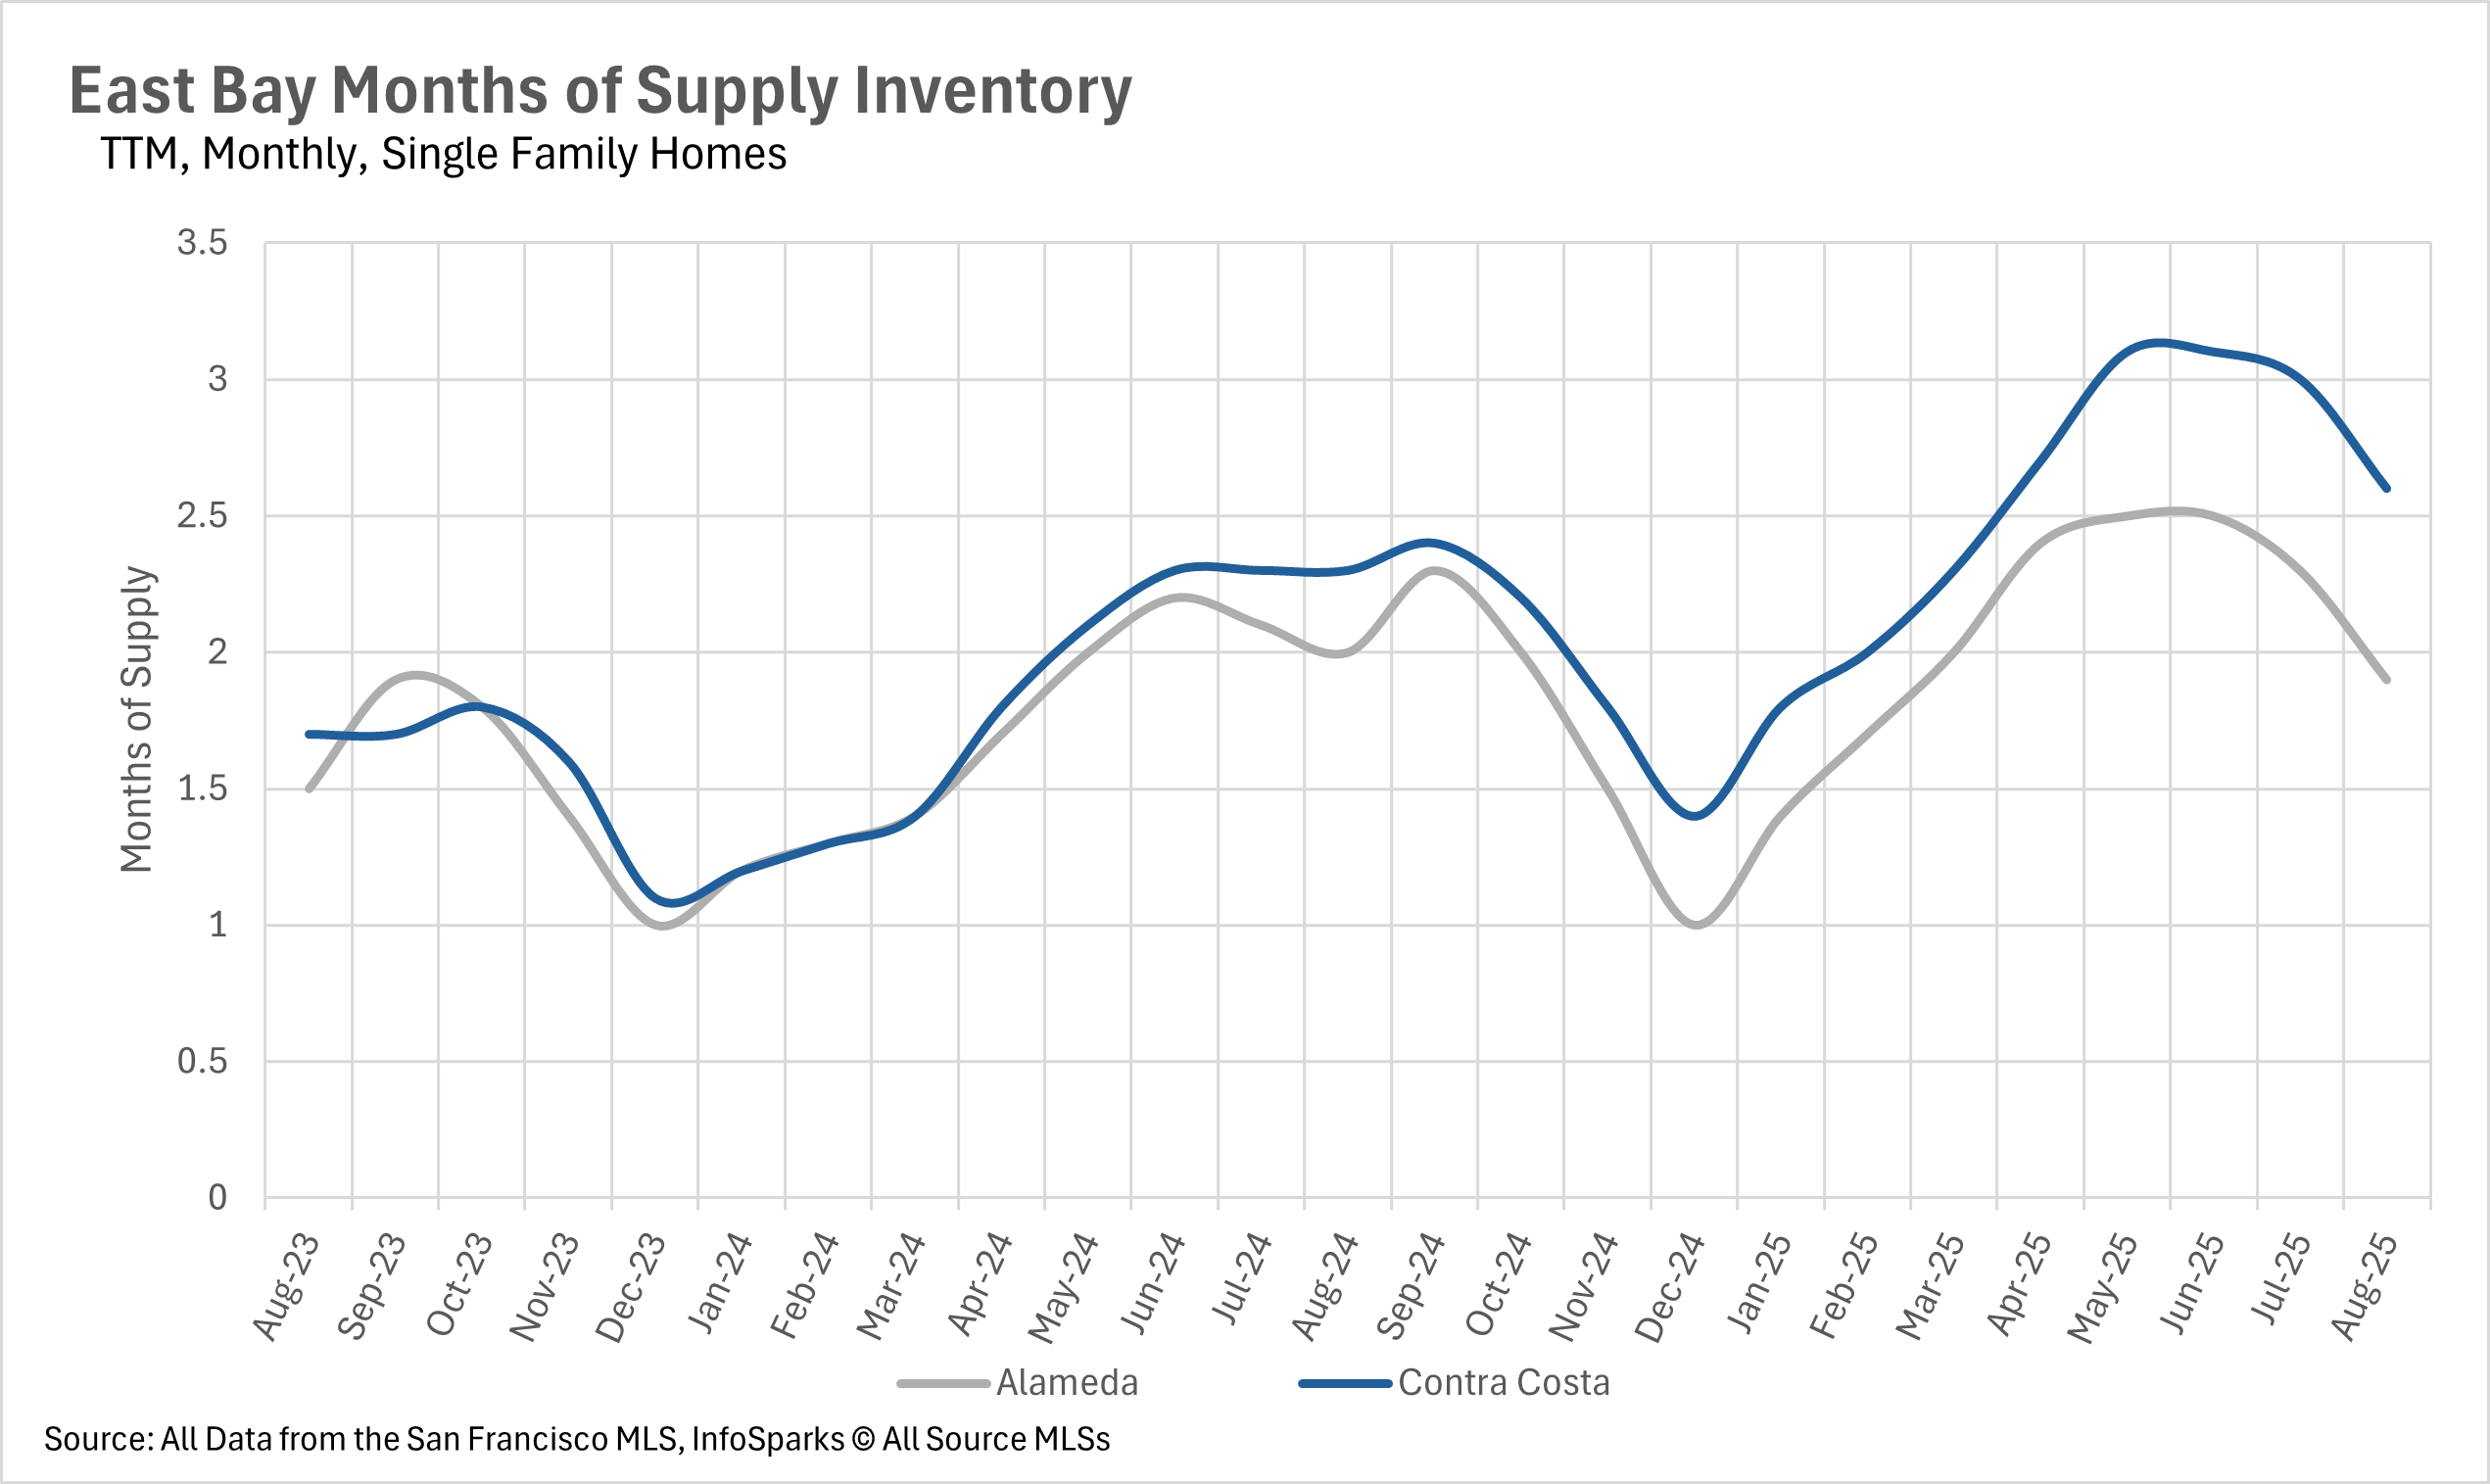
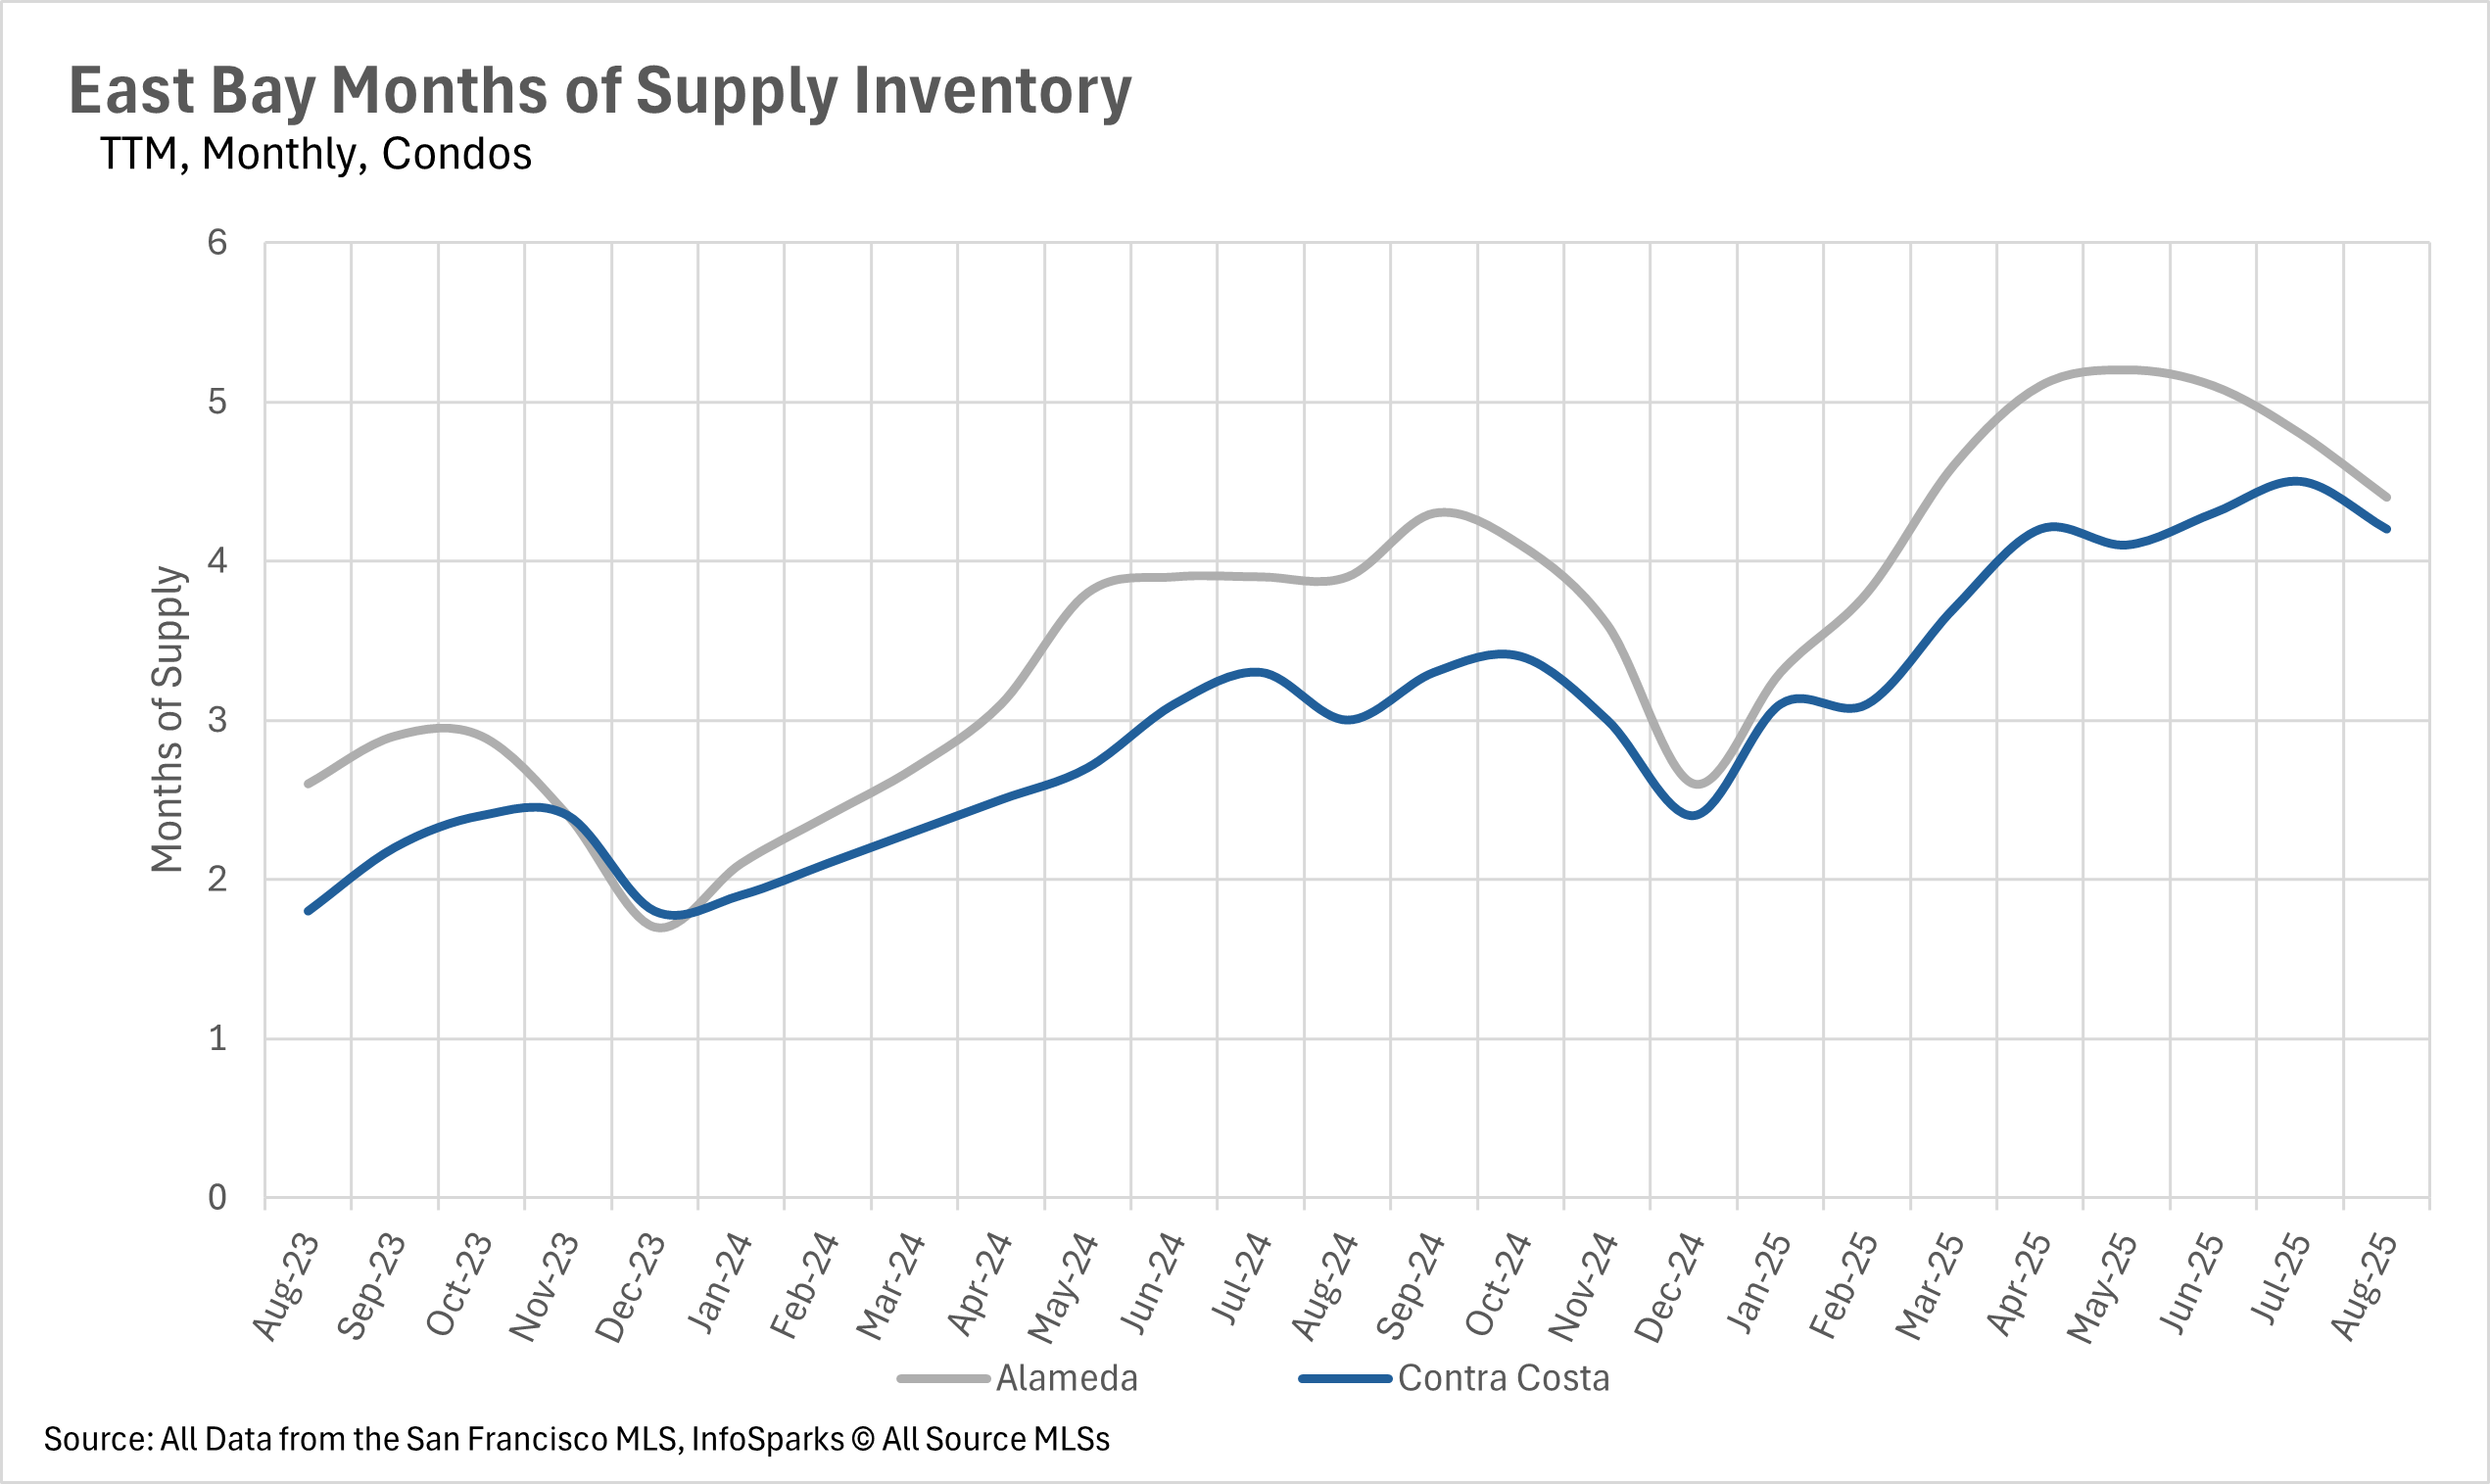
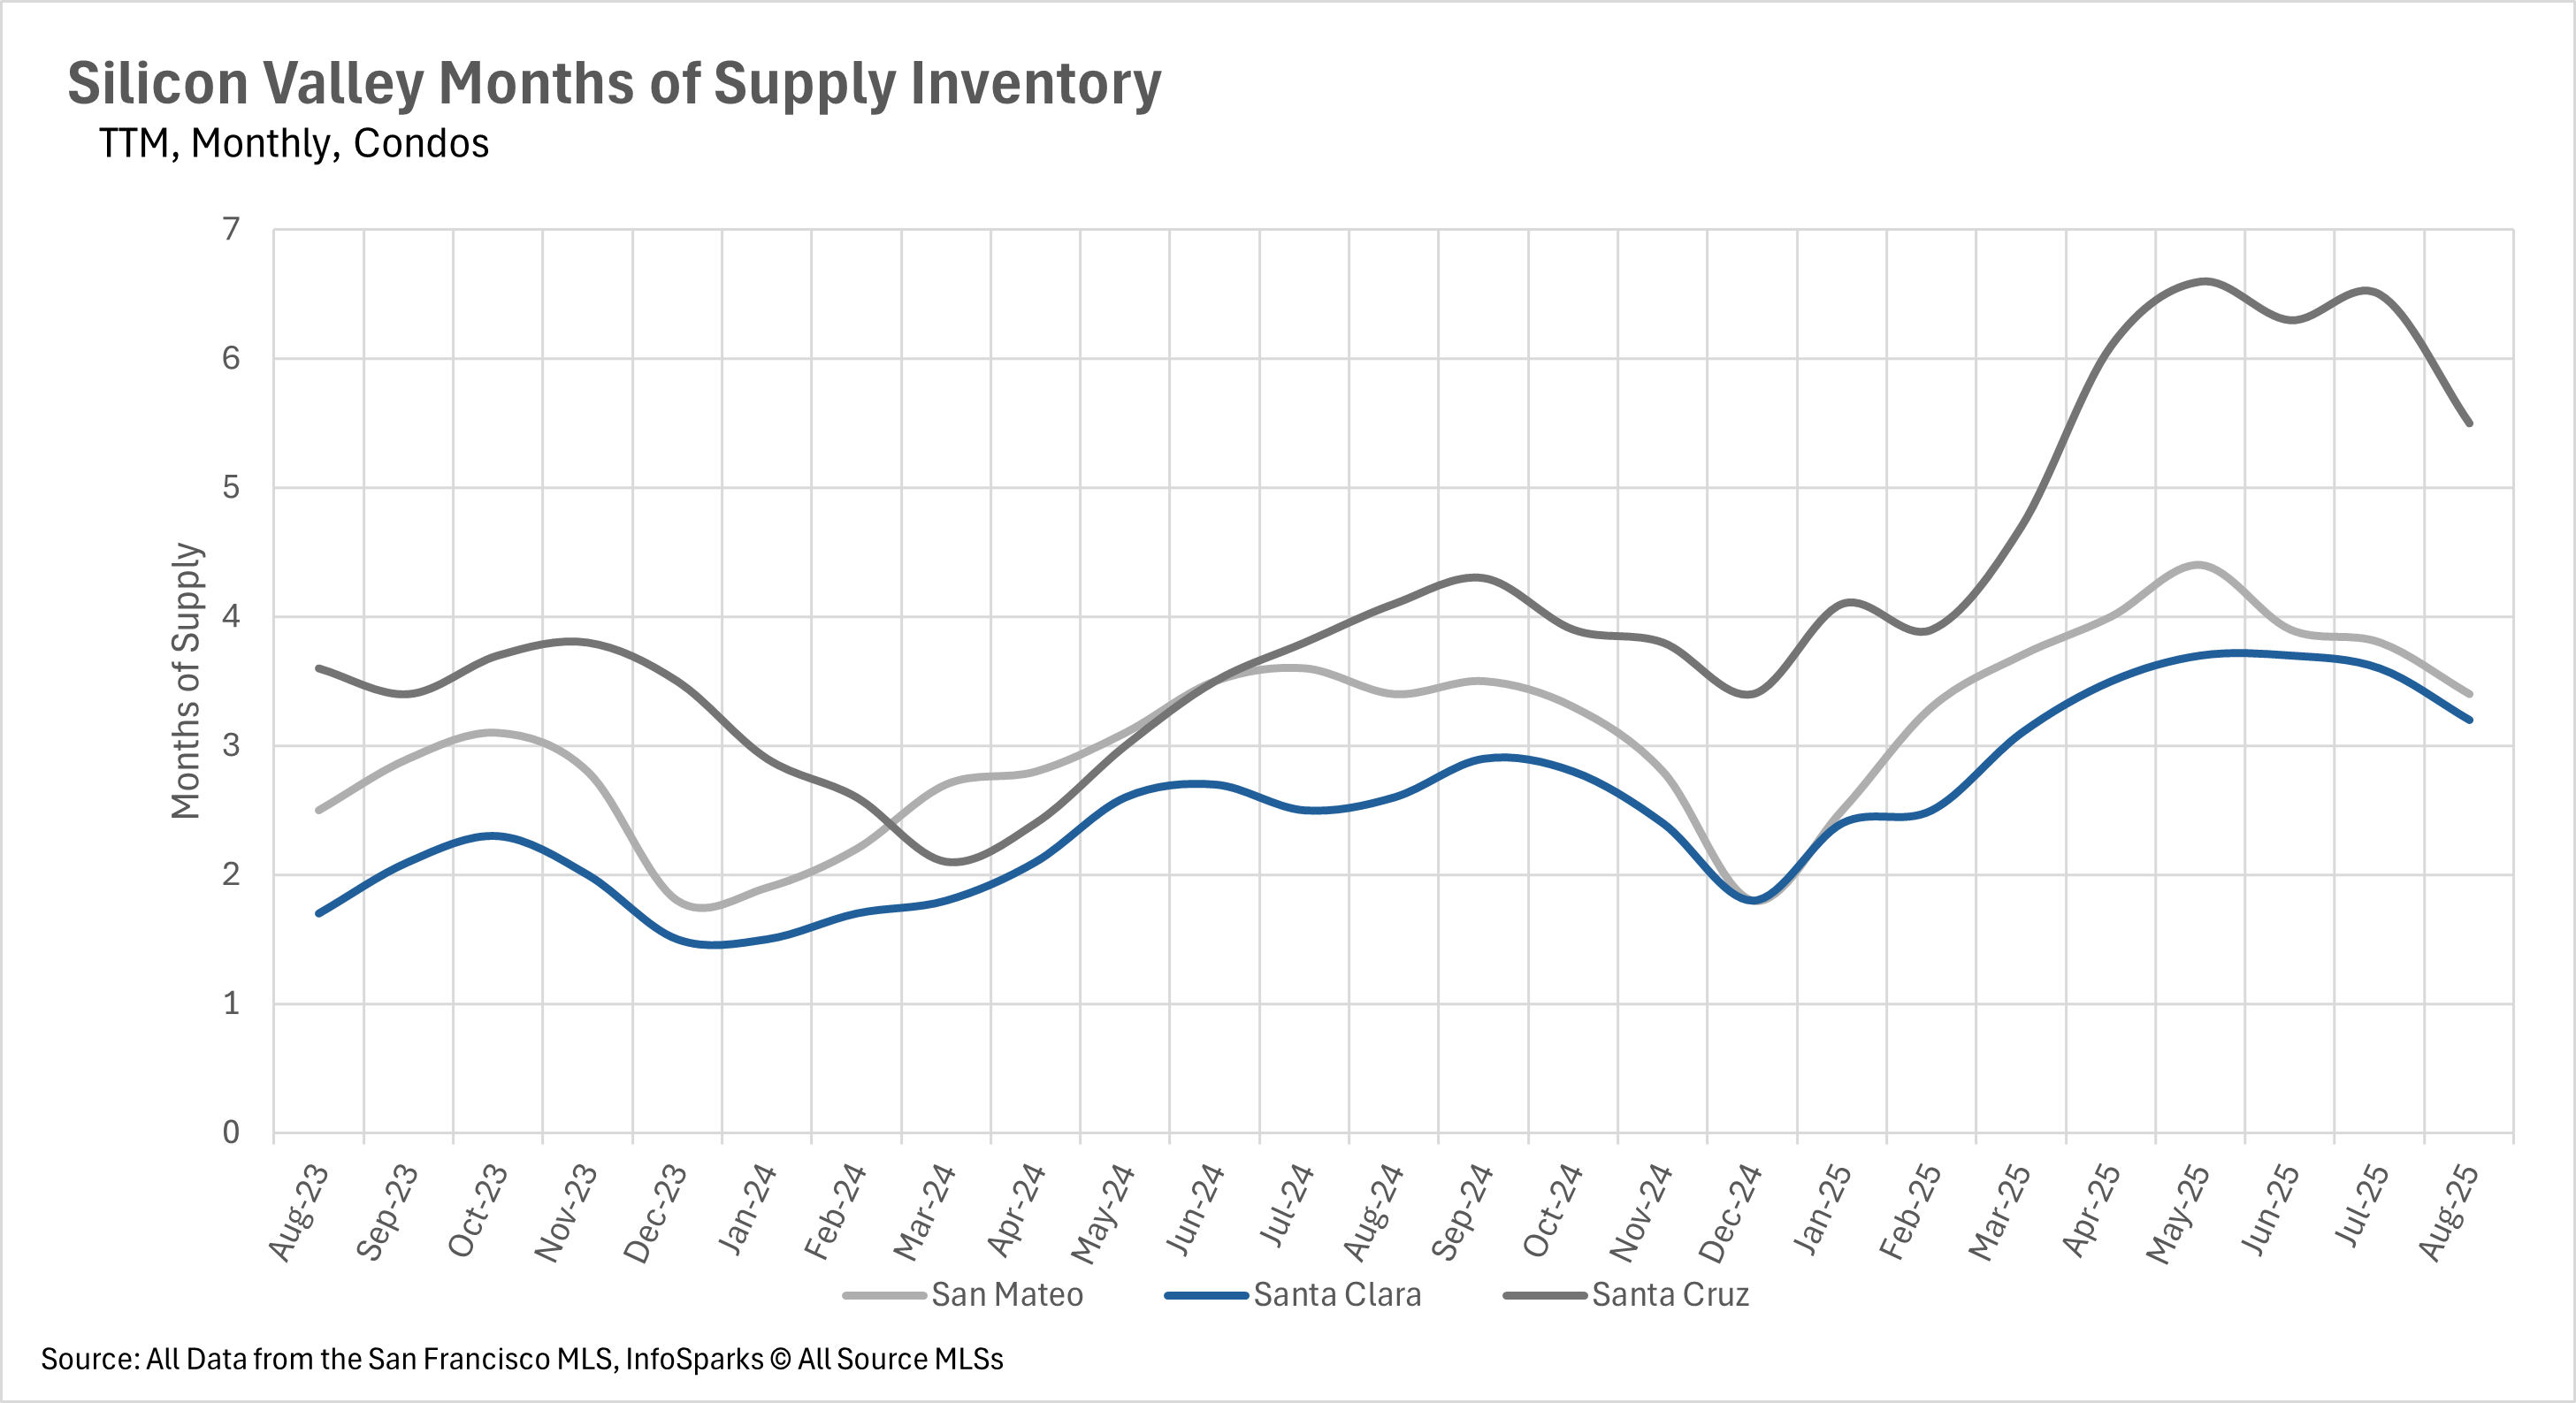
August reinforced the Bay Area's clear segmentation by property type rather than geographic location. San Francisco made headlines by achieving seller's market status for both single-family homes (1.1 months of supply) and condos (2.8 months of supply) - a rare occurrence that highlights the area's extreme inventory constraints. Silicon Valley maintained its competitive stance for single-family homes, with San Mateo and Santa Clara Counties at ultra-low 1.5 and 1.3 months respectively, while Santa Cruz County remained a buyer's market at 3.9 months. All Silicon Valley condo markets favored buyers, ranging from 3.2 months in Santa Clara to 5.5 months in Santa Cruz County. The East Bay preserved its traditional split with single-family homes strongly favoring sellers at 1.9 months in Alameda and 2.6 months in Contra Costa, while condos remained buyer-friendly at 4.4 and 4.2 months respectively. The North Bay showed the most variation, with Marin achieving perfect balance at 3.0 months for single-family homes, while Solano (3.3 months), Sonoma (3.9 months), and Napa (7.6 months) all favored buyers. North Bay condos uniformly favored buyers, with supply ranging from 4.0 months in Marin to 7.5 months in Napa County. This consistent pattern across the region suggests that single-family homes have retained their premium status and scarcity value, while condos present substantial opportunities for buyers willing to navigate longer timelines and increased inventory choices.
Local Lowdown Data
Line chart comparing East Bay days on market in Alameda and Contra Costa from August 2023 to August 2025.
Bar chart comparing year-over-year East Bay condo price changes in Alameda and Contra Costa counties, September 2024 to August 2025.
Line chart comparing monthly condo days on market in Alameda and Contra Costa from August 2023 to August 2025.
East Bay single-family home inventory chart comparing new listings, sold listings, and homes for sale from August 2023 to August 2025.
East Bay condo inventory chart comparing monthly new listings, sold listings, and homes for sale from August 2023 to August 2025.
Line chart of monthly East Bay condo prices, August 2022–August 2025; Alameda prices exceed Contra Costa prices.
Bar chart of year-over-year East Bay single-family home price changes in Alameda and Contra Costa counties.
Line chart comparing monthly single-family home inventory supply in Alameda and Contra Costa, August 2023–August 2025.
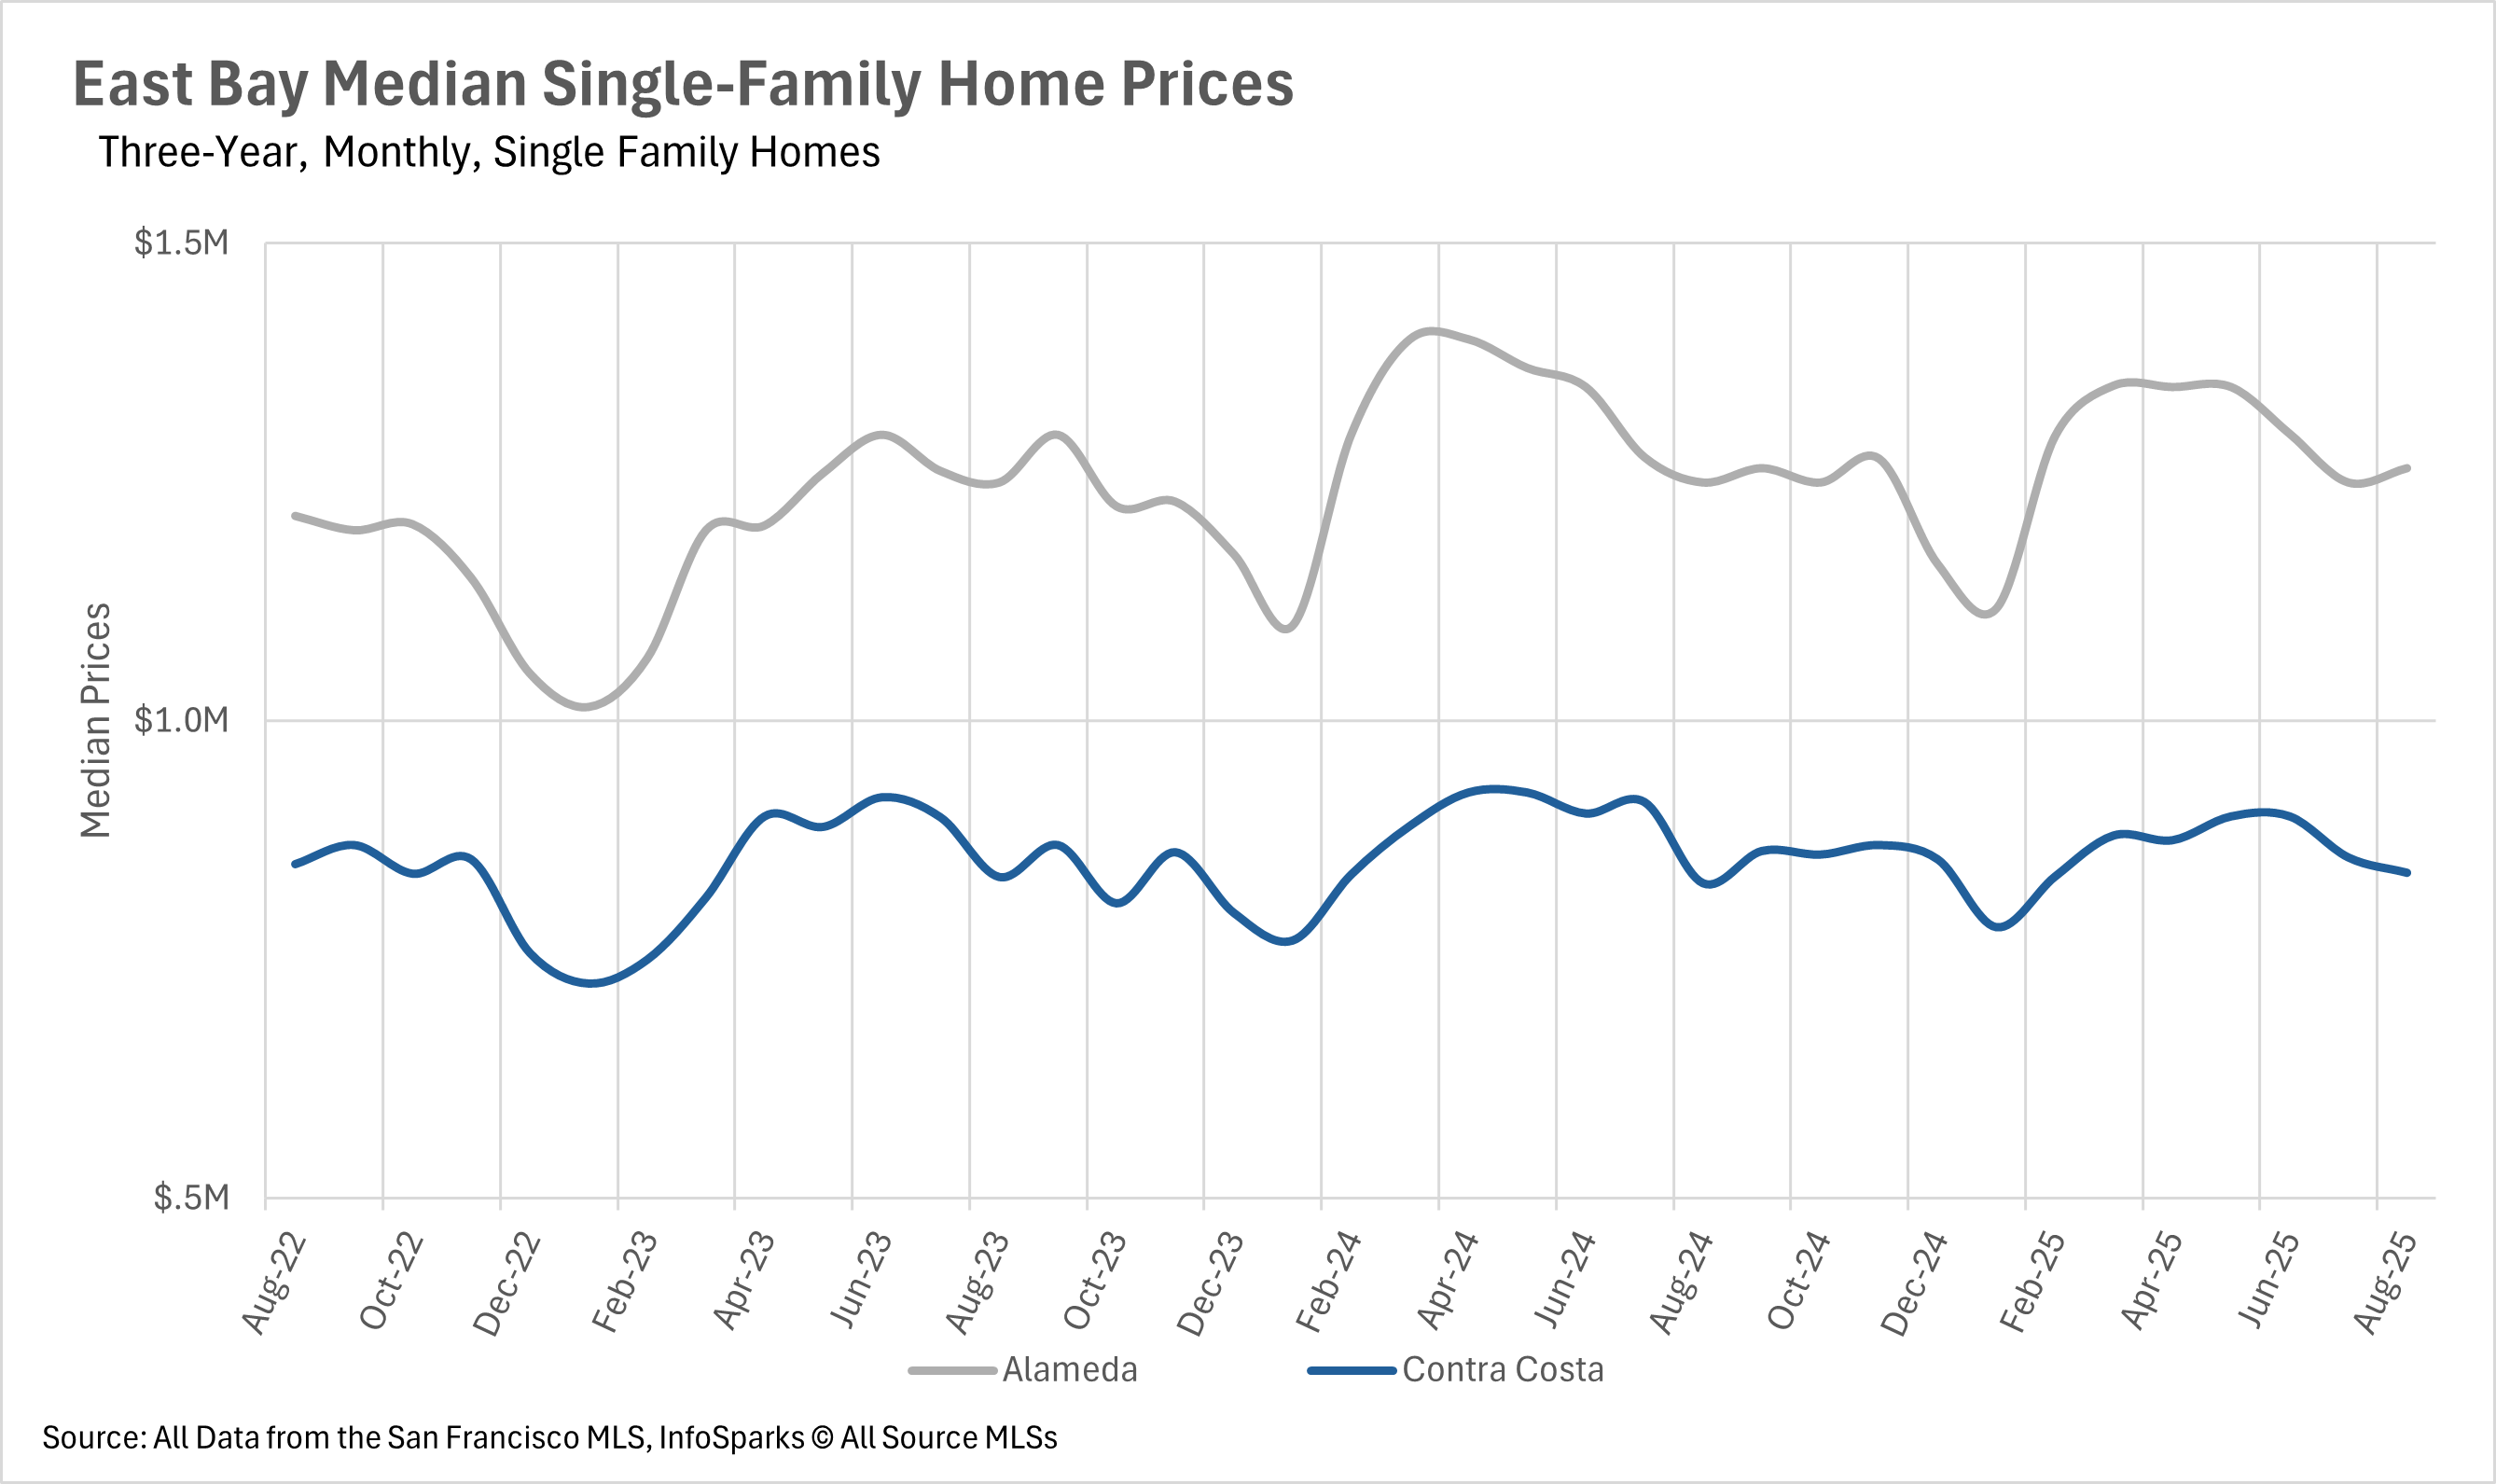
Line chart of East Bay single-family home prices, with monthly Alameda and Contra Costa medians from August 2022 to August 2025.
Line chart comparing monthly condo inventory supply in Alameda and Contra Costa from August 2023 to August 2025.
Line chart of North Bay condo days on market by county, August 2023–August 2025; Napa has the largest spikes.
North Bay condo inventory chart, August 2023–August 2025, with listings, sales, and homes for sale.
Line chart comparing monthly days on market for single-family homes in four North Bay counties, August 2023–August 2025.
Chart of year-over-year North Bay condo price changes by county, September 2024 through August 2025.
Chart of North Bay single-family home listings and sales, August 2023–August 2025, with for-sale inventory peaking in spring 2025.
Bar chart of North Bay single-family home price changes by county, September 2024 to August 2025.
Line chart of monthly North Bay condo prices by county, August 2022–August 2025; Napa fluctuates most sharply.
Line chart of North Bay condo inventory months of supply by county, August 2023–August 2025.
Line chart of North Bay housing inventory, August 2023–August 2025, comparing Napa, Sonoma, Marin, and Solano.
Line chart comparing three years of monthly median single-family home prices in Sonoma, Marin, Solano, and Napa counties.
Chart compares San Francisco year-over-year median price changes for single-family homes and condos, September 2024–August 2025.
San Francisco condo inventory chart comparing monthly new listings, sold listings, and homes for sale from August 2023 to August 2025.
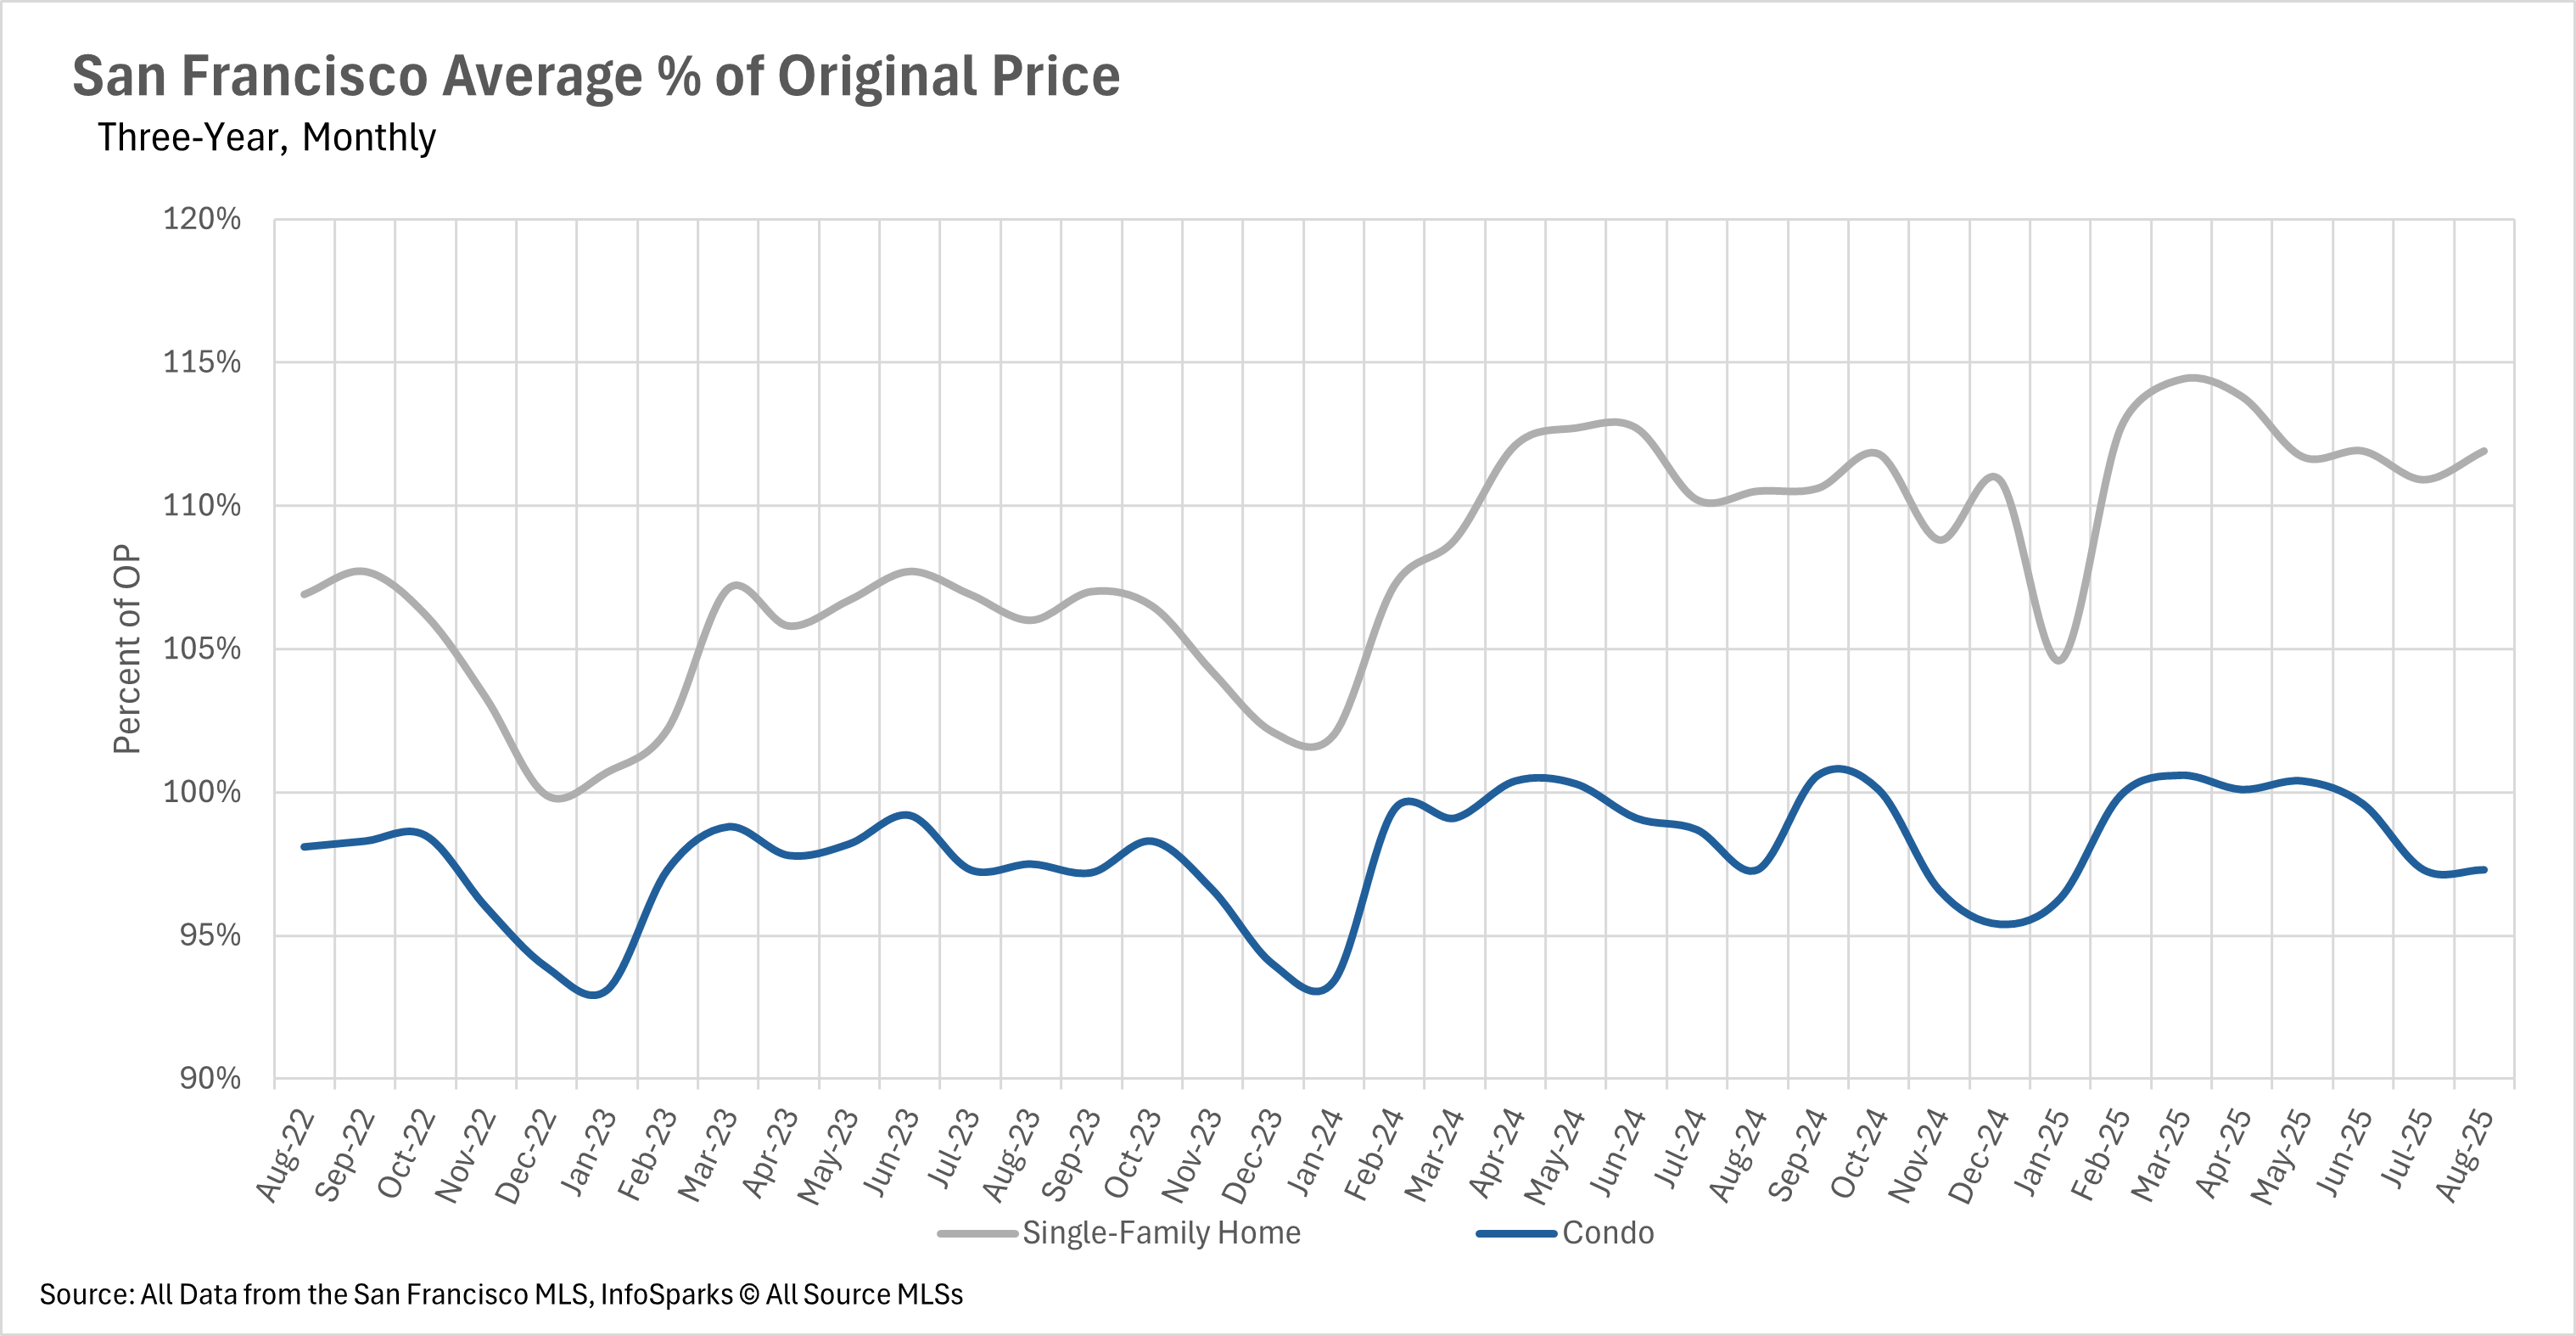
San Francisco sale prices as a percentage of original price, monthly: single-family homes in gray and condos in blue, August 2022–August 2025.
San Francisco days-on-market chart: condo and single-family home trends from August 2023 to August 2025.
Chart of monthly San Francisco median home and condo prices from August 2022 to August 2025.
San Francisco months of supply inventory chart comparing single-family homes and condos from August 2023 to August 2025.
San Francisco single-family home inventory chart compares monthly new and sold listings with homes for sale, August 2023–August 2025.
Chart of monthly Silicon Valley condo listings, sales, and for-sale inventory from August 2023 to August 2025.
Chart of Silicon Valley single-family home listings, sales, and inventory from August 2023 to August 2025.
Chart of year-over-year condo median price changes in three Bay Area counties, September 2024 to August 2025.
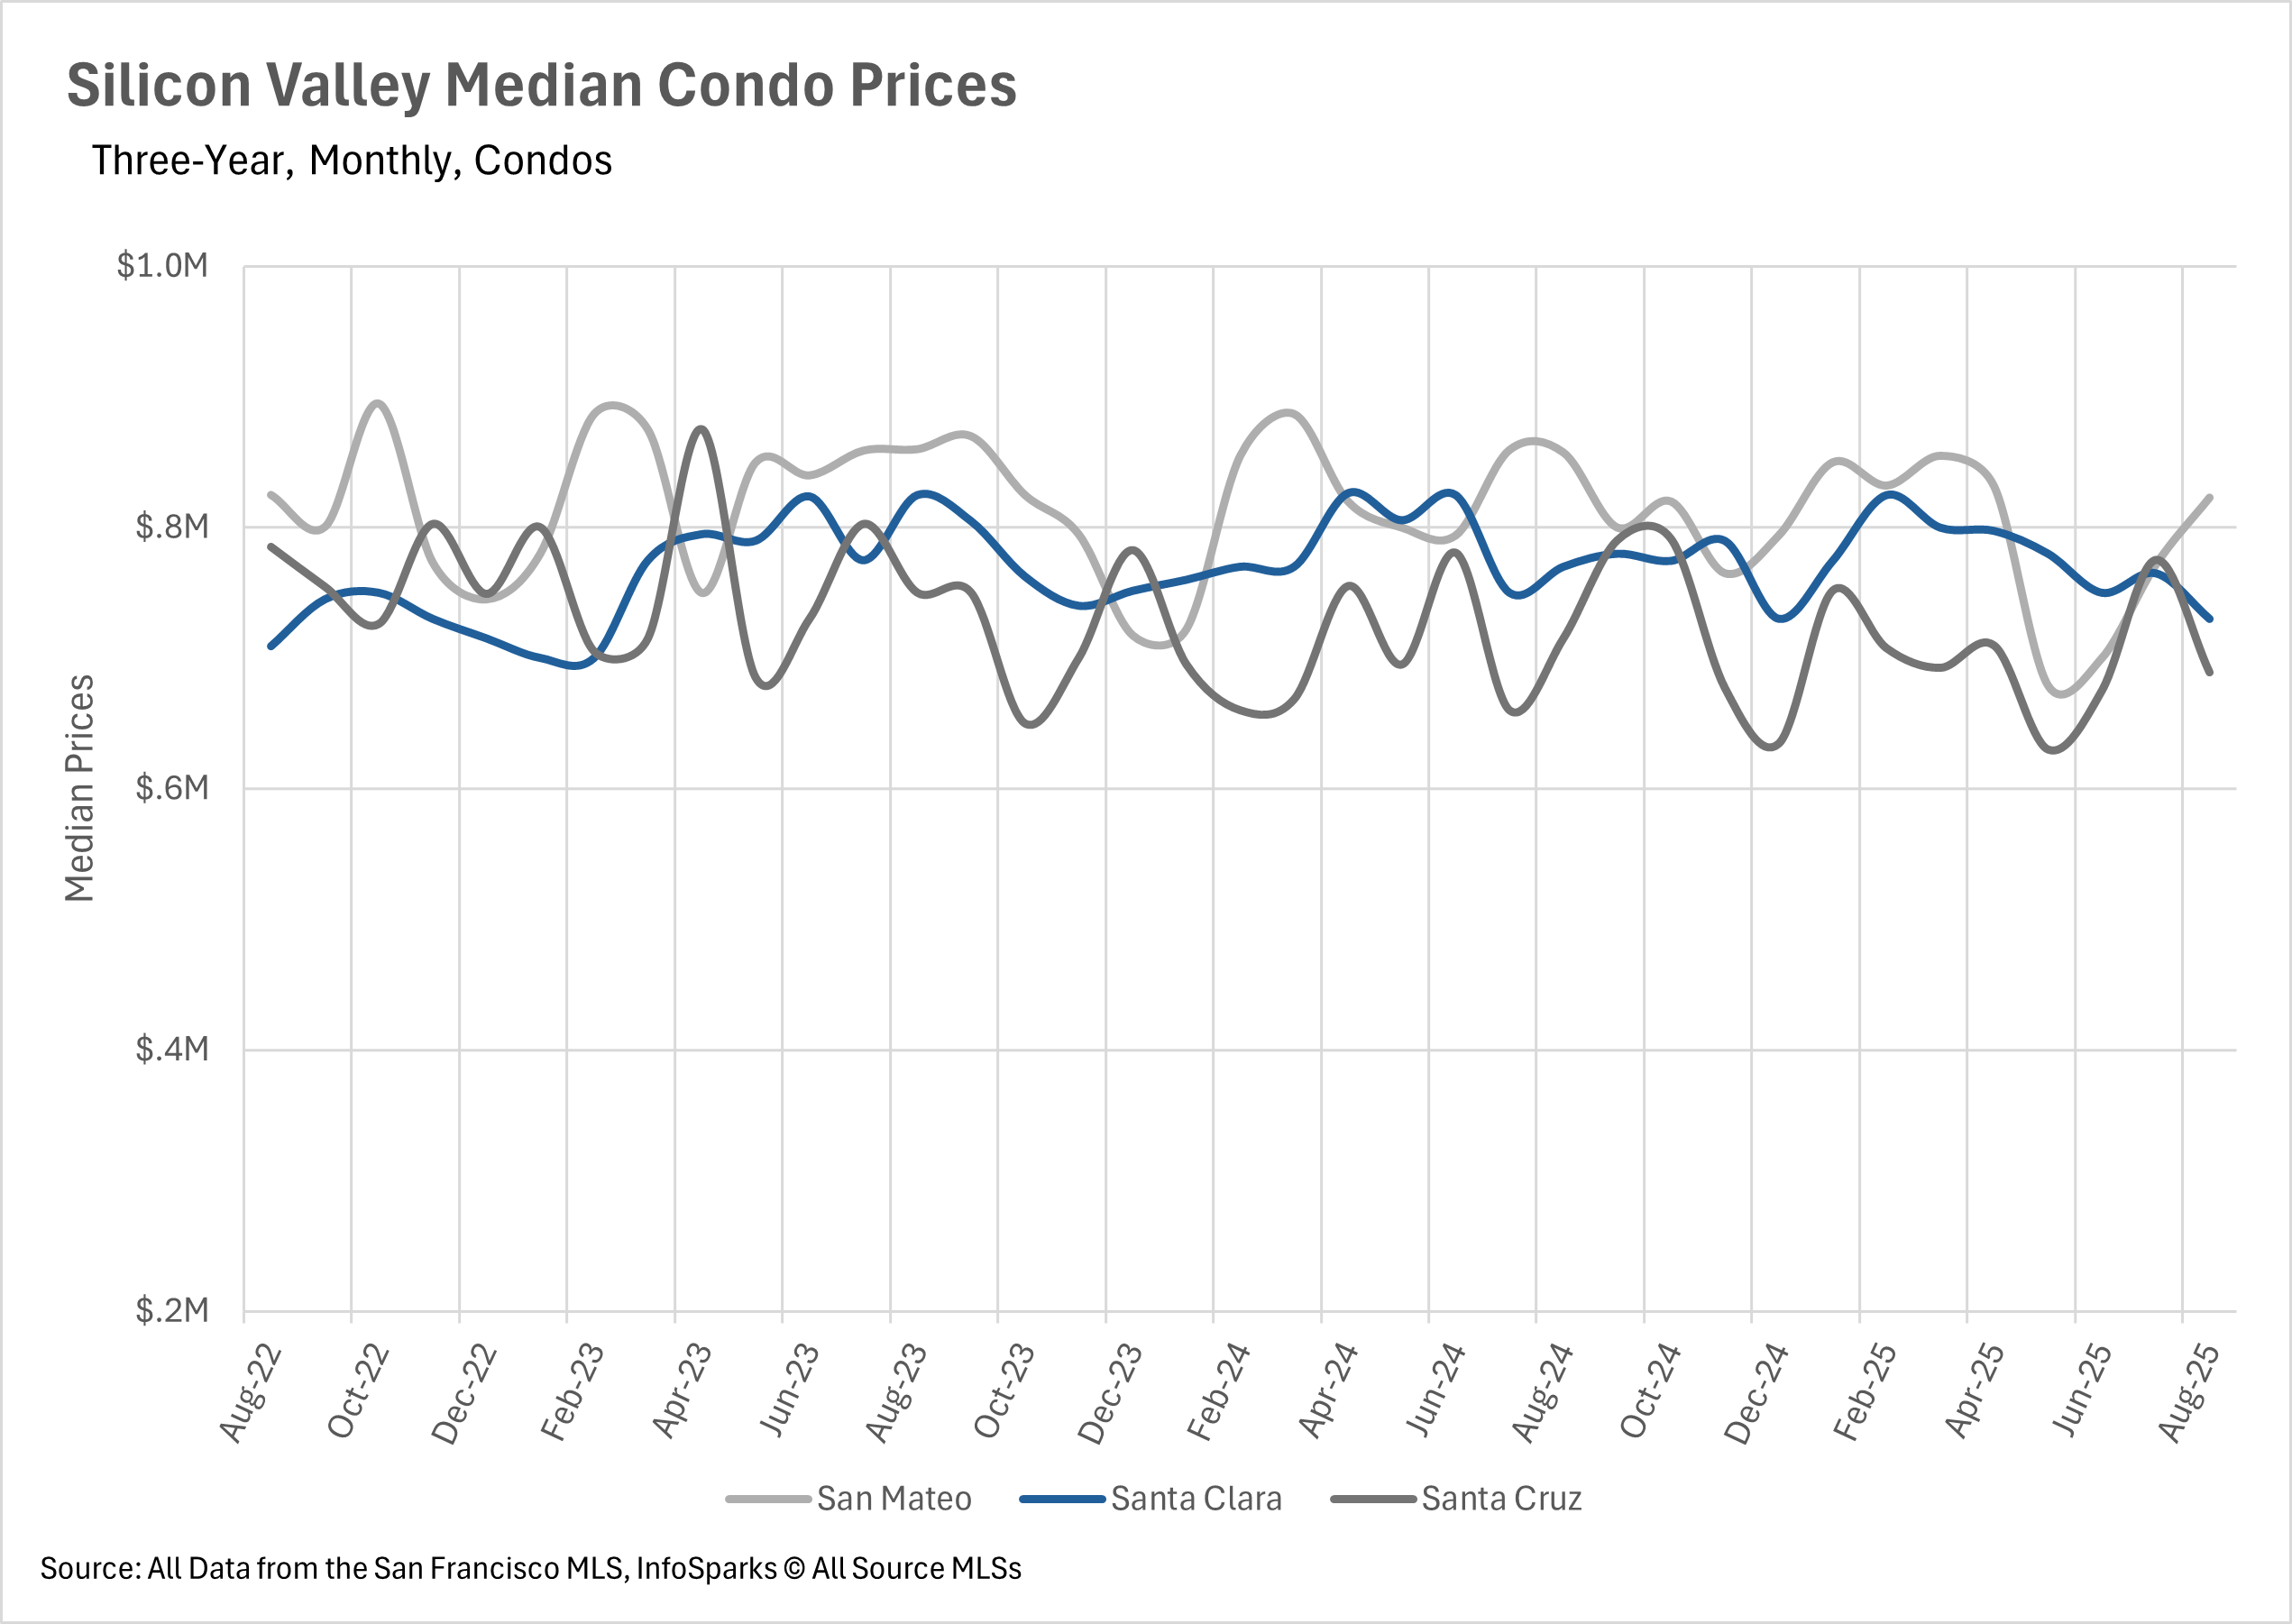
Line chart of monthly median condo prices in San Mateo, Santa Clara, and Santa Cruz counties, August 2022–August 2025.
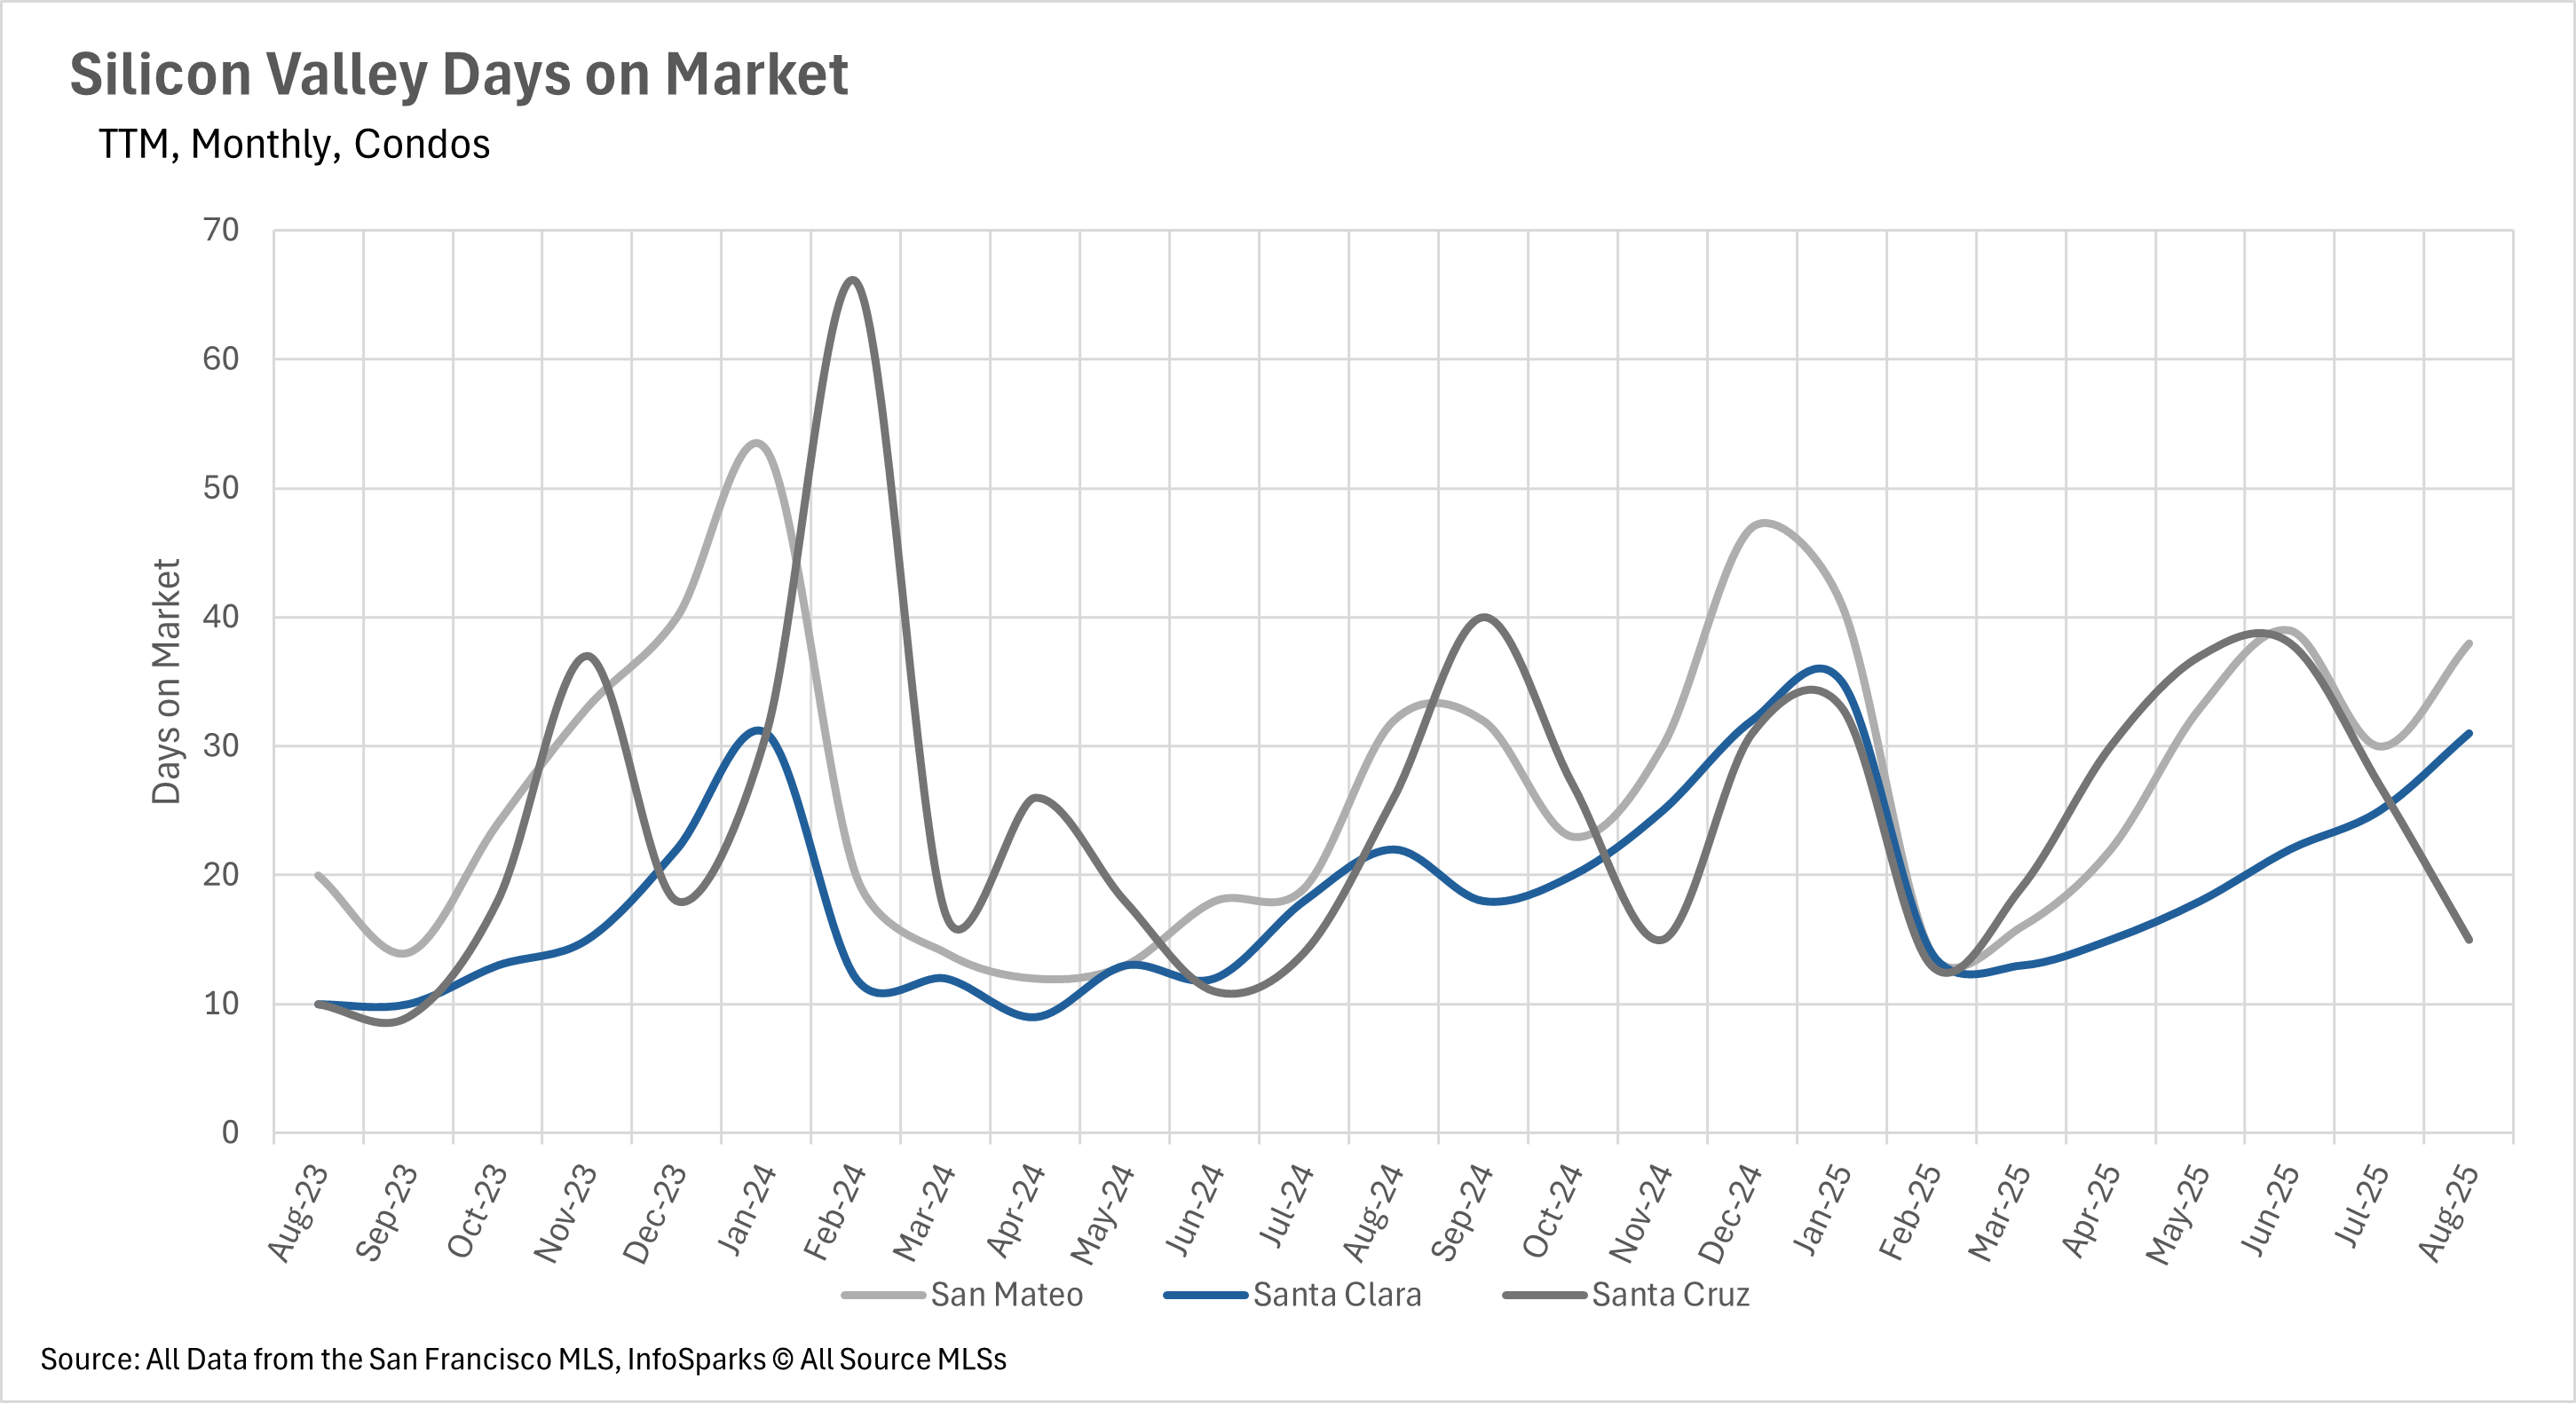
Line chart comparing monthly condo days on market in San Mateo, Santa Clara, and Santa Cruz counties, August 2023–August 2025.
Line chart comparing days on market for single-family homes in San Mateo, Santa Clara, and Santa Cruz, August 2023–August 2025.
Bar chart comparing year-over-year median single-family home price changes in San Mateo, Santa Clara, and Santa Cruz.
Line chart of monthly condo supply in San Mateo, Santa Clara, and Santa Cruz counties, August 2023–August 2025.
Line chart of Silicon Valley home inventory supply by county, August 2023–August 2025; Santa Cruz is highest.
Line chart of monthly median single-family home prices in San Mateo, Santa Clara, and Santa Cruz counties, 2022–2025.
 

ActivePipe Message ID: 3295295

max-width:100%

Let’s Talk

You’ve got questions and we can’t wait to answer them.