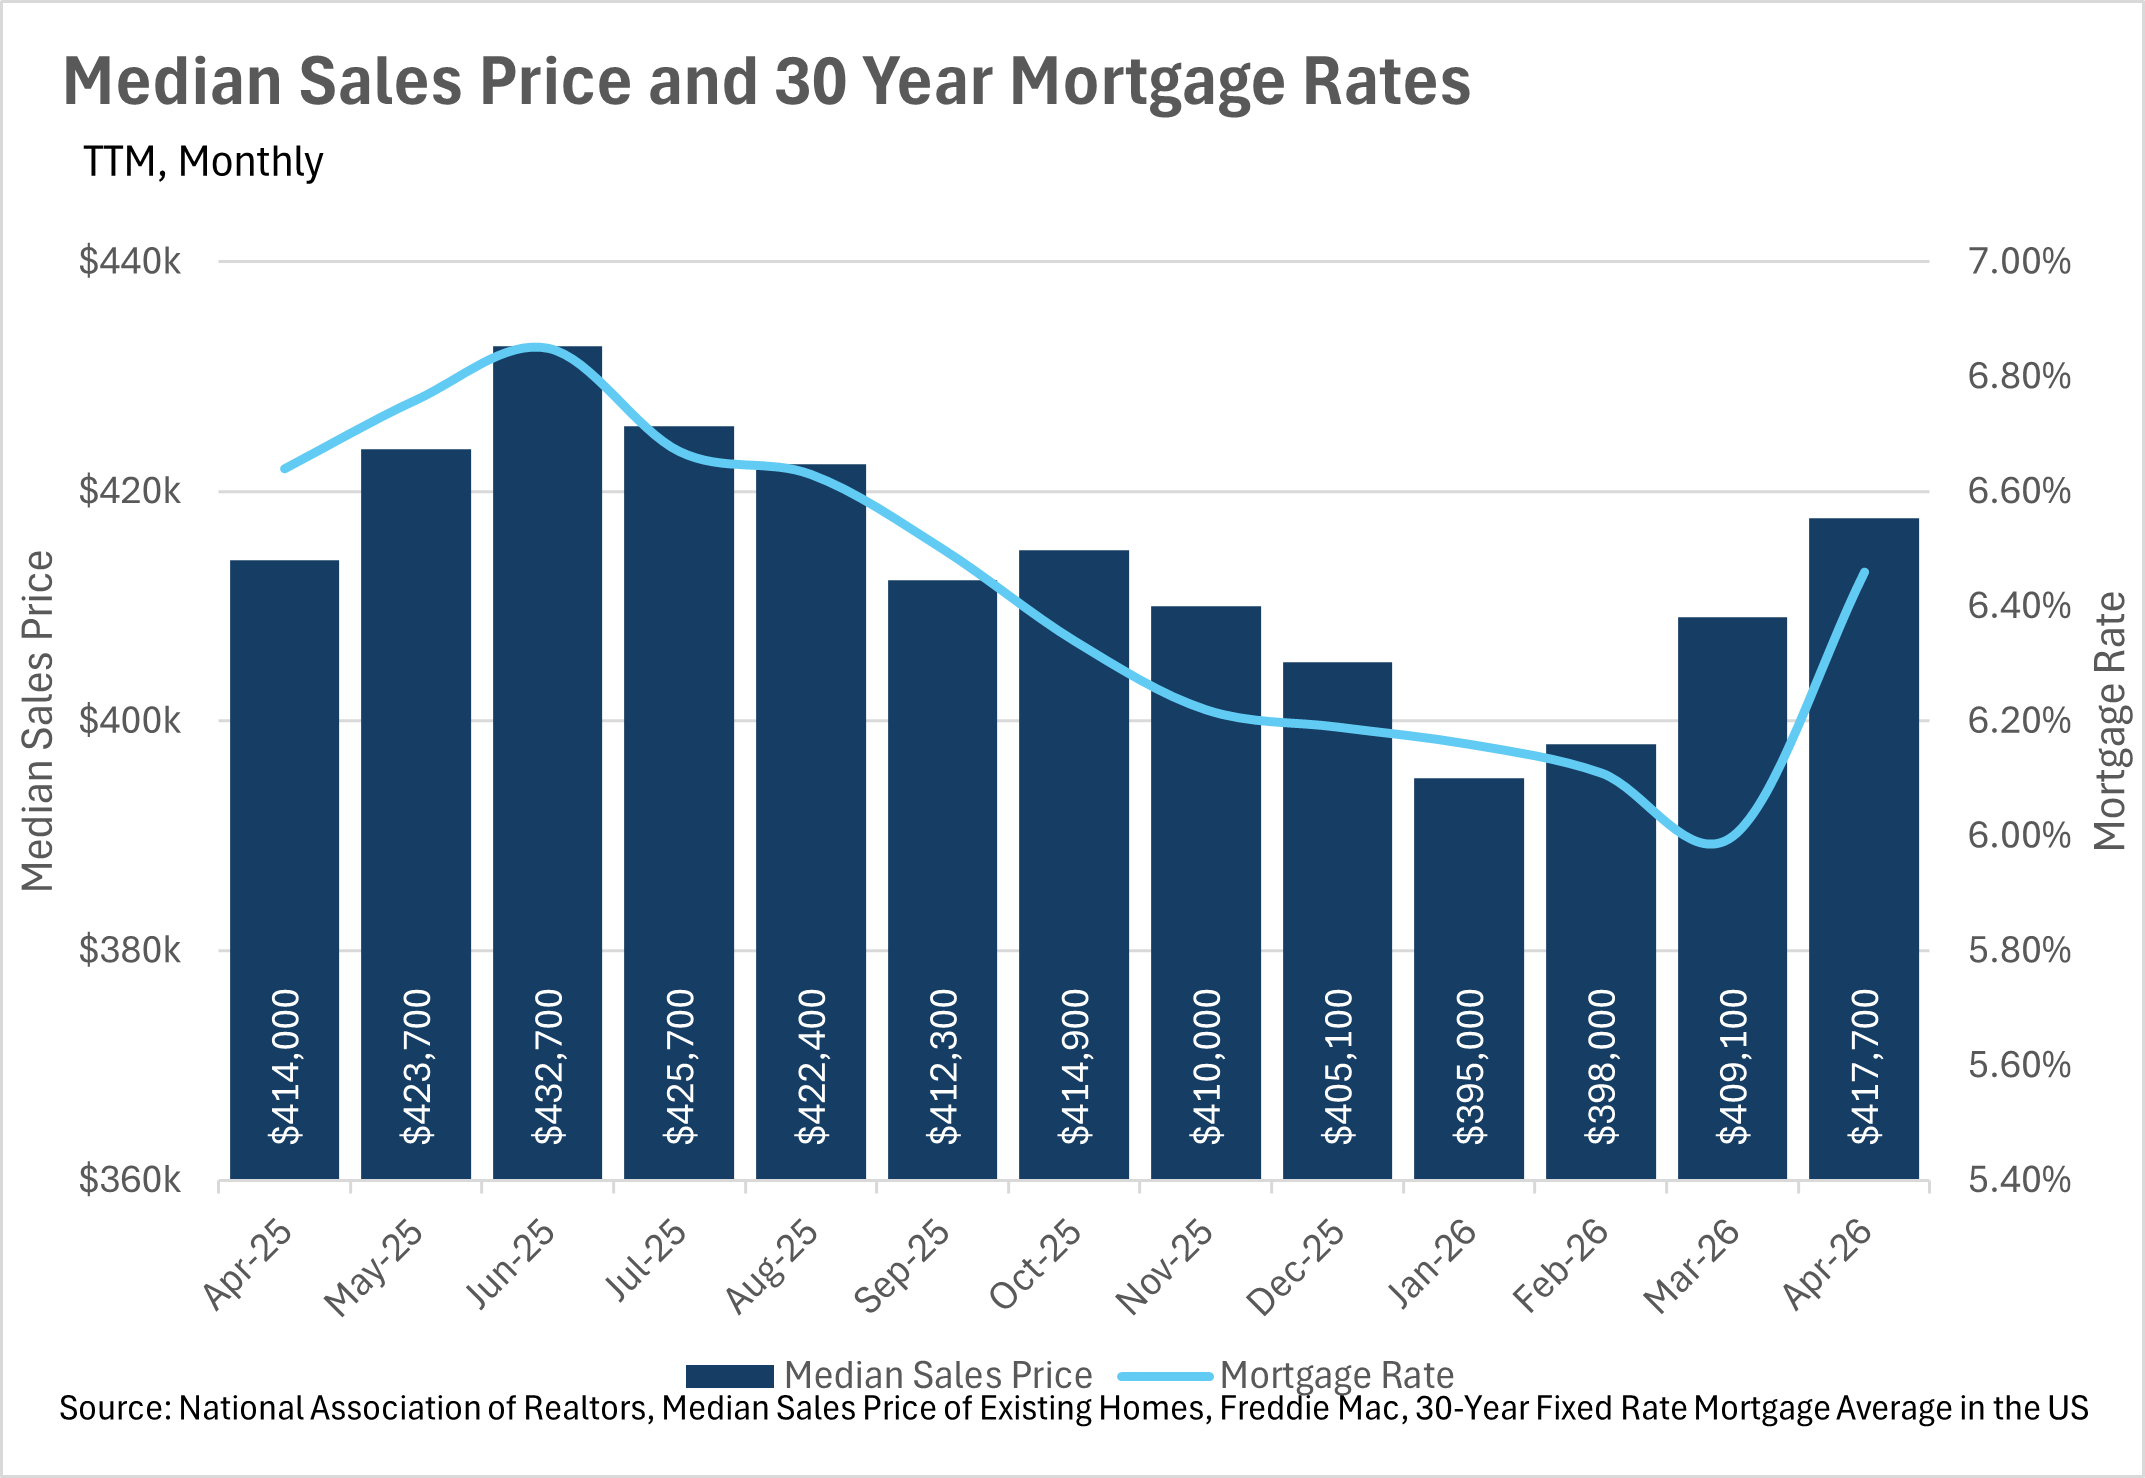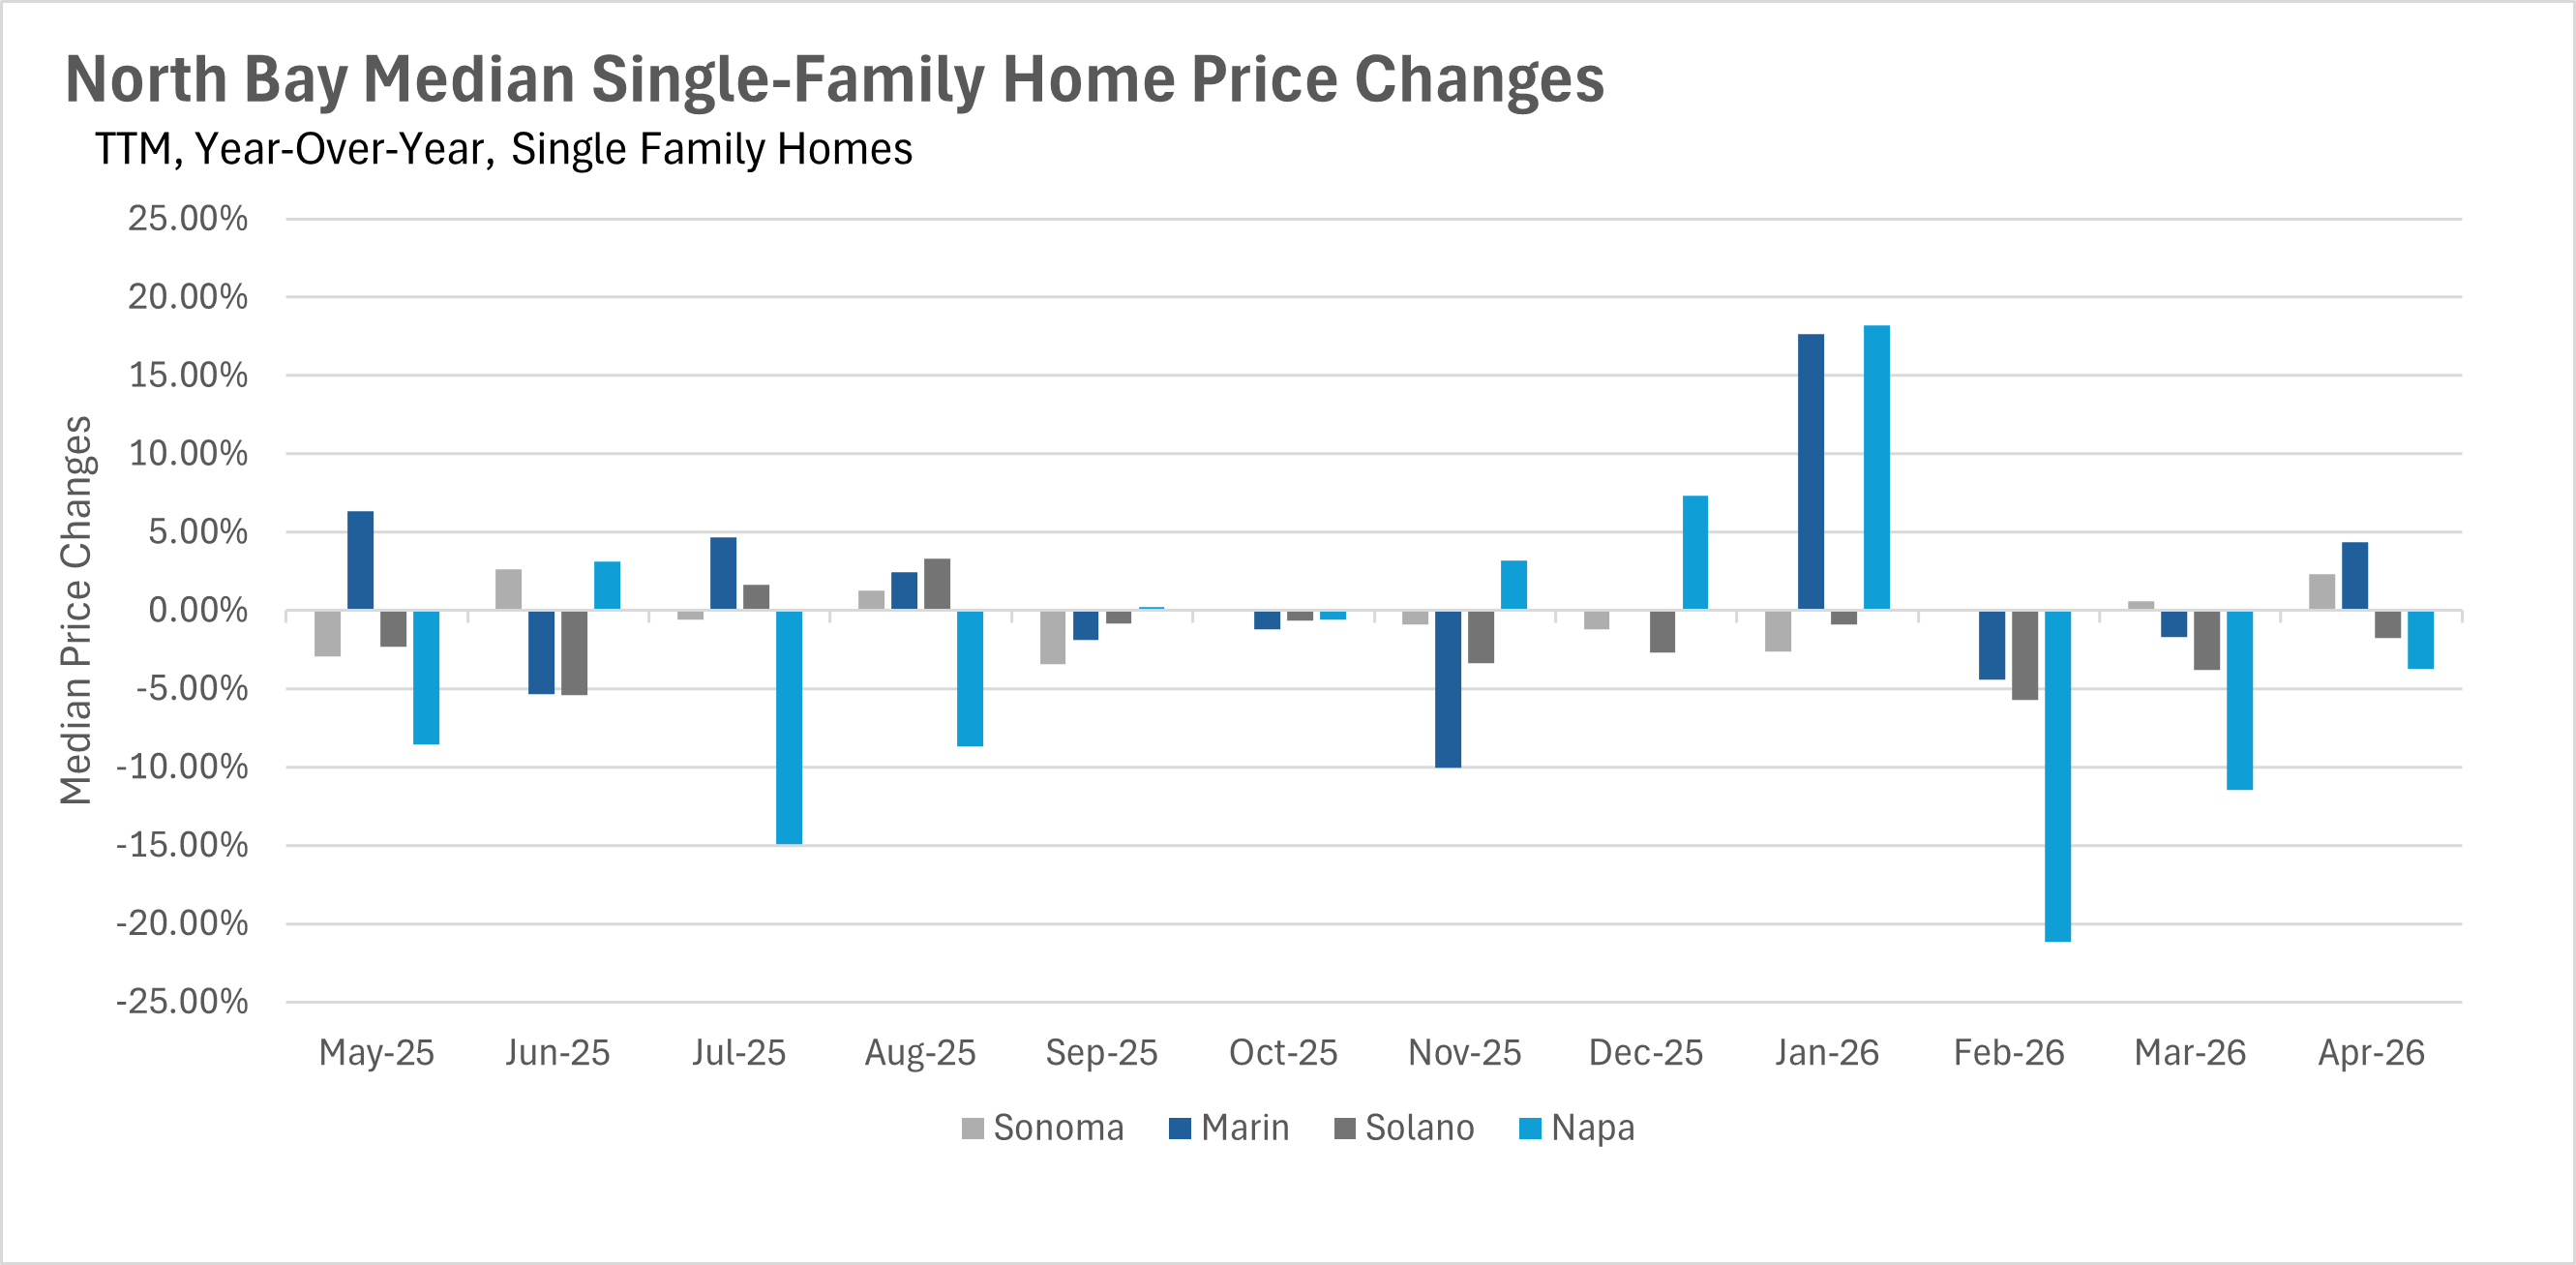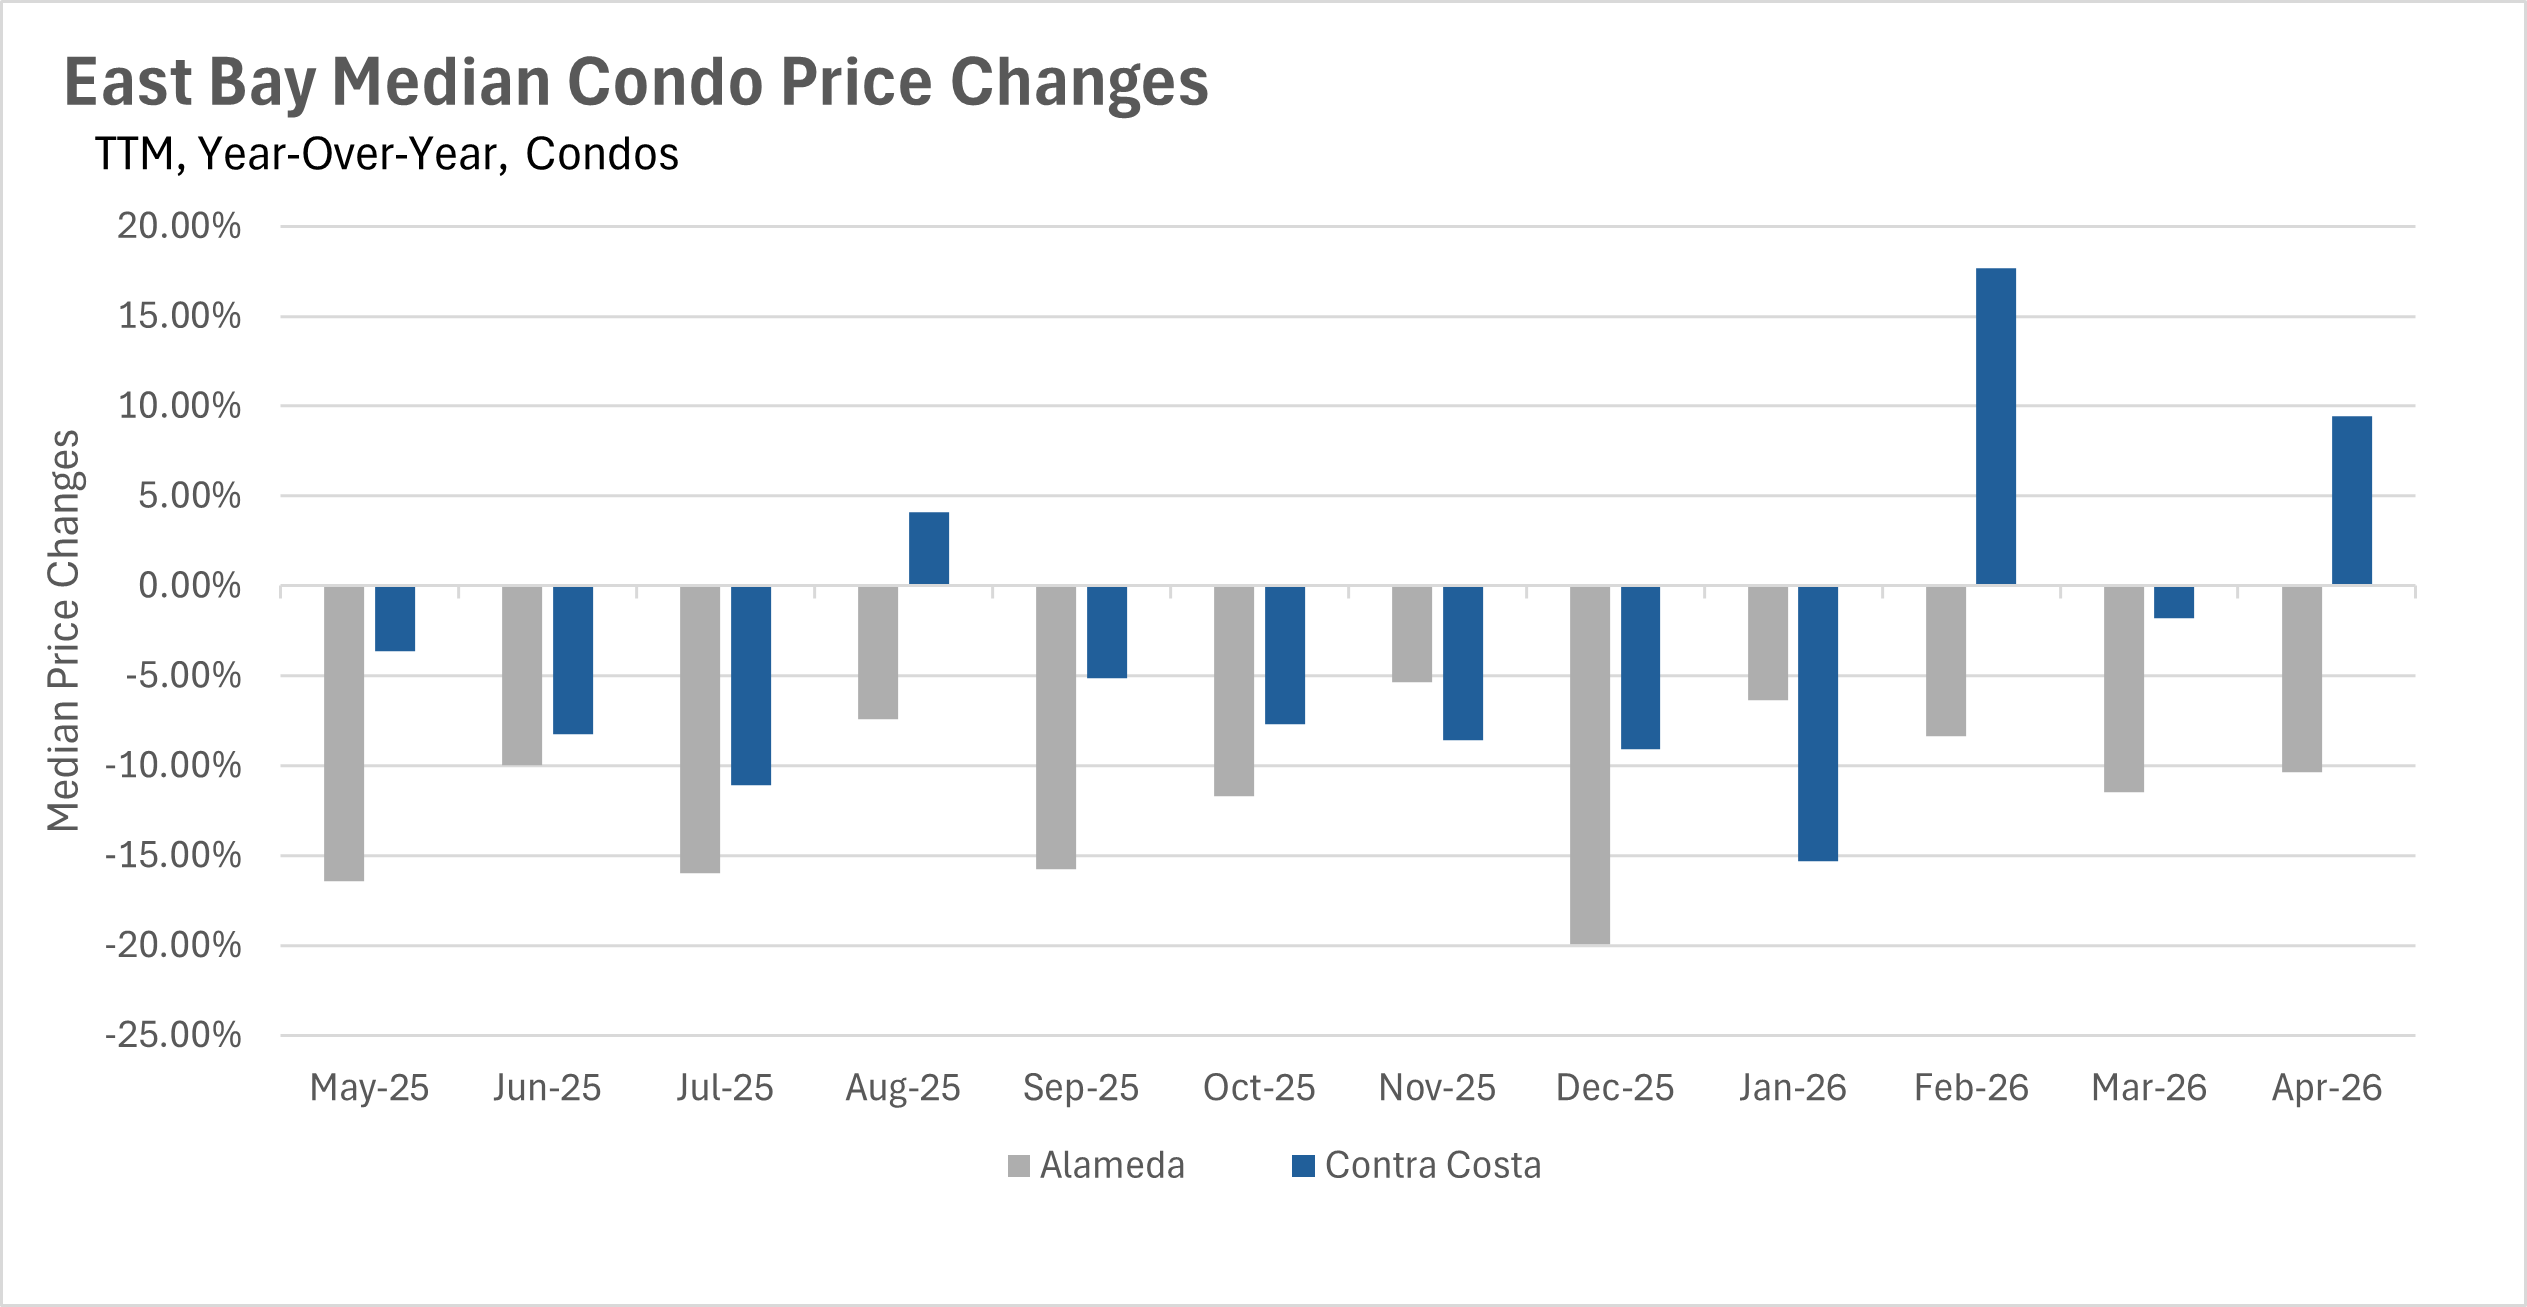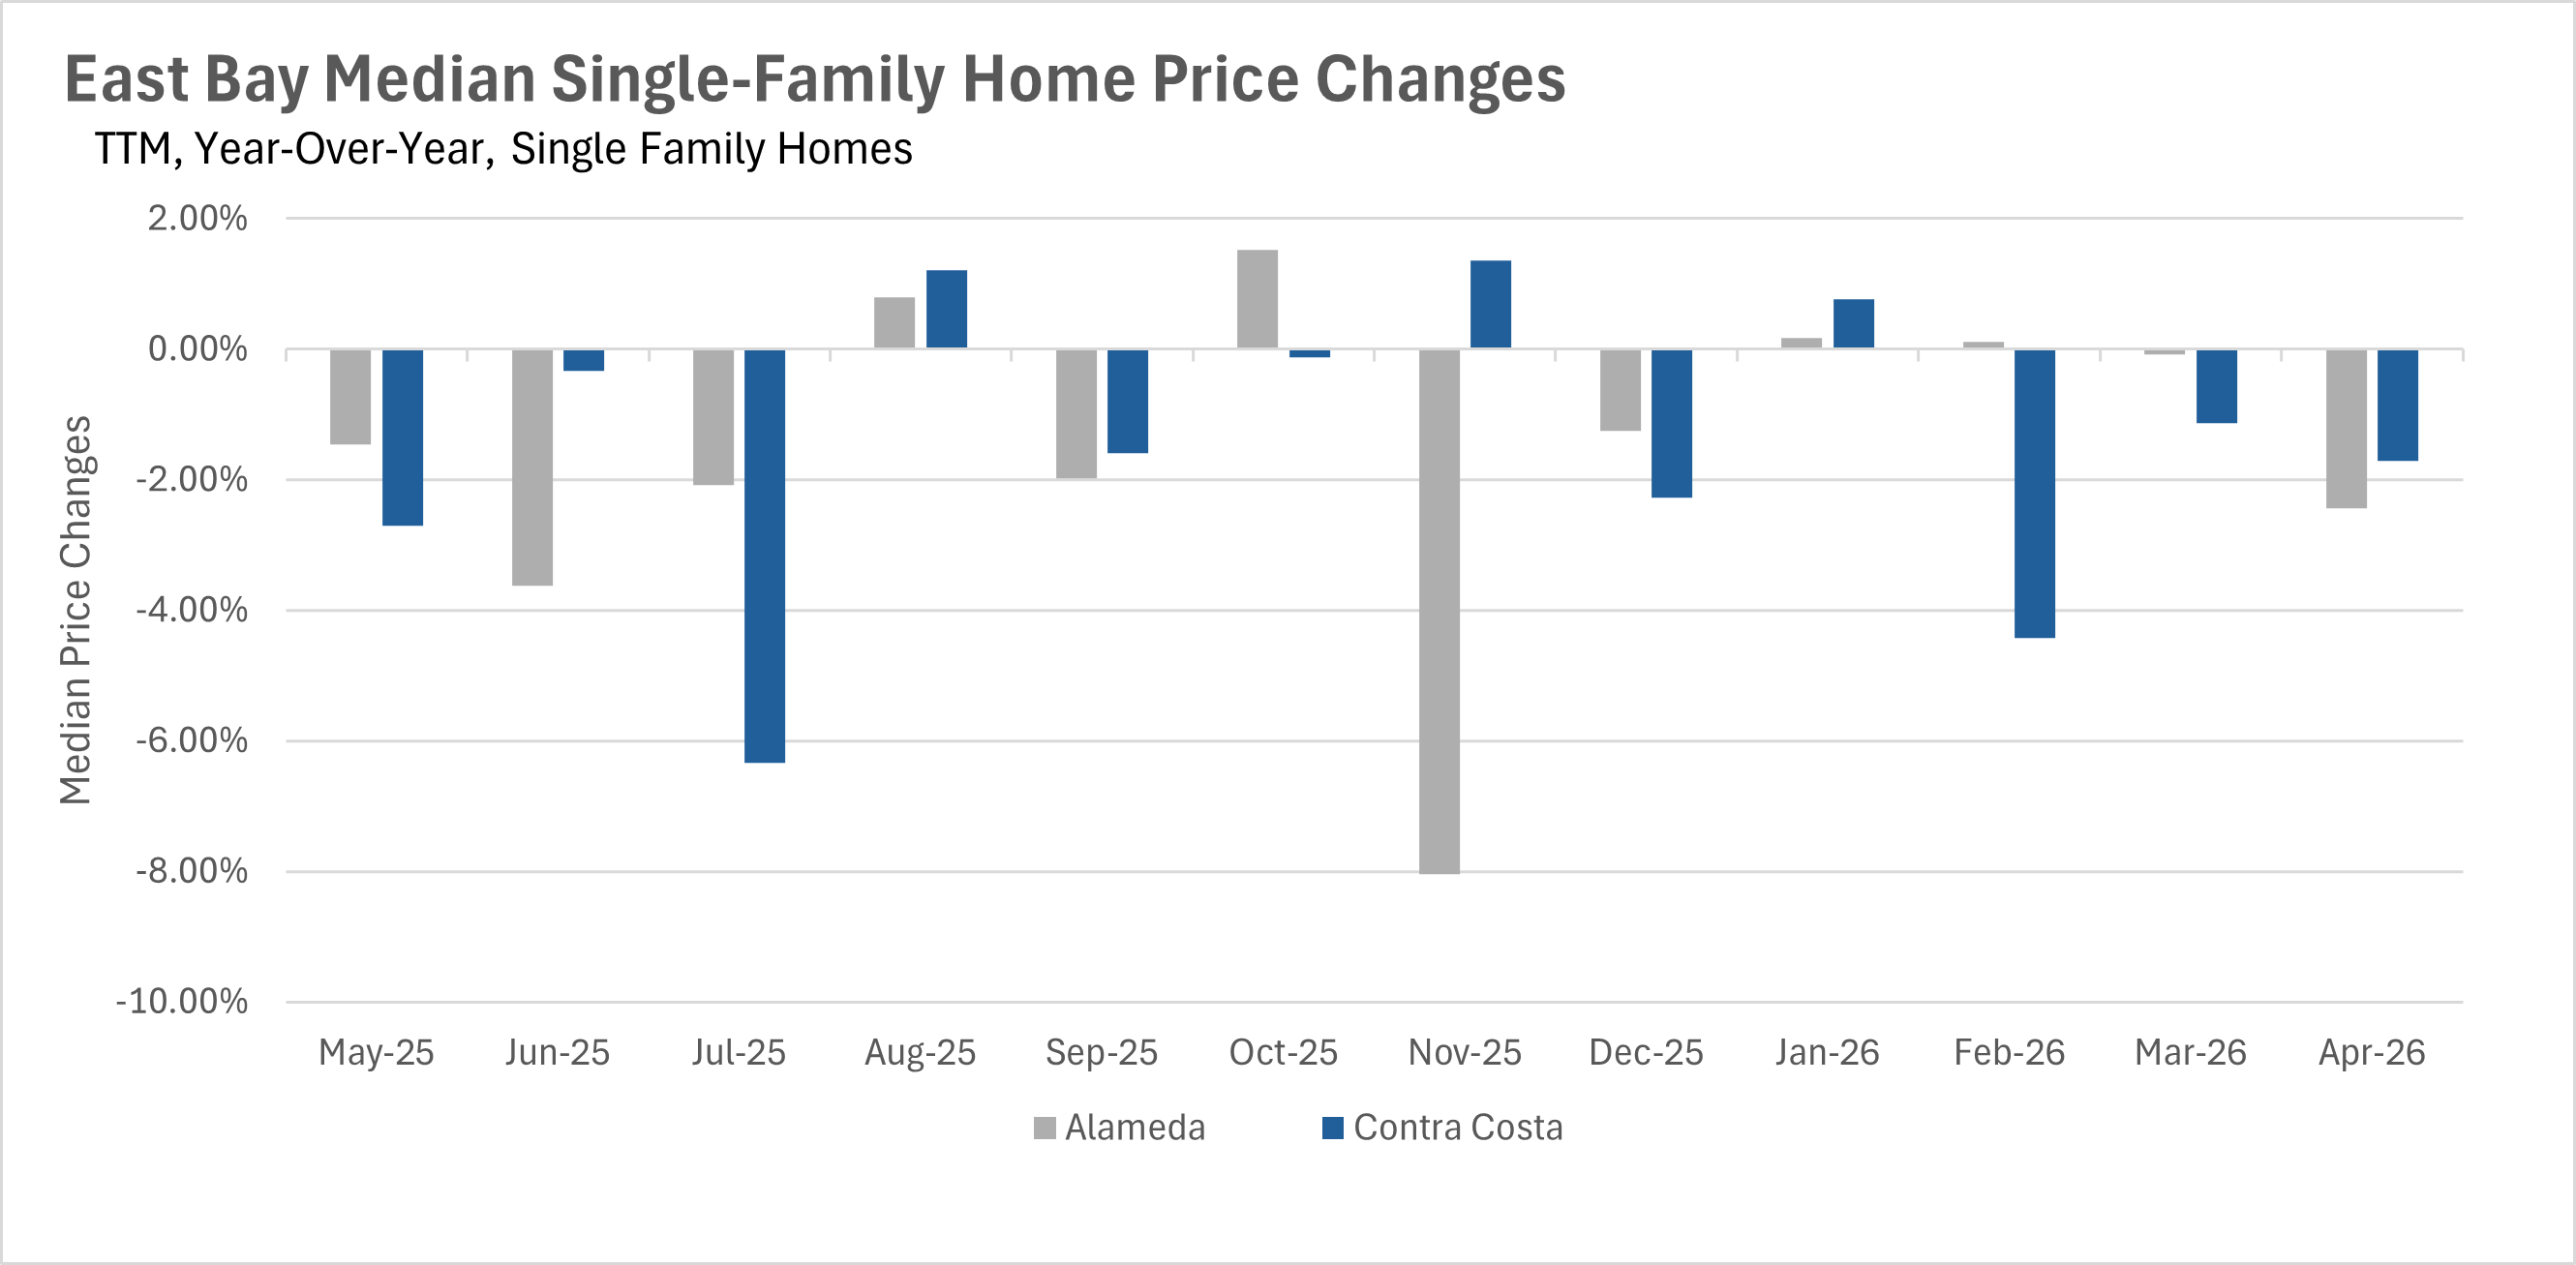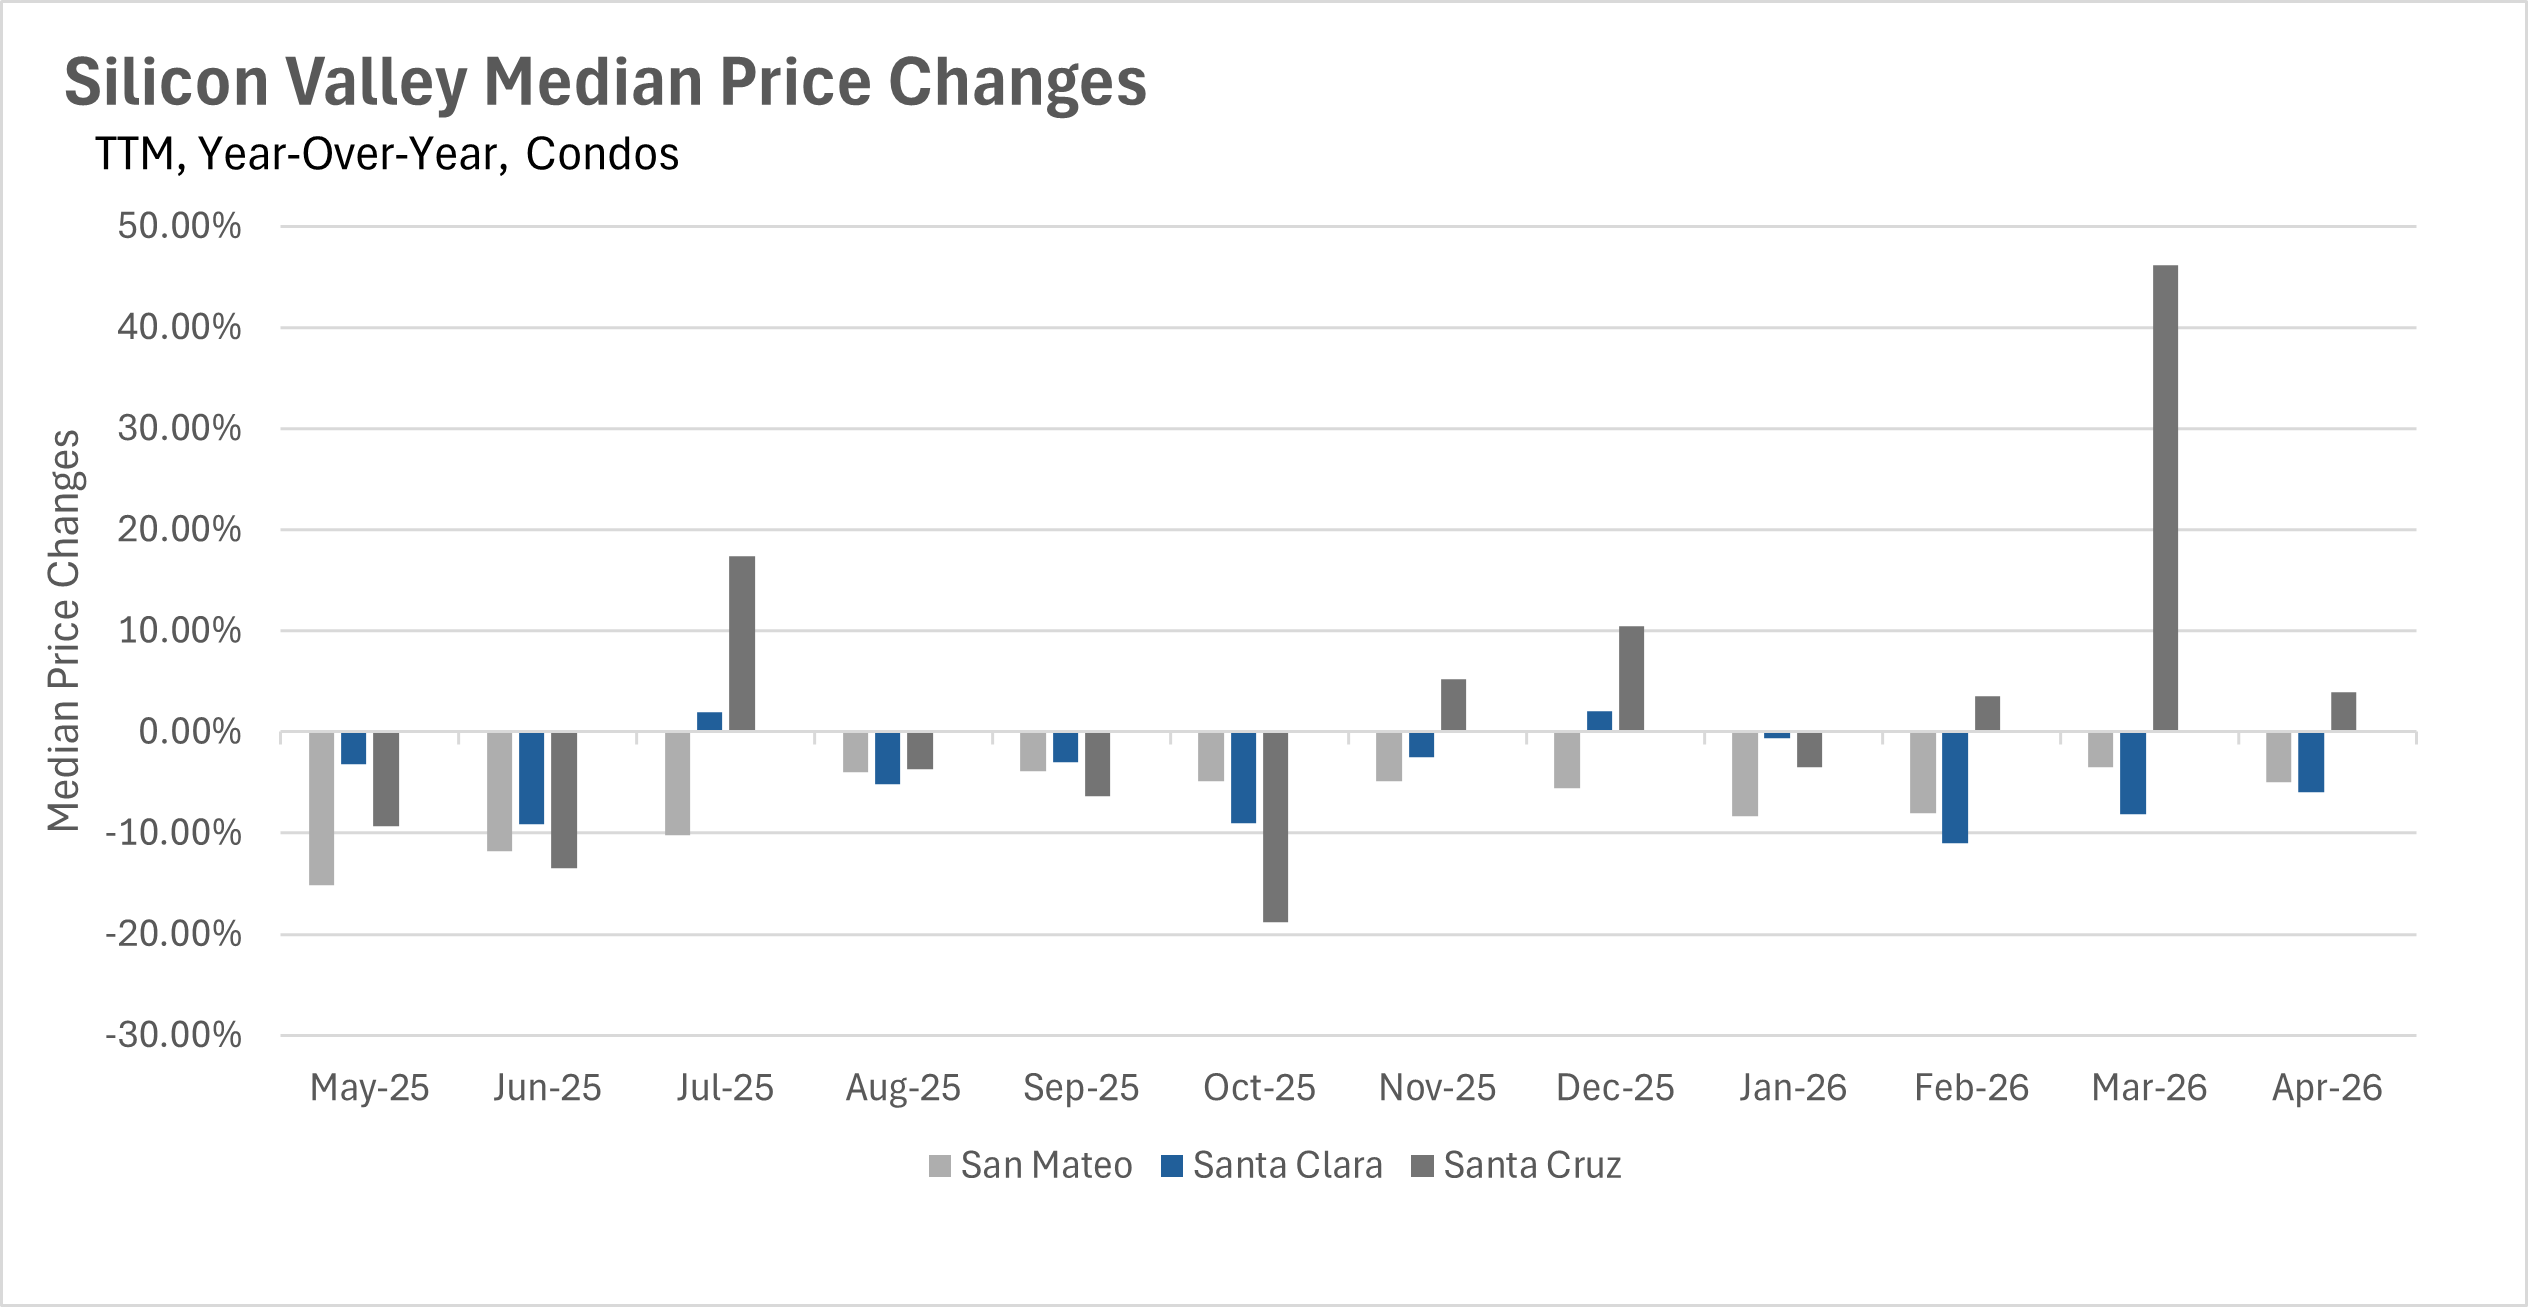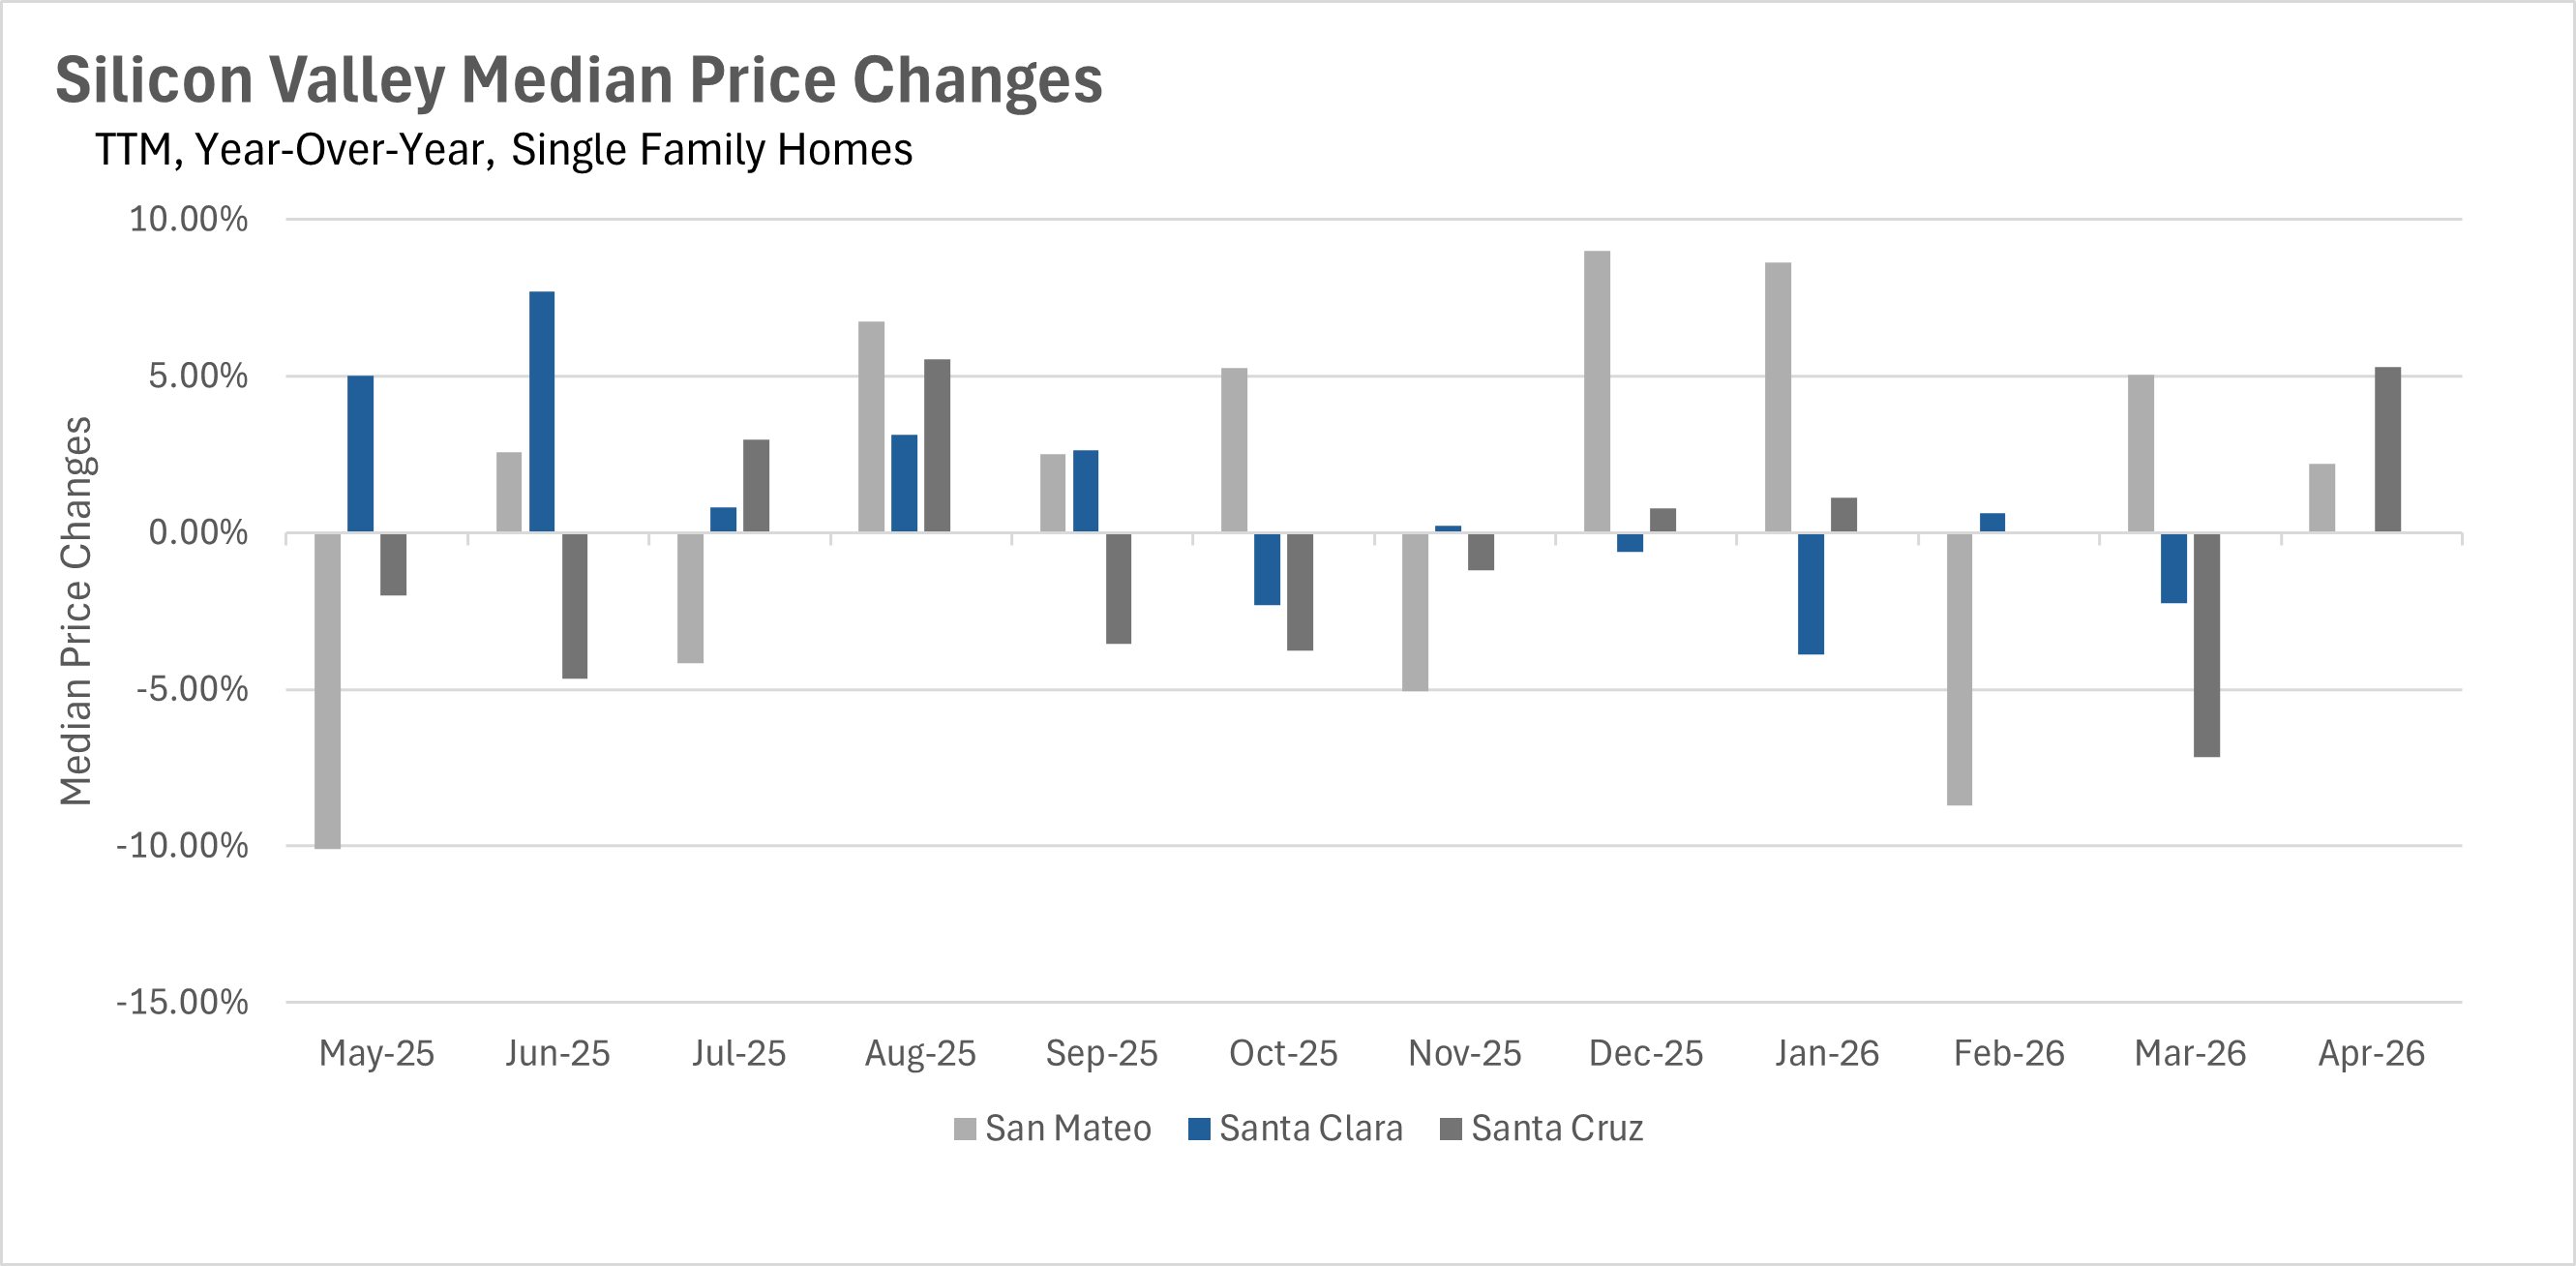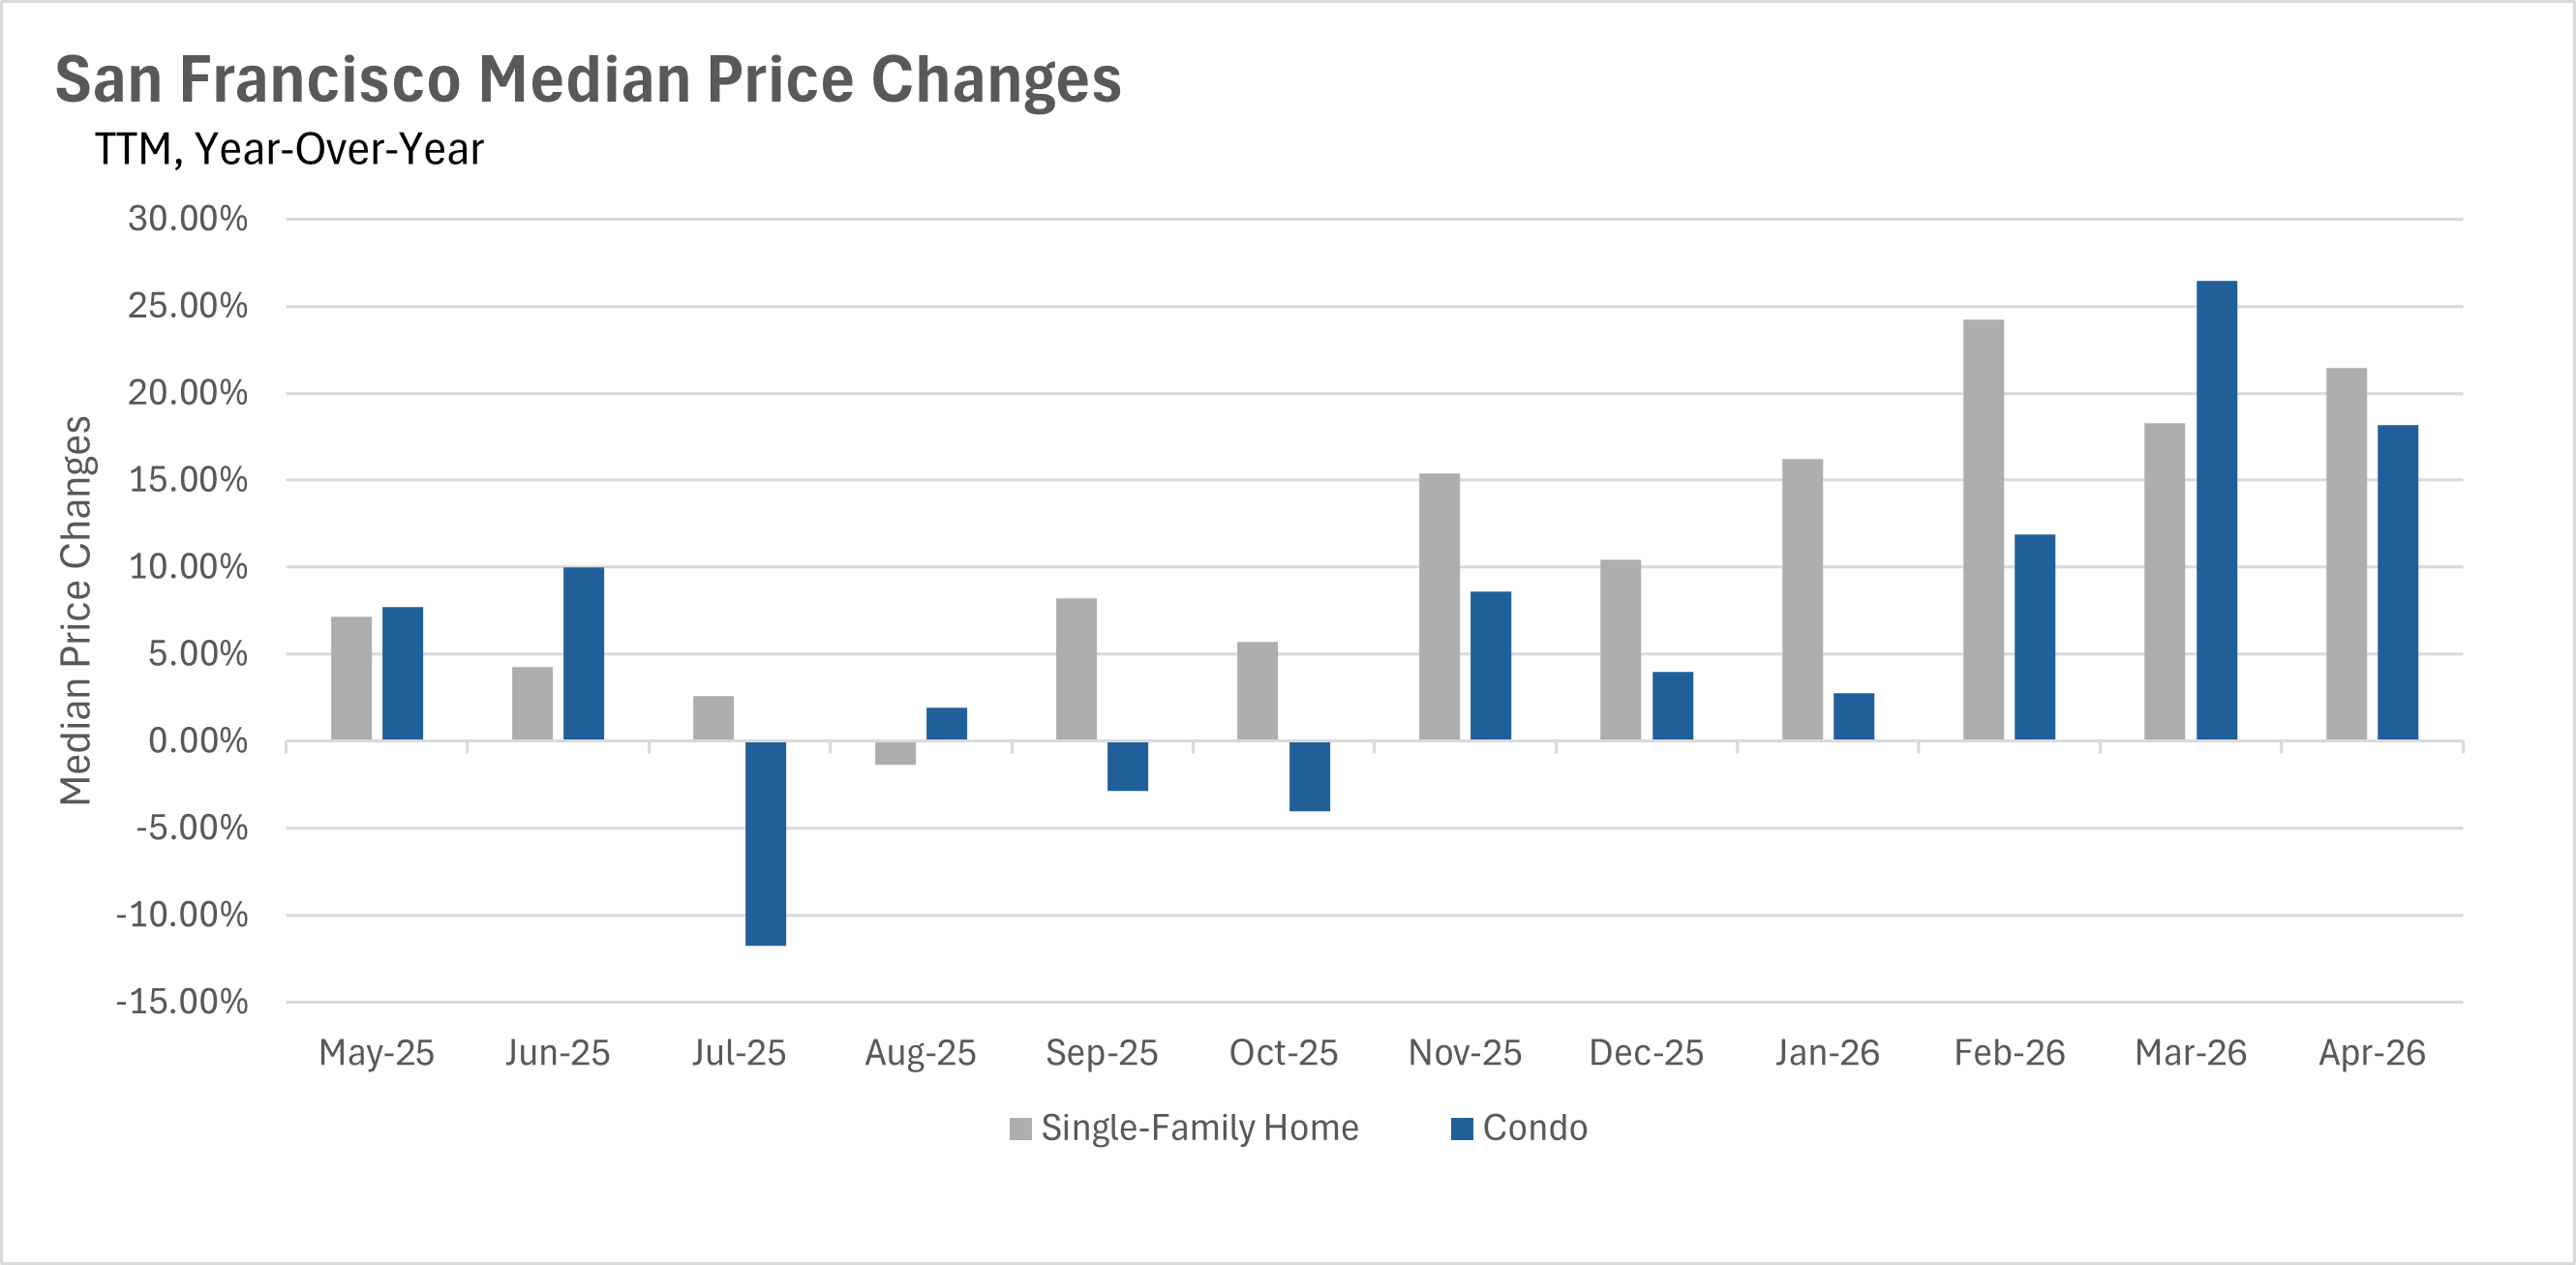Median home sale prices bounced back in a big way in April, as the spring selling season kicked into gear with nearly a 1% year-over-year increase.
Greater Bay Area market update

The Big Story
Quick Take:
  • Median home sale prices bounced back in a big way in April, as the spring selling season kicked into gear with nearly a 1% year-over-year increase.
  • Inventory levels continue to climb, with new listings pouring onto the market as sellers look to capitalize on the busier spring months.
  • Existing home sales are essentially flat on a year-over-year basis, as rising mortgage rates give buyers a reason to pause.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
 
Spring has sprung, and so have median sale prices
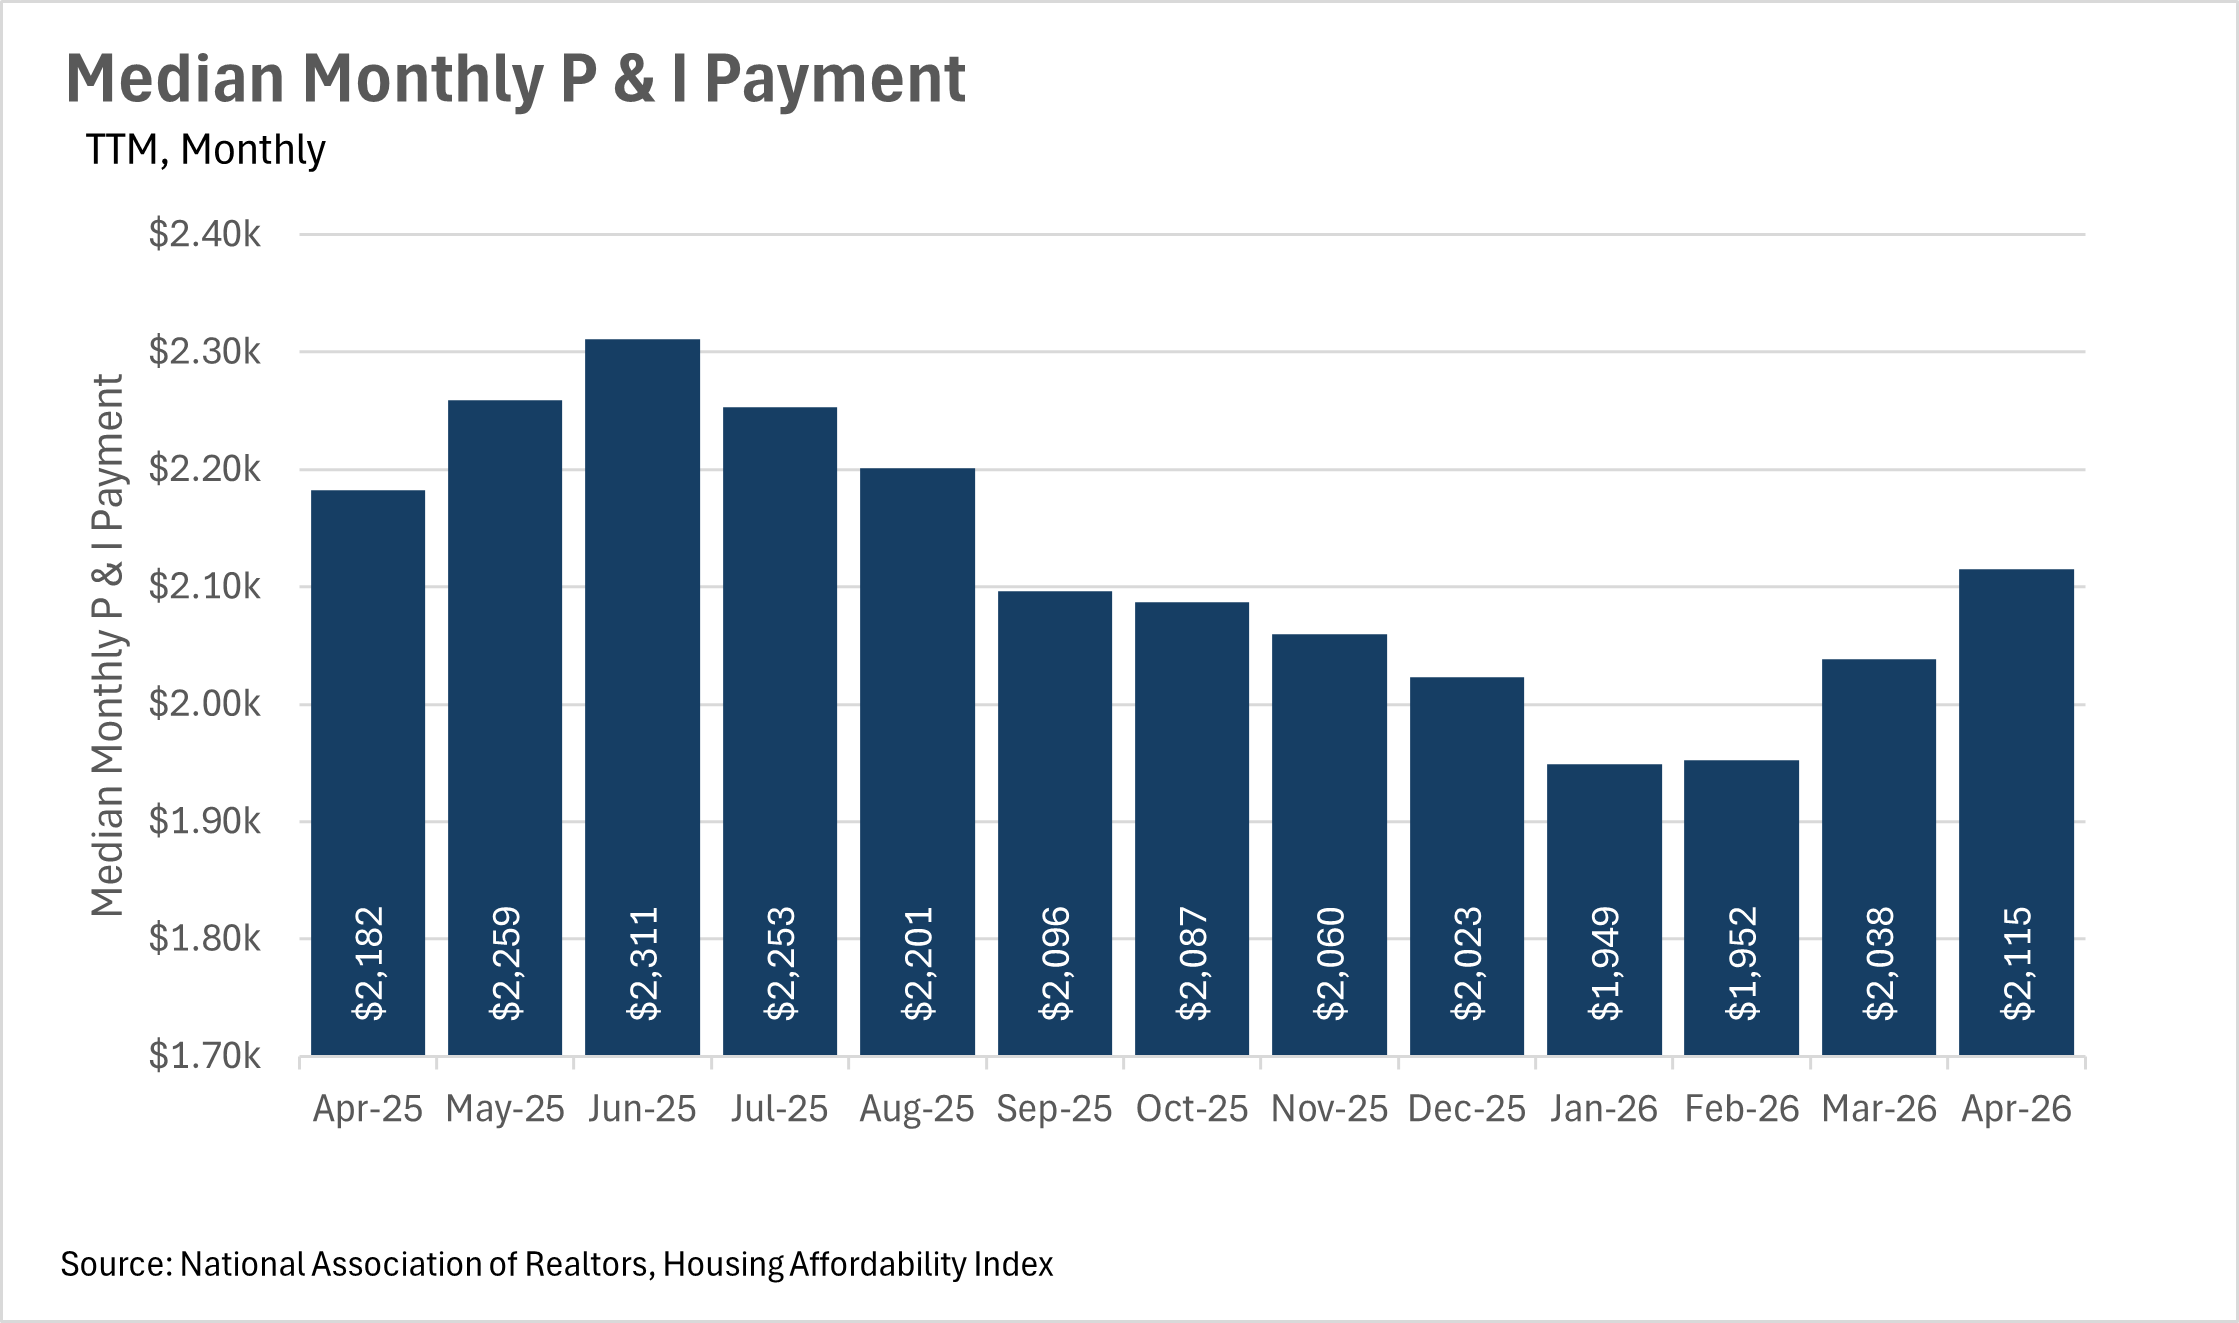
After several months of relatively flat price action, median home sale prices picked up some serious momentum in April. The median home sold for $417,700 in April, representing a 2.10% month-over-month increase and a 0.89% year-over-year gain. This bounce is especially notable when you consider that the median sale price had been on a downward trend from June of last year all the way through January, when it bottomed out at $395,000. Since then, we've seen three consecutive months of month-over-month increases, which tells us that the spring selling season is bringing some renewed energy to the market. However, it's worth noting that mortgage rates have ticked back up in recent weeks, with the average 30-year rate climbing to 6.46% in April, up from the 6.00% low we saw in March. This uptick in rates pushed the median monthly P&I payment up to $2,115, though this is still 3.07% lower than the $2,182 the median homeowner was paying at this time last year. If rates continue to climb, it could put a ceiling on how much further prices can rise in the near term.
New listings are flooding the market as sellers get off the sidelines
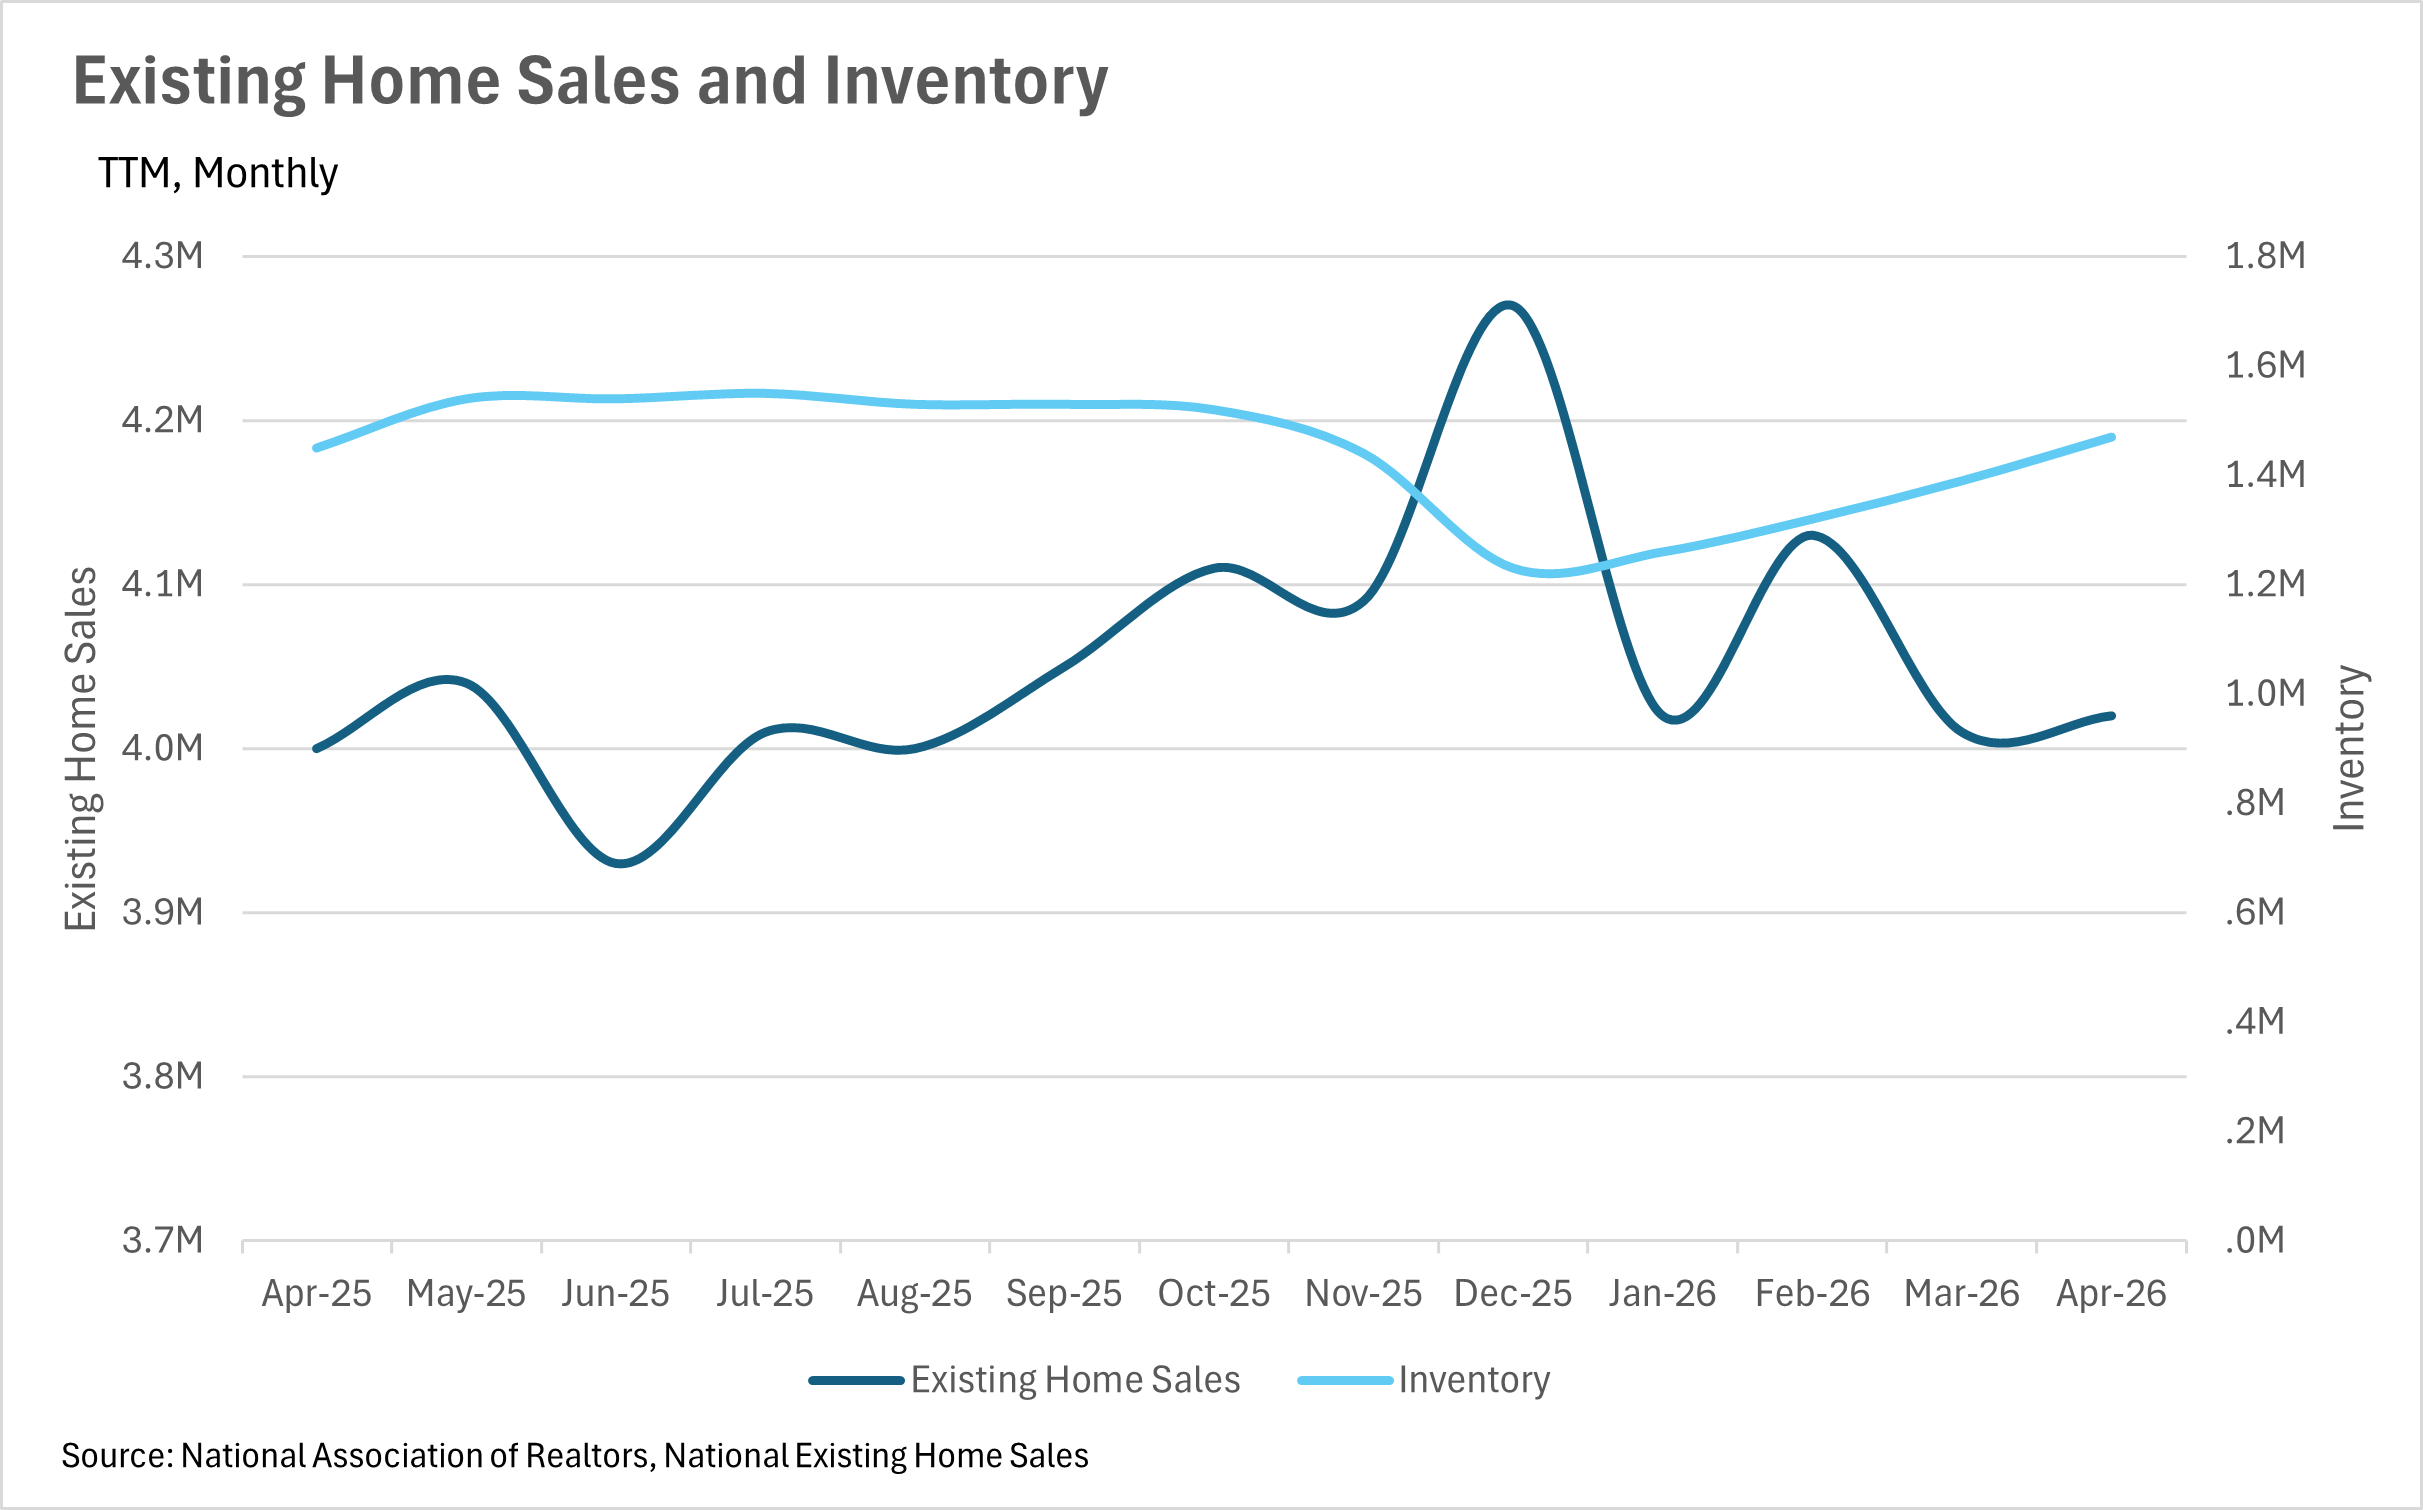
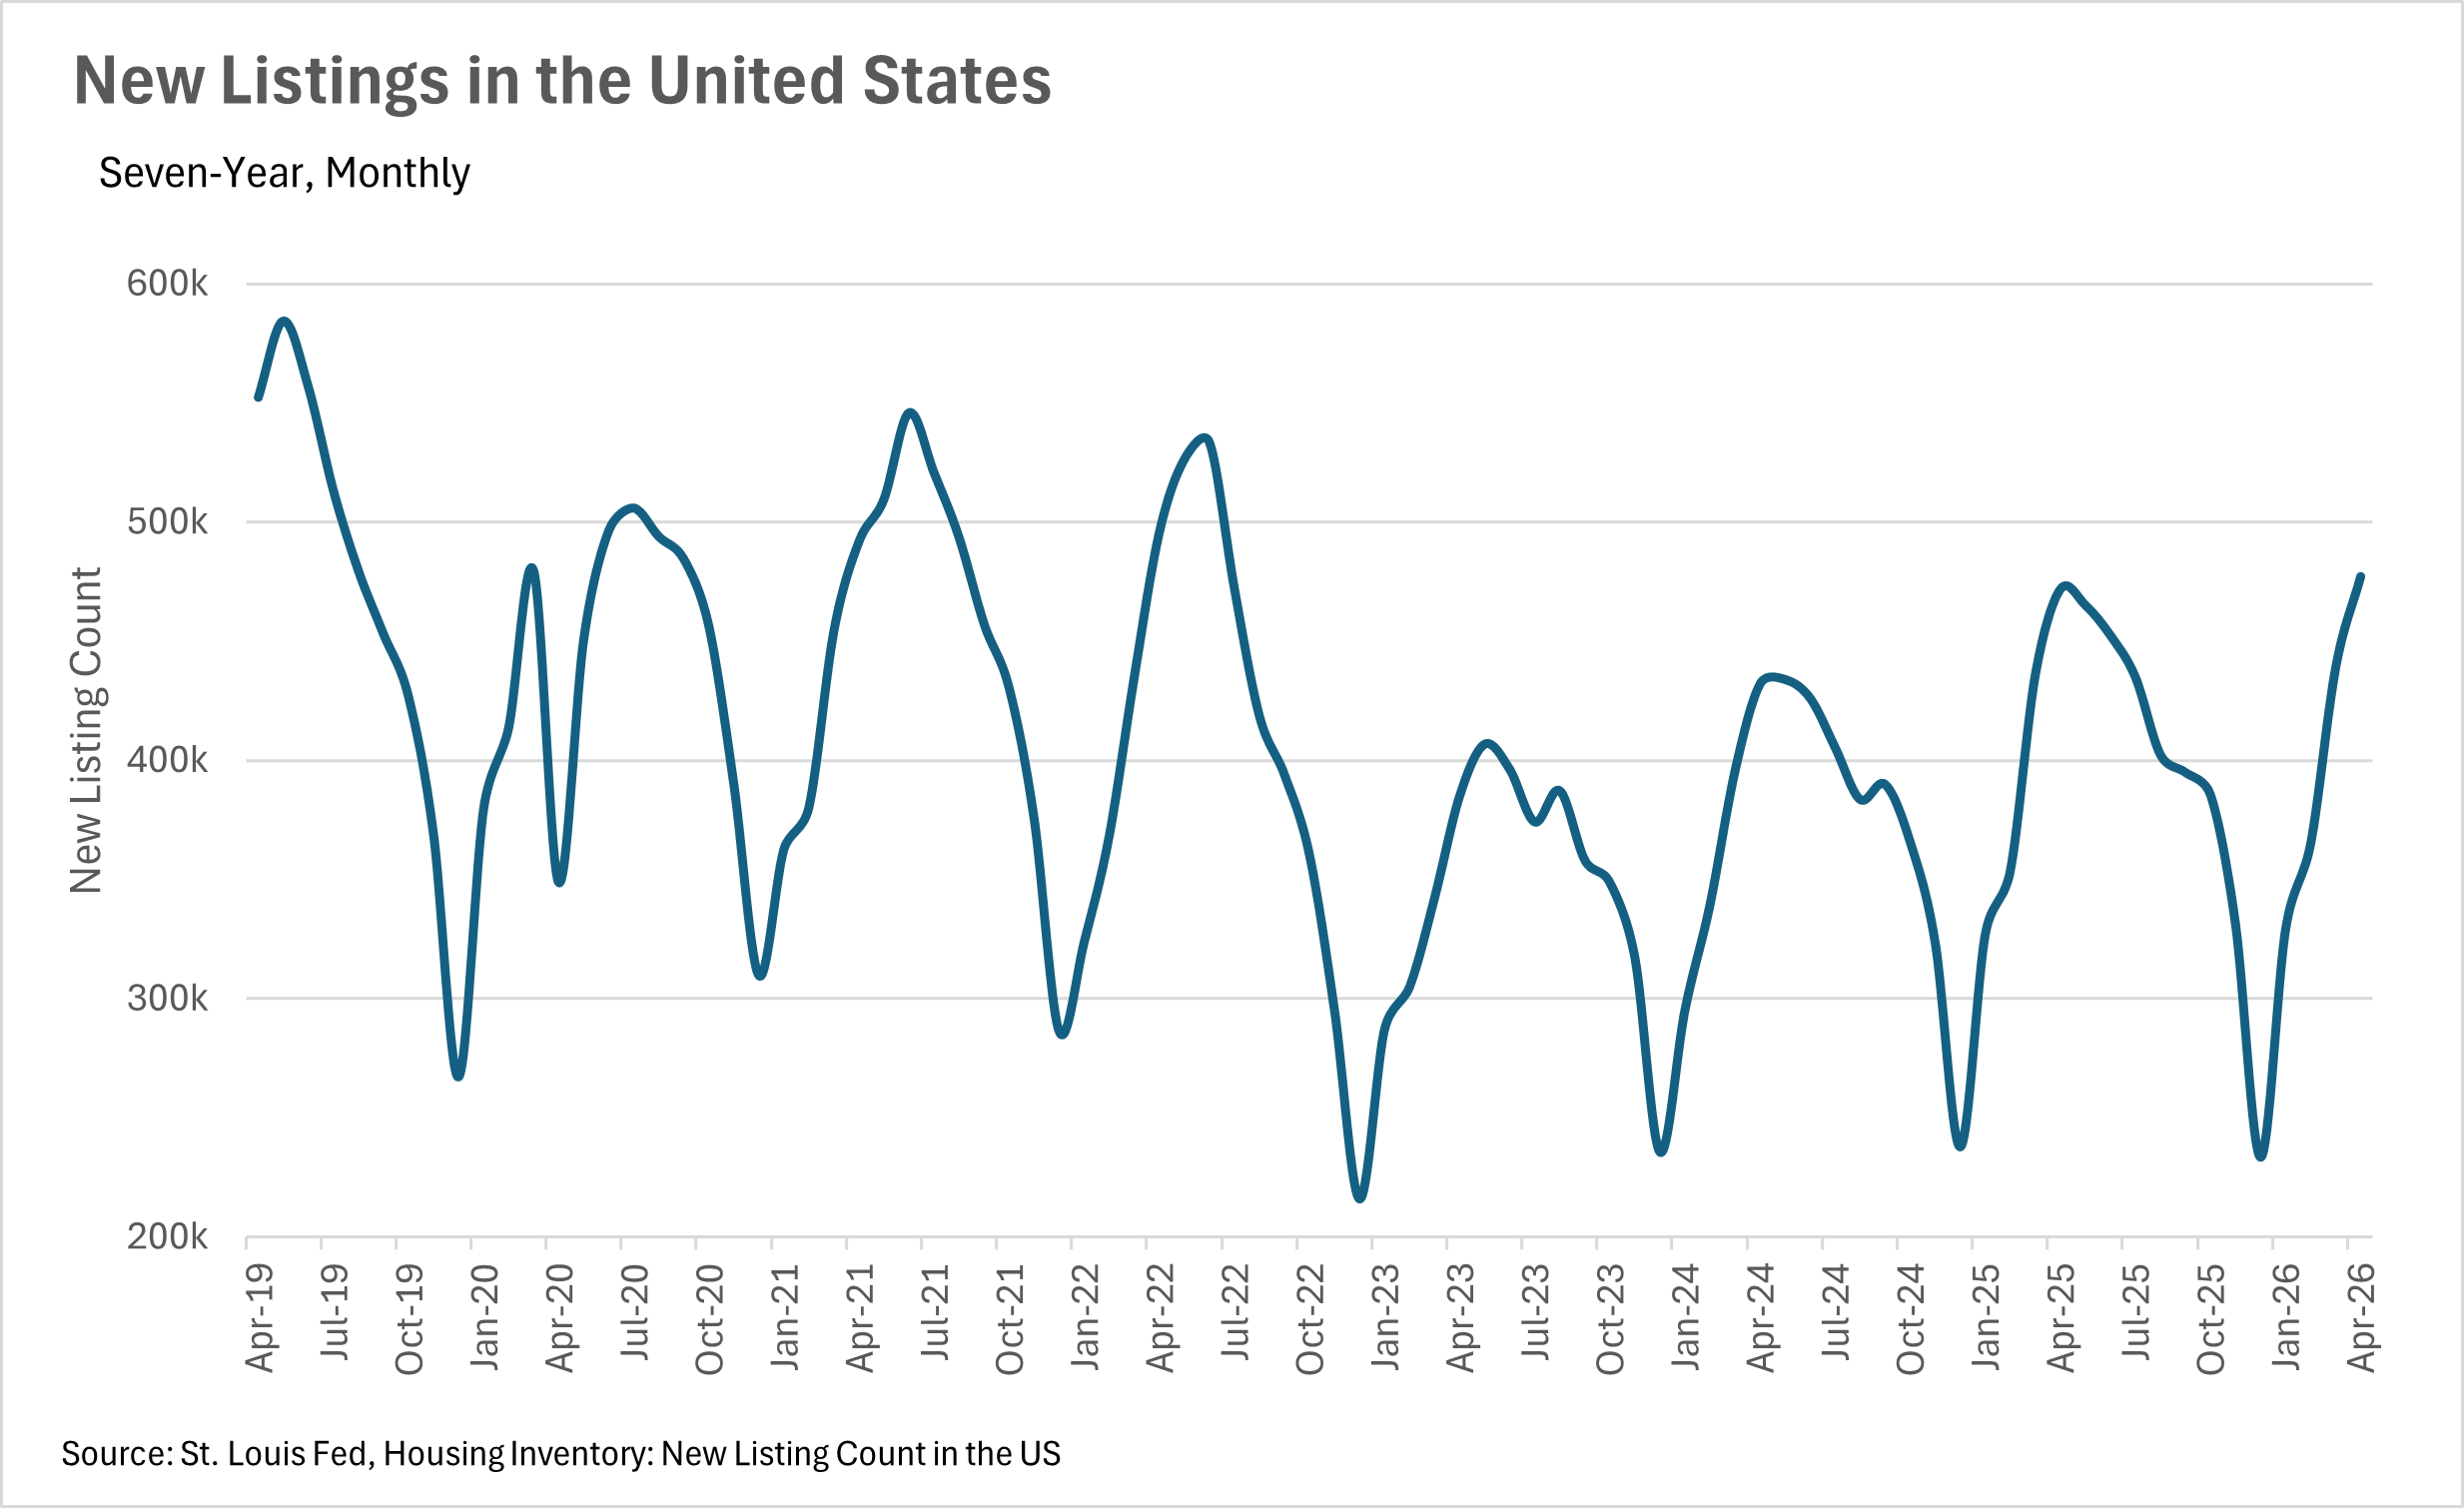
As the spring selling season heats up, we're seeing a significant wave of new listings hit the market. In April, there were 477,116 new listings nationwide, representing an 8.70% month-over-month increase and a 1.13% year-over-year increase. This influx of new listings is great news for buyers who have been dealing with limited options for the better part of the past few years. On the inventory side, there are now 1,470,000 homes available for sale, representing a 5.76% month-over-month increase and a 1.38% year-over-year increase. Inventory has been steadily building since its December low of 1,230,000, and we're now approaching the levels we were seeing during the peak of inventory season last summer. If this trend continues through May and June, buyers could find themselves with the most options they've had in quite some time, which would be a welcome shift in a market that has been starved for supply.
Existing home sales are holding steady, but buyers remain cautious
Despite the influx of new inventory and three consecutive months of rising prices, existing home sales have remained relatively flat. In April, 4,020,000 homes changed hands, representing just a 0.50% year-over-year increase and a 0.25% month-over-month uptick. While it's encouraging that sales are at least trending in the right direction, the pace of improvement has been glacial, which suggests that many buyers are still sitting on the sidelines. Part of the story here is the recent uptick in mortgage rates. After falling steadily from 6.85% last June to 6.00% in March, rates have bounced back to 6.46%, which may have given some prospective buyers cold feet. If rates stabilize or begin to decline again, we could see existing home sales pick up in a meaningful way as we move into the summer months. For now, though, it seems like buyers are content to wait and watch.
A balancing act heading into the summer
When determining whether a market is a buyers' market or a sellers' market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller's market, whereas markets with more than three months of MSI are considered buyers' markets.
 
At the national level, we're seeing the market inch closer to a more balanced state. Inventory continues to build heading into the summer, while existing home sales have been essentially flat, meaning that the available supply is lasting a bit longer than it did at this time last year. However, the recent reversal in mortgage rates adds a layer of uncertainty to the equation. If rates continue to rise, we could see demand soften further, which would push the market toward buyers. On the other hand, if rates settle back down and buyers start to re-engage, the growing inventory could get absorbed quickly, keeping the market tilted in favor of sellers. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
Big Story Data
Line chart of existing home sales and inventory from April 2025 to April 2026; sales peak in December, while inventory rises afterward.
Chart comparing monthly median home sale prices and 30-year mortgage rates from April 2025 to April 2026.
Line chart of monthly U.S. new listings, April 2019–April 2026, with recurring seasonal peaks and dips.
Bar chart of median monthly principal and interest payments, peaking at $2,311 in June 2025 and bottoming at $1,949 in January 2026.
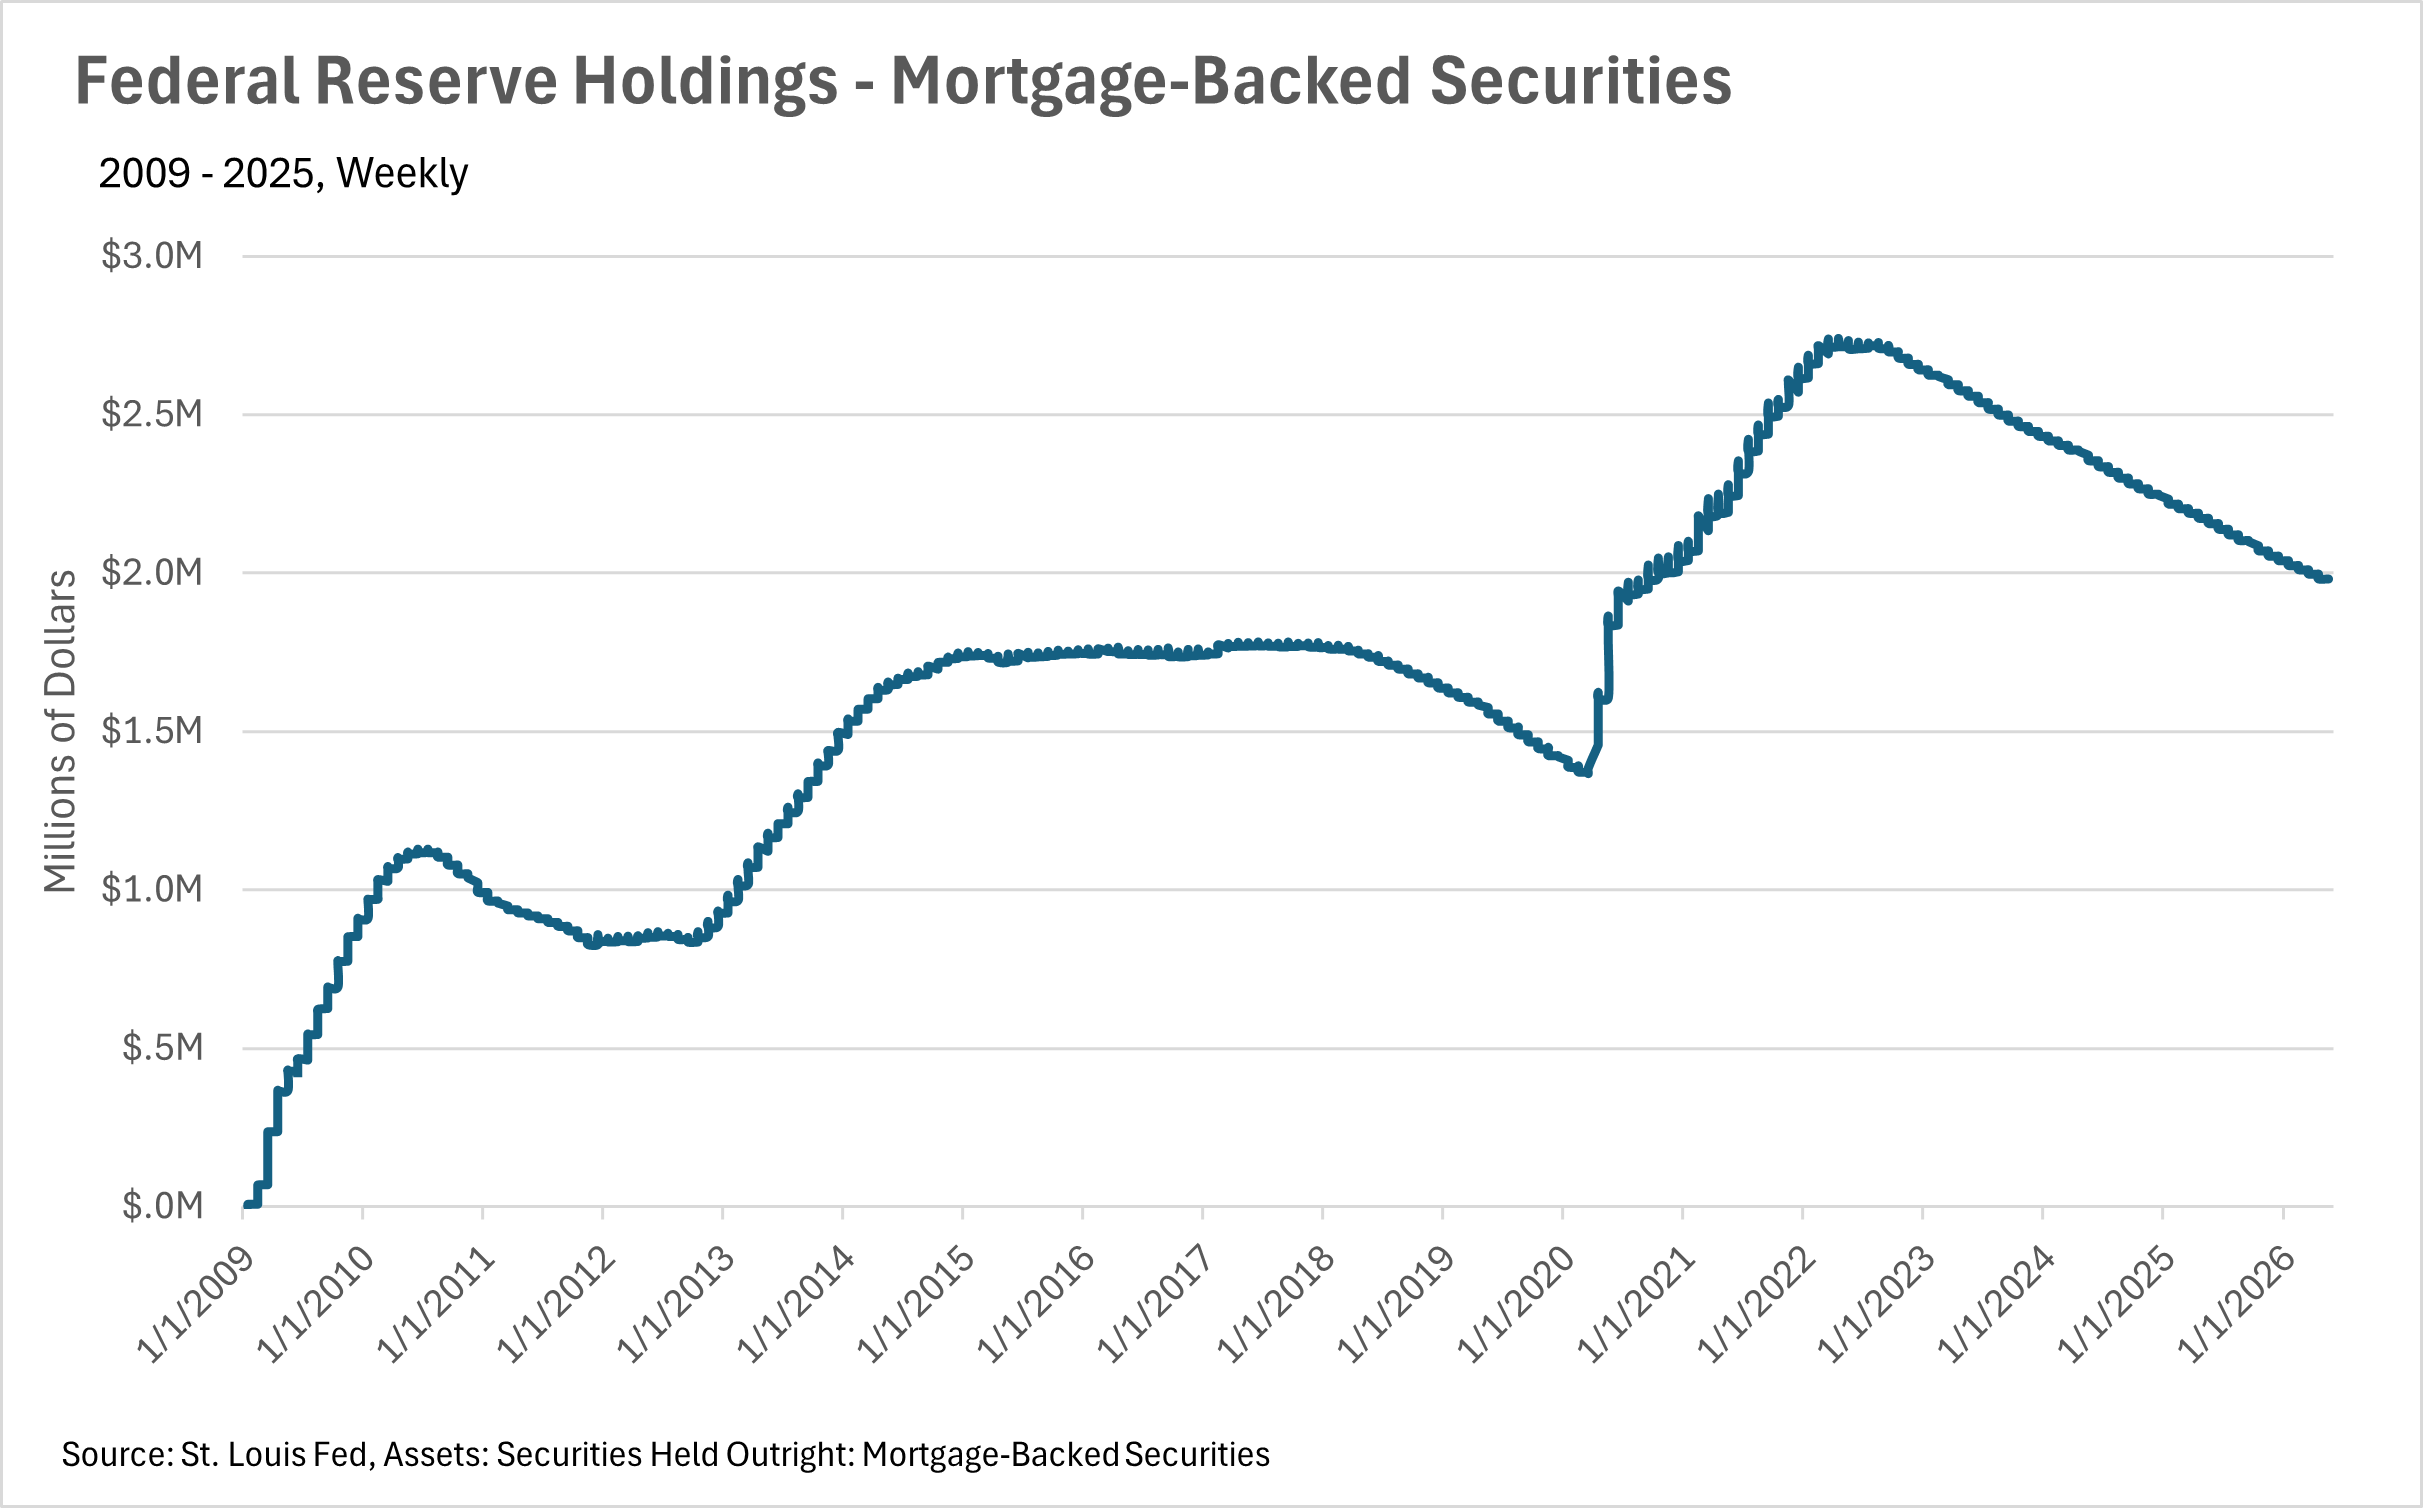
Line chart of Federal Reserve mortgage-backed securities holdings, peaking near $2.7 trillion in 2022 before declining.
The Local Lowdown
Quick Take:
  • San Francisco continues to lead the Bay Area with double-digit price appreciation in both single-family homes and condos, while prices across Silicon Valley and the western North Bay are also gaining ground.
  • Inventory levels remain well below last year across the entire region, with year-over-year declines ranging from 12% in Silicon Valley to nearly 37% in the North Bay and close to 40% in San Francisco.
  • Single-family homes are selling at an incredibly fast clip, with listings in Santa Clara County moving in just 9 days and San Francisco homes routinely selling for more than 20% over asking price.
  • The condo market has become a buyer's market in several East Bay and North Bay counties, creating a stark contrast with the fiercely competitive single-family home market.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
San Francisco shatters records while much of the Bay Area posts steady gains
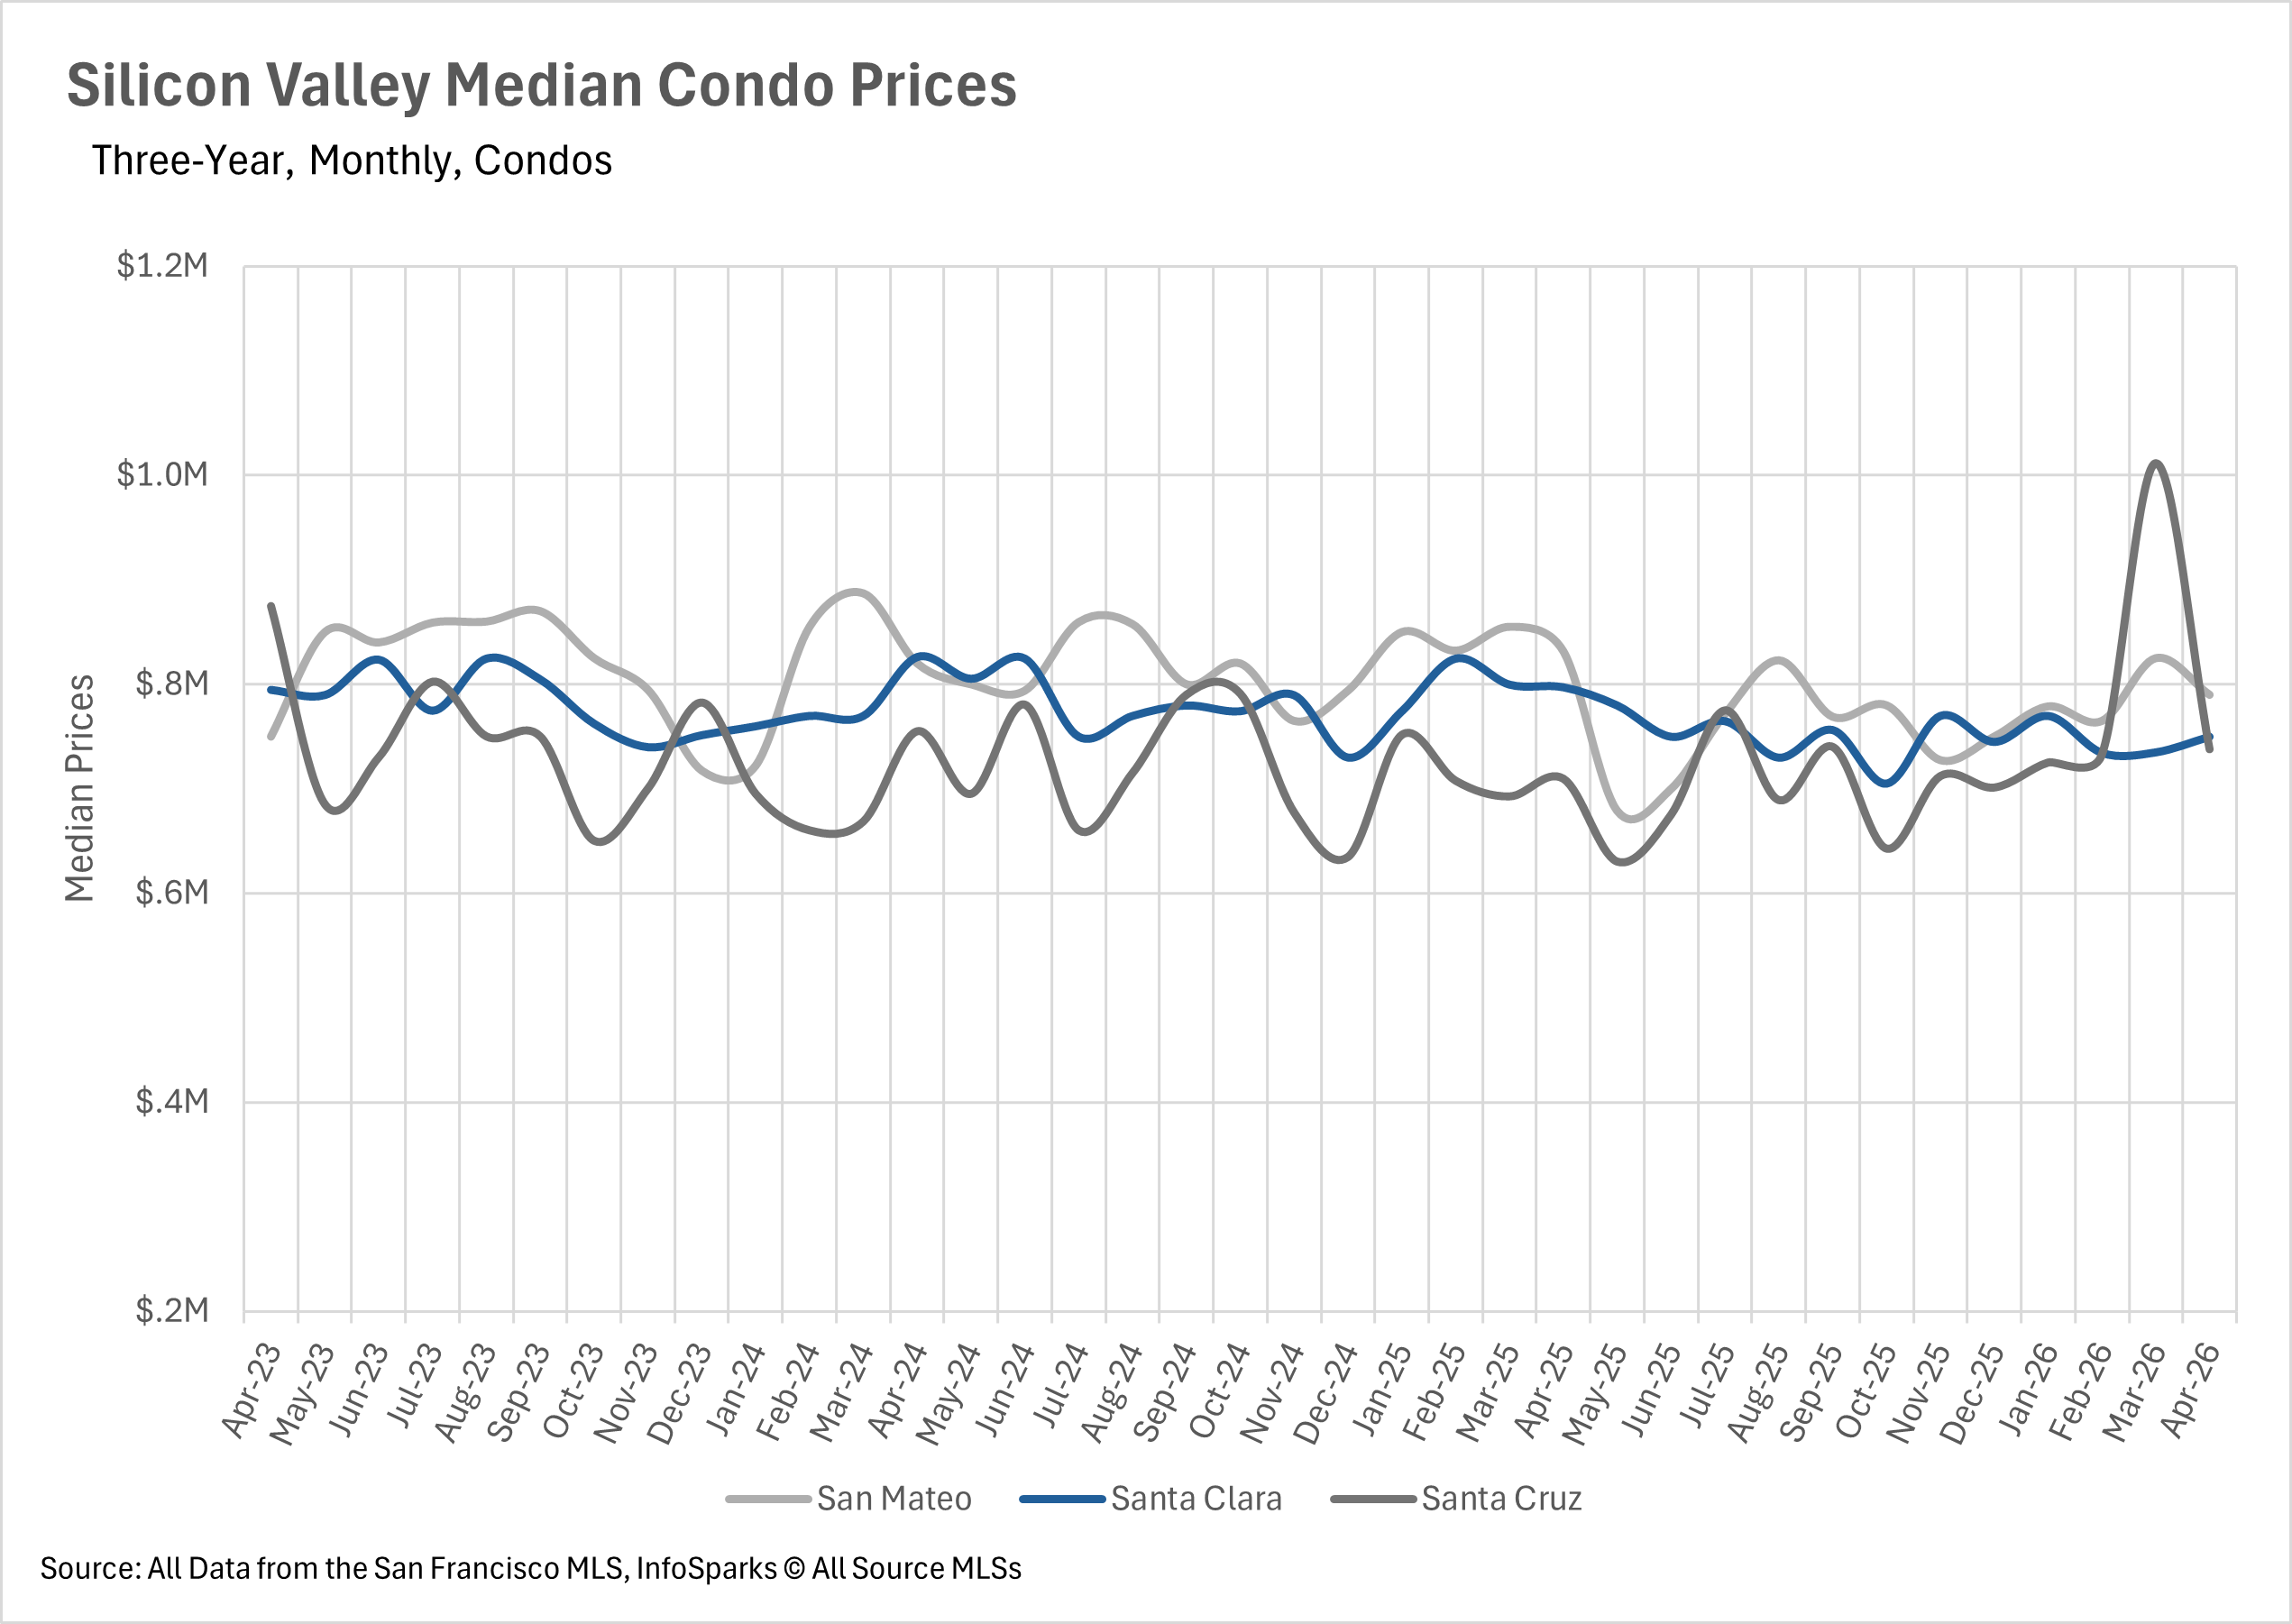
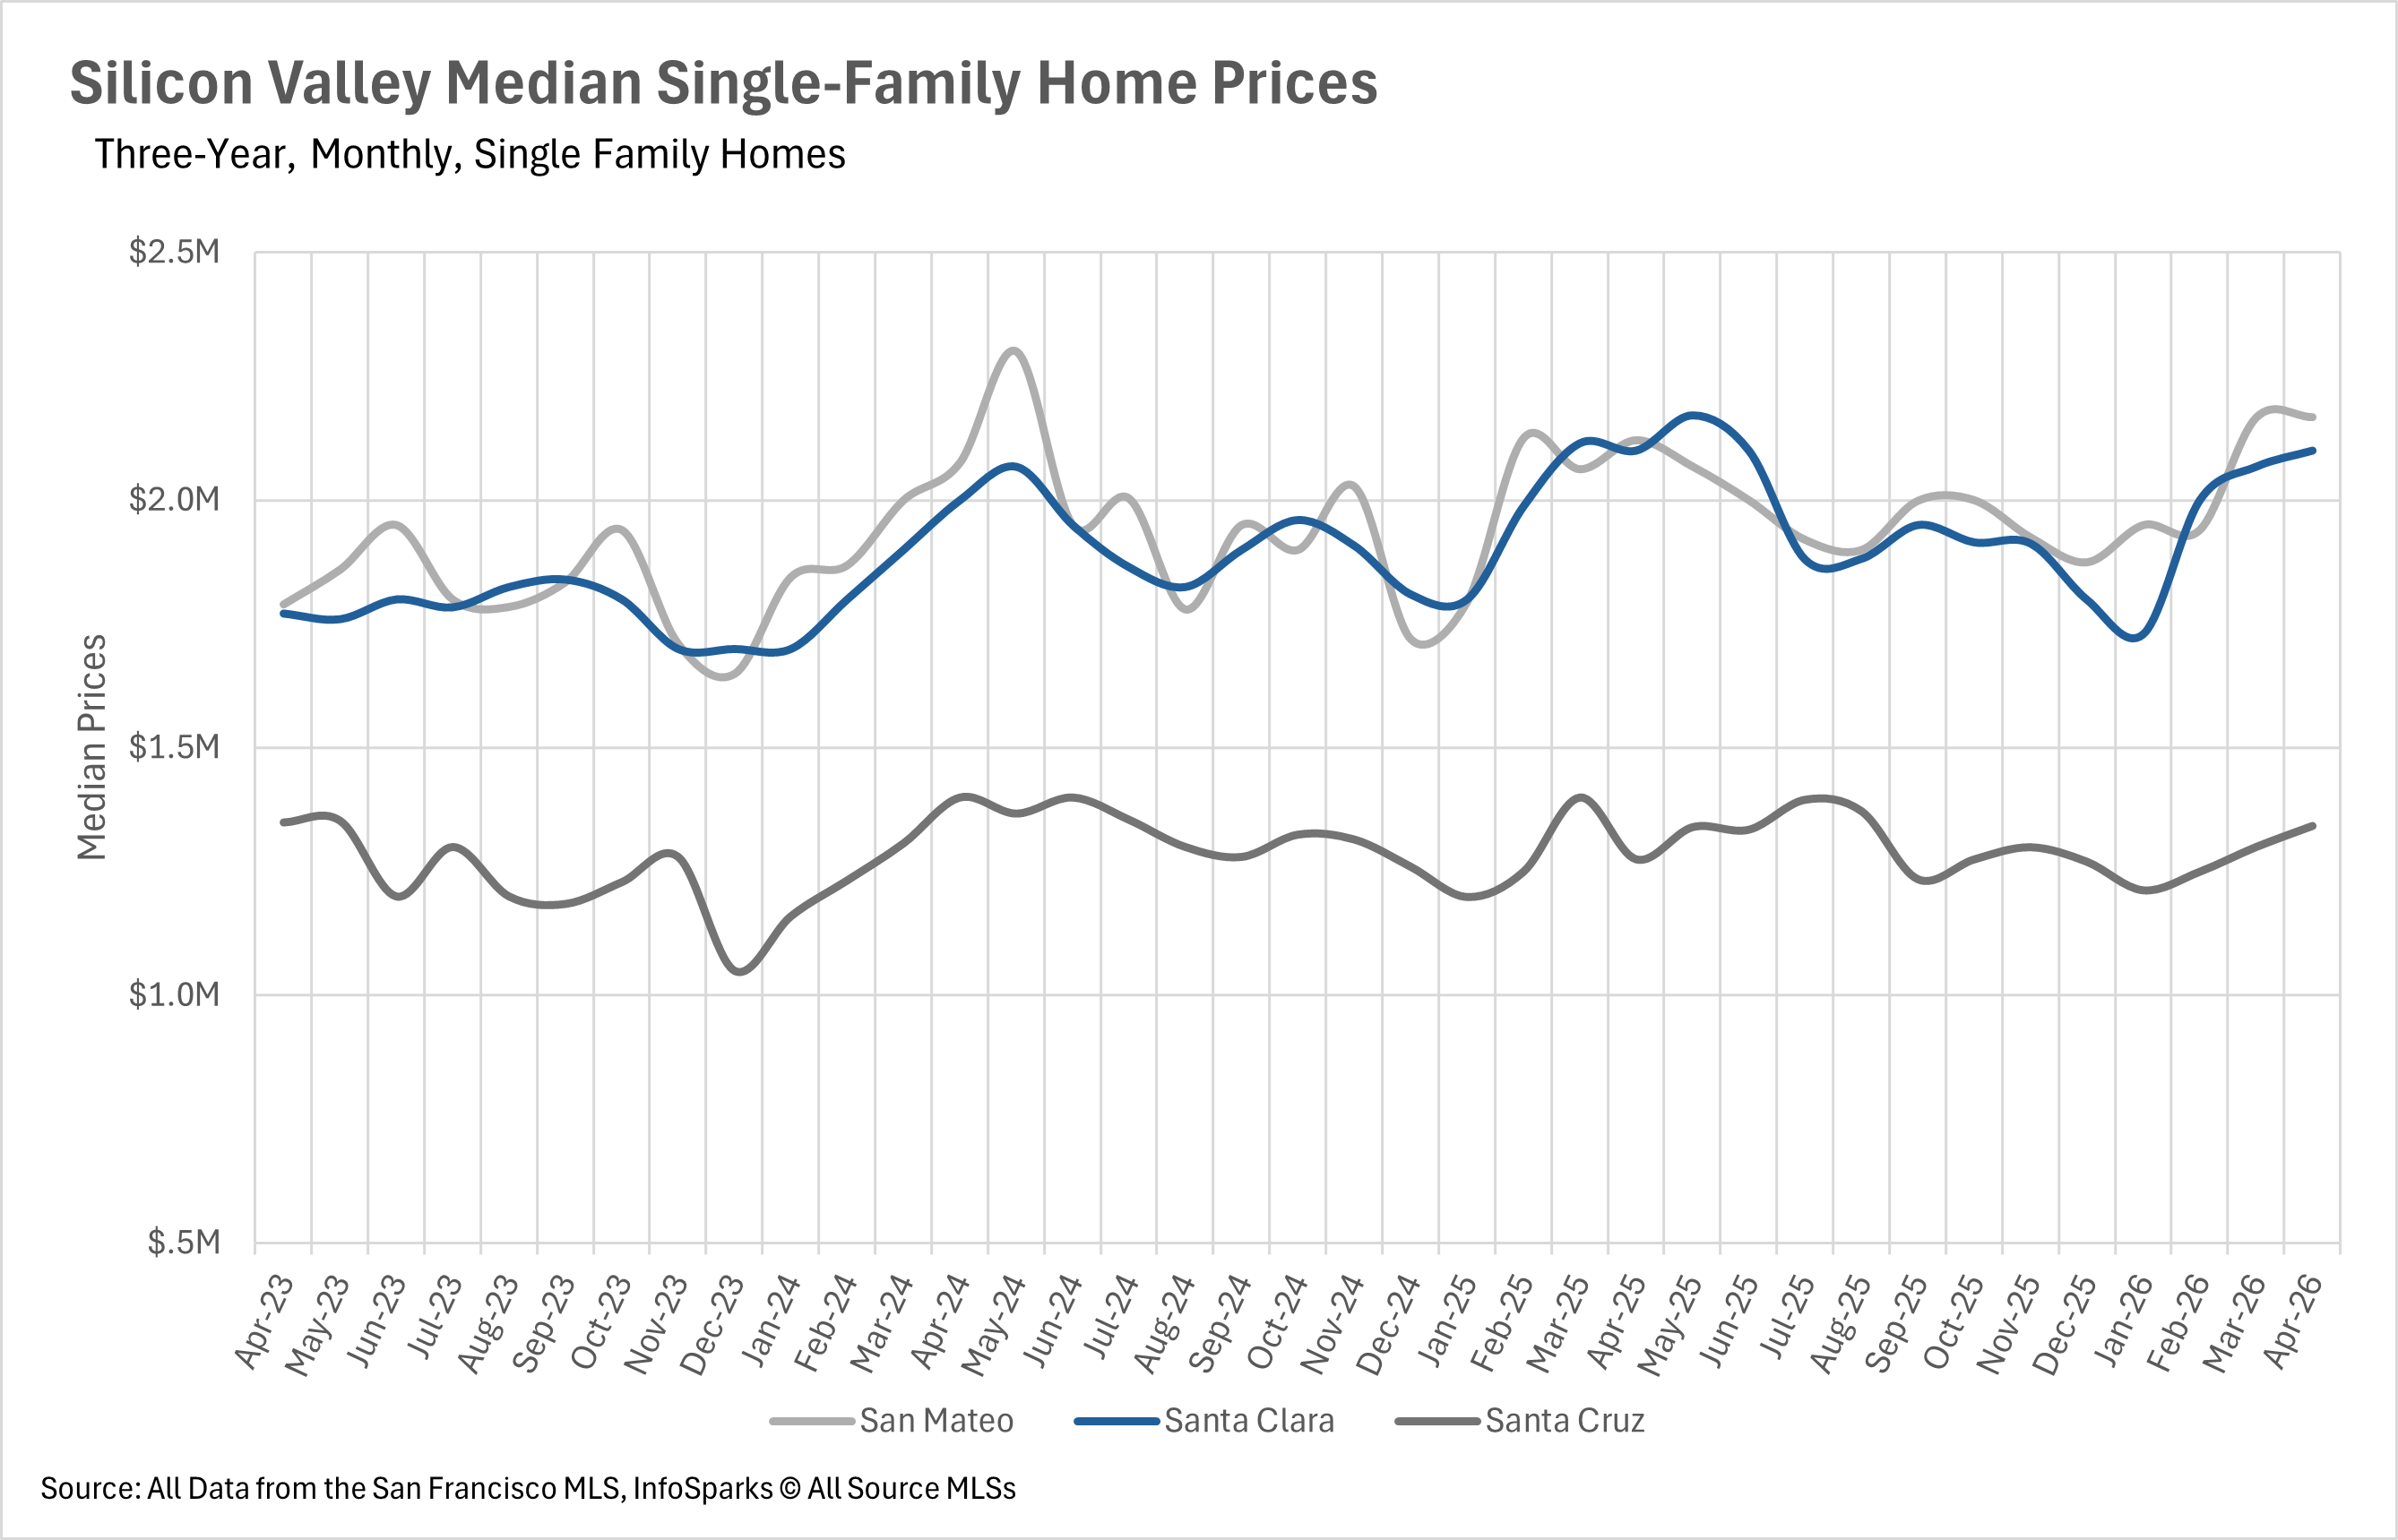
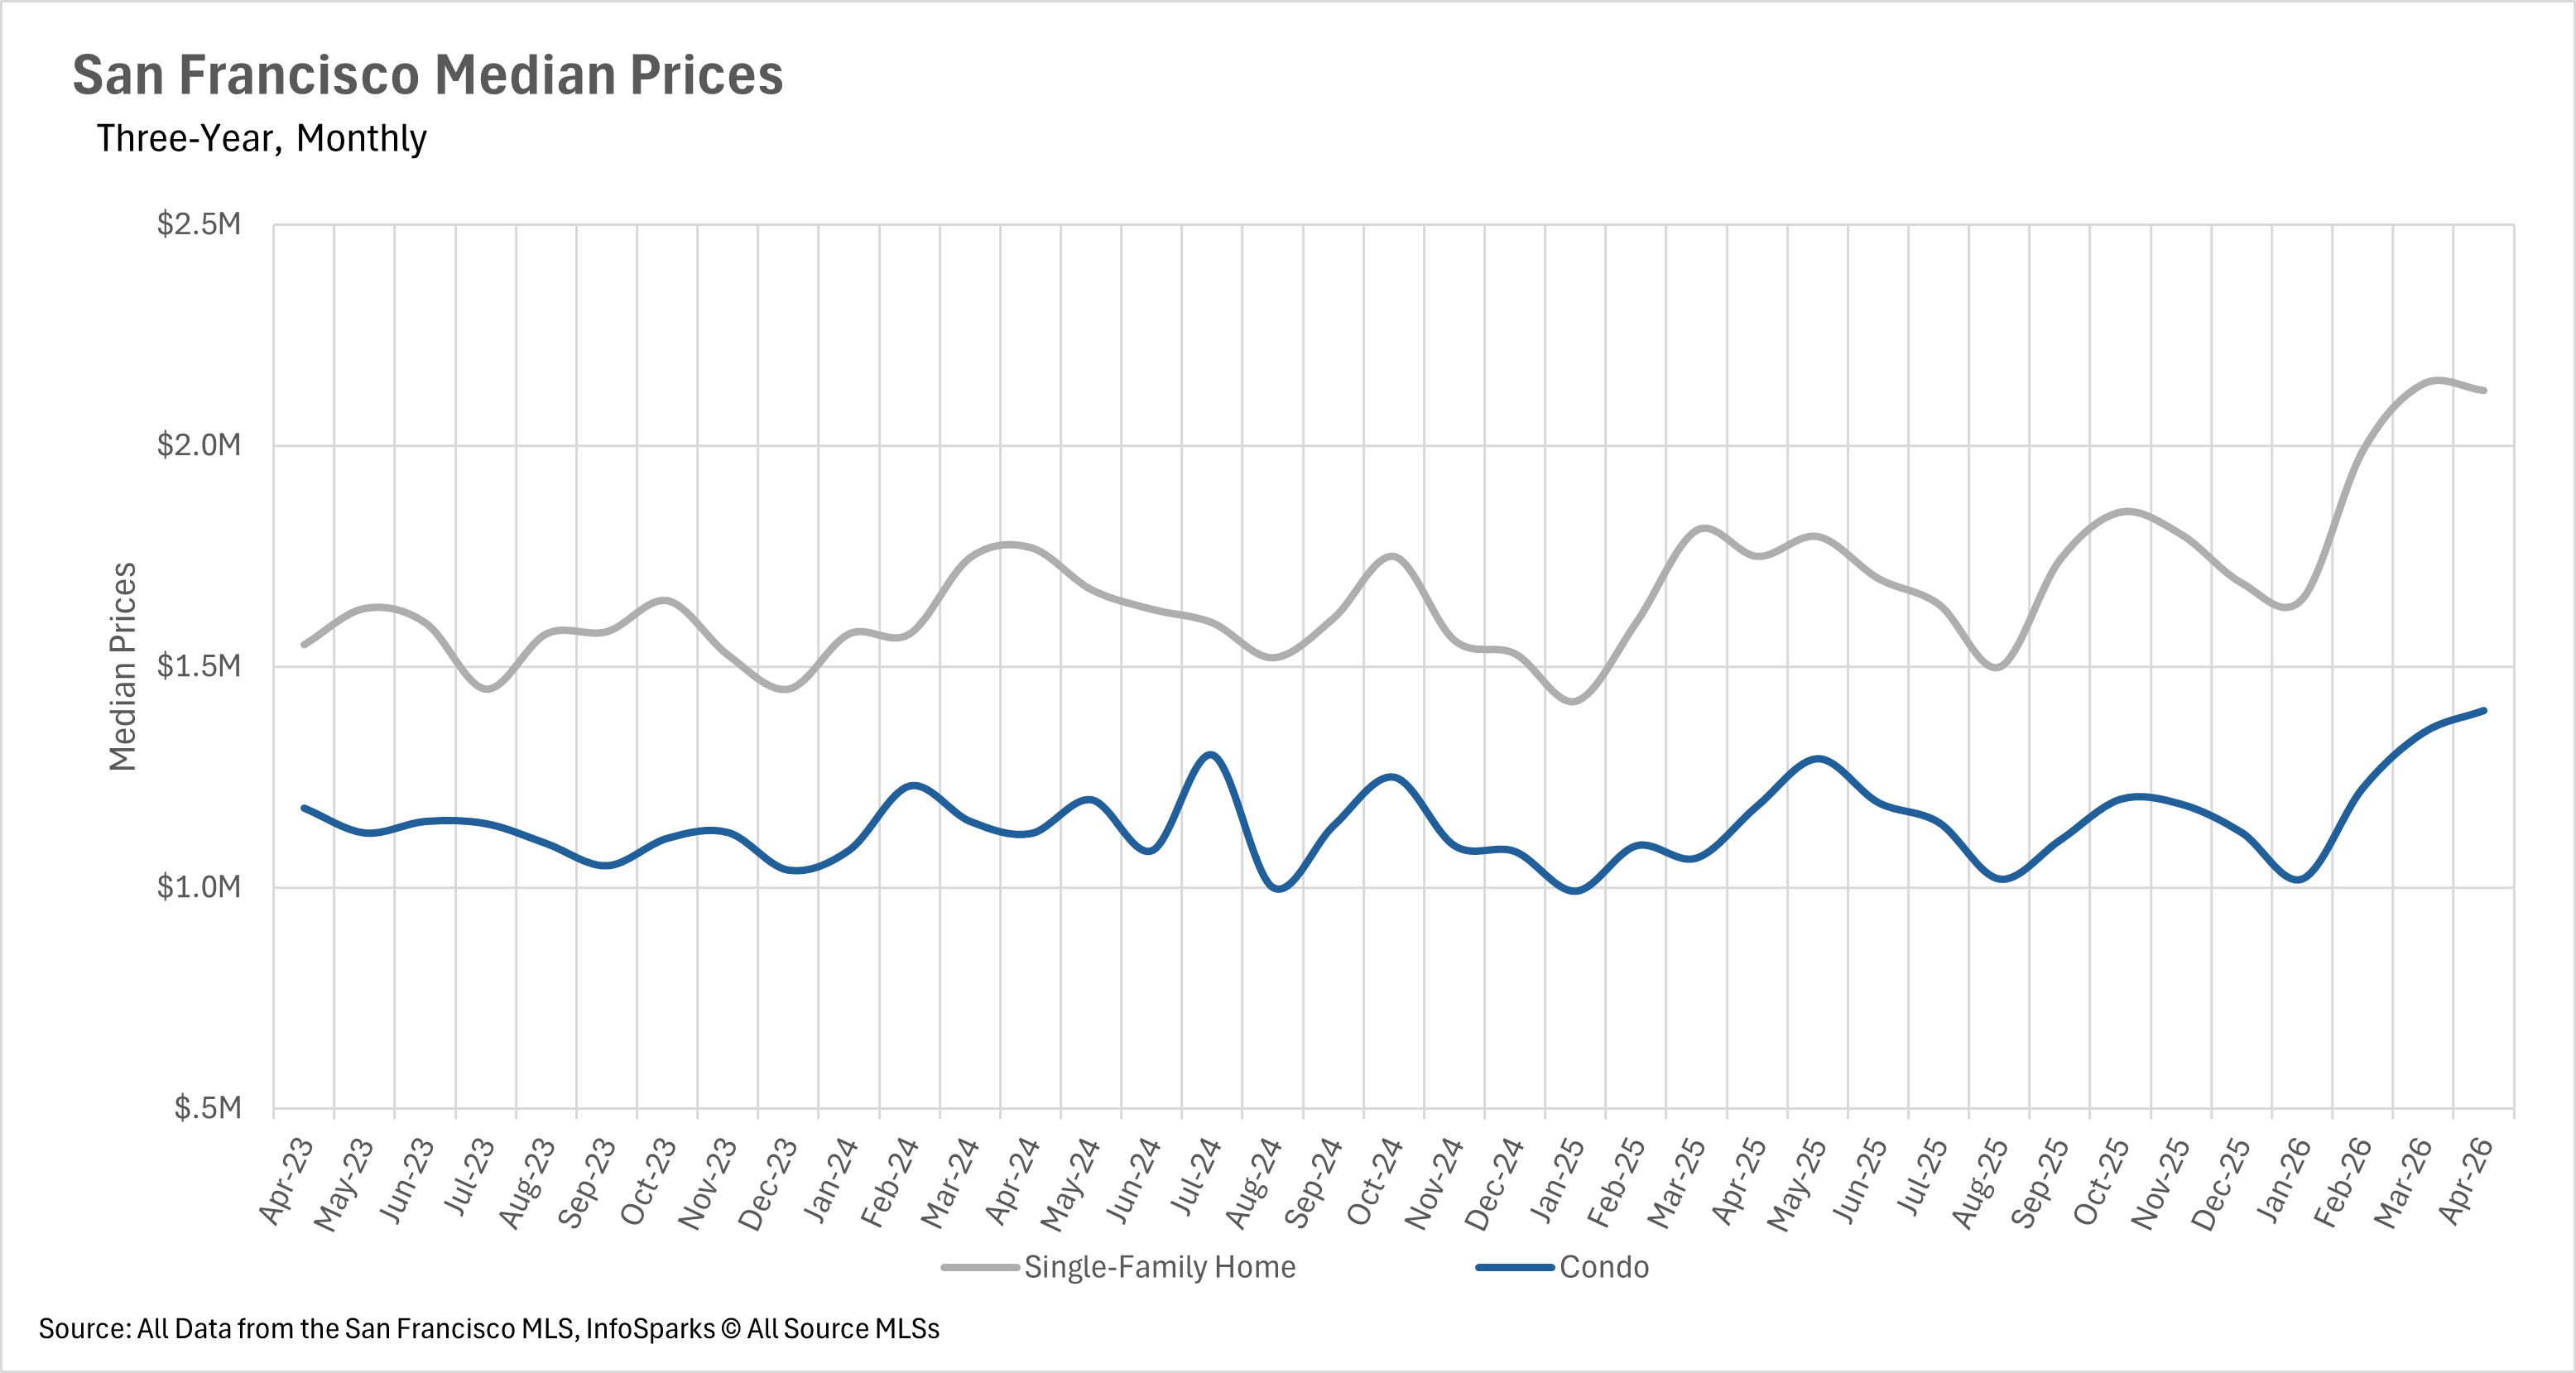
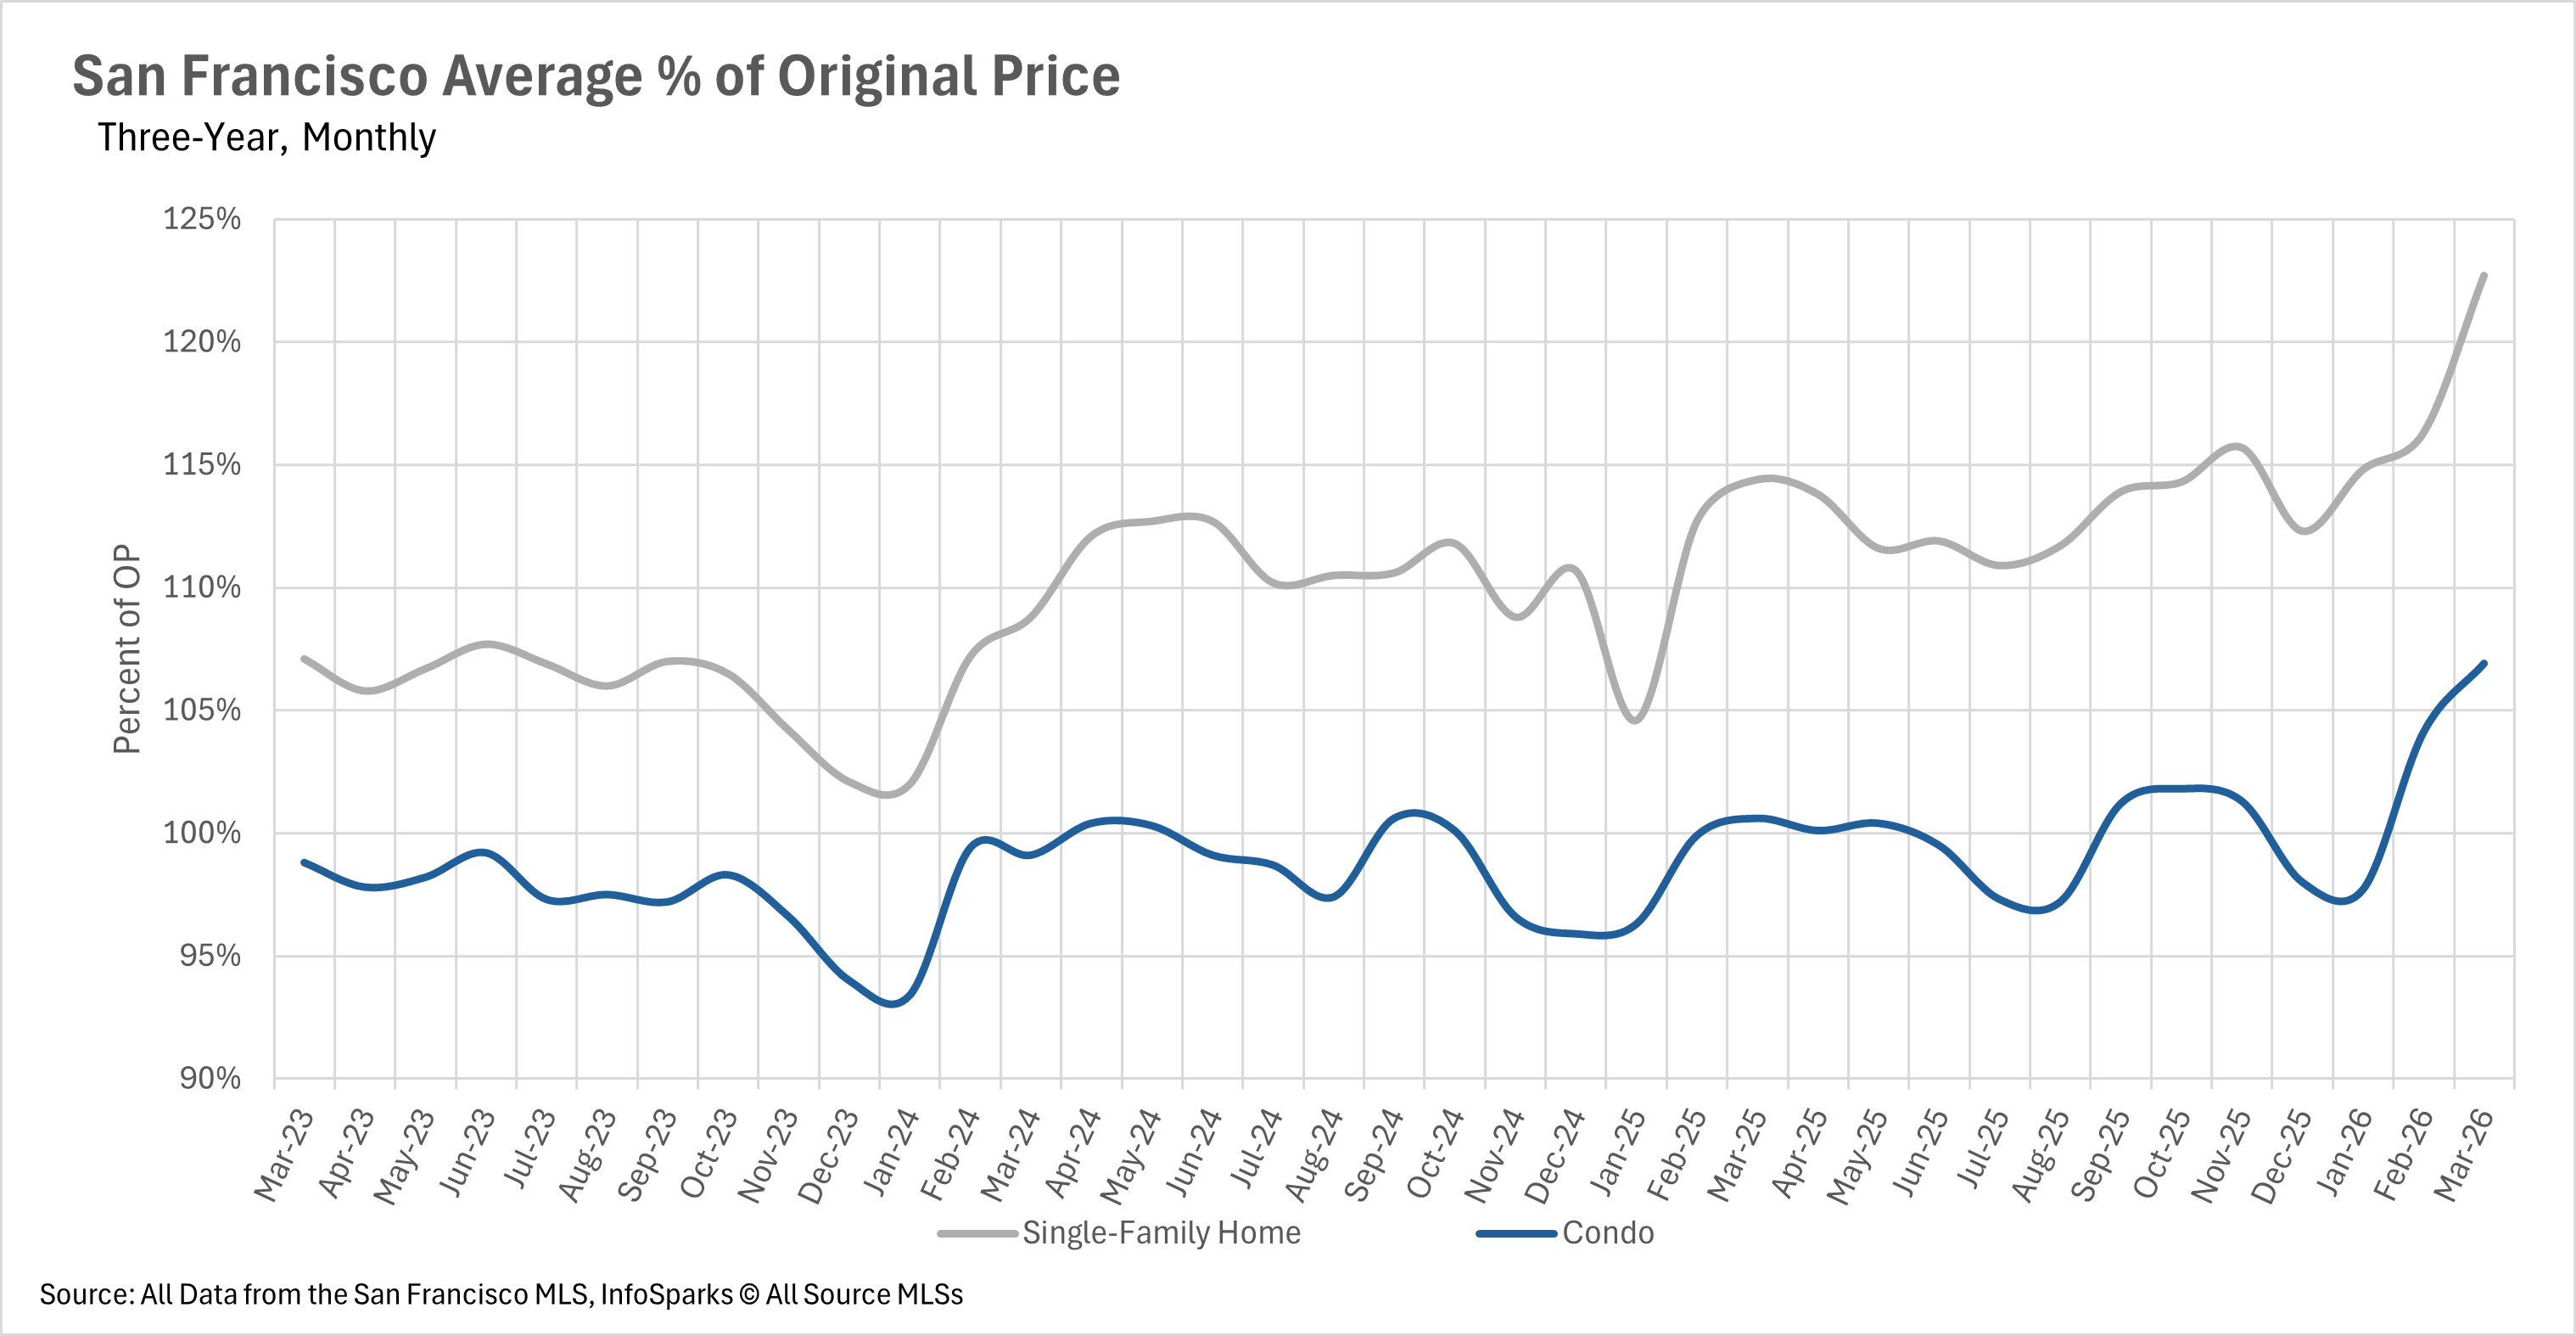
April brought another month of remarkable price appreciation to San Francisco, with single-family homes climbing 21.43% year-over-year to a median sale price of $2,125,000 and condos surging 18.14% to $1,400,000. These double-digit gains have become the norm in San Francisco, where competition for homes remains at a fever pitch. Across Silicon Valley, prices moved in a positive direction as well, with San Mateo County single-family homes up 2.19% to $2,167,500 and Santa Cruz County posting a 5.29% gain to $1,342,500, while Santa Clara County held perfectly steady at $2,100,000.
 
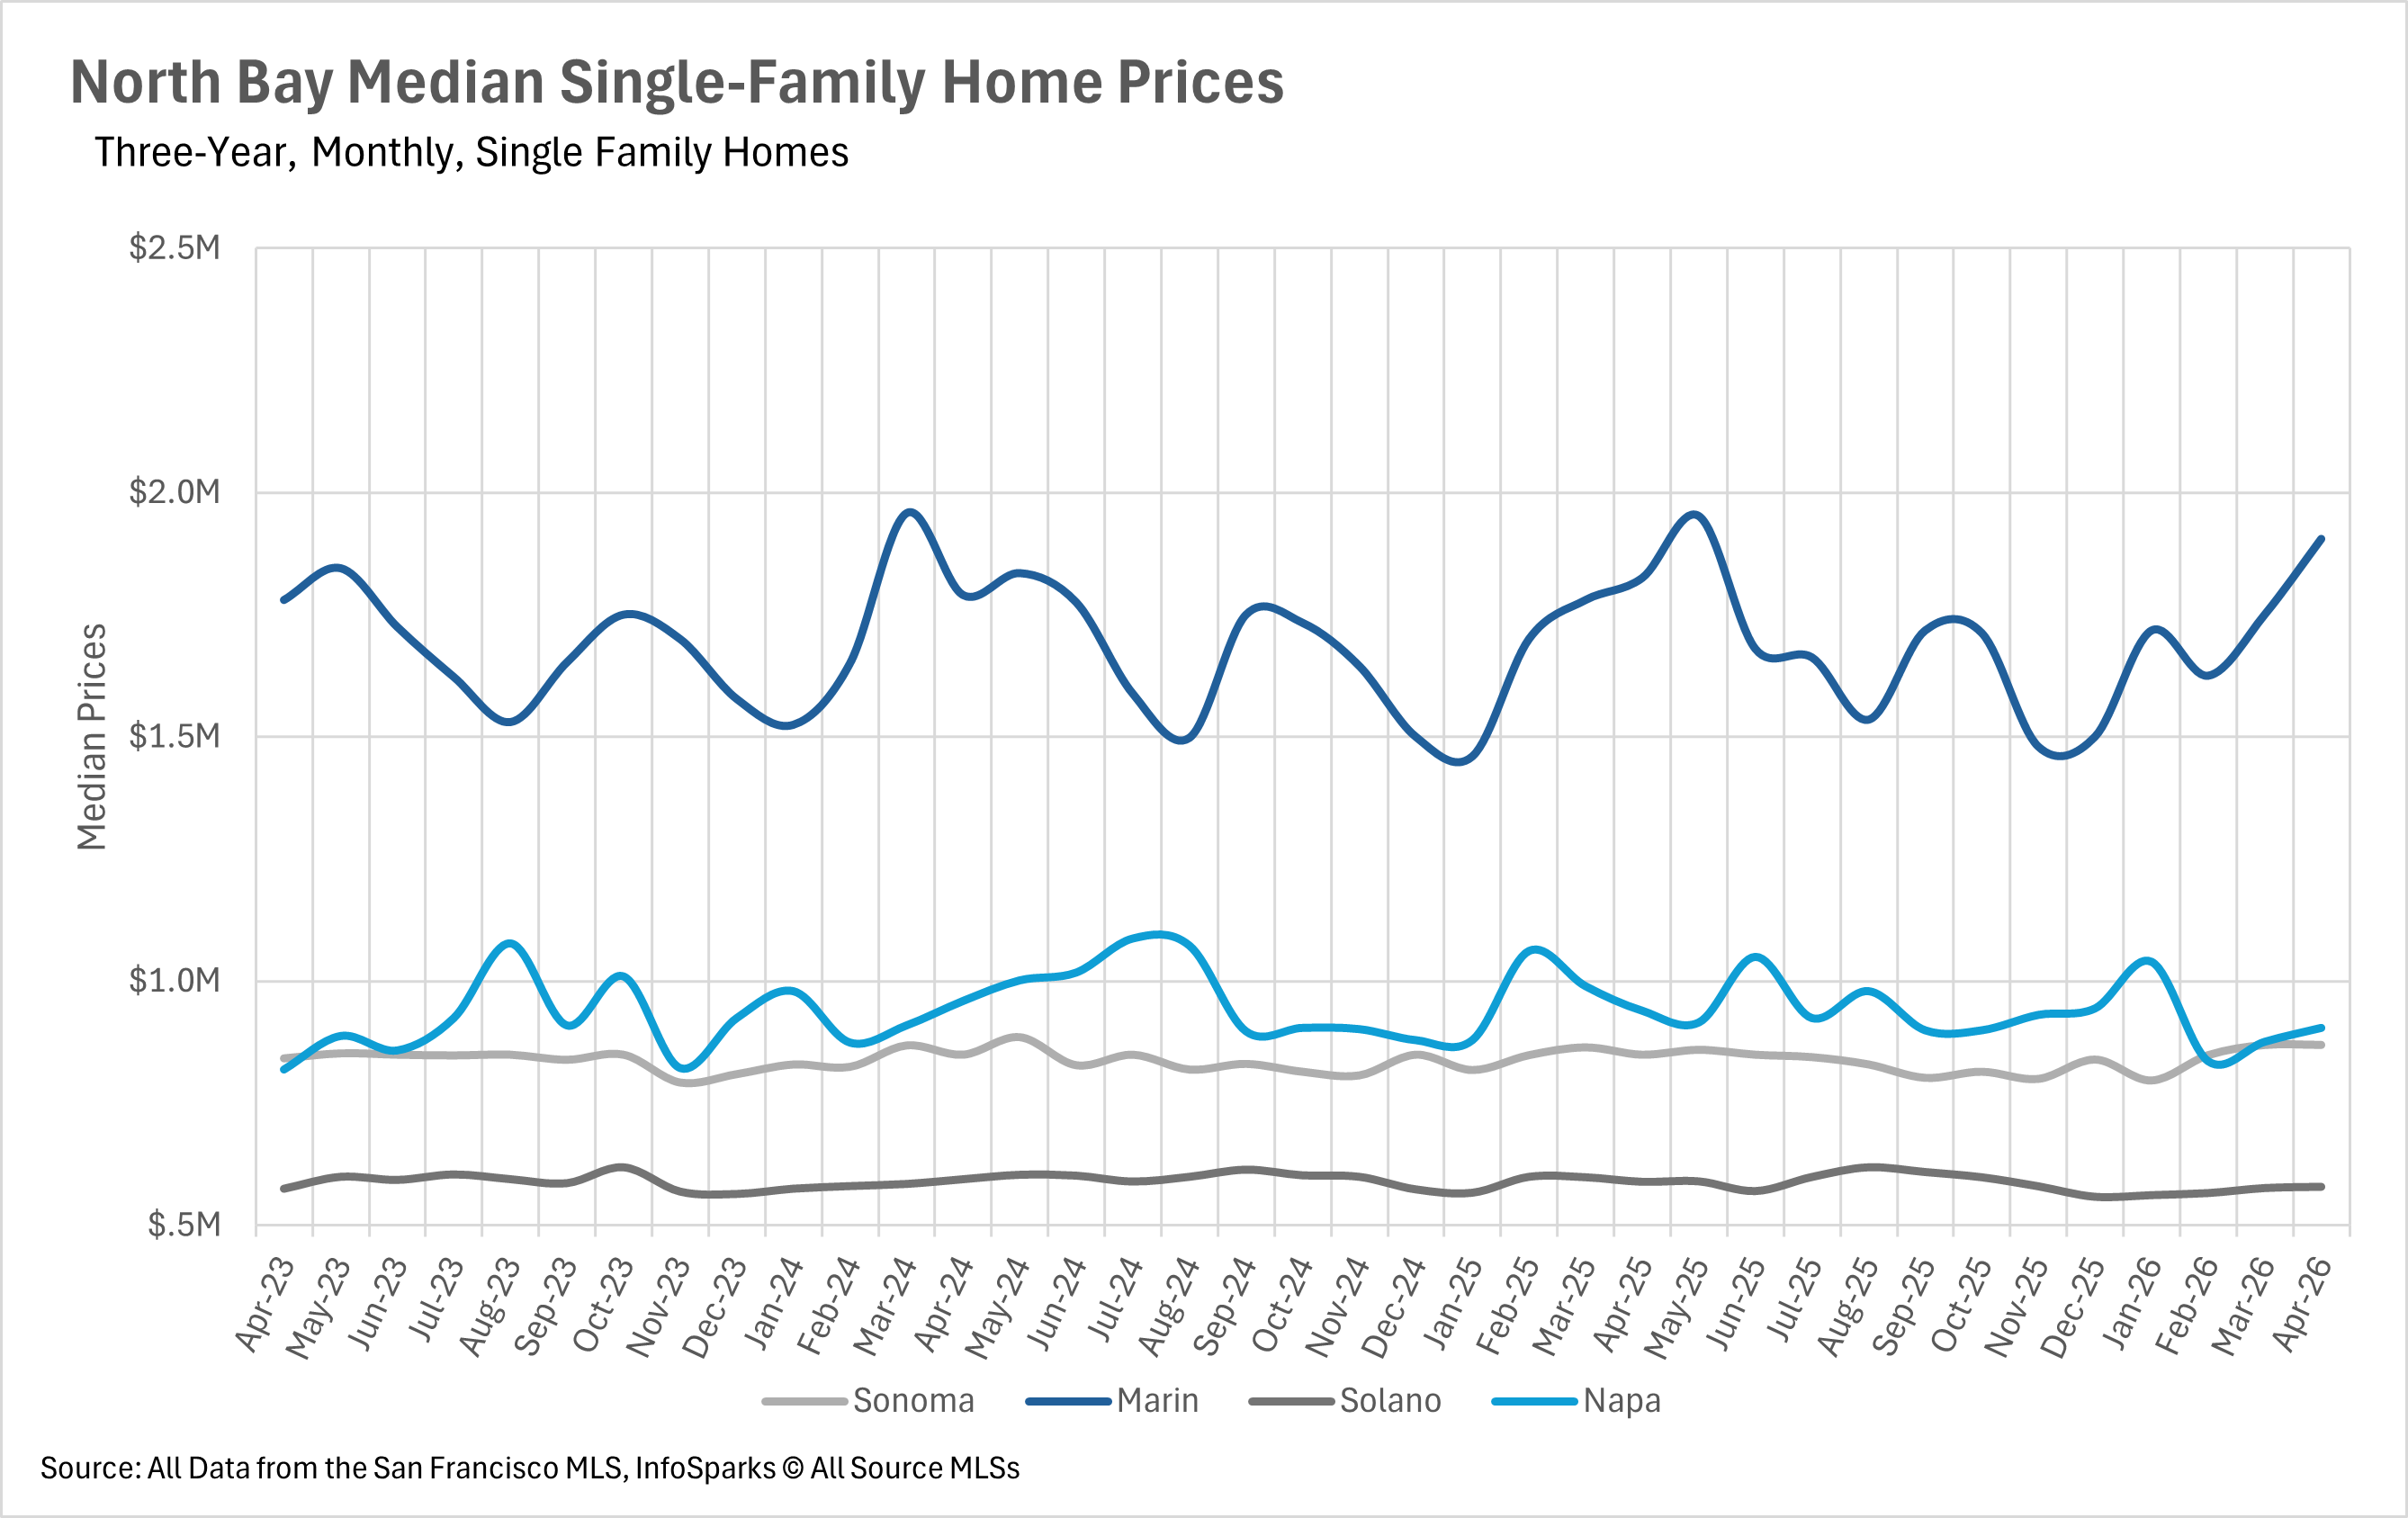
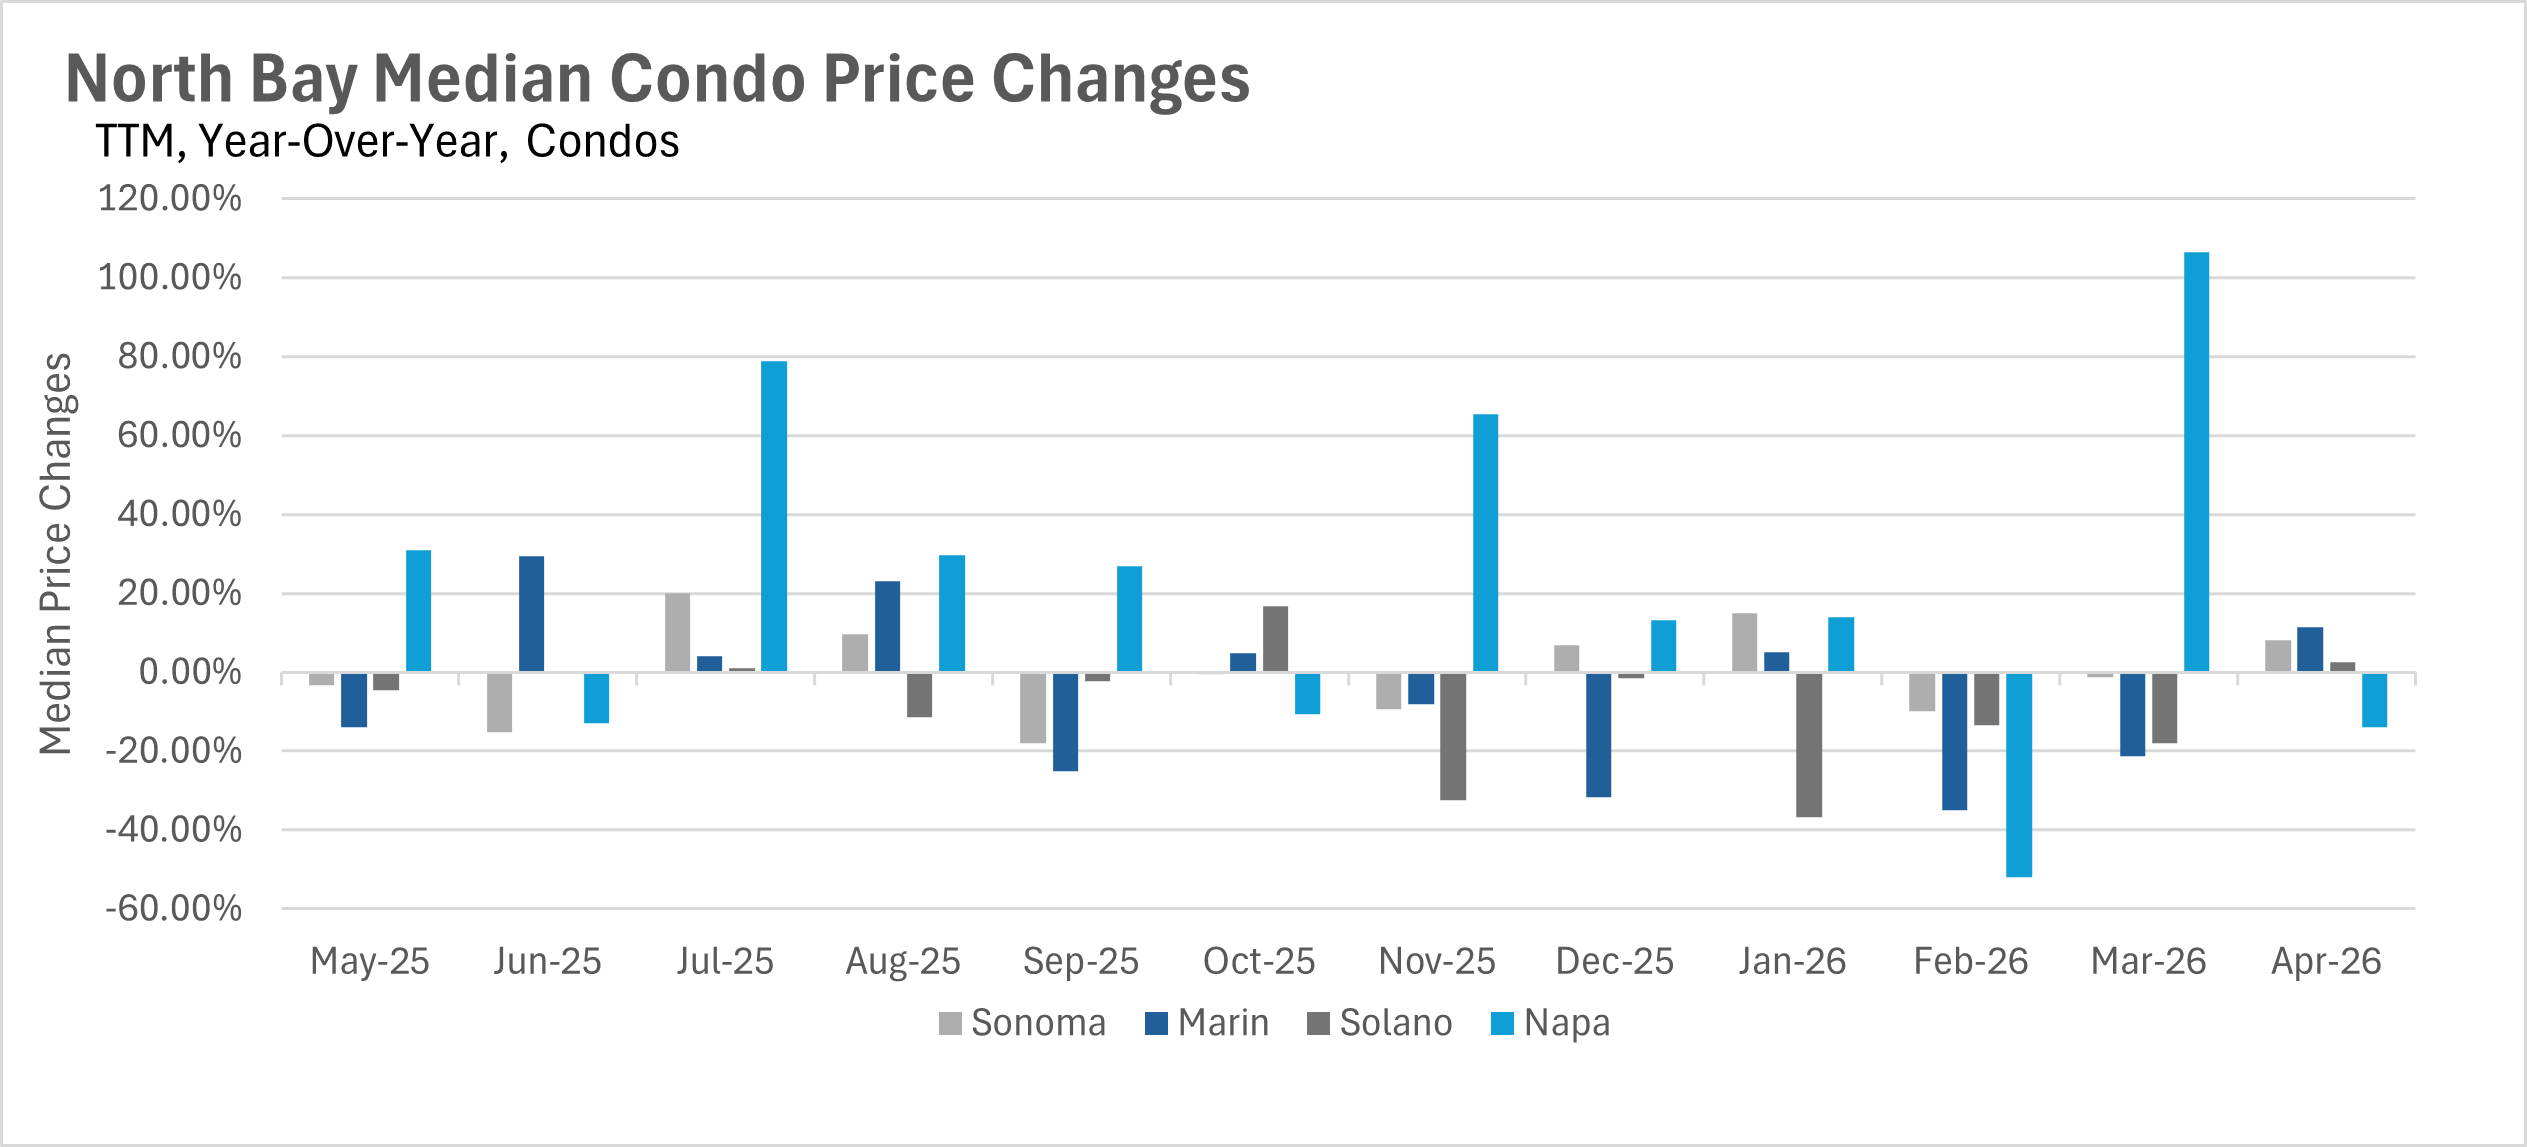
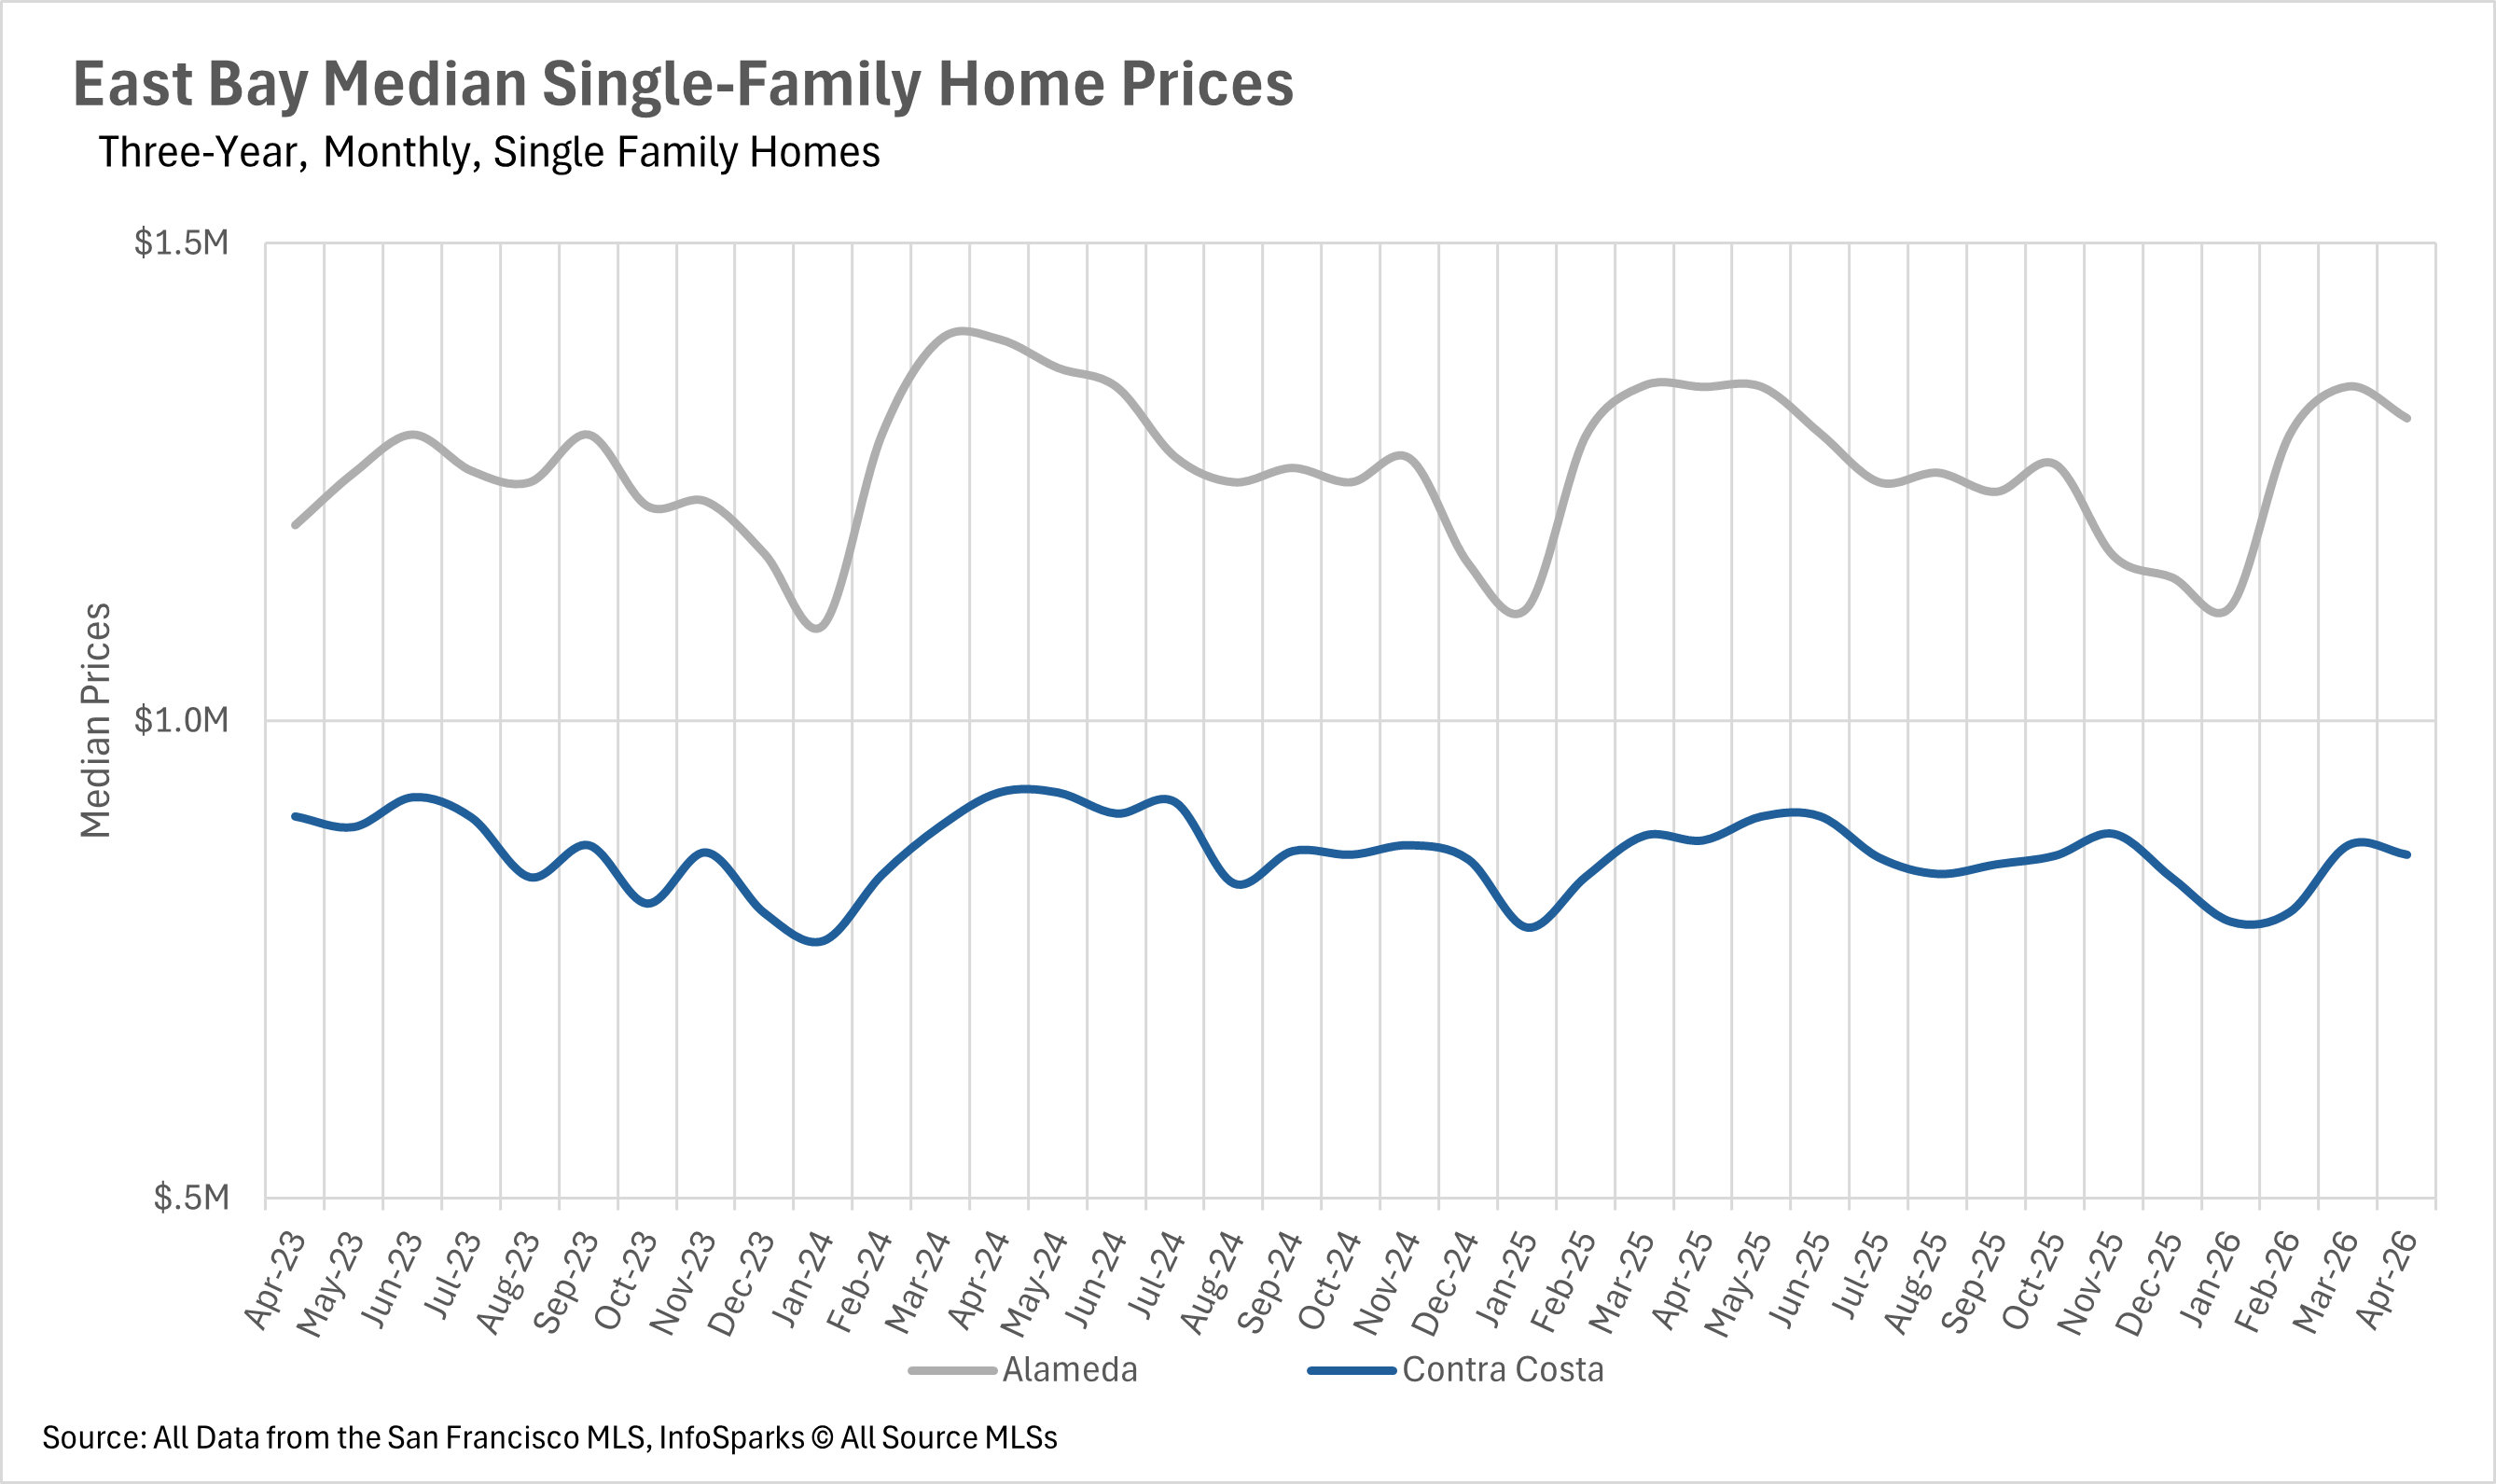
The North Bay saw encouraging results in Marin and Sonoma Counties, with year-over-year gains of 4.38% and 2.35%, respectively, though Napa and Solano Counties continued to soften. The East Bay experienced modest single-family price declines in both counties, with Alameda County down 2.44% and Contra Costa County down 1.71%. The condo market remains a tale of two worlds, with San Francisco condos commanding premiums of roughly 7% over asking price, while Alameda County condos declined 10.38% and Silicon Valley condos posted declines across the board.
The Bay Area's persistent inventory shortage is defining the spring market
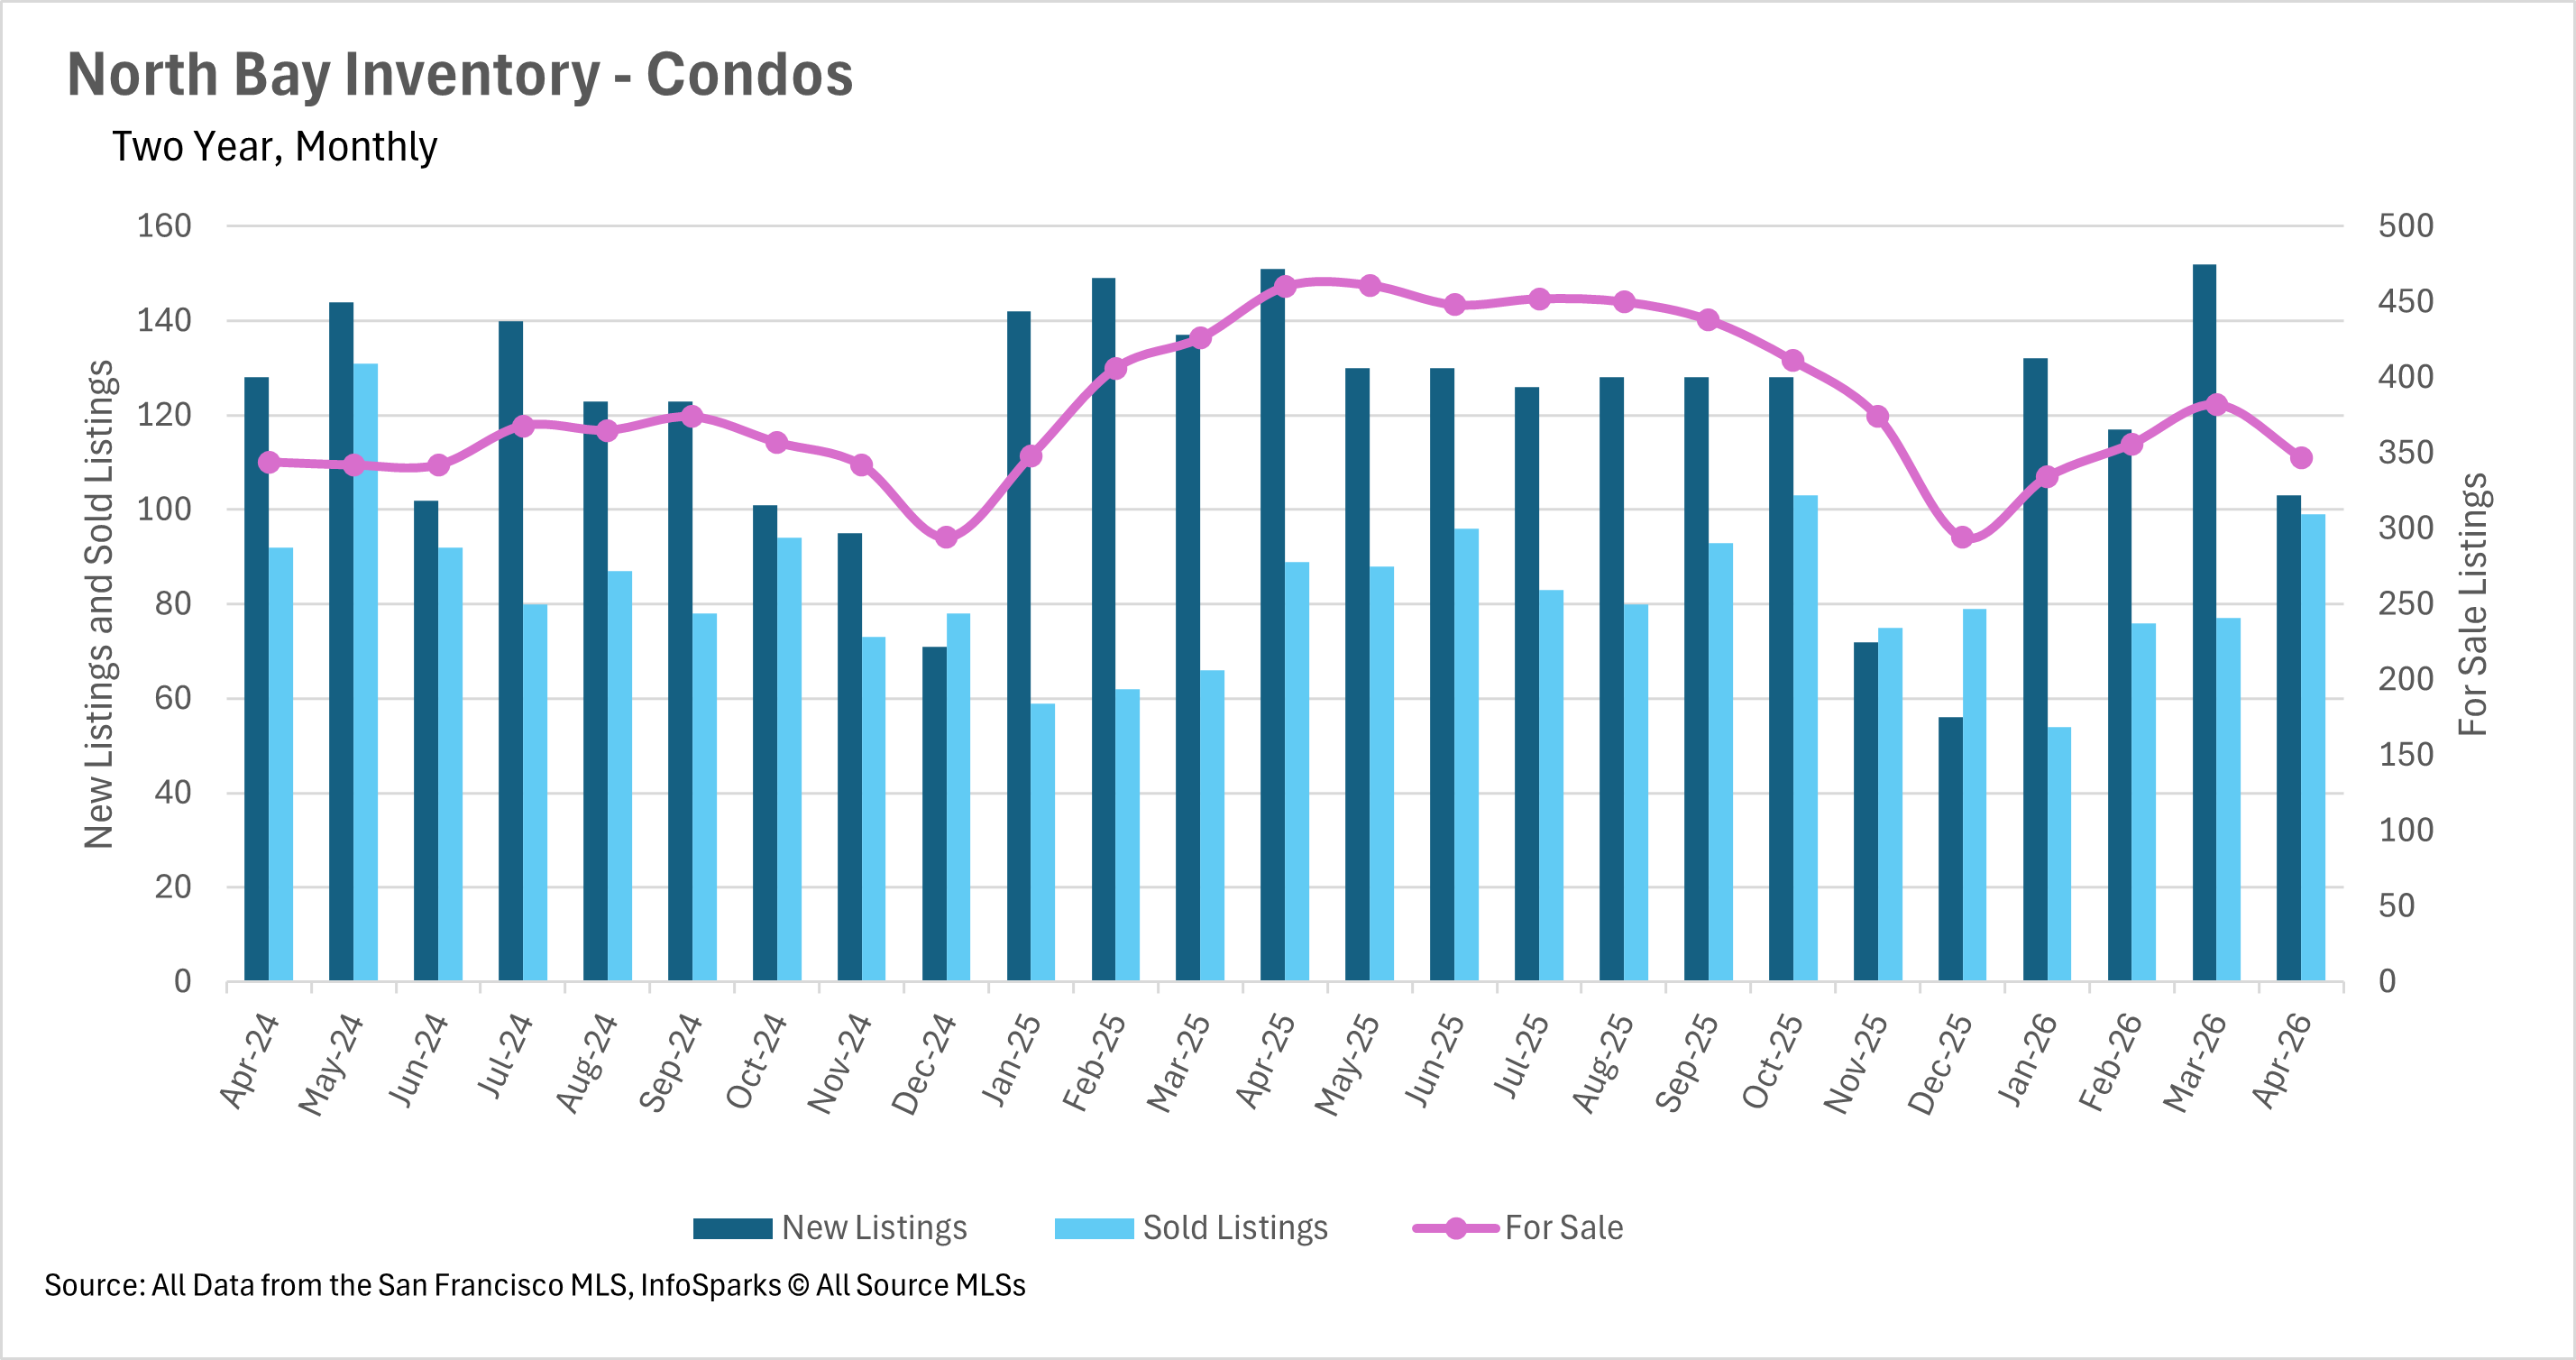
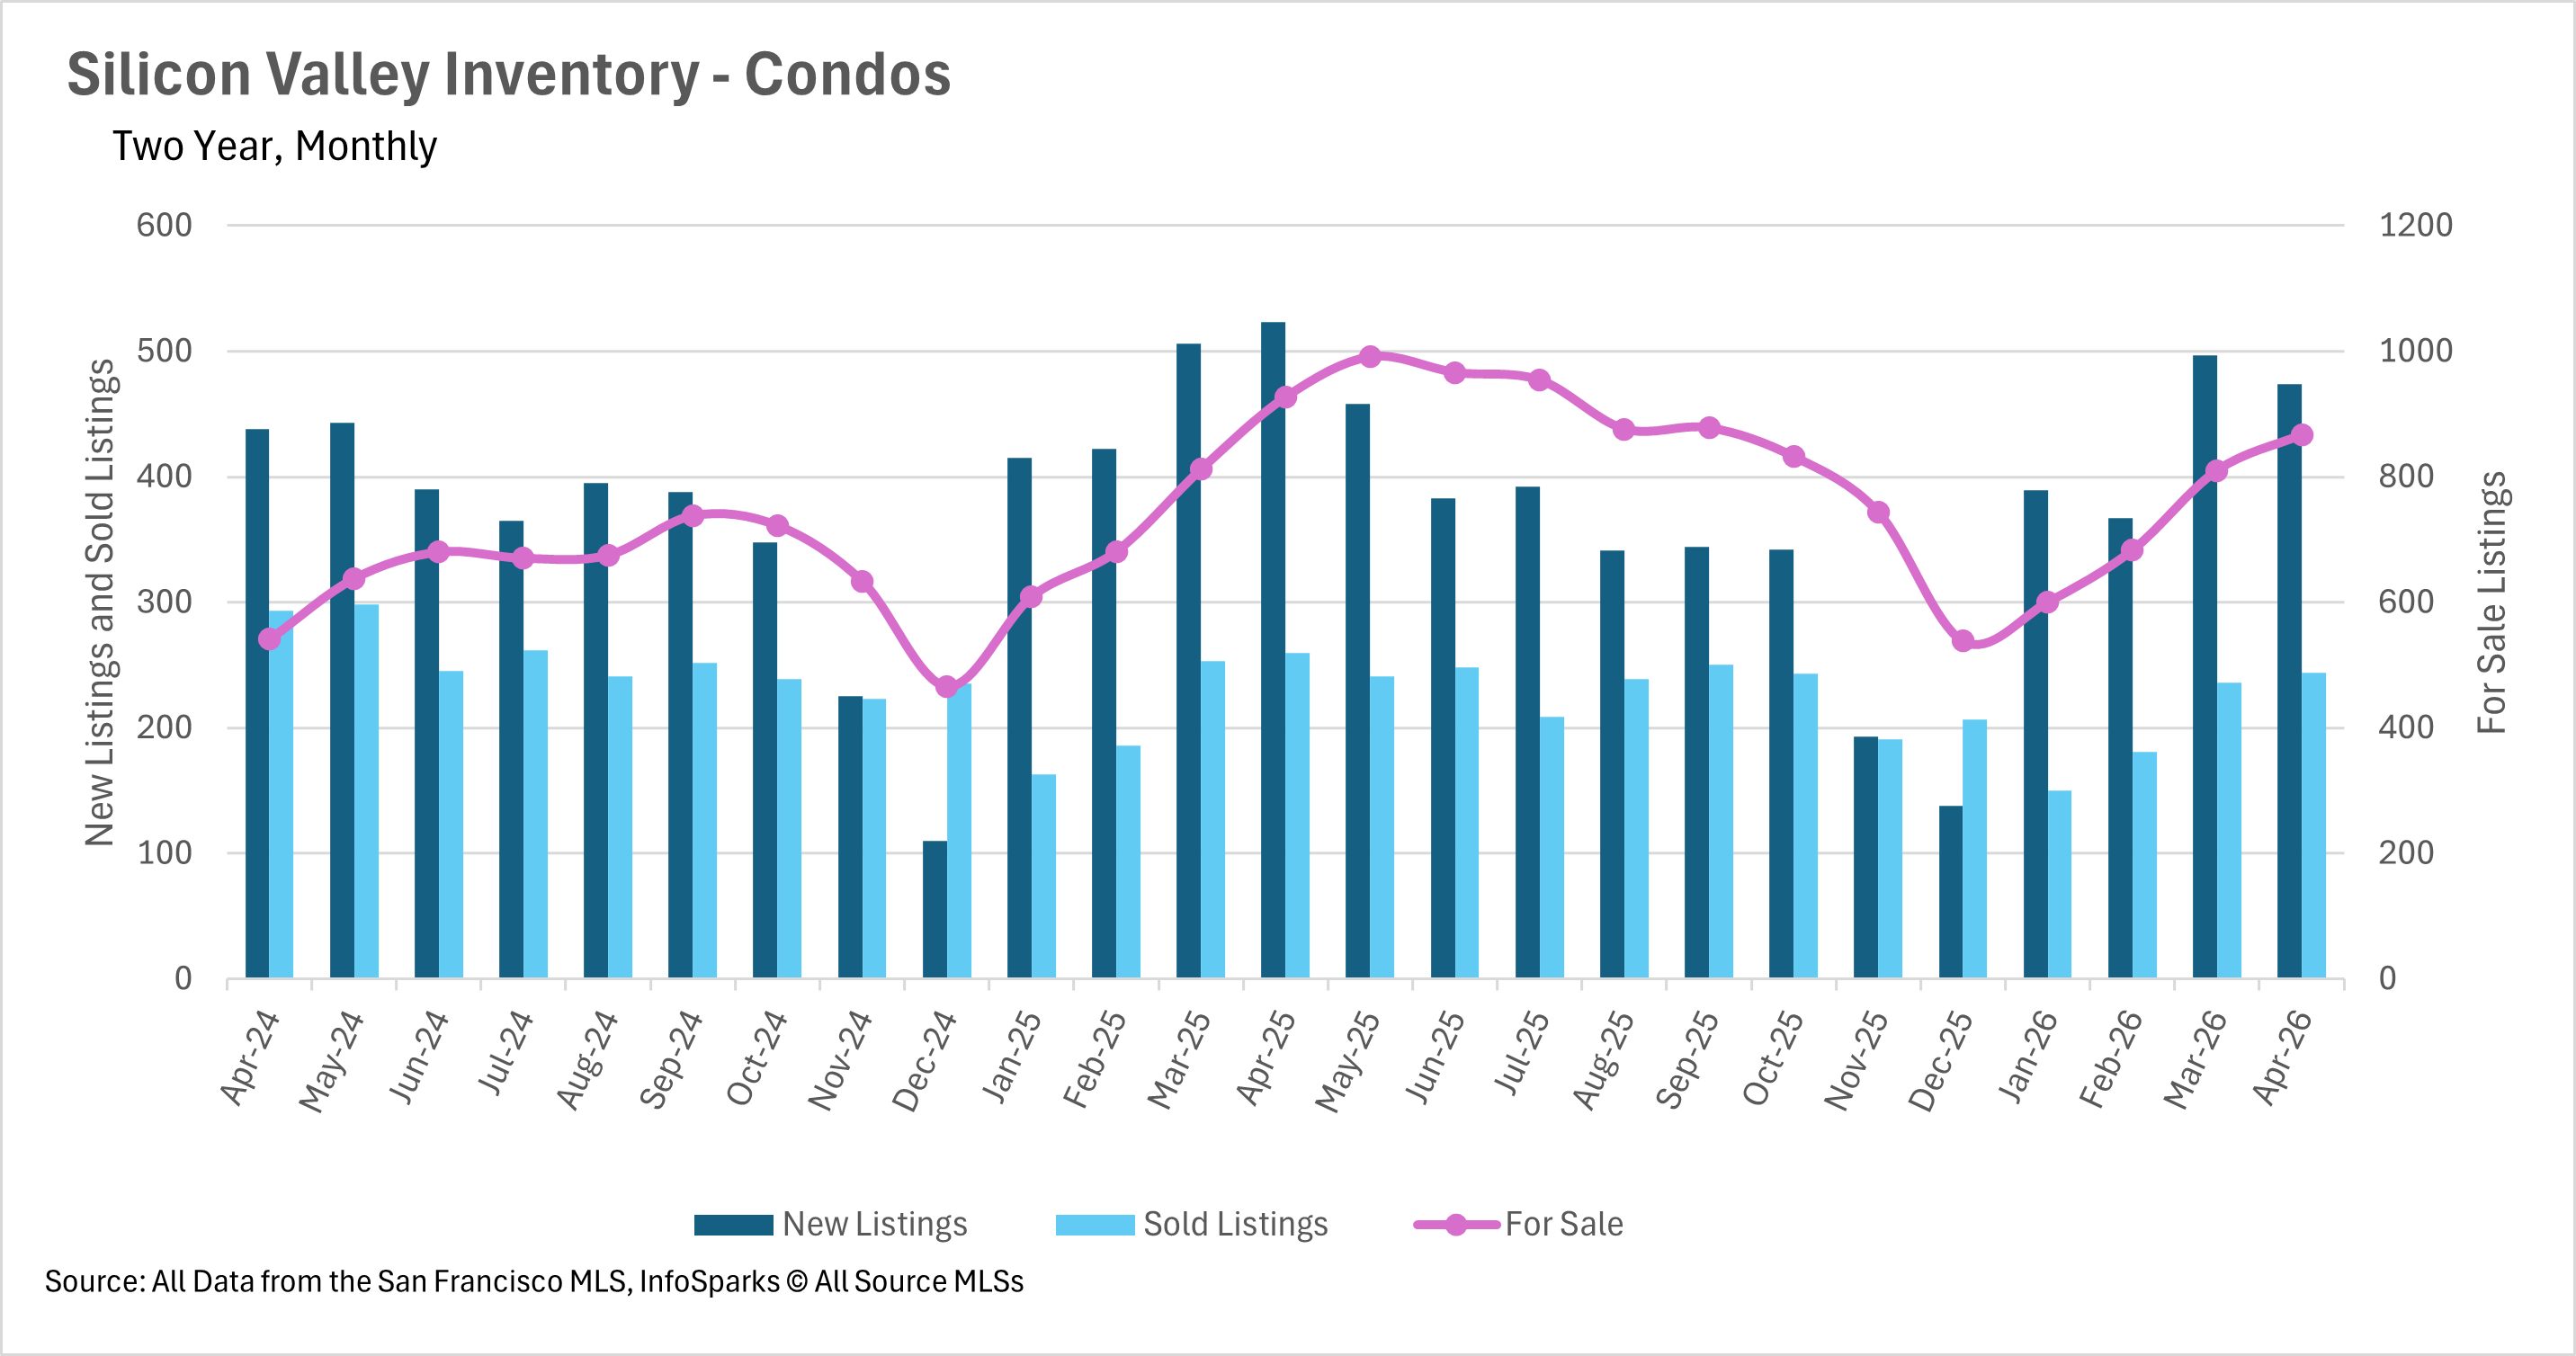
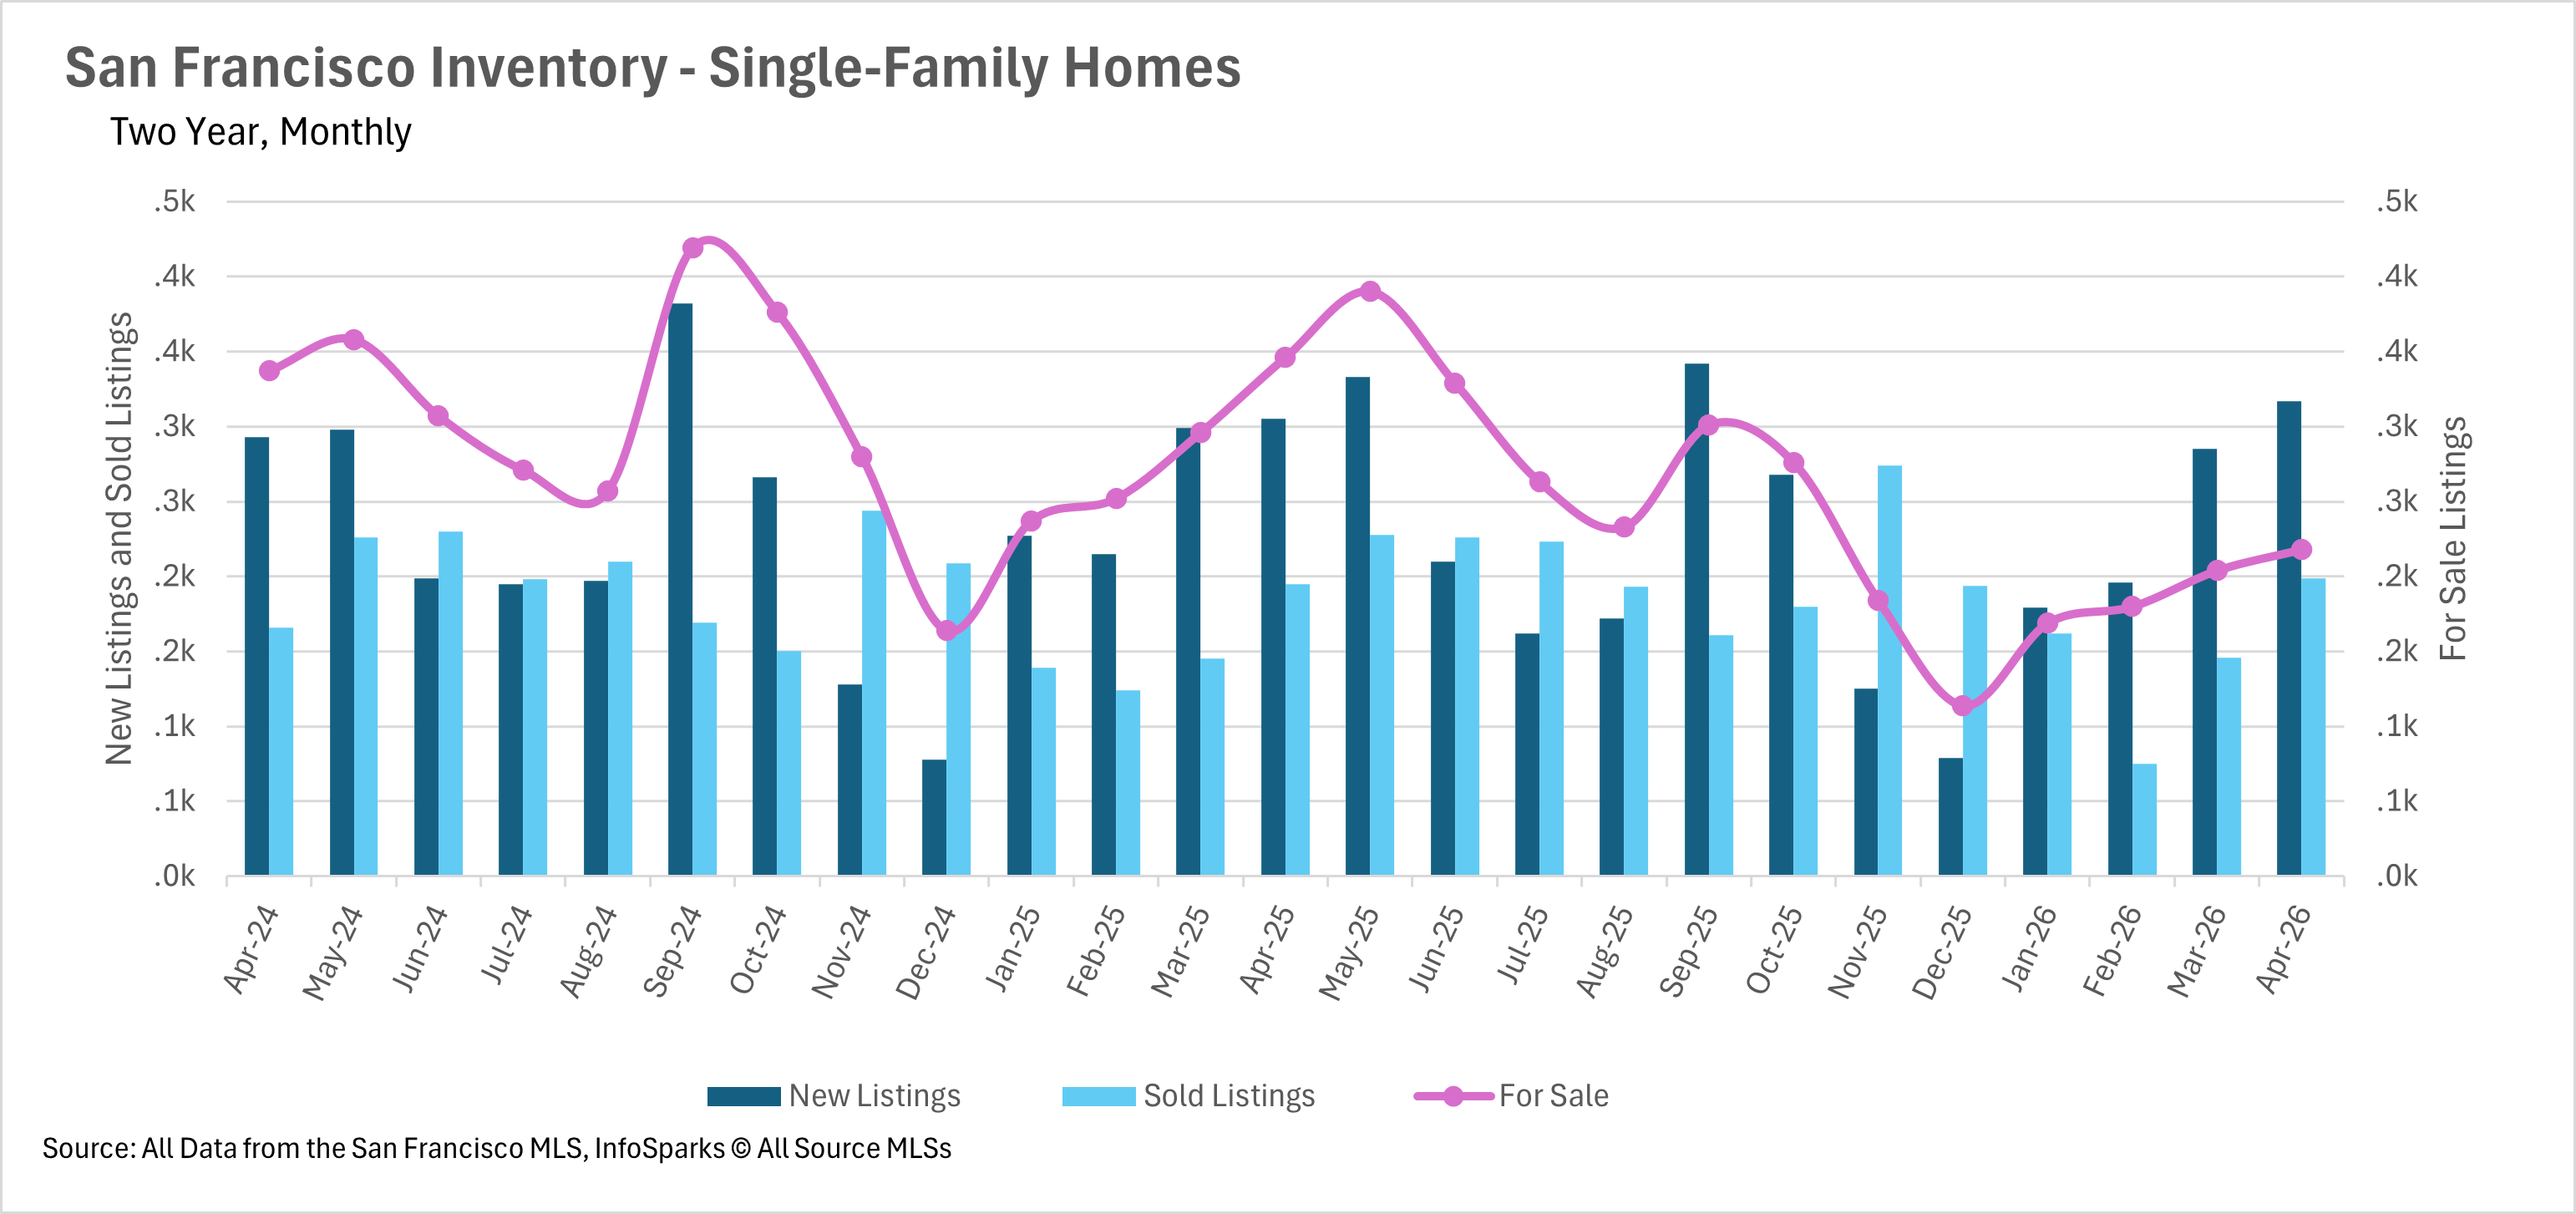
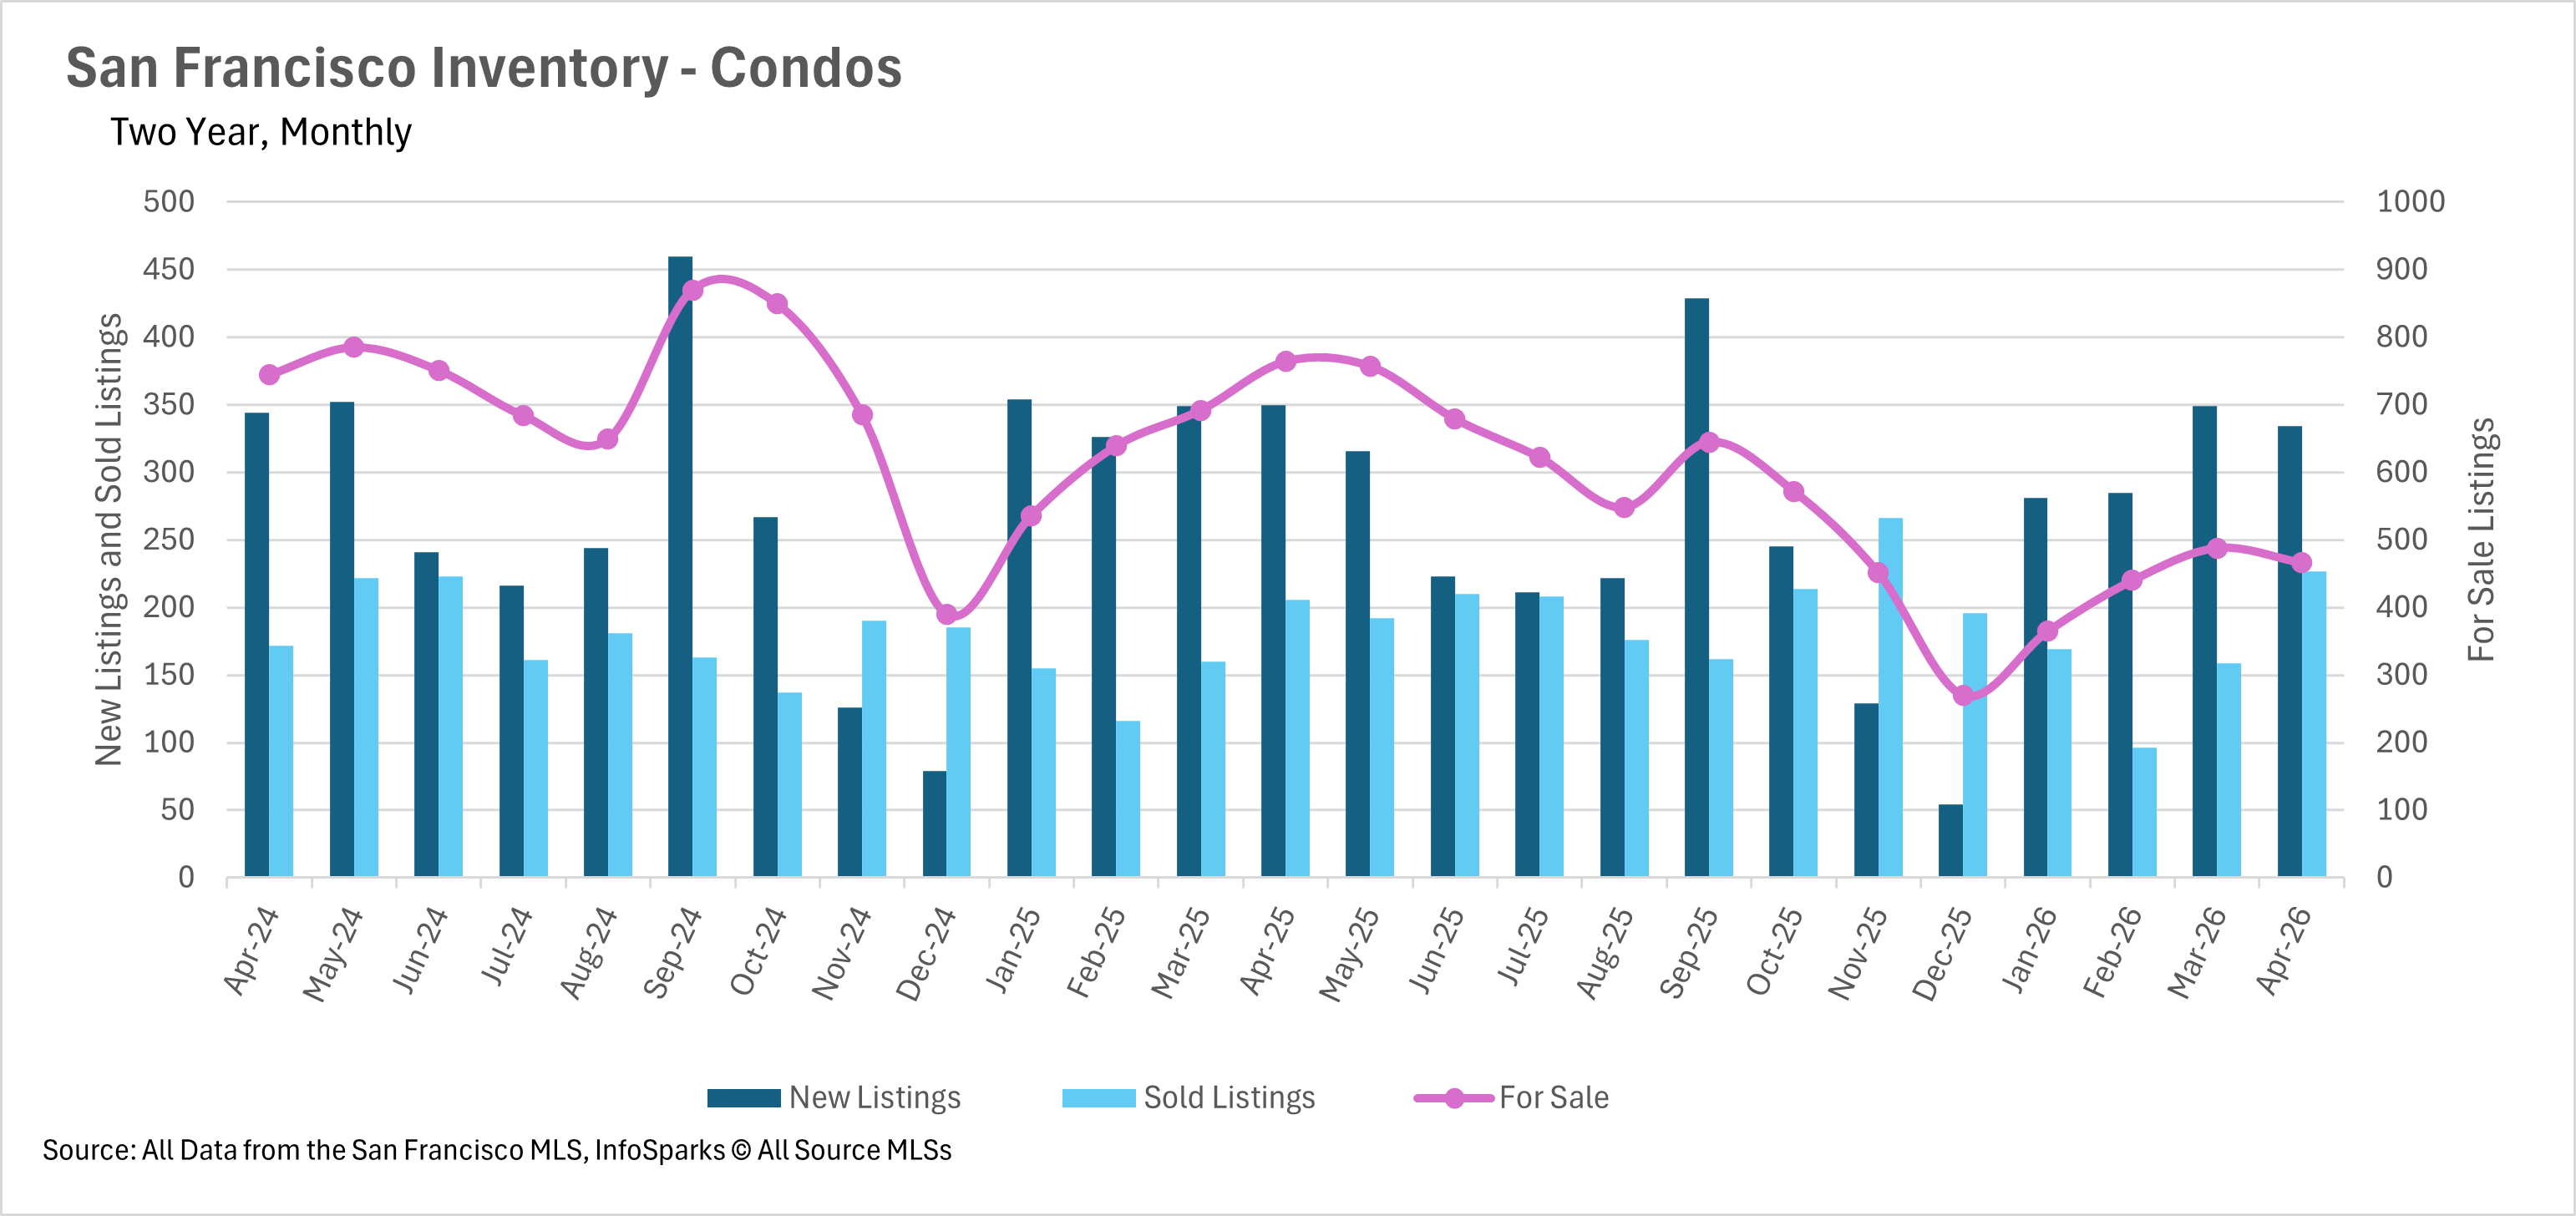
Despite being in the heart of the spring selling season, inventory levels across the Bay Area remain stubbornly below where they were a year ago. San Francisco continues to experience some of the most severe constraints, with single-family inventory down 36.99% and condo inventory down 39.01%, leaving fewer than 700 homes available for sale in the entire city. The North Bay isn't far behind, with single-family home inventory down 36.98% and condo inventory down 24.57%.
 
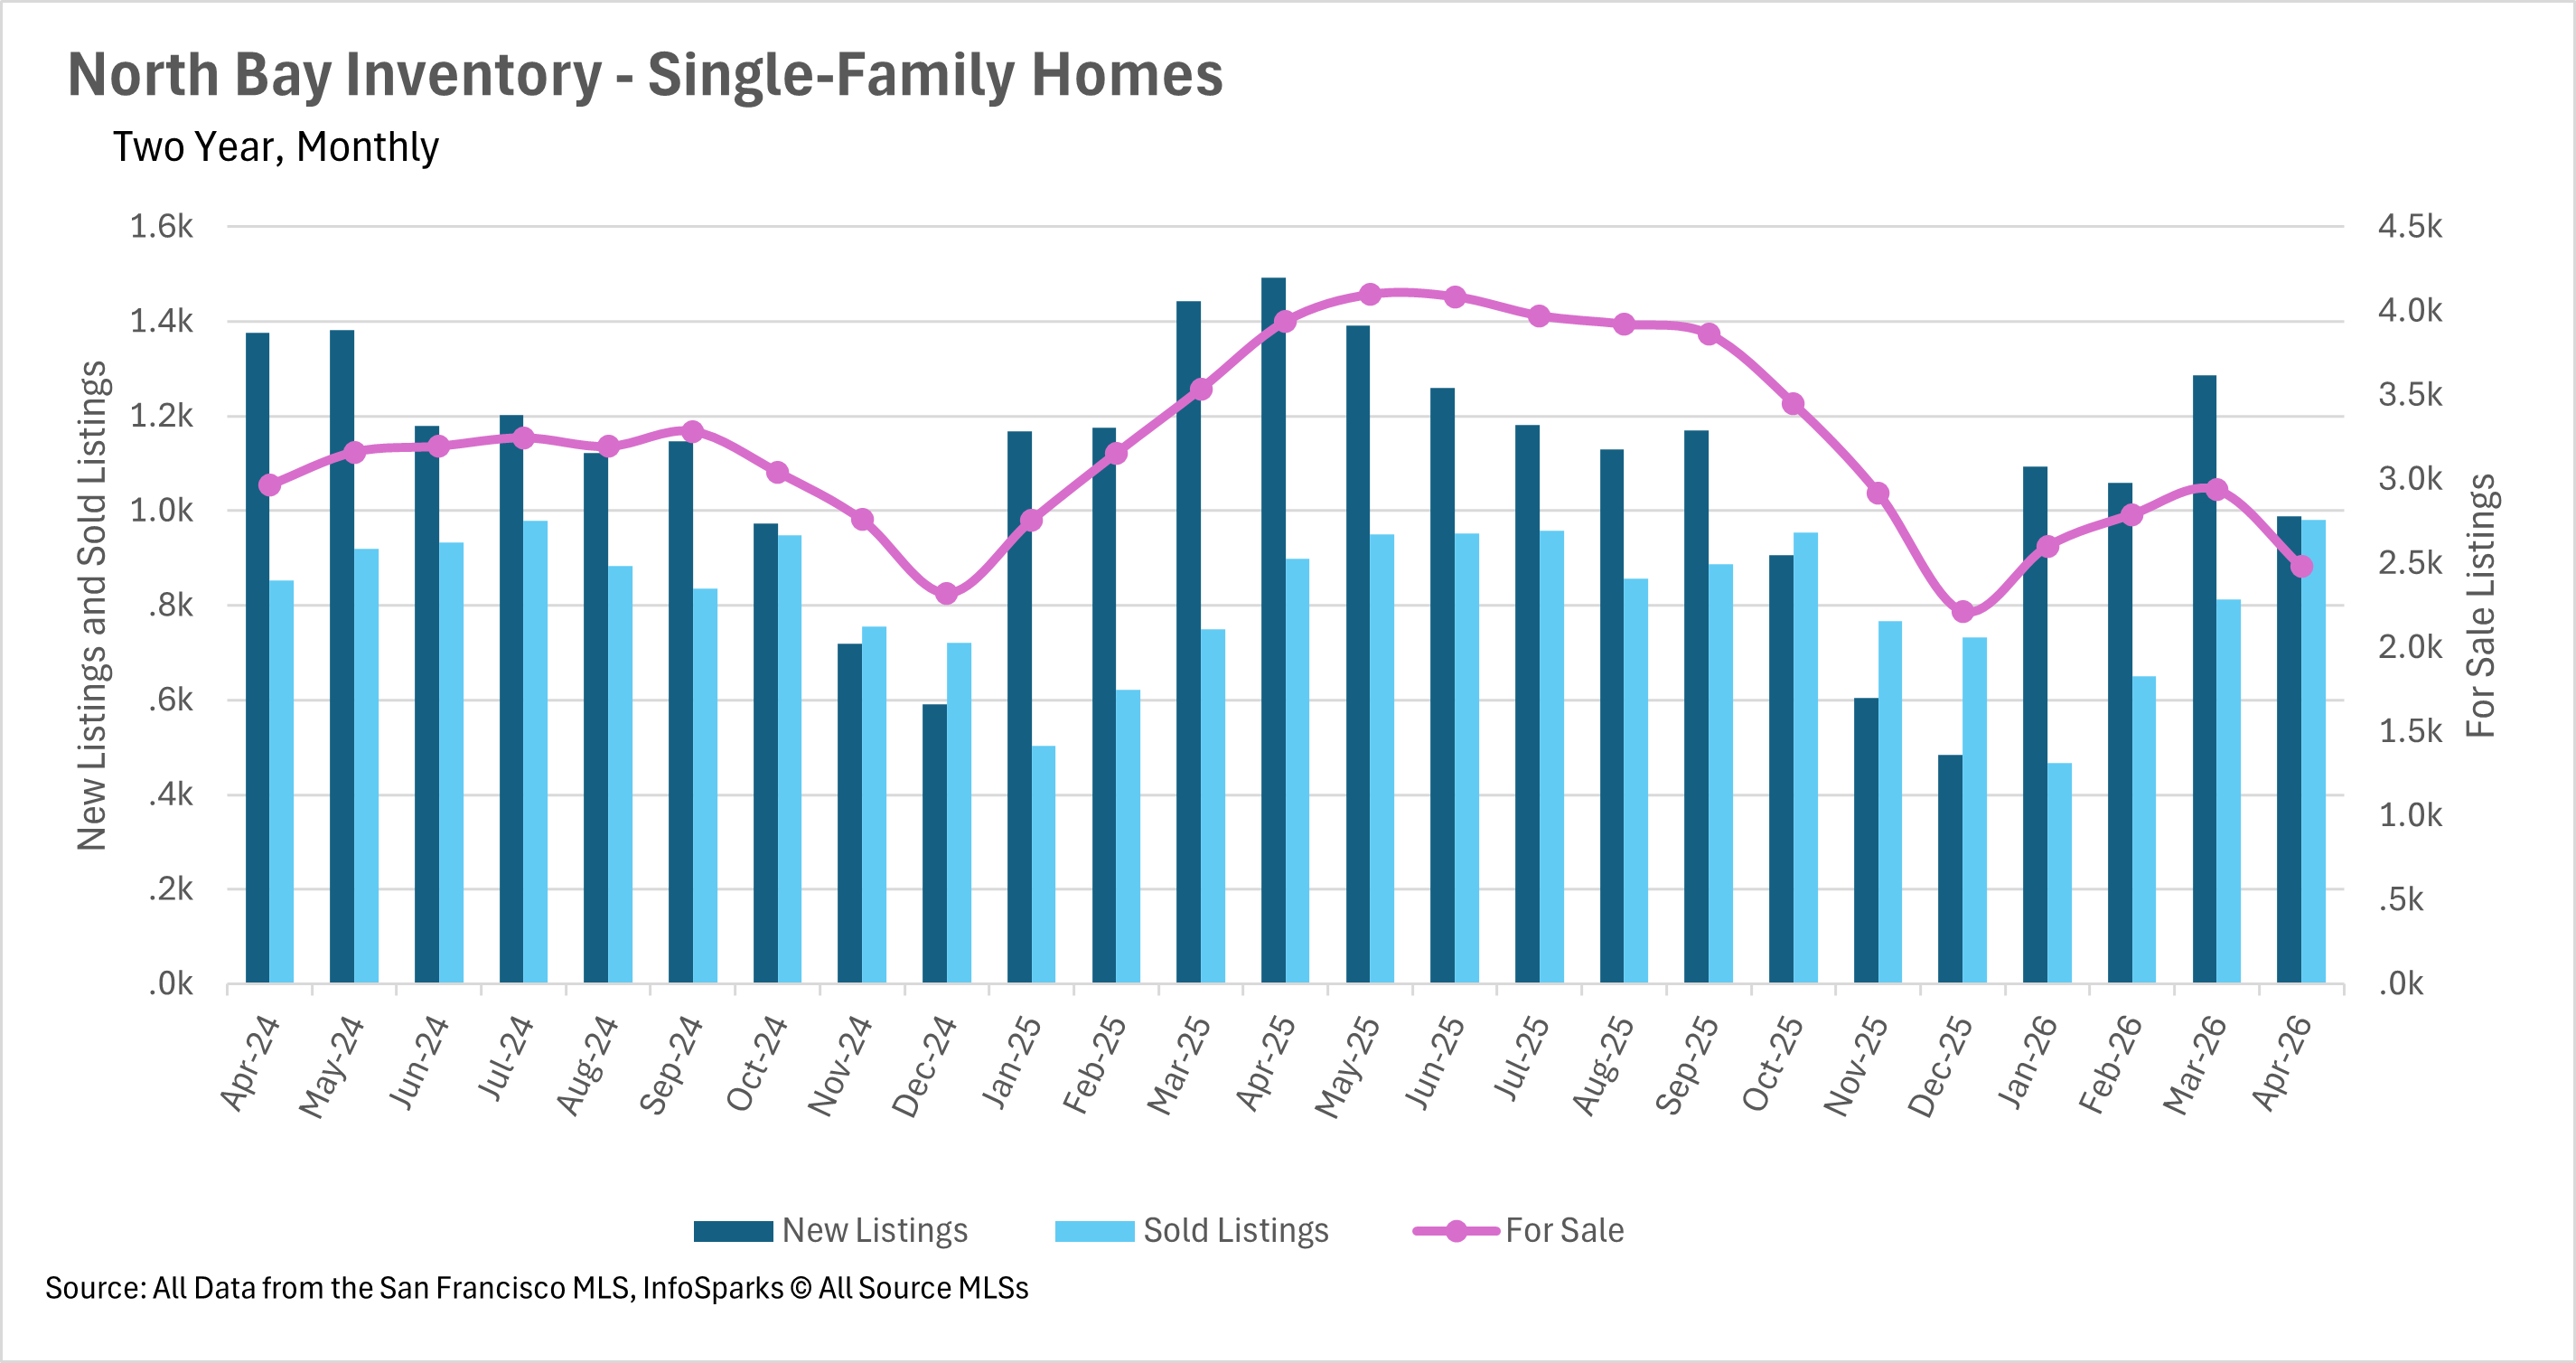
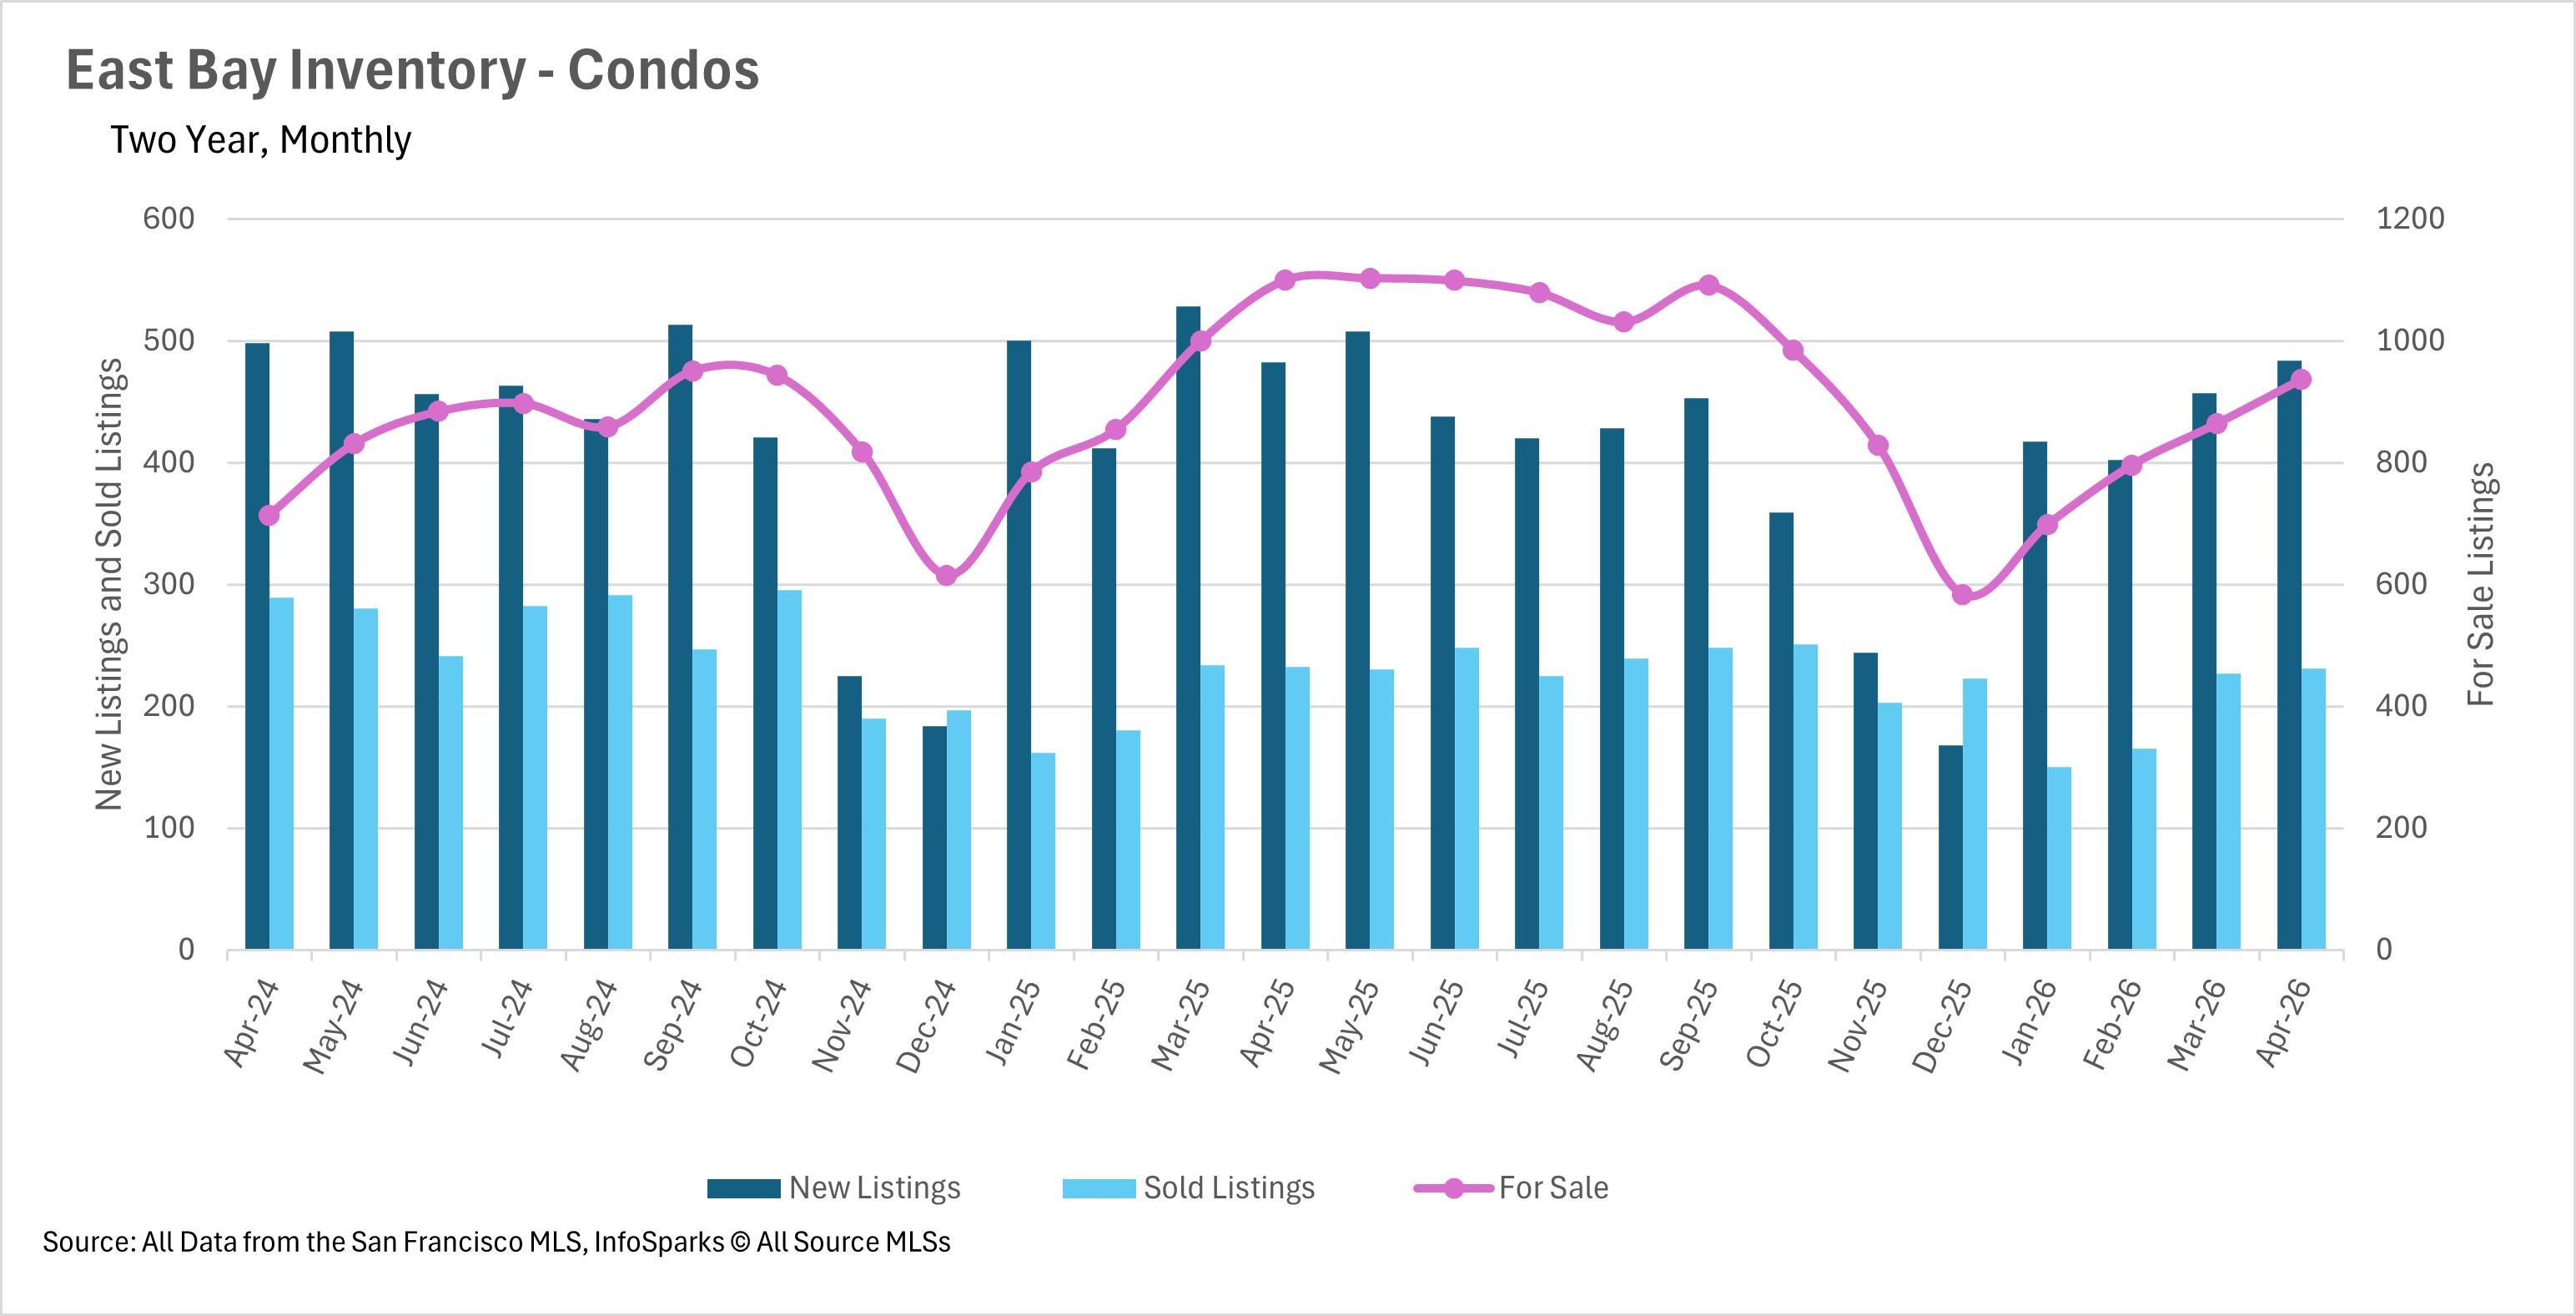
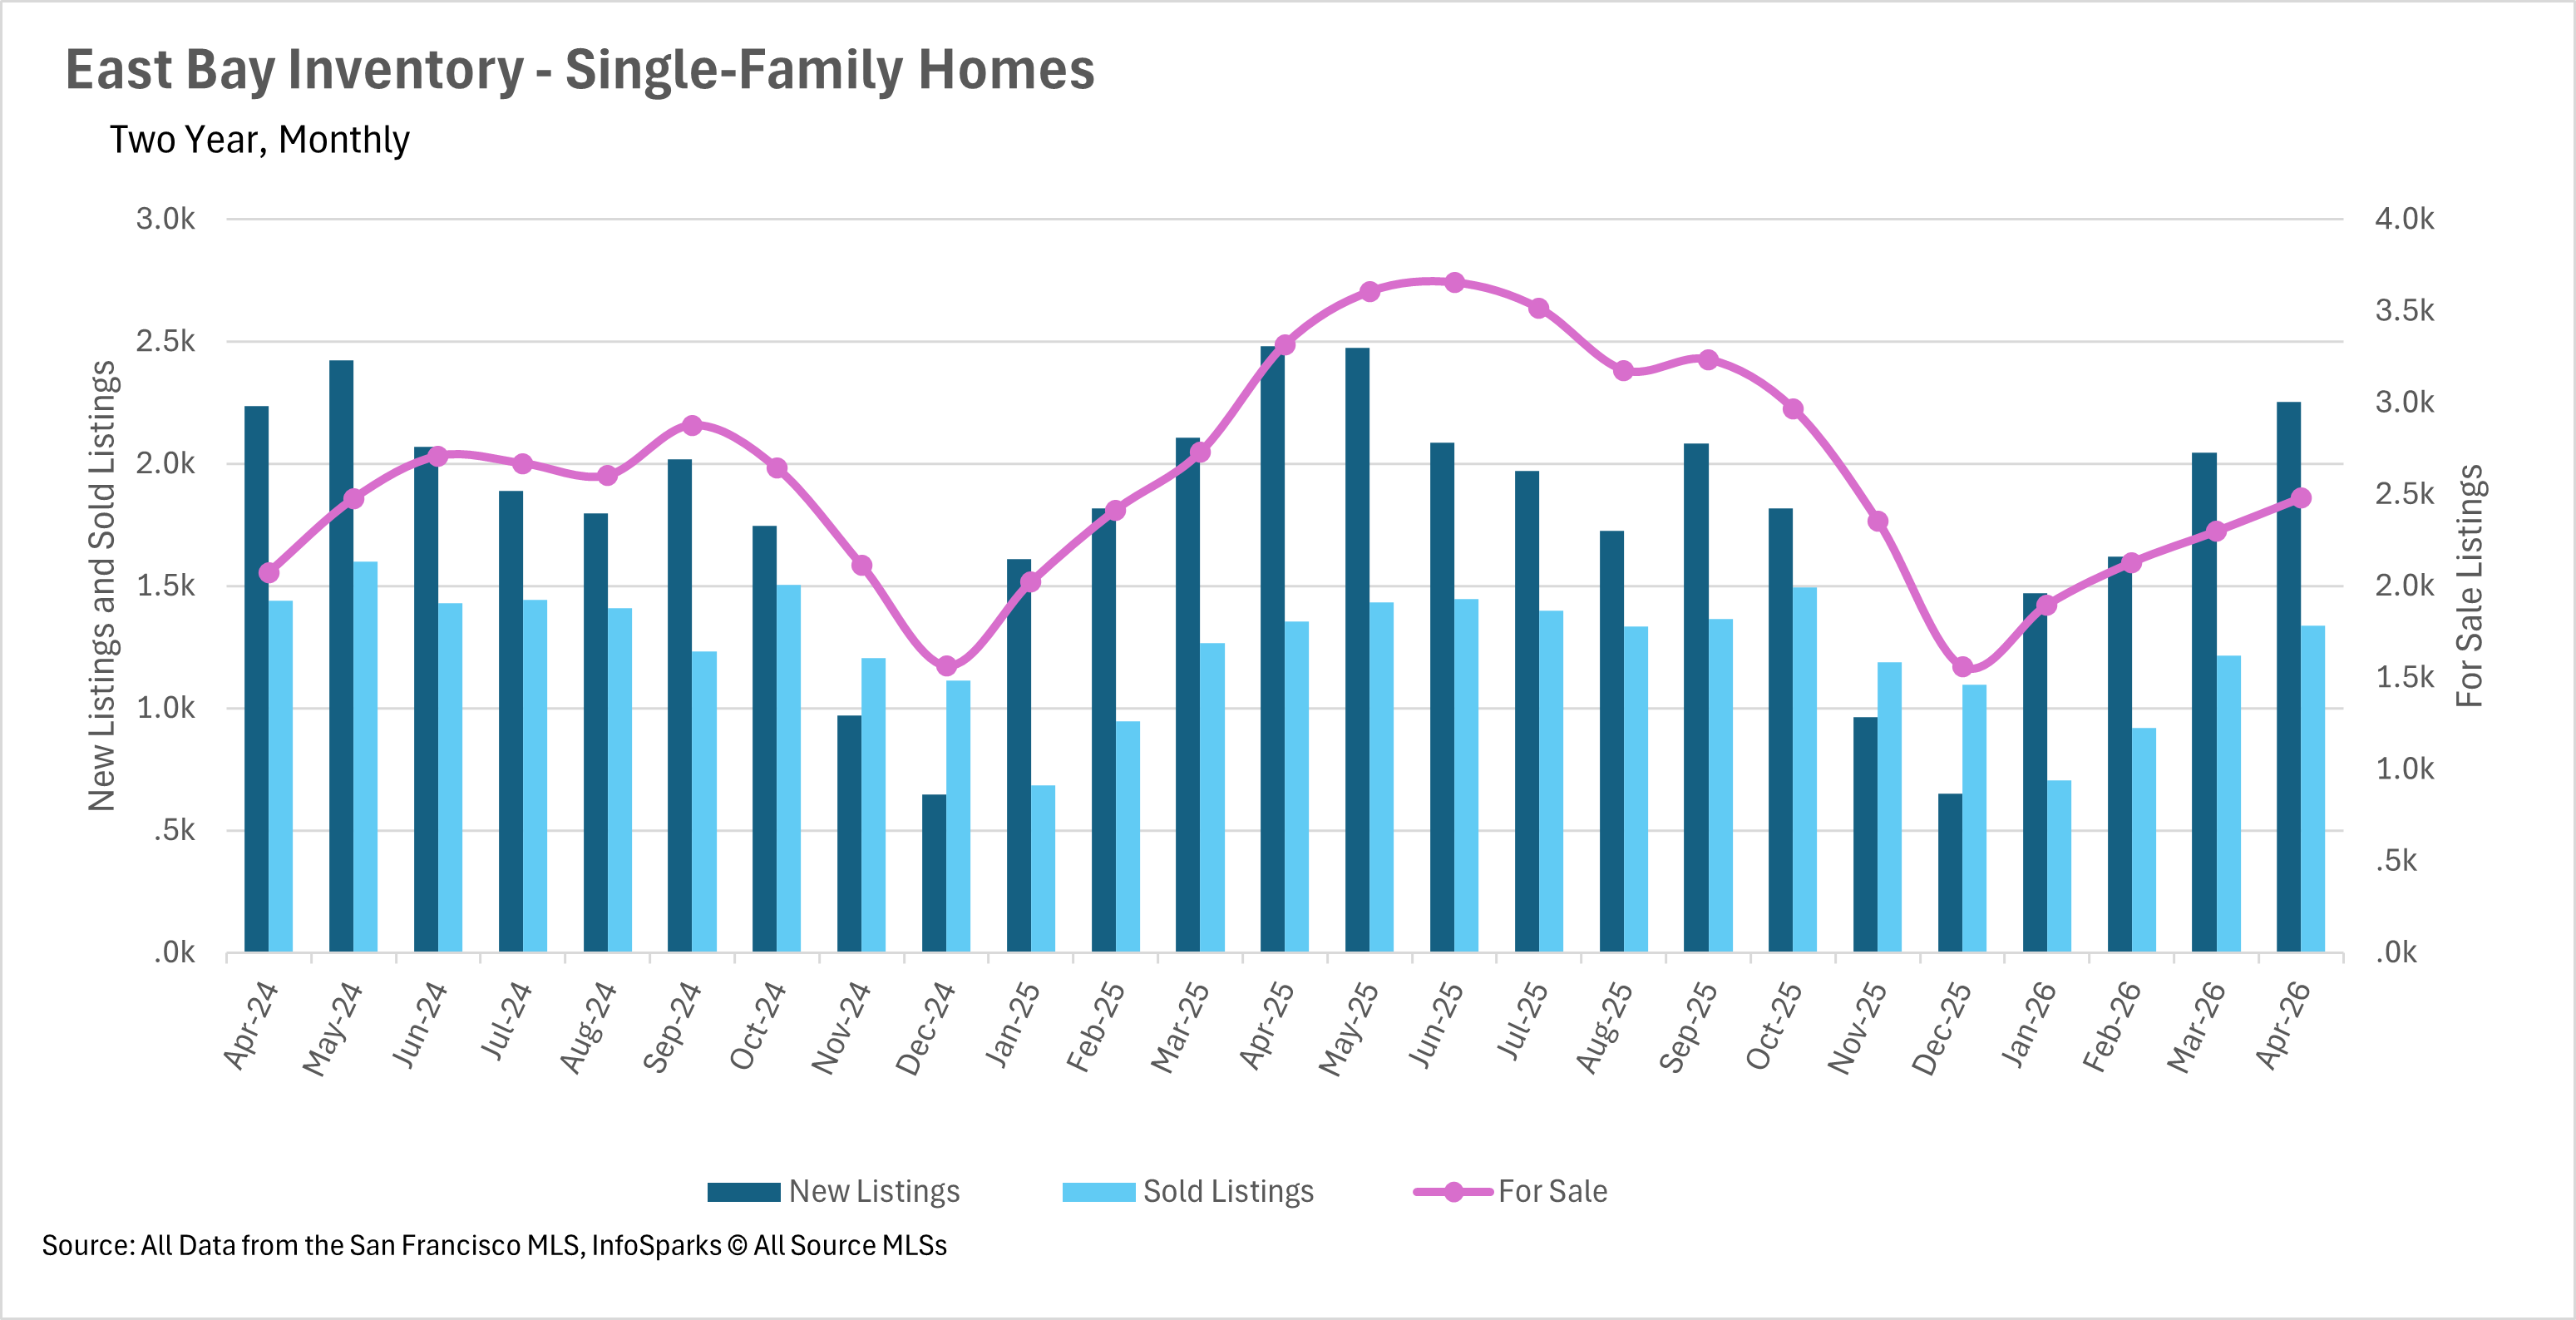
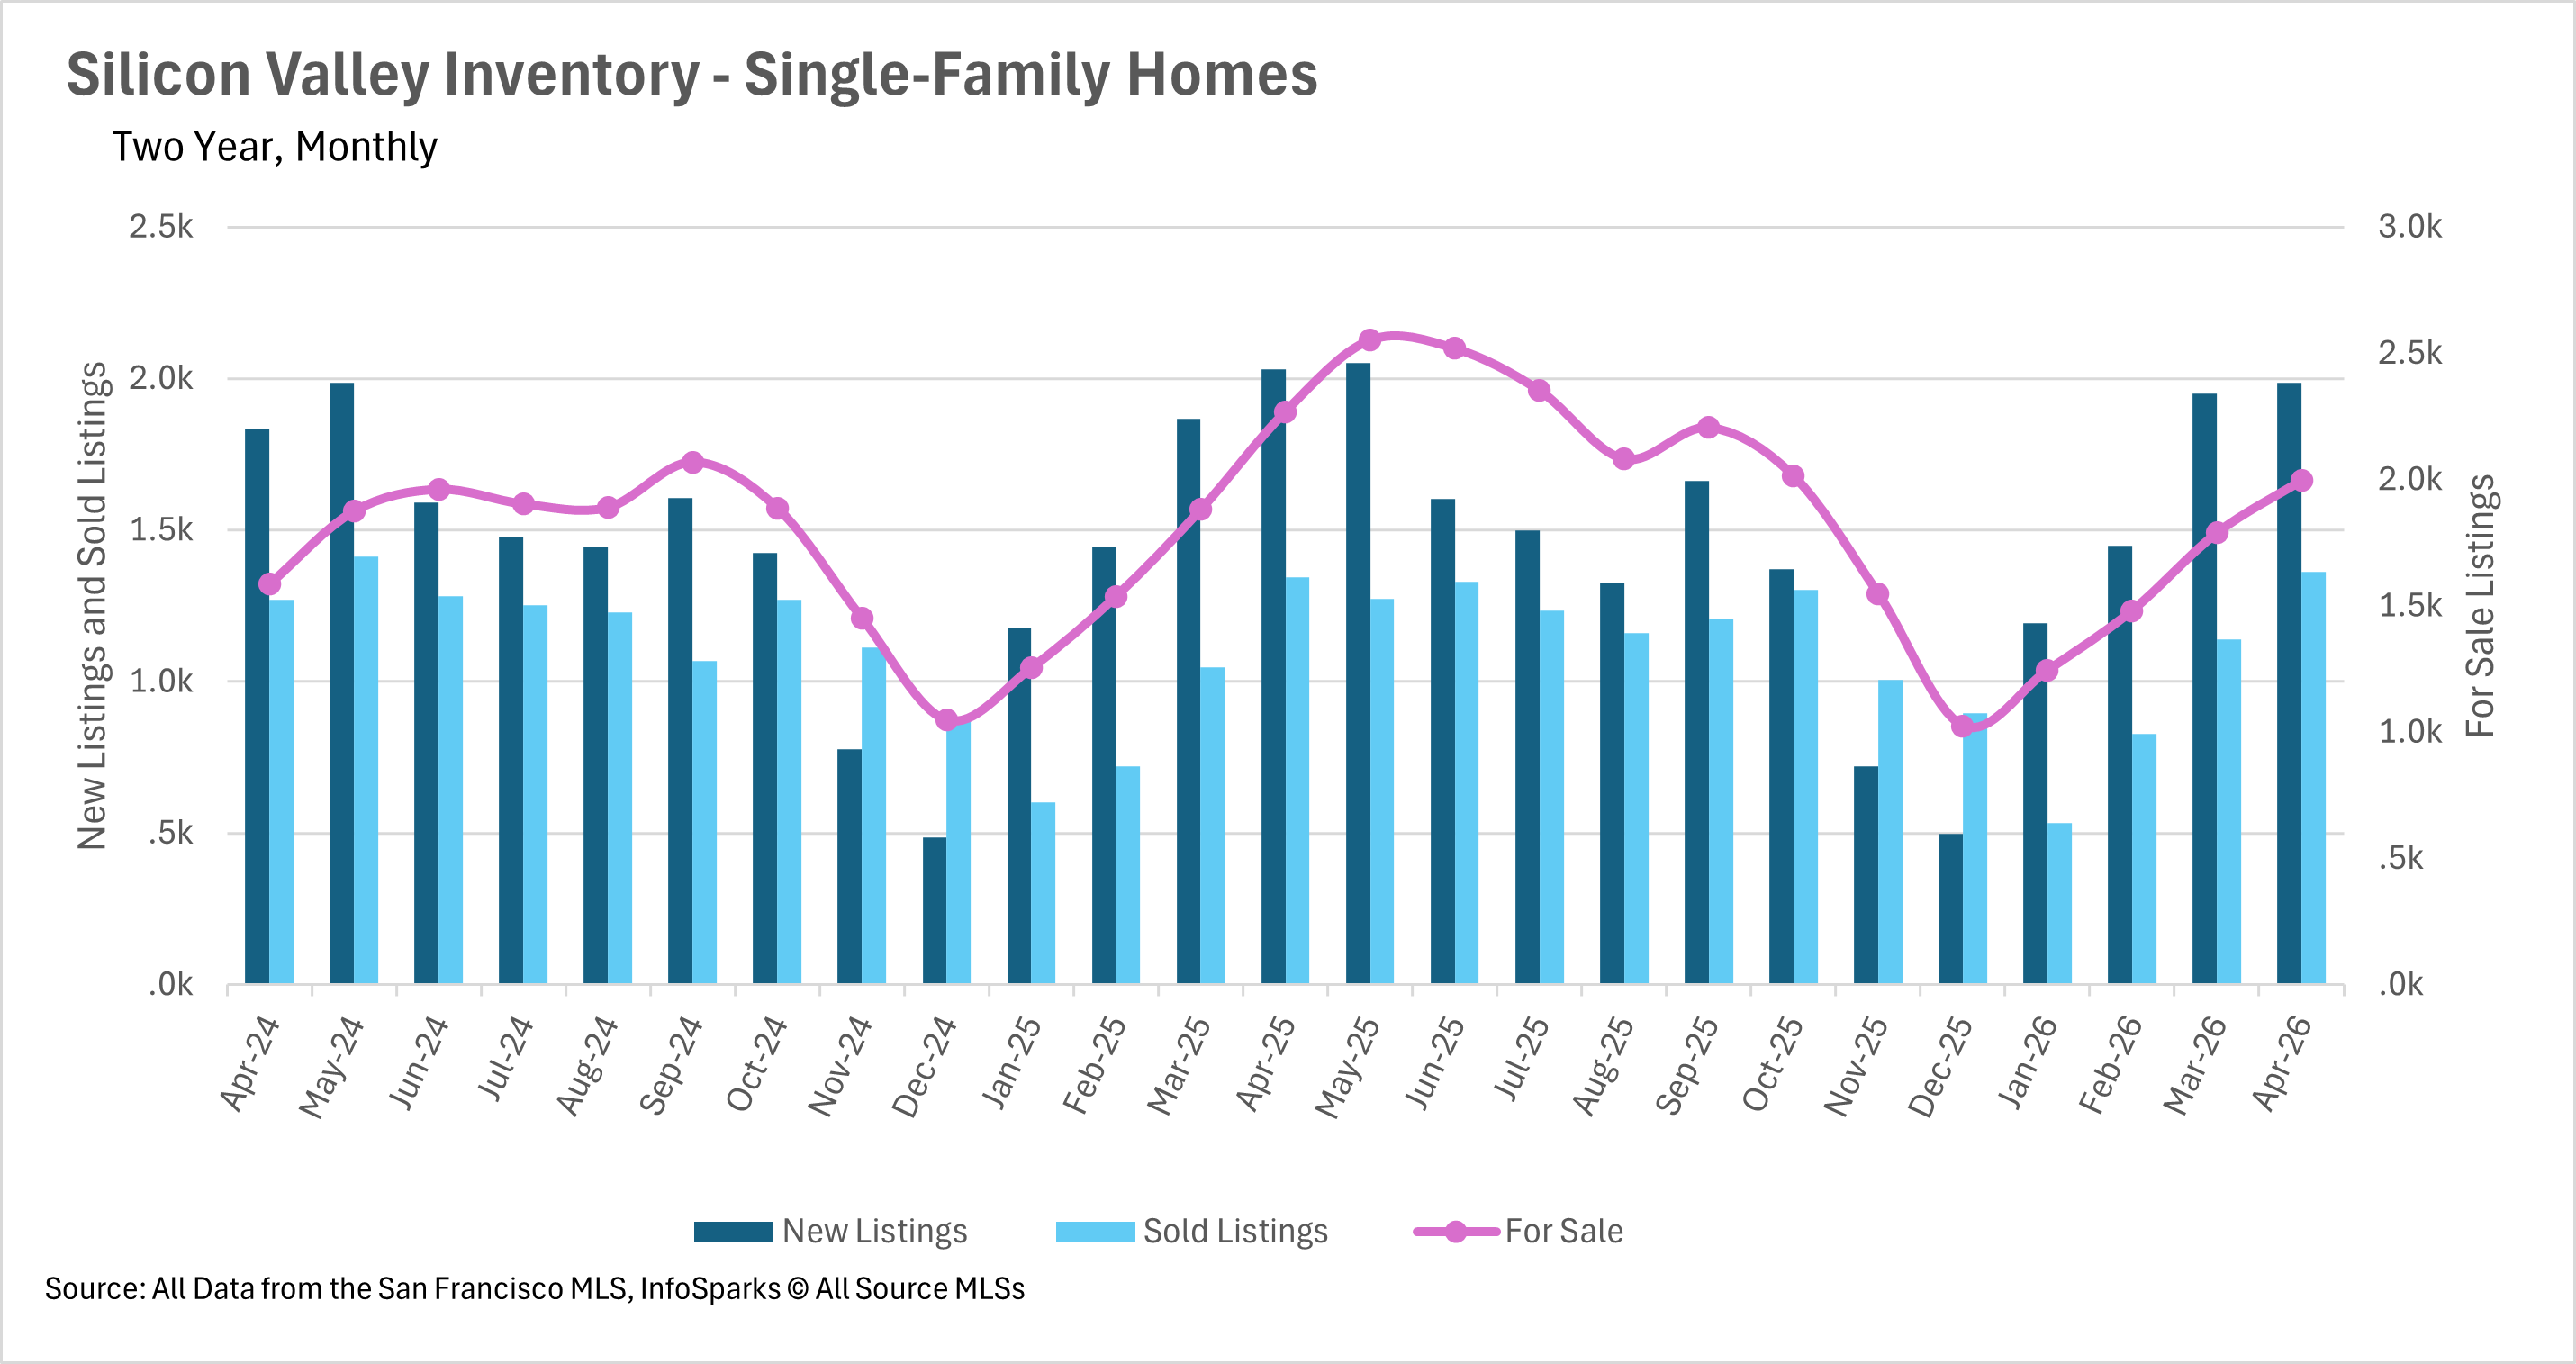
The East Bay has seen single-family inventory decline by 25.23% and condo inventory drop by 14.82%. Silicon Valley rounds out the picture with single-family inventory down 12.03% and condo inventory down 6.47%. The silver lining is that transaction activity remains healthy. North Bay single-family home sales are up 9.01% year-over-year, and April saw nearly as many single-family home sales as new listings in the North Bay, underscoring just how quickly the market is absorbing available supply. Until more sellers decide to list their properties, buyers will continue to face an incredibly competitive landscape.
Single-family homes are selling in days, but the condo market is a mixed bag
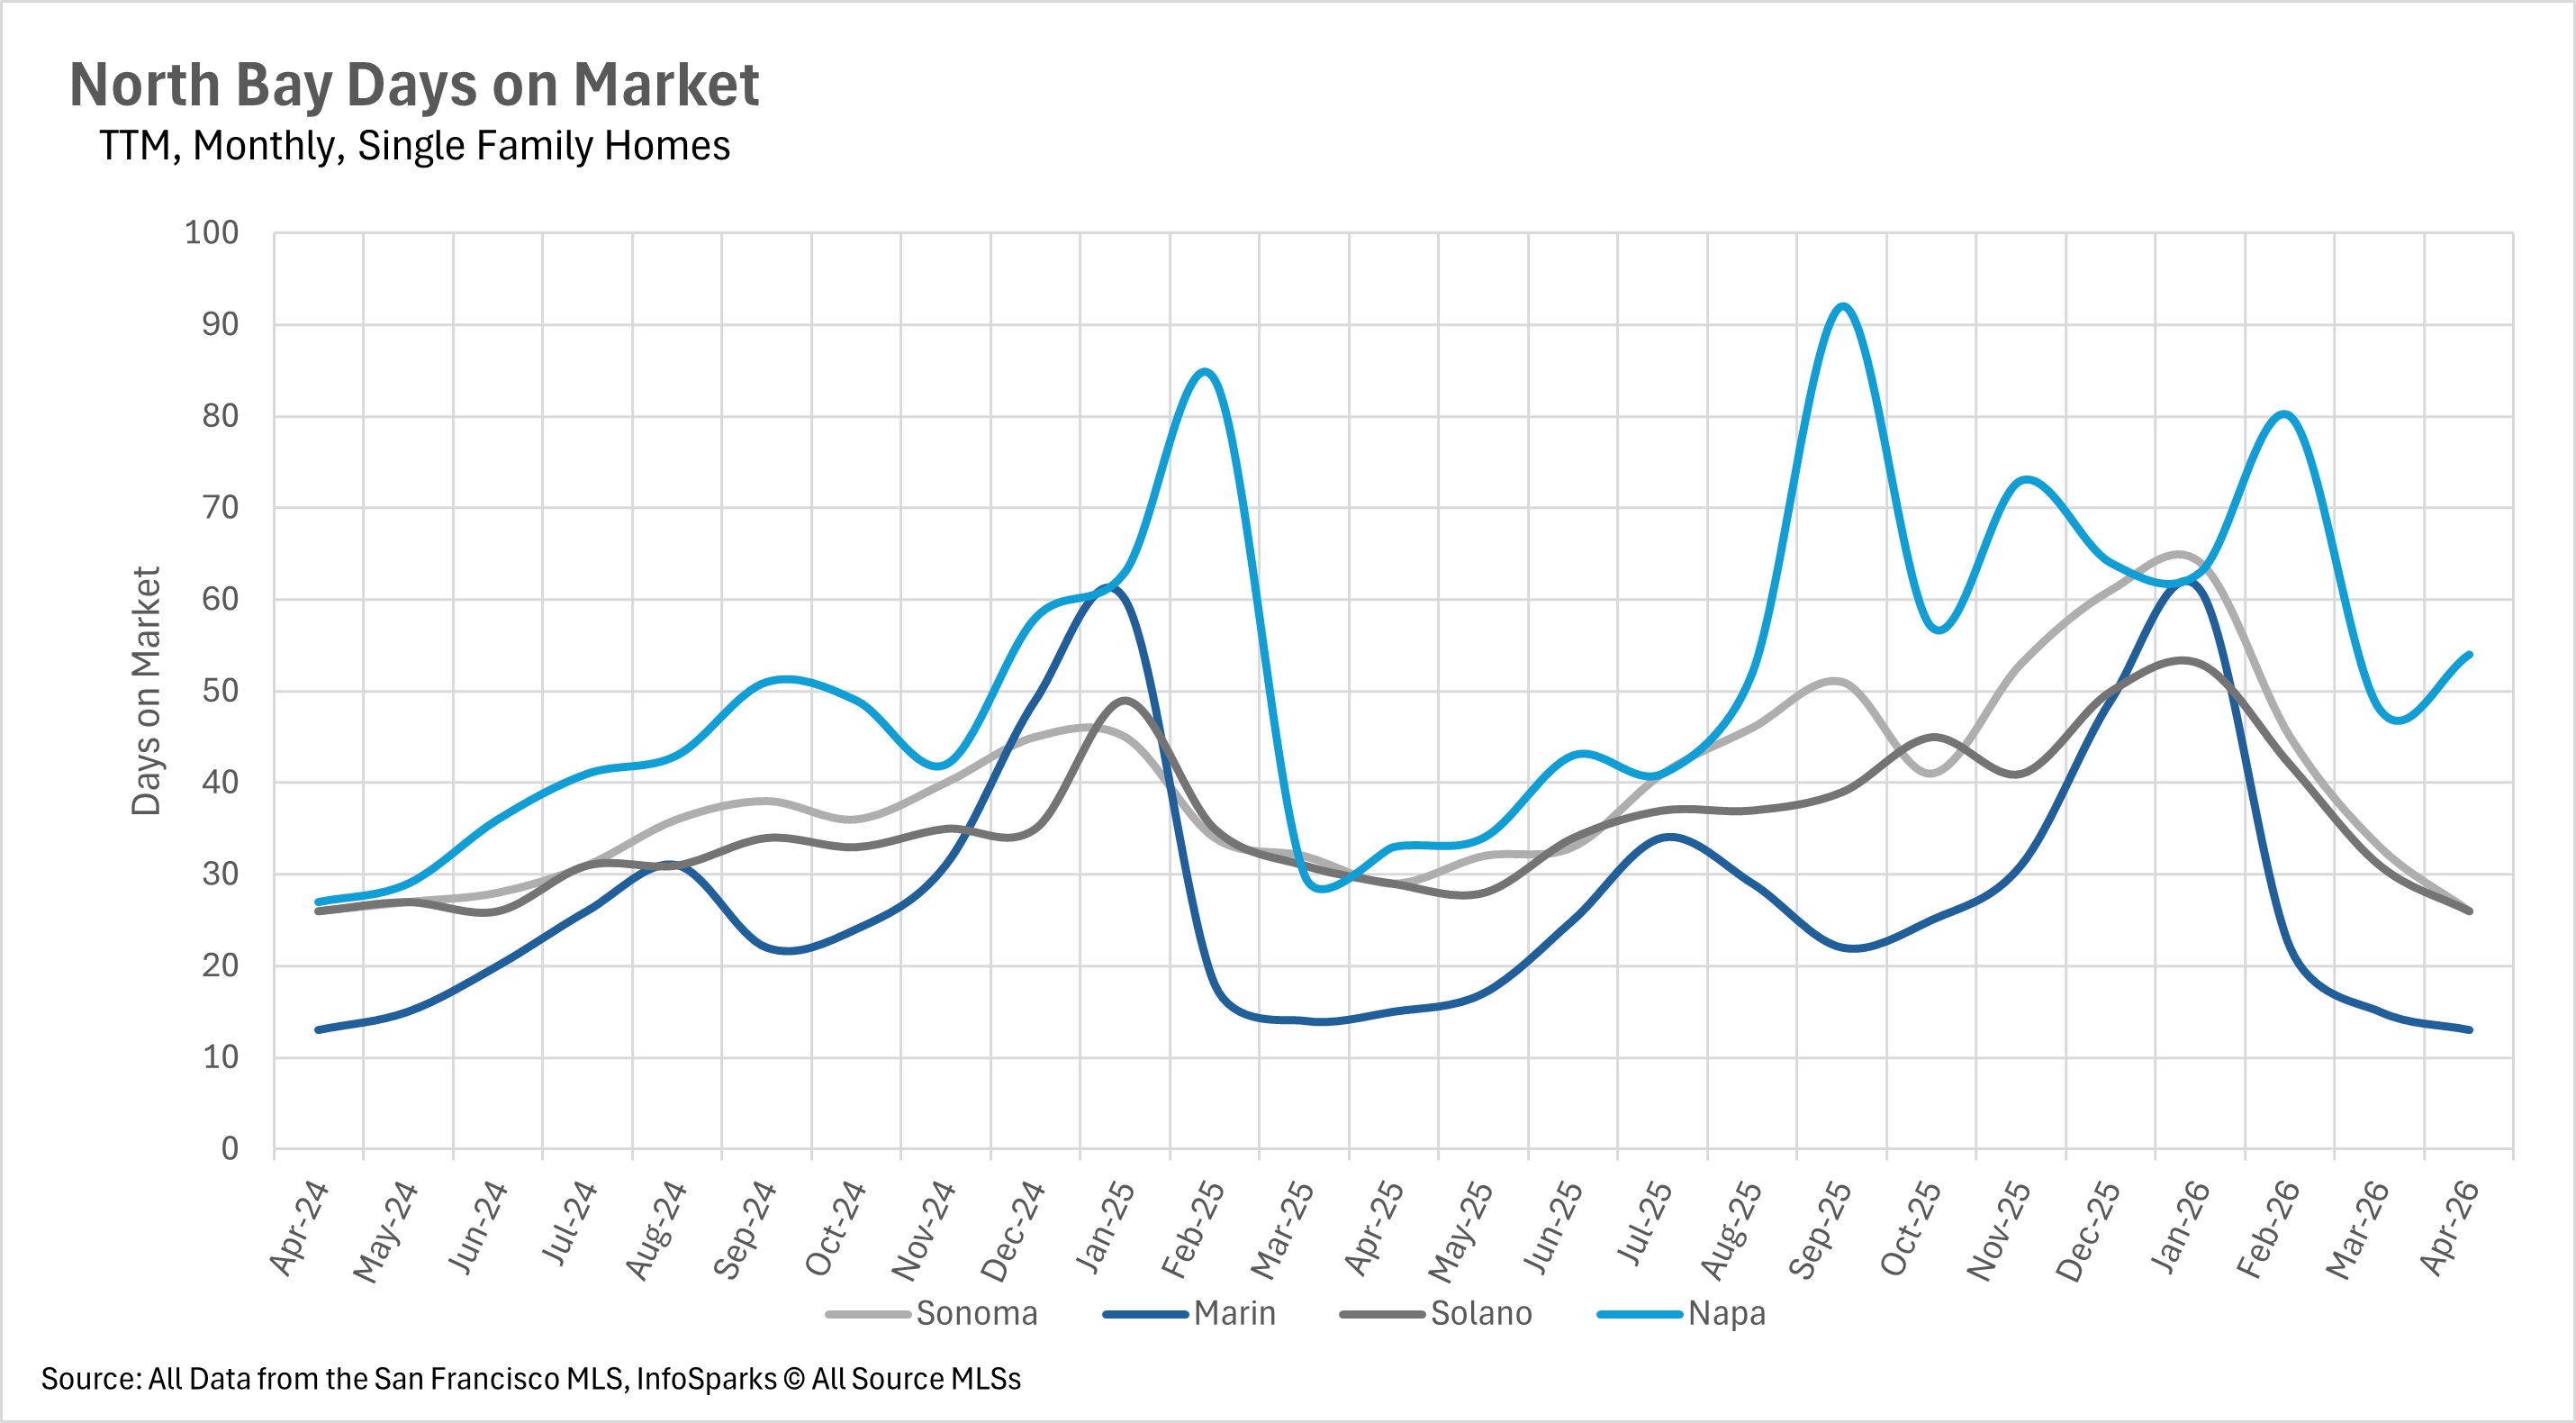
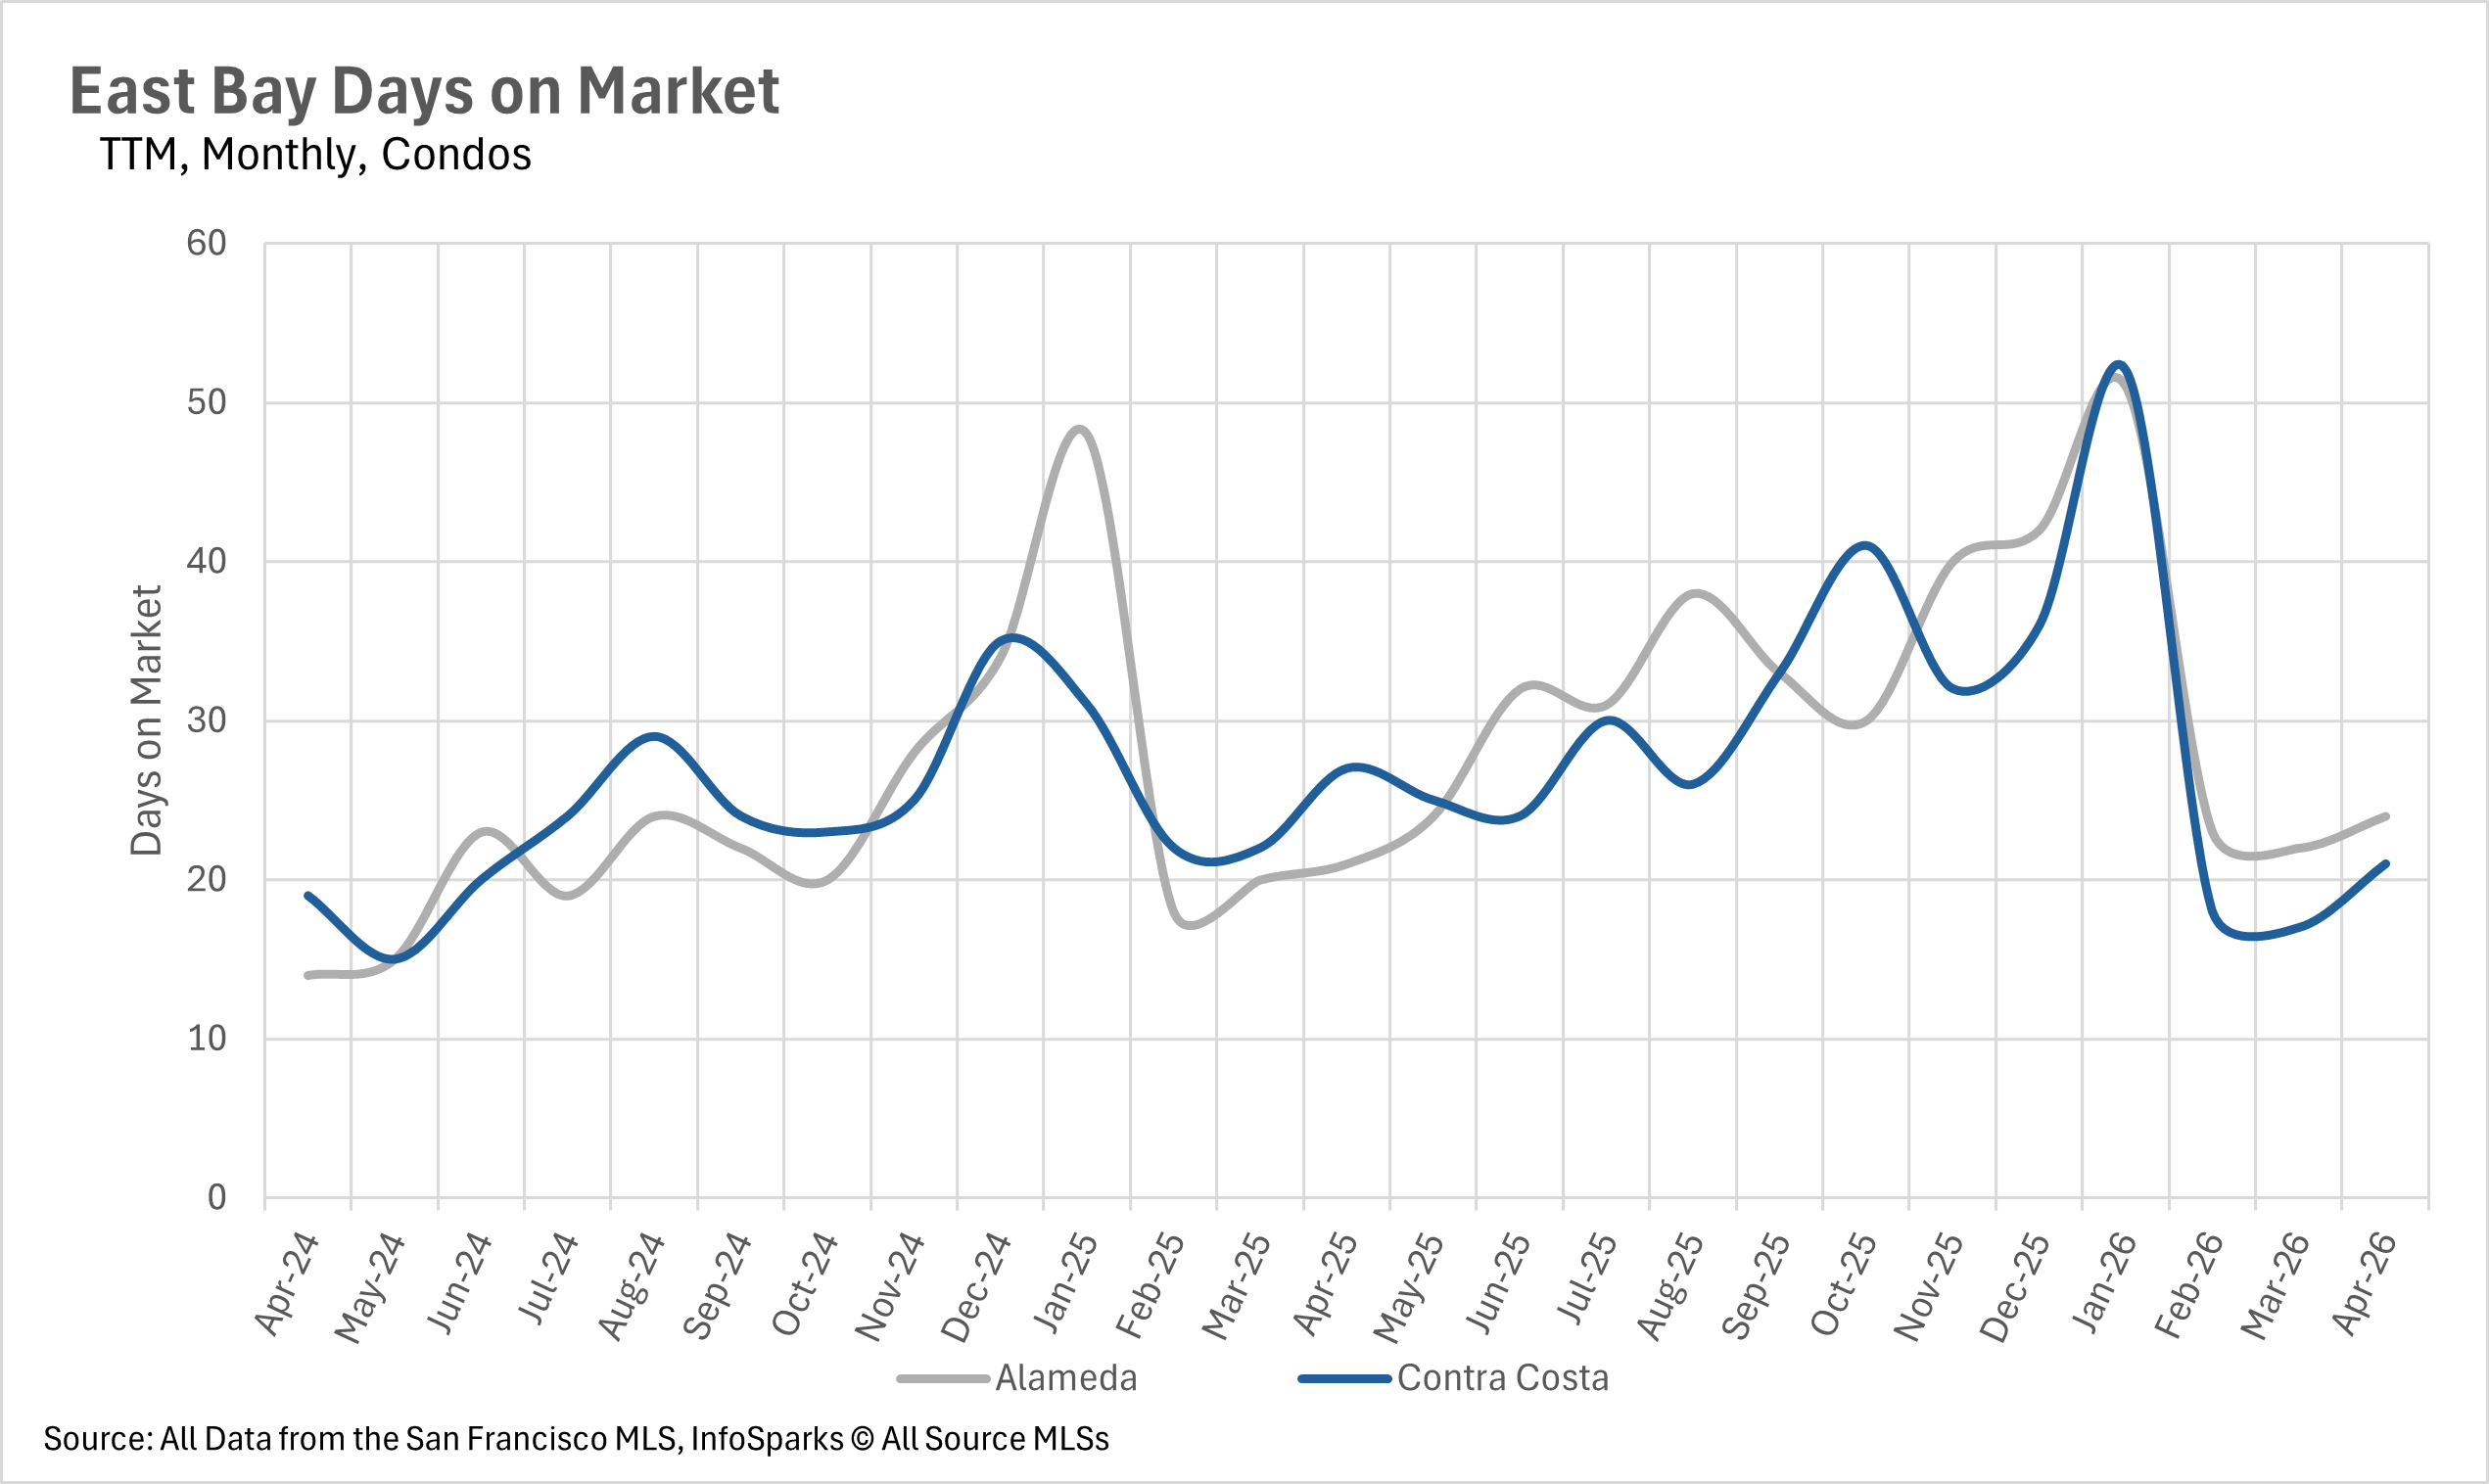
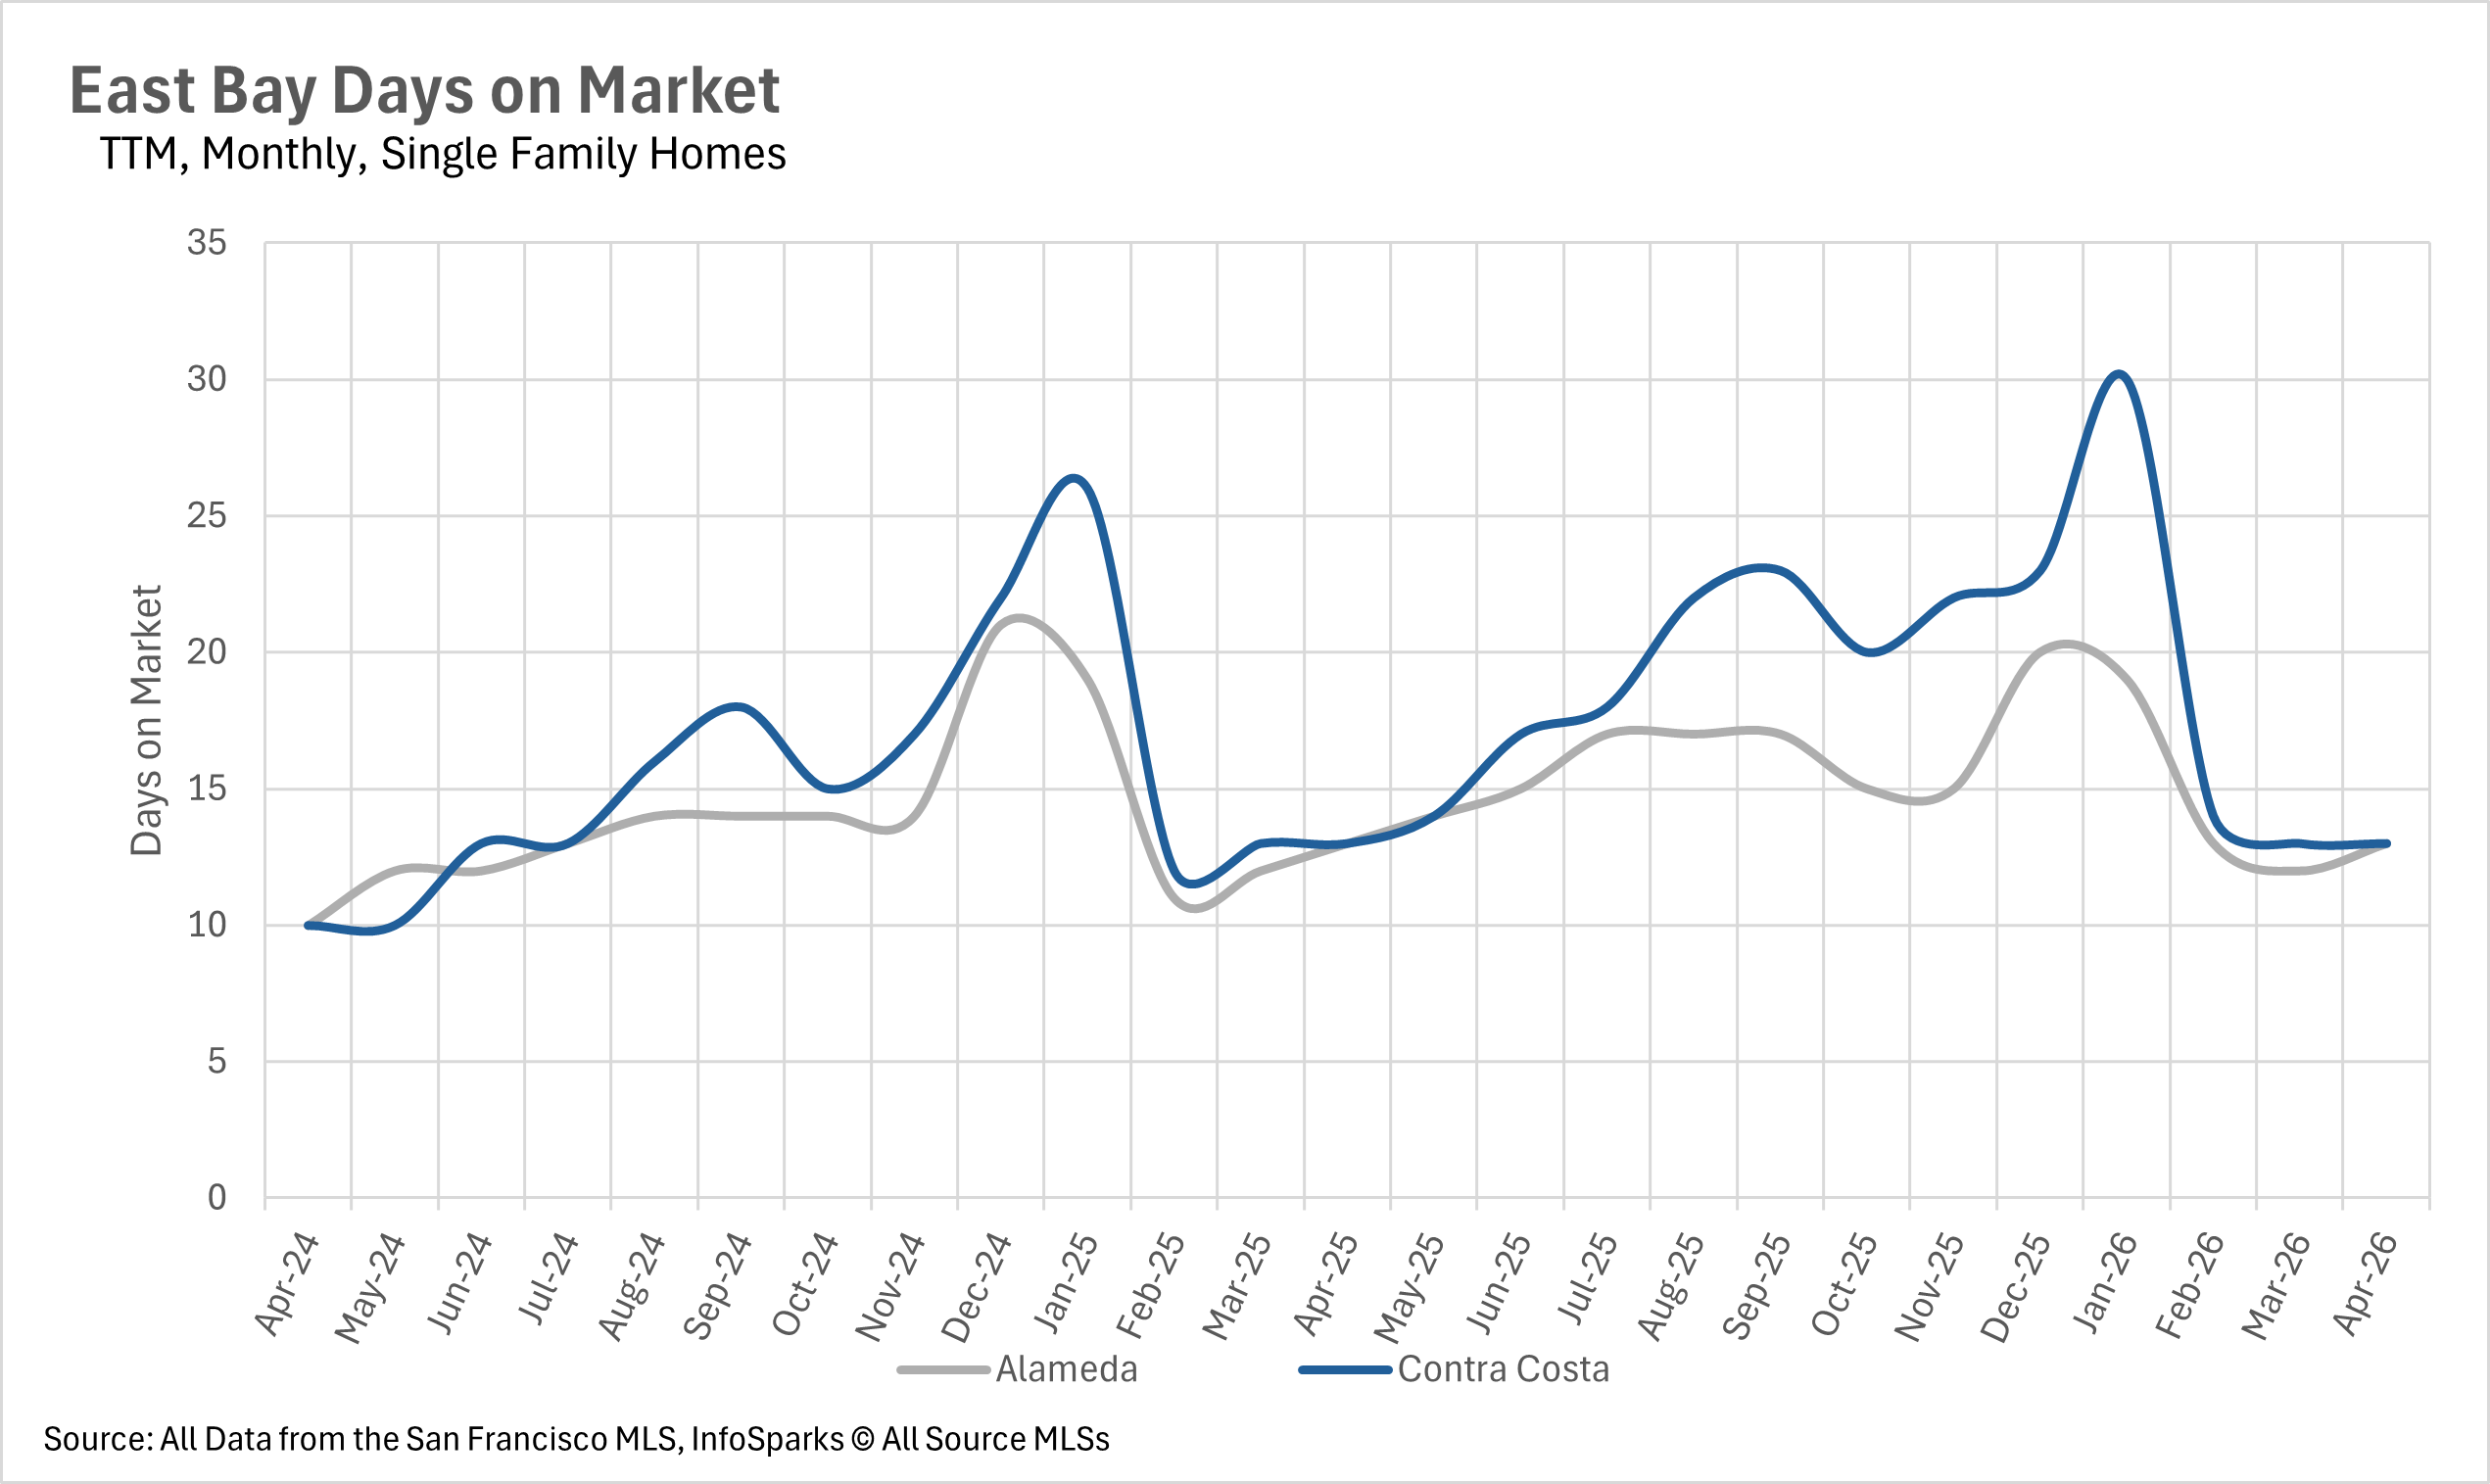
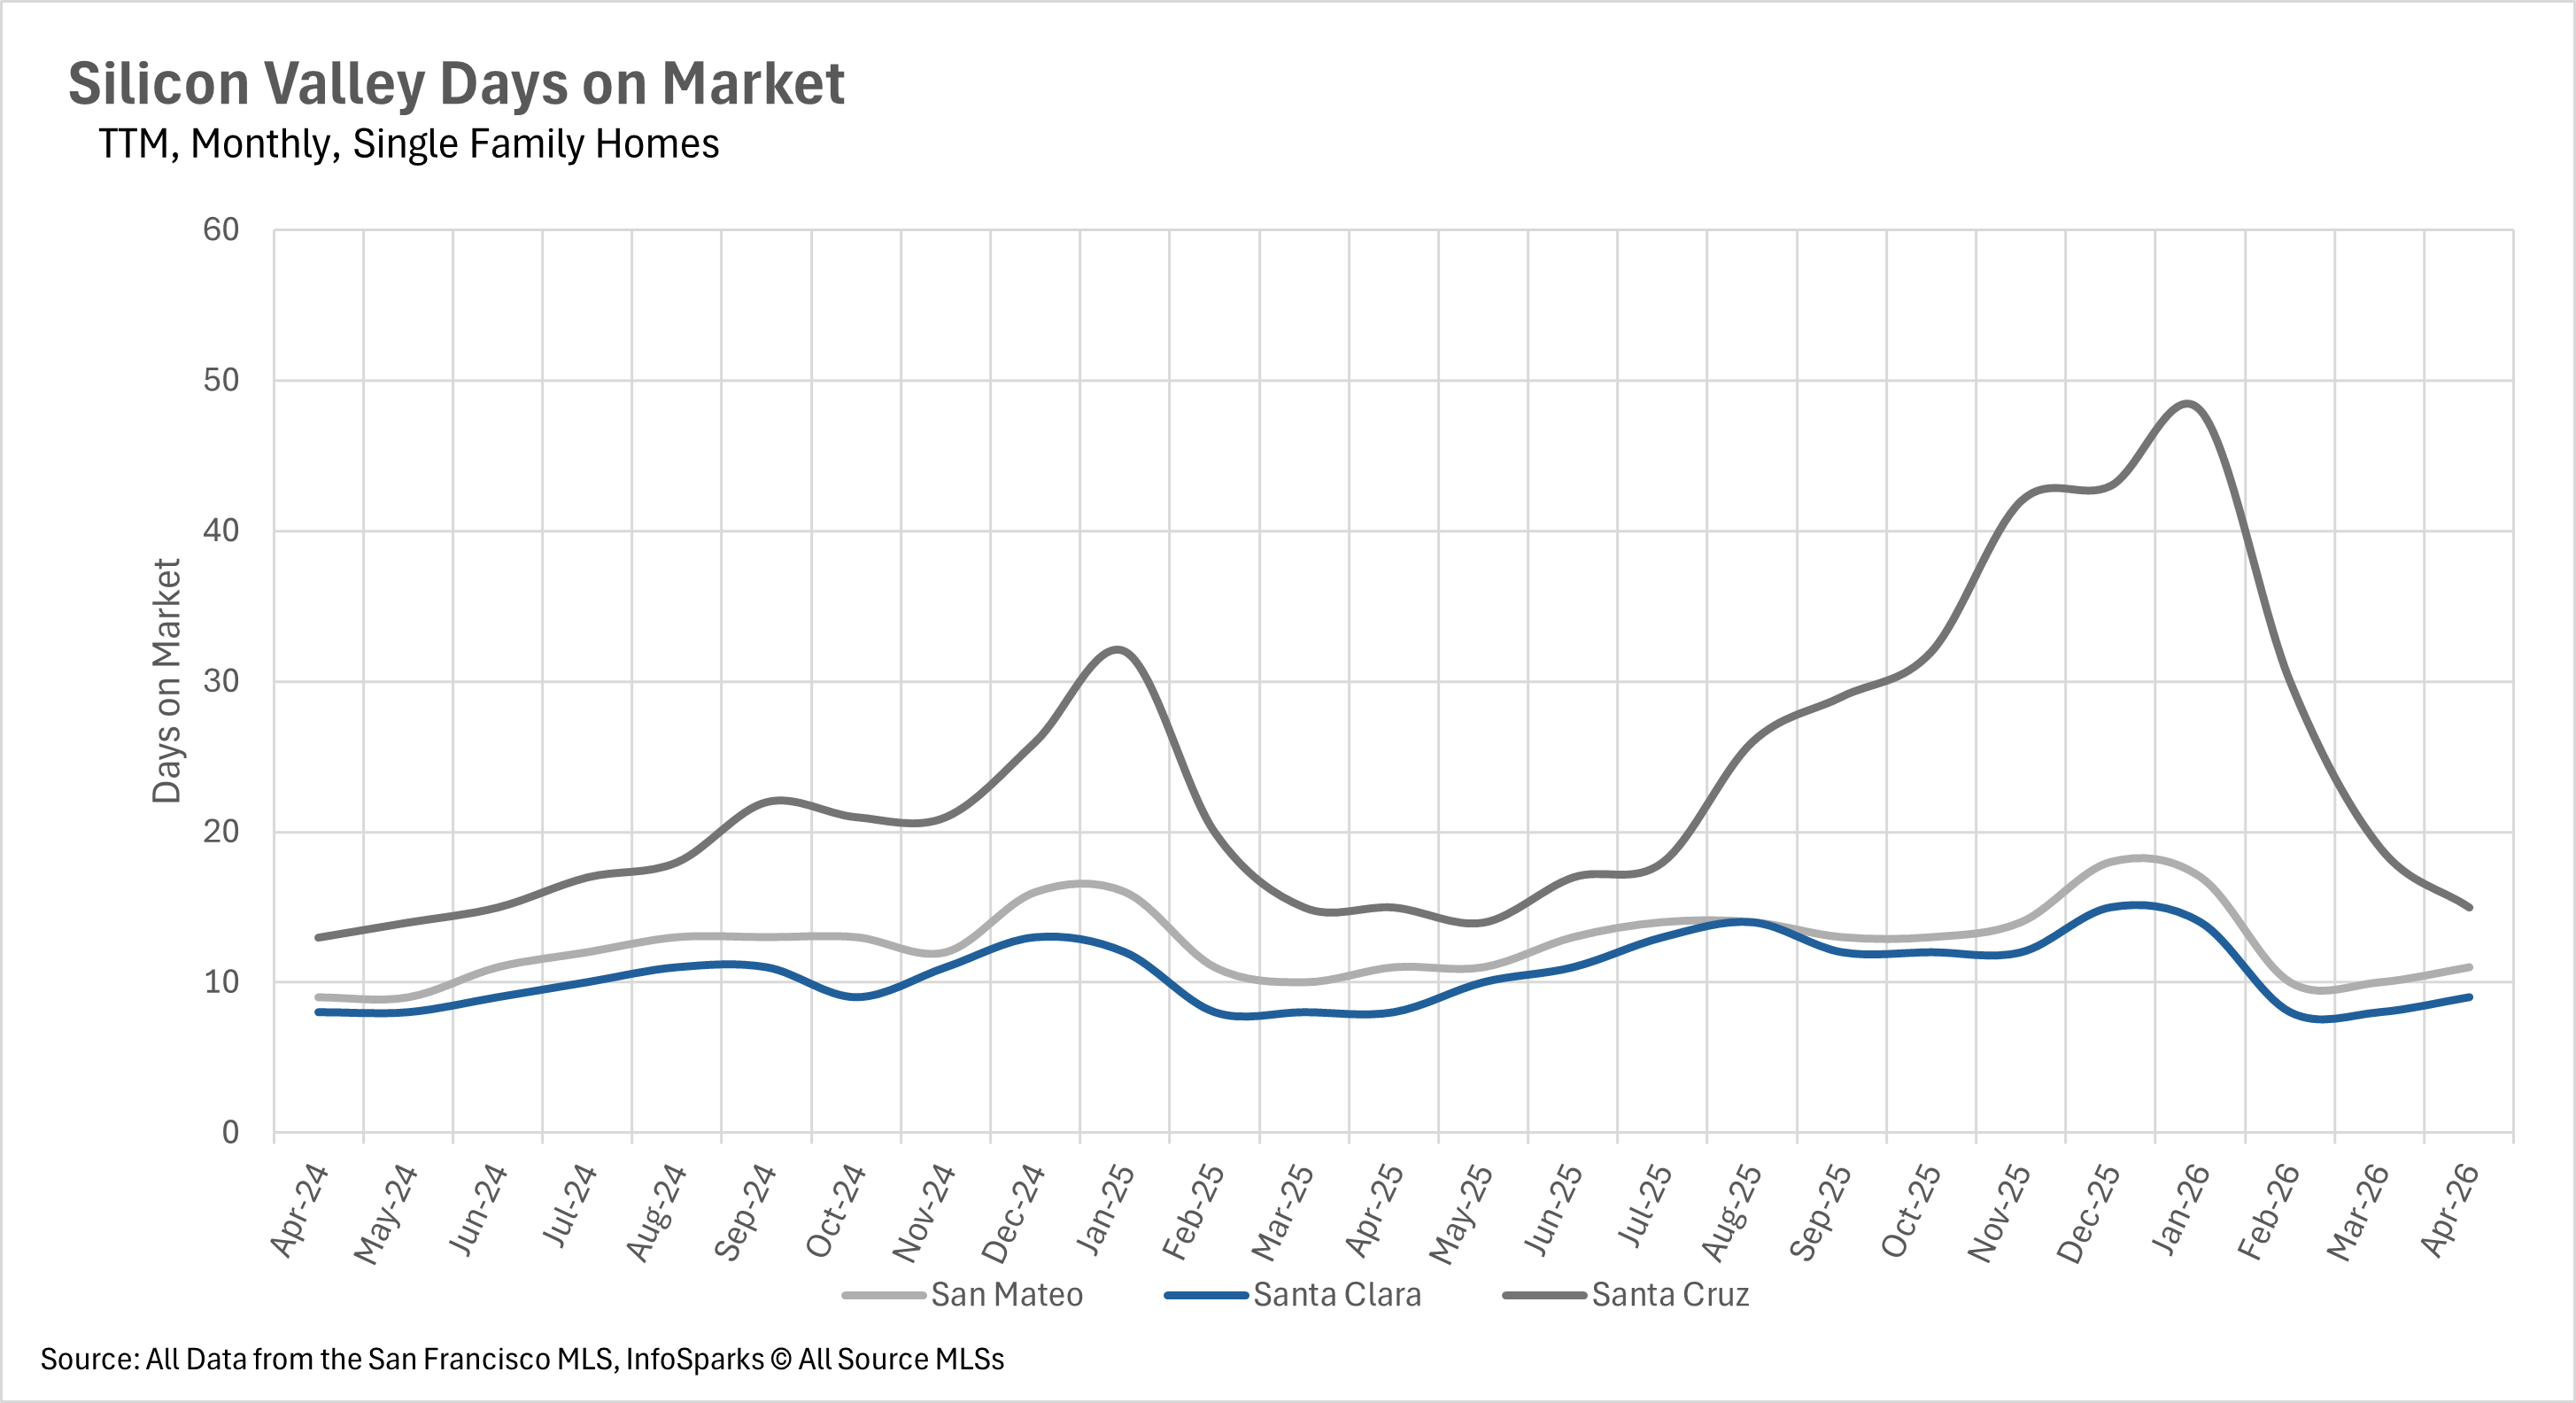
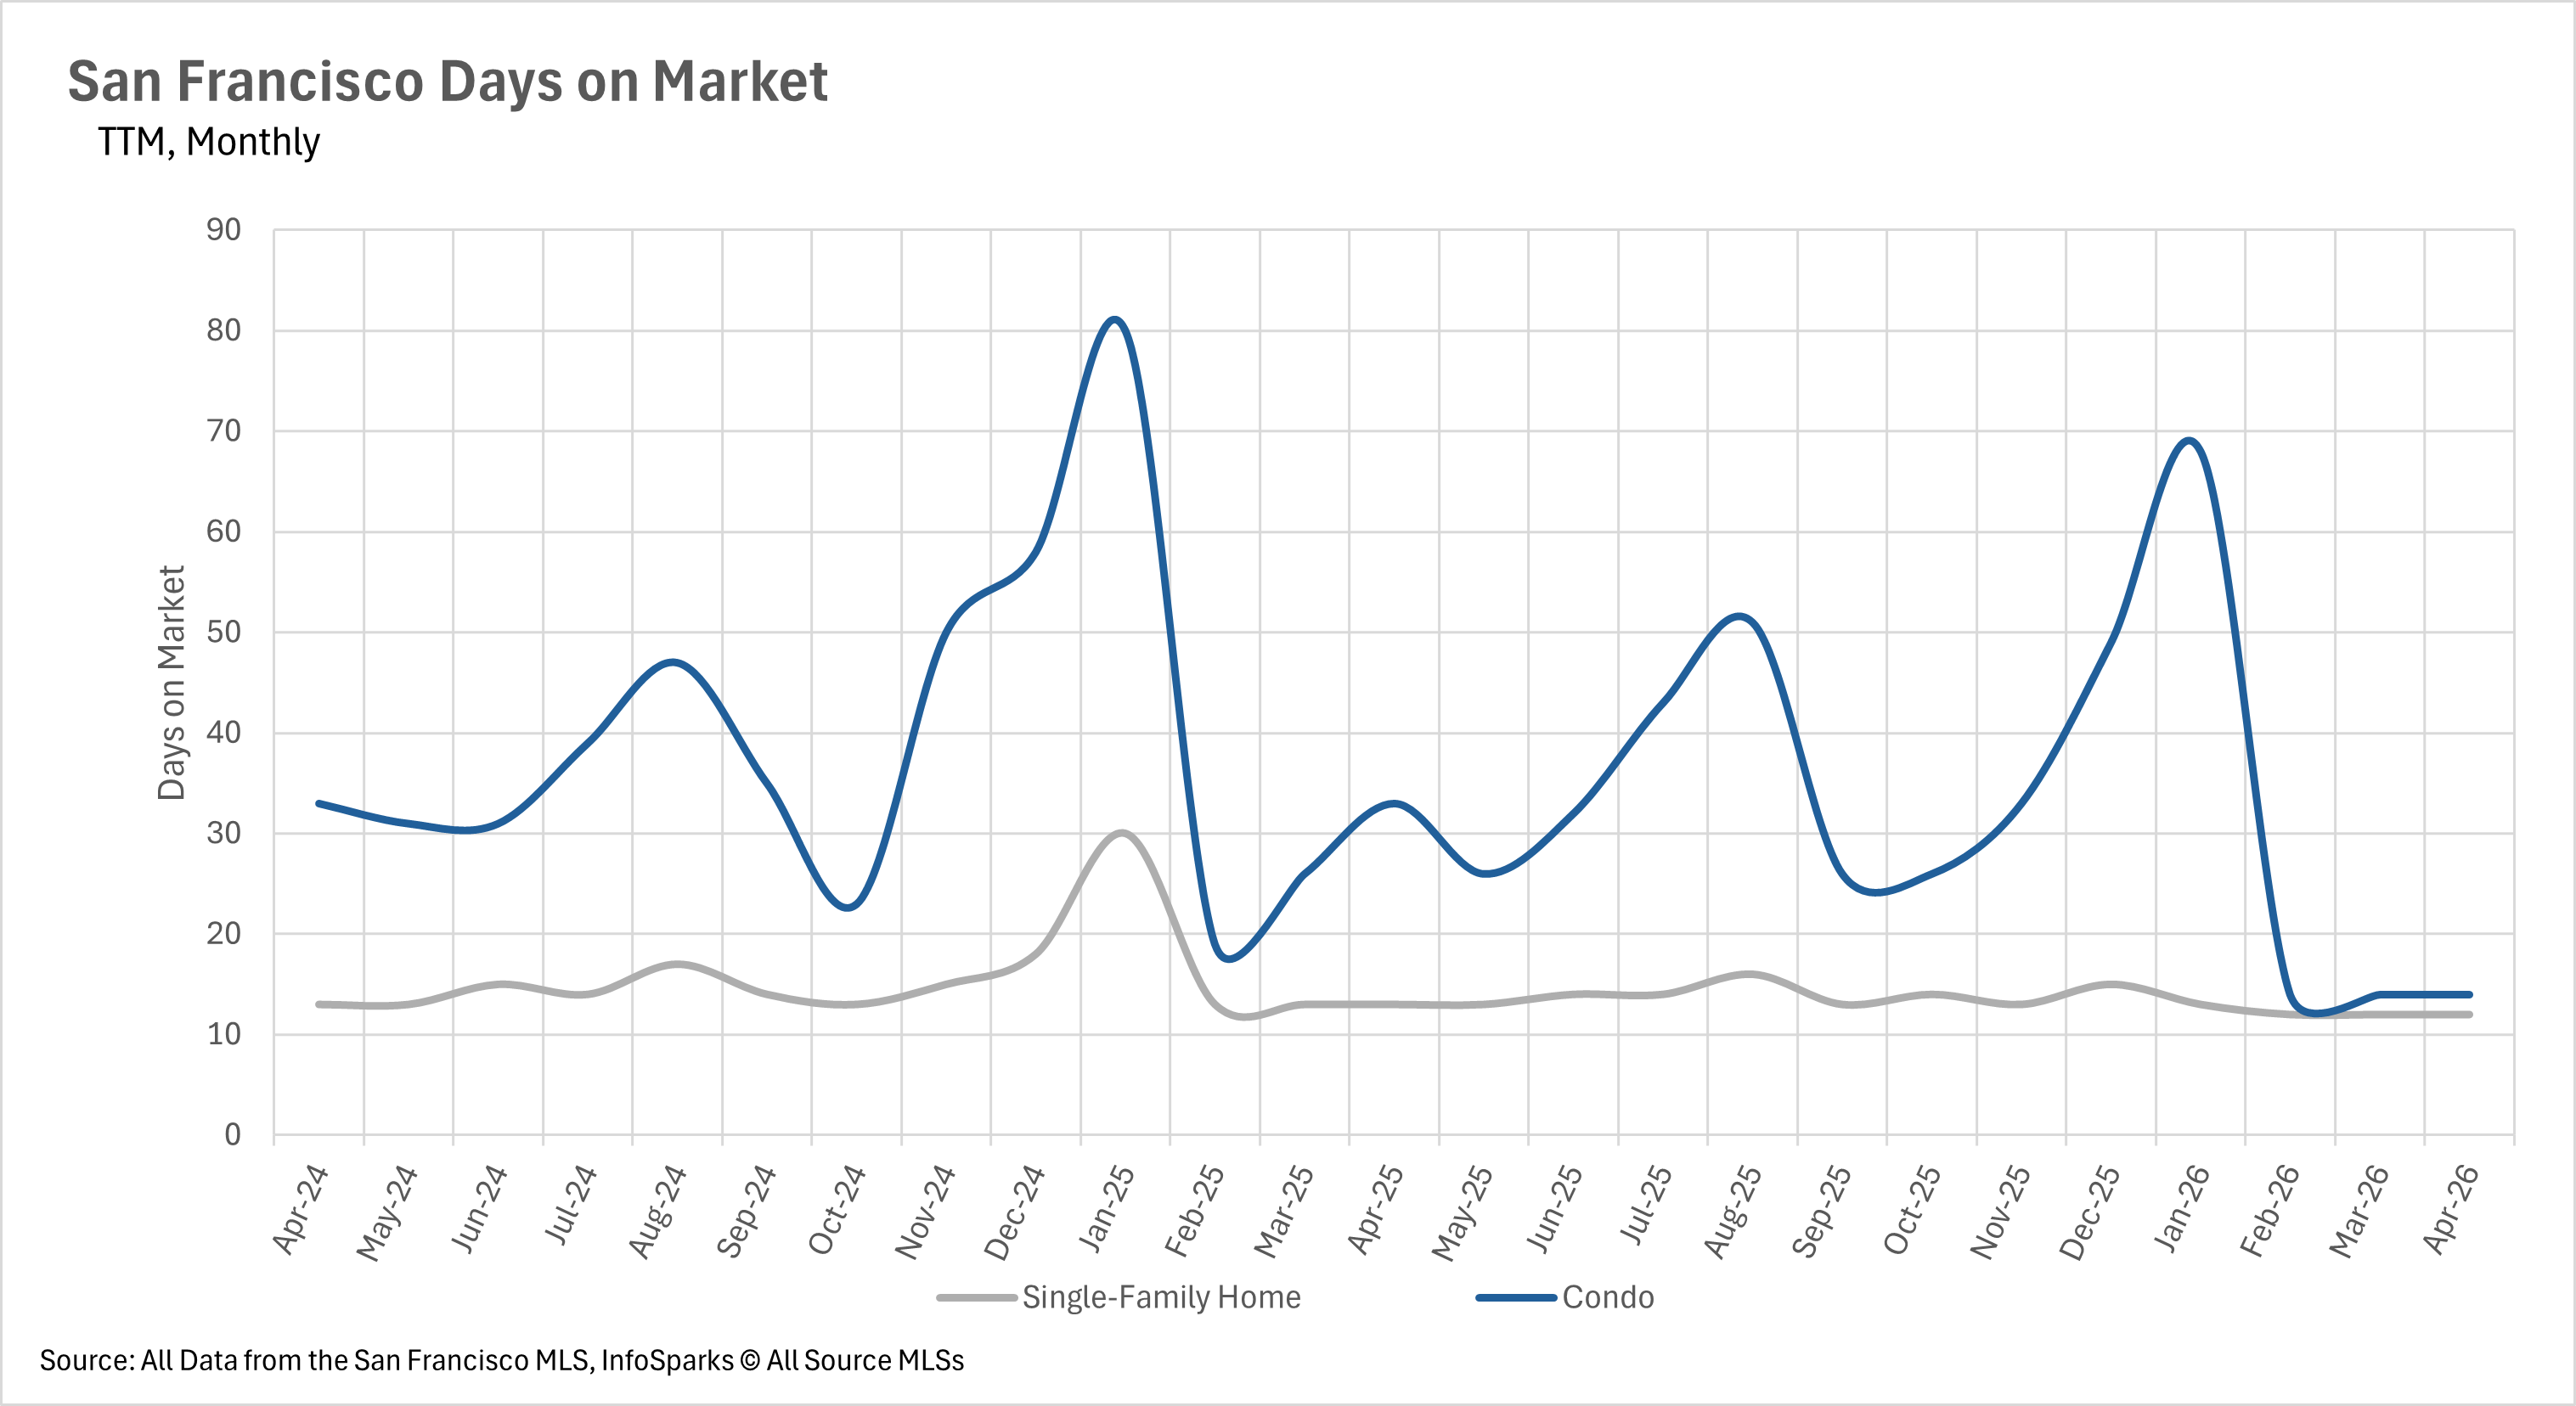
The pace of sales for single-family homes across the Bay Area remains exceptional. In Santa Clara County, the average home is selling in just 9 days. San Mateo County homes are moving in 11 days, San Francisco single-family homes in 12 days, and Marin County homes in just 13 days. East Bay listings are closing in 13 days in both Alameda and Contra Costa Counties, while Sonoma and Solano Counties are both clocking in at 26 days. These figures are largely unchanged from a year ago, demonstrating the sustained strength of buyer demand.
 
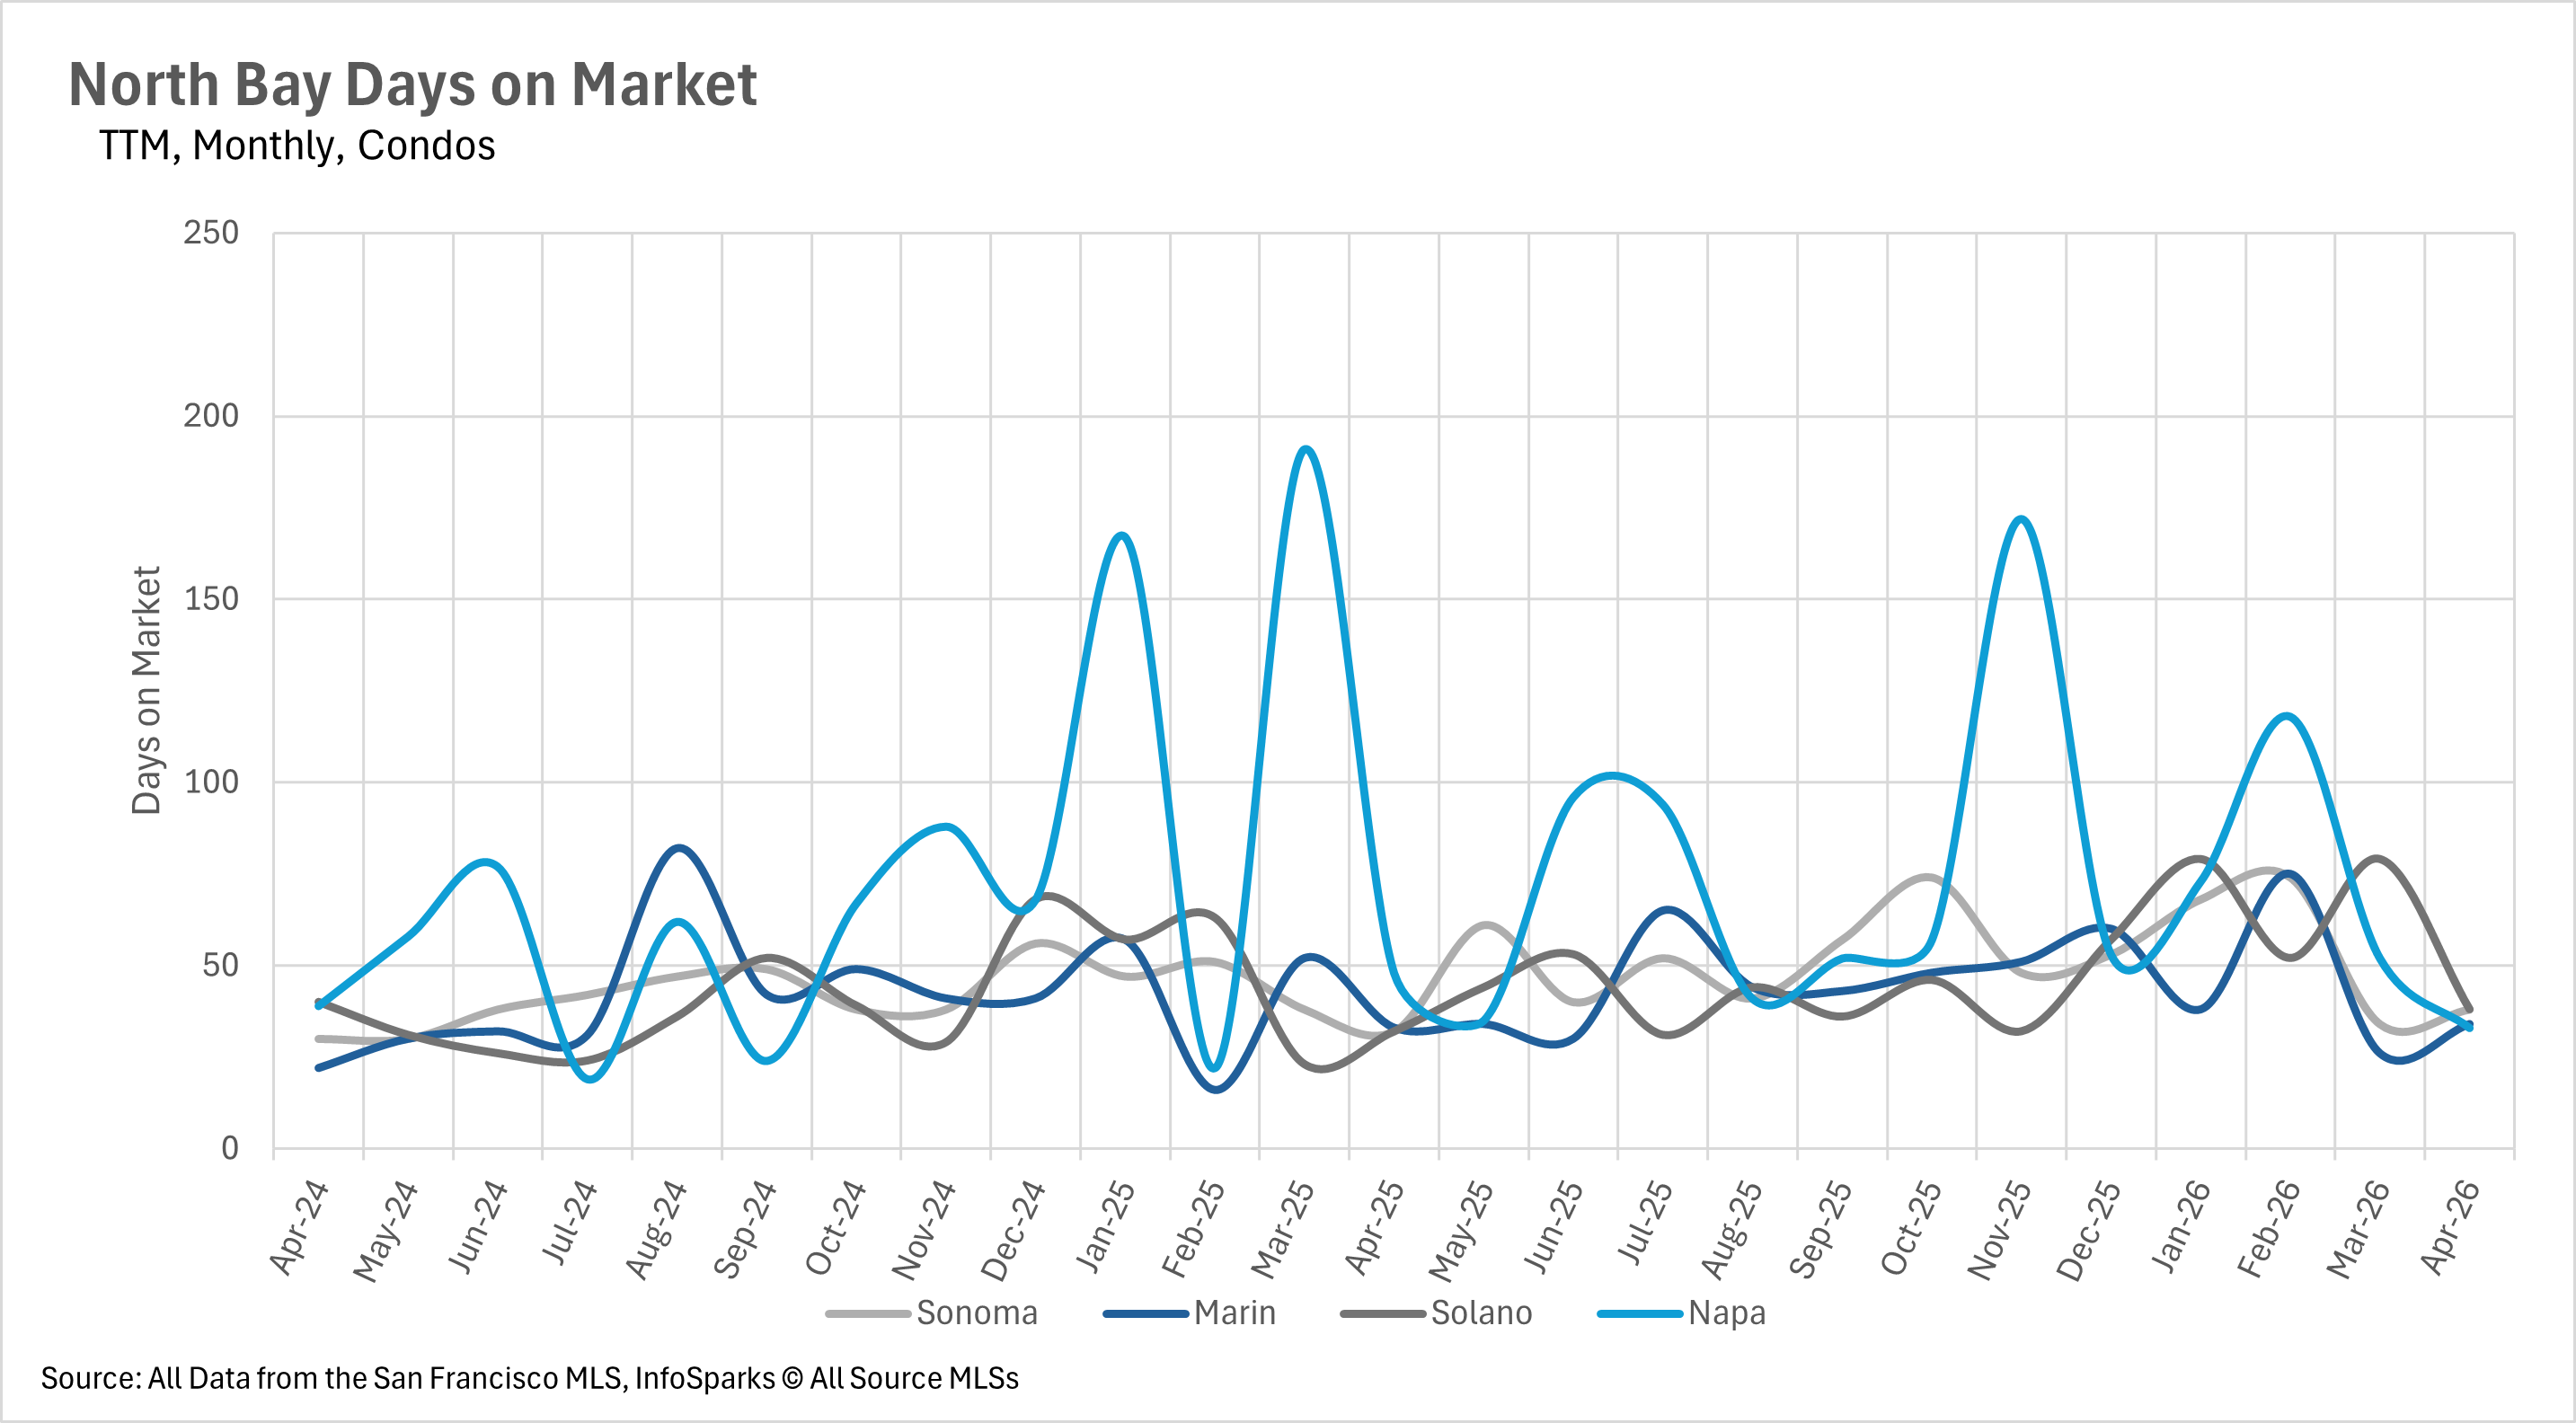
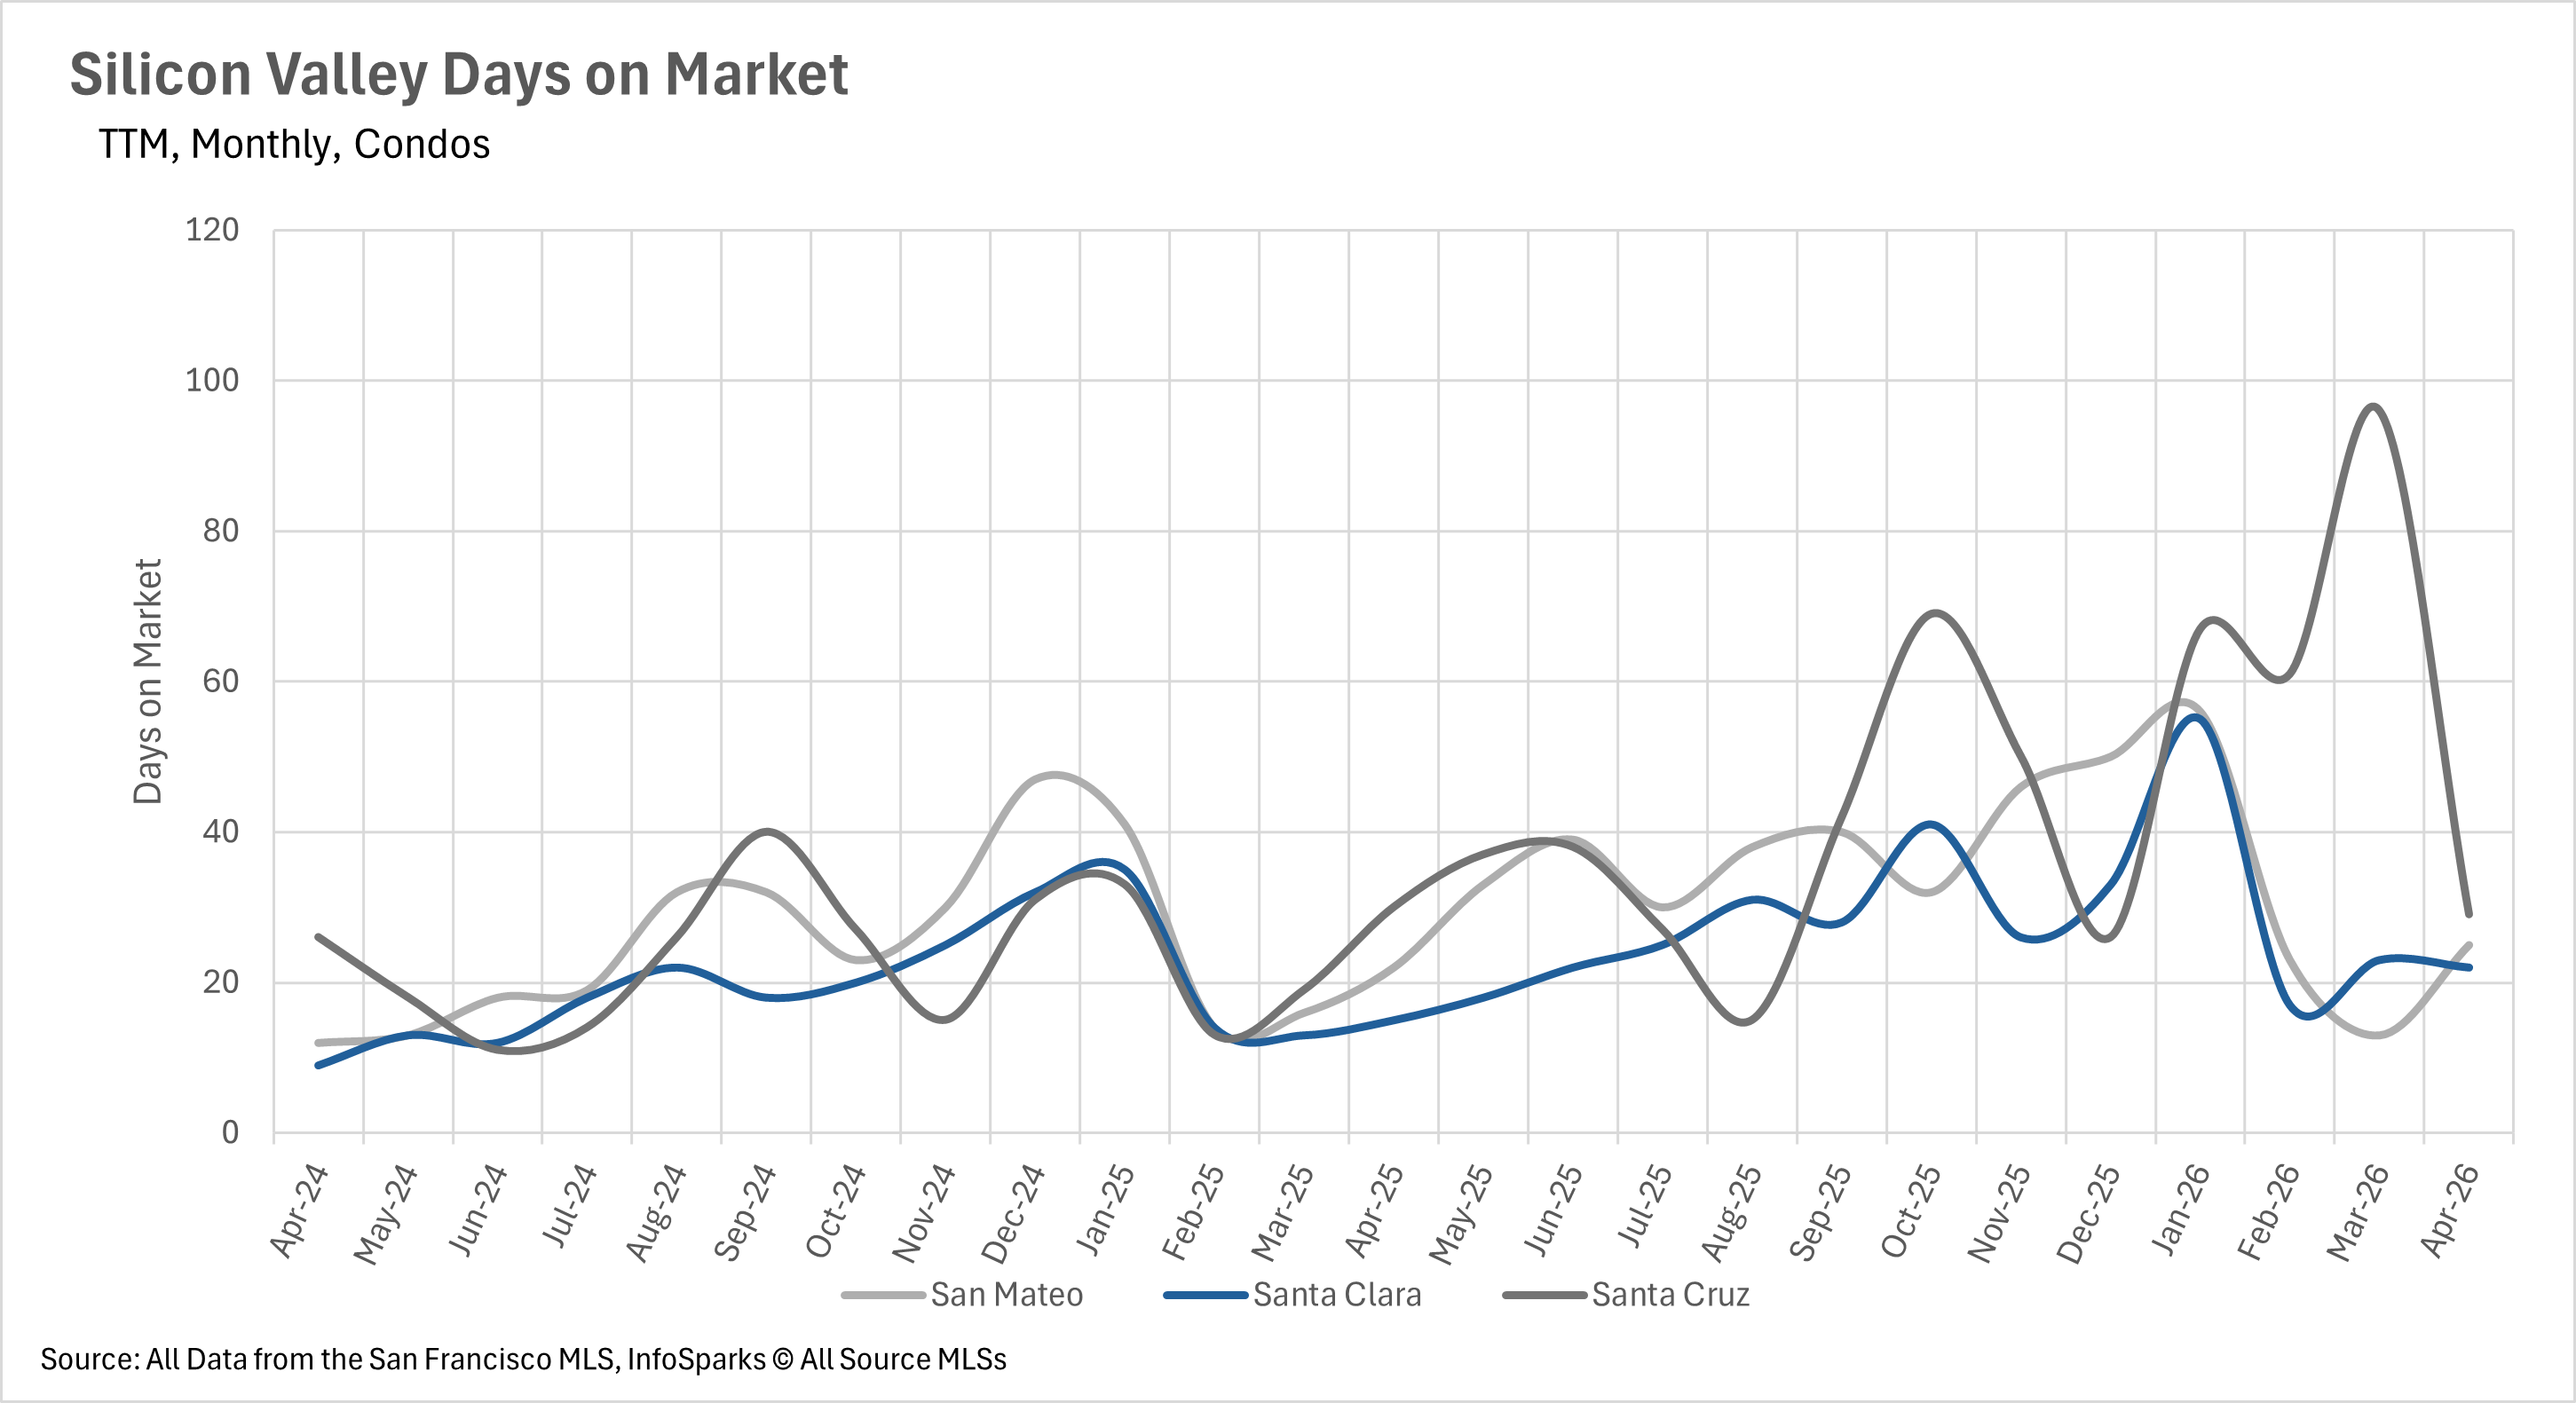
The condo market is a more complicated picture. San Francisco condos have seen one of the most dramatic transformations, selling in just 14 days compared to 33 days last April, a 57.58% year-over-year decline. However, Santa Clara County condos are spending 46.67% more time on the market than last year, and San Mateo County condos are up 13.64%. The lone bright spot outside of San Francisco is Santa Cruz County, where condo days on market actually improved by 3.33% compared to last April.
Sellers dominate the single-family market while condo buyers gain leverage
When determining whether a market is a buyers' market or a sellers' market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller's market, whereas markets with more than three months of MSI are considered a buyers' market.
 
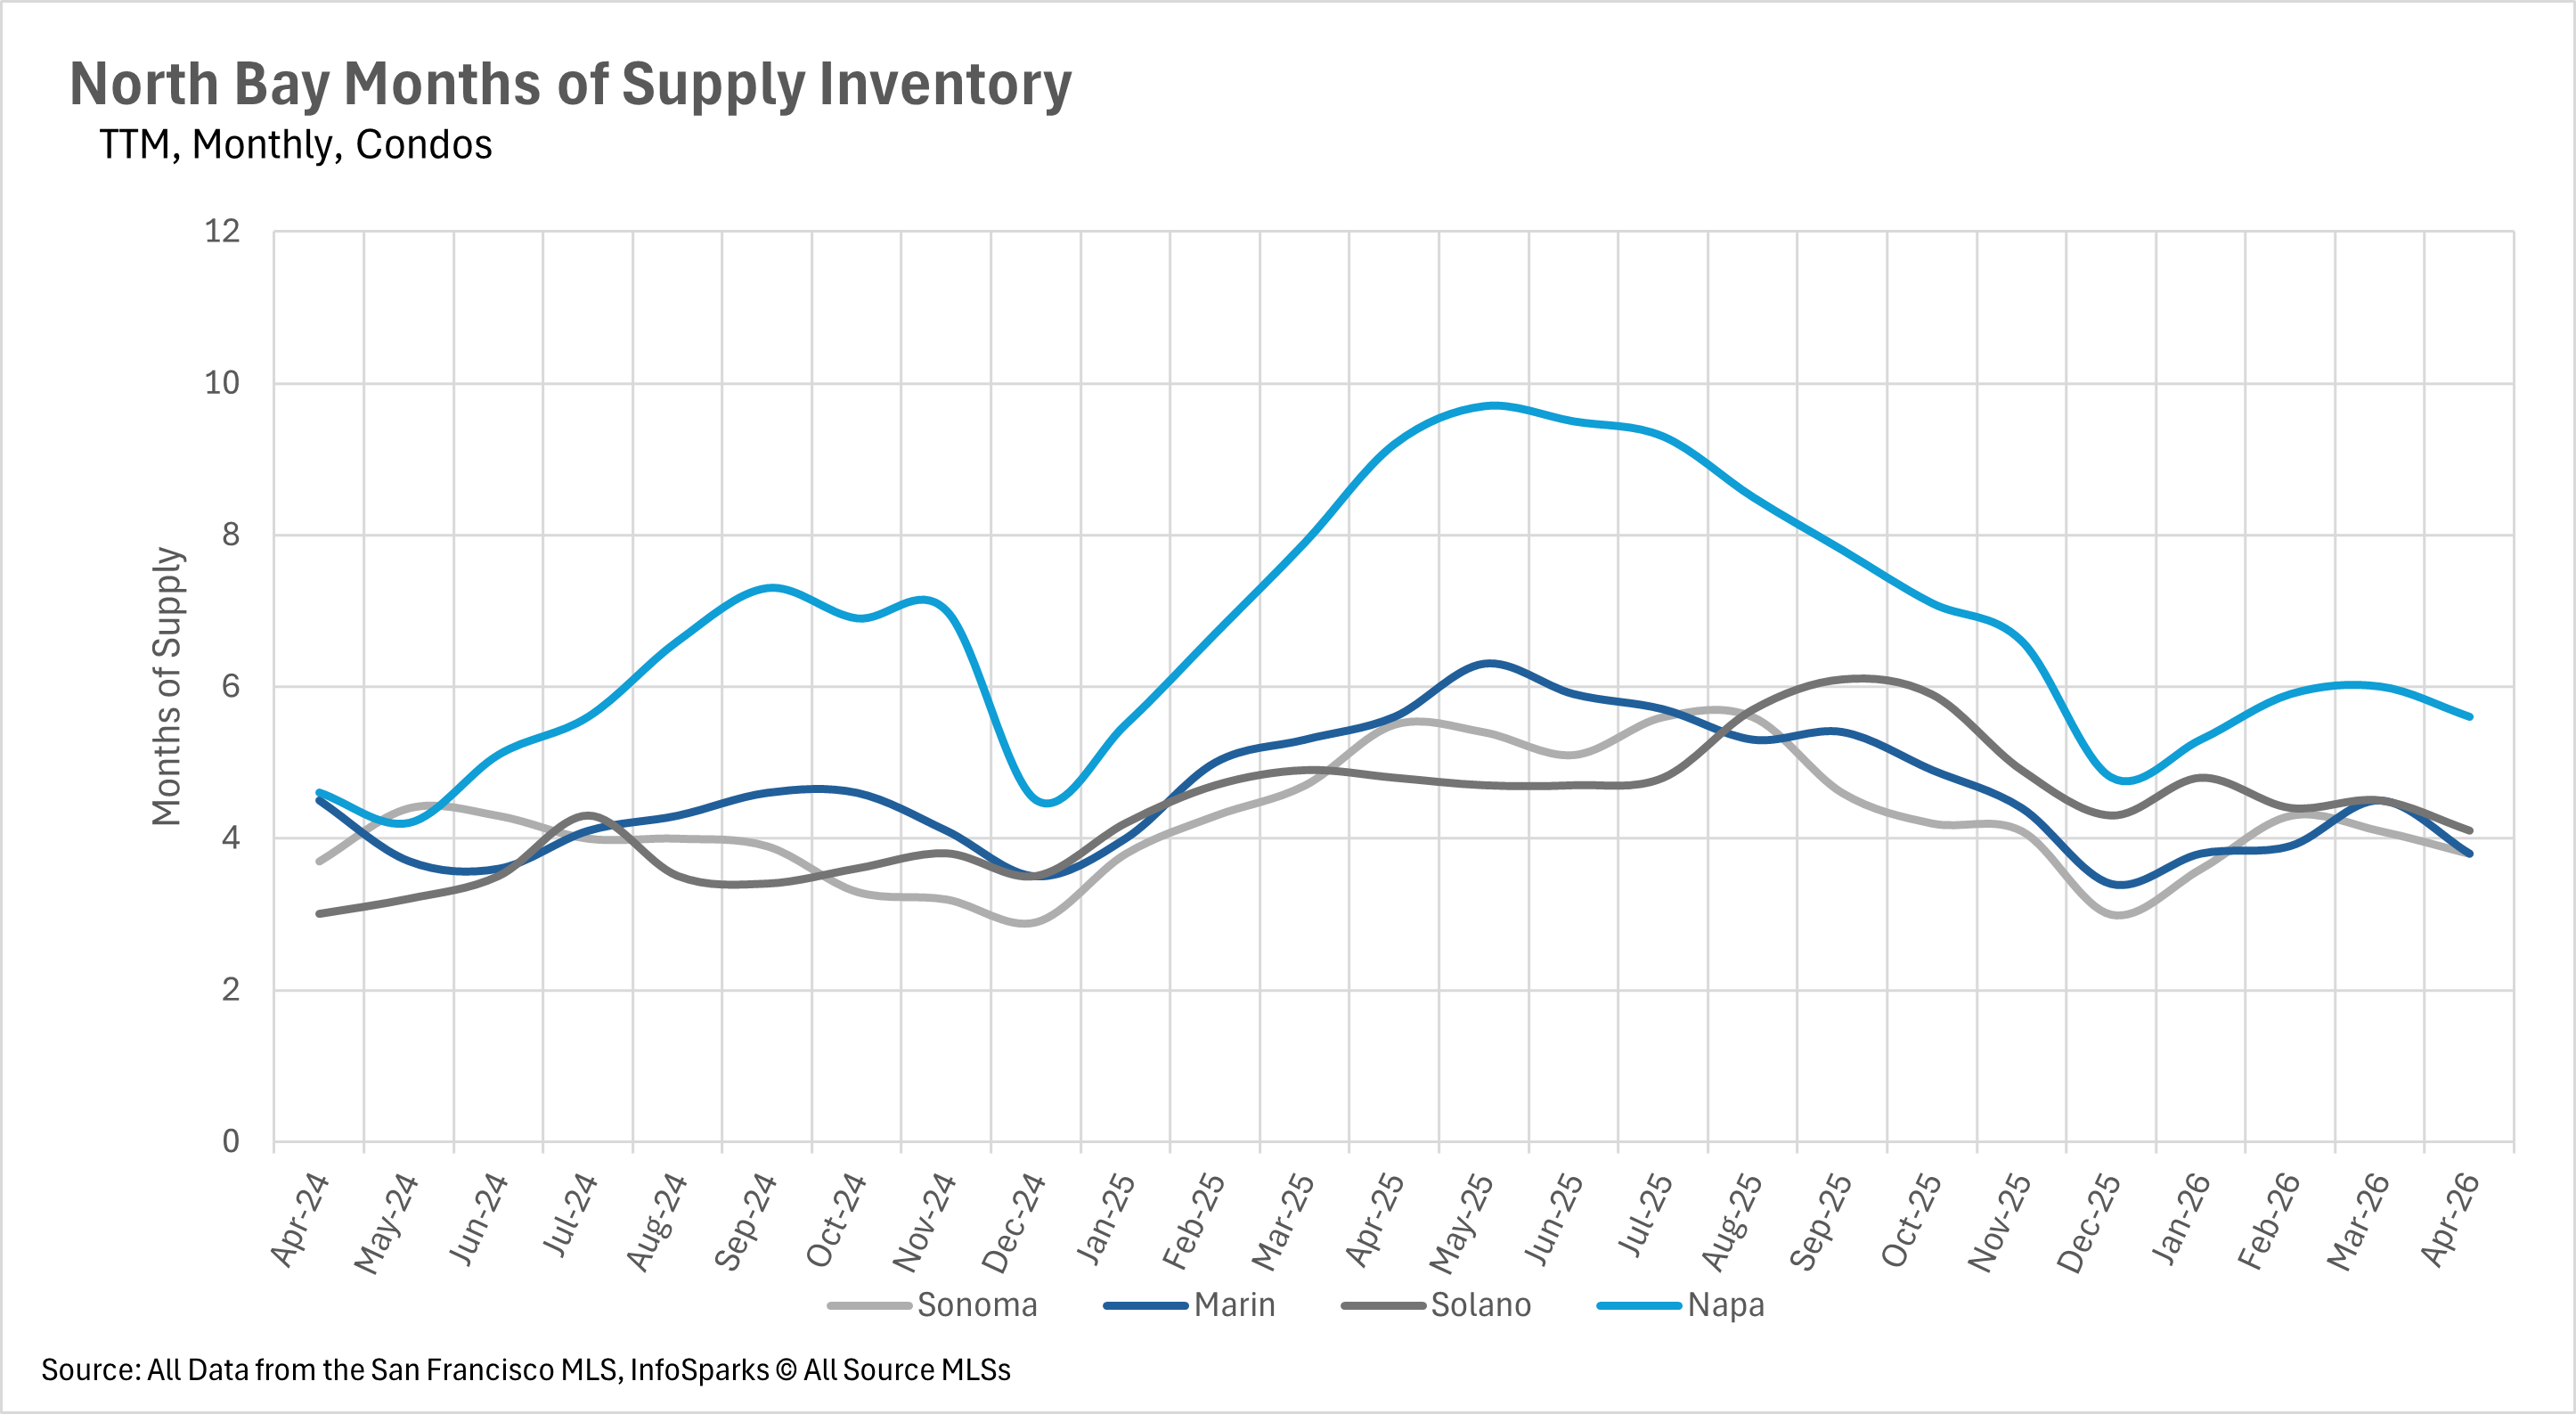
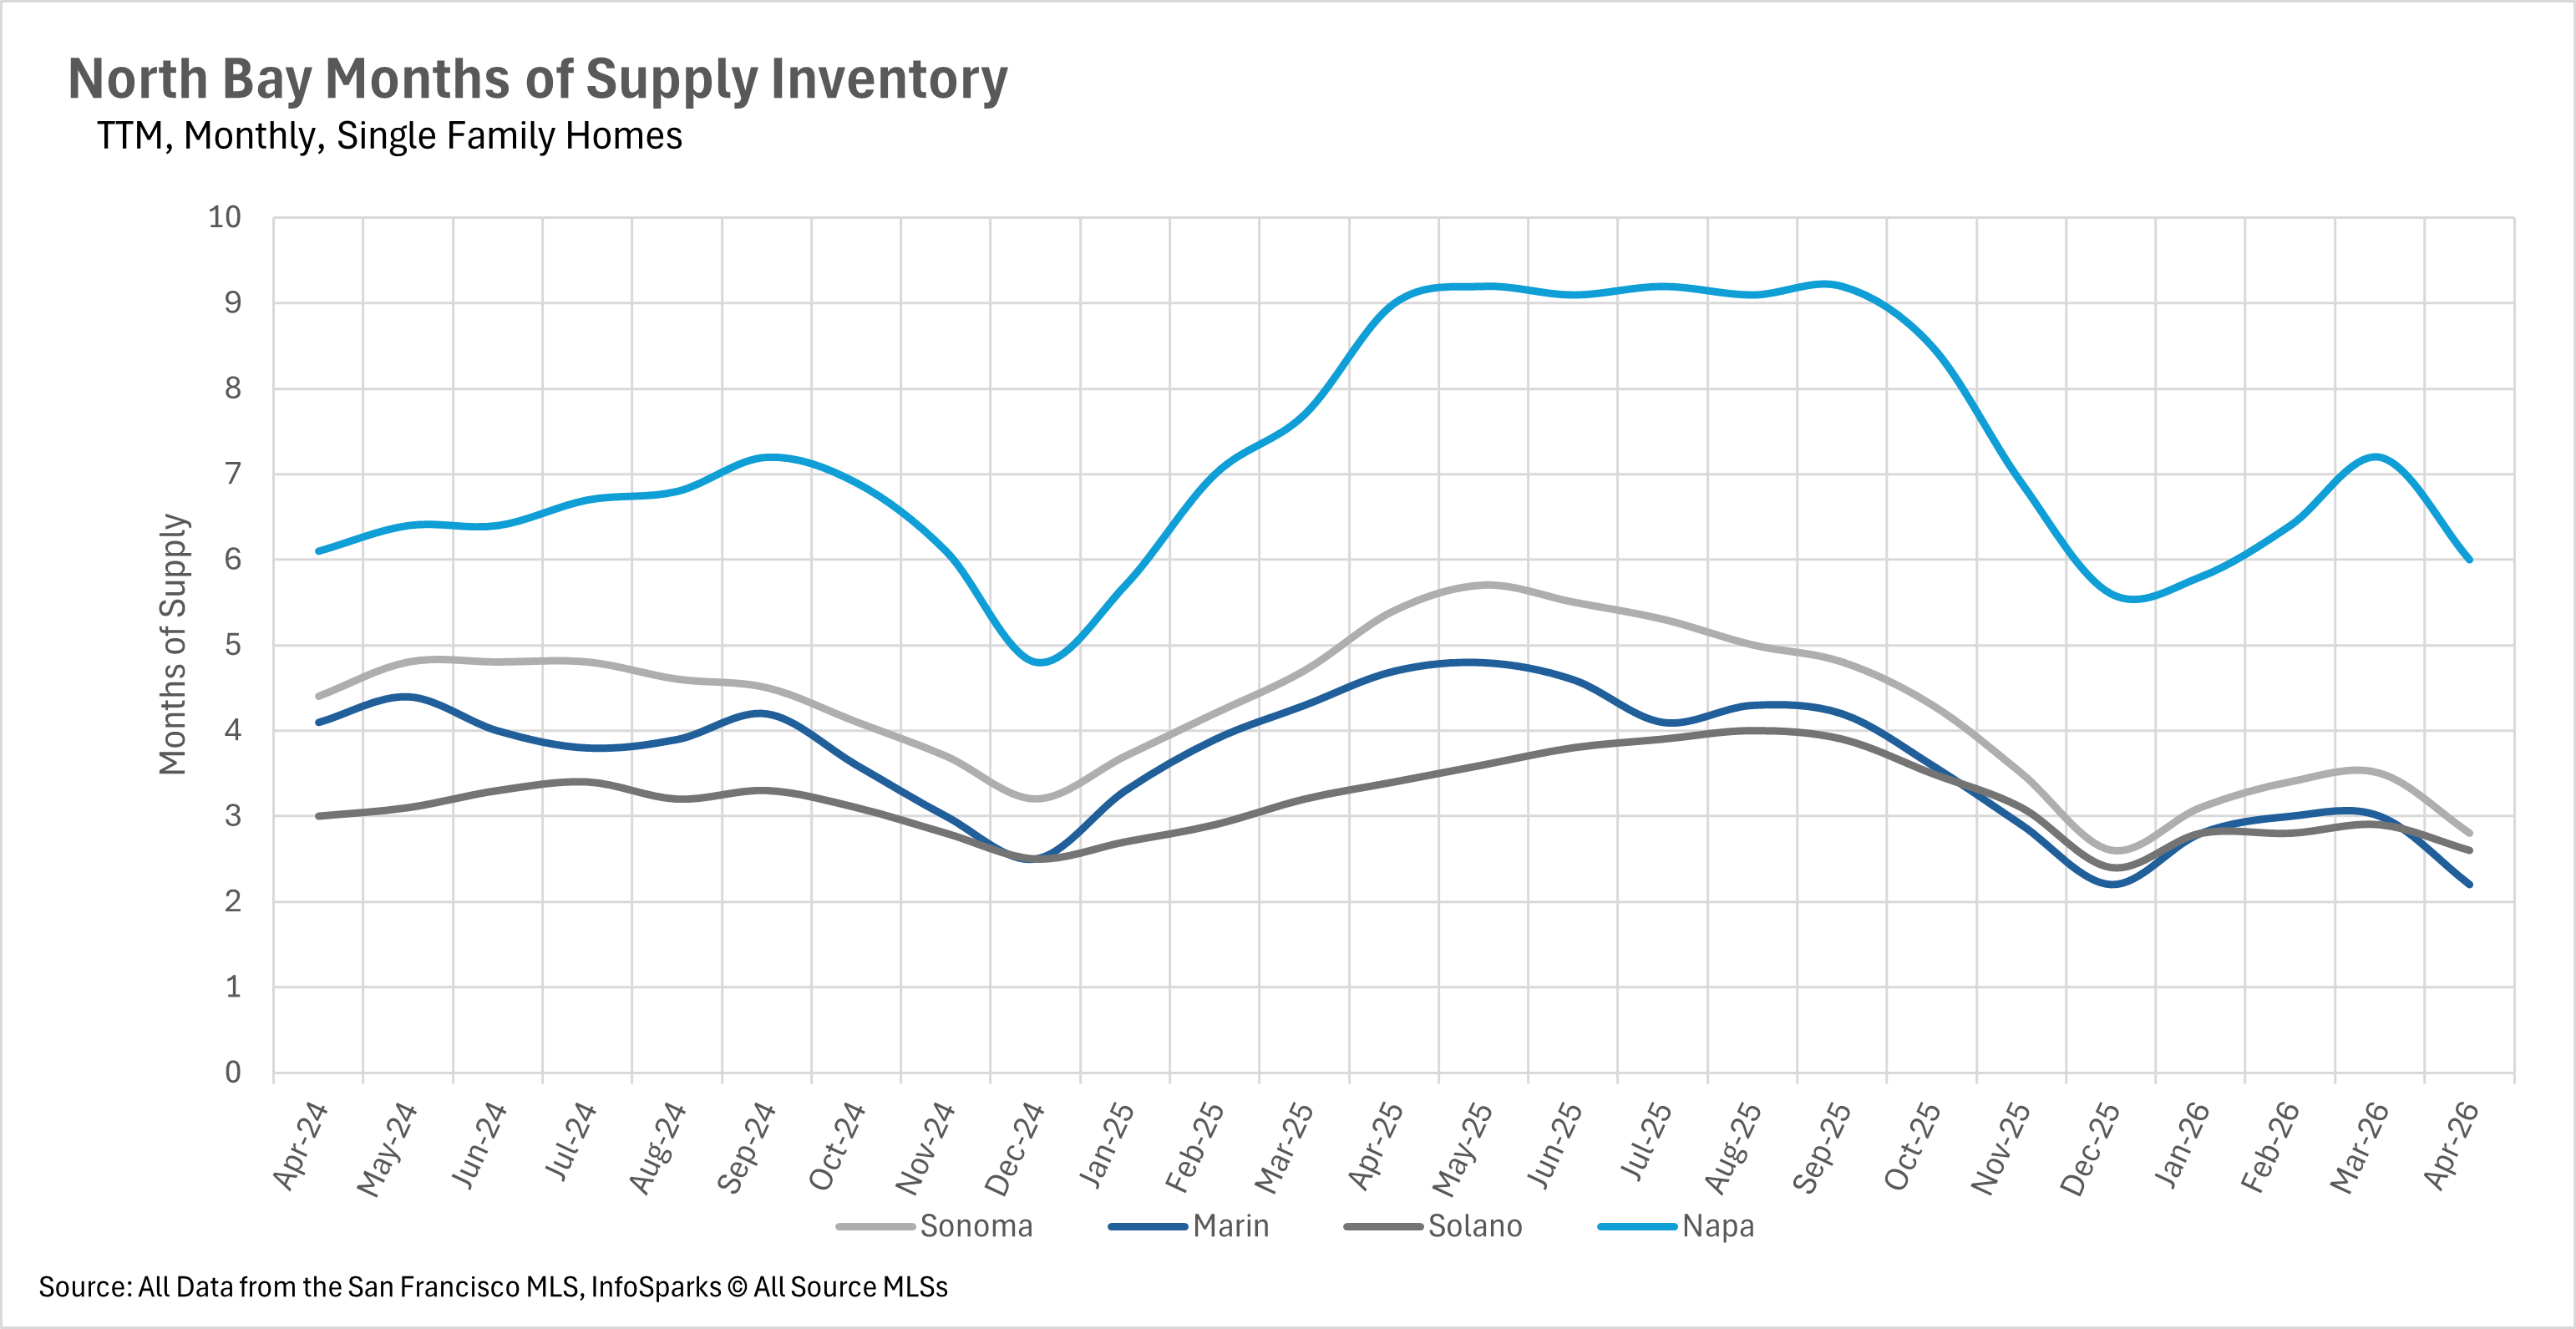
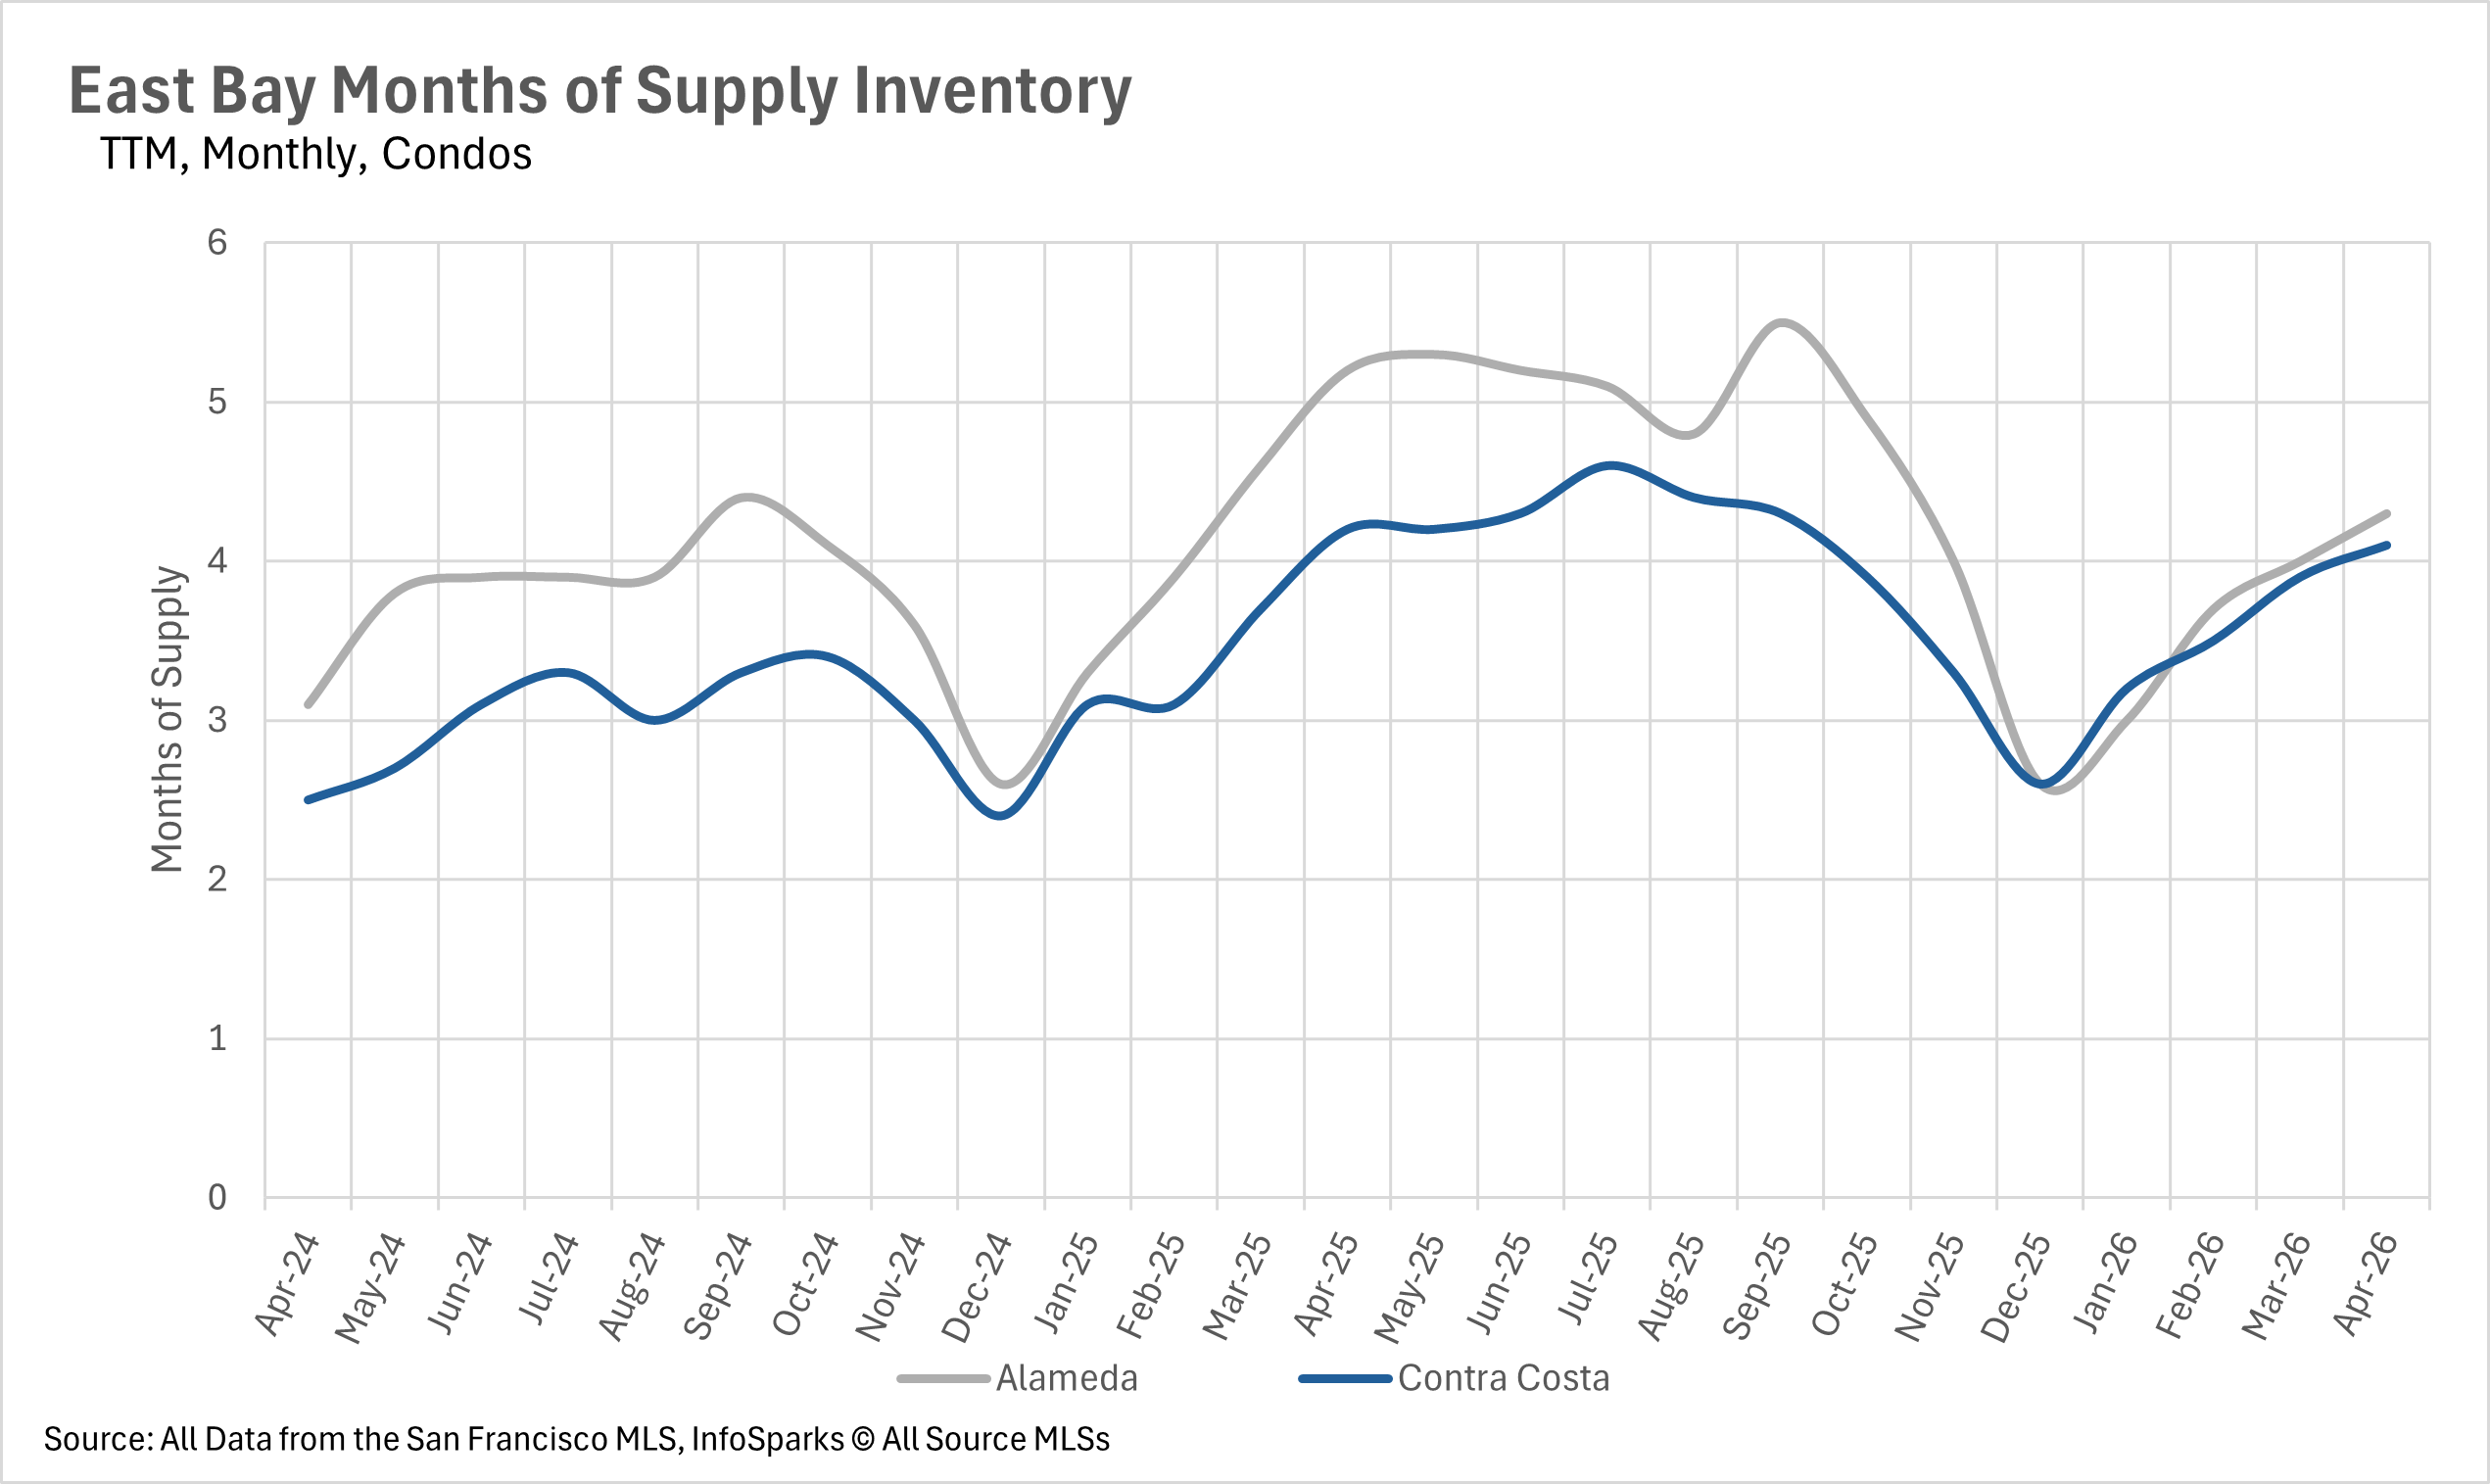
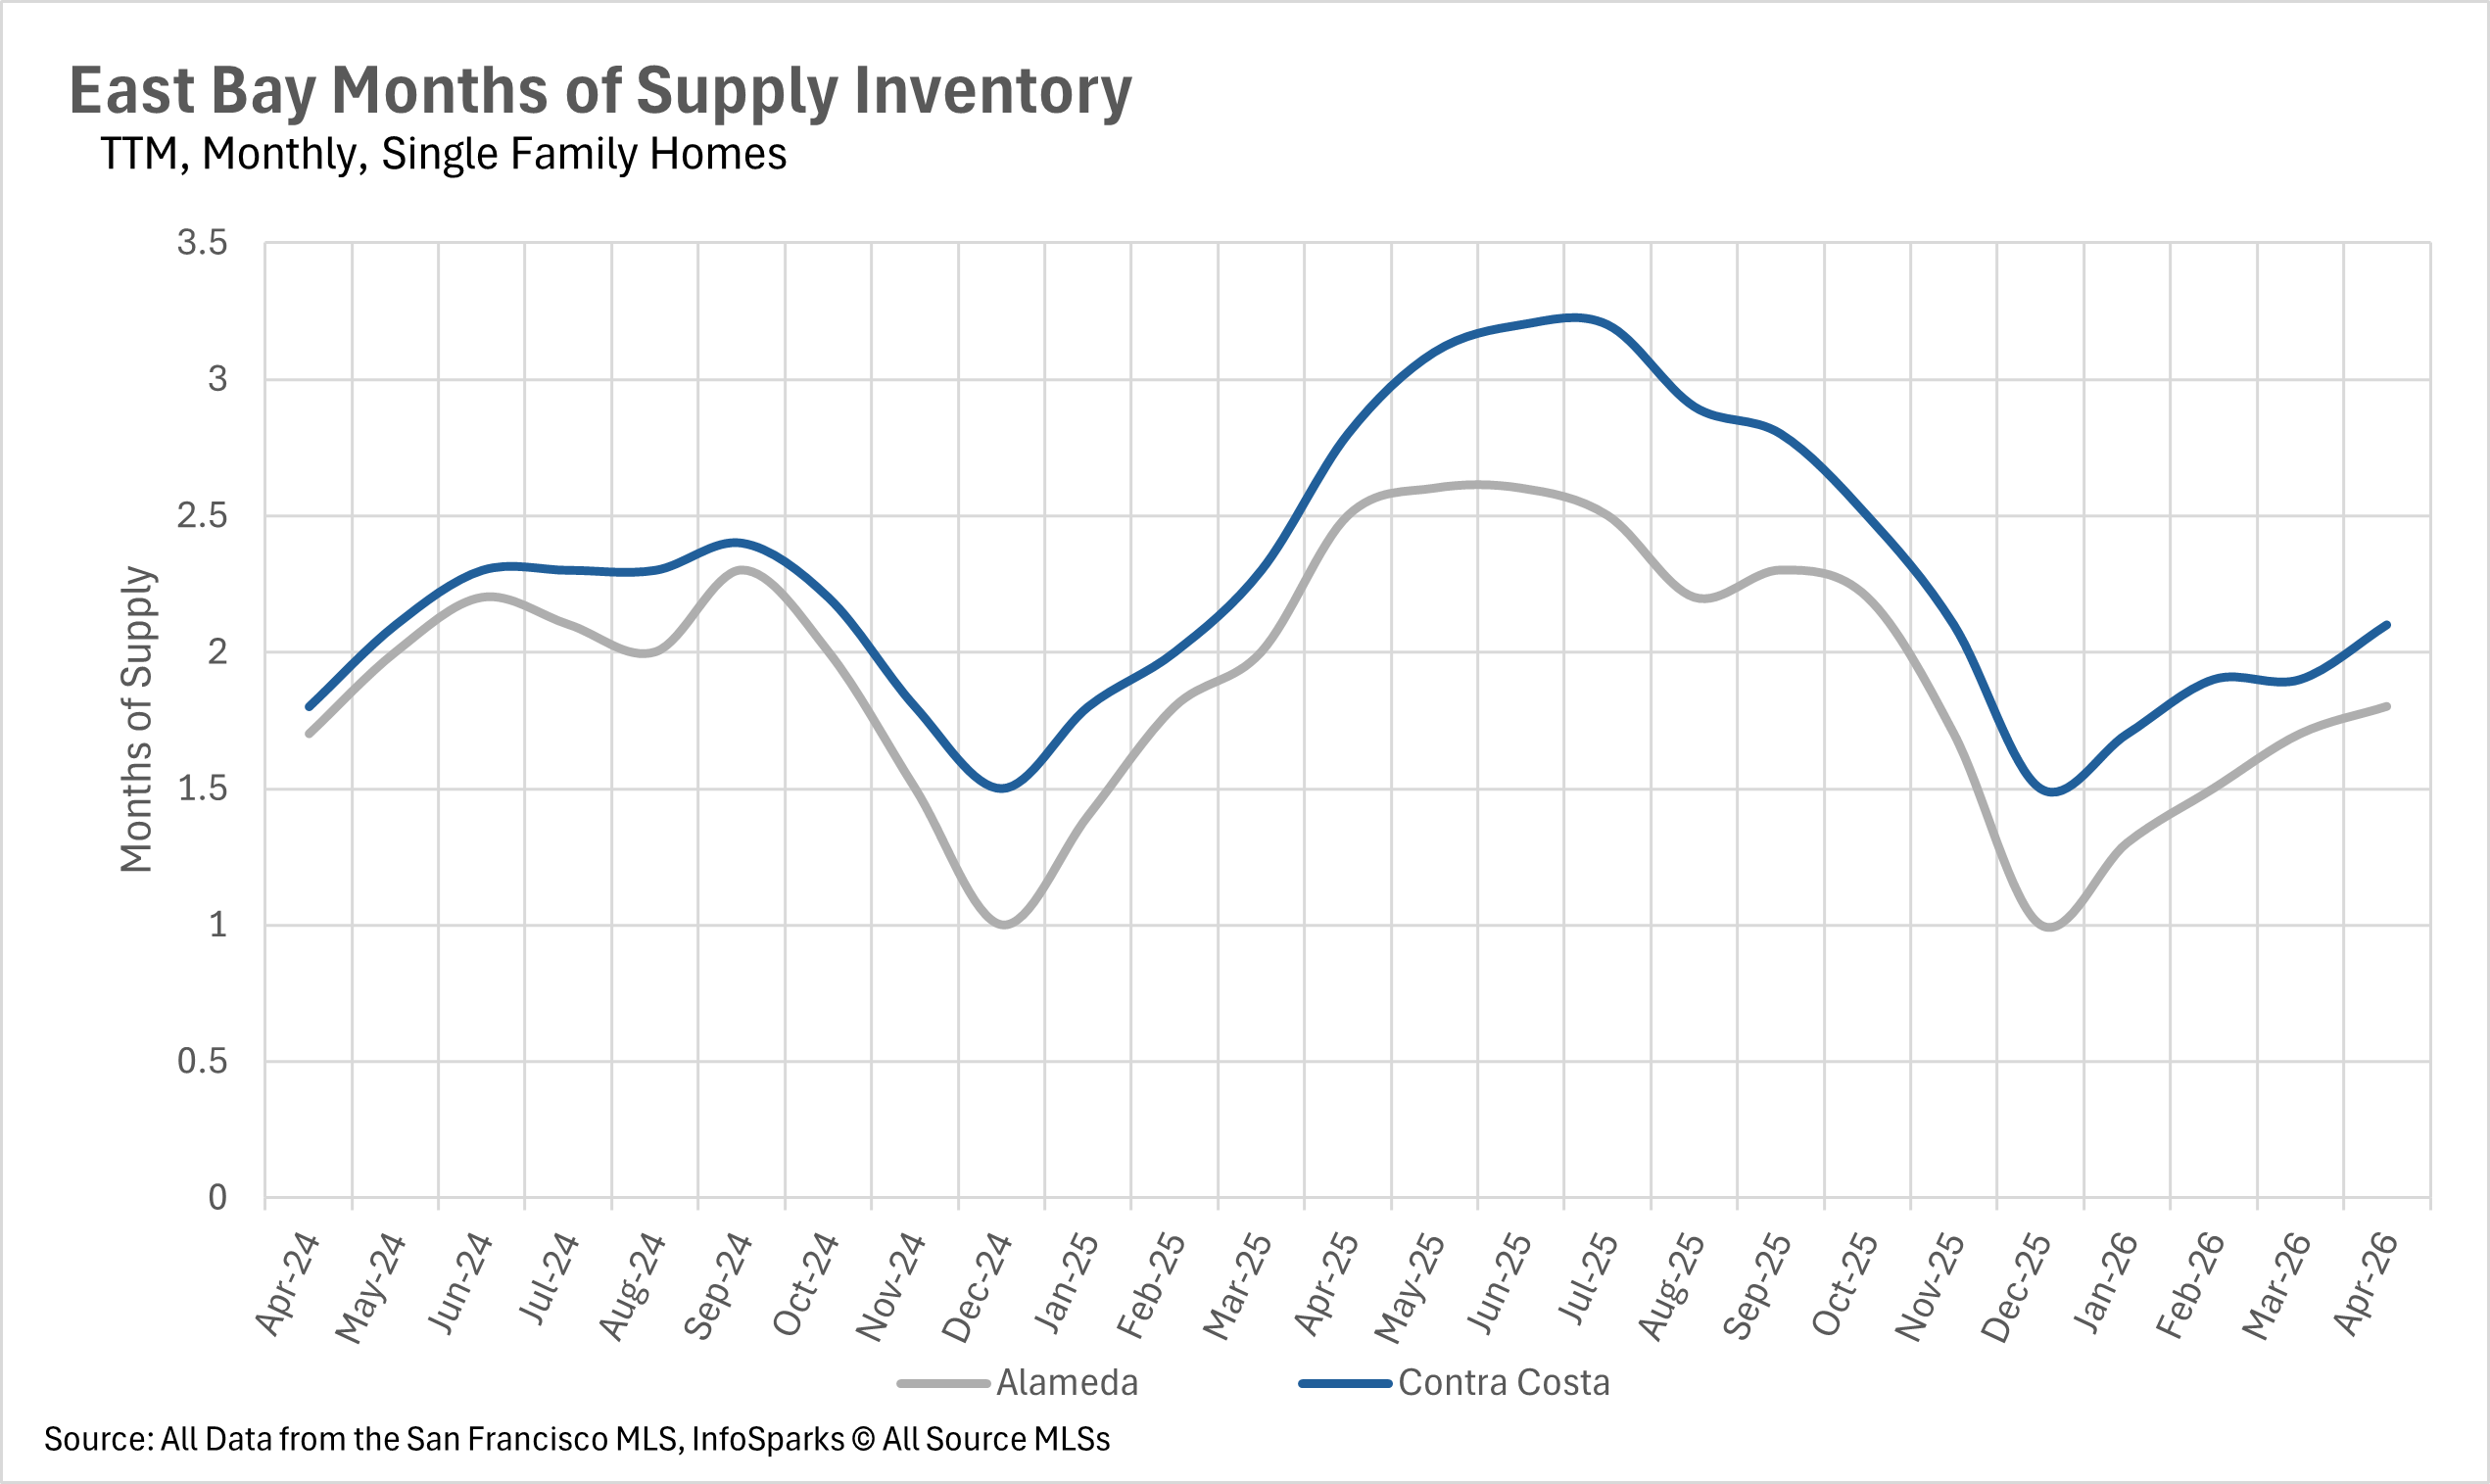
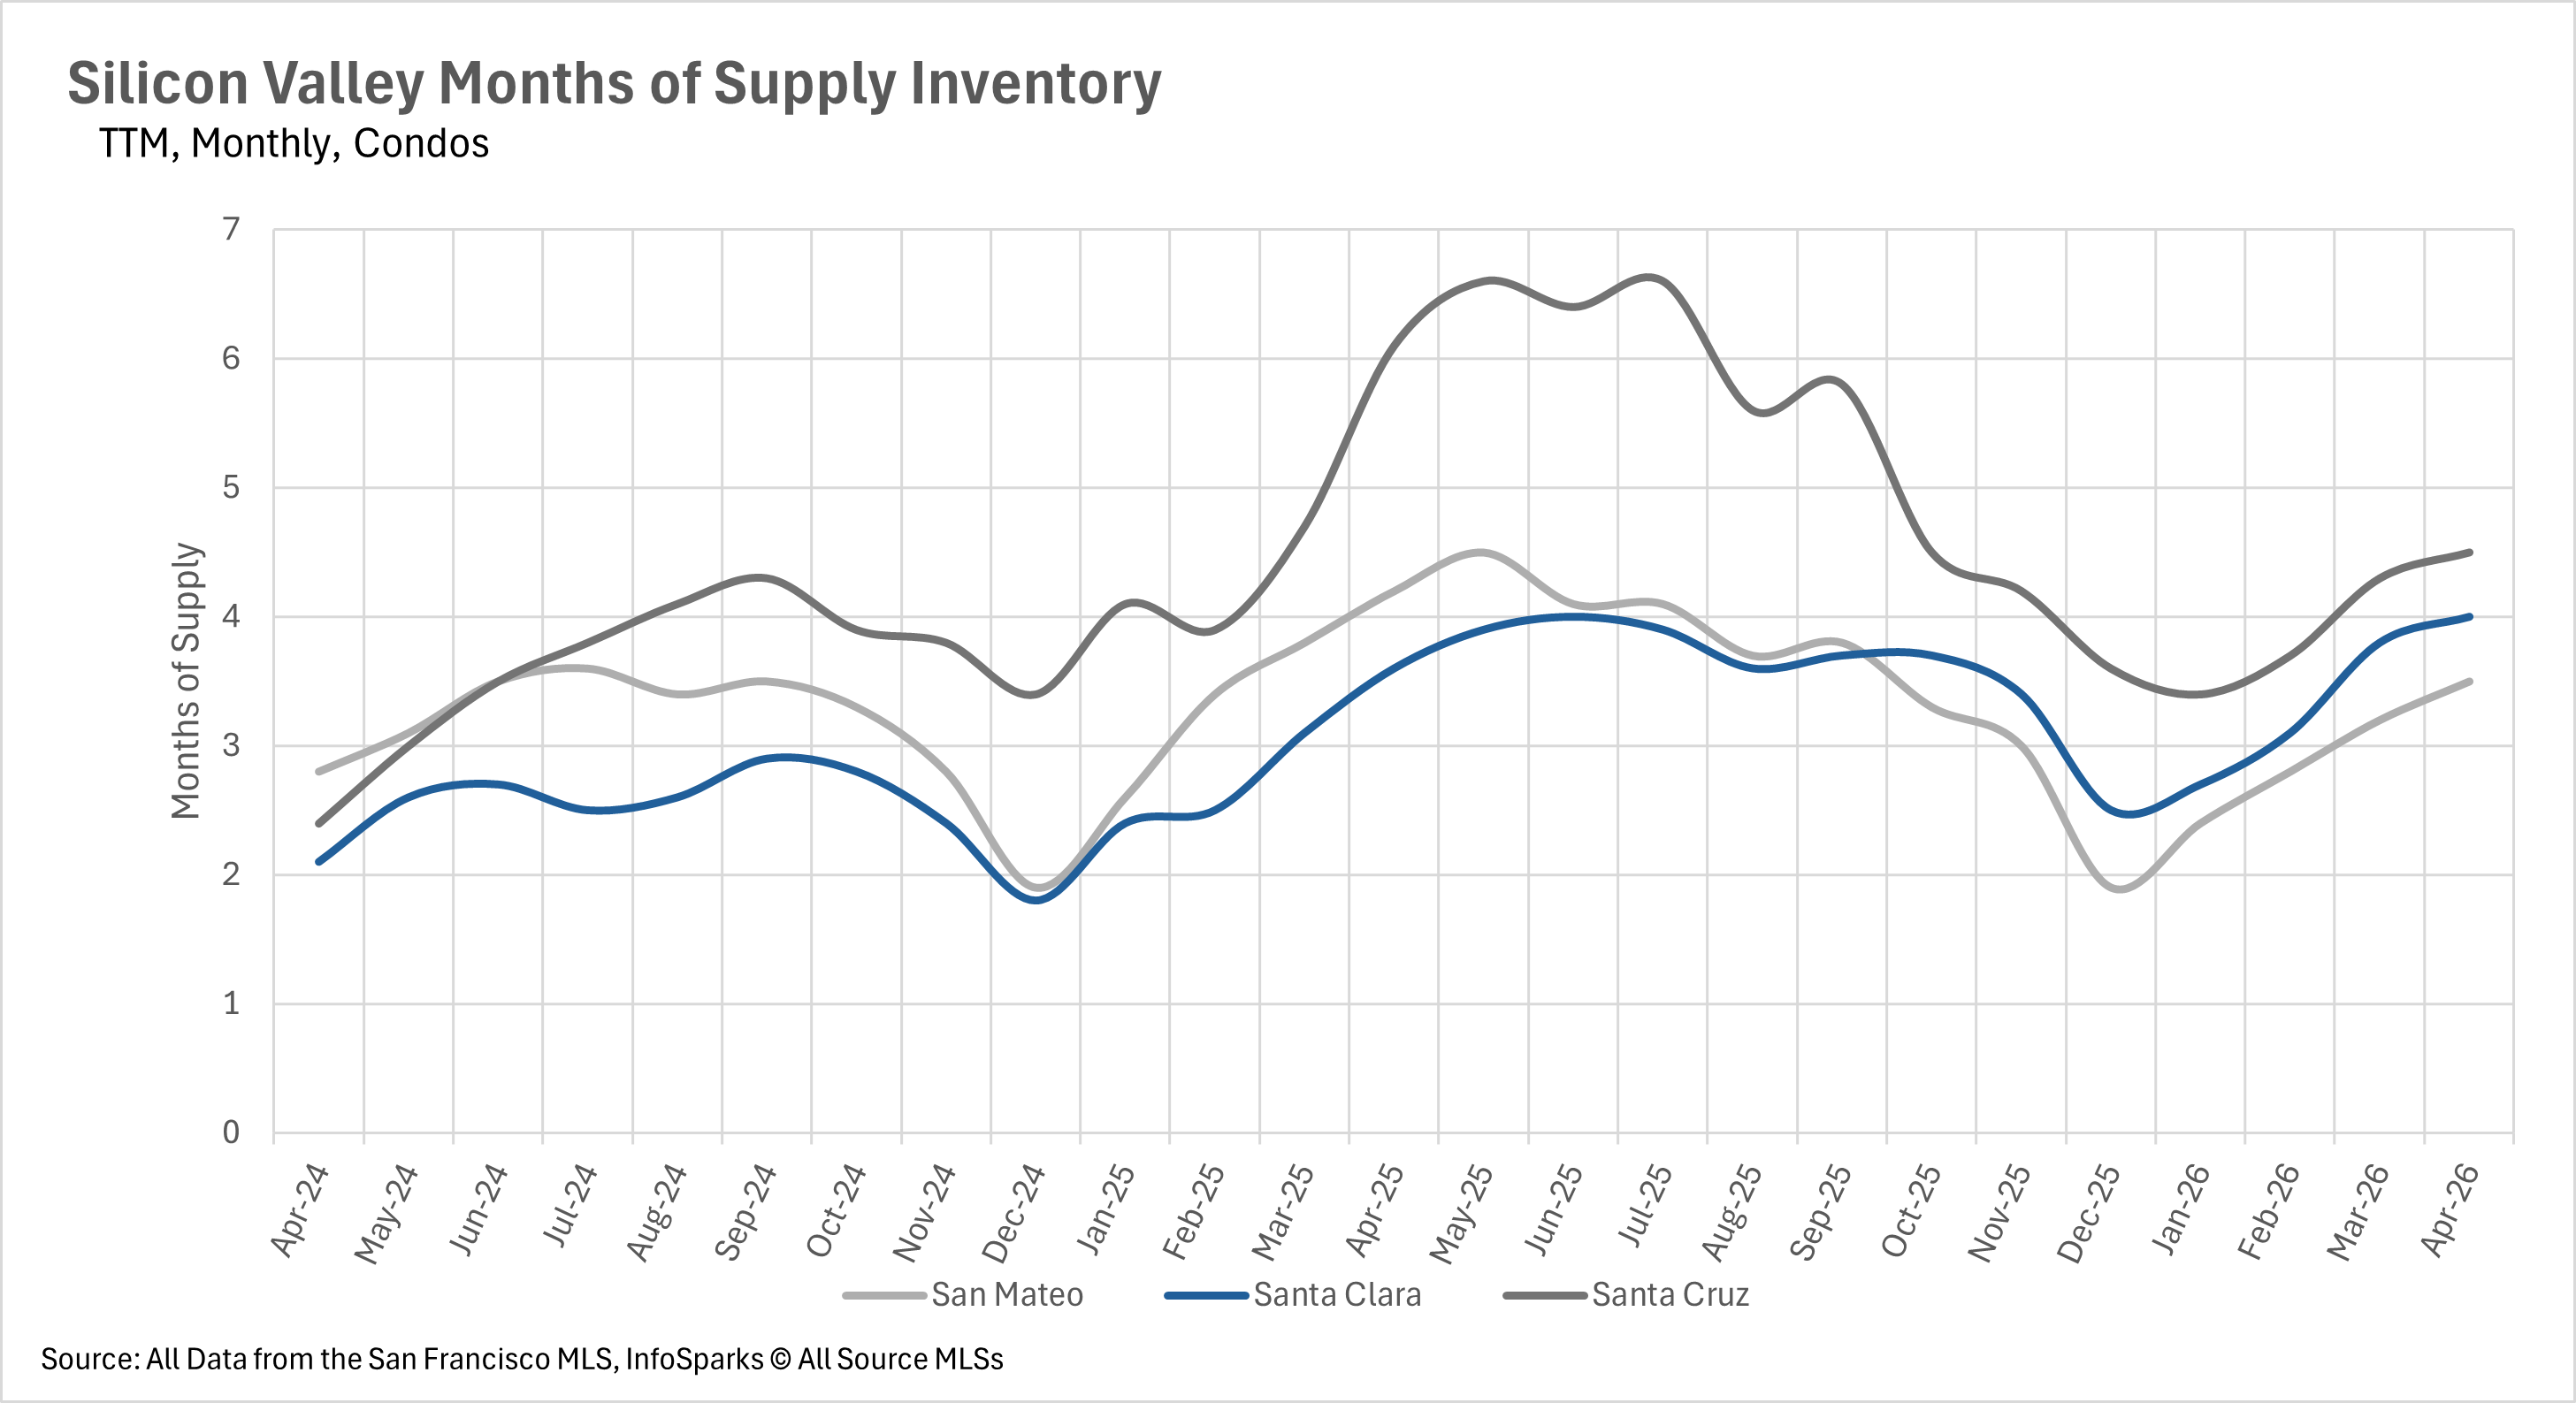
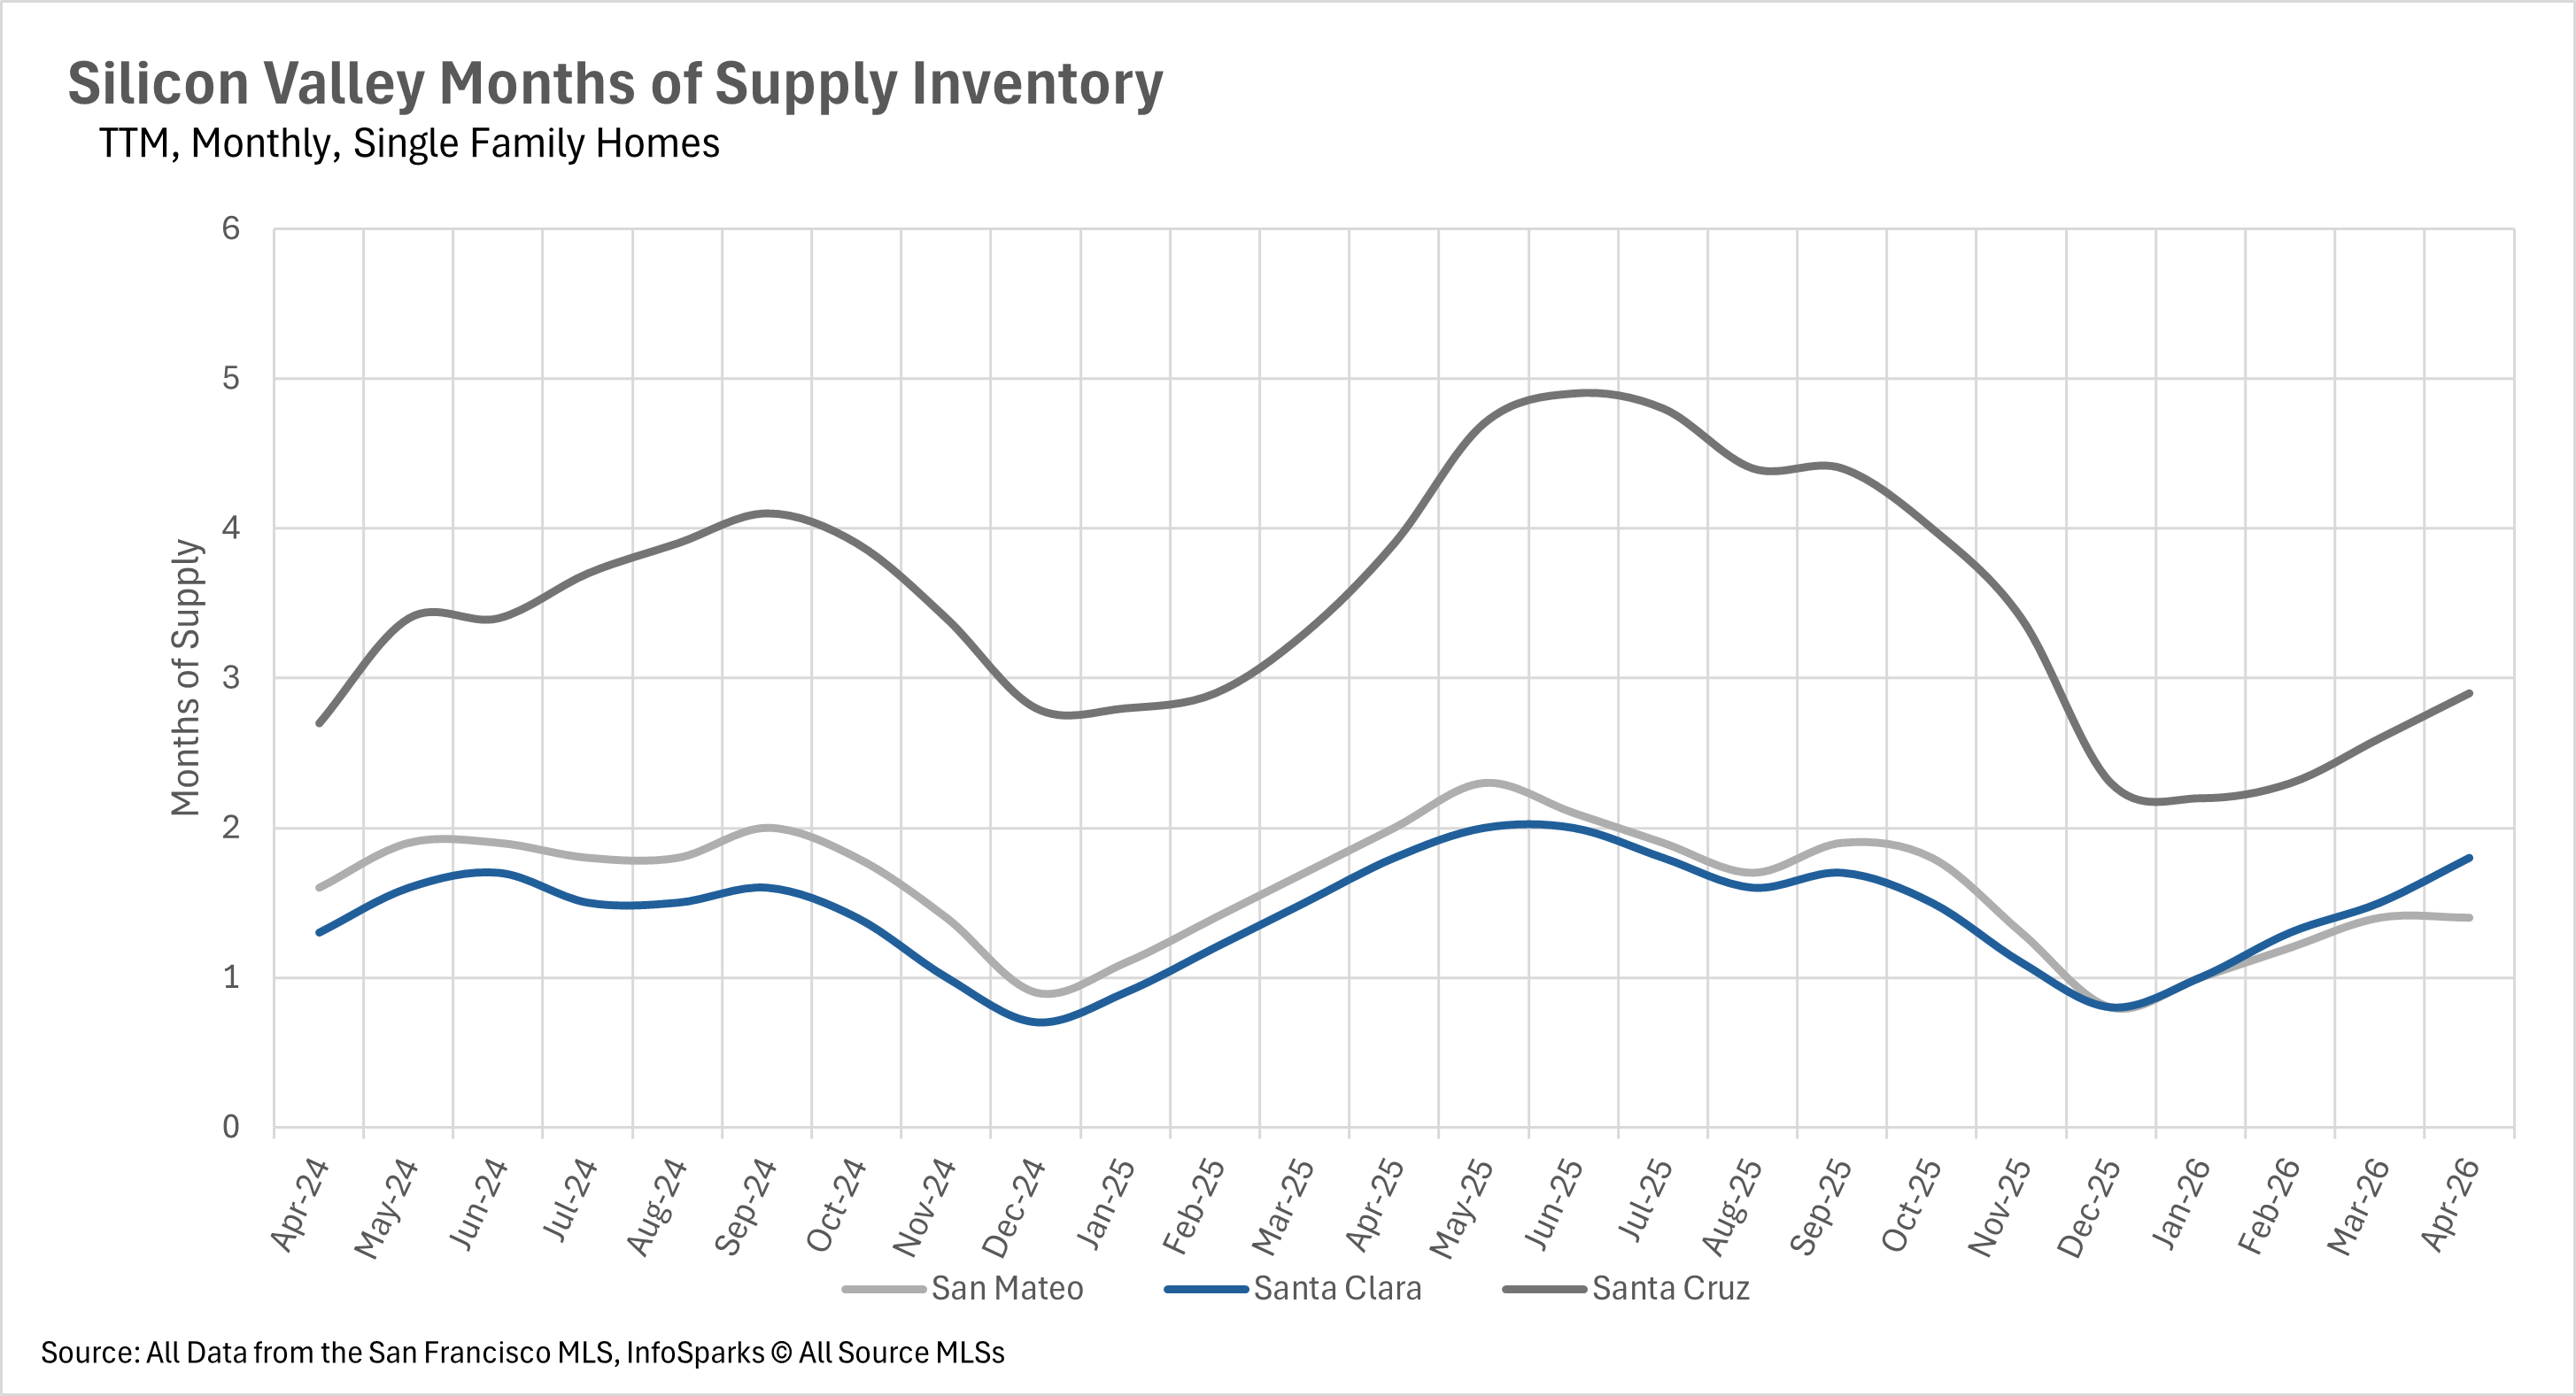
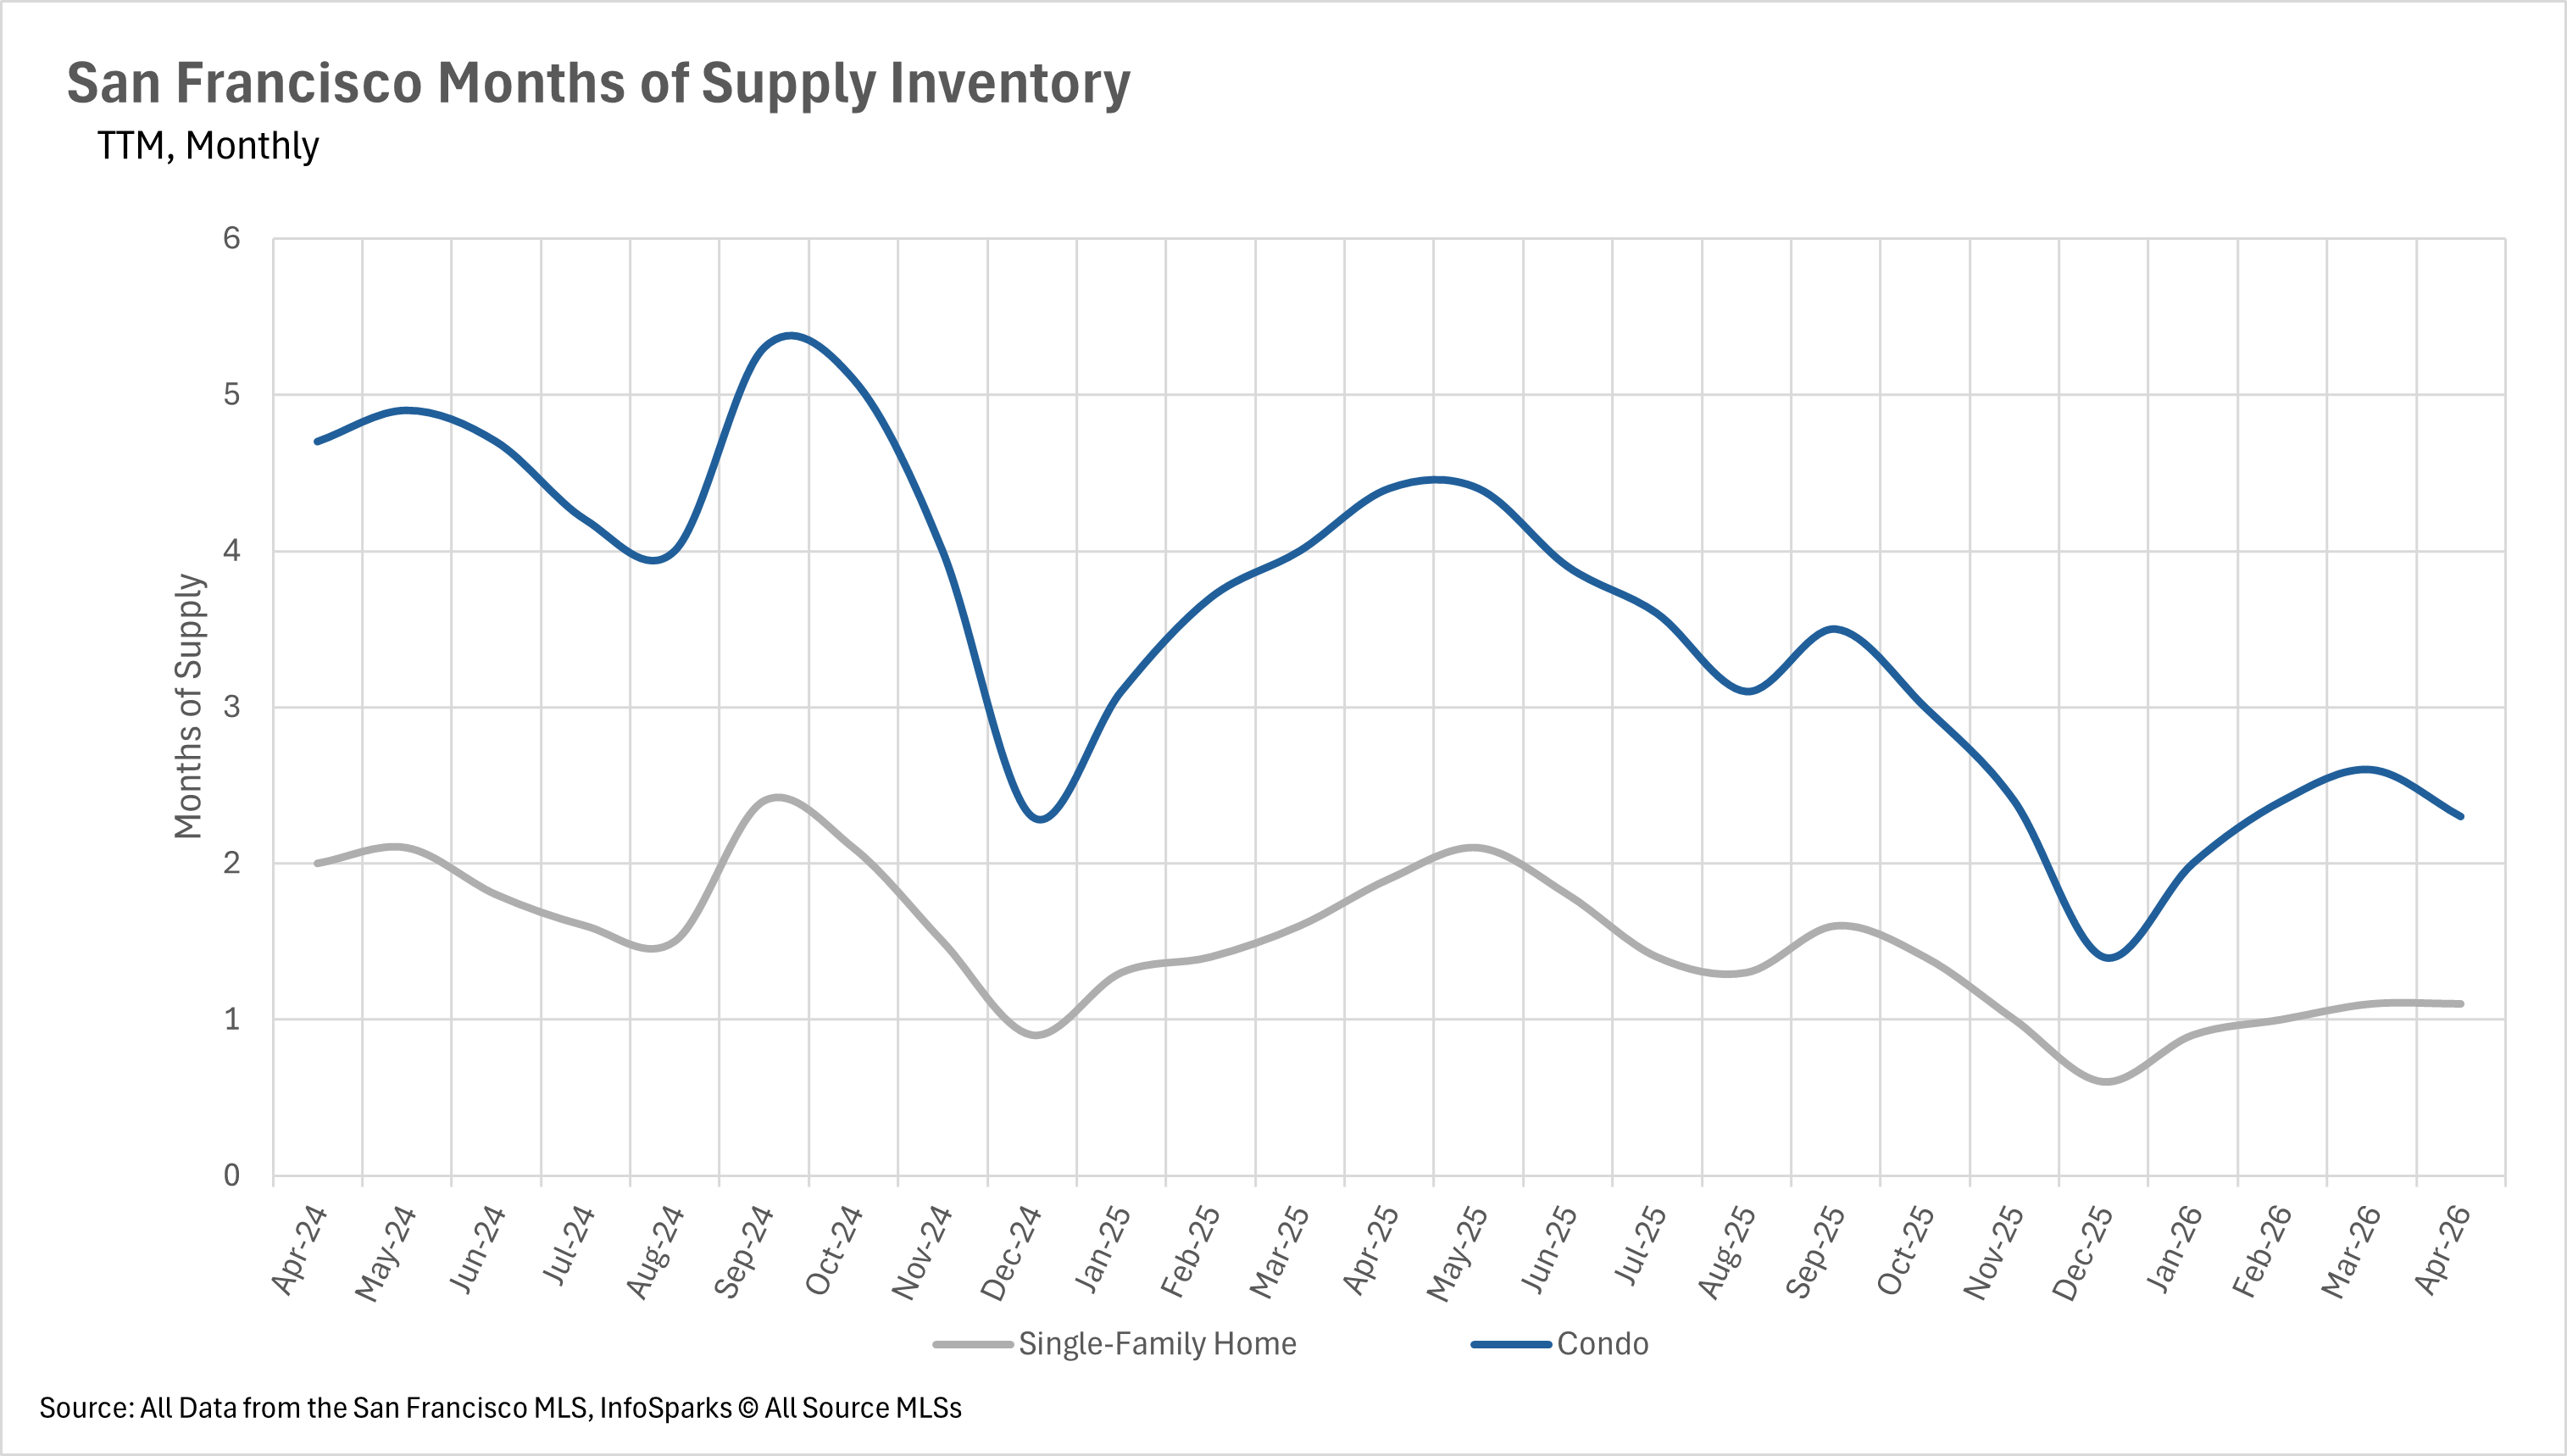
The single-family home market remains firmly in seller's territory across the Bay Area. San Francisco has just 1.1 months of supply, while San Mateo County sits at 1.4 months and Santa Clara County at 1.8 months. Alameda County has 1.8 months, Contra Costa County 2.1 months, Marin County 2.2 months, Solano County 2.6 months, Sonoma County 2.8 months, and Santa Cruz County 2.9 months. Napa County remains the lone outlier at 6 months, though this still represents a 33.33% year-over-year decline. The condo market, however, has shifted decisively in favor of buyers in several areas. Alameda County has 4.3 months of condo supply, Contra Costa County 4.1 months, Santa Cruz County 4.5 months, Santa Clara County 4 months, and Napa County 5.6 months. San Francisco's condo market has bucked this trend entirely, transforming from a buyer's market last April at 4.4 months to a strong seller's market today at just 2.3 months. The growing divide between the single-family and condo markets remains one of the most defining characteristics of the Bay Area heading into the summer months.
Local Lowdown Data
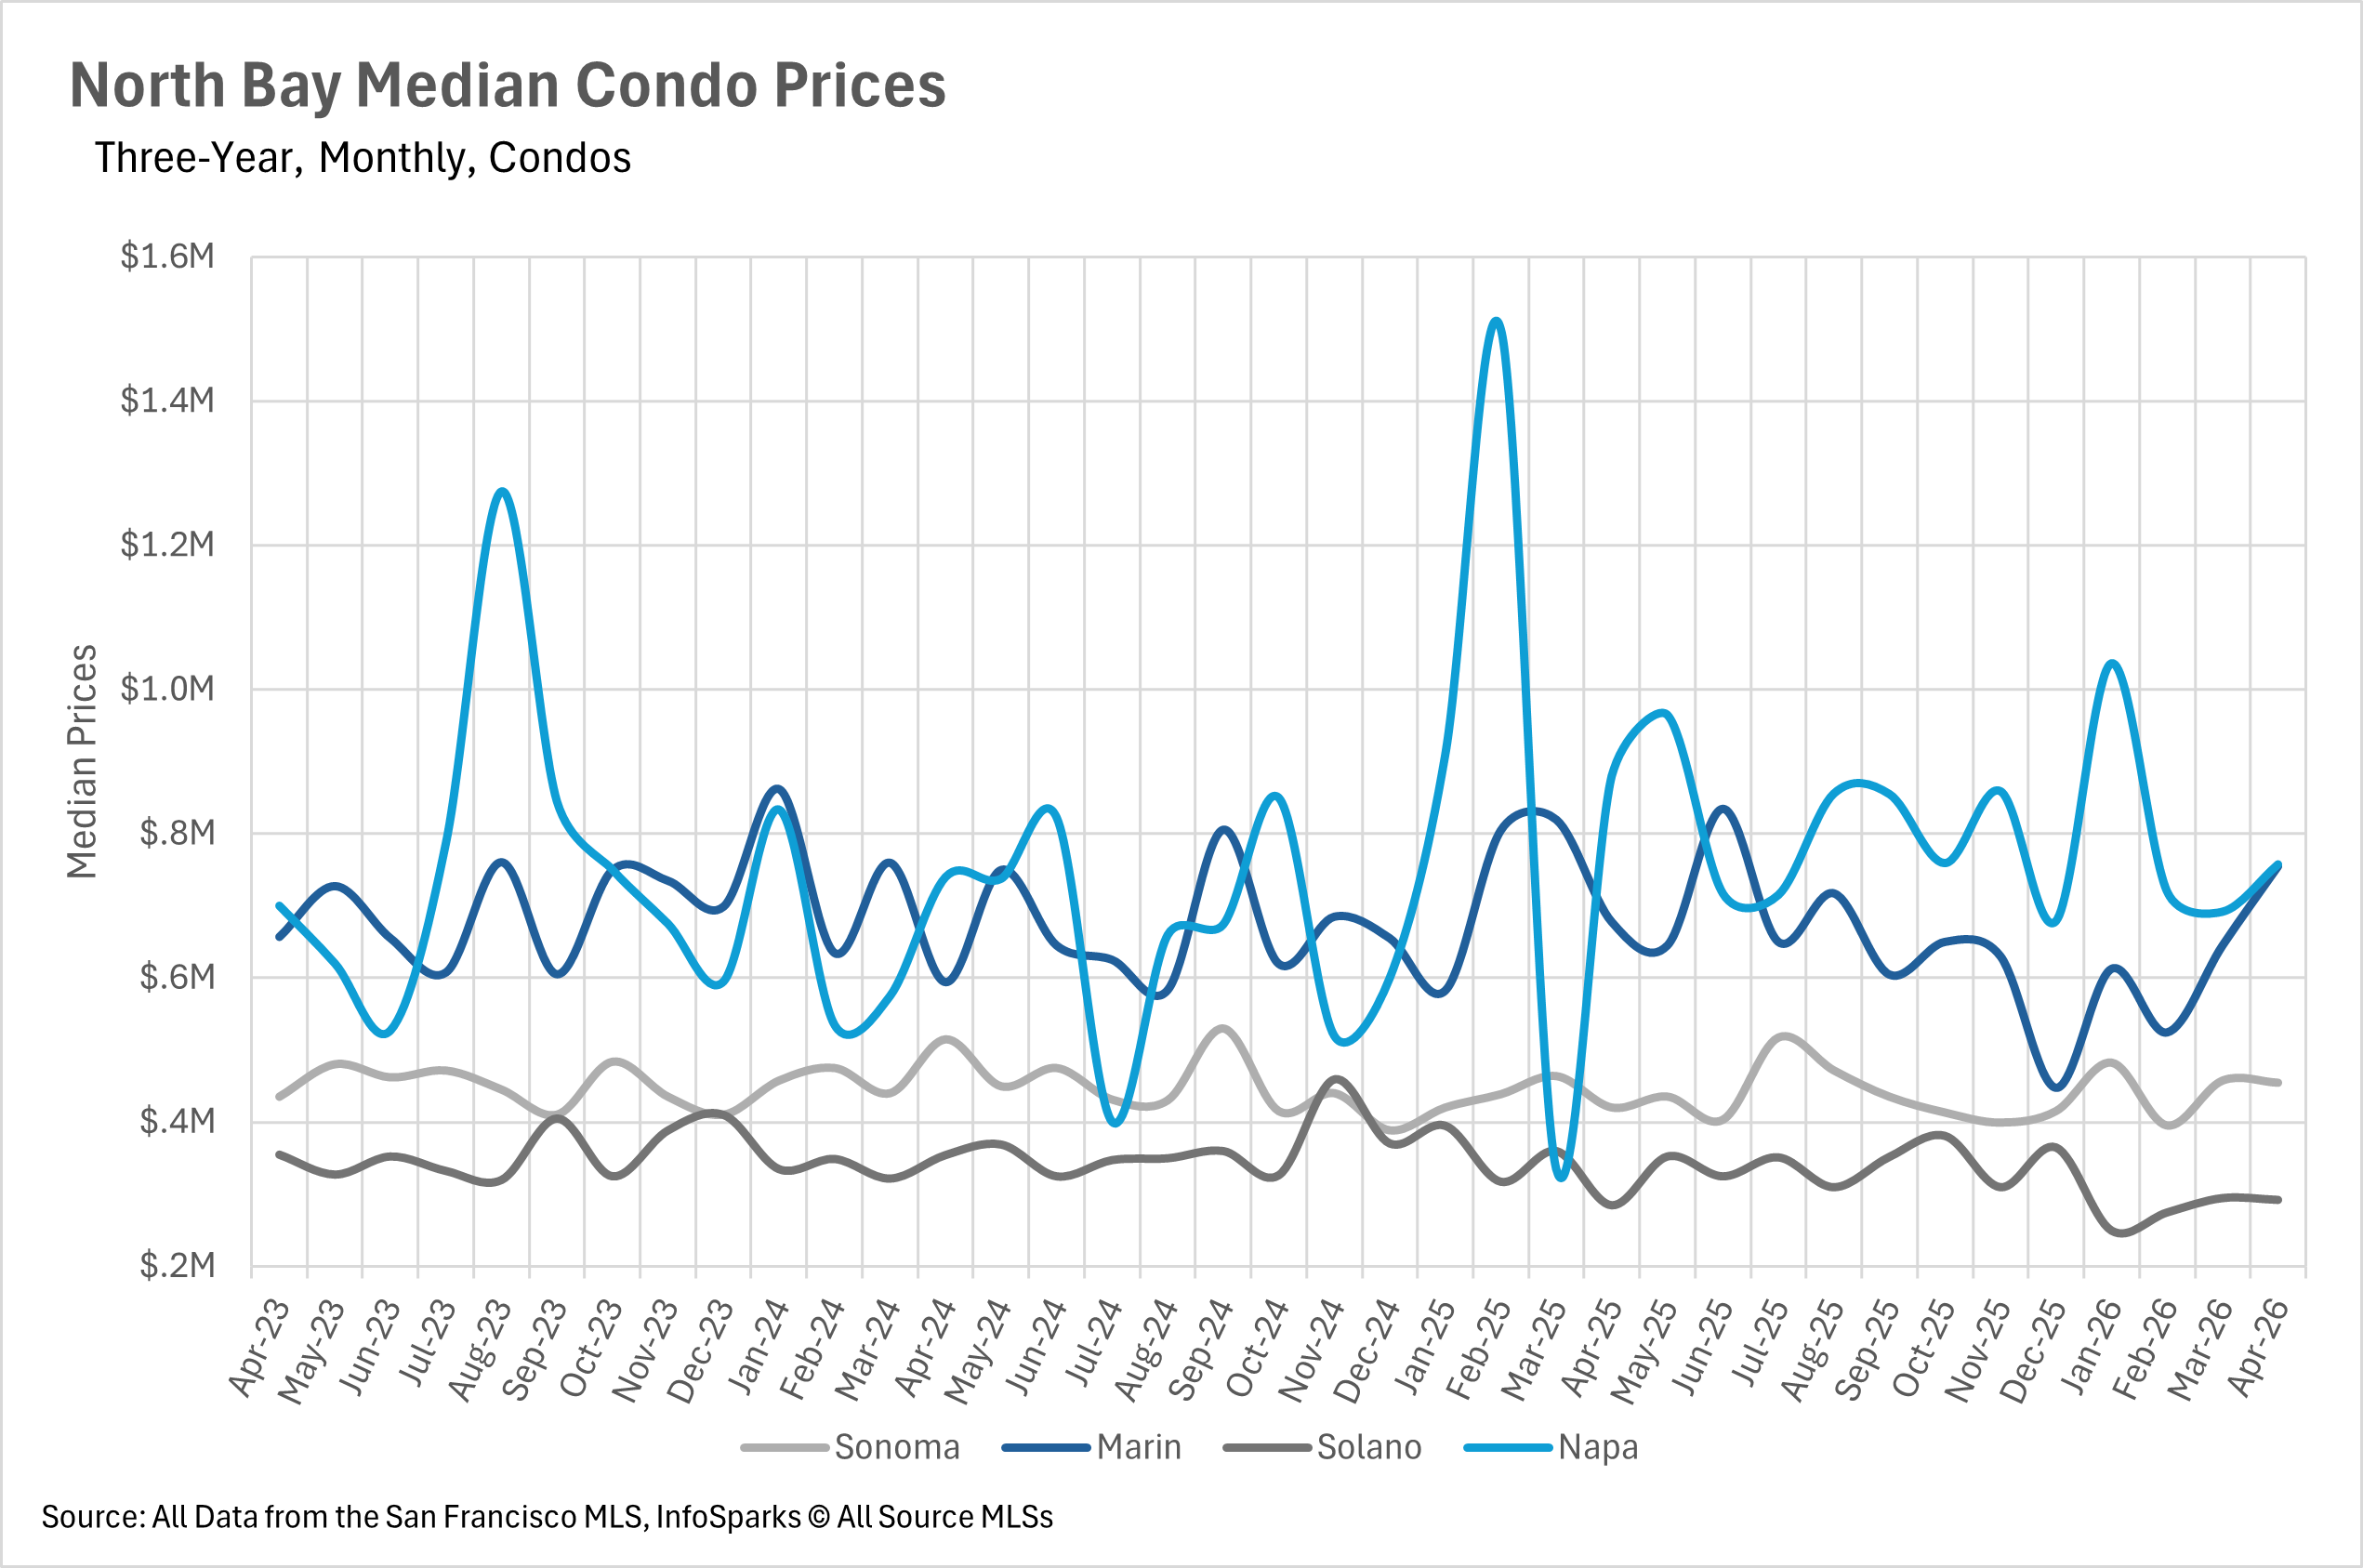
Line chart comparing monthly median condo prices in Sonoma, Marin, Solano, and Napa counties, April 2023–April 2026.
Line chart of monthly median single-family home prices in Marin, Napa, Sonoma, and Solano counties, April 2023–April 2026.
Chart of year-over-year North Bay condo price changes by county, May 2025 through April 2026.
Chart of year-over-year median single-family home price changes in Sonoma, Marin, Solano, and Napa, May 2025–April 2026.
Chart of North Bay condo inventory from April 2024 to April 2026, showing new, sold, and for-sale listings.
Chart of North Bay single-family home listings and sales, April 2024–April 2026.
Line chart comparing monthly condo inventory supply in Sonoma, Marin, Solano, and Napa from April 2024 to April 2026.
Line chart comparing monthly single-family home inventory in four North Bay counties from April 2024 to April 2026.
Line chart comparing monthly condo days on market in Sonoma, Marin, Solano, and Napa counties from April 2024 to April 2026.
Line chart comparing monthly days on market for single-family homes in Sonoma, Marin, Solano, and Napa, April 2024–April 2026.
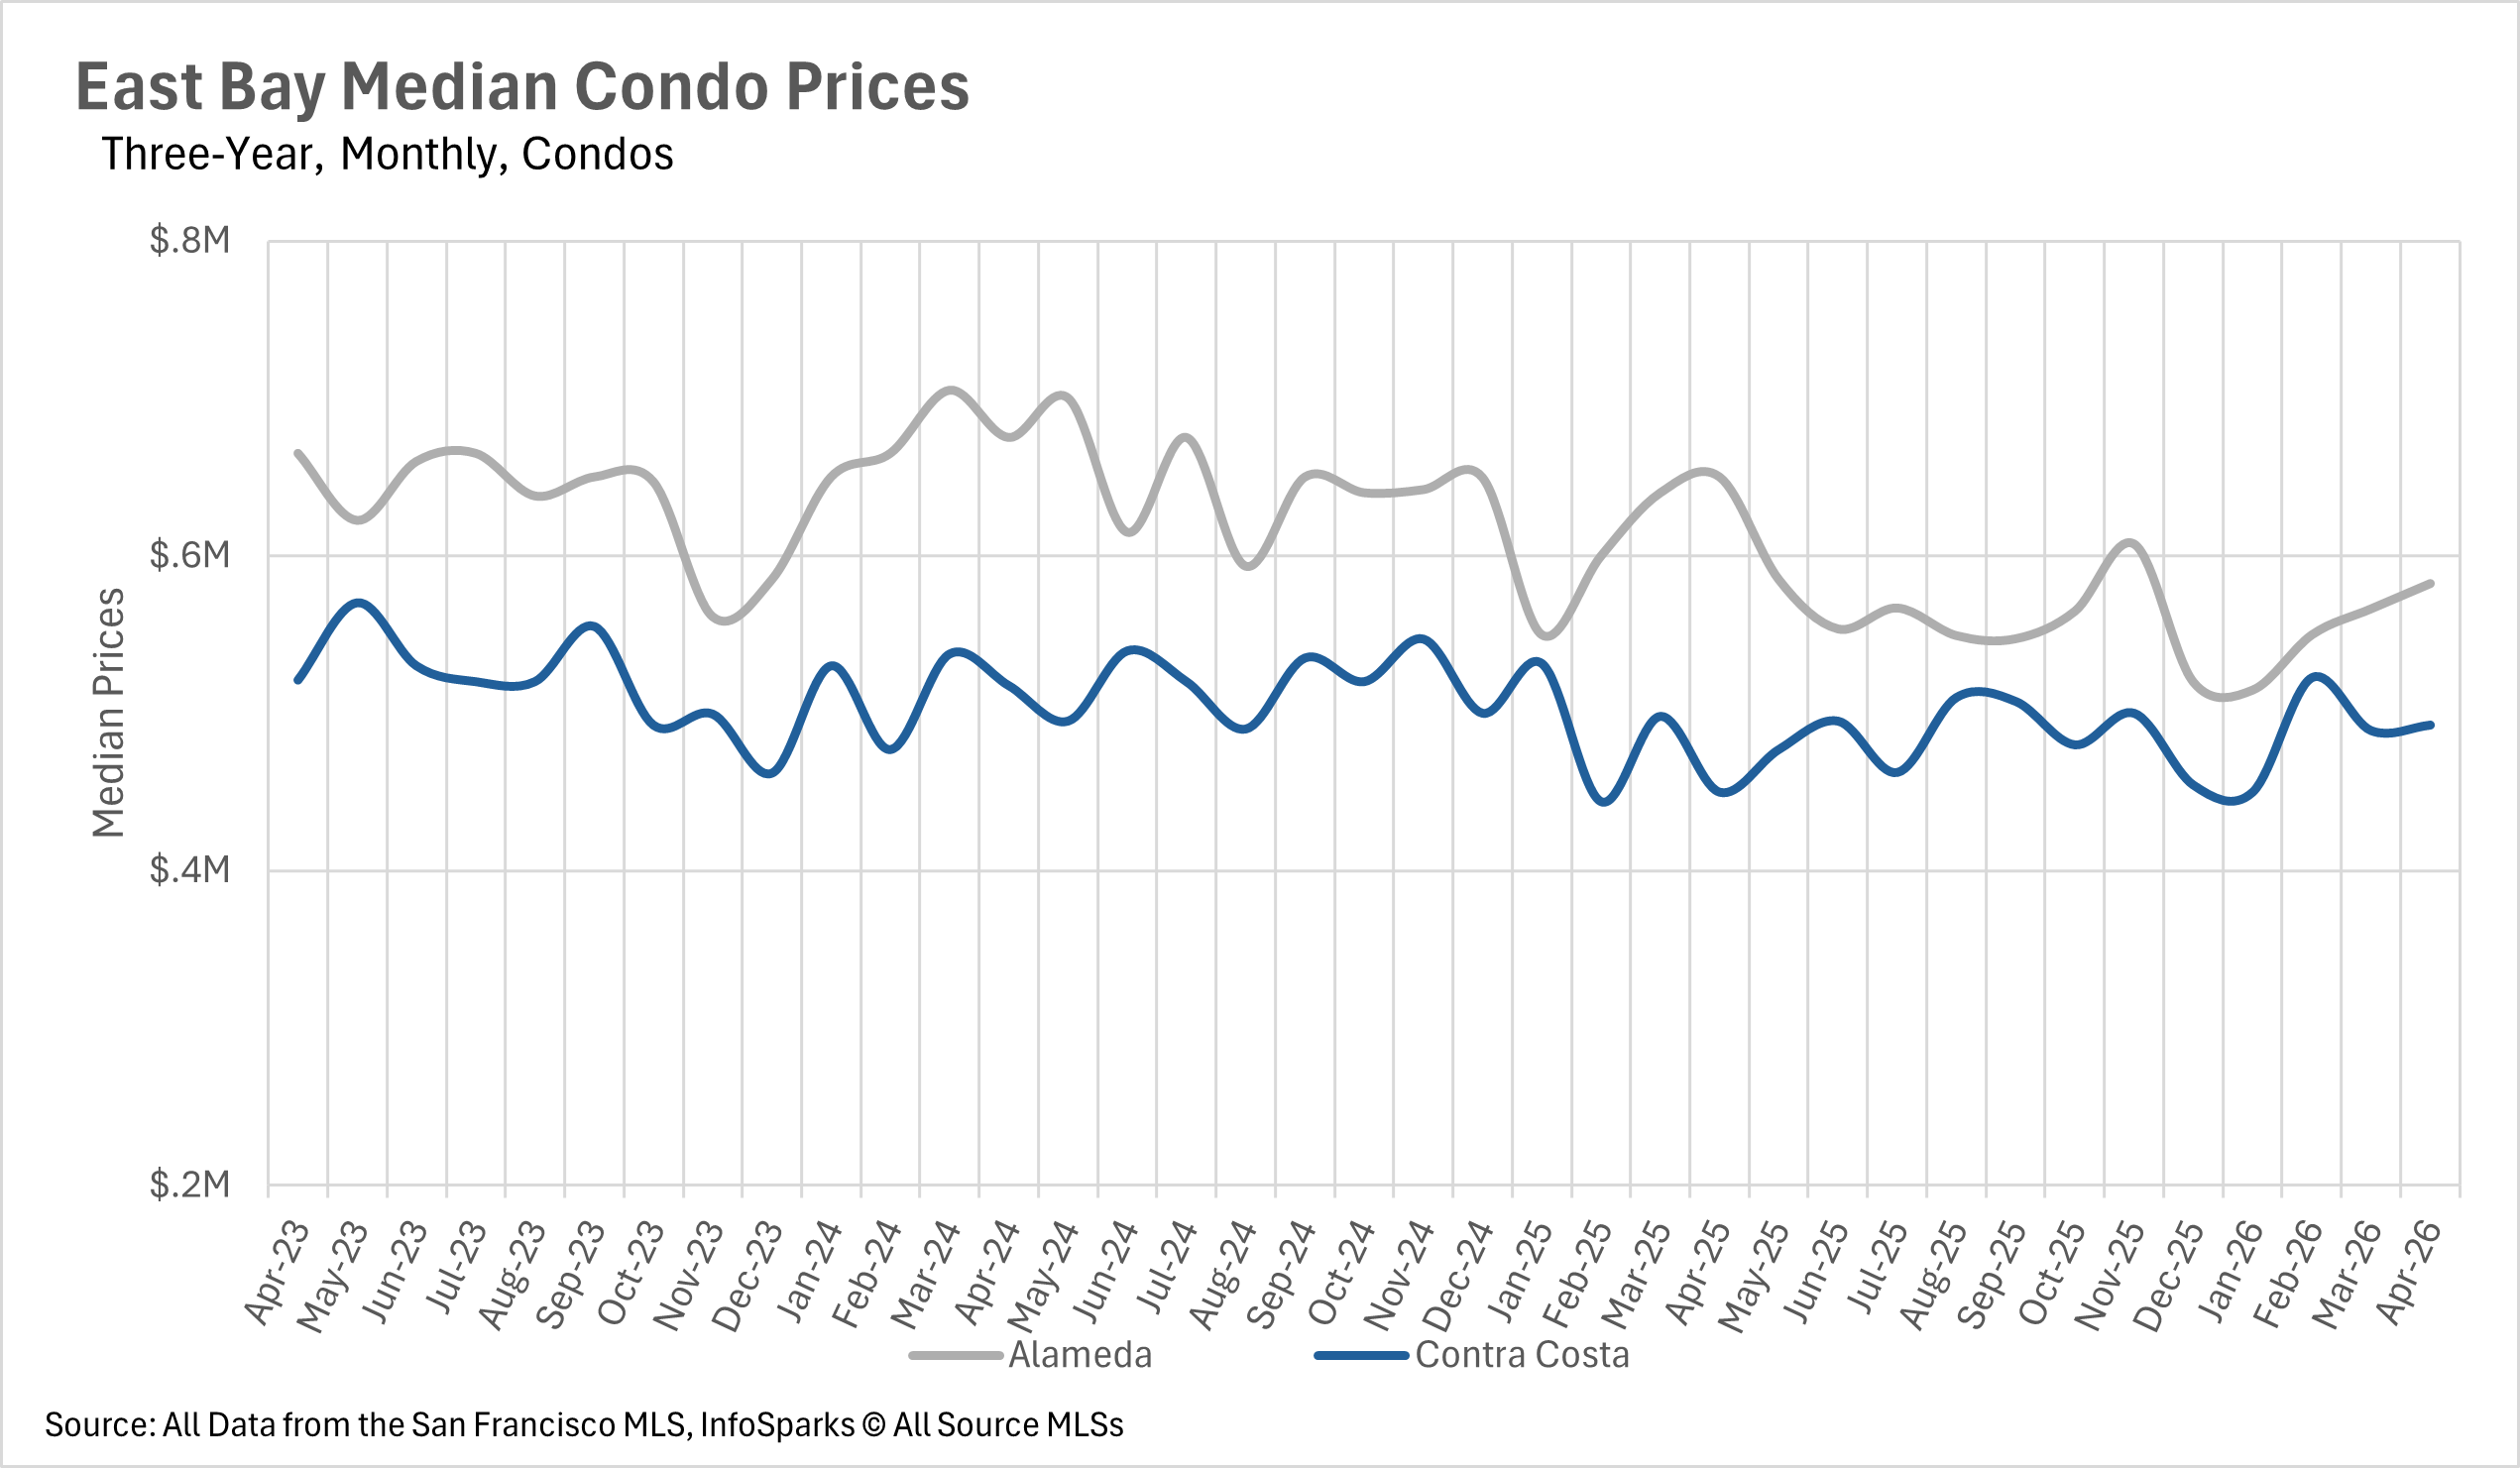
Line chart comparing monthly median condo prices in Alameda and Contra Costa counties, April 2023–April 2026.
Line chart comparing monthly median single-family home prices in Alameda and Contra Costa counties, April 2023–April 2026.
Bar chart comparing year-over-year East Bay condo price changes in Alameda and Contra Costa counties, May 2025–April 2026.
Chart comparing monthly year-over-year single-family home price changes in Alameda and Contra Costa counties, May 2025–April 2026.
Chart of East Bay condo listings from April 2024 to April 2026, with monthly new, sold, and for-sale listings.
Chart of East Bay single-family home listings, sales, and homes for sale from April 2024 to April 2026.
Line chart comparing monthly condo inventory supply in Alameda and Contra Costa counties, April 2024–April 2026.
Chart comparing monthly single-family home supply in Alameda and Contra Costa from April 2024 to April 2026.
Line chart comparing monthly condo days on market in Alameda and Contra Costa counties, April 2024 to April 2026.
East Bay days on market chart: Contra Costa peaks near 30 days in January 2026; Alameda peaks near 20.
Line chart comparing monthly median condo prices in San Mateo, Santa Clara, and Santa Cruz counties, April 2023–April 2026.
Chart of monthly median single-family home prices in San Mateo, Santa Clara, and Santa Cruz counties, April 2023–April 2026.
Chart of year-over-year Silicon Valley condo median price changes by county, May 2025 to April 2026.
Chart of year-over-year Silicon Valley single-family home price changes by county, May 2025 to April 2026.
Chart of Silicon Valley condo listings from April 2024 to April 2026, showing new, sold, and for-sale listings.
Chart of Silicon Valley single-family home listings, sales, and homes for sale from April 2024 to April 2026.
Line chart of monthly condo supply inventory in San Mateo, Santa Clara, and Santa Cruz from April 2024 to April 2026.
Line chart comparing monthly single-family home inventory supply in San Mateo, Santa Clara, and Santa Cruz counties, April 2024–April 2026.
Line chart of monthly condo days on market in San Mateo, Santa Clara, and Santa Cruz, April 2024–April 2026.
Line chart comparing monthly days on market for single-family homes in San Mateo, Santa Clara, and Santa Cruz.
Chart of monthly San Francisco median prices for single-family homes and condos, April 2023 to April 2026.
Bar chart comparing year-over-year San Francisco median price changes for single-family homes and condos, May 2025–April 2026.
Line chart of San Francisco home prices as a percent of original price, March 2023–March 2026; single-family homes and condos.
Chart of San Francisco condo listings, sales, and inventory from April 2024 to April 2026.
Chart of San Francisco single-family home inventory, new listings, and sold listings from April 2024 to April 2026.
Line chart comparing San Francisco single-family home and condo months of supply from April 2024 to April 2026.
San Francisco days on market, April 2024–April 2026: condo listings fluctuate more than single-family homes.
 

ActivePipe Message ID: 3826603

Let’s Talk

You’ve got questions and we can’t wait to answer them.