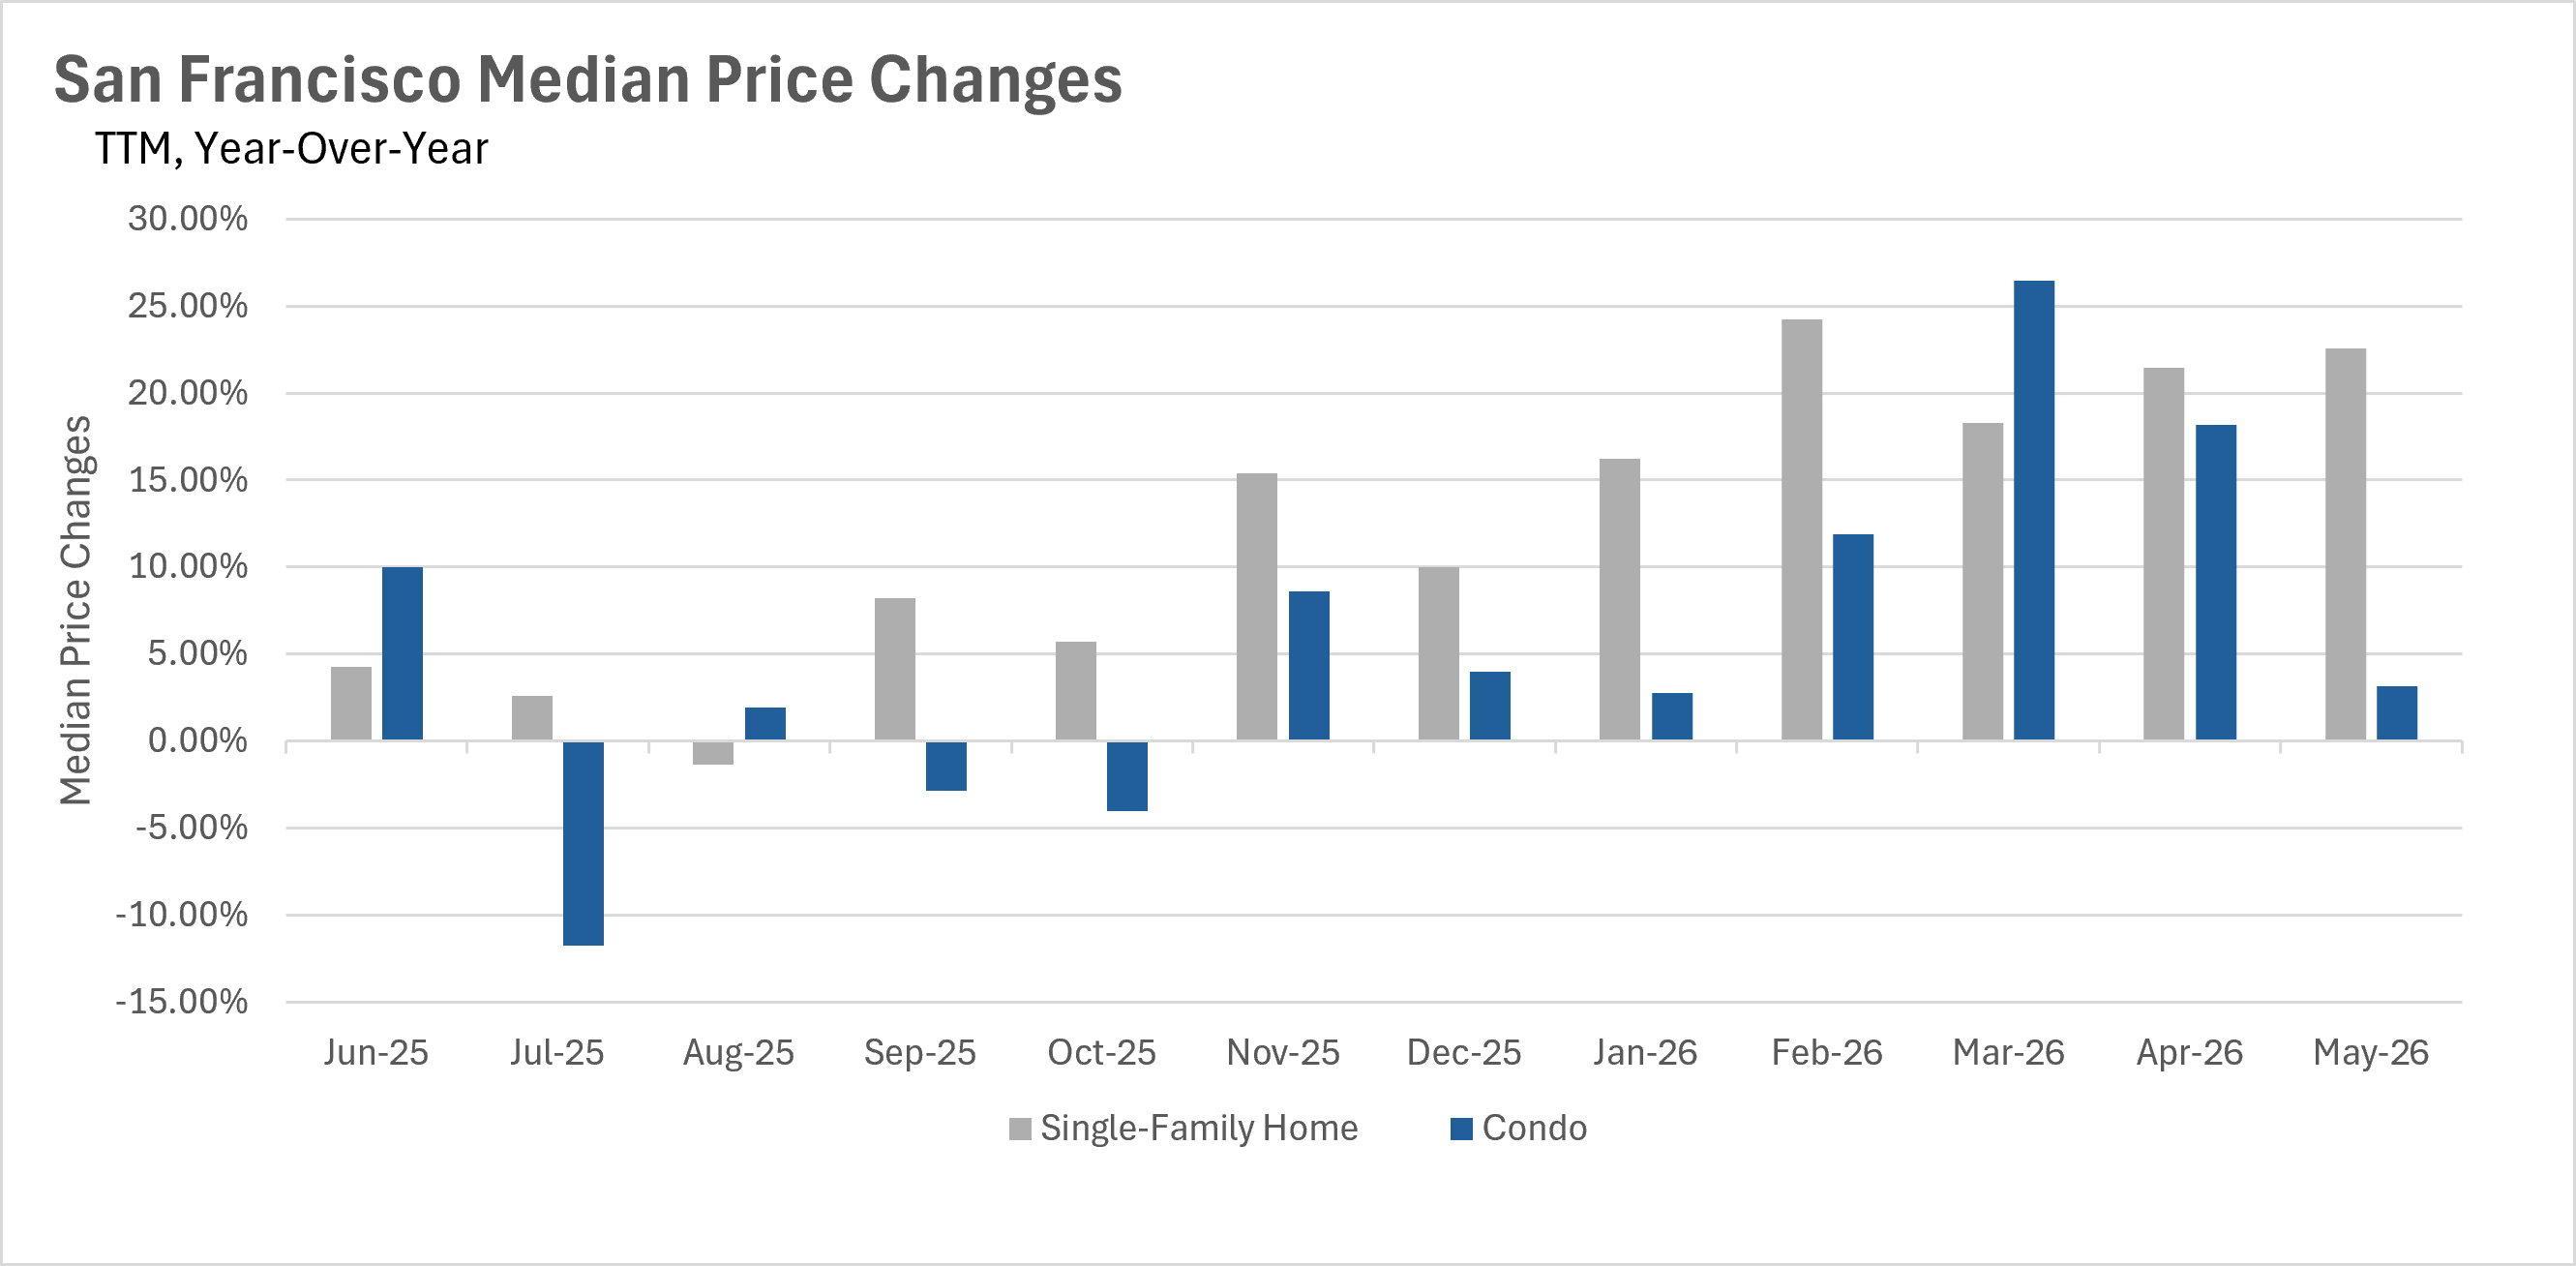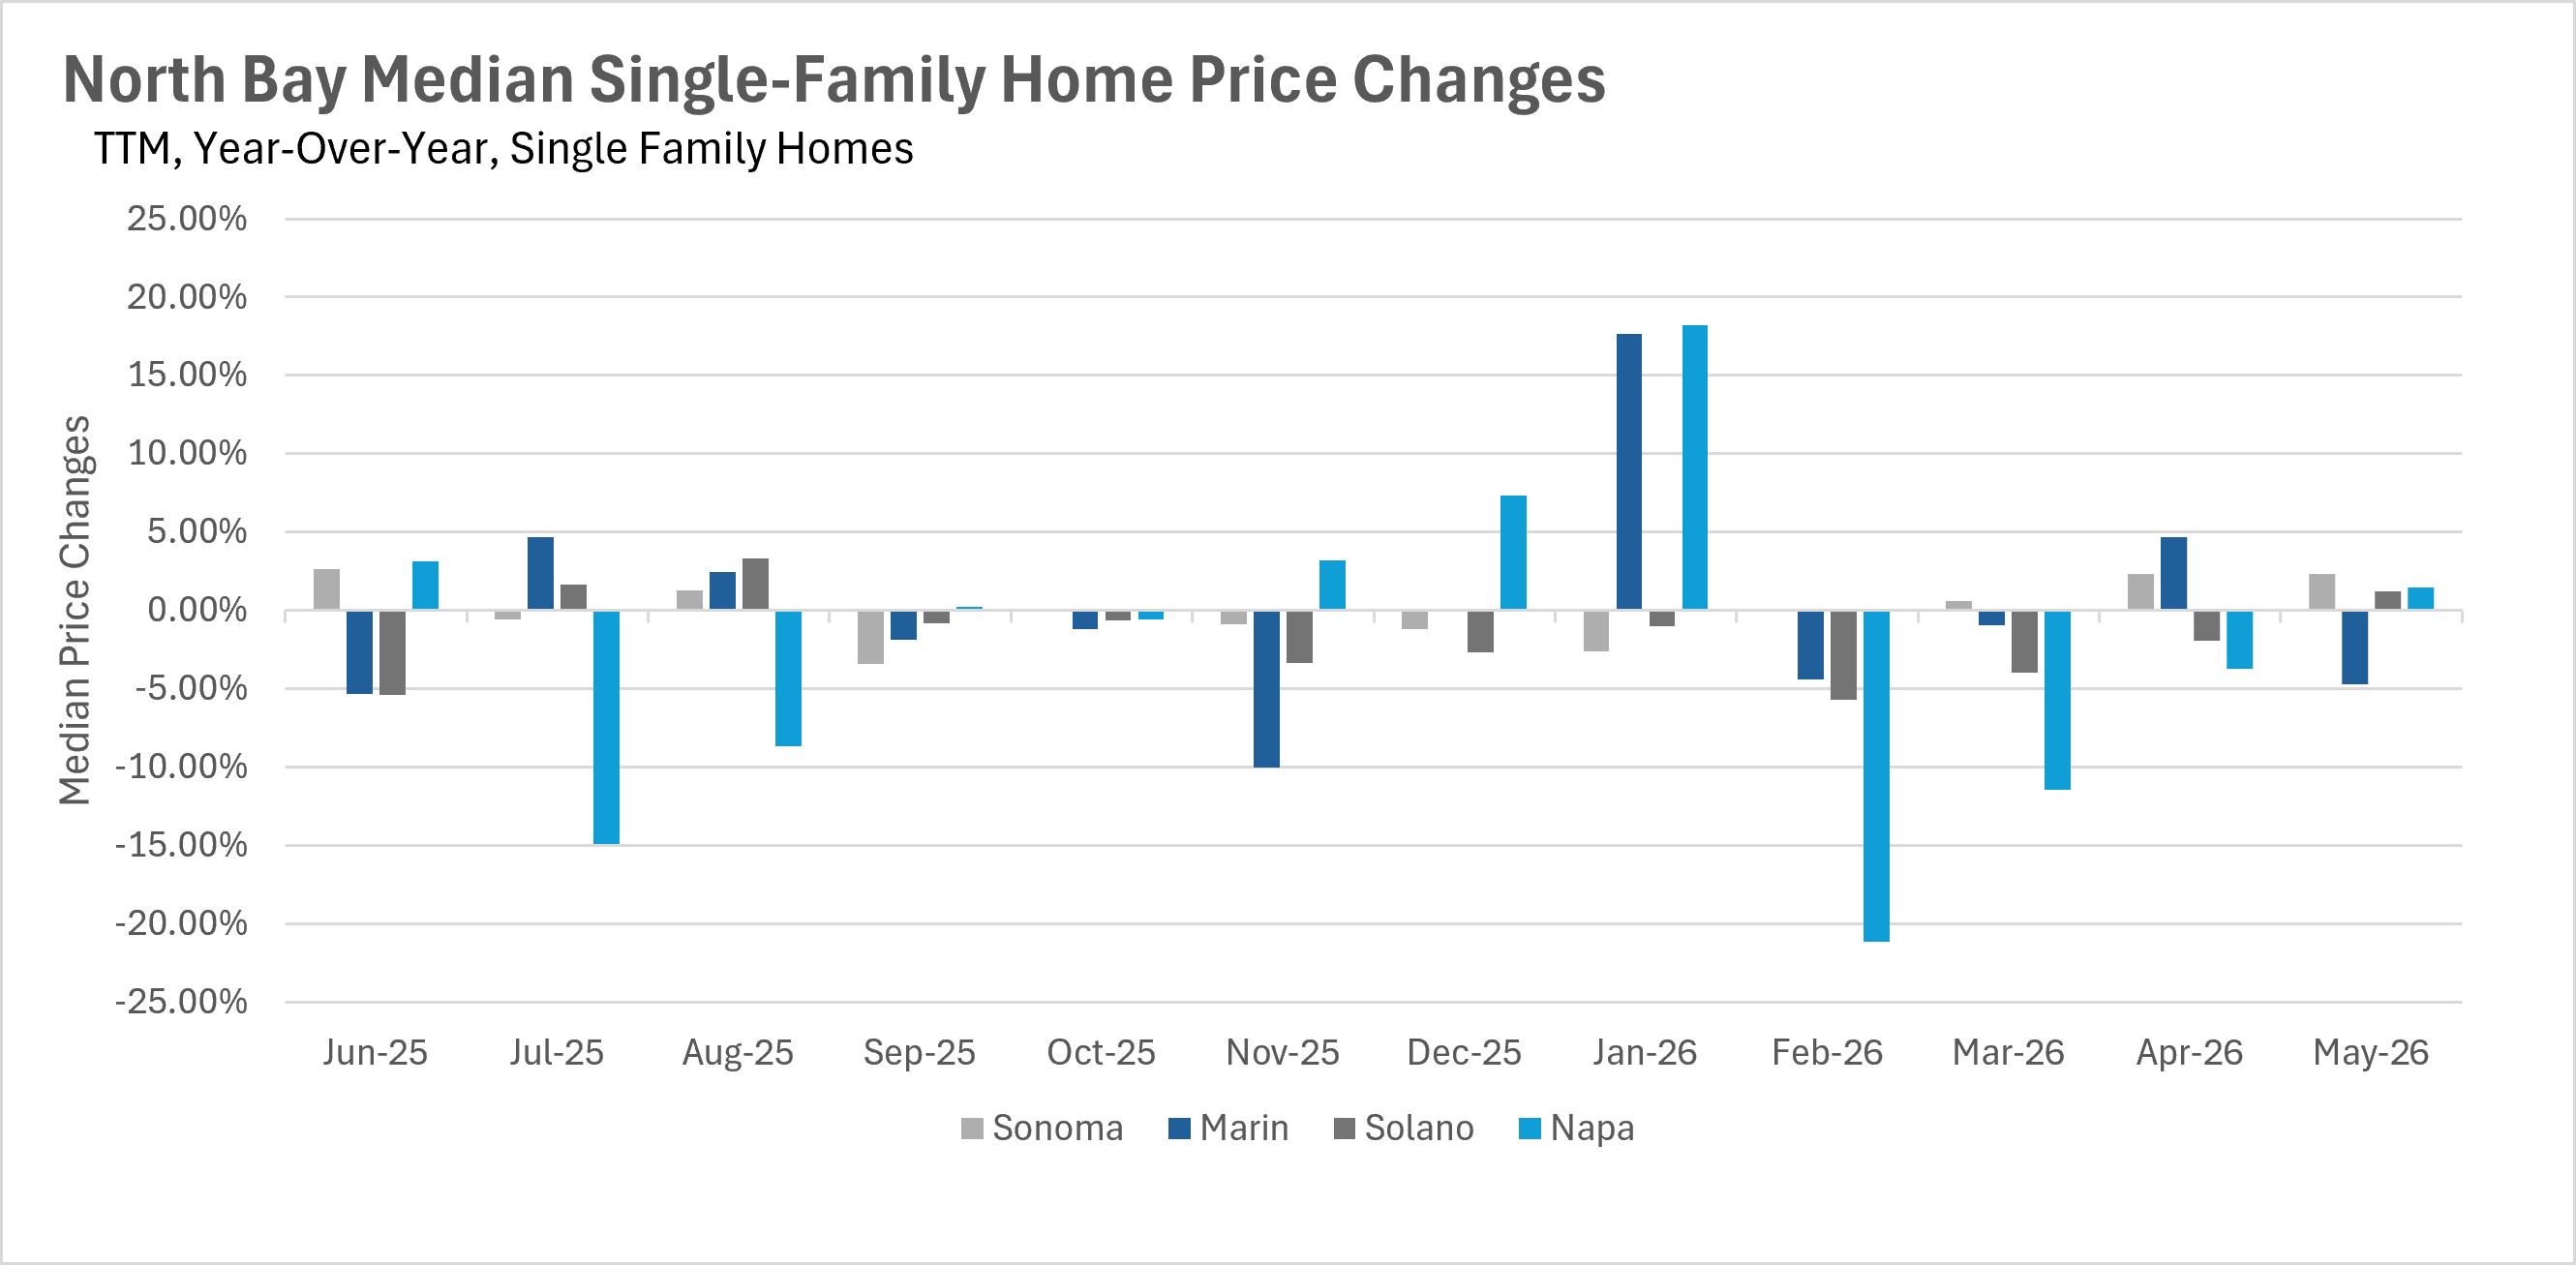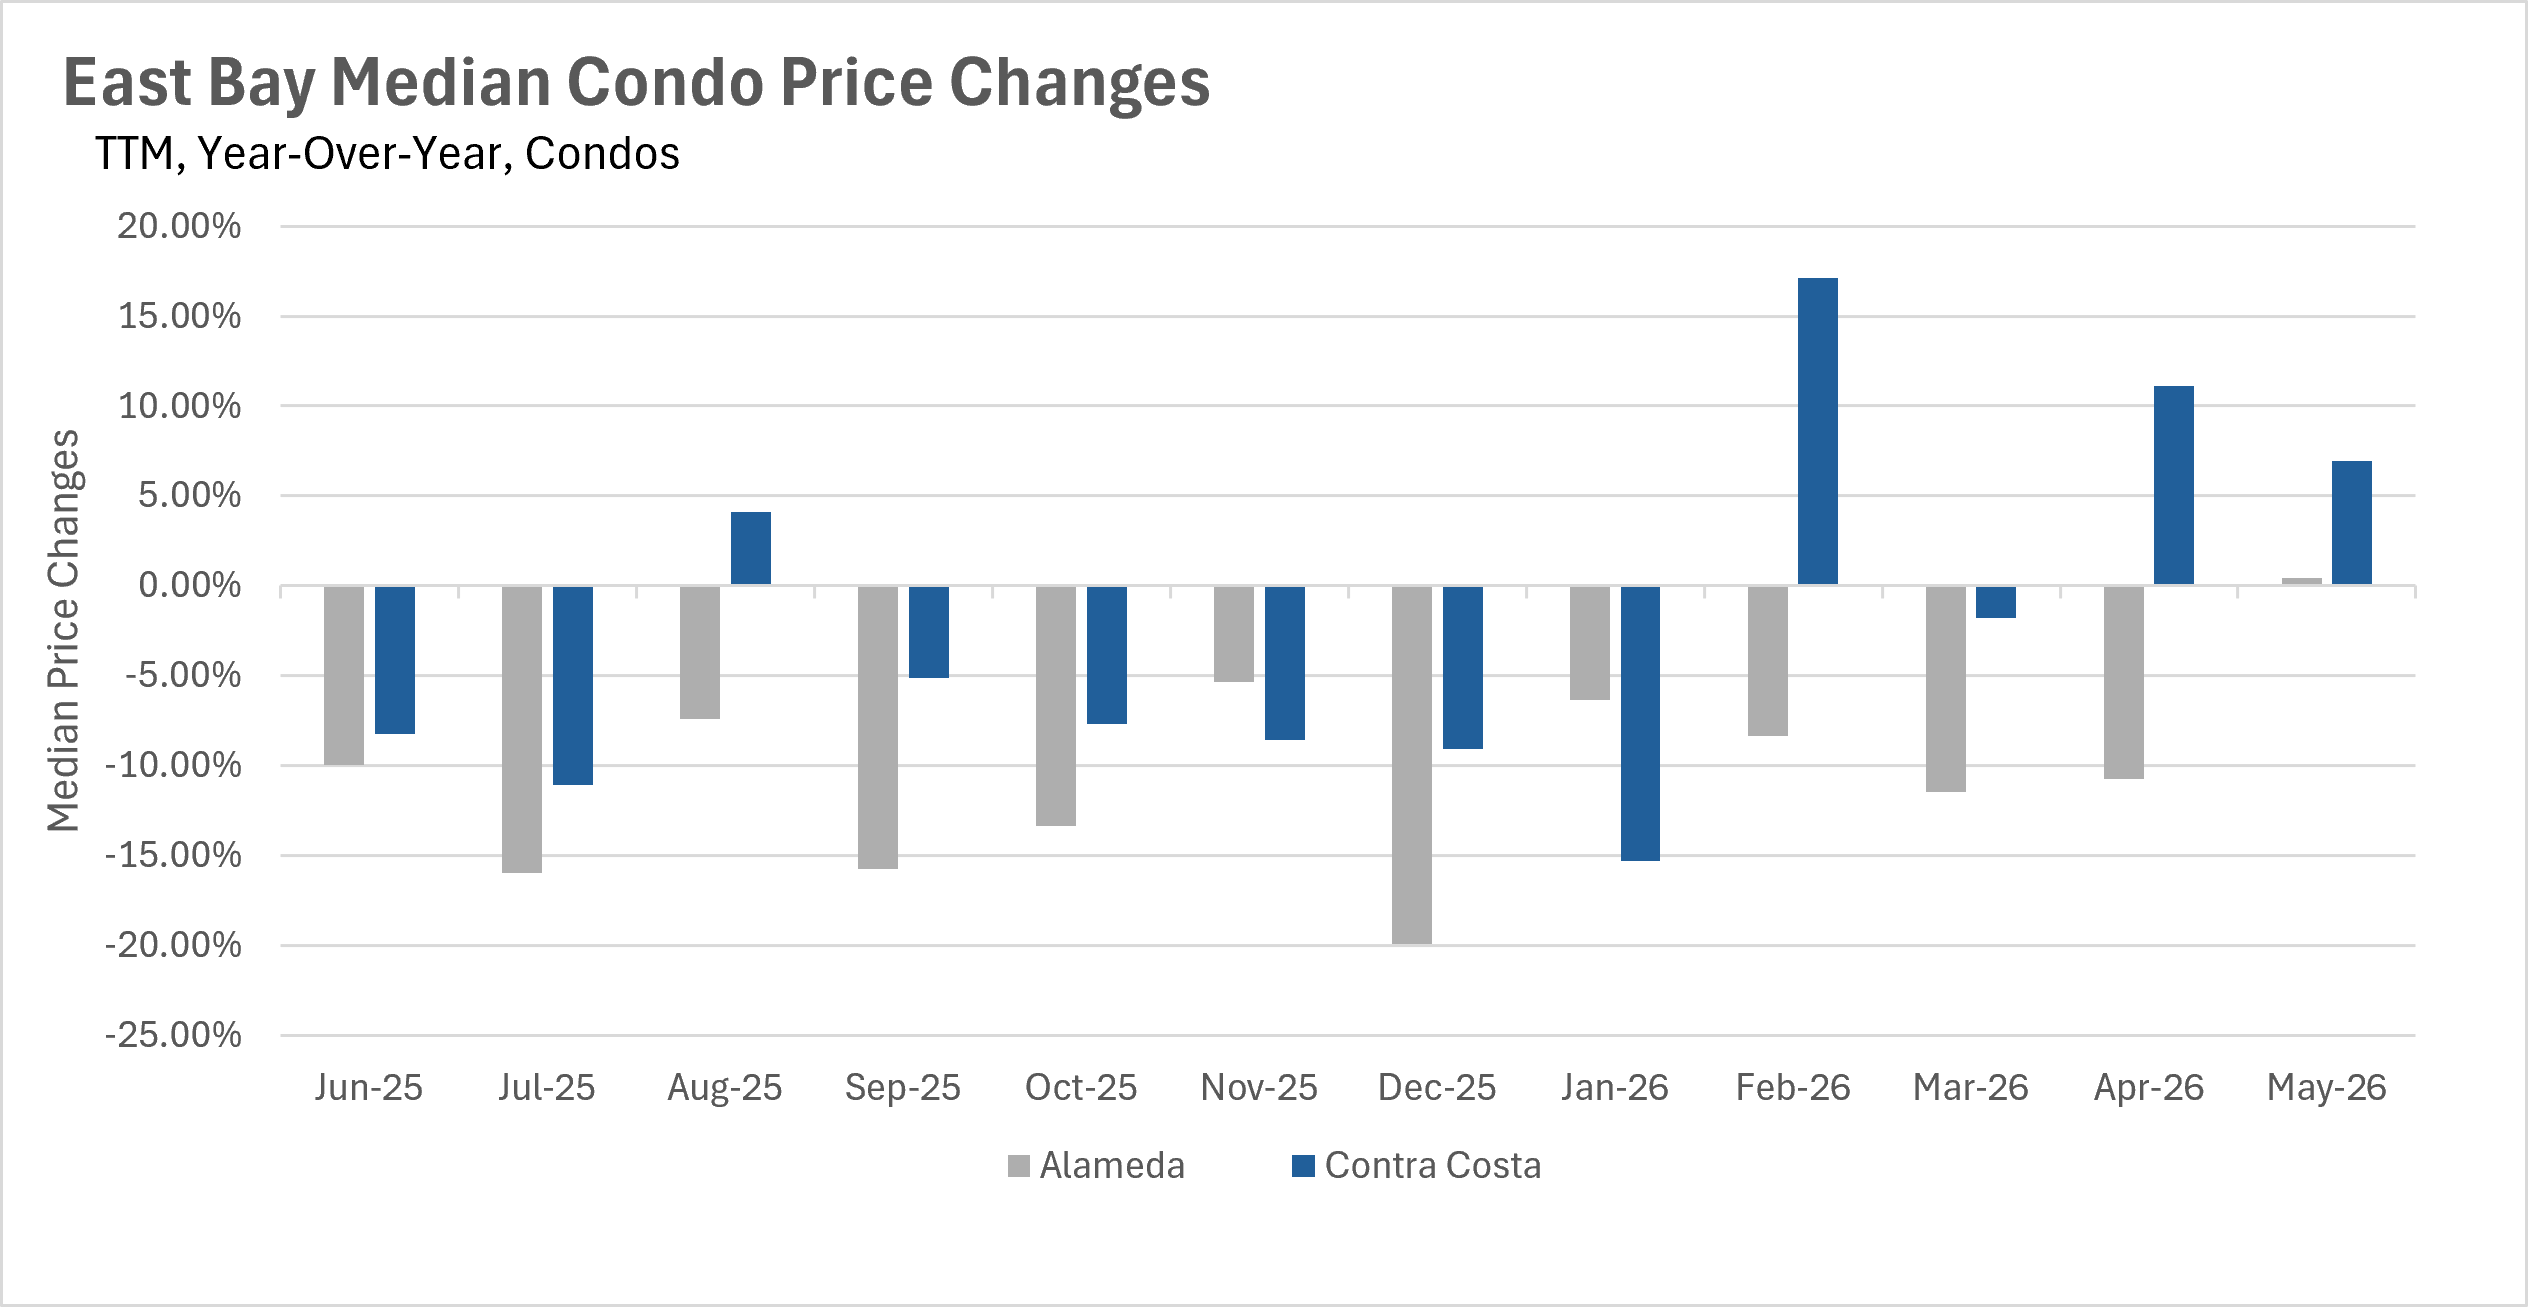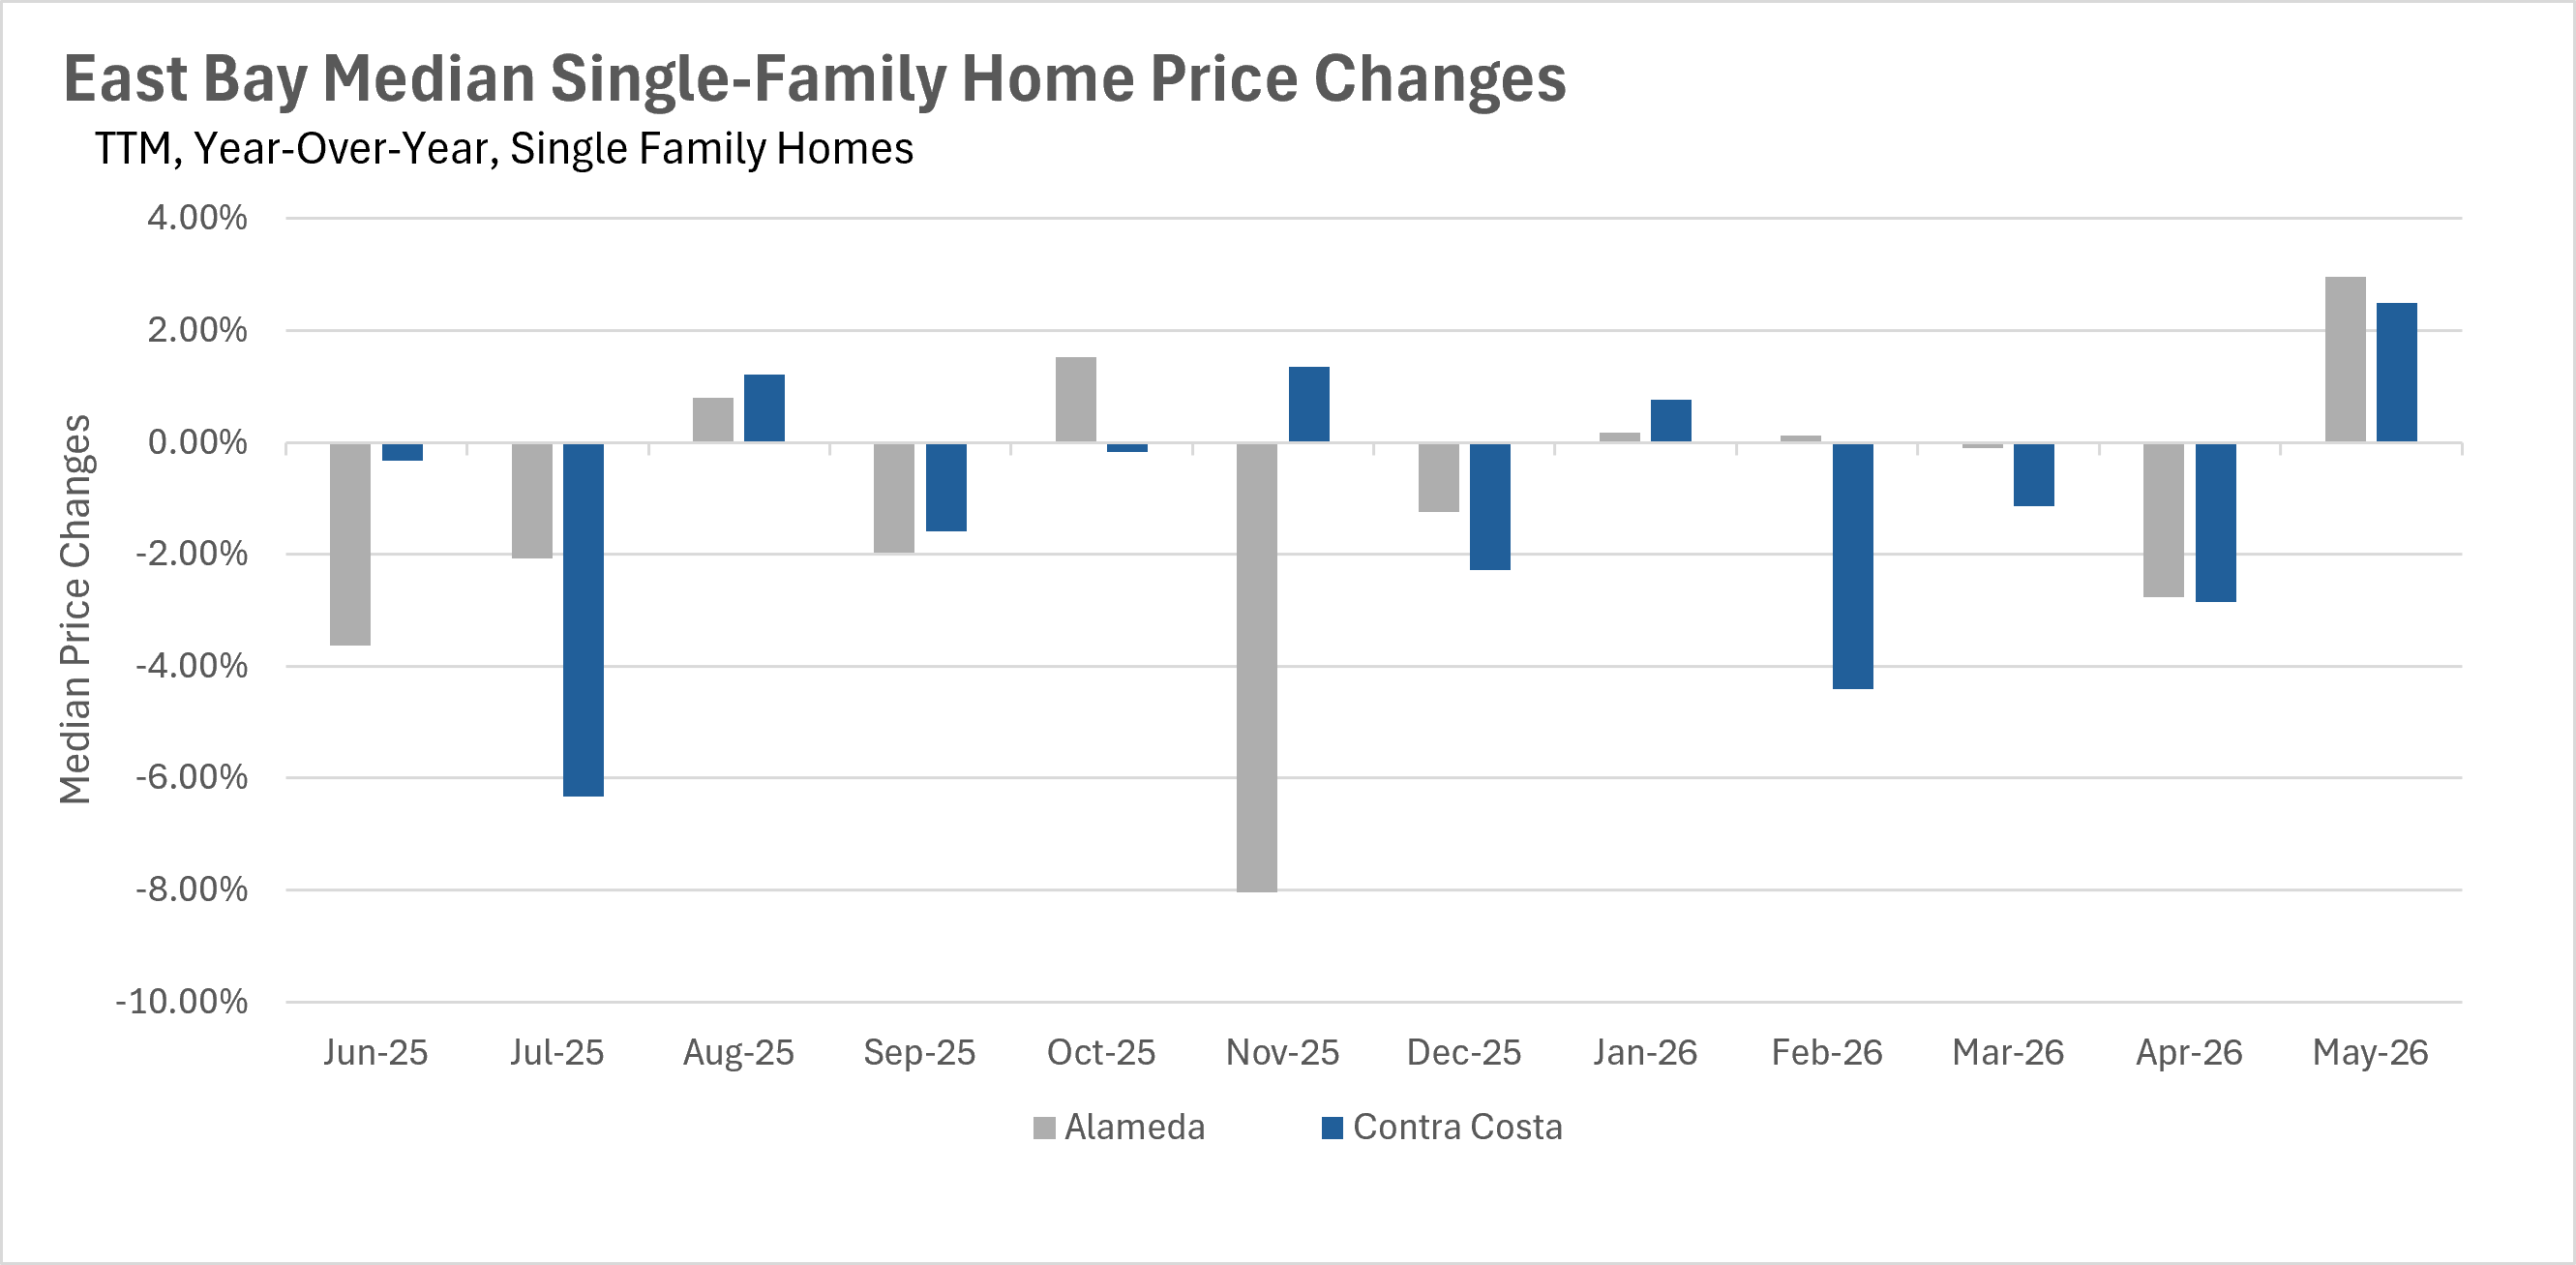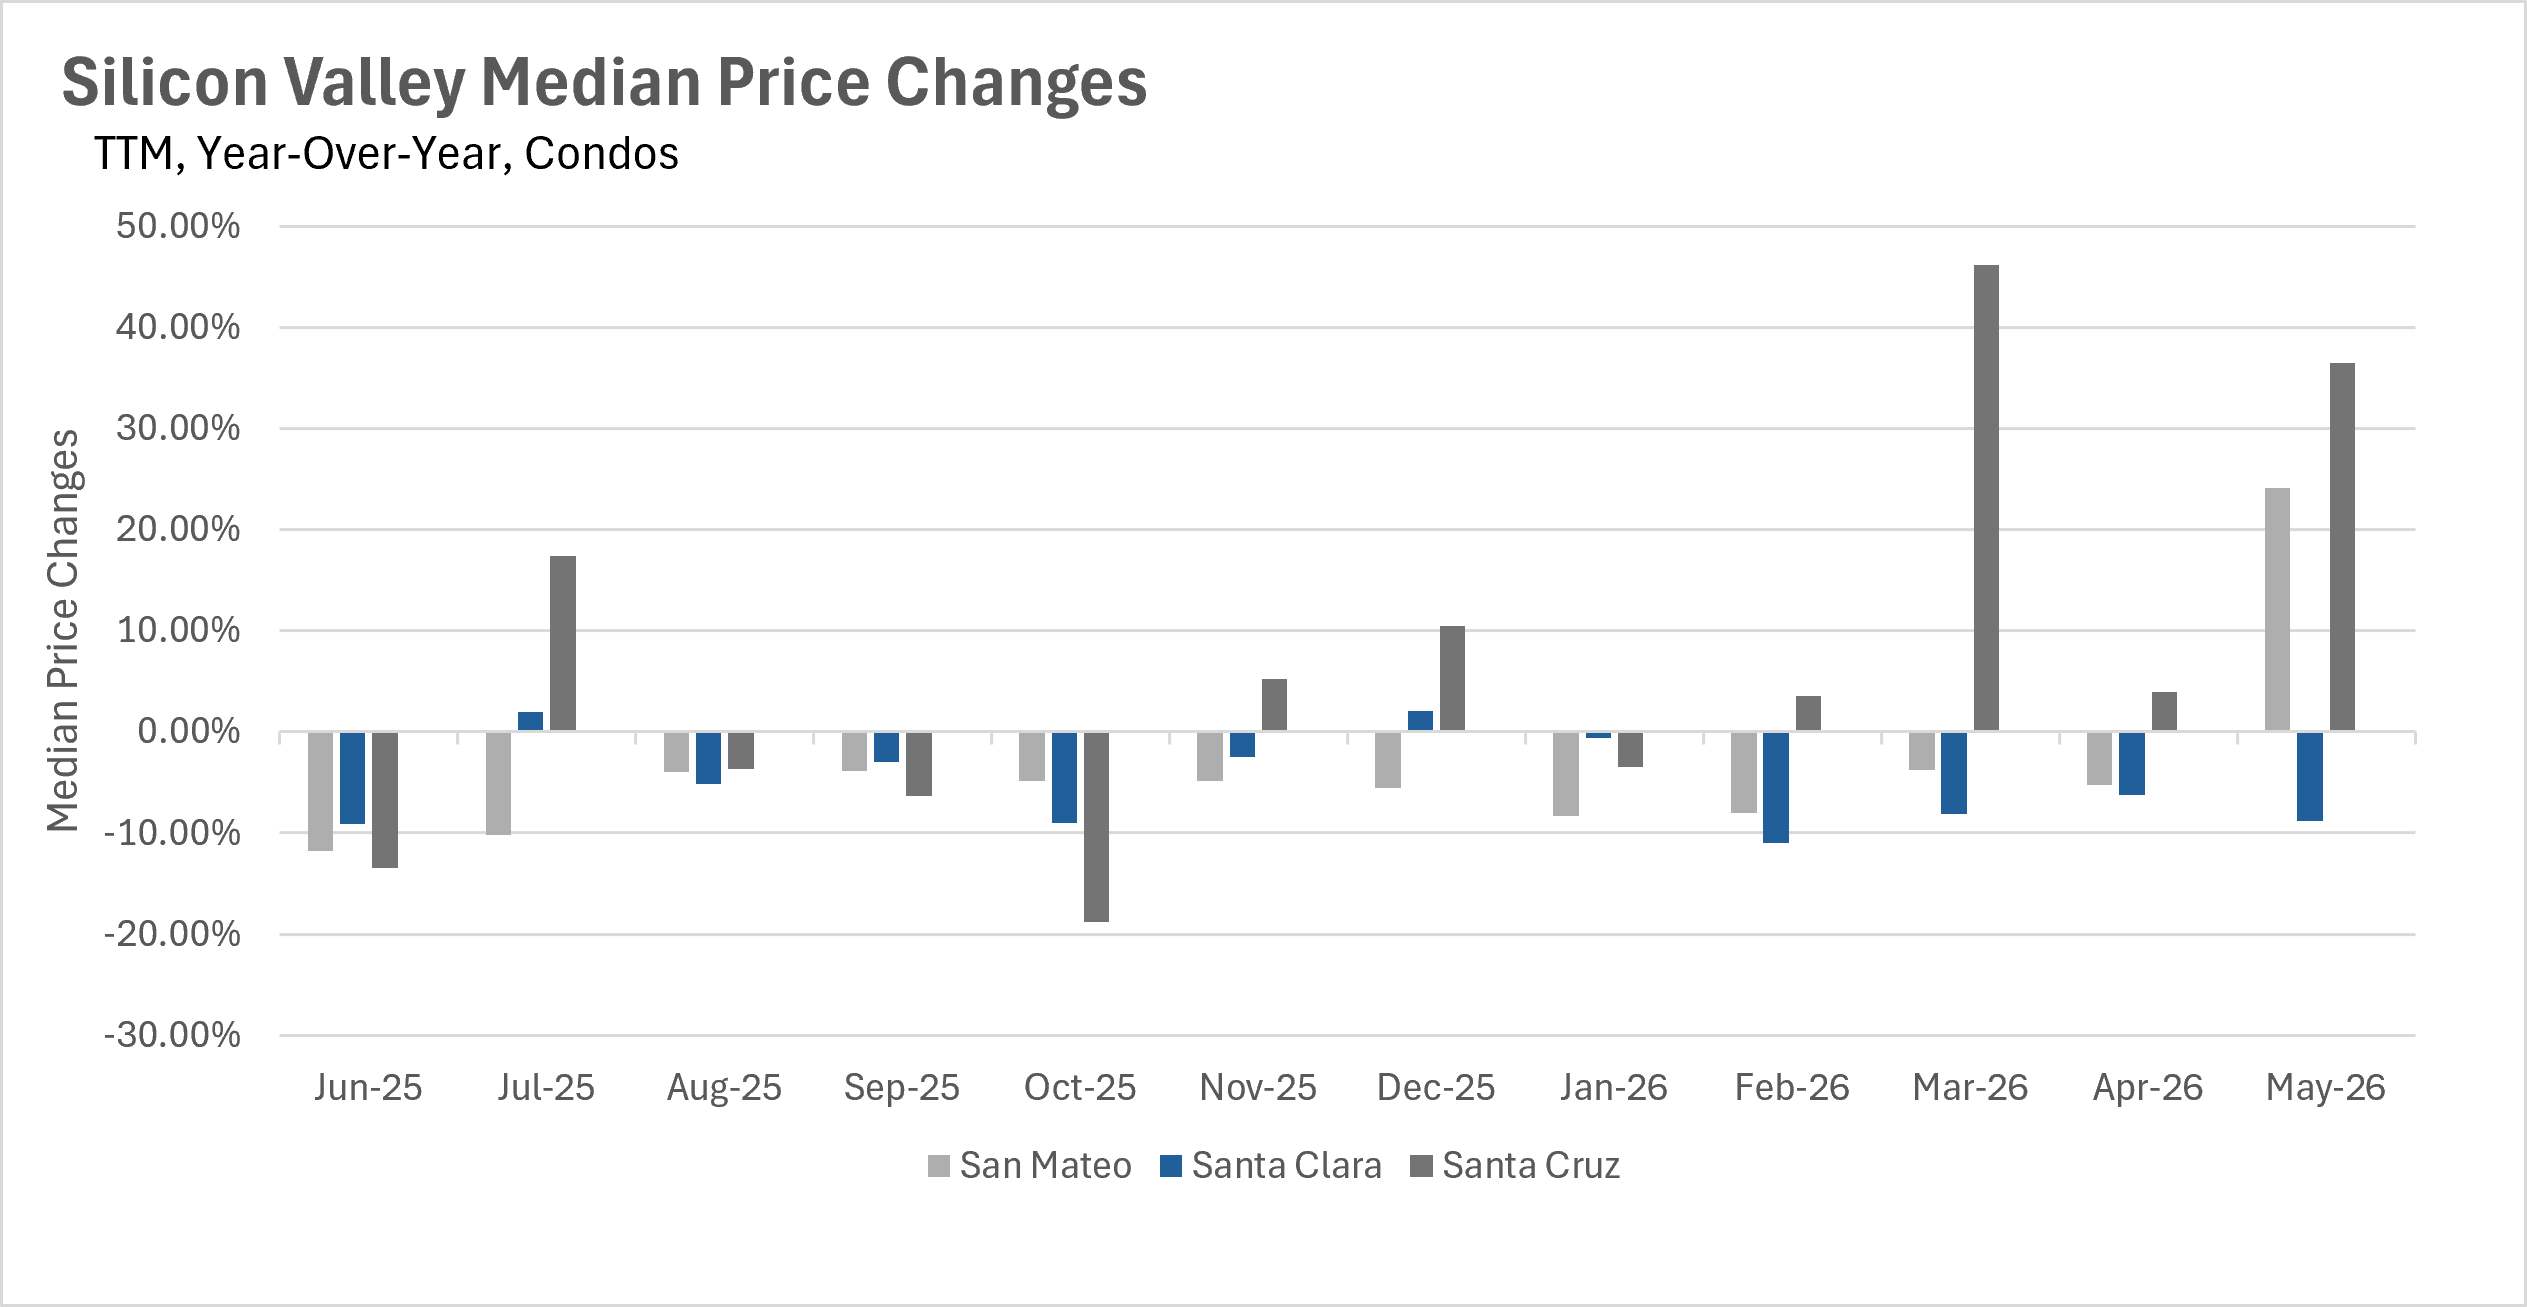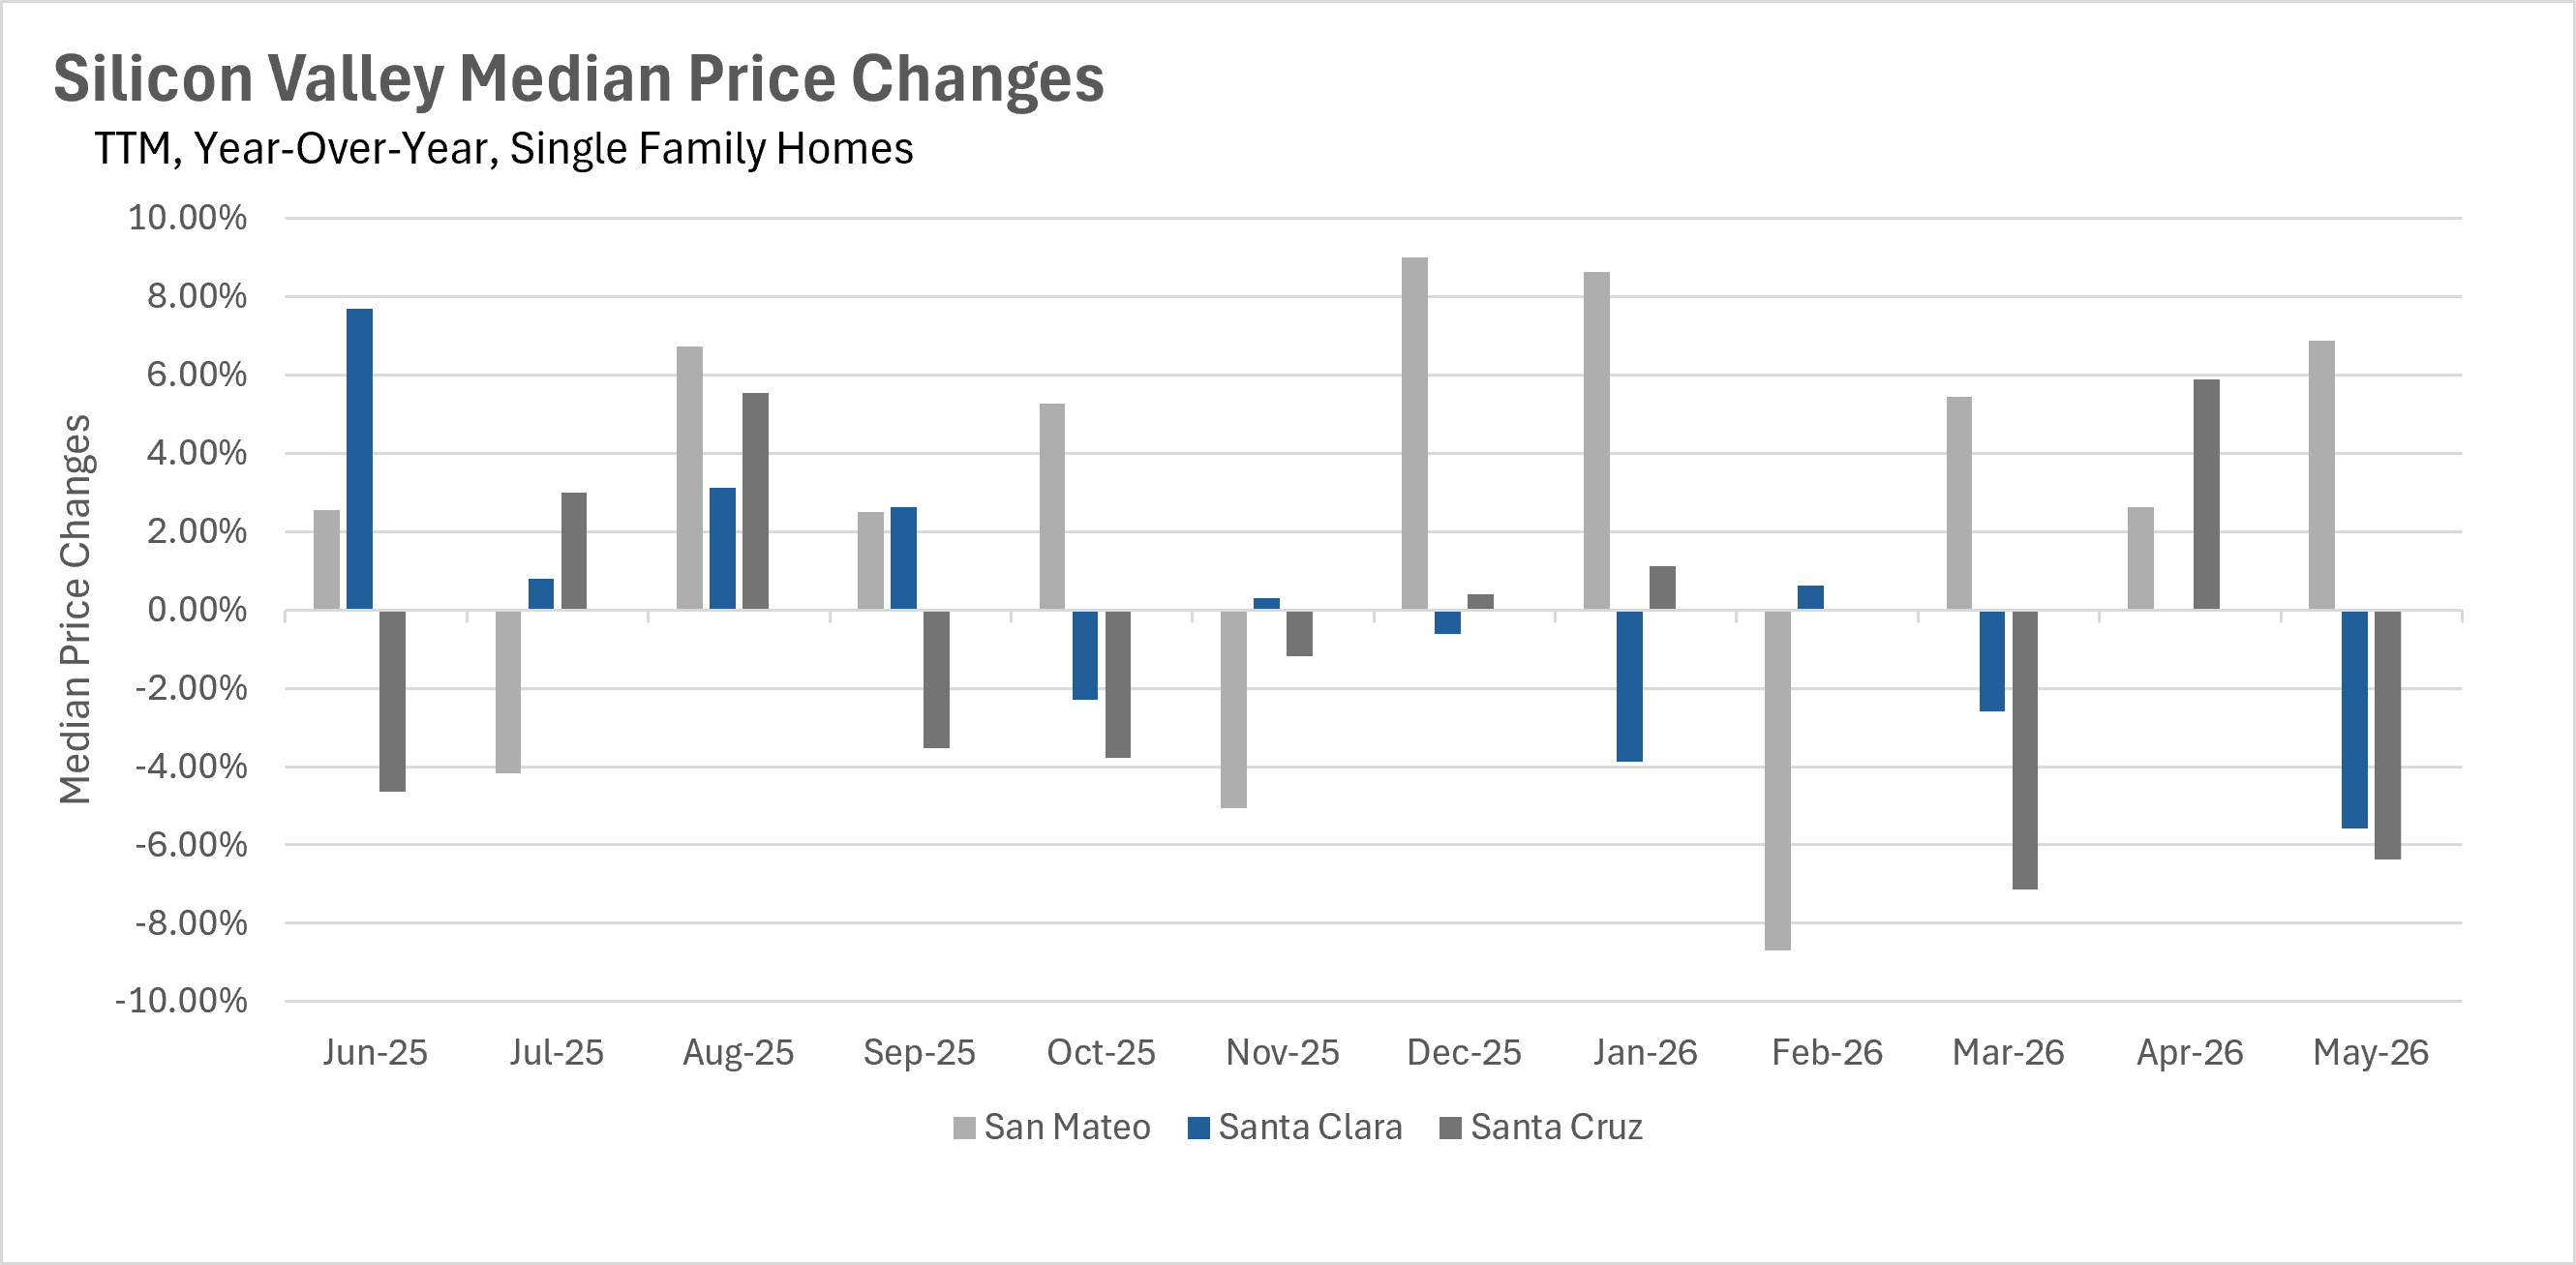Median home sale prices surged past last year's levels in May...
Greater Bay Area market update

The Big Story
Quick Take:
  • Median home sale prices surged past last year's levels in May, as the spring selling season continues to build momentum.
  • Inventory levels have climbed back to where they were at this time last year, giving buyers more options heading into the summer.
  • Existing home sales posted their strongest year-over-year gain in quite some time, signaling that buyers are finally coming off the sidelines.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.

The spring rally is in full swing
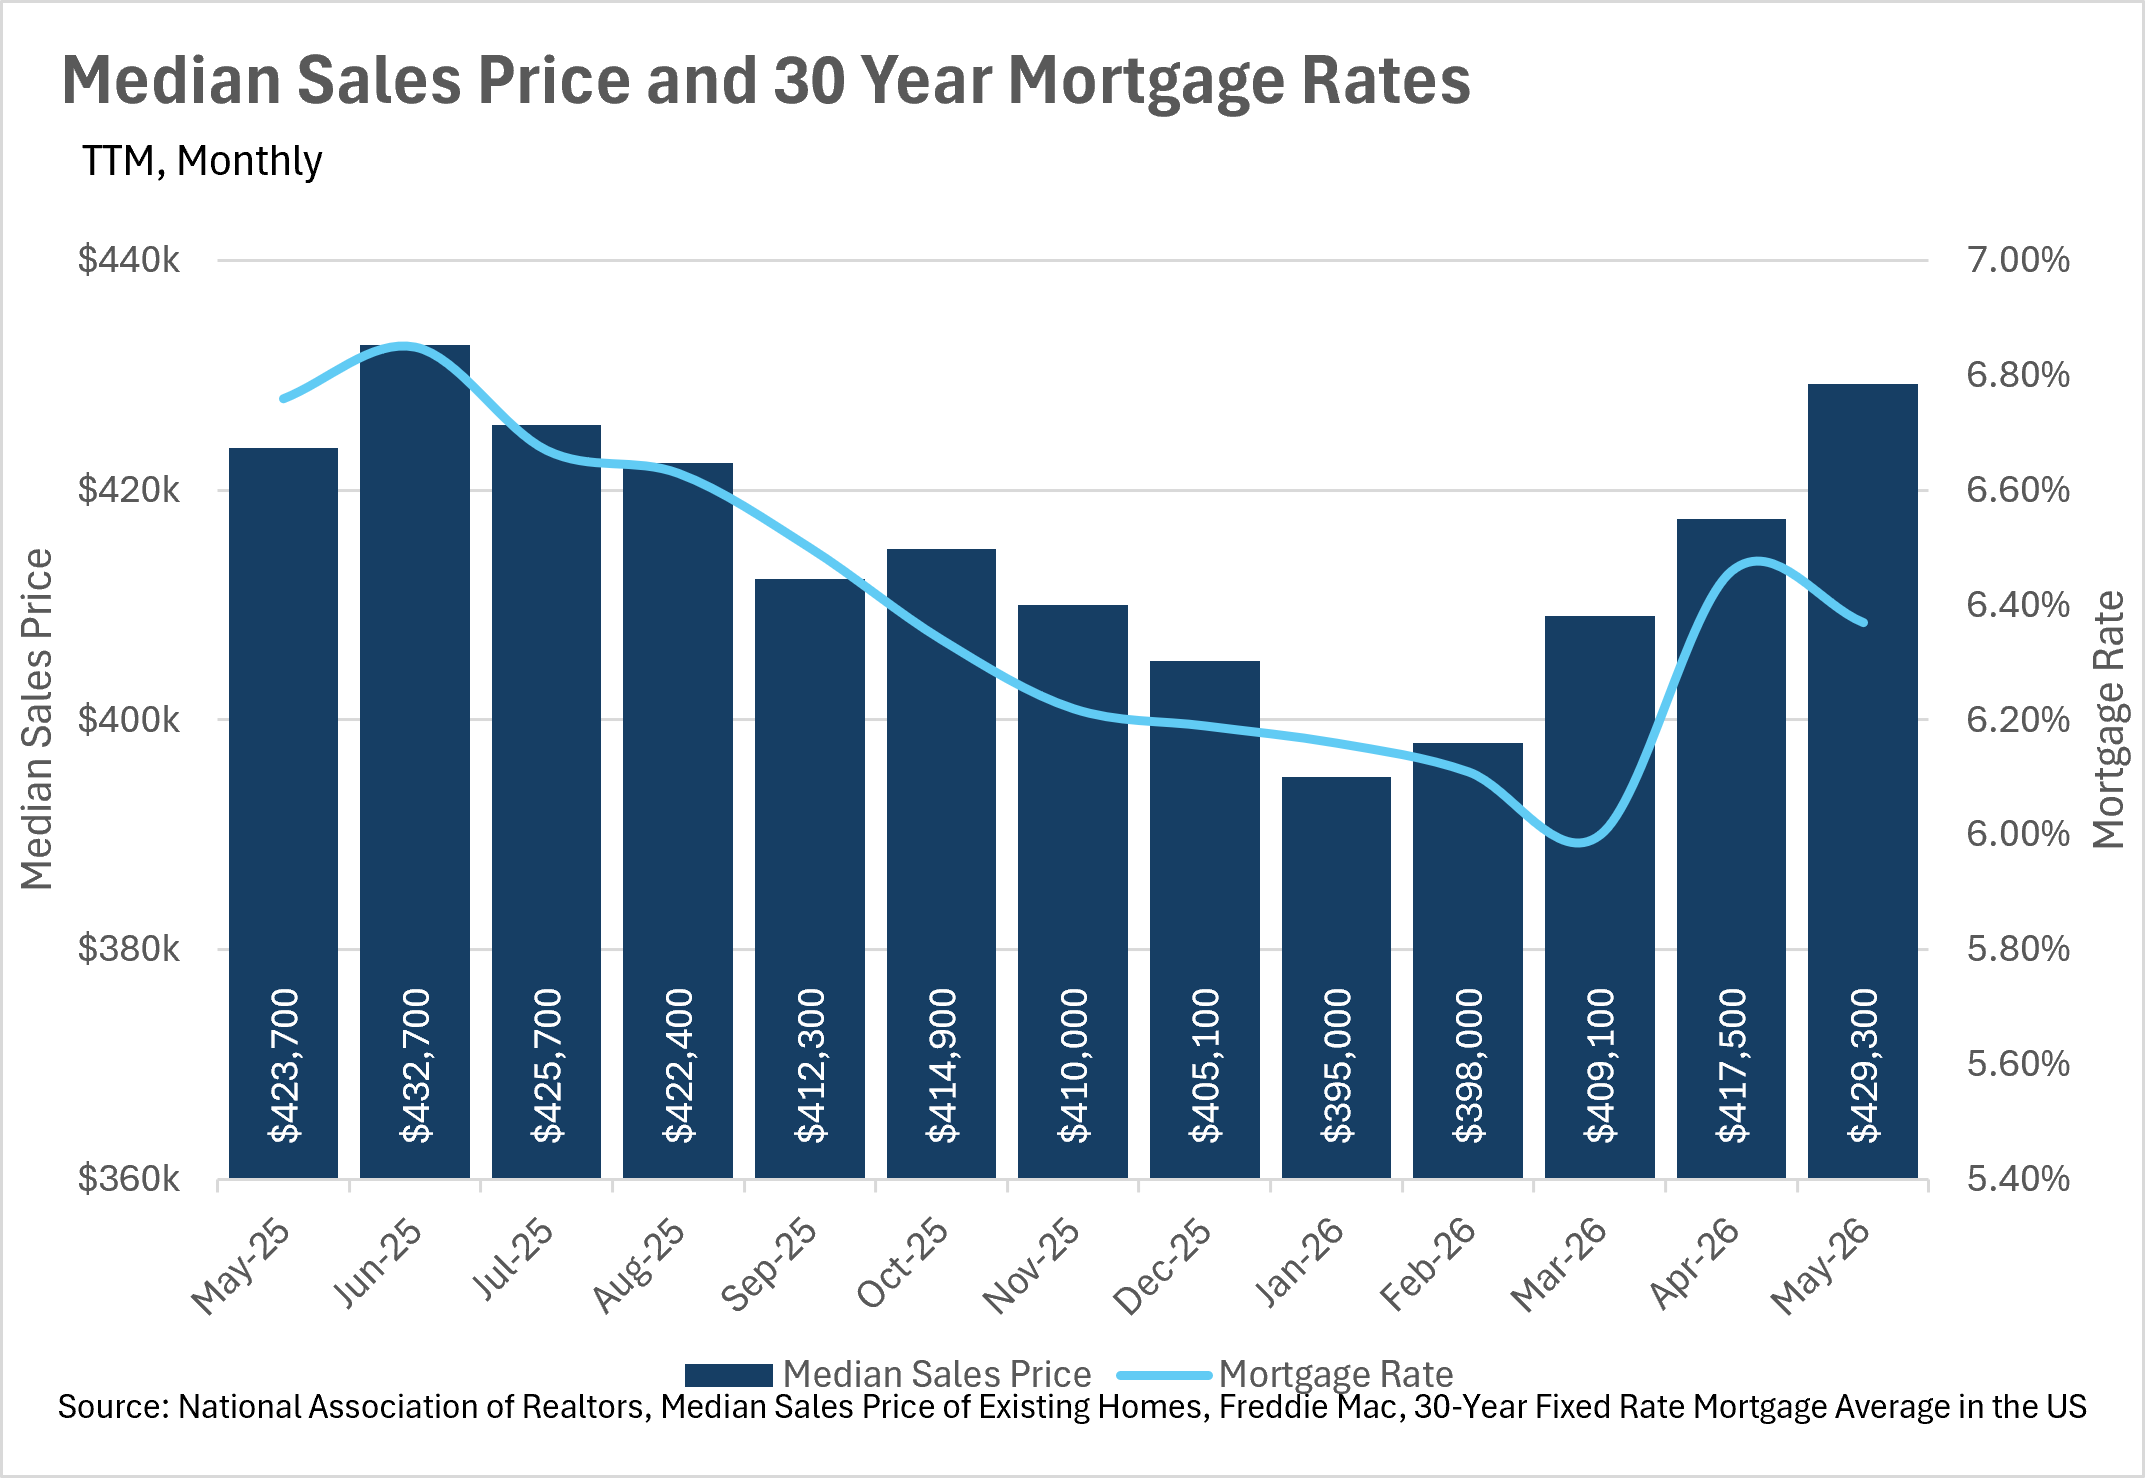
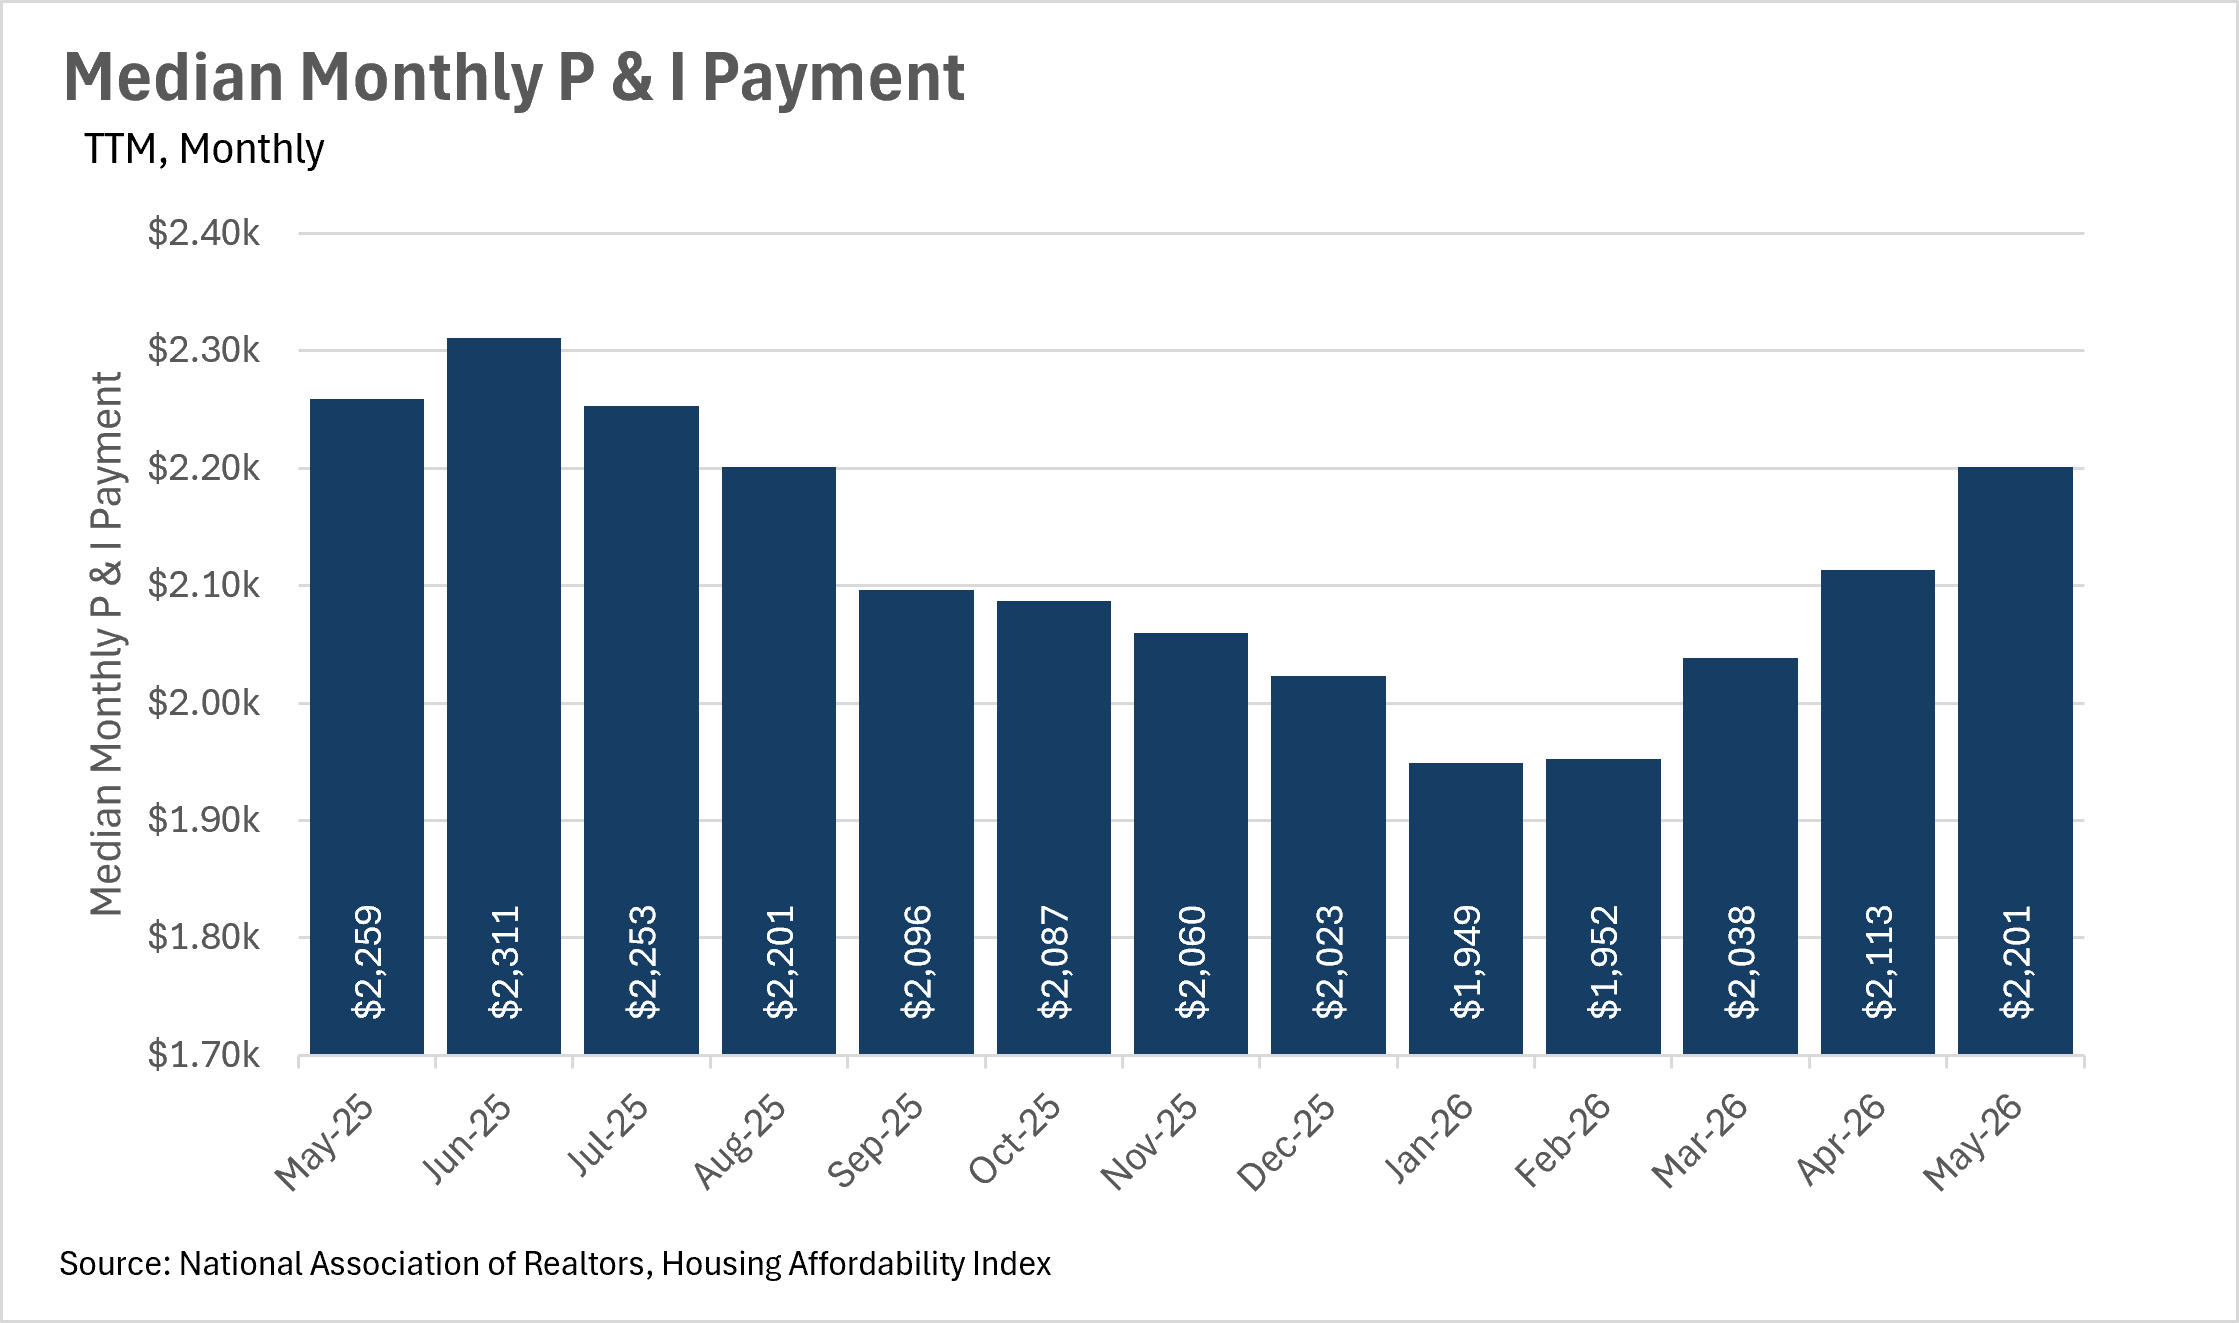
The spring selling season has delivered exactly the kind of price action that sellers were hoping for. The median home sold for $429,300 in May, representing a 2.83% month-over-month increase and a 1.32% year-over-year gain. This marks the fourth consecutive month of month-over-month price increases since the market bottomed out at $395,000 in January, and it's the highest median sale price we've seen since last summer. Helping fuel this rally is the fact that mortgage rates have come back down a bit after their April spike, settling at 6.37% in May, which is 5.77% lower than the 6.76% we were seeing at this time last year. That said, the median monthly P&I payment came in at $2,201, which is only 2.57% lower than the $2,259 the median homeowner was paying a year ago. The affordability gap is narrowing, as rising prices are beginning to eat into the savings that lower rates have provided. It'll be worth keeping a close eye on this dynamic as we move deeper into the summer months.
Inventory is back to last year's levels just in time for the summer rush
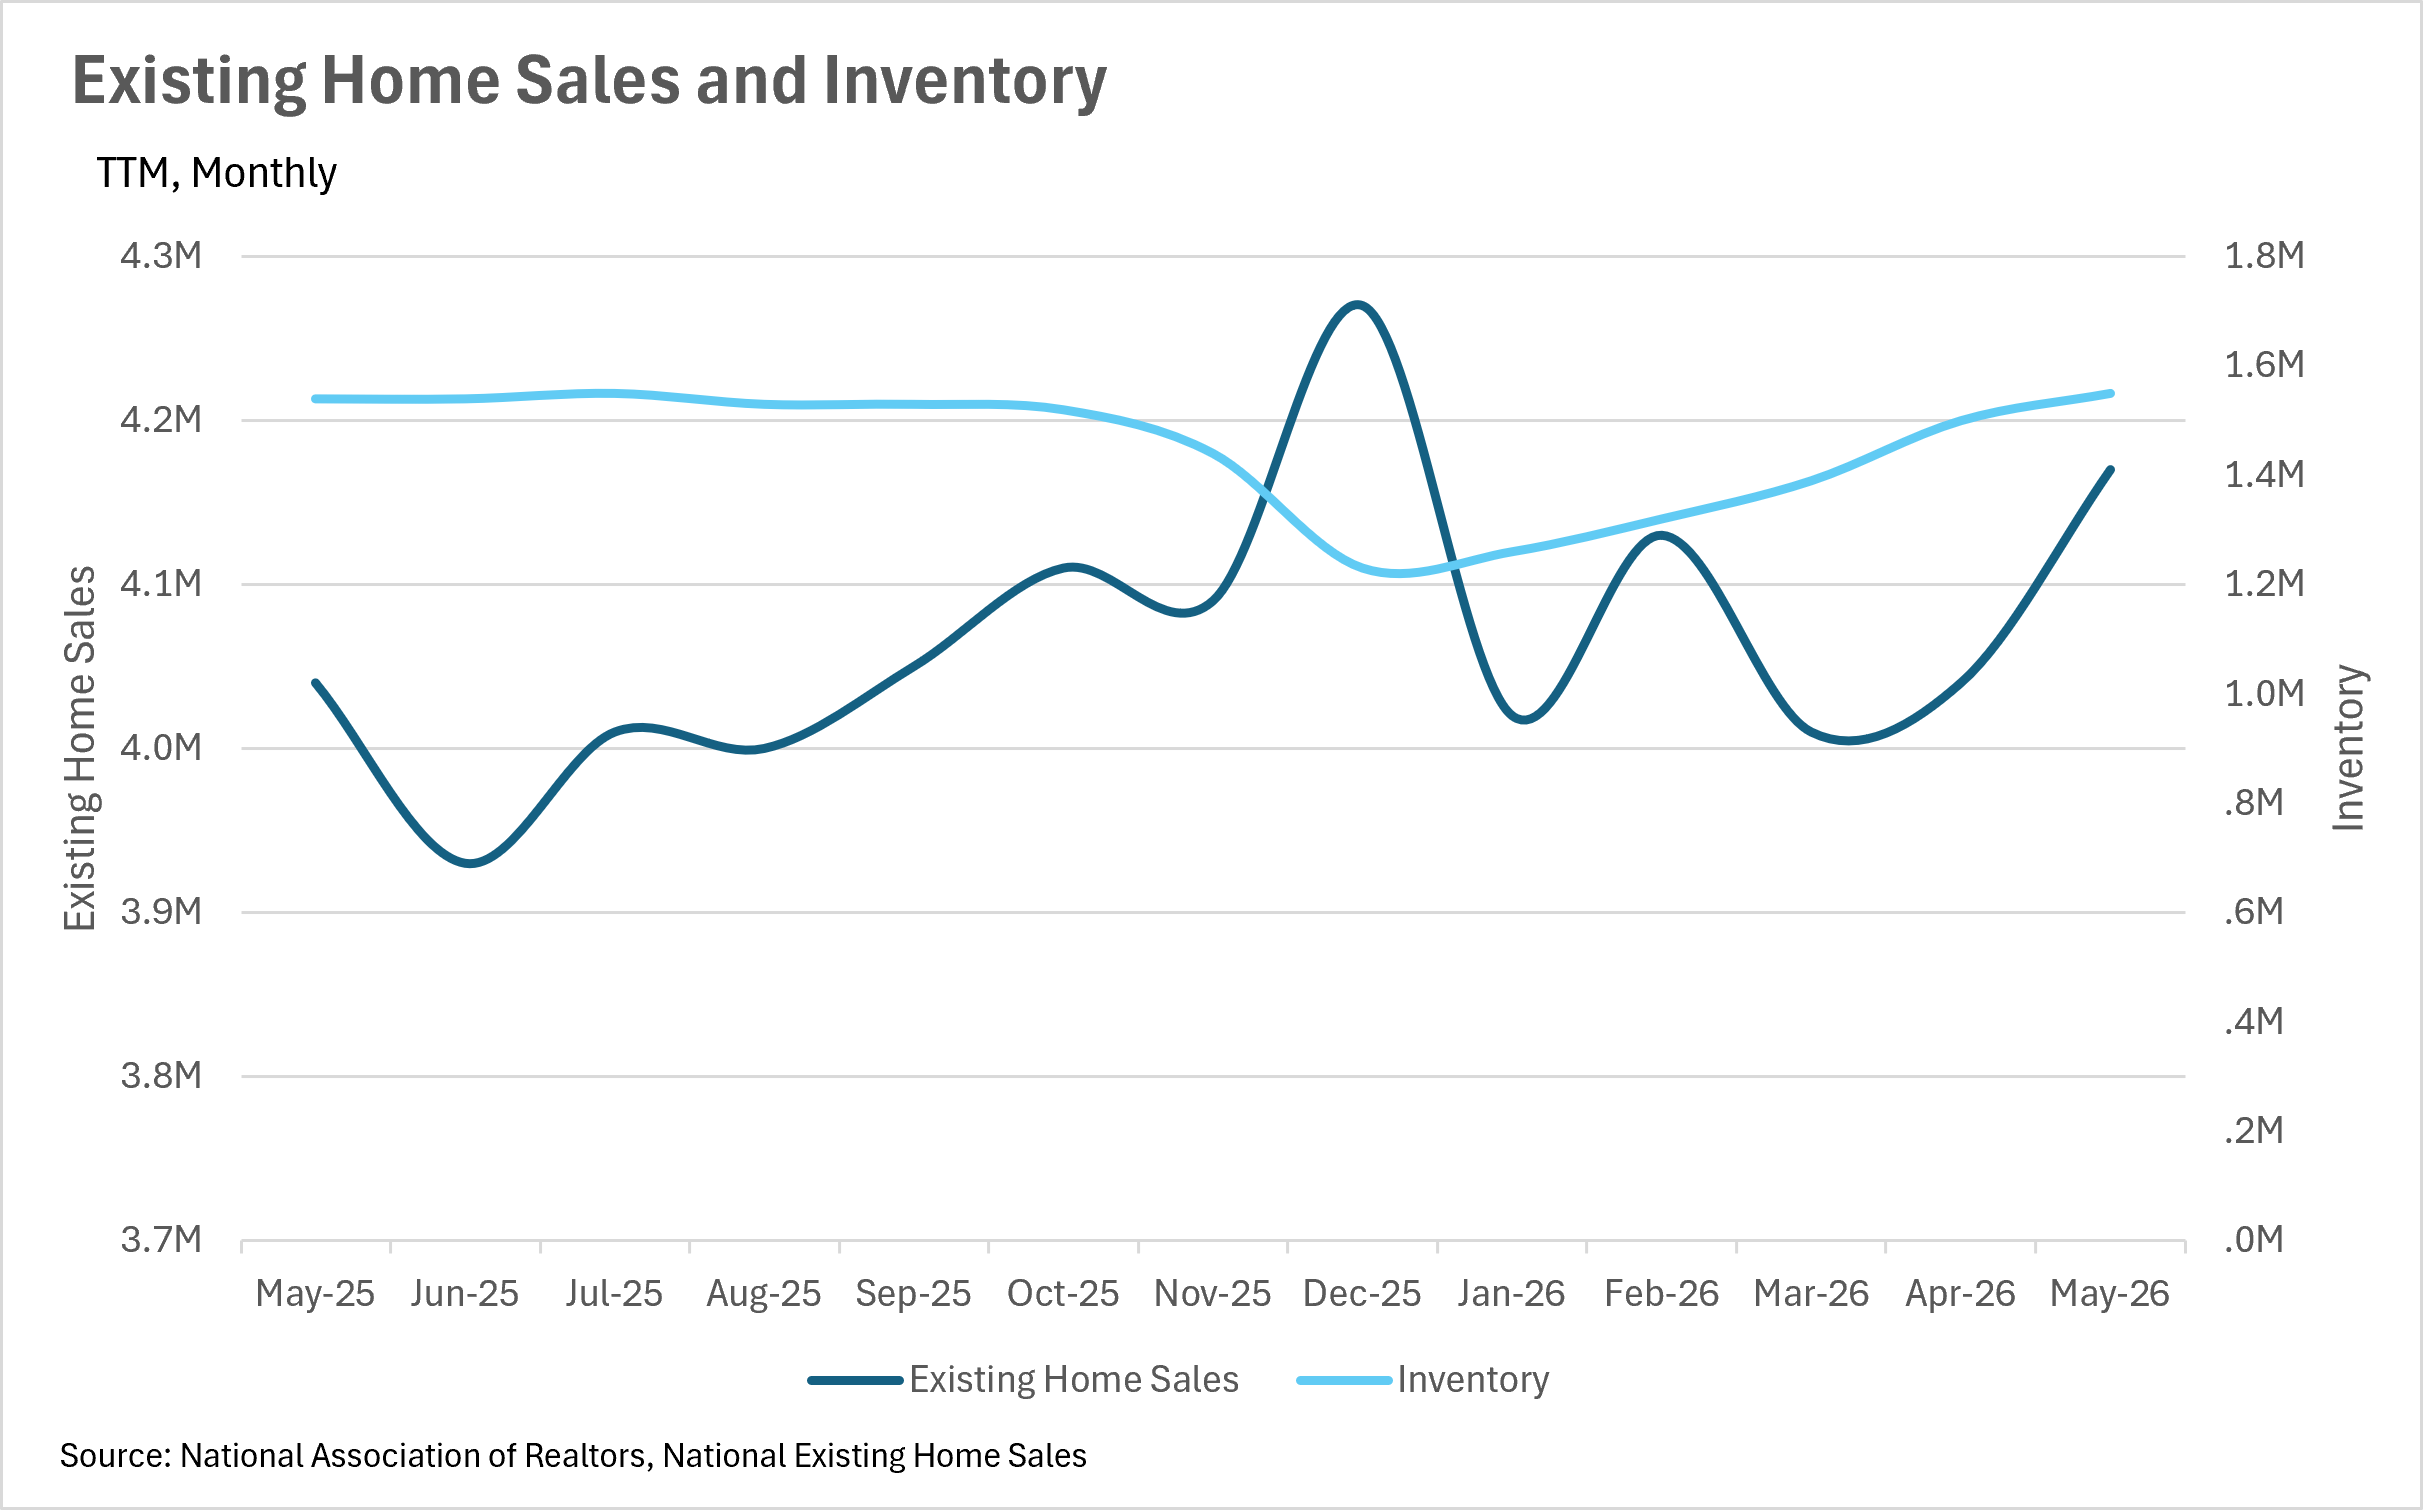
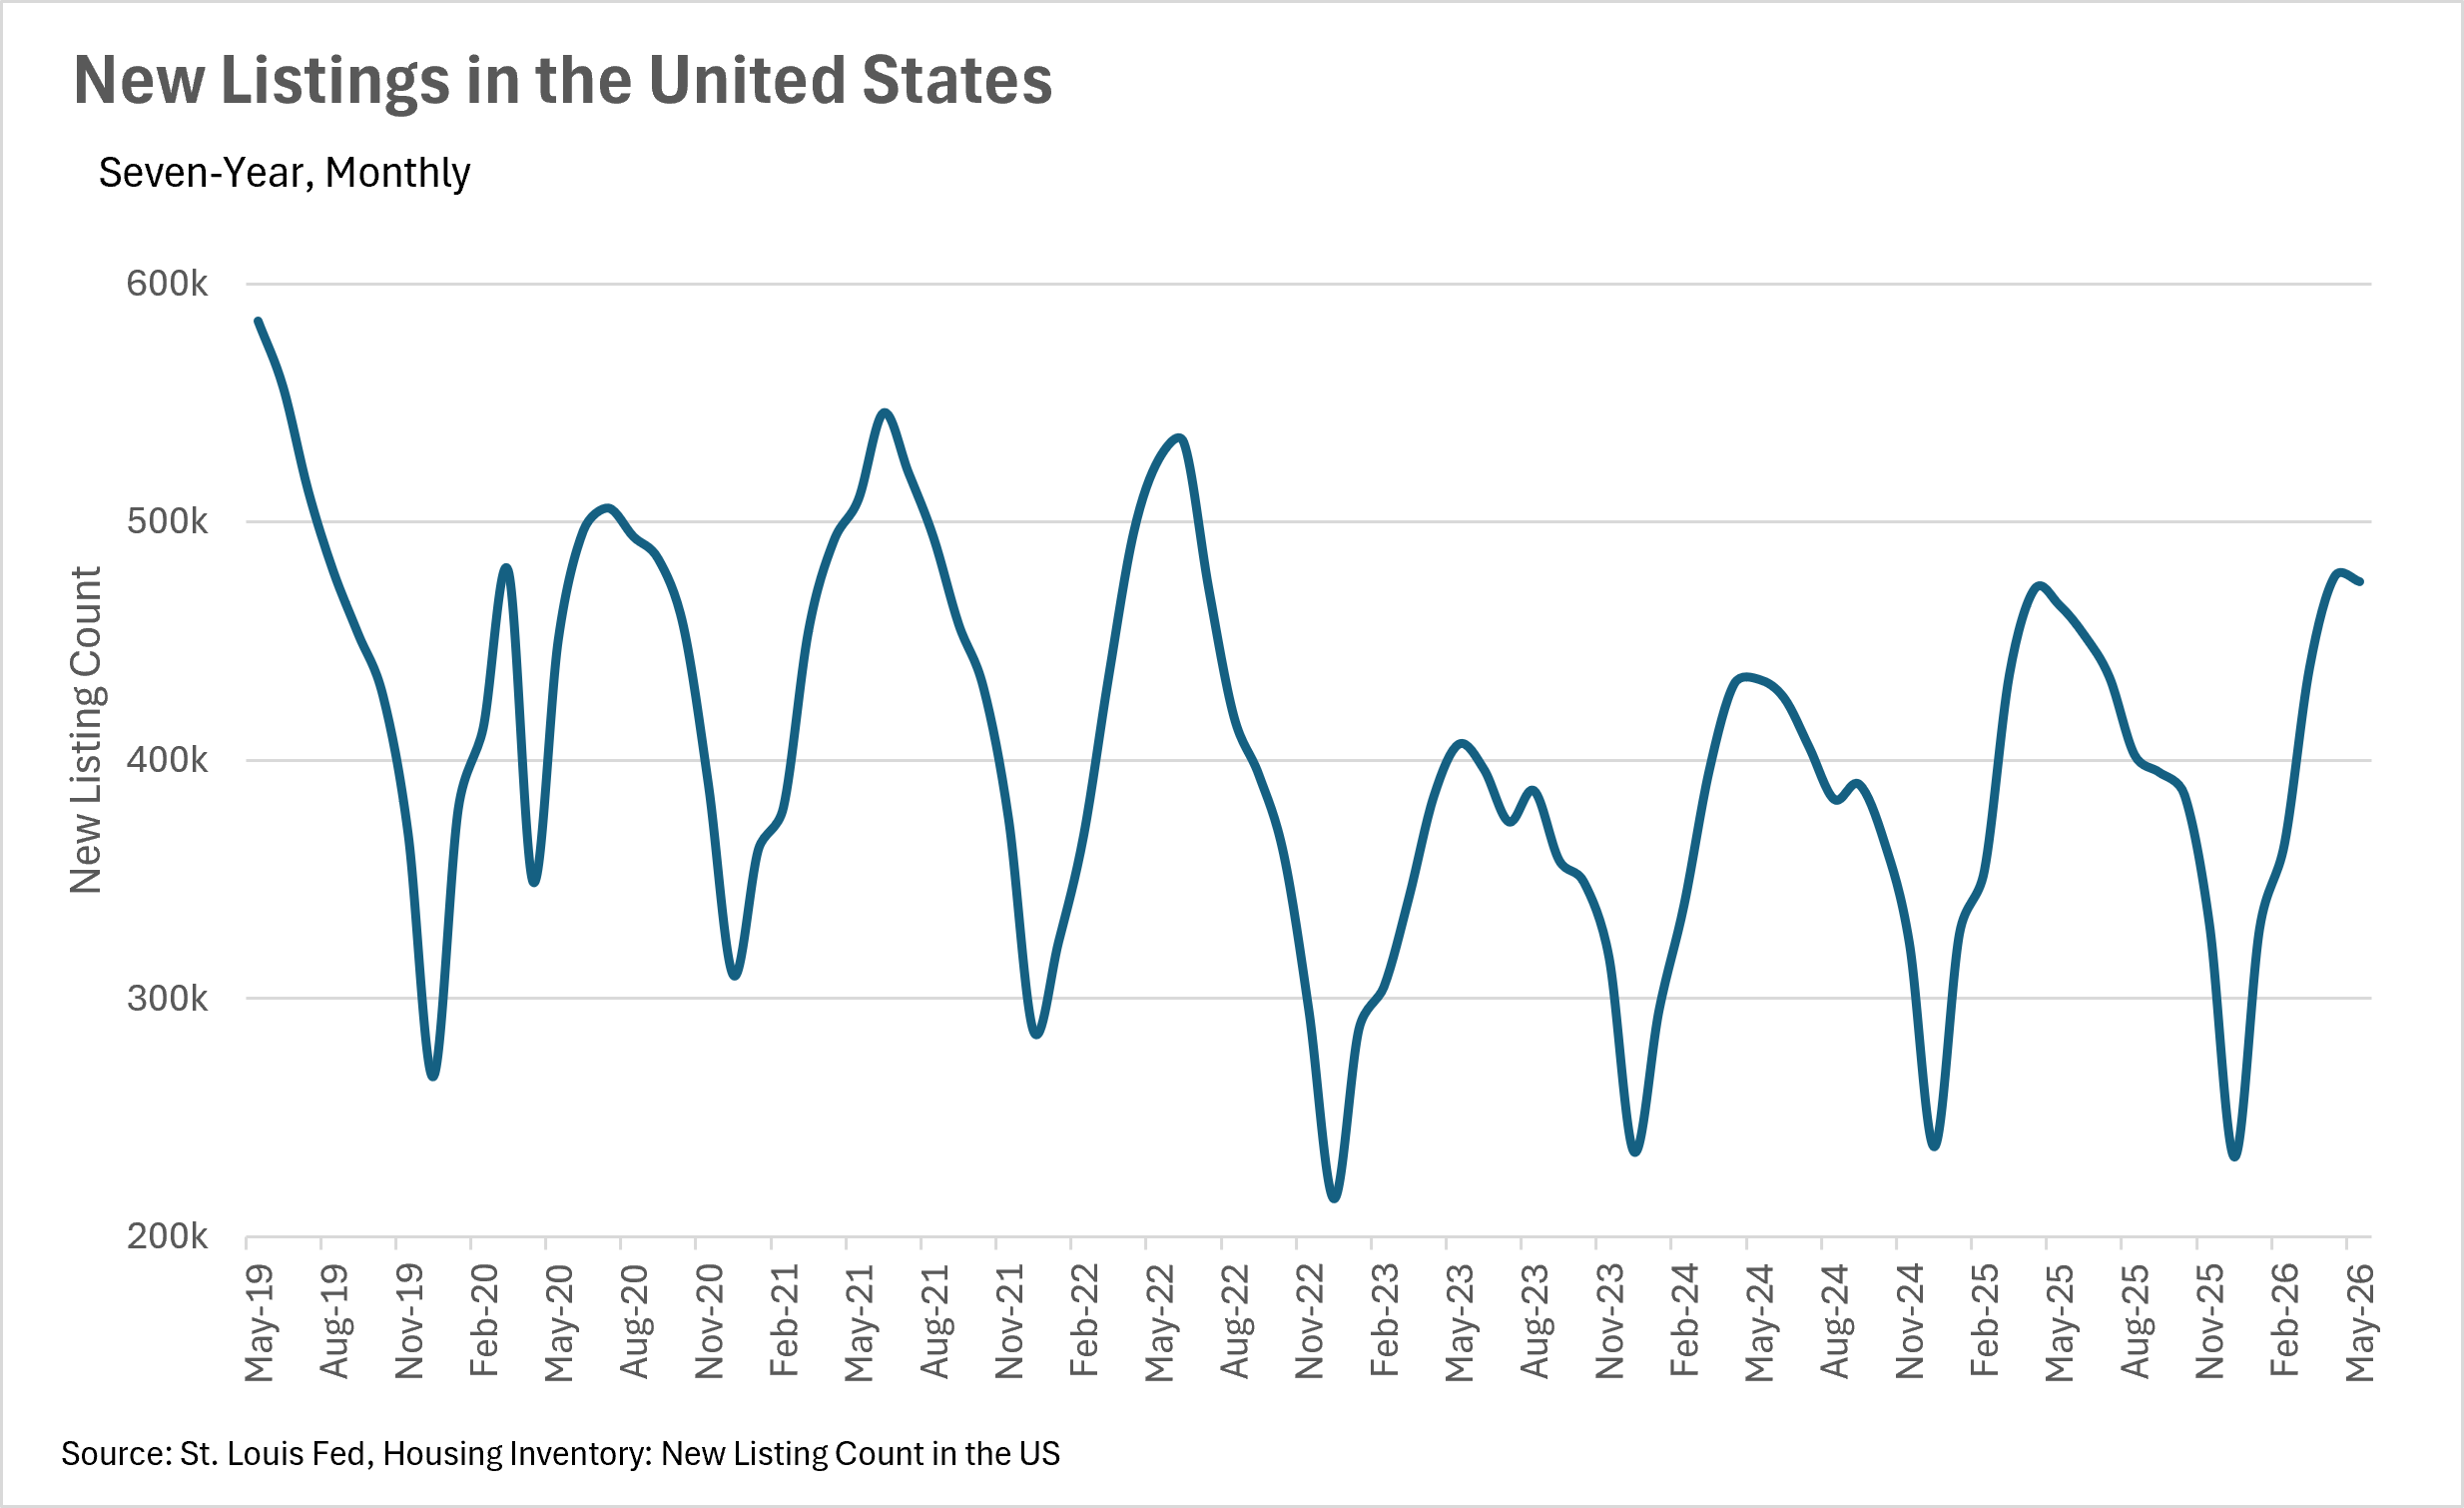
After spending much of the winter and early spring playing catch-up, inventory levels have finally returned to where they were at this time last year. In May, there were 1,550,000 homes available for sale, representing a 0.65% year-over-year increase and a 3.33% month-over-month gain. While the year-over-year increase is modest, it's encouraging to see inventory keeping pace with last year's levels, especially considering how tight supply has been for the past several years. On the new listings front, 474,976 new listings hit the market in May, representing a 2.12% year-over-year increase, though this was a slight 0.45% decline from April's pace. This tells us that sellers are still actively listing their homes, but the initial spring rush may be tapering off just a bit. If inventory continues to build through June and July, buyers heading into the summer could find themselves with the most options they've had in years.
Buyers are back, and they're buying
Perhaps the most encouraging data point this month is the significant uptick in existing home sales. In May, 4,170,000 homes changed hands, representing a 3.22% increase on both a month-over-month and year-over-year basis. This is a meaningful shift from the sluggish sales figures we've been tracking over the past several months, and it suggests that the combination of lower mortgage rates and growing inventory is finally pulling buyers off the sidelines. It's also worth noting that this is the highest existing home sales figure we've seen since December, when the market saw its seasonal year-end push. If this momentum carries through the summer, we could be looking at one of the more active selling seasons we've seen in recent years. Of course, the big wildcard here is mortgage rates. If rates continue to decline, it could add even more fuel to the fire. But if they tick back up, as they did in April, it could pump the brakes on what has been a very promising start to the summer.
The tug-of-war between buyers and sellers continues
When determining whether a market is a buyers' market or a sellers' market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller's market, whereas markets with more than three months of MSI are considered buyers' markets.

Right now, the national market finds itself in an interesting position. Inventory is growing, but existing home sales are growing right along with it, which means the months of supply on the market hasn't shifted dramatically in either direction. The fact that both supply and demand are ticking up simultaneously tells us that we're in a relatively balanced market at the national level. However, the direction of mortgage rates over the next couple of months will likely determine which way the scale tips. If rates continue their downward trajectory, demand could outpace supply, pushing us back toward a seller's market. On the other hand, if rates climb again, inventory could pile up, giving buyers the upper hand. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!

Big Story Data

Line chart comparing existing home sales and inventory from May 2025 to May 2026.

Chart of monthly median home prices and 30-year mortgage rates from May 2025 through May 2026.

Line chart of U.S. monthly new listings, May 2019–May 2026, with recurring seasonal peaks and winter lows.

Bar chart of median monthly principal and interest payments, declining to $1,949 in January 2026 before rising to $2,201 in May.

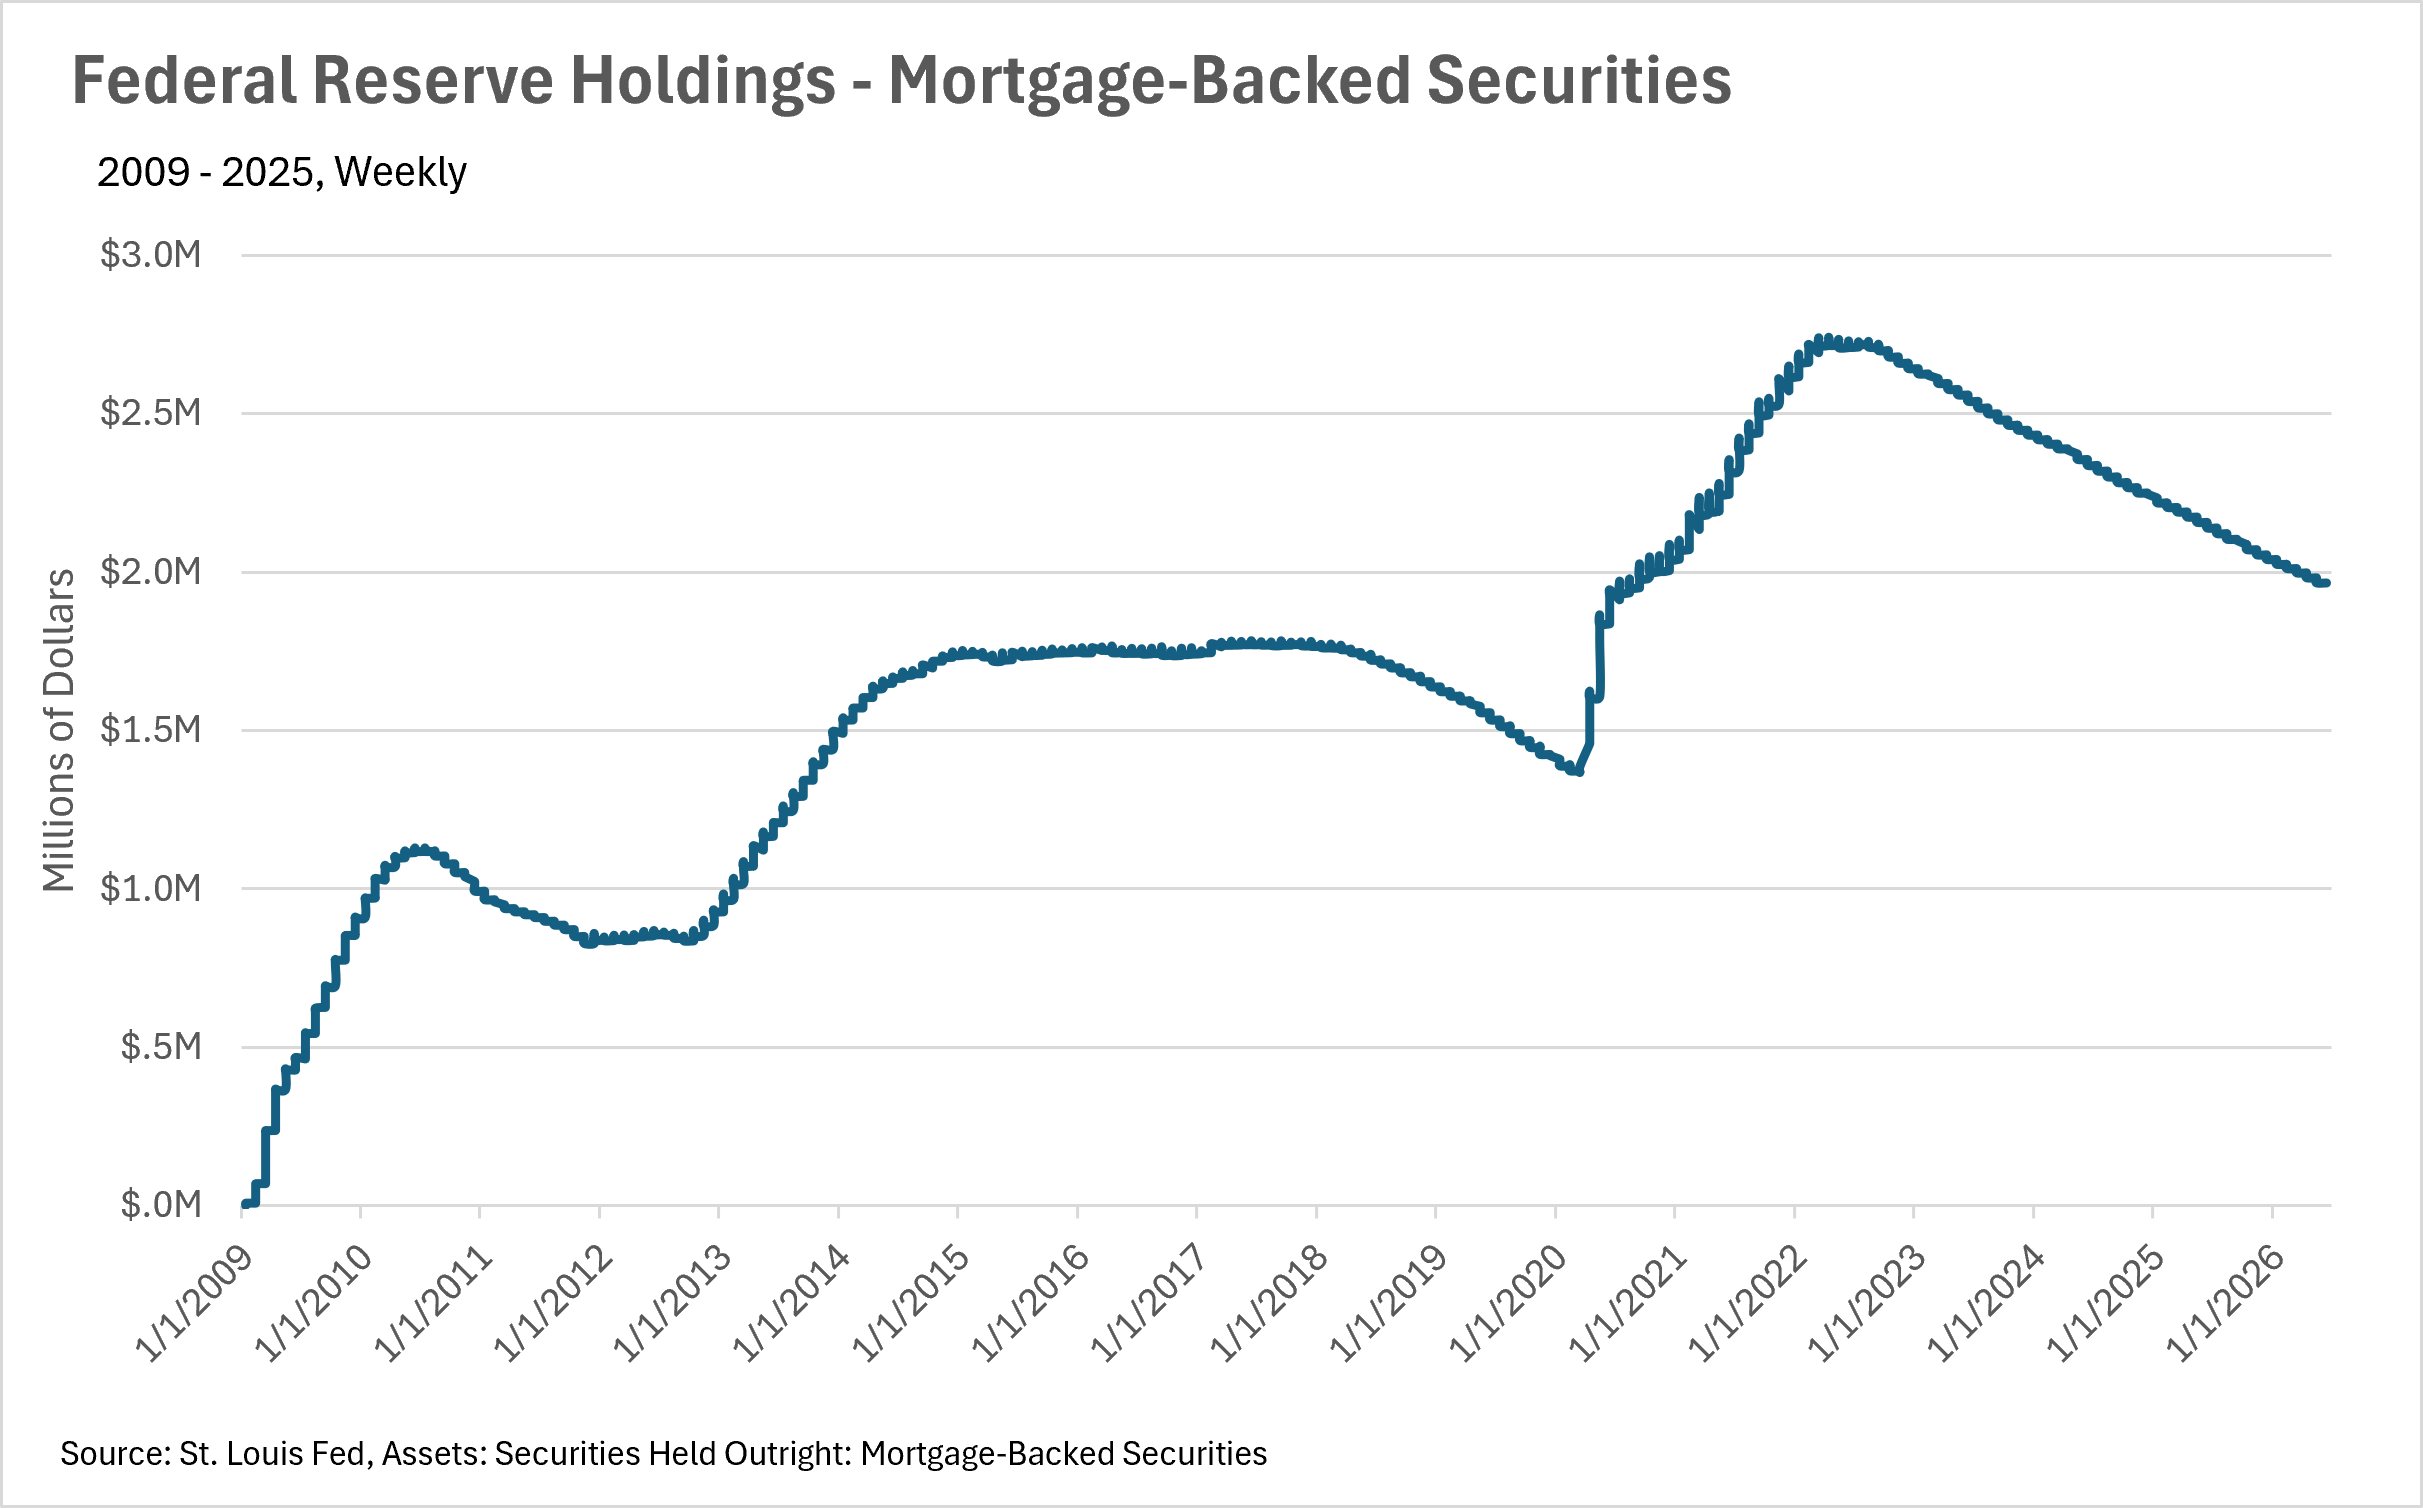
Line chart of Federal Reserve mortgage-backed securities holdings, peaking near $2.7 million in 2022 before declining.

The Local Lowdown
Quick Take:
  • Prices are rising across much of the Bay Area, with San Francisco single-family homes breaching the $2.2 million mark for the first time and the East Bay posting gains across both single-family homes and condos for the first time in over a year.
  • Inventory levels have plummeted across the region, with year-over-year declines ranging from nearly 19% in Silicon Valley to more than 44% in San Francisco, leaving buyers with extremely limited options heading into summer.
  • Single-family homes are selling in roughly two weeks or less throughout the Bay Area, while the condo market is showing signs of improvement in several sub-markets.
  • The single-family home market is firmly in seller's territory across virtually every county, while the condo market remains more favorable for buyers in several East Bay and North Bay markets.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.

Prices are climbing as the Bay Area heads into summer
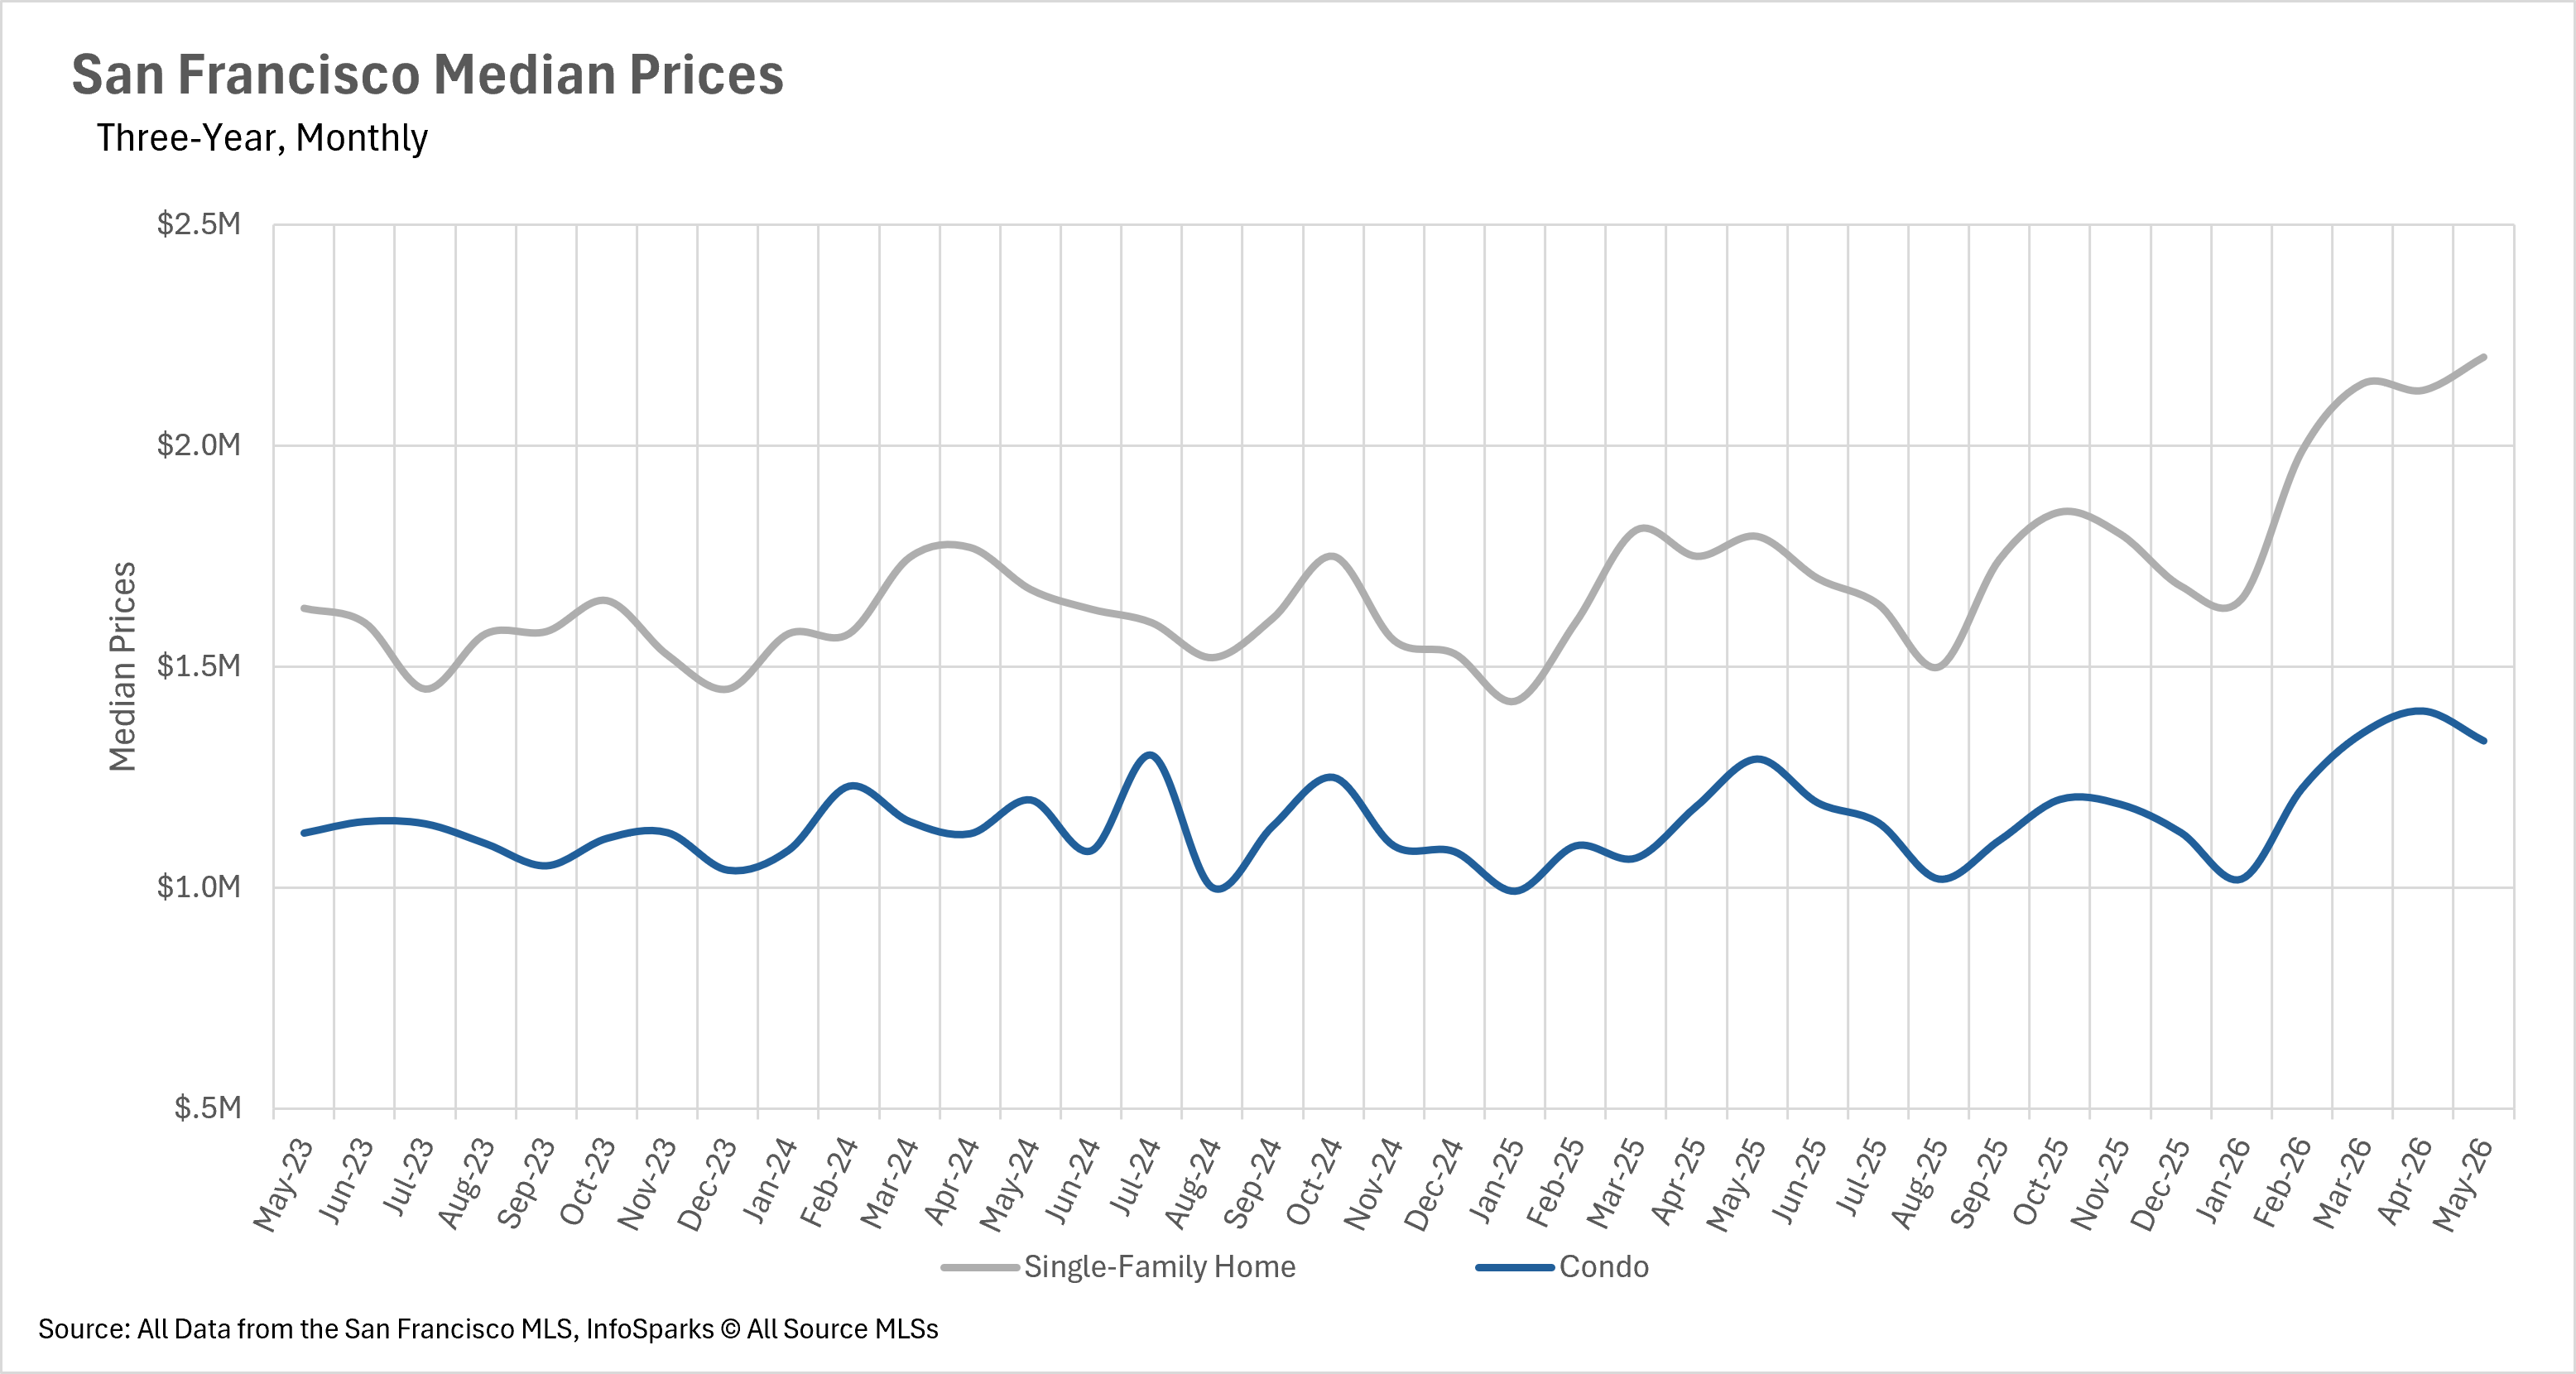
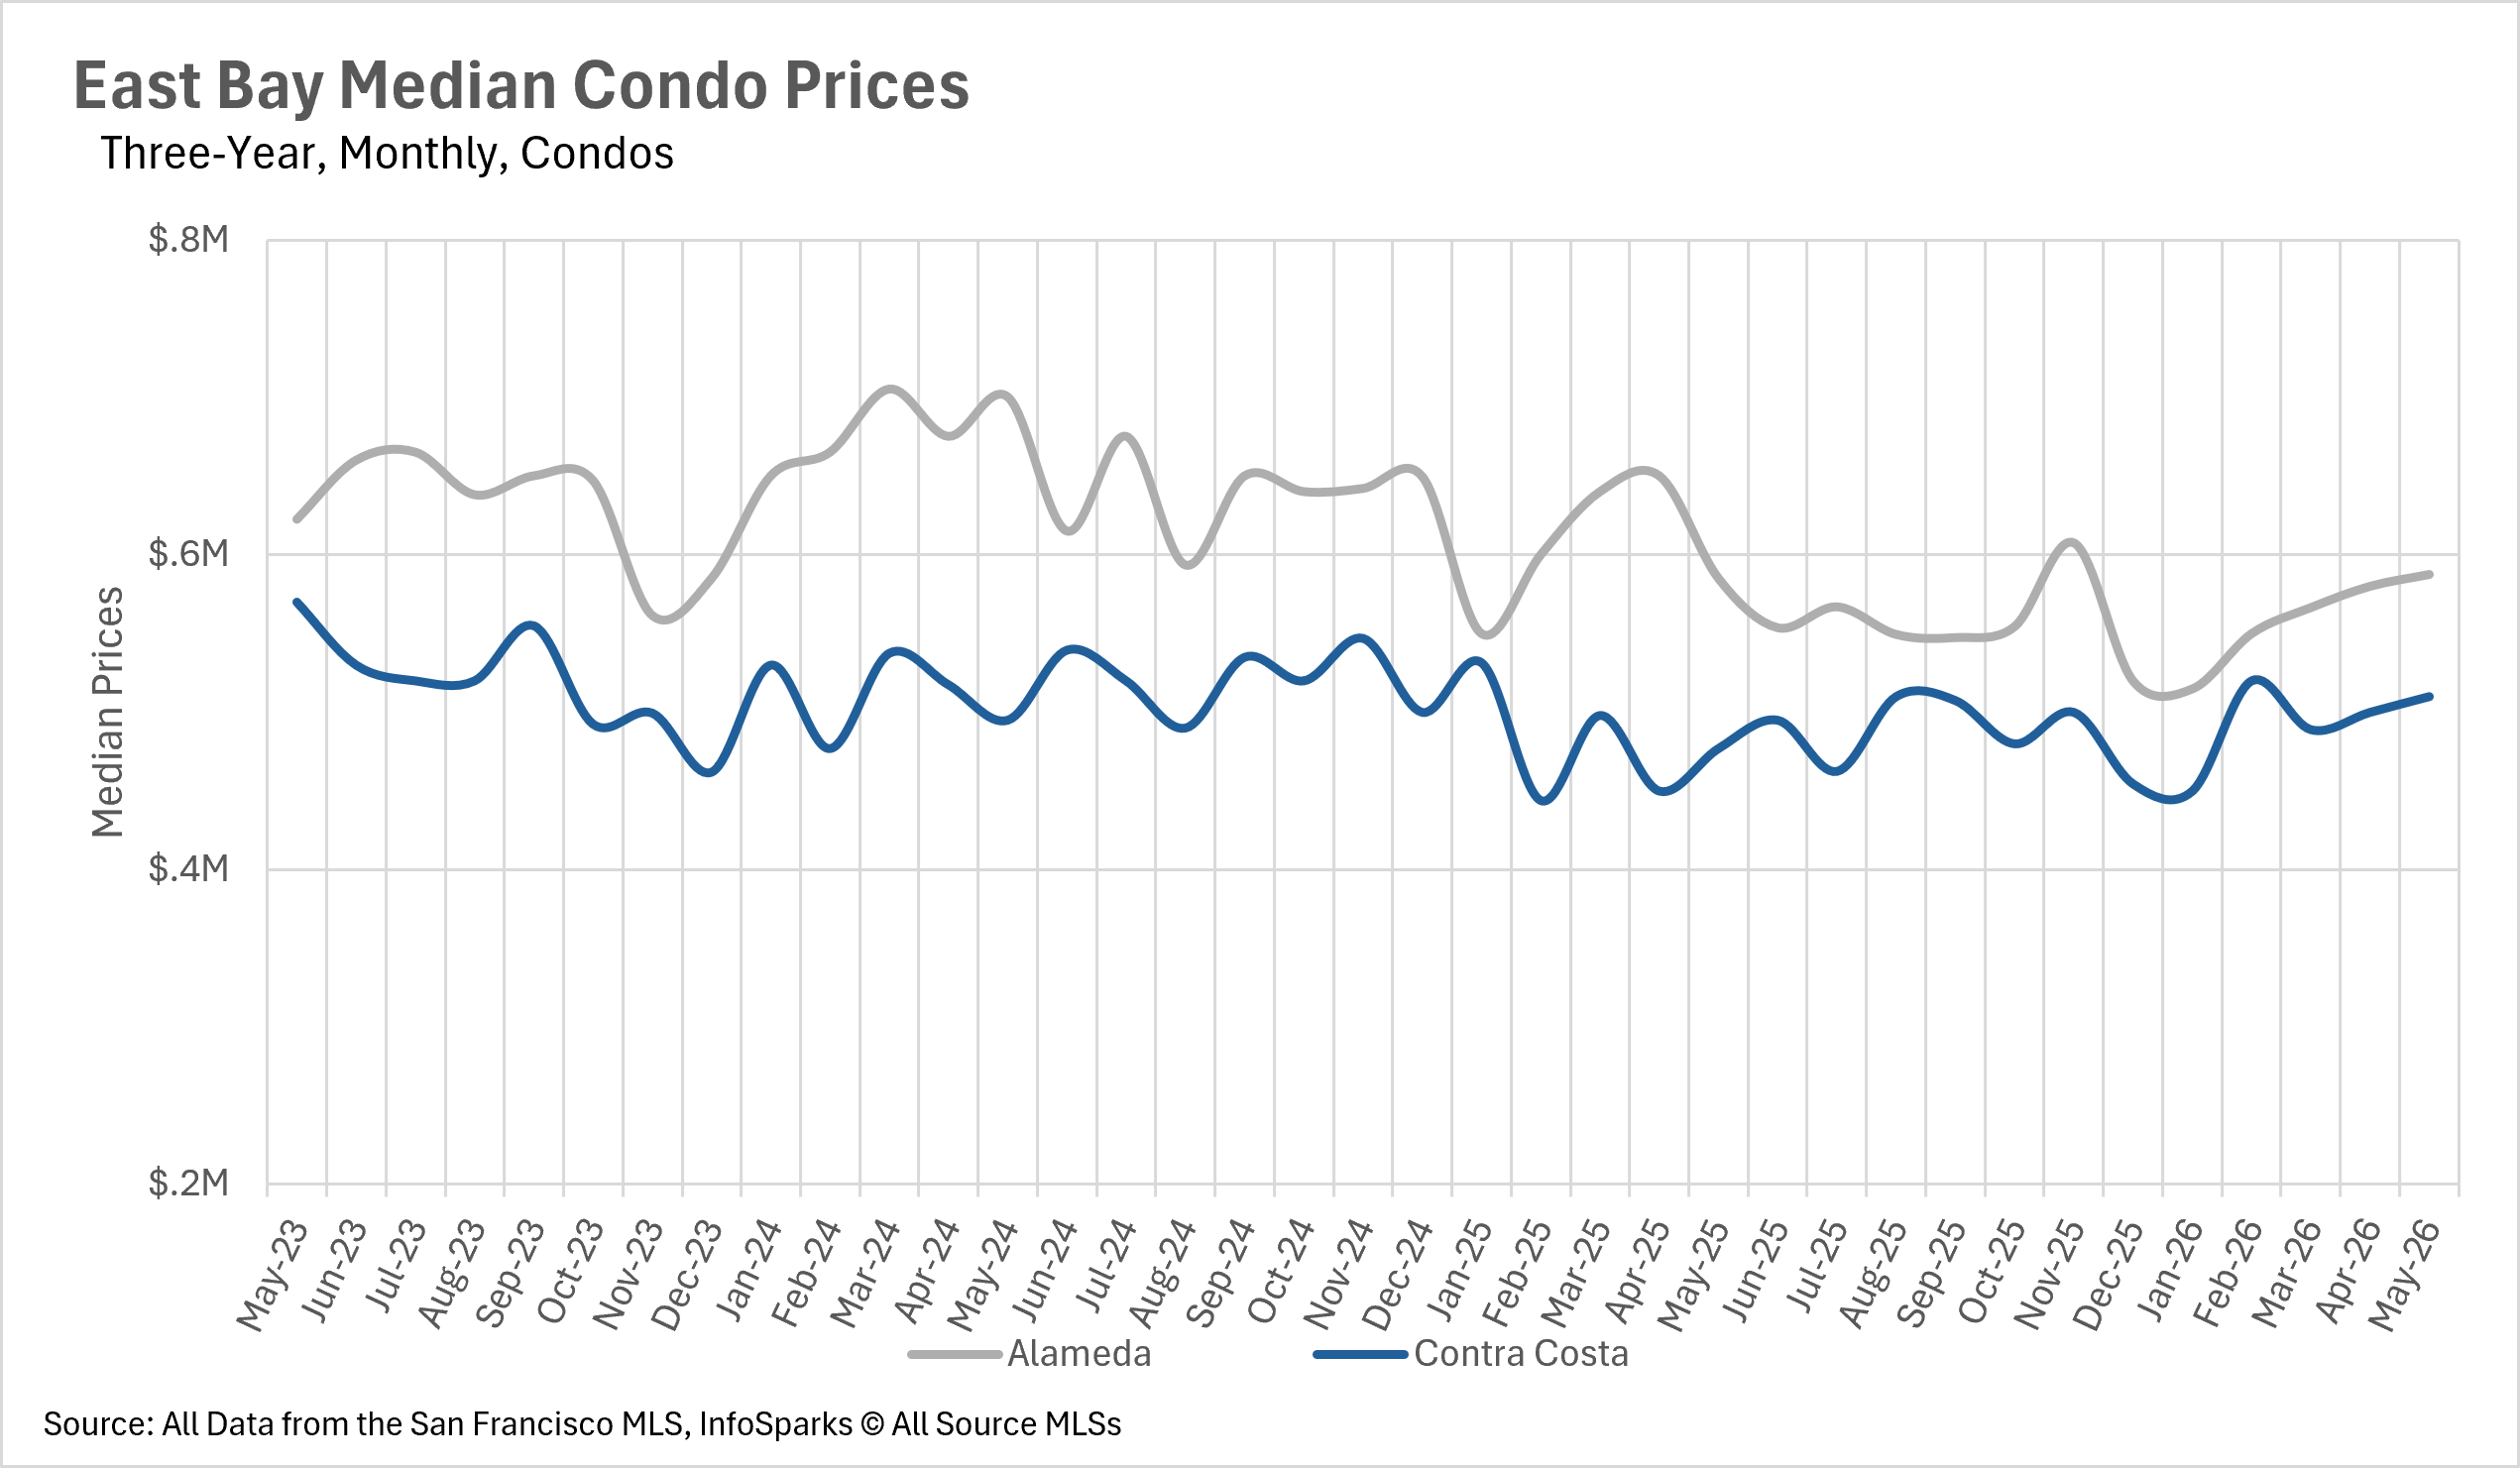
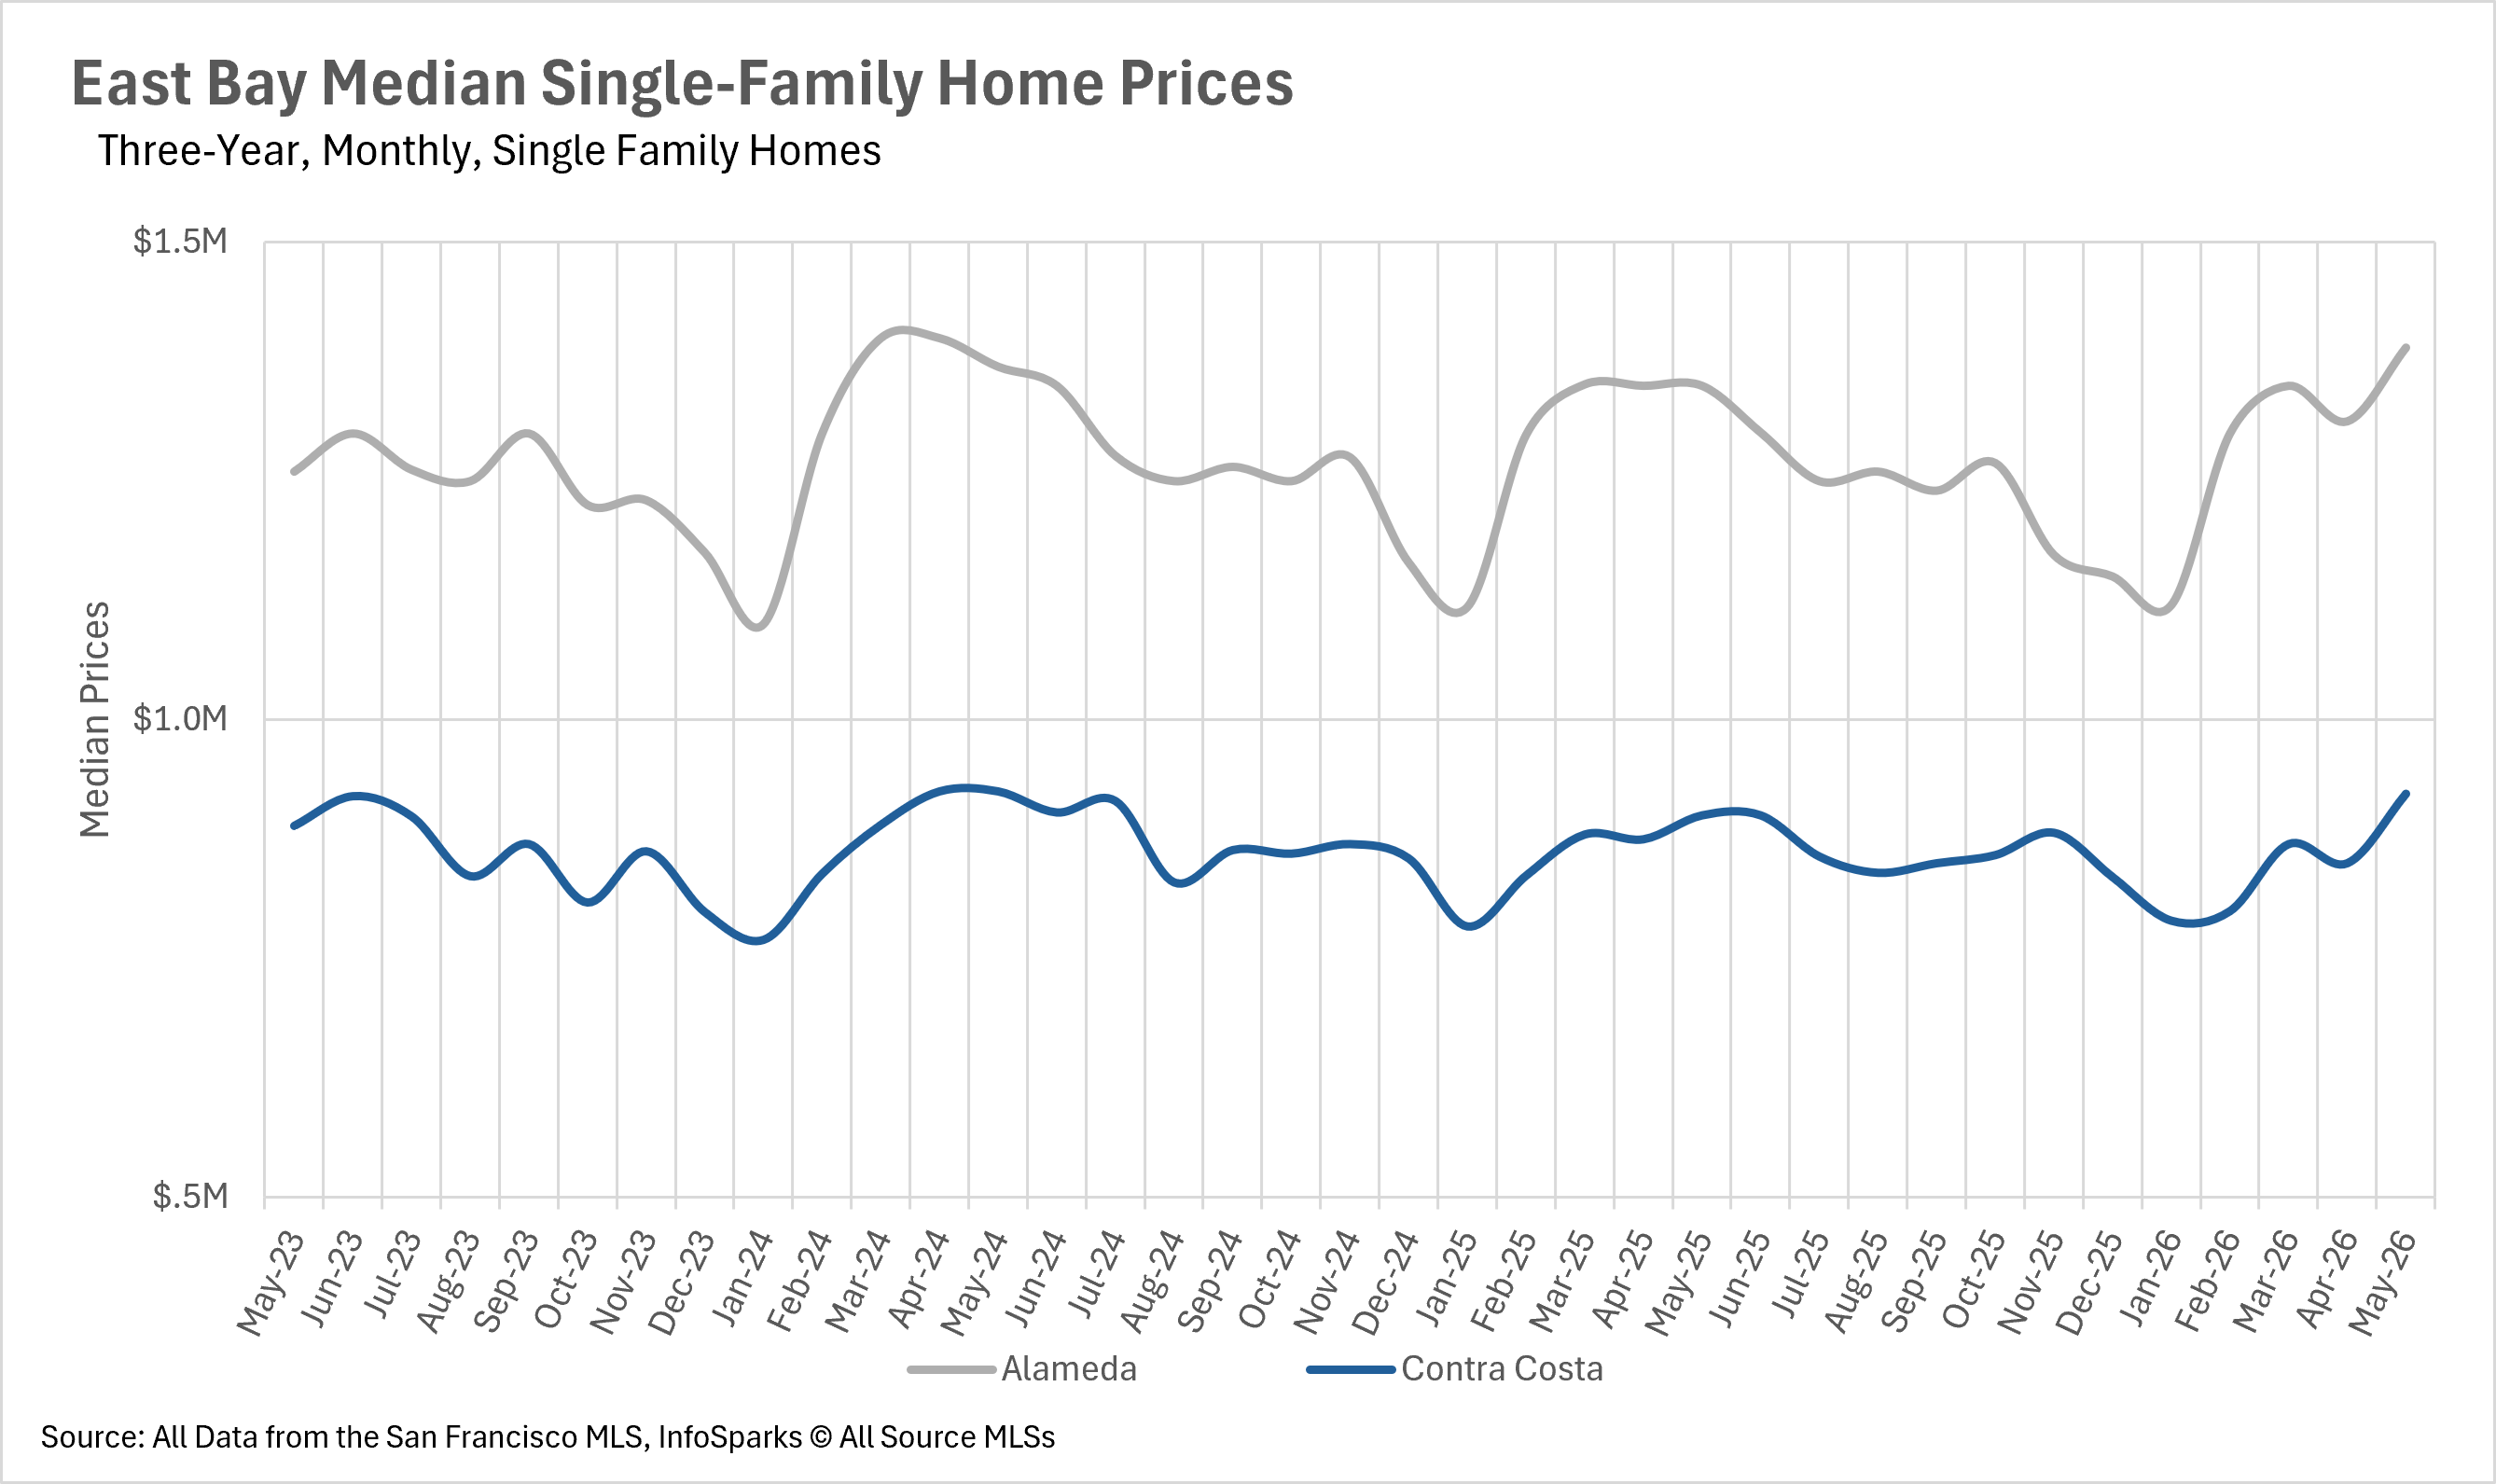
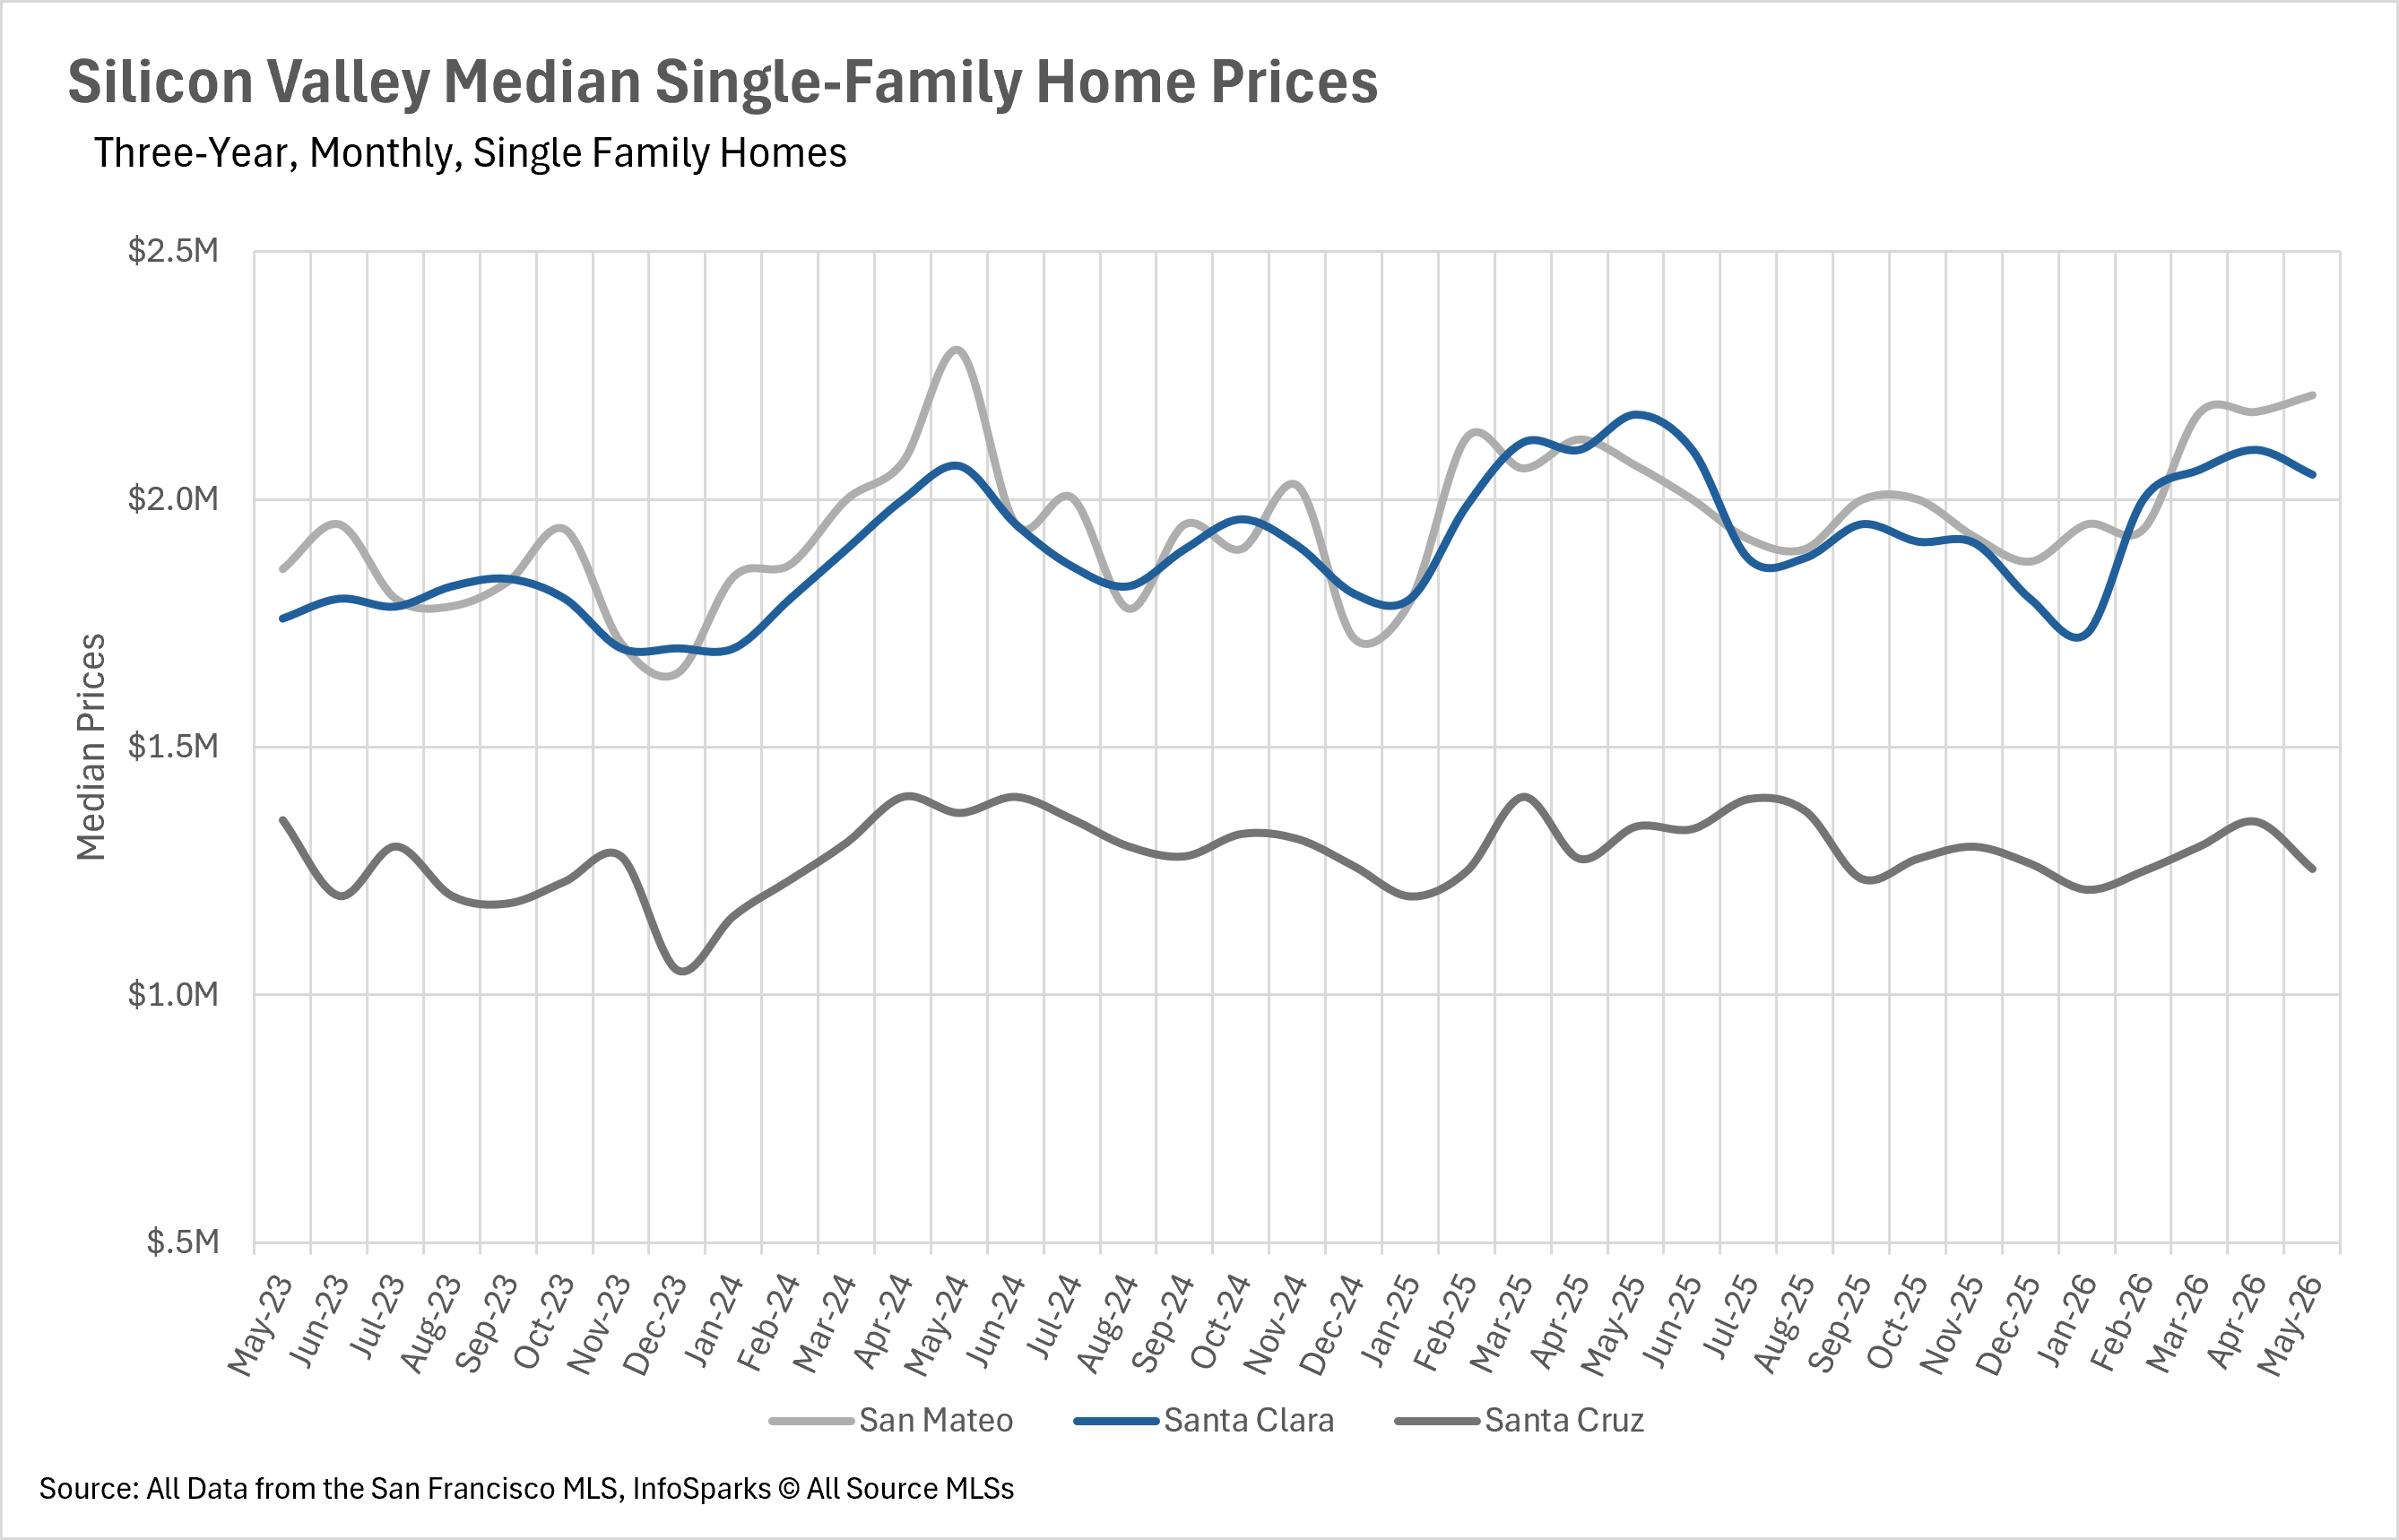
May brought positive momentum to much of the Bay Area's single-family home market, with several notable milestones along the way. San Francisco's median single-family home sale price soared 22.56% year-over-year to $2,200,000, marking one of the strongest gains in the market's recent history. In Silicon Valley, San Mateo County posted an impressive 6.87% year-over-year increase to $2,210,000, though Santa Clara County pulled back 5.58% to $2,050,000 and Santa Cruz County declined 6.38% to $1,254,500. The East Bay delivered a welcome surprise, as both Alameda and Contra Costa Counties posted year-over-year gains of 2.96% and 2.50%, respectively.

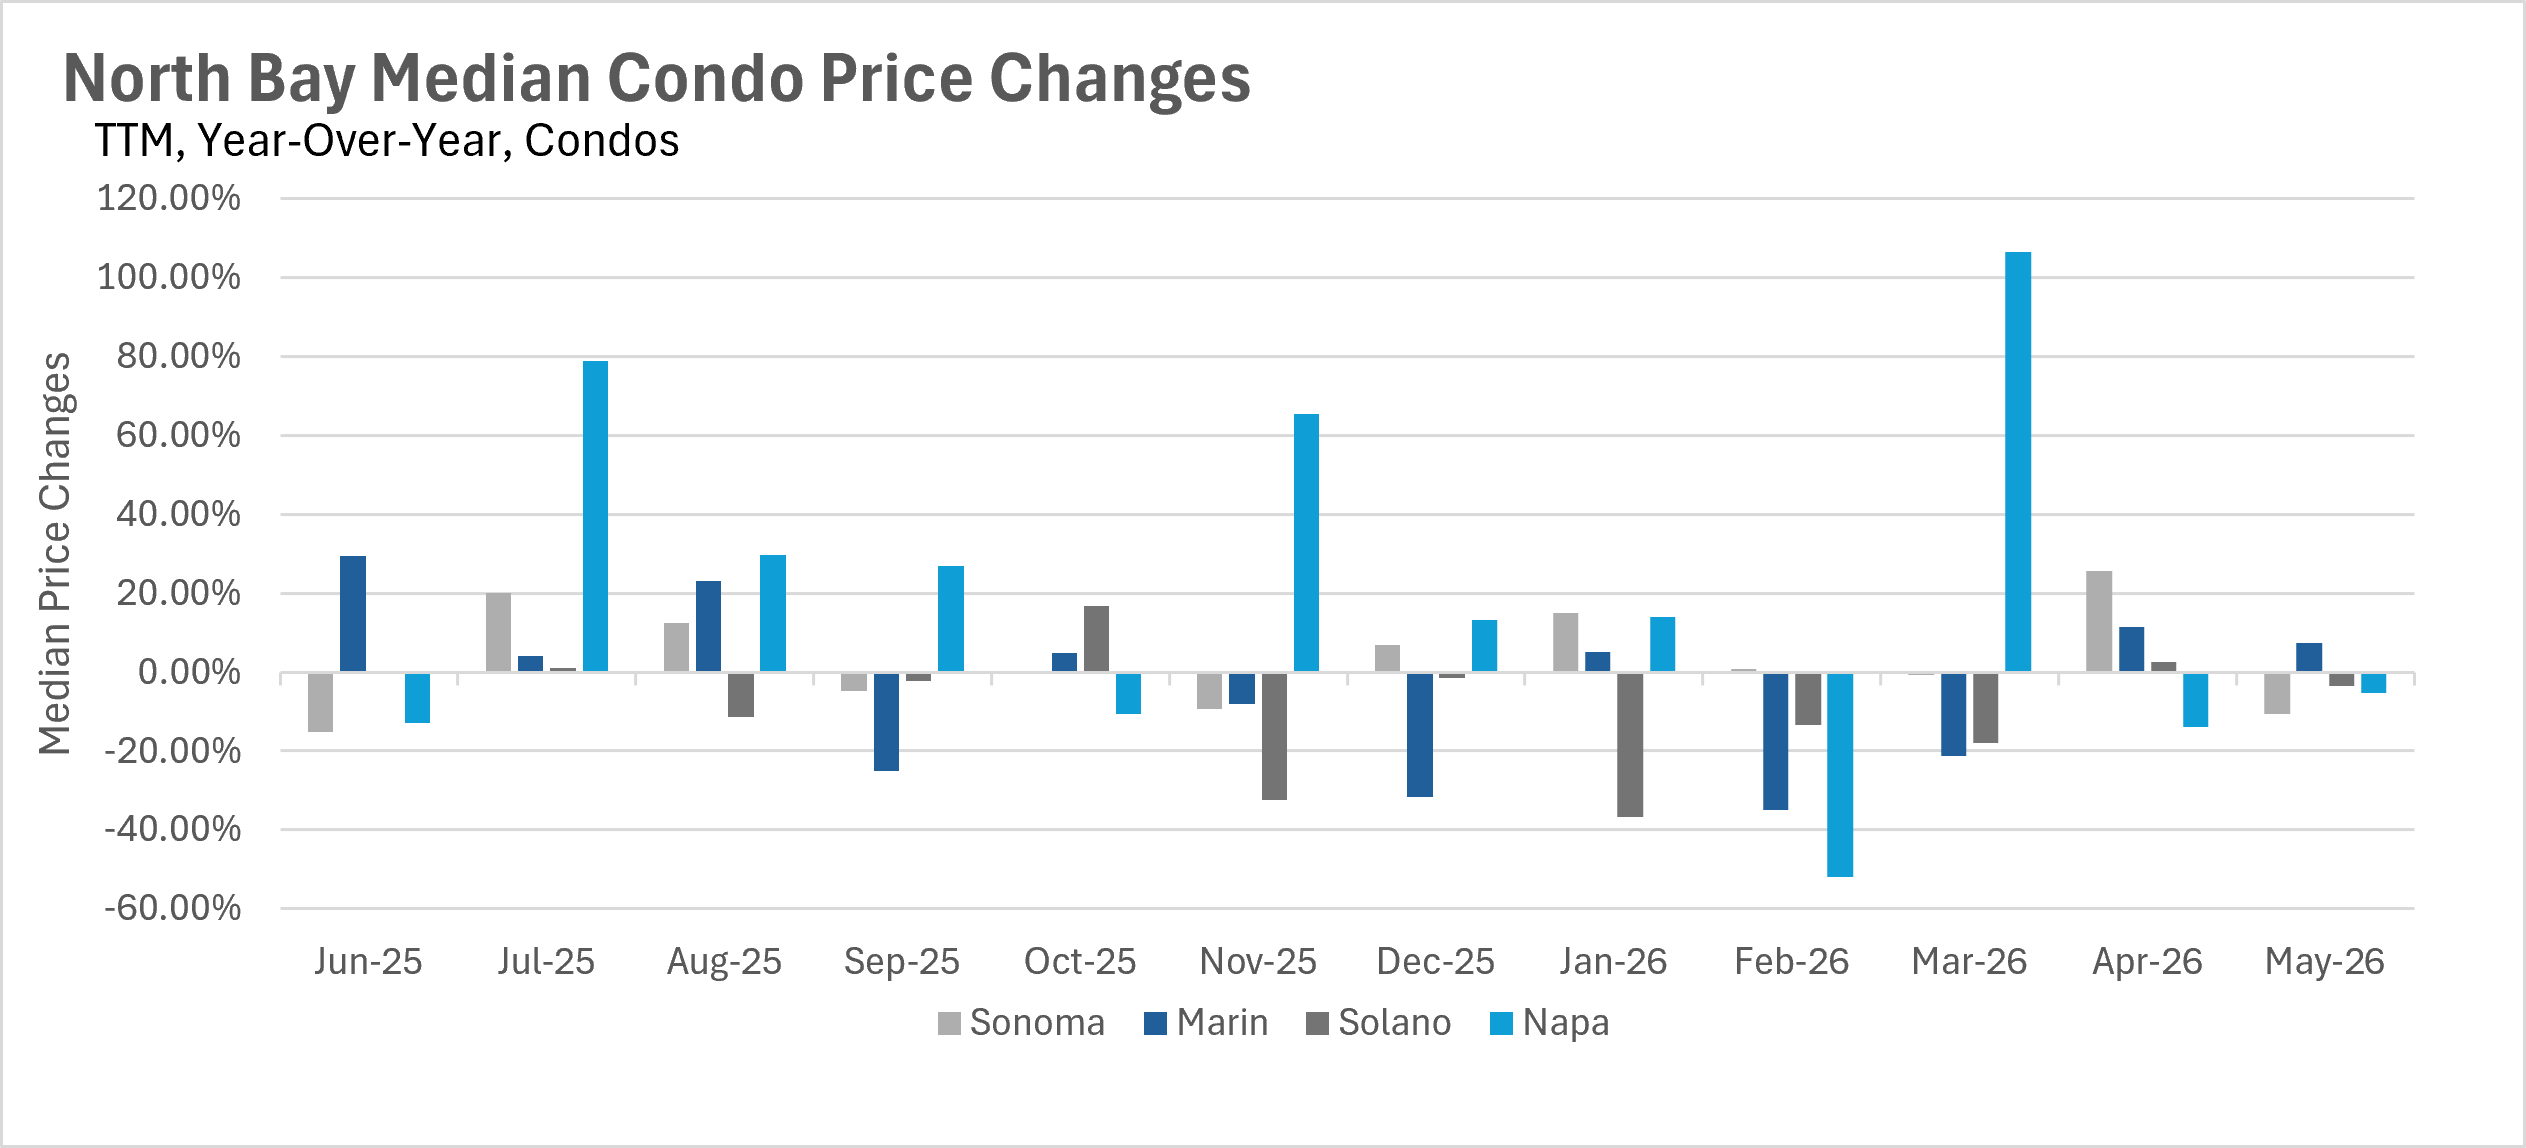
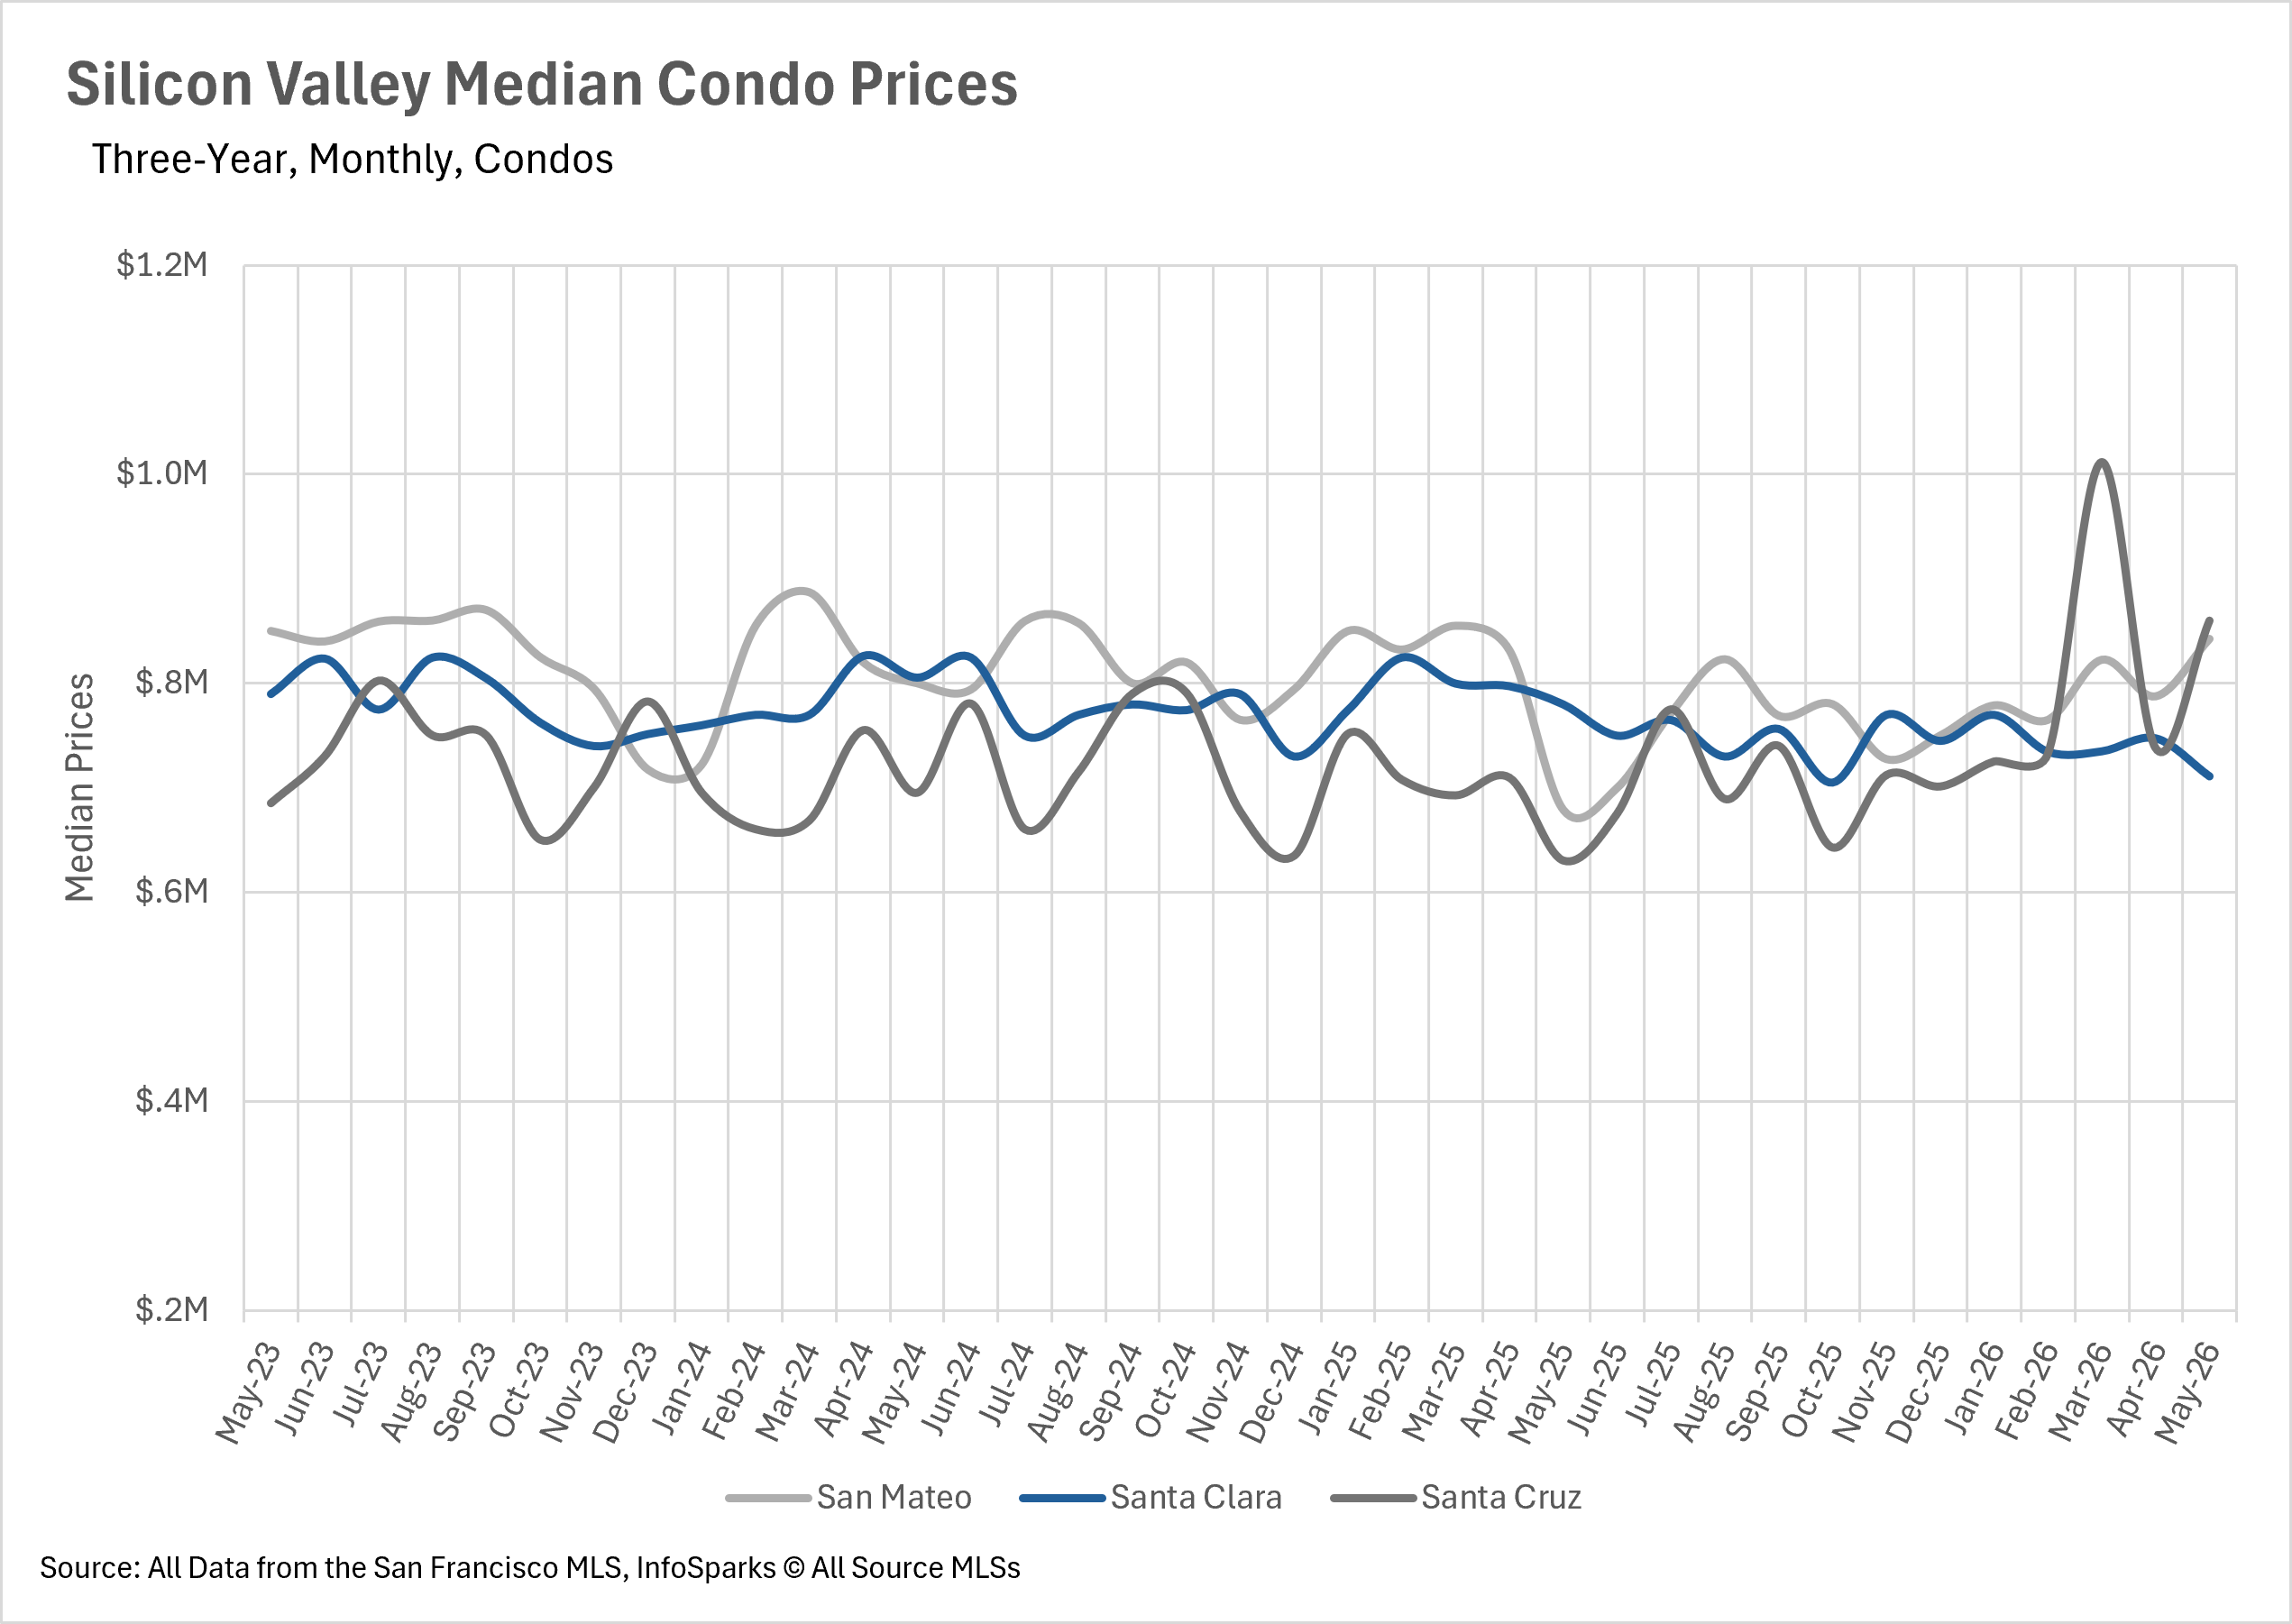
Three of the four North Bay counties also saw gains, with Sonoma County up 2.33%, Napa County up 1.47%, and Solano County up 1.19%, though Marin County declined 4.70%. On the condo side, the East Bay stood out as both counties posted positive year-over-year growth for the first time in quite some time. Silicon Valley's condo market was a wild card, with San Mateo County condos surging 24.06% and Santa Cruz County condos skyrocketing 36.51%, while Santa Clara County condos continued to decline by 8.85%.

Inventory has reached critically low levels across the Bay Area
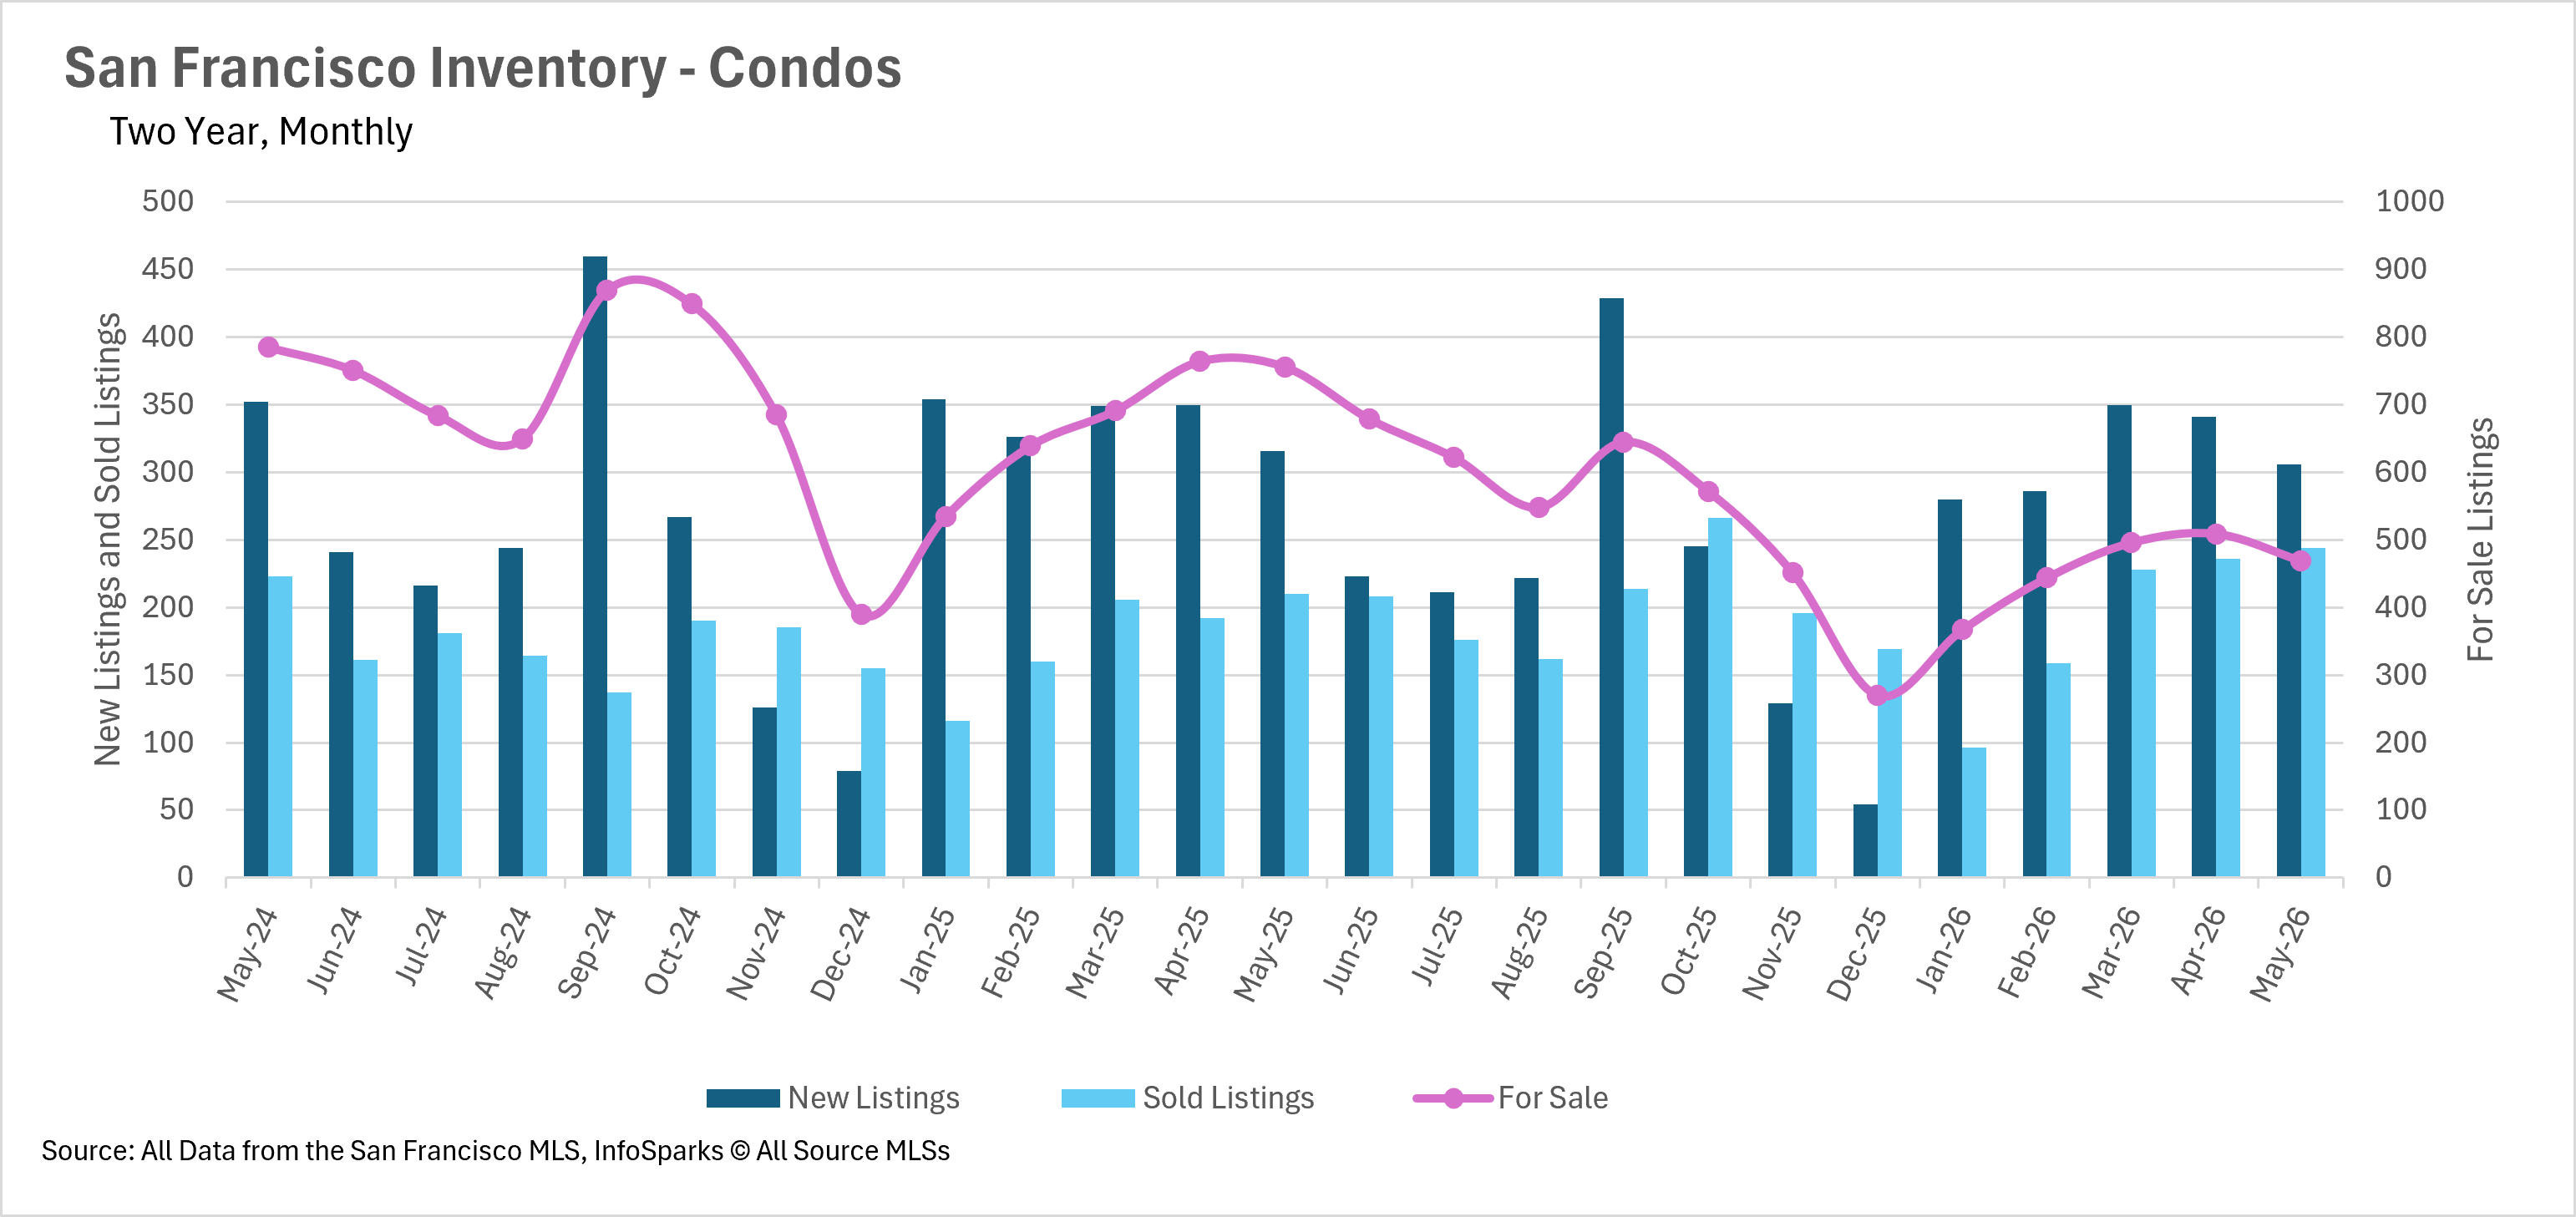
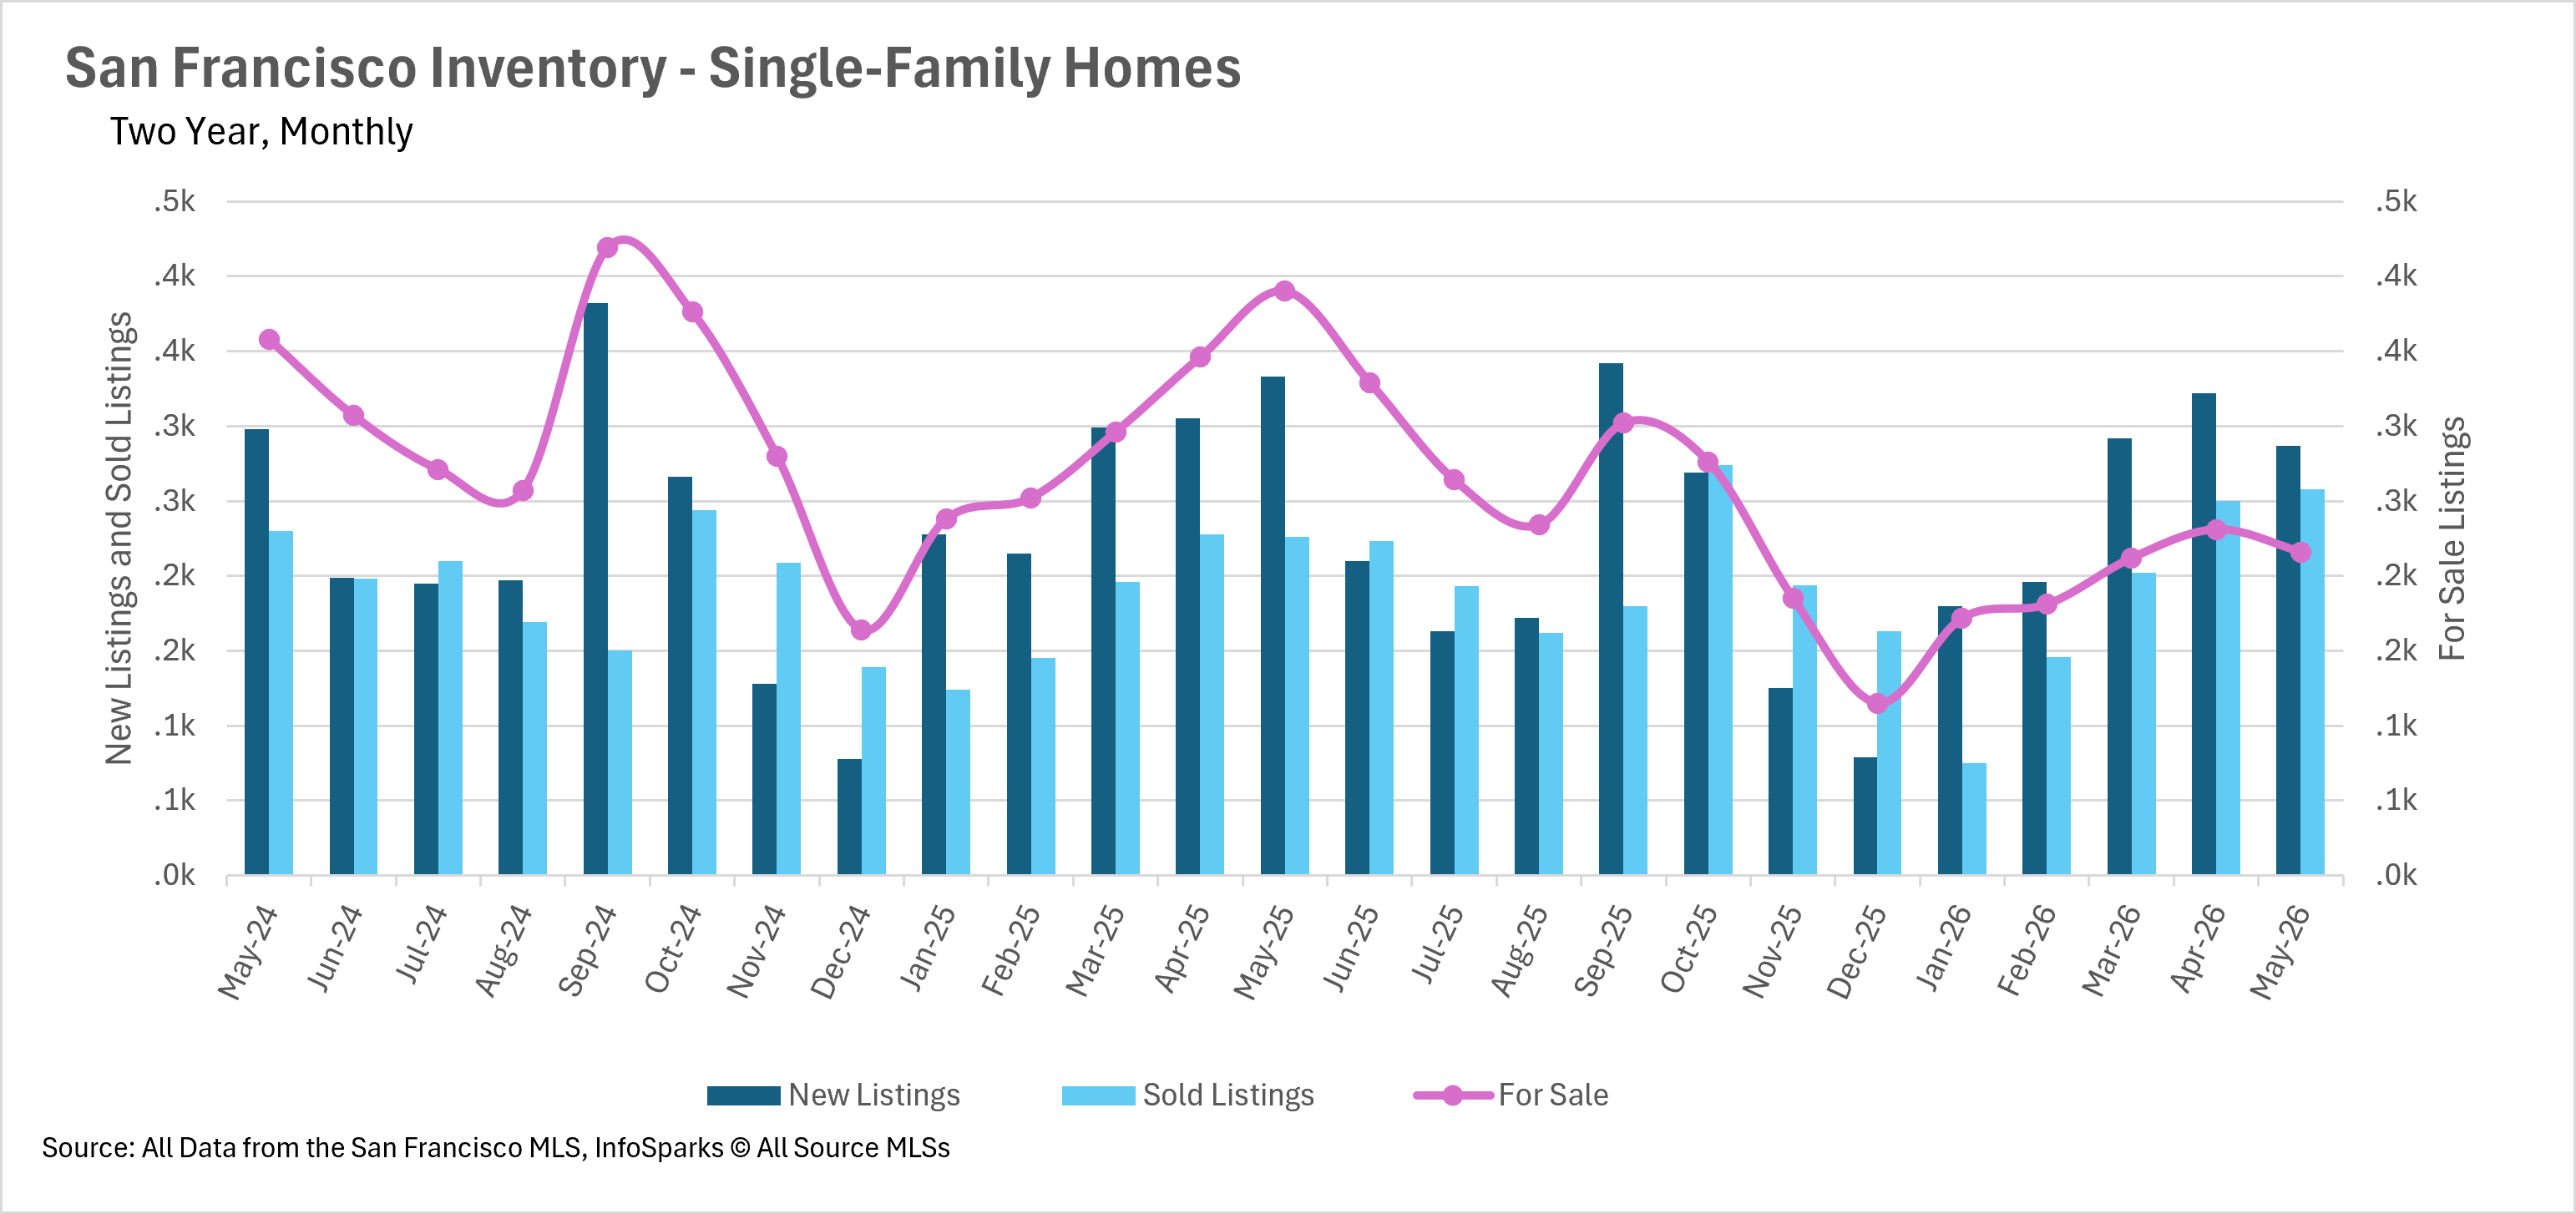
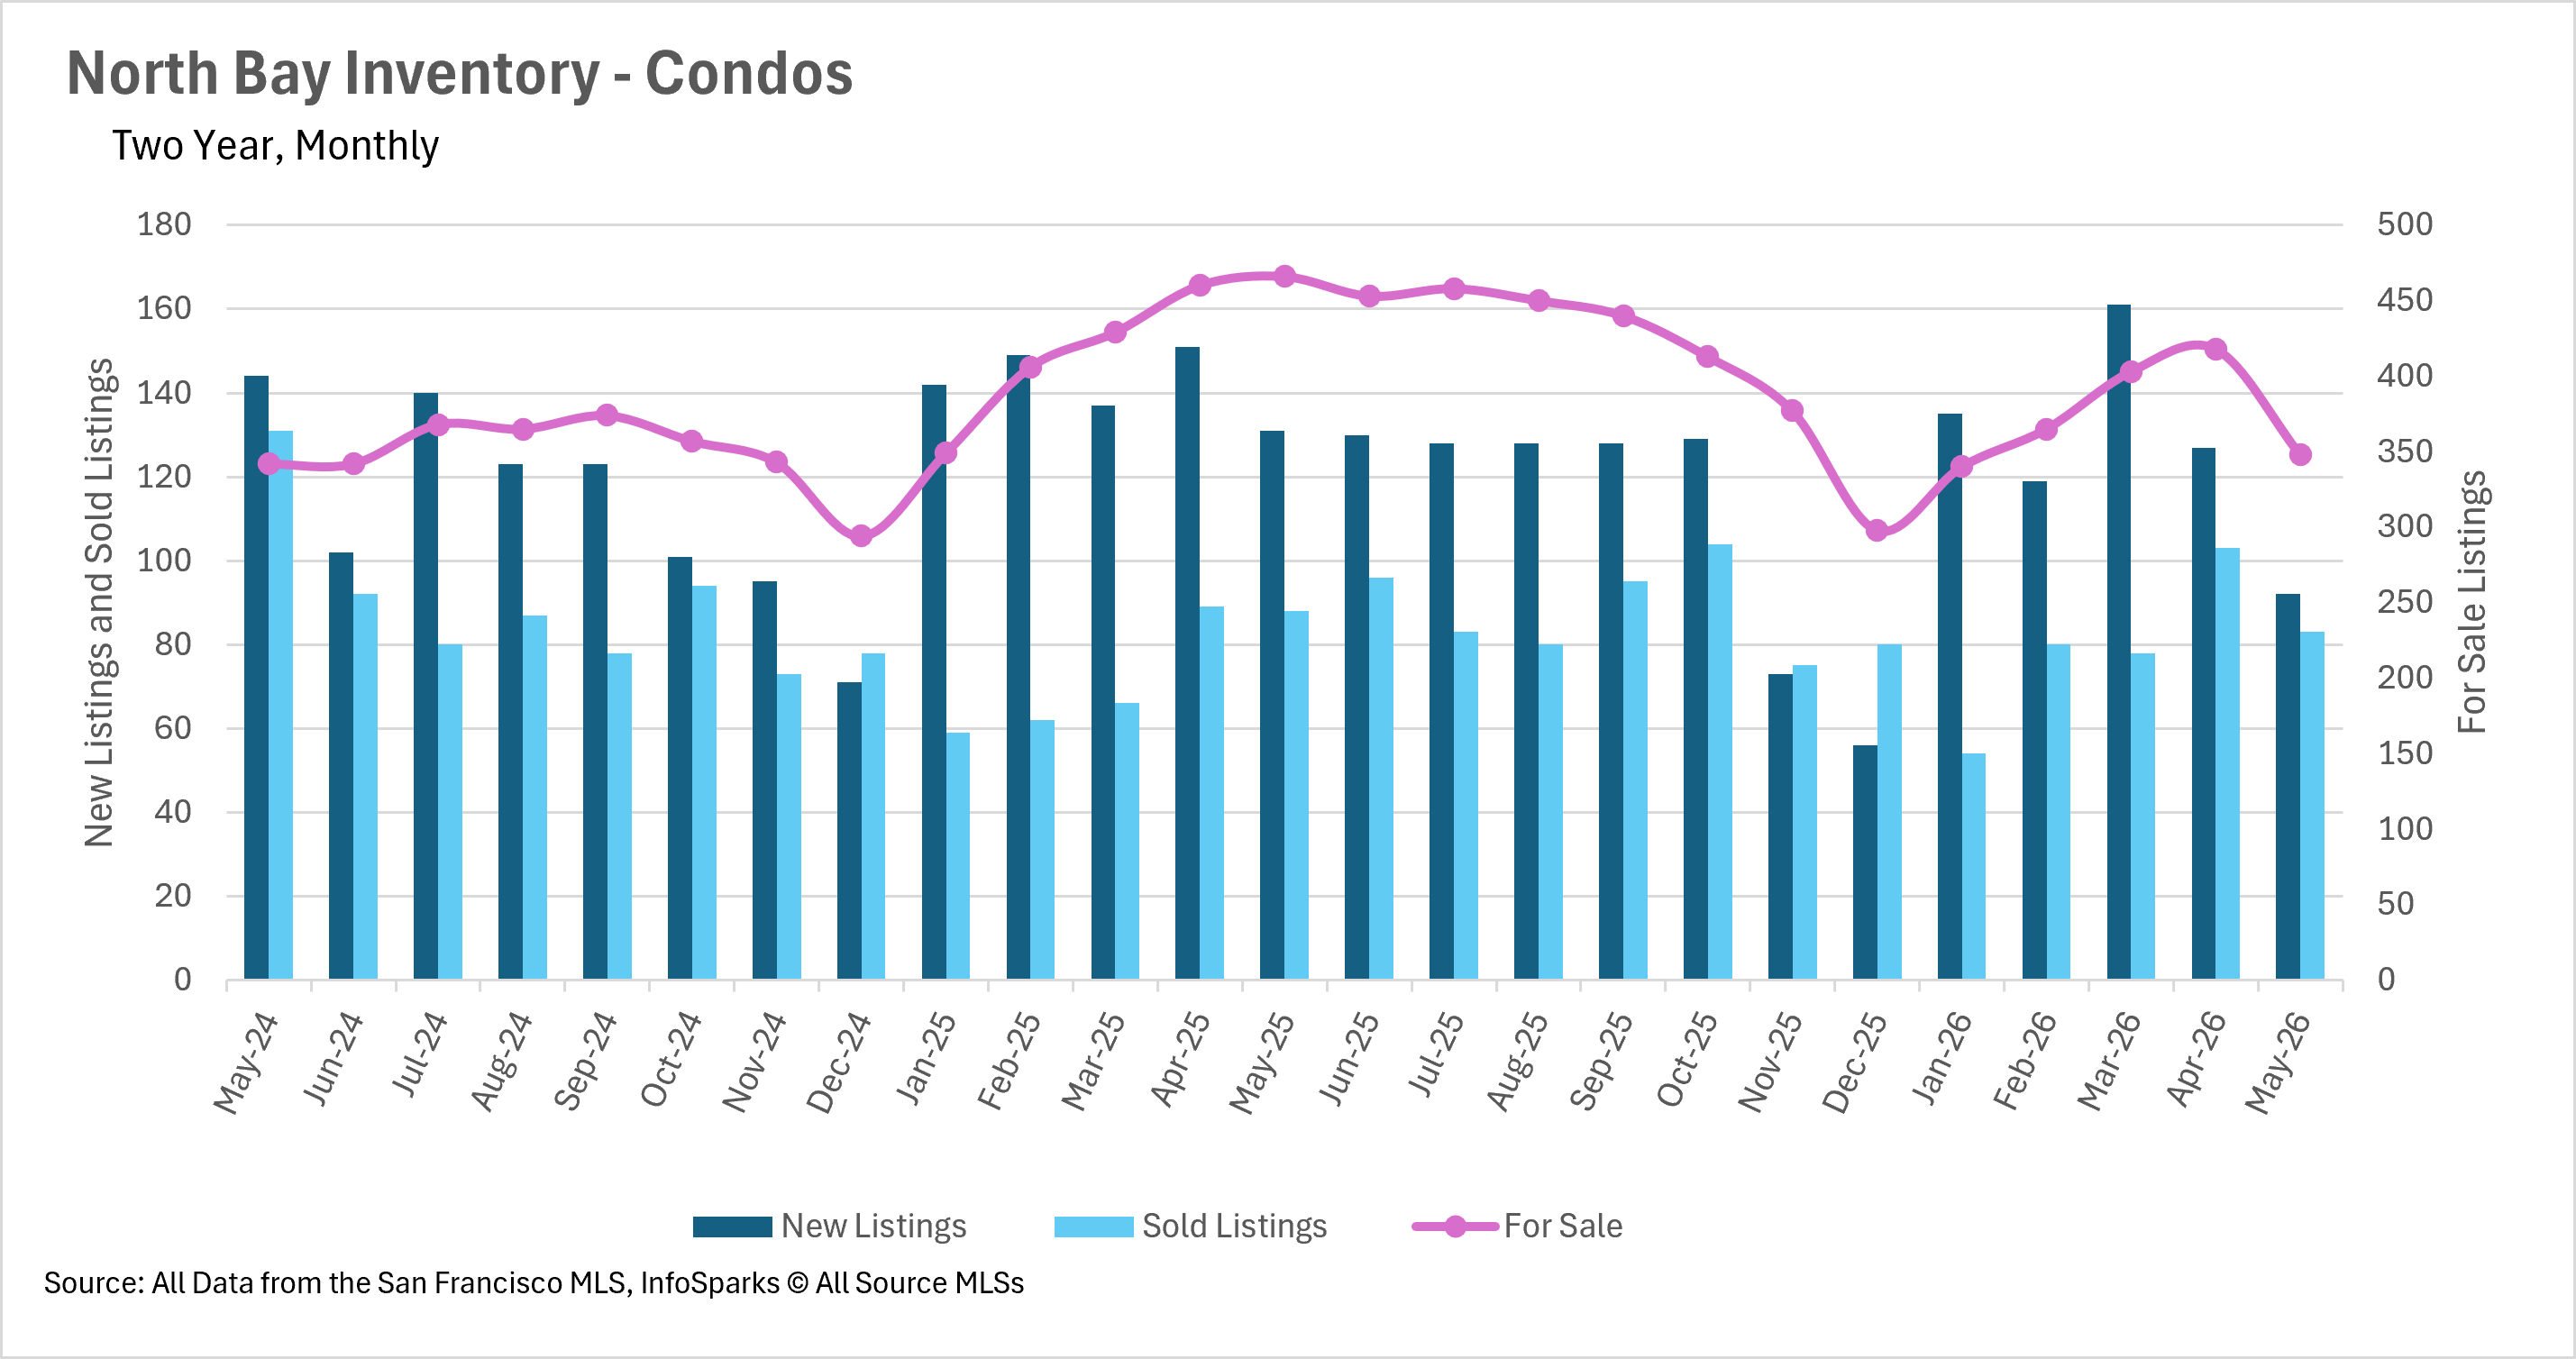
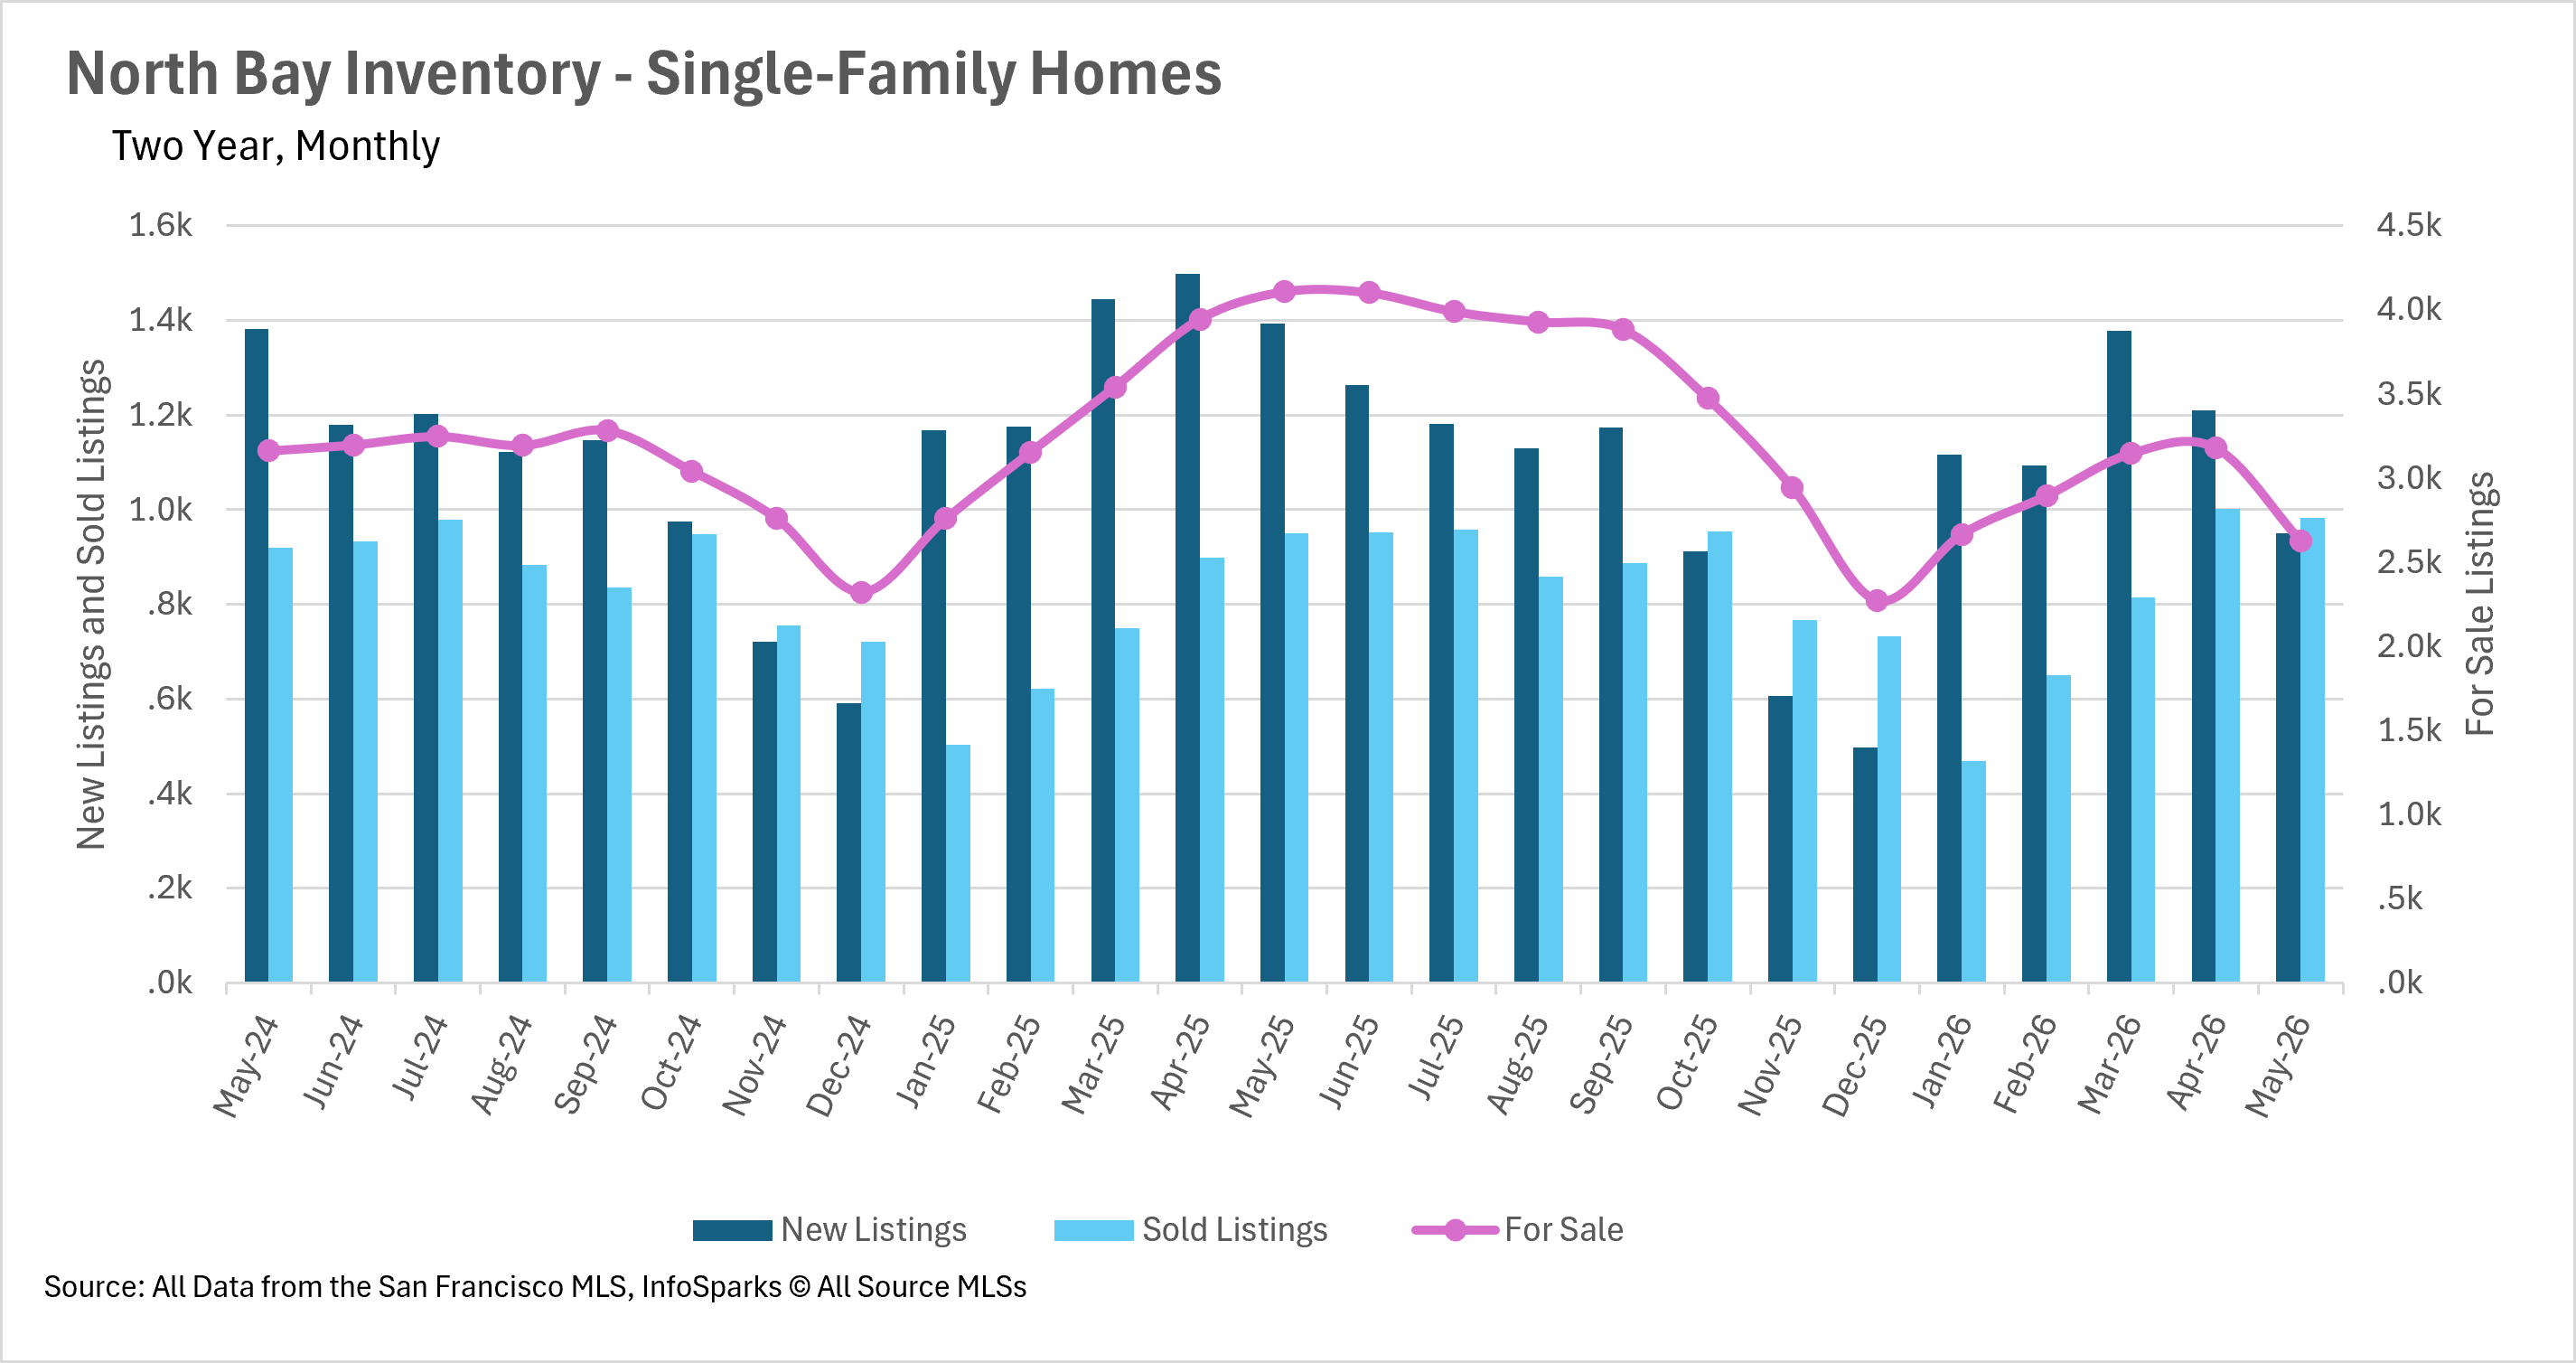
The inventory shortage that has defined the Bay Area market throughout 2026 has only intensified as we move into the summer selling season. San Francisco is experiencing the most severe crunch, with single-family inventory down a staggering 44.62% year-over-year and condo inventory down 37.96%, leaving fewer than 700 homes available for sale in the entire city. The North Bay is also feeling the squeeze, with single-family home inventory down 36% and condo inventory down 25.32%.

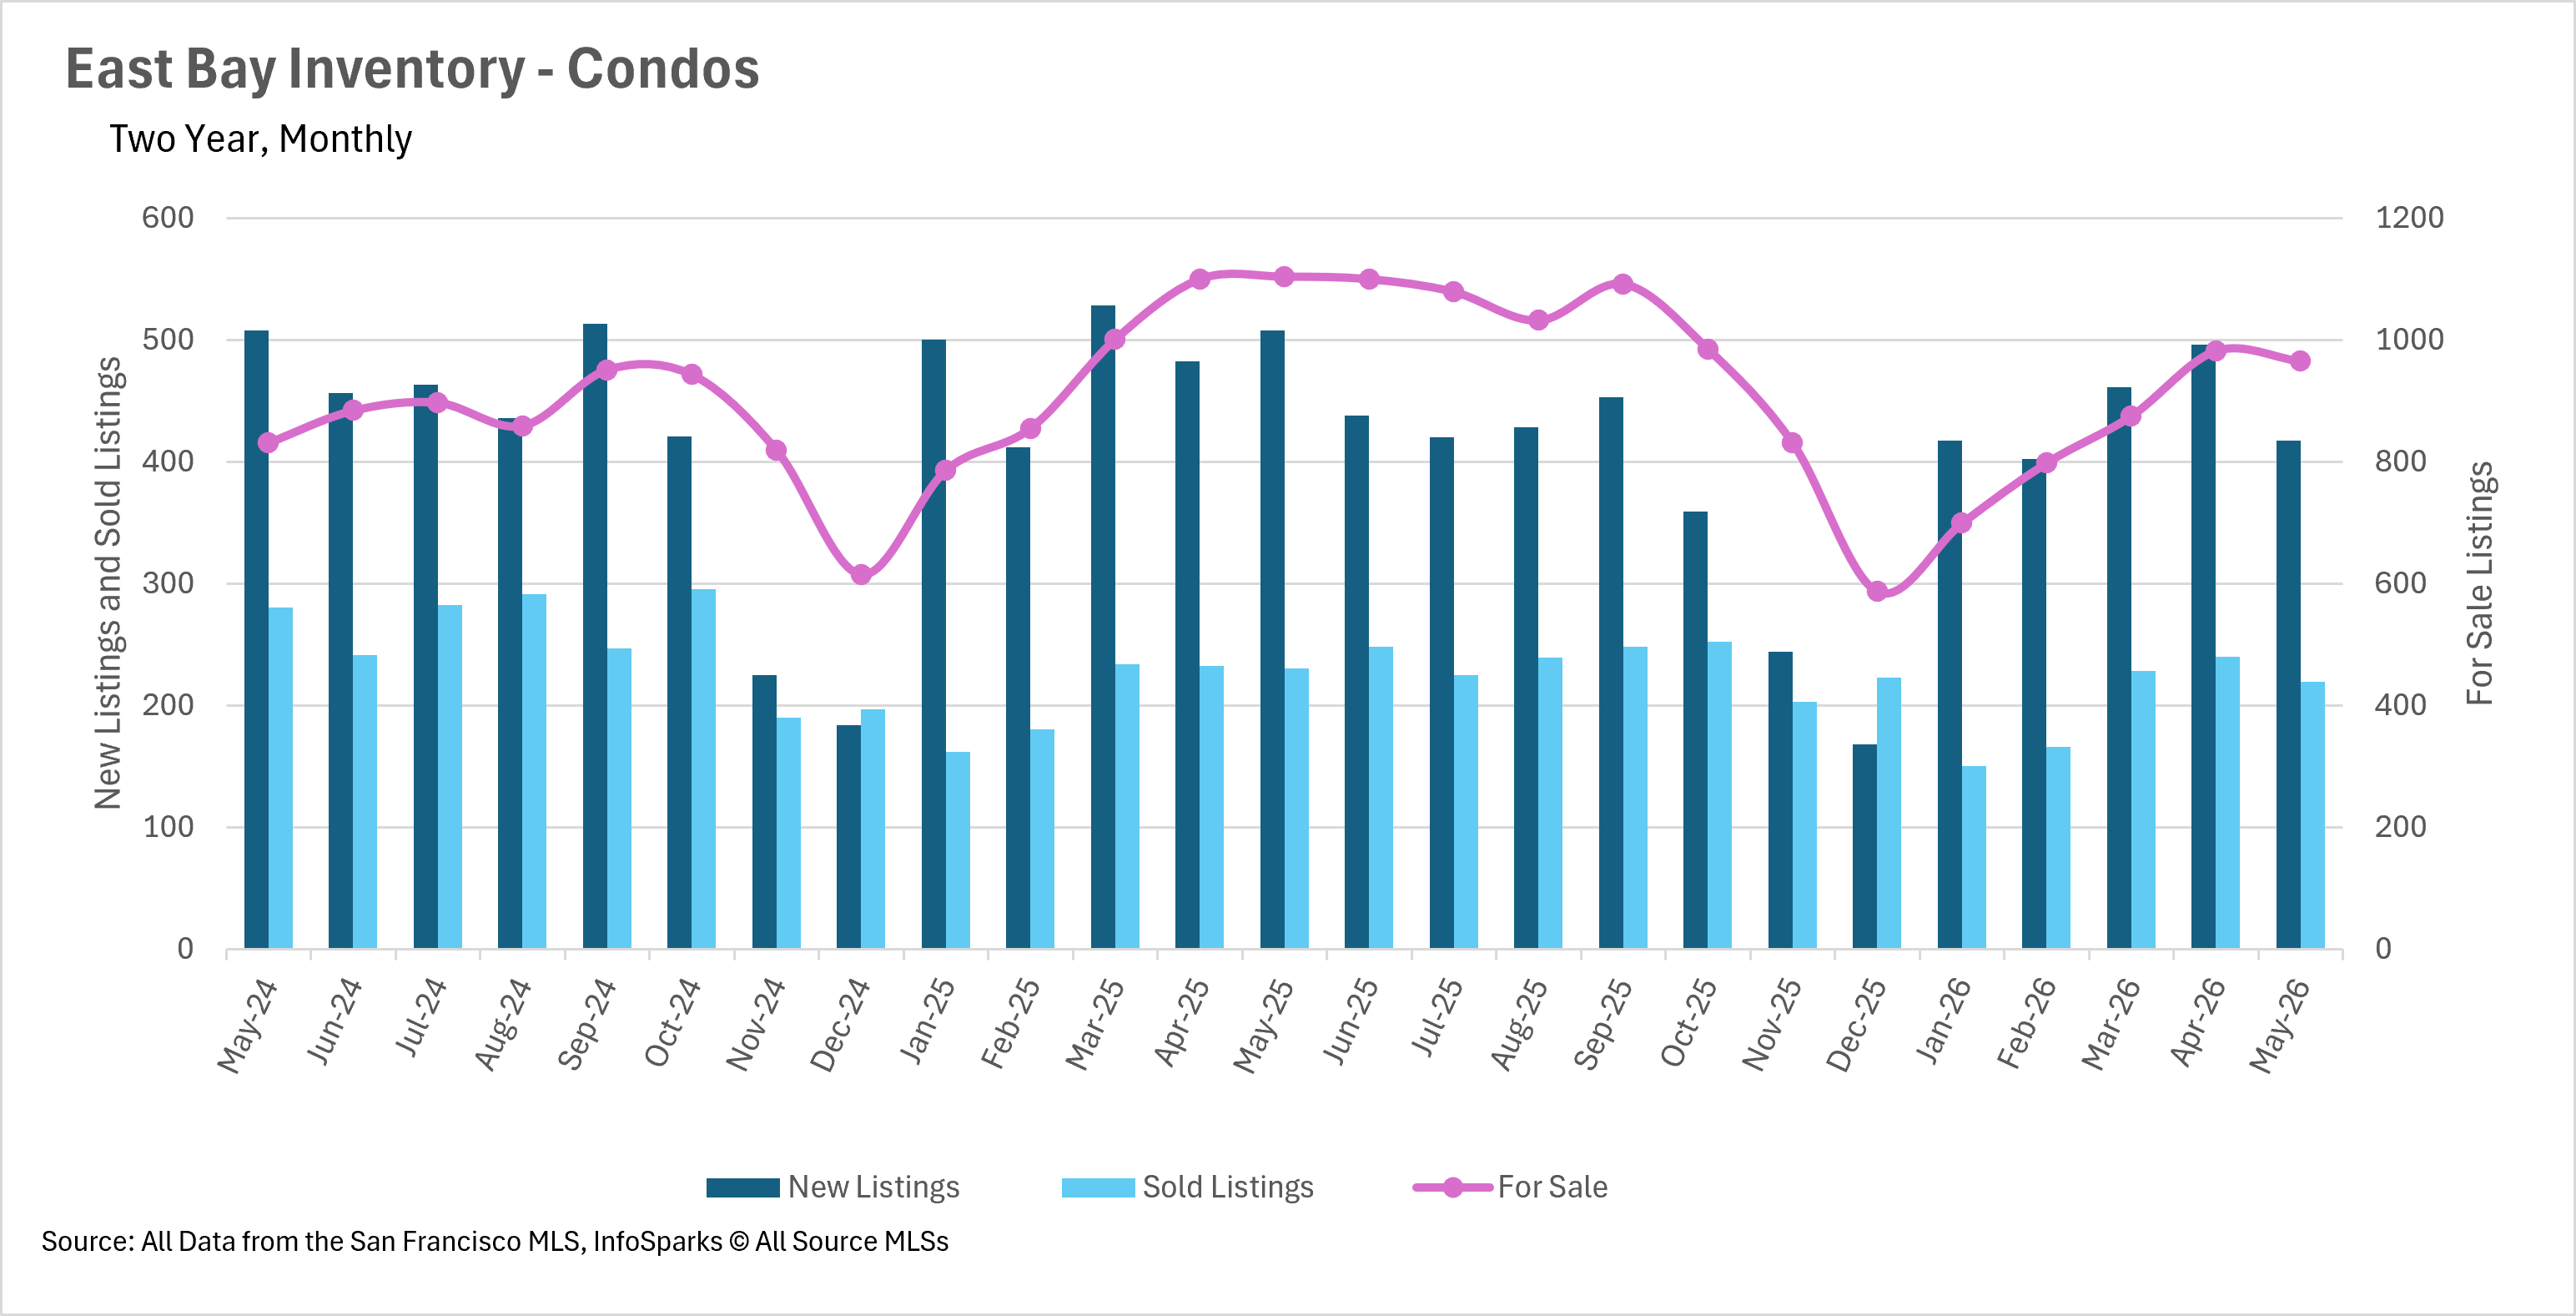
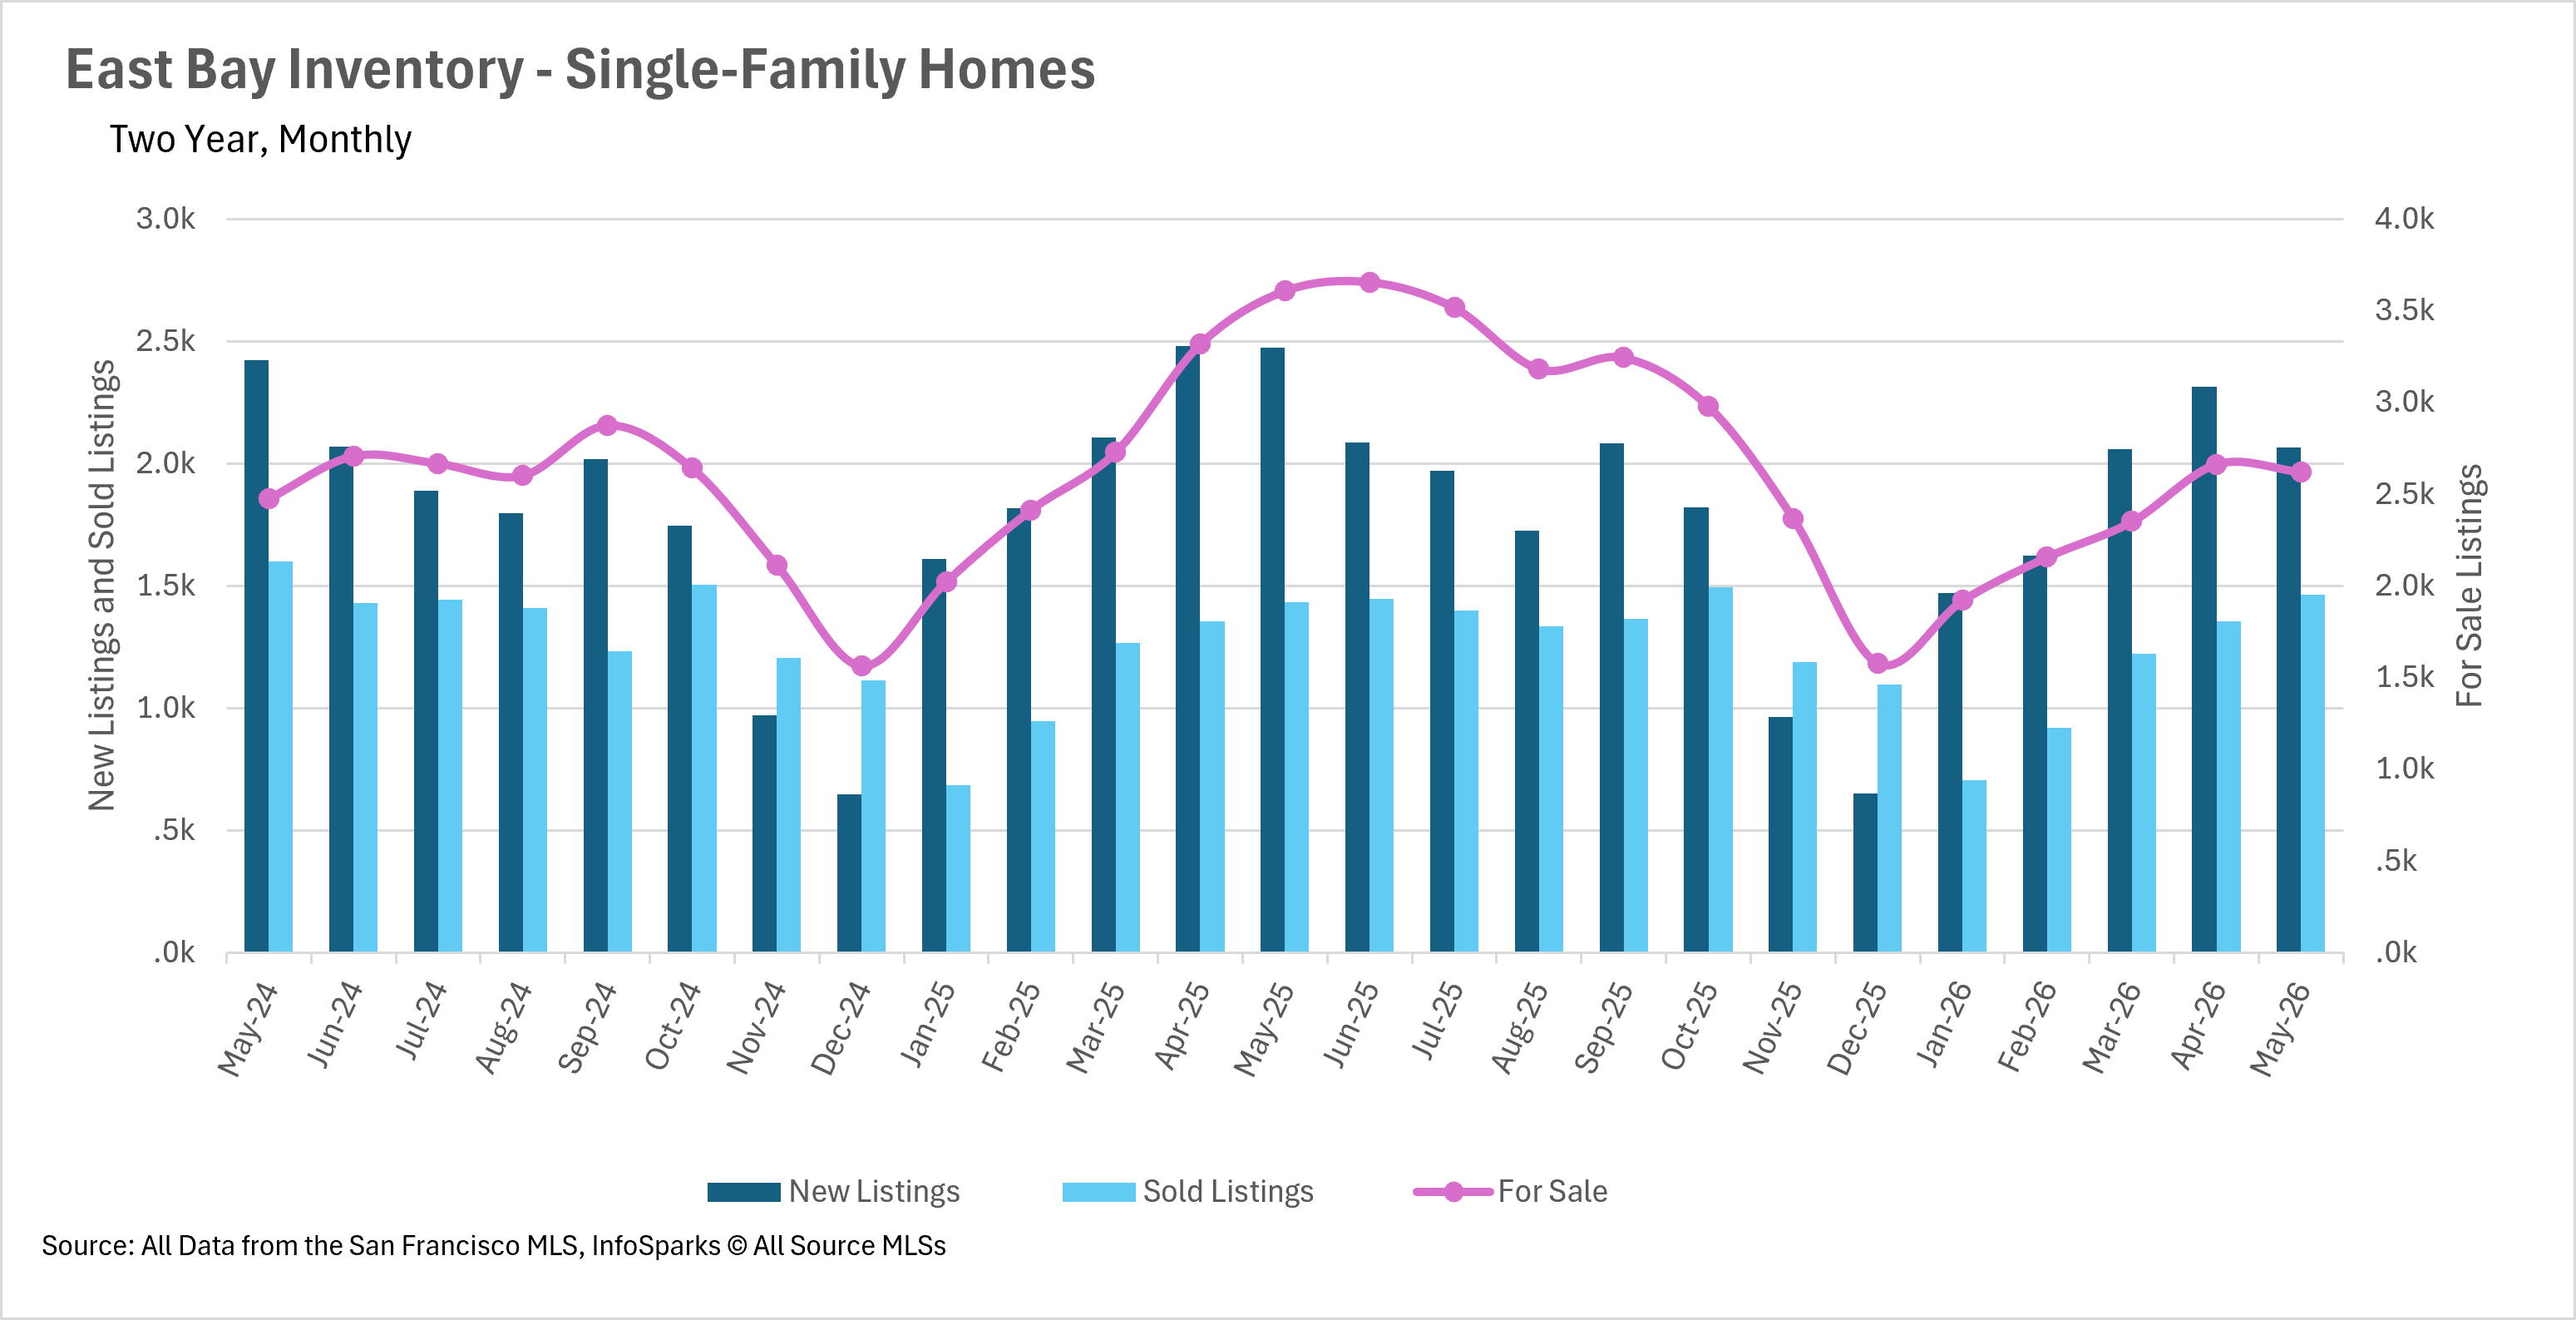
The East Bay has seen single-family inventory decline by 27.38% and condo inventory drop by 12.59%, while Silicon Valley's single-family inventory is down 18.94% and condo inventory is down 9.77%. New listings continue to trail last year's pace in most markets, with the North Bay seeing single-family new listings down 31.73% and Silicon Valley down 11.79%. On the demand side, sold listings are actually up in several markets, with Silicon Valley single-family sales up 4.47% and North Bay single-family sales up 3.37%. This combination of declining supply and steady or growing demand is the primary driver behind the price appreciation we're seeing across much of the region.

Single-family homes are selling quickly, and the condo market is picking up speed
The pace of sales for single-family homes across the Bay Area remains remarkably fast as the summer selling season approaches. San Francisco single-family homes are selling in just 12 days, while Santa Clara County homes are moving in 11 days and San Mateo County homes in 12 days. In the East Bay, single-family homes in both Alameda and Contra Costa Counties are selling in just 13 days, a 7.14% improvement compared to last year.

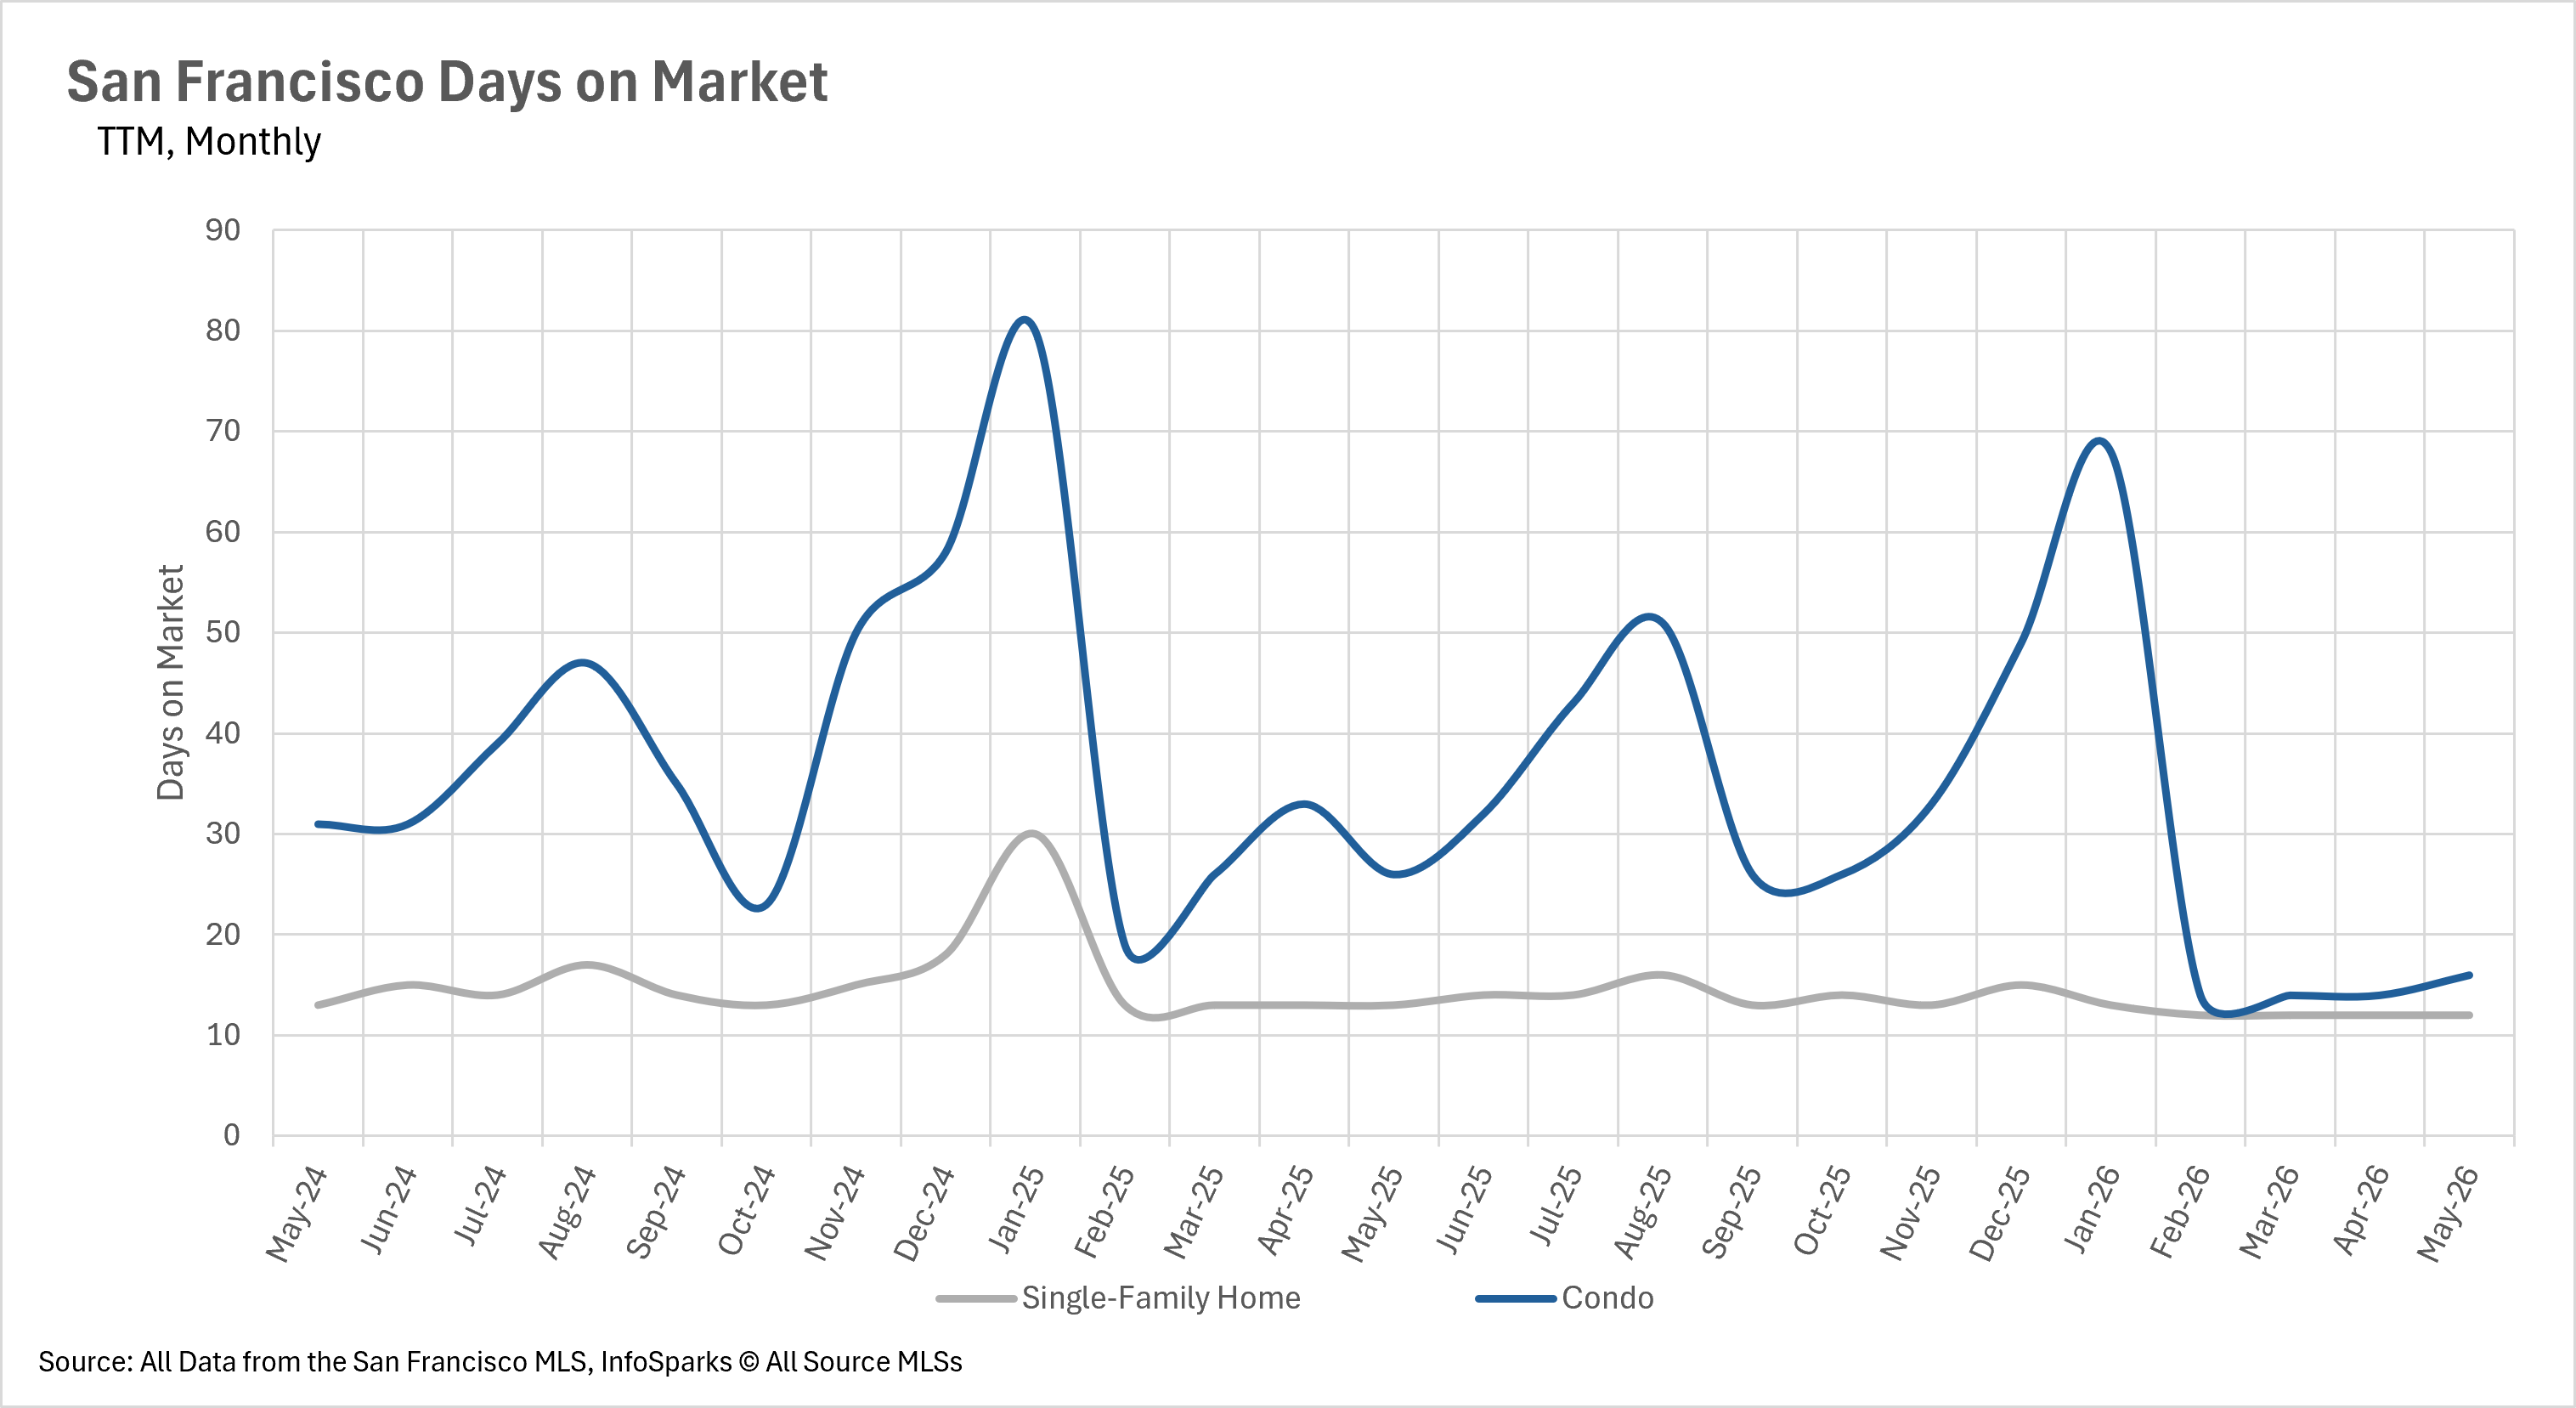
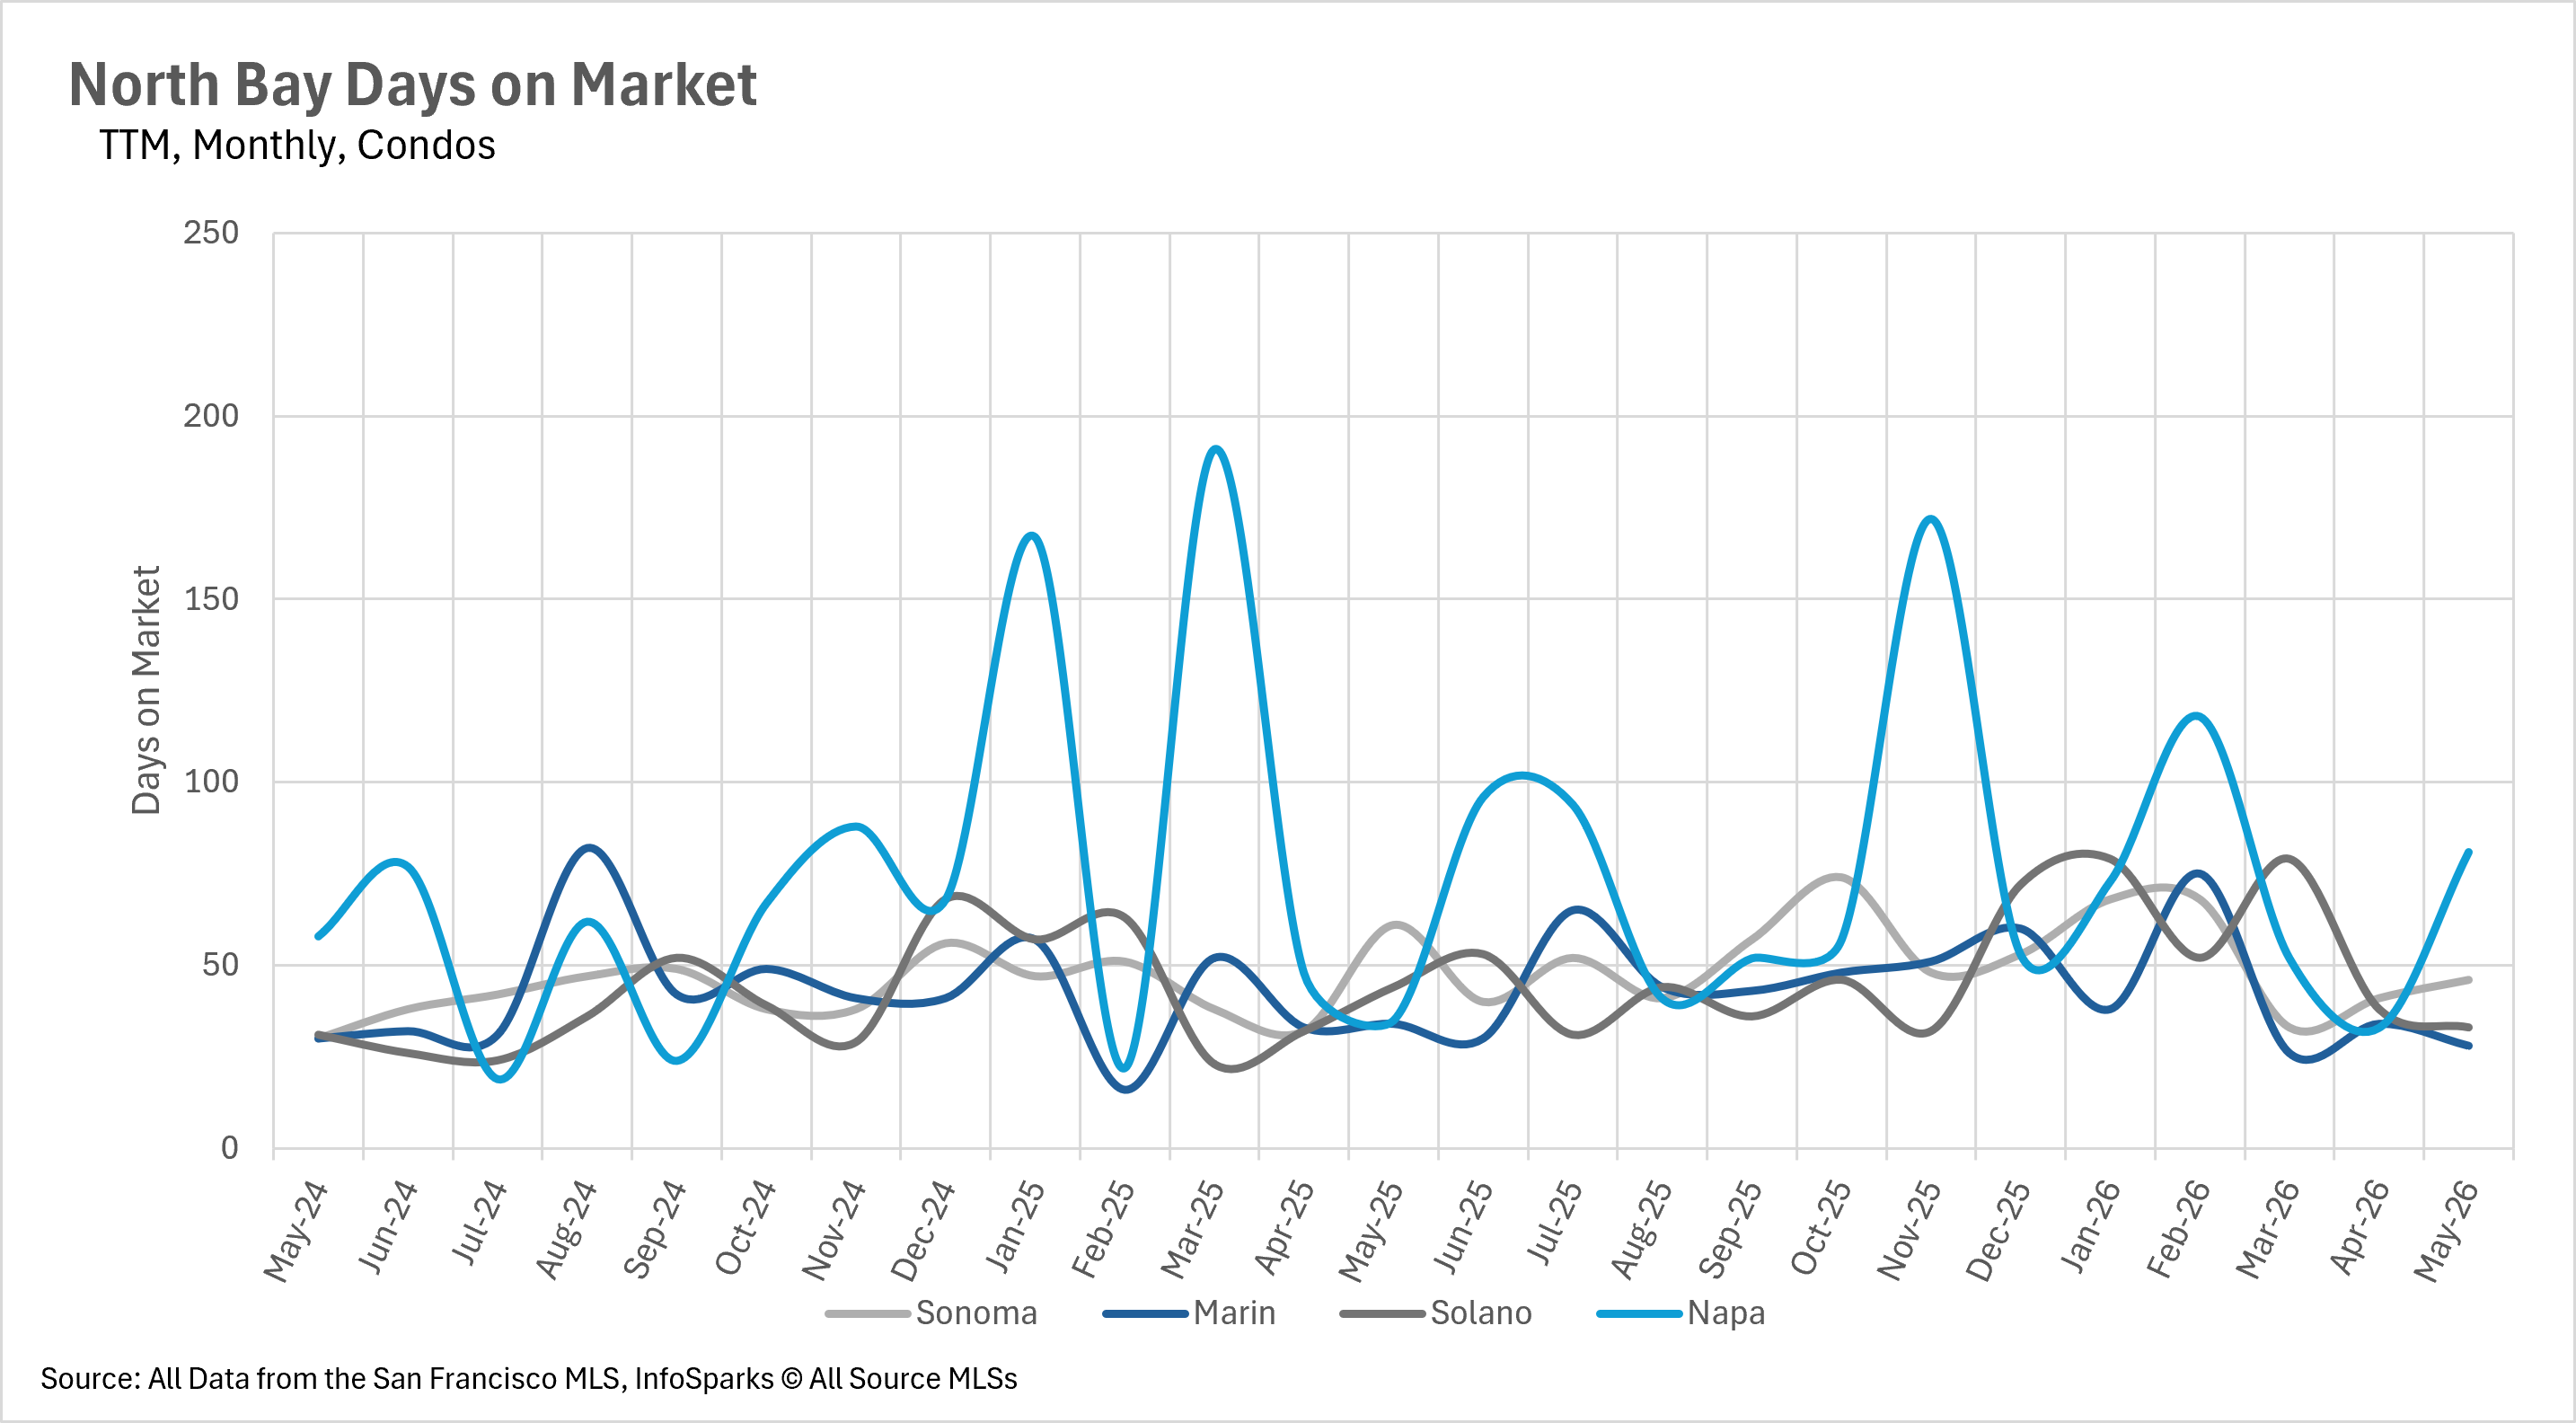
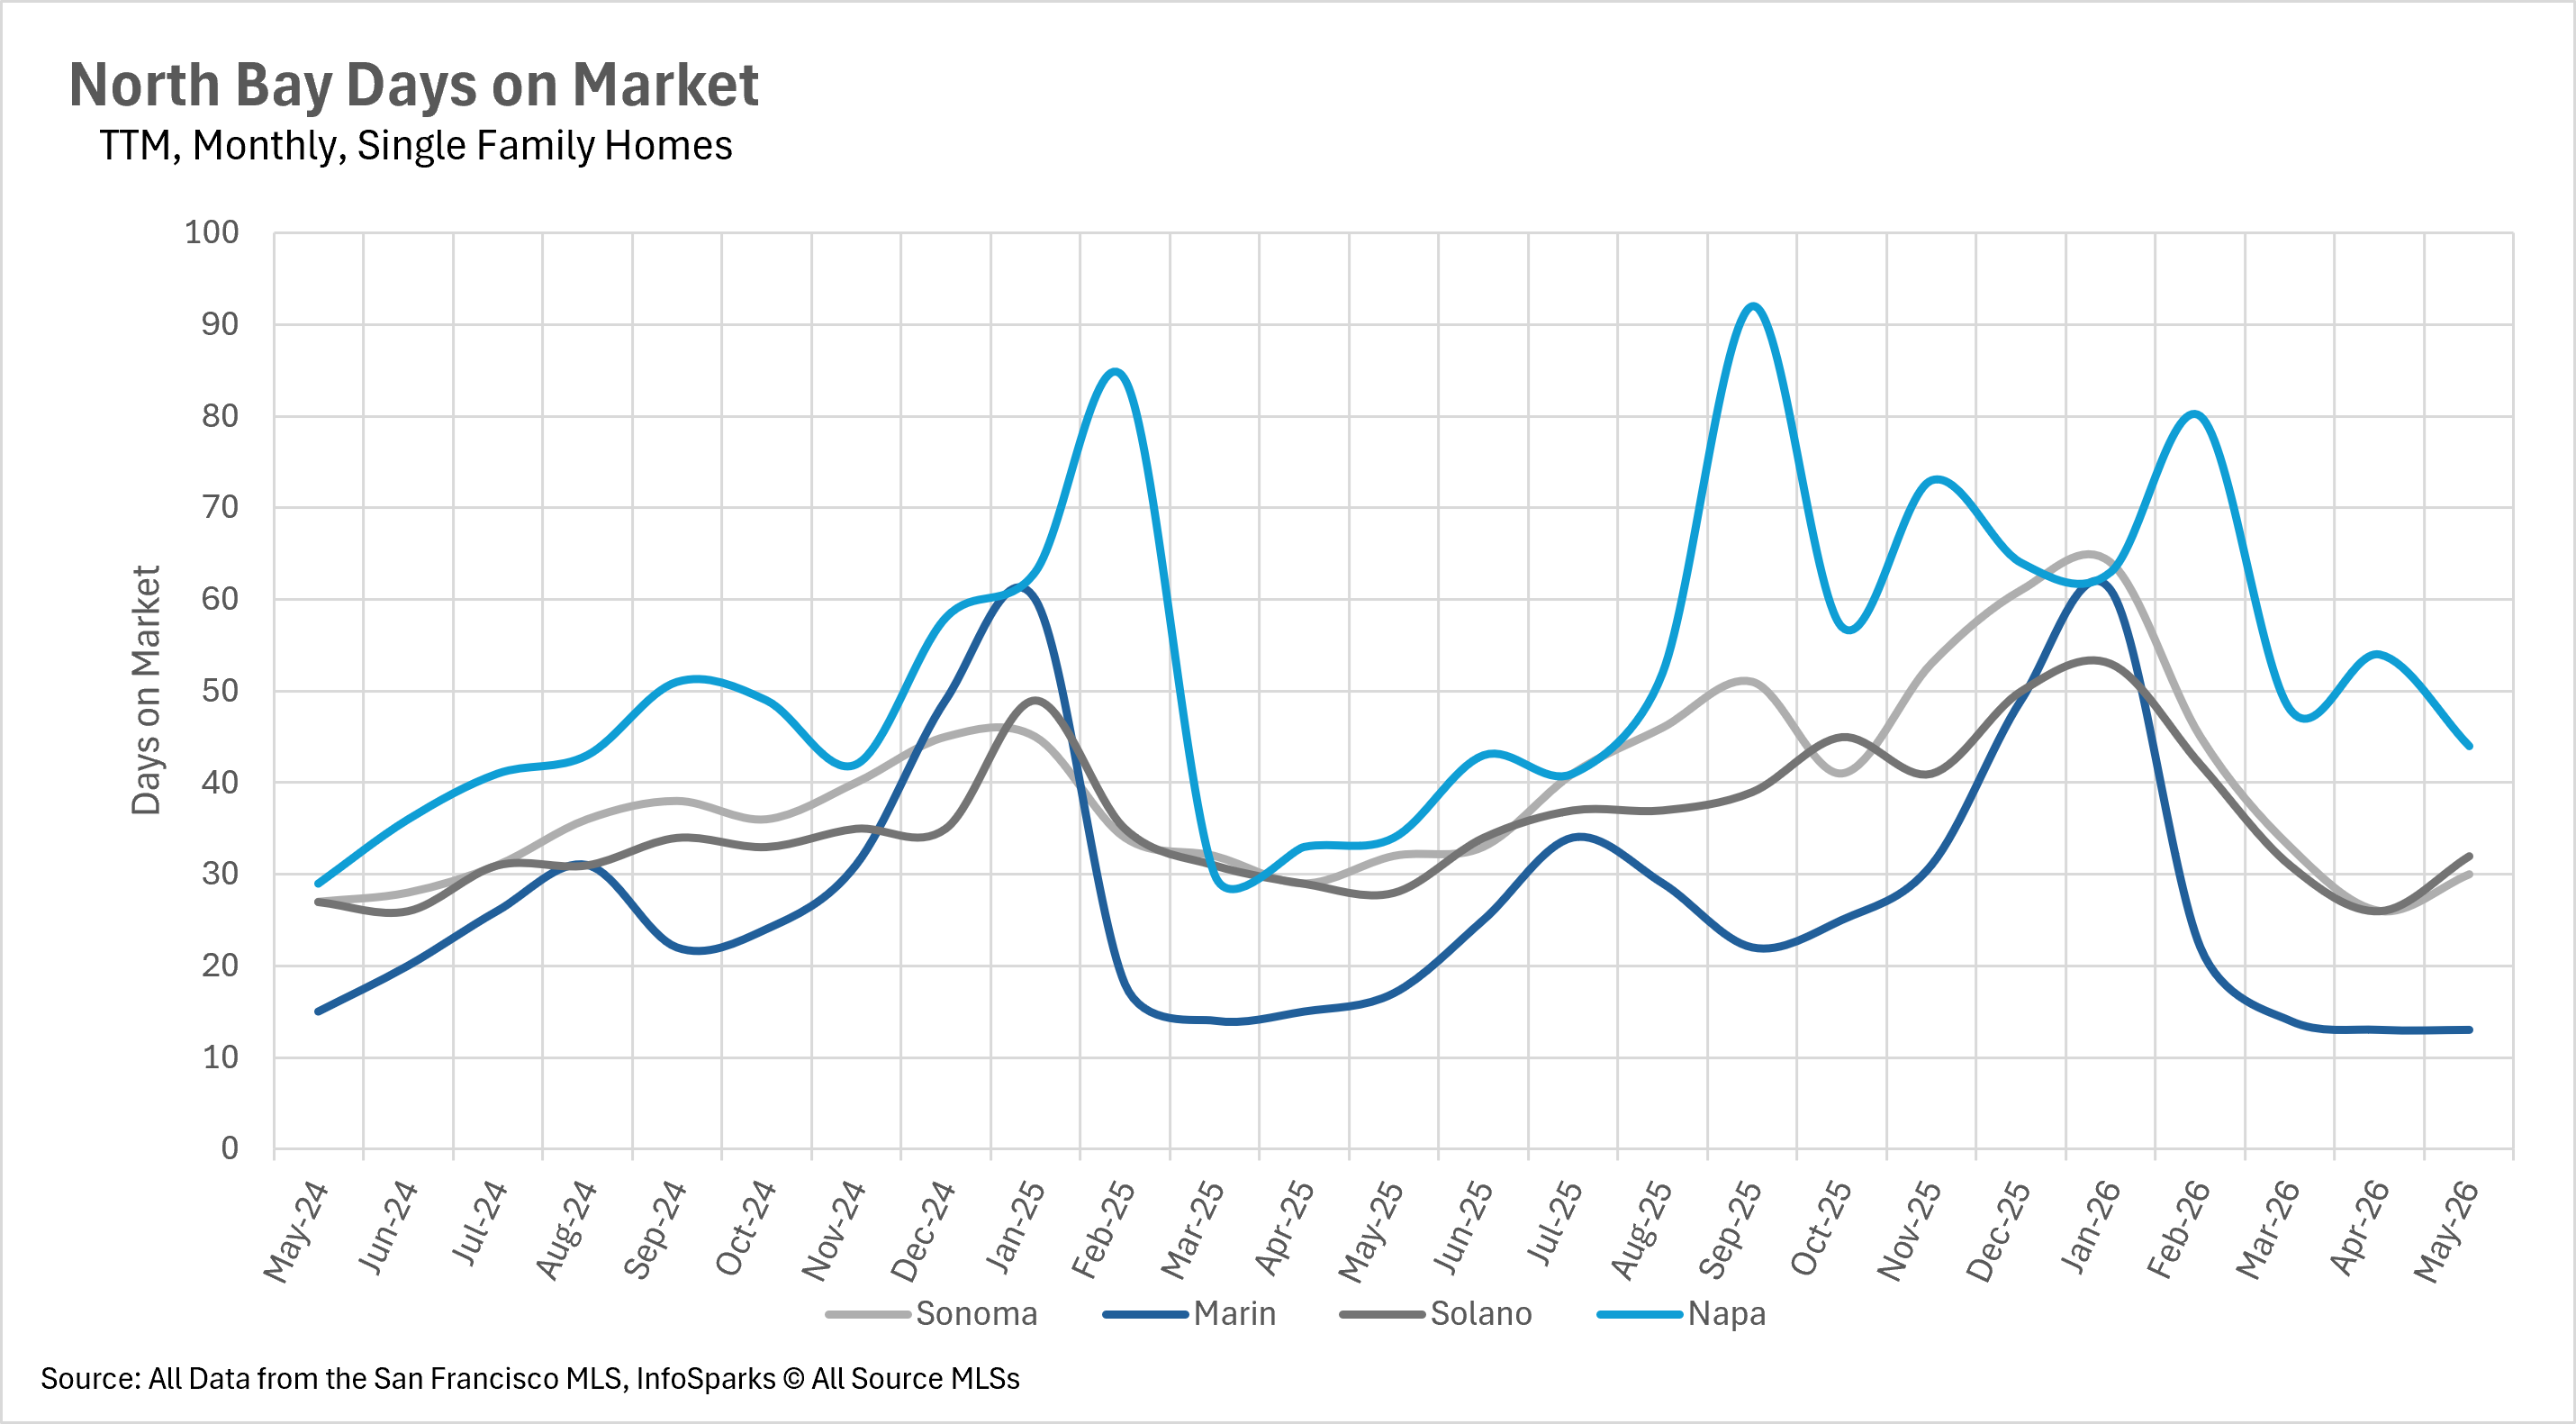
The North Bay saw impressive velocity as well, with Marin County single-family homes selling in just 13 days, a 23.53% improvement year-over-year, and Sonoma County homes moving 6.25% faster at 30 days. The condo market is also showing encouraging signs of improvement in several markets. San Mateo County condos are selling 15.15% faster than last year, Santa Cruz County condos are moving 37.84% faster, and North Bay condos in Sonoma, Solano, and Marin Counties are all selling considerably more quickly than they were a year ago. San Francisco condos are now selling in just 16 days, a 38.46% year-over-year decline. The notable exception is Napa County, where condos are spending 131.43% more time on the market at a median of 81 days.
Sellers continue to dominate the single-family market heading into summer
When determining whether a market is a buyers' market or a sellers' market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller's market, whereas markets with more than three months of MSI are considered a buyers' market.

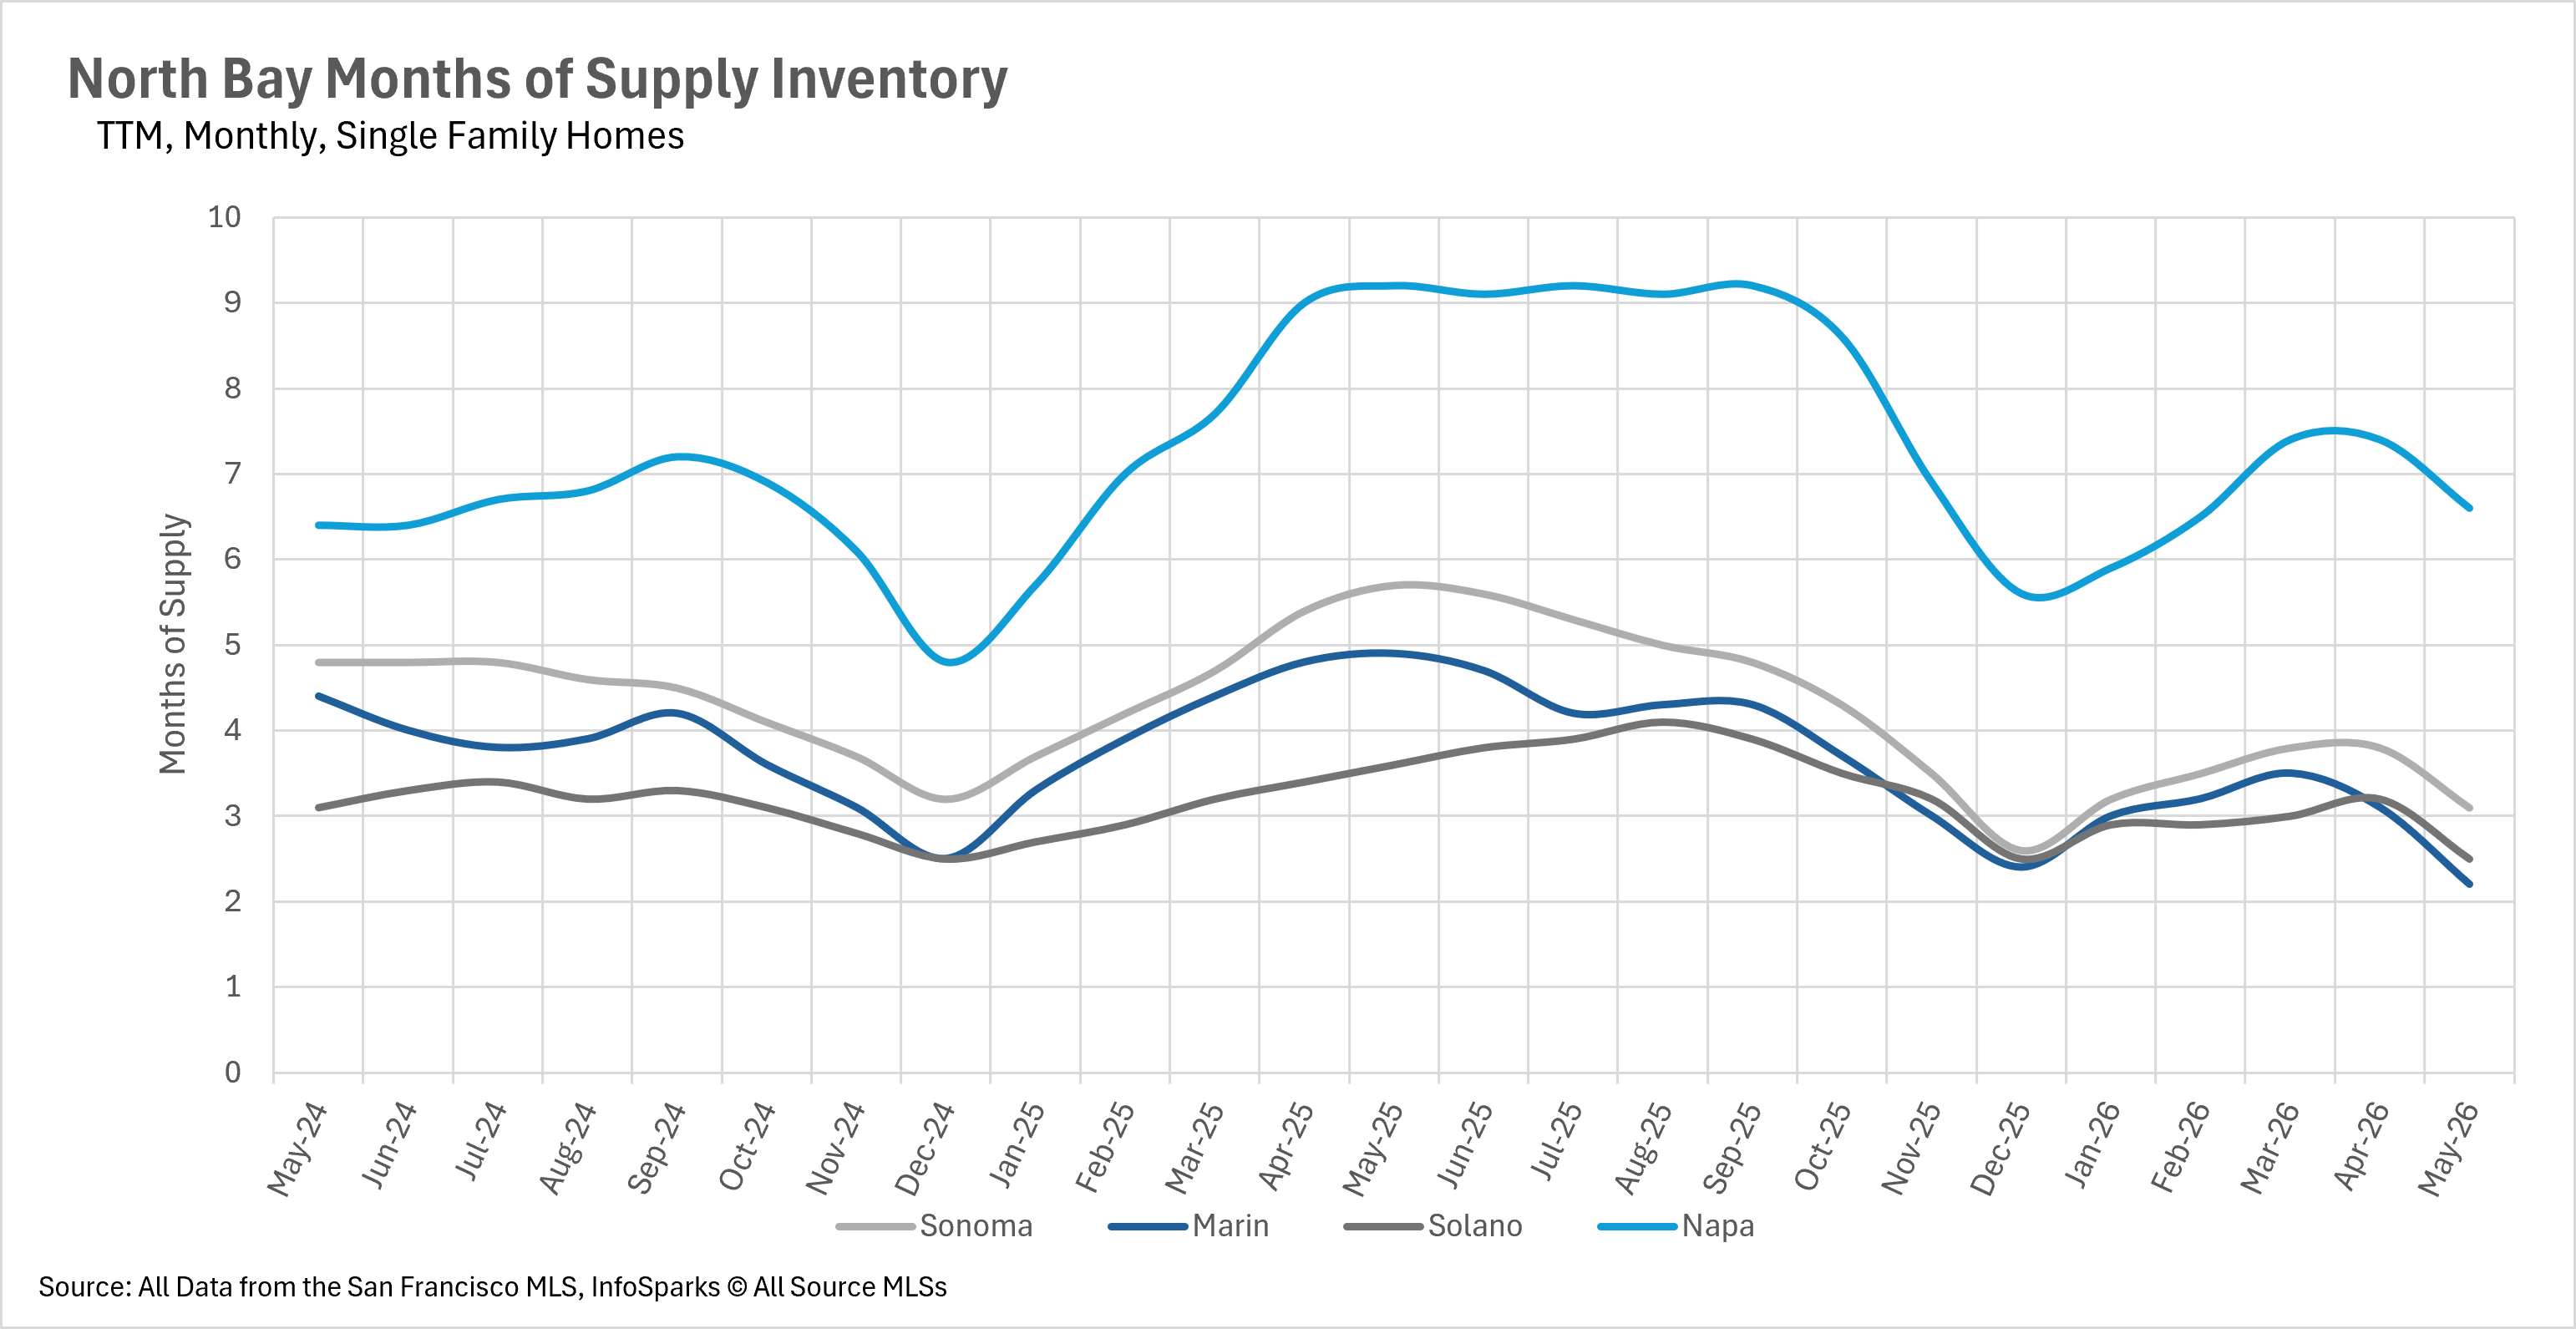
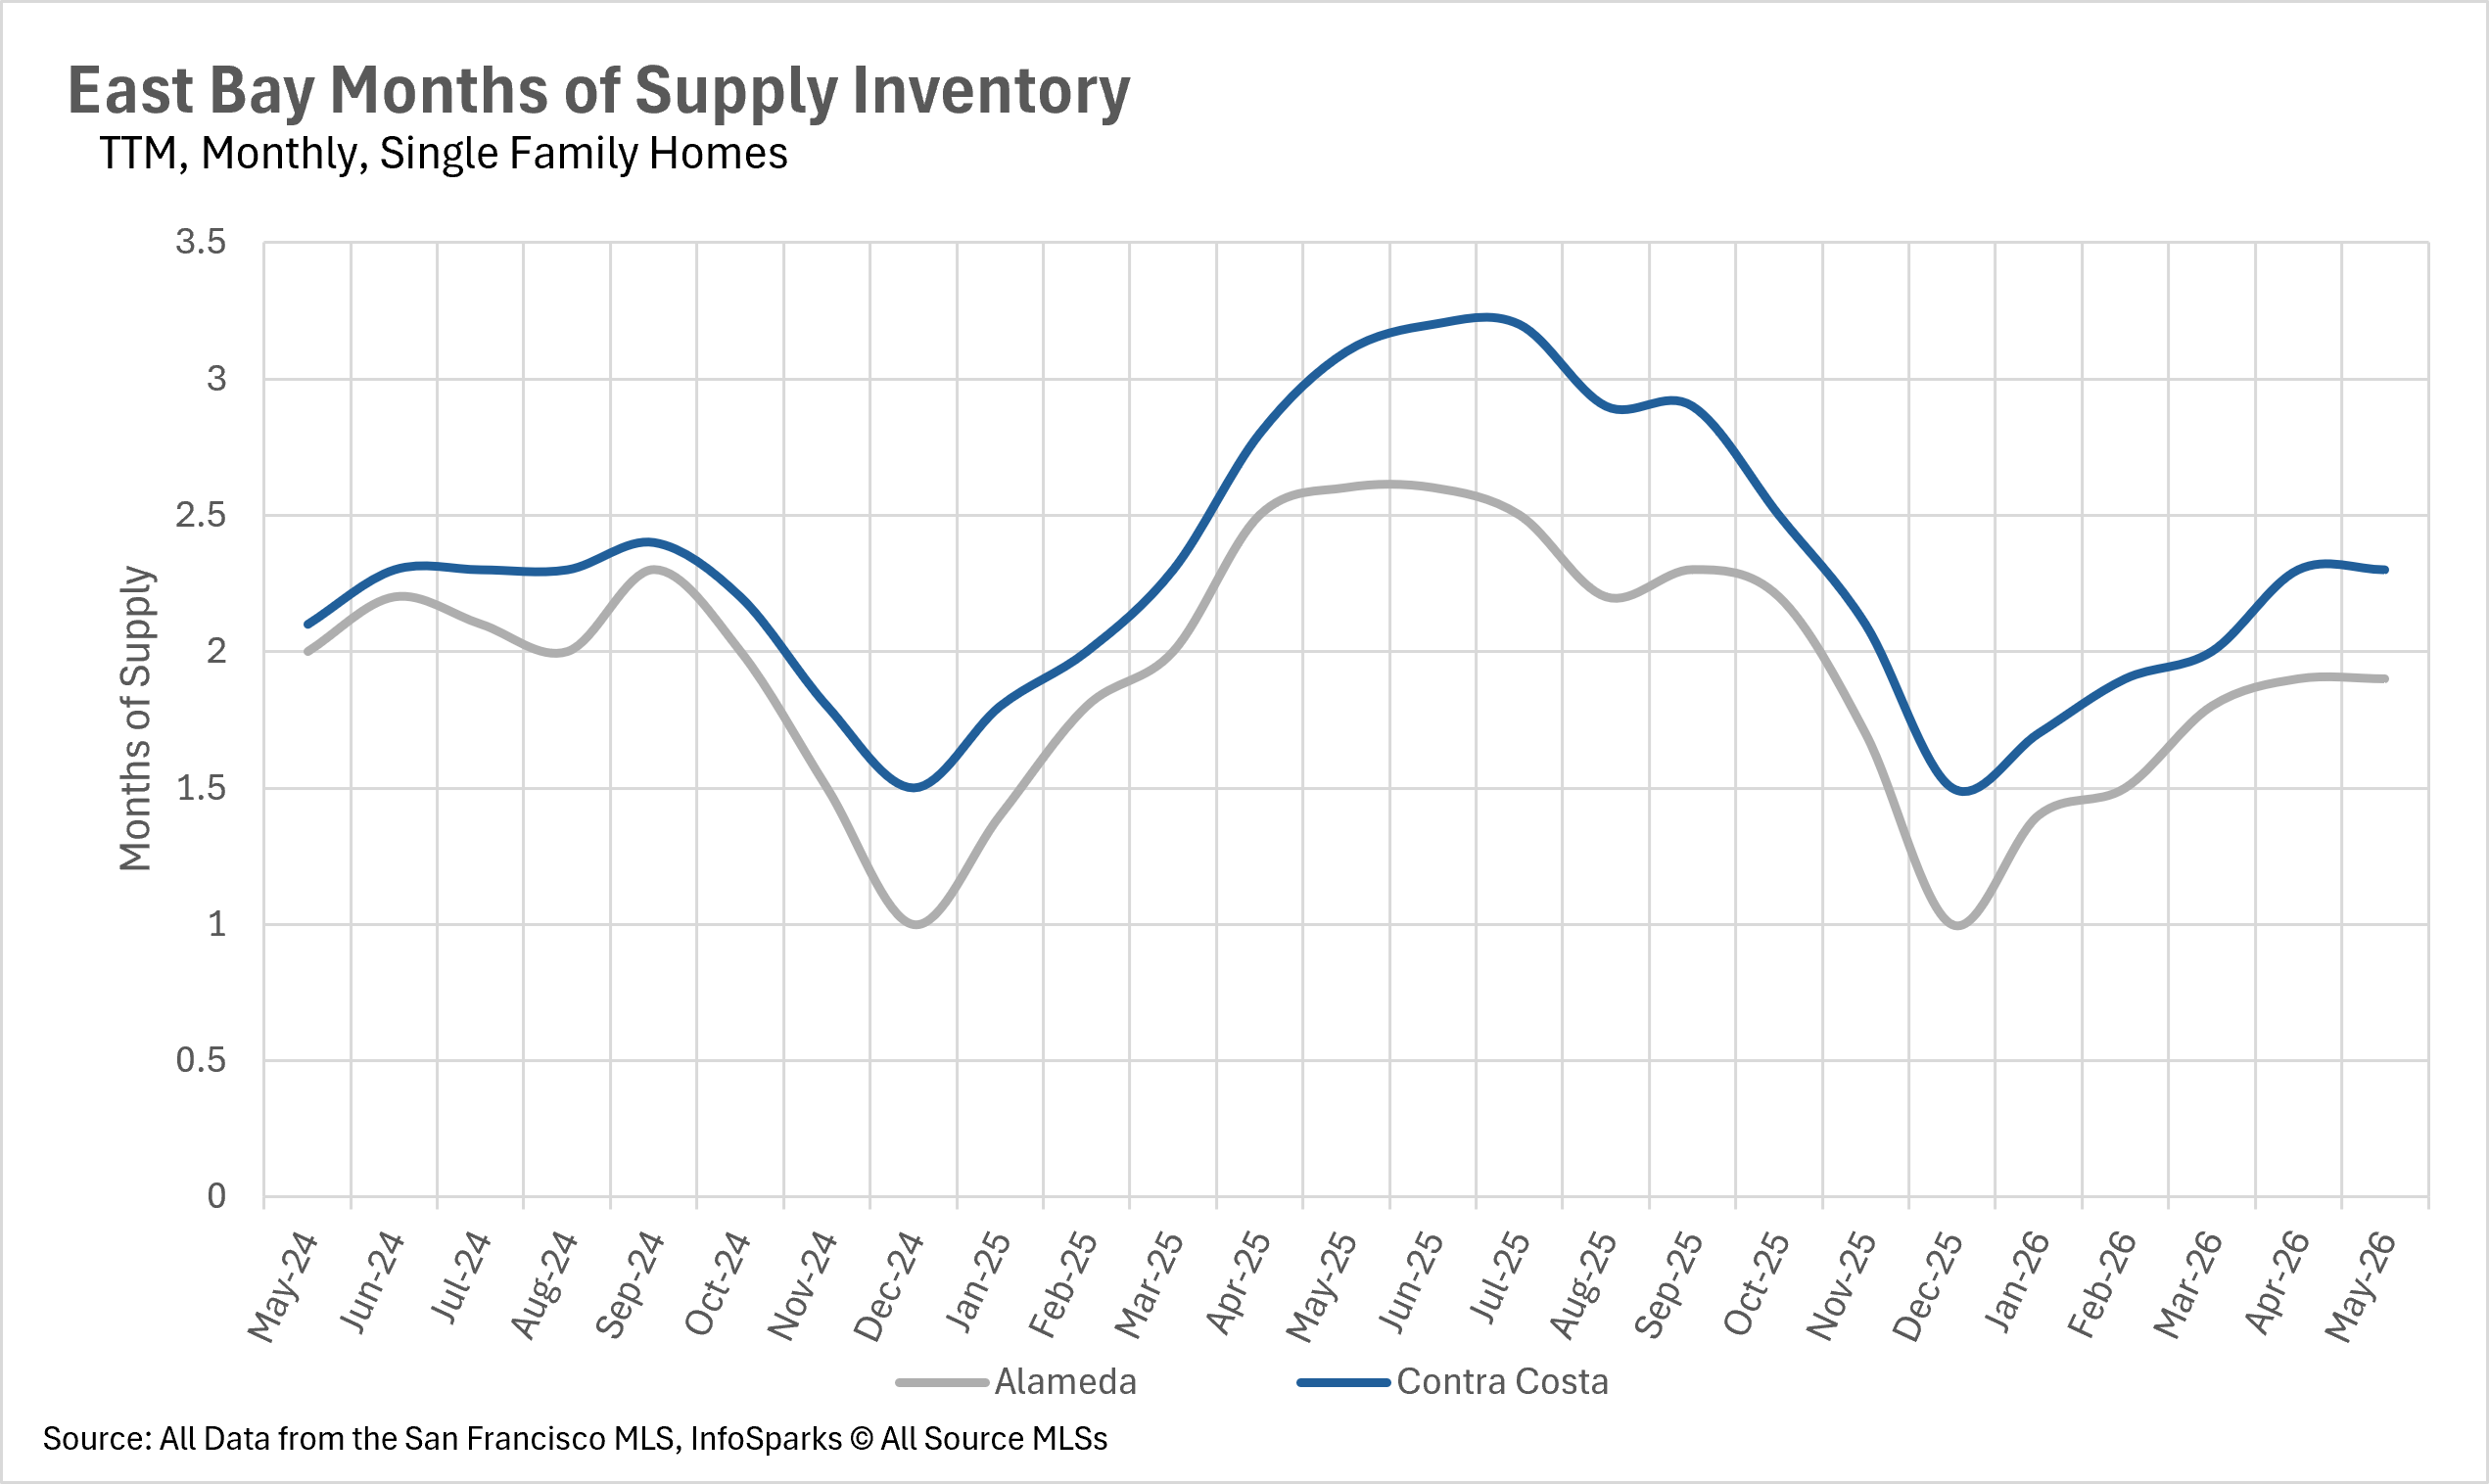
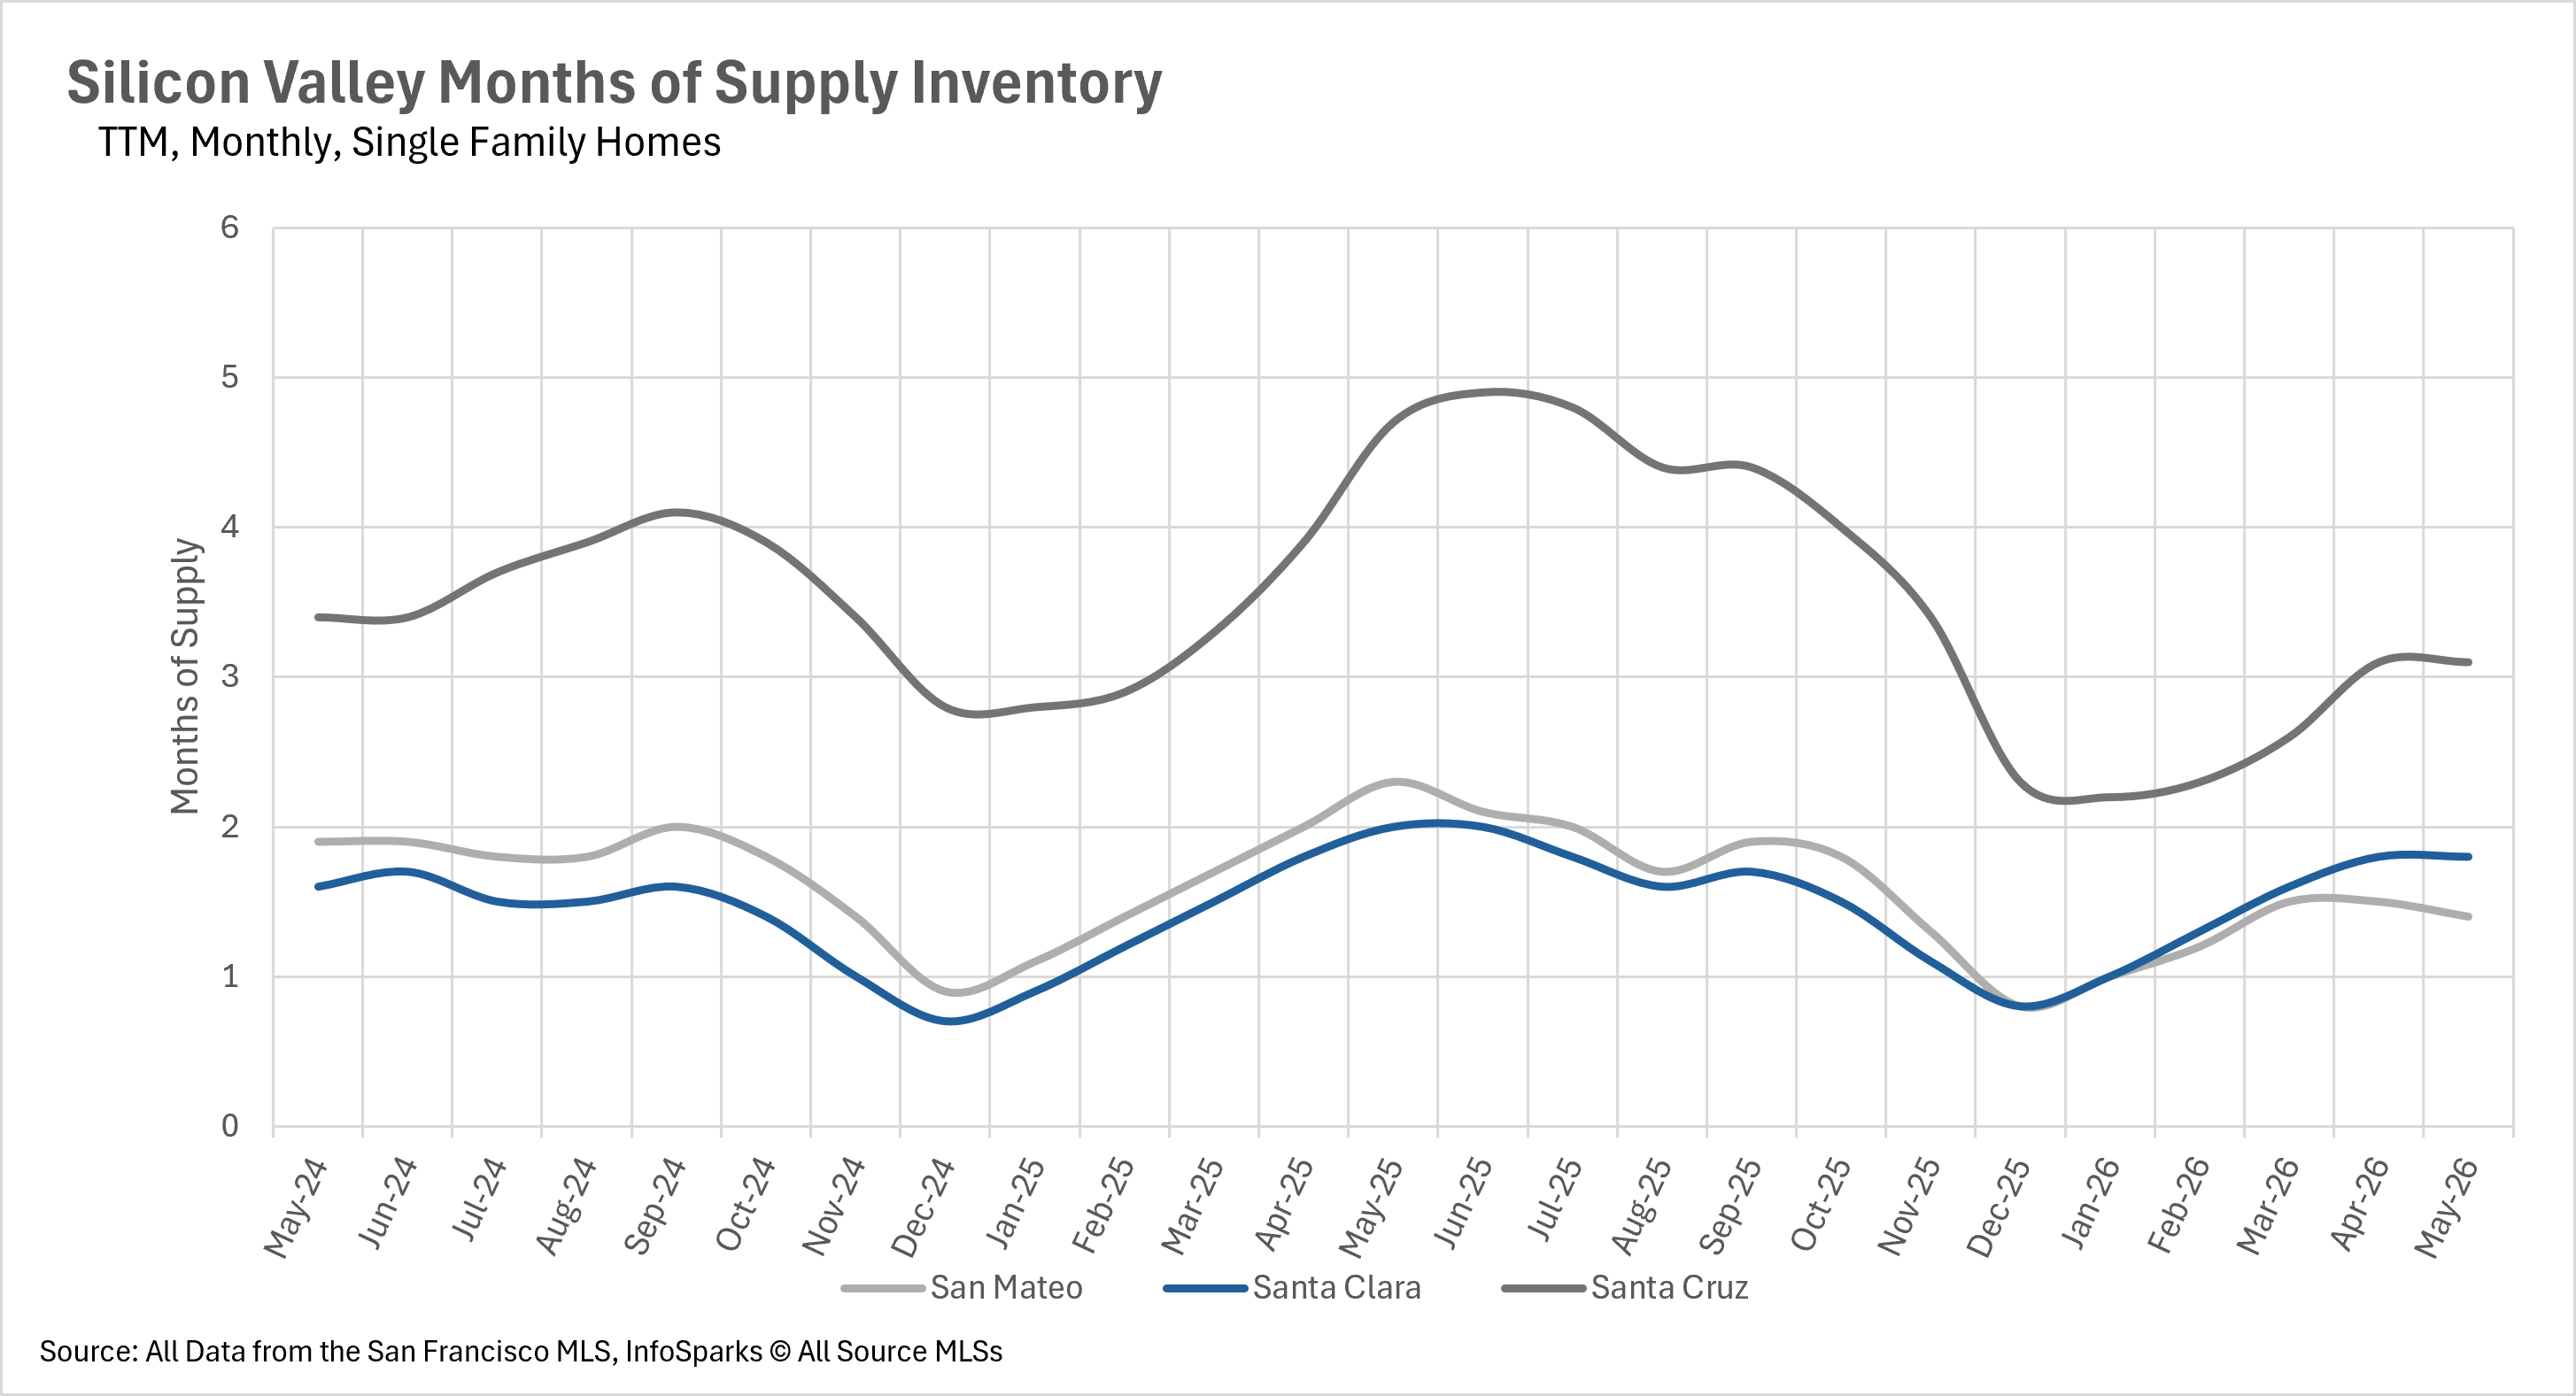
The single-family home market is deeply entrenched in seller's territory across the Bay Area as we head into summer. San Francisco sits at just 1.1 months of supply, down nearly 48% year-over-year. San Mateo County has 1.4 months of supply, down a dramatic 39.13%, while Santa Clara County has 1.8 months, down 10%. Alameda County sits at 1.9 months, Marin County at 2.2 months, Contra Costa County at 2.3 months, Solano County at 2.5 months, Sonoma County at 3.1 months, and Santa Cruz County at 3.1 months. Napa County remains the lone buyer's market at 6.6 months, though even that figure is down 28.26% year-over-year.

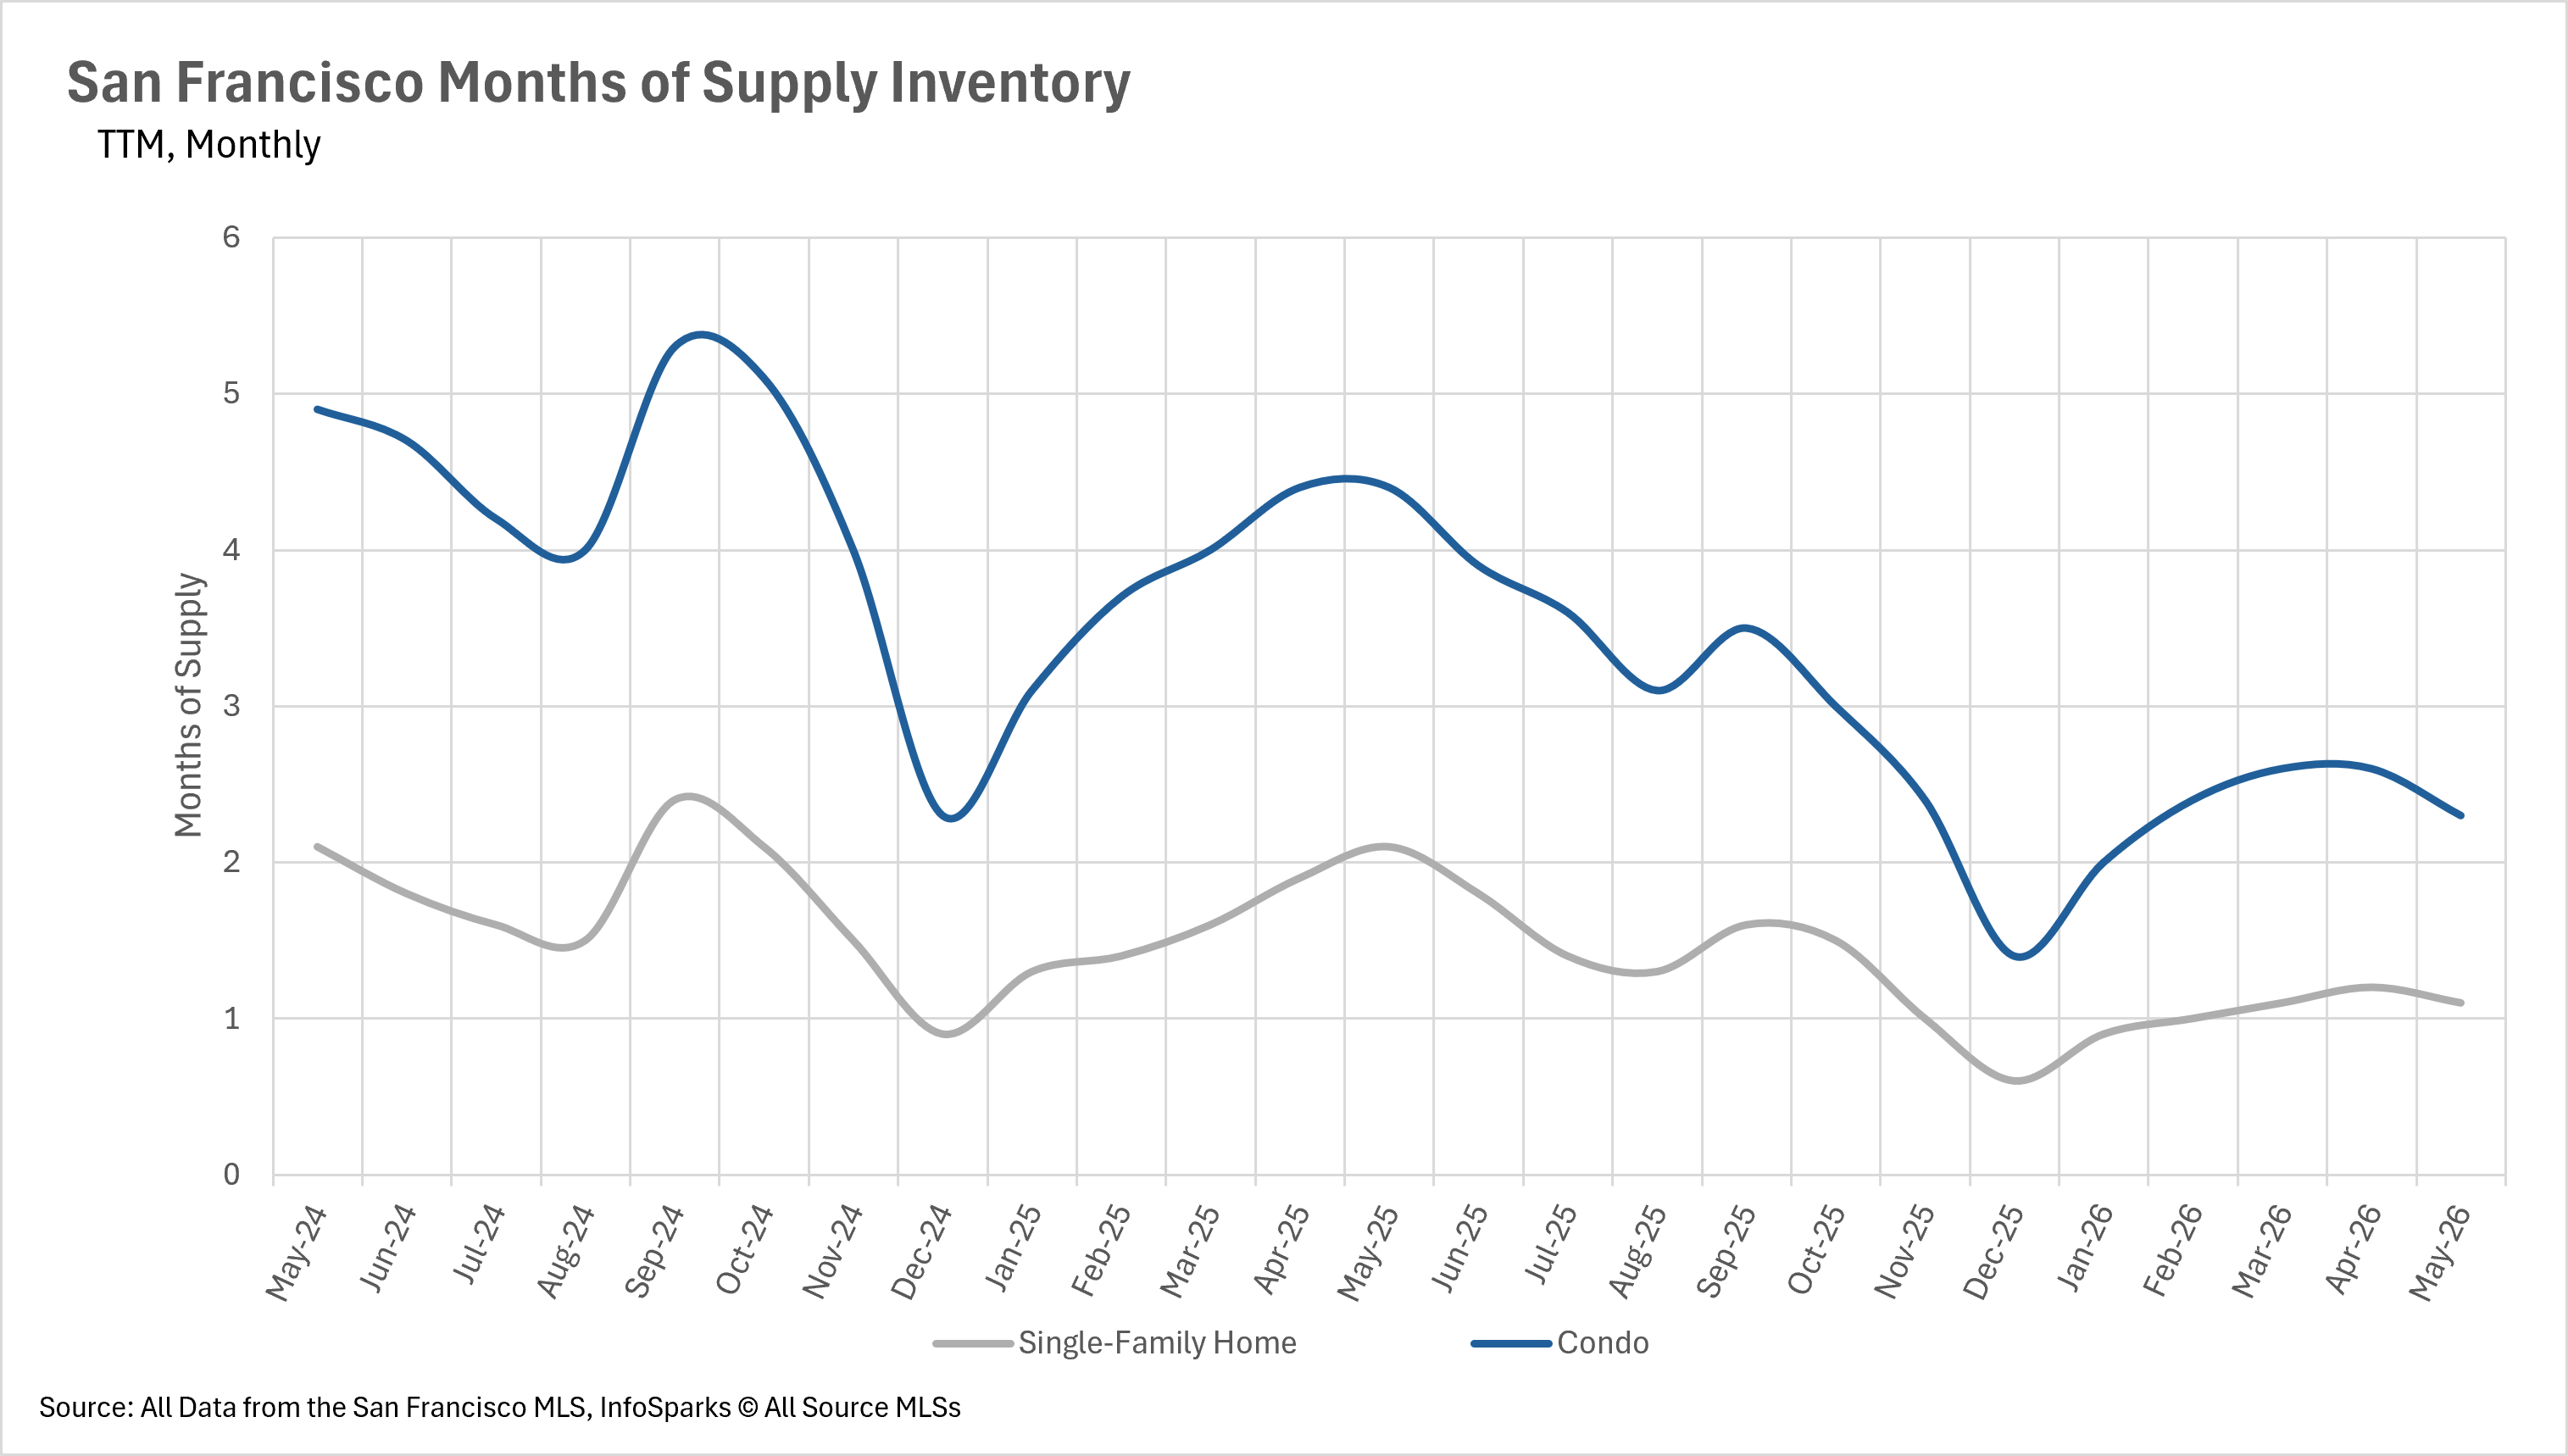
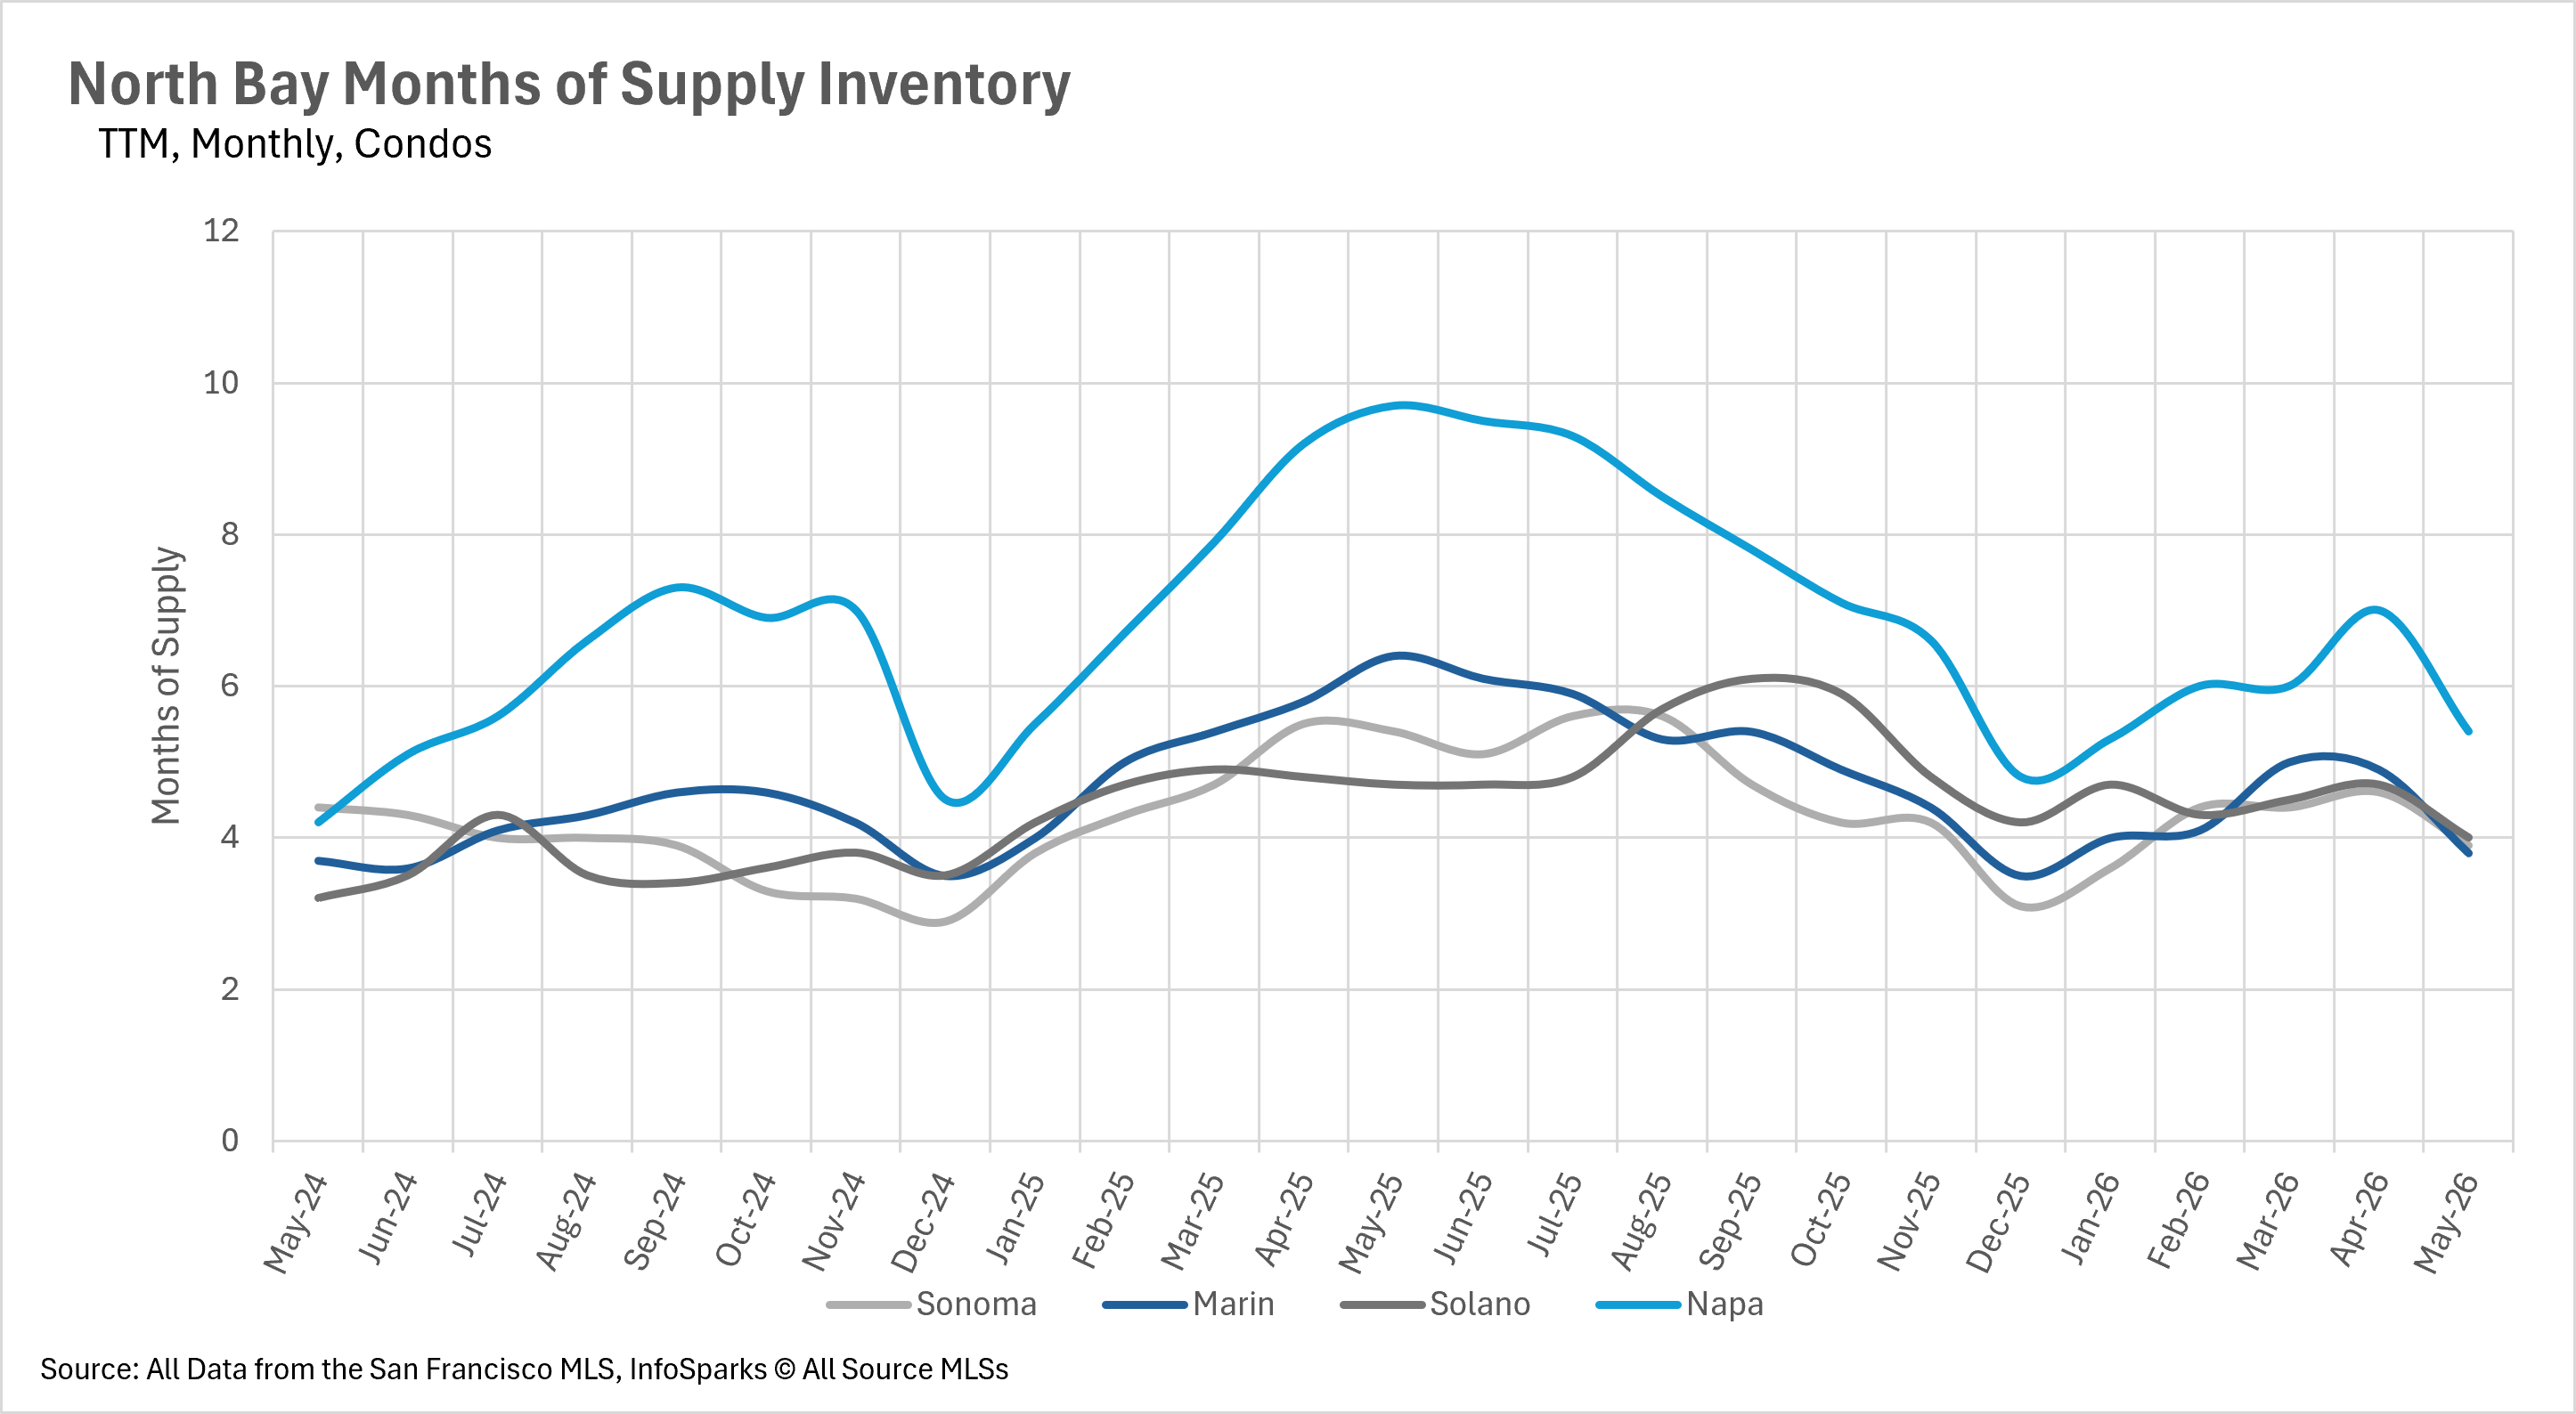
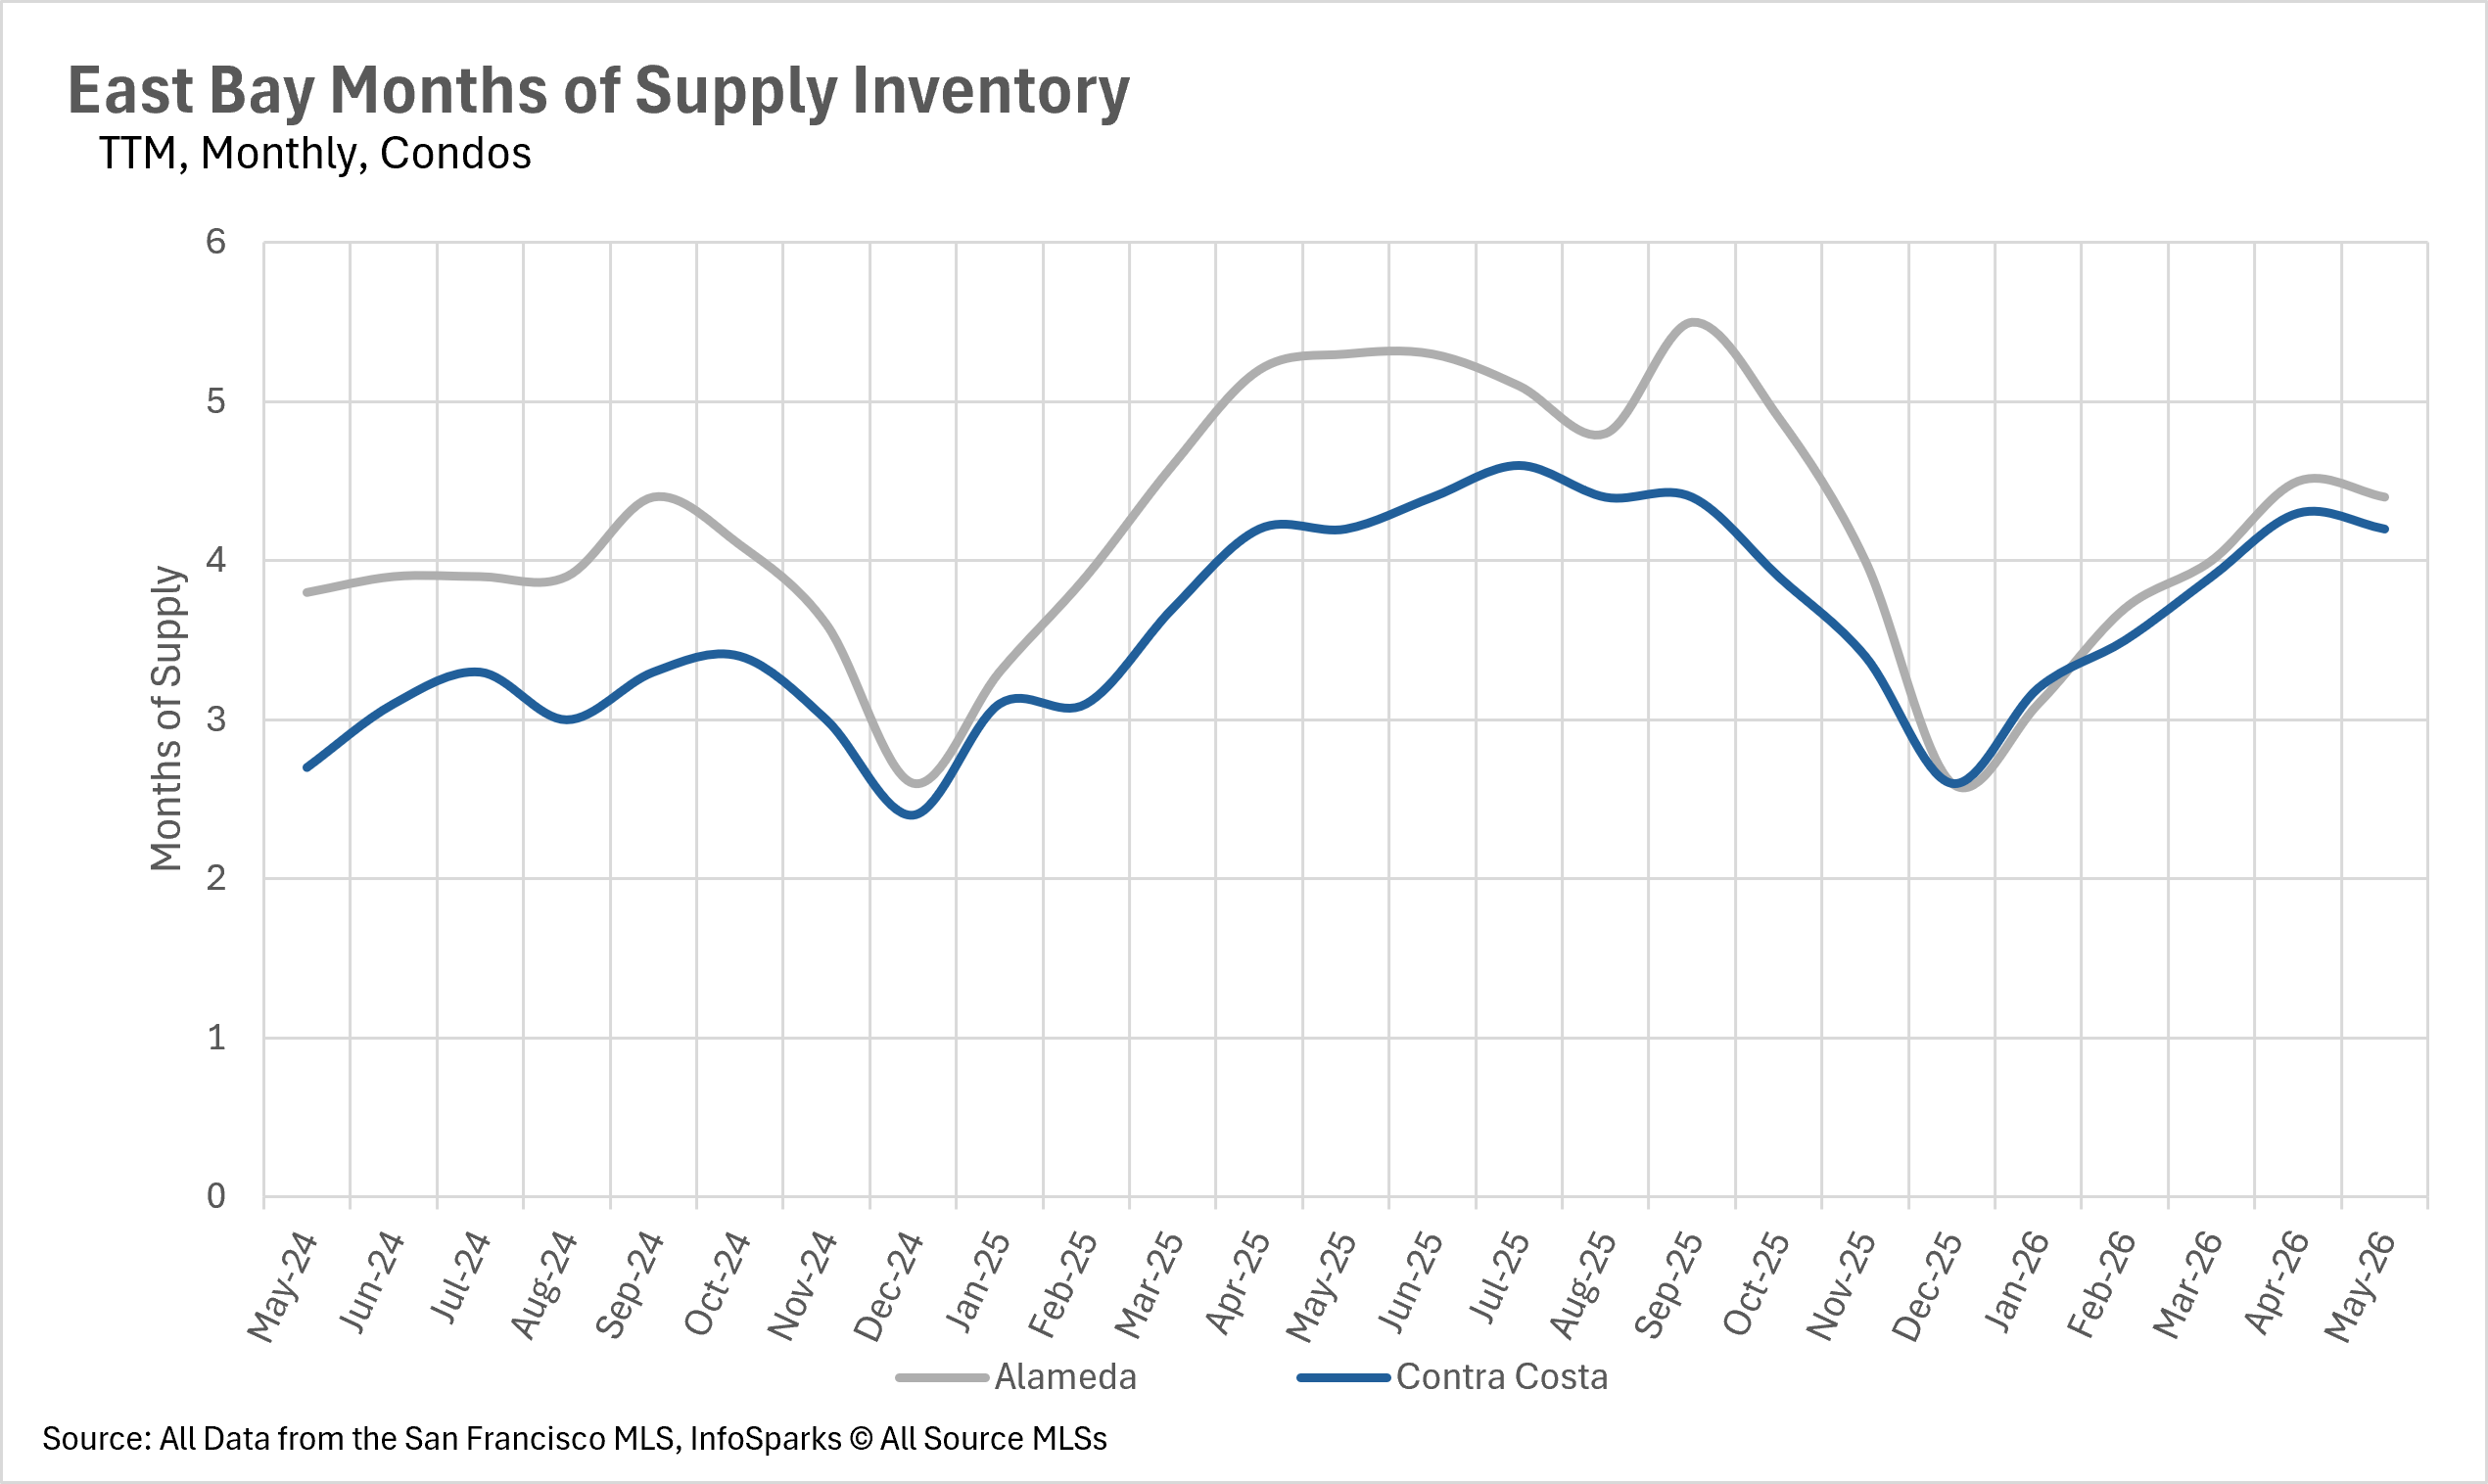
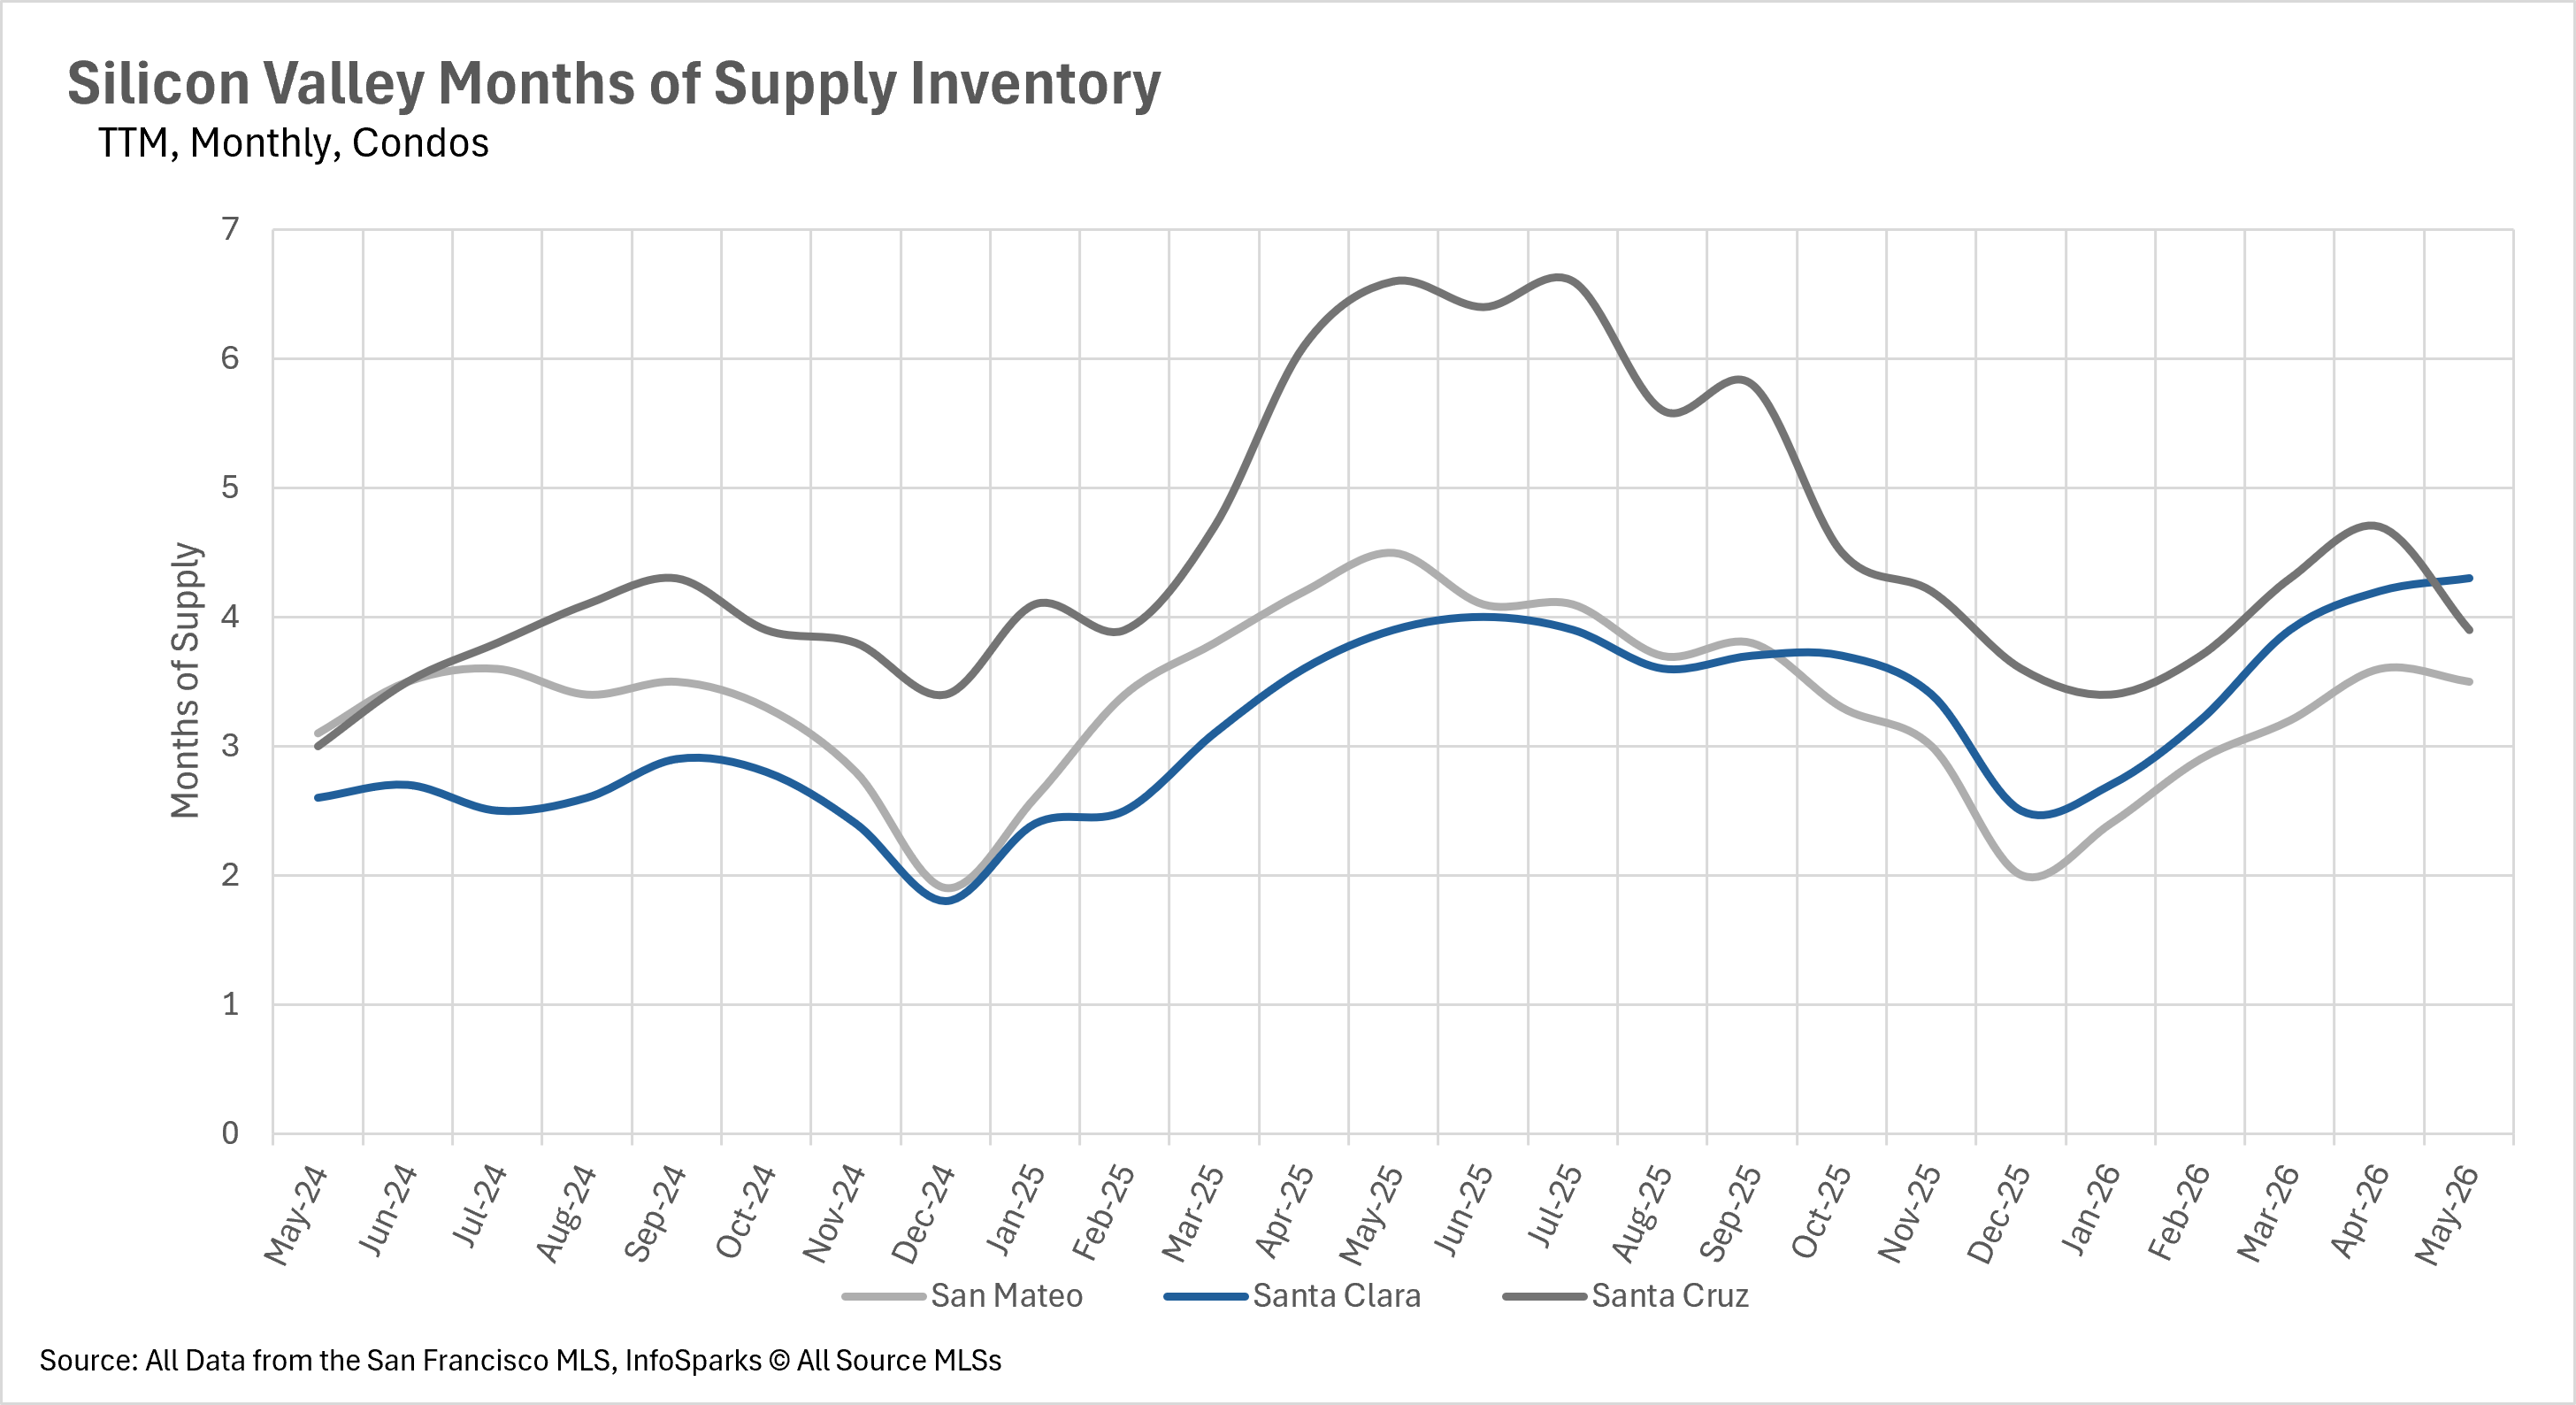
The condo market continues to offer more balance for buyers. San Francisco's condo market has fully transformed from buyer's territory last year at 4.4 months to a strong seller's market at just 2.3 months. However, most other areas remain in buyer's or balanced territory, with Alameda County at 4.4 months, Contra Costa County at 4.2 months, Santa Clara County at 4.3 months, Napa County at 5.4 months, and Solano County at 4 months. As we head into the busiest season of the year, sellers in the single-family home market are positioned to enjoy significant leverage across nearly every corner of the Bay Area.

Local Lowdown Data

San Francisco monthly median-price chart, May 2023–May 2026; single-family prices surge above $2 million in 2026.

Chart comparing year-over-year San Francisco median price changes for single-family homes and condos, June 2025–May 2026.

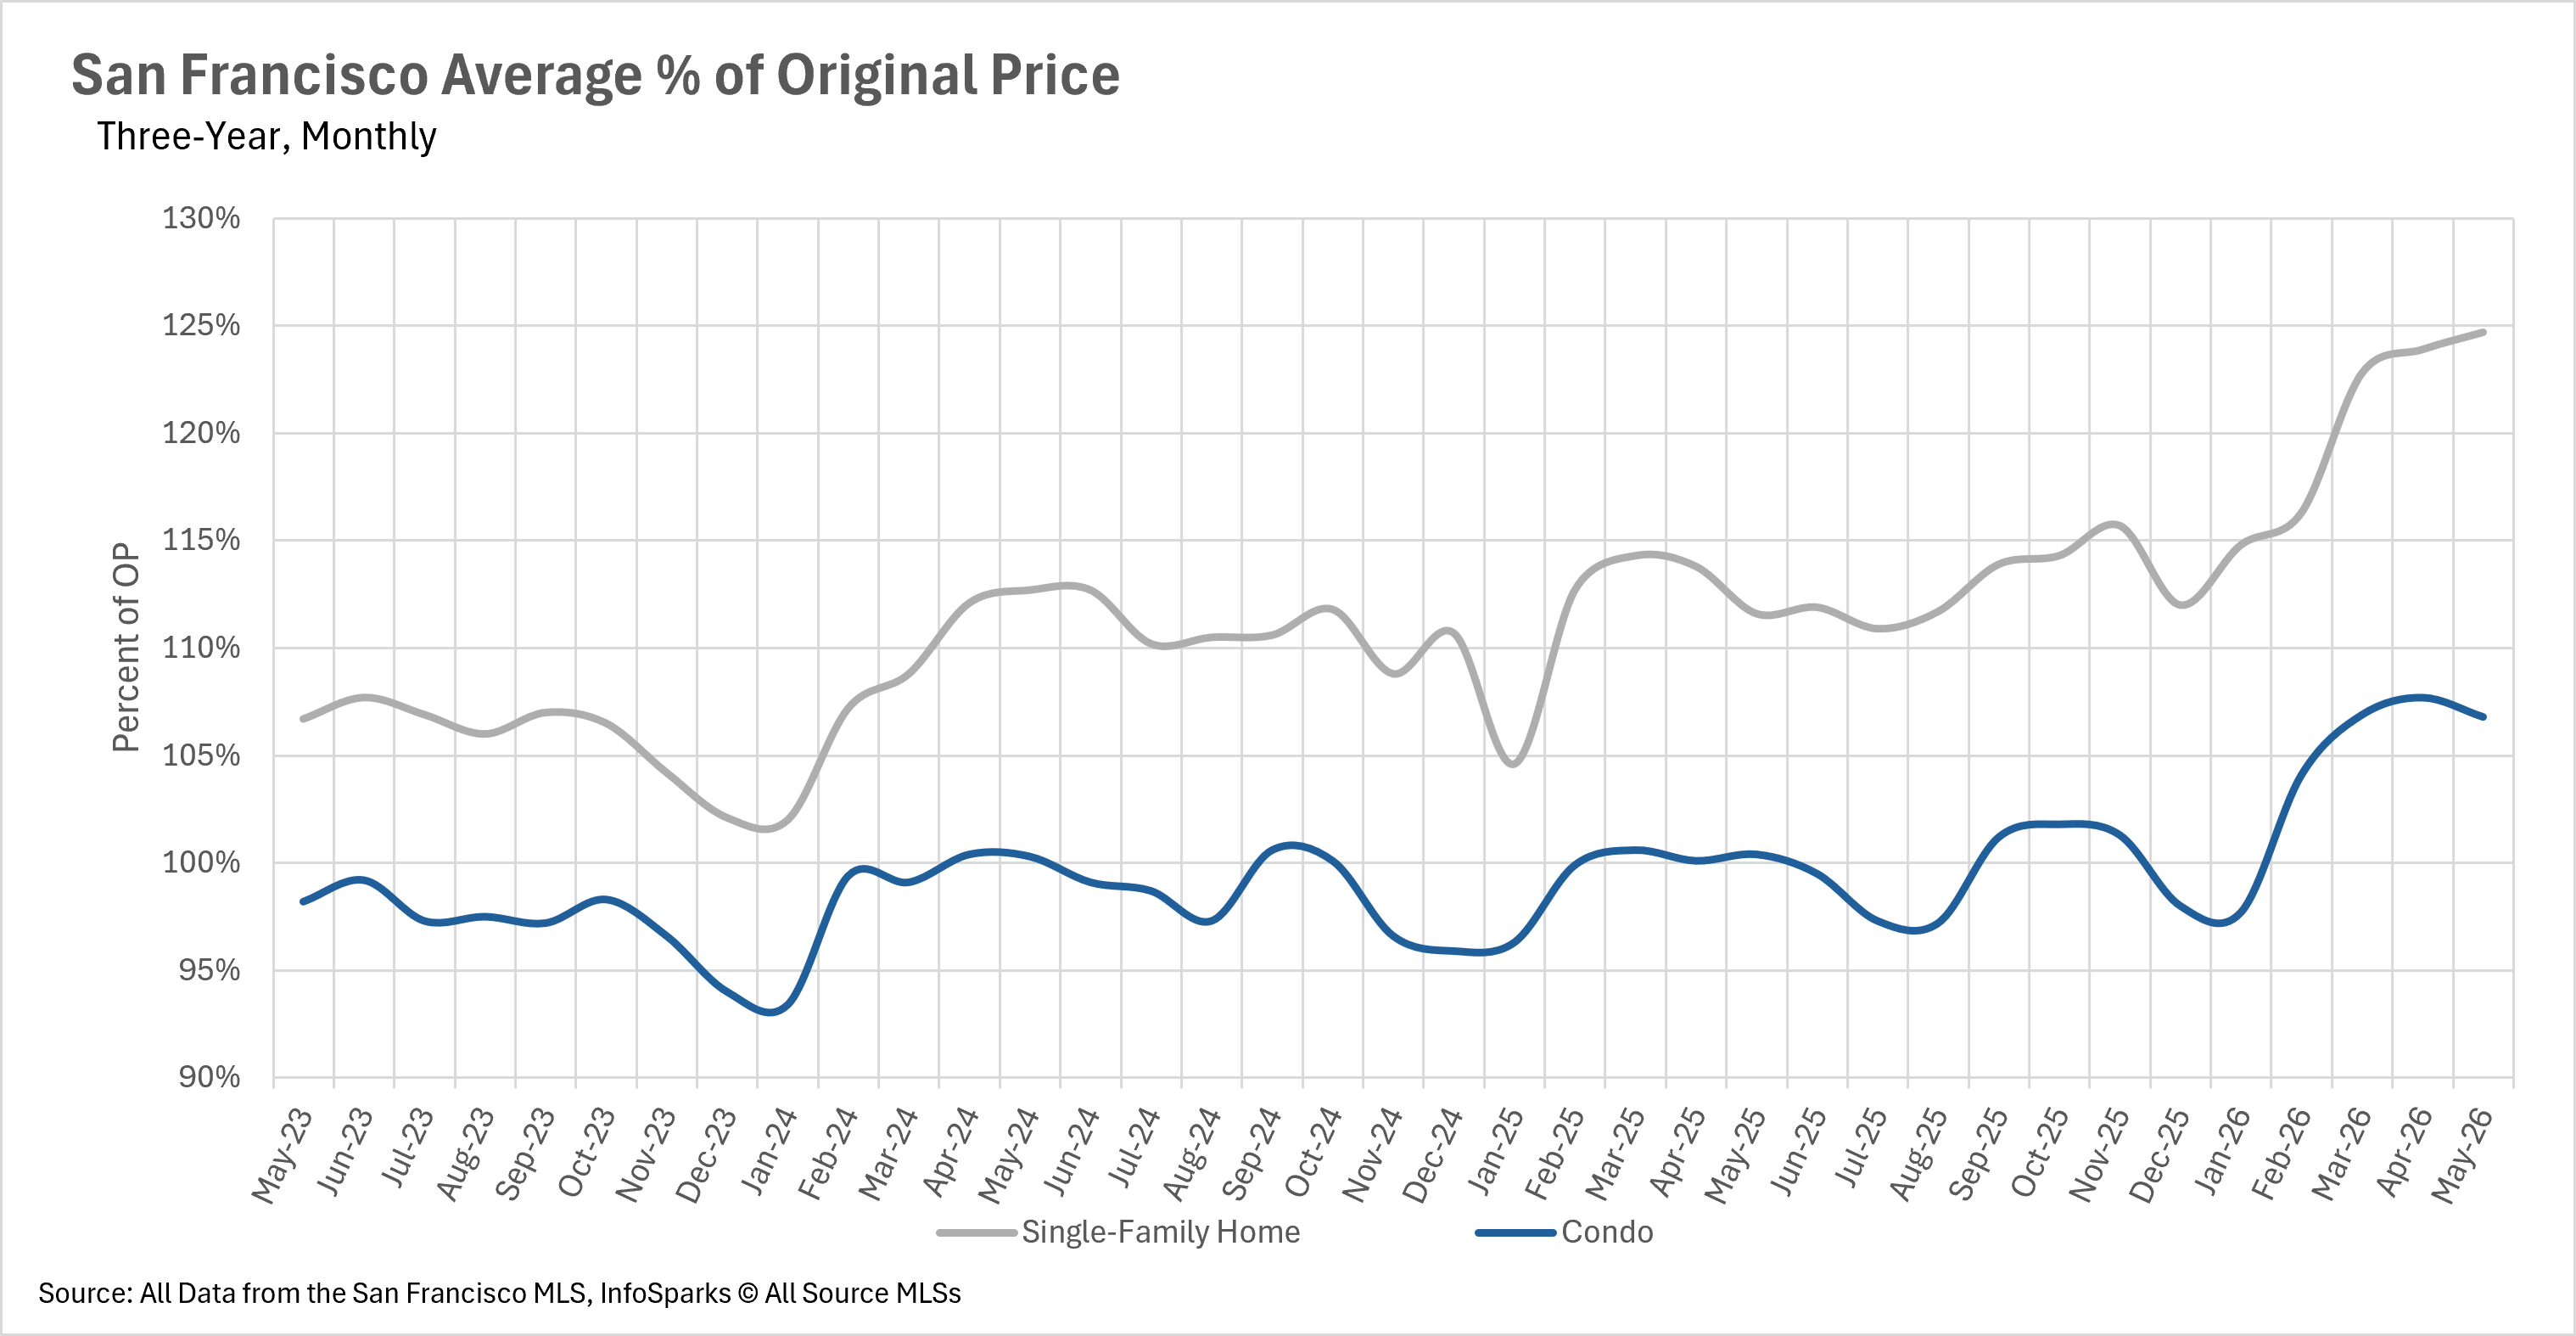
San Francisco home sale prices as a percentage of original price, shown monthly for single-family homes and condos, May 2023–May 2026.

San Francisco condo inventory chart showing monthly new listings, sold listings, and listings for sale, May 2024–May 2026.

San Francisco single-family home inventory chart comparing new, sold, and for-sale listings over two years.

Chart comparing San Francisco condo and single-family home months of supply from May 2024 to May 2026.

Chart comparing monthly San Francisco days on market for single-family homes and condos from May 2024 to May 2026.

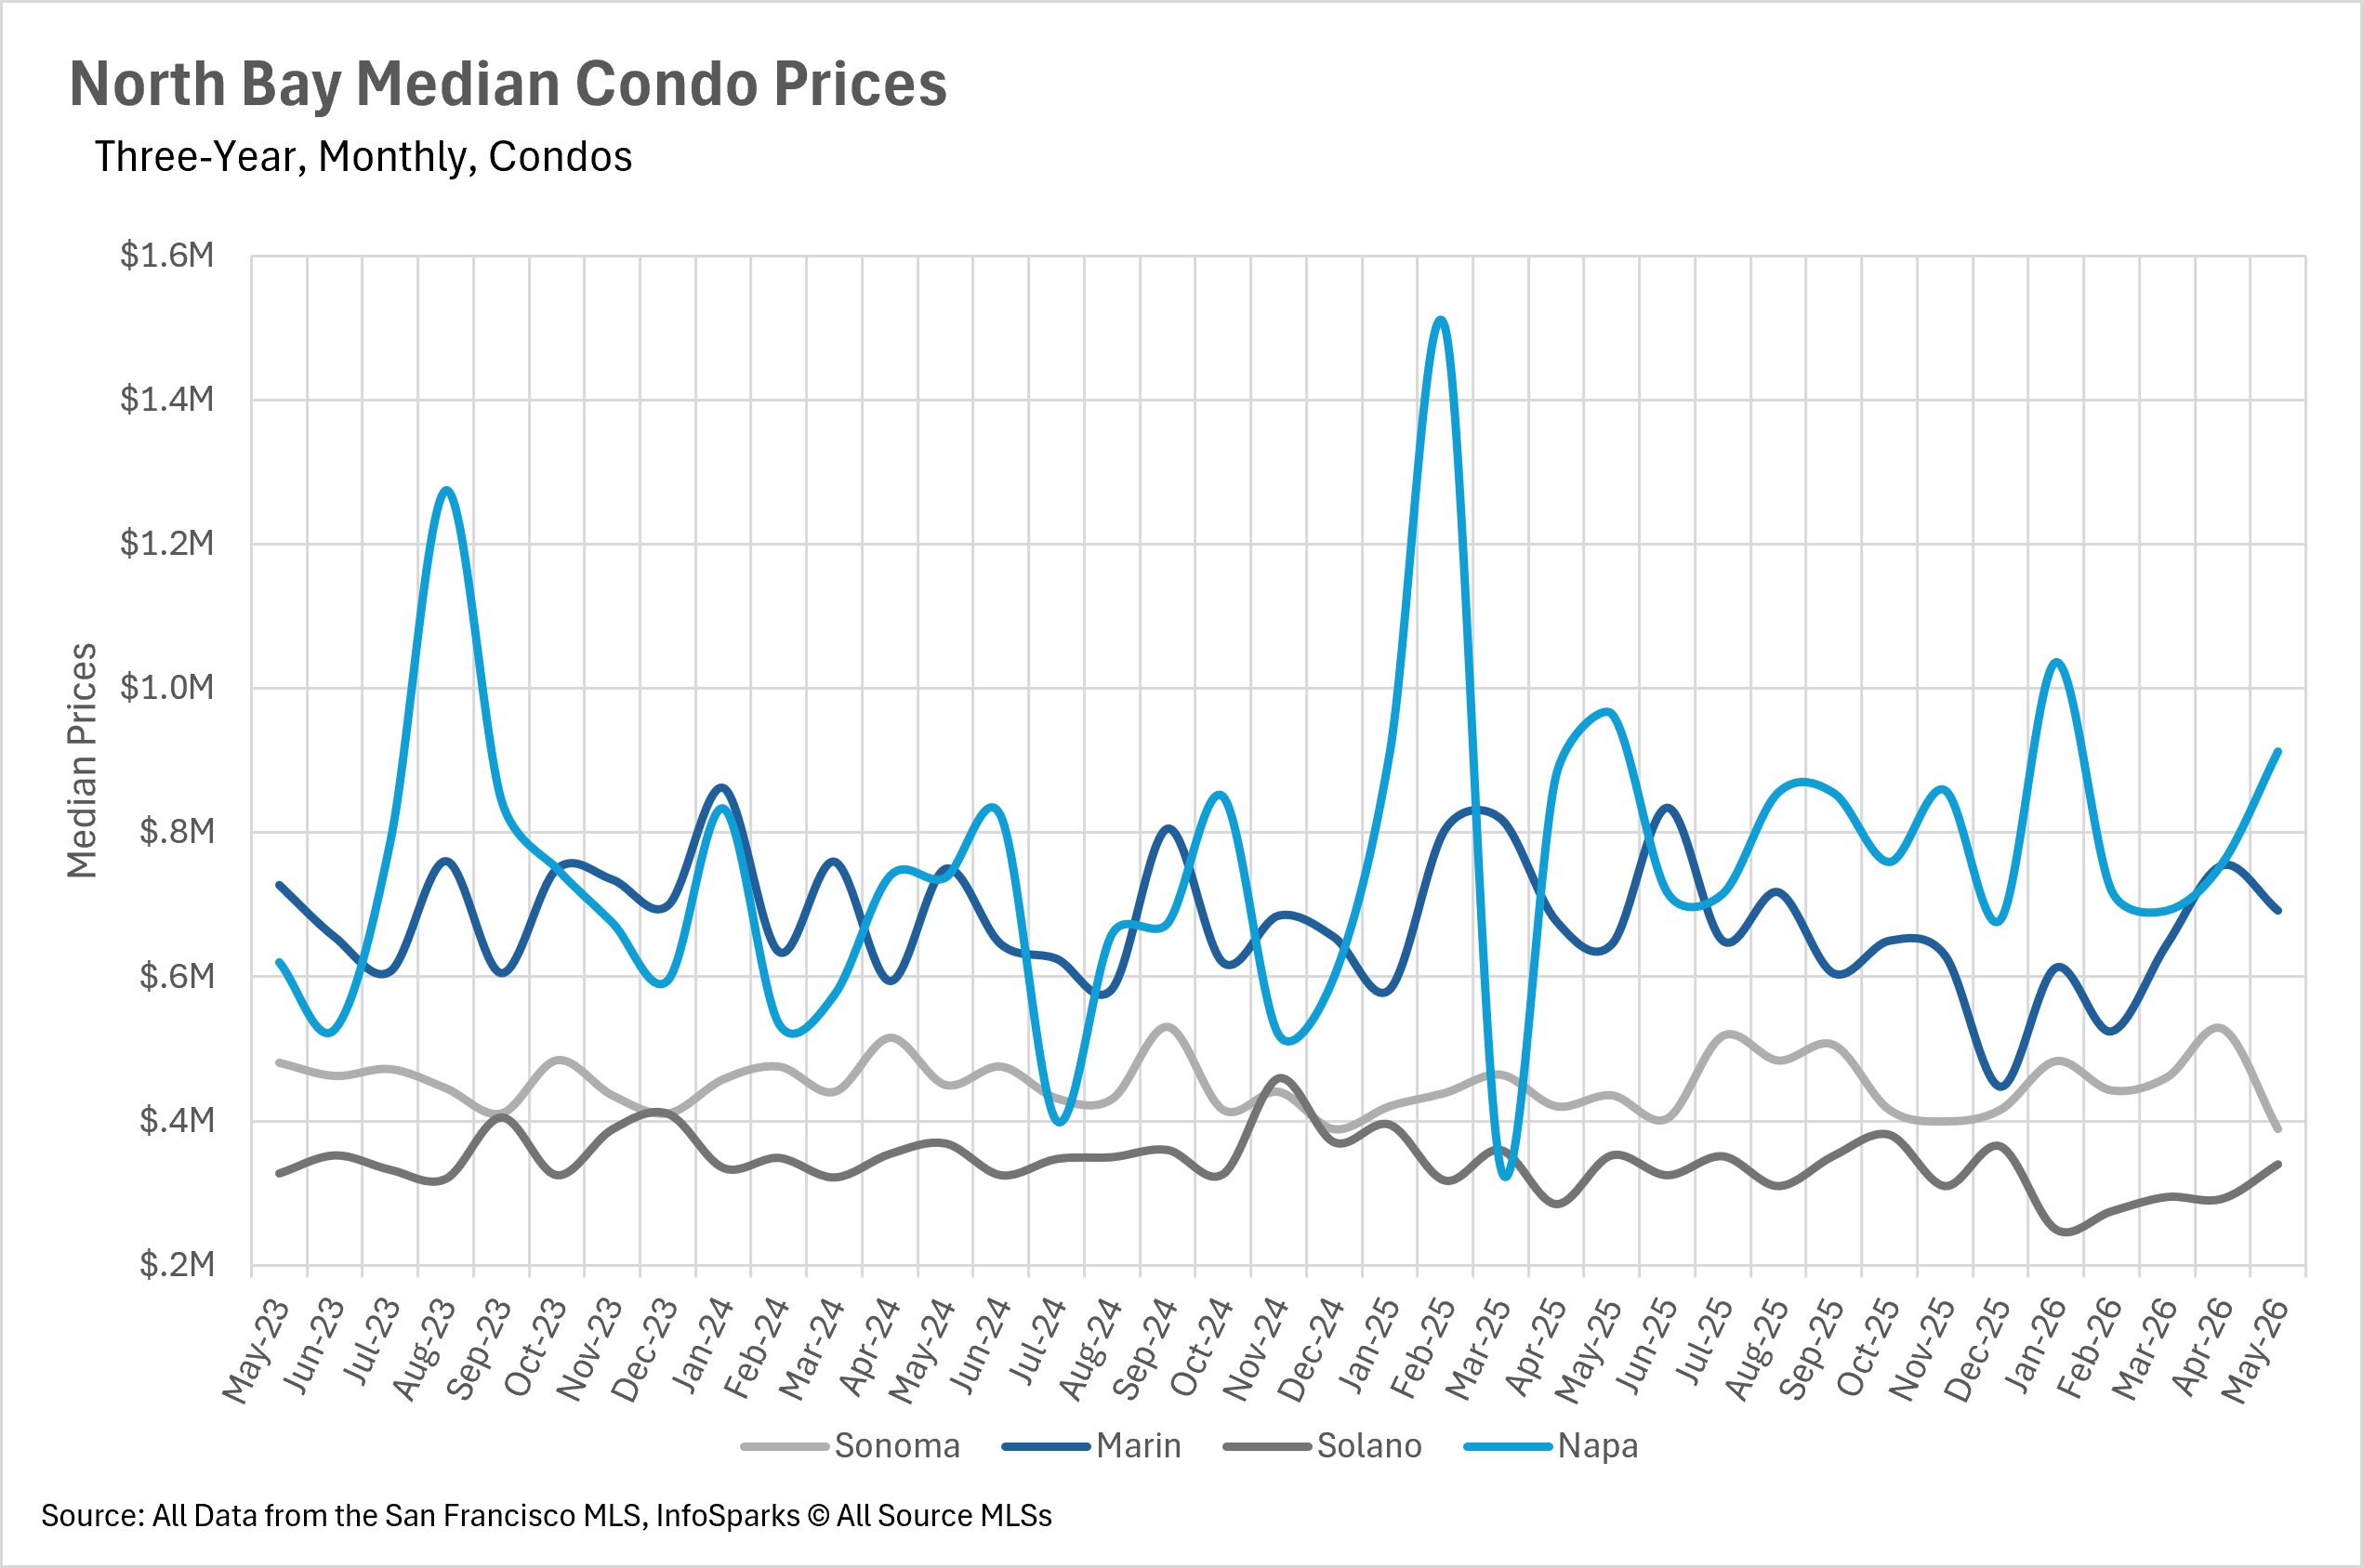
Line chart of monthly North Bay condo prices by county from May 2023 to May 2026, with Napa showing the widest swings.

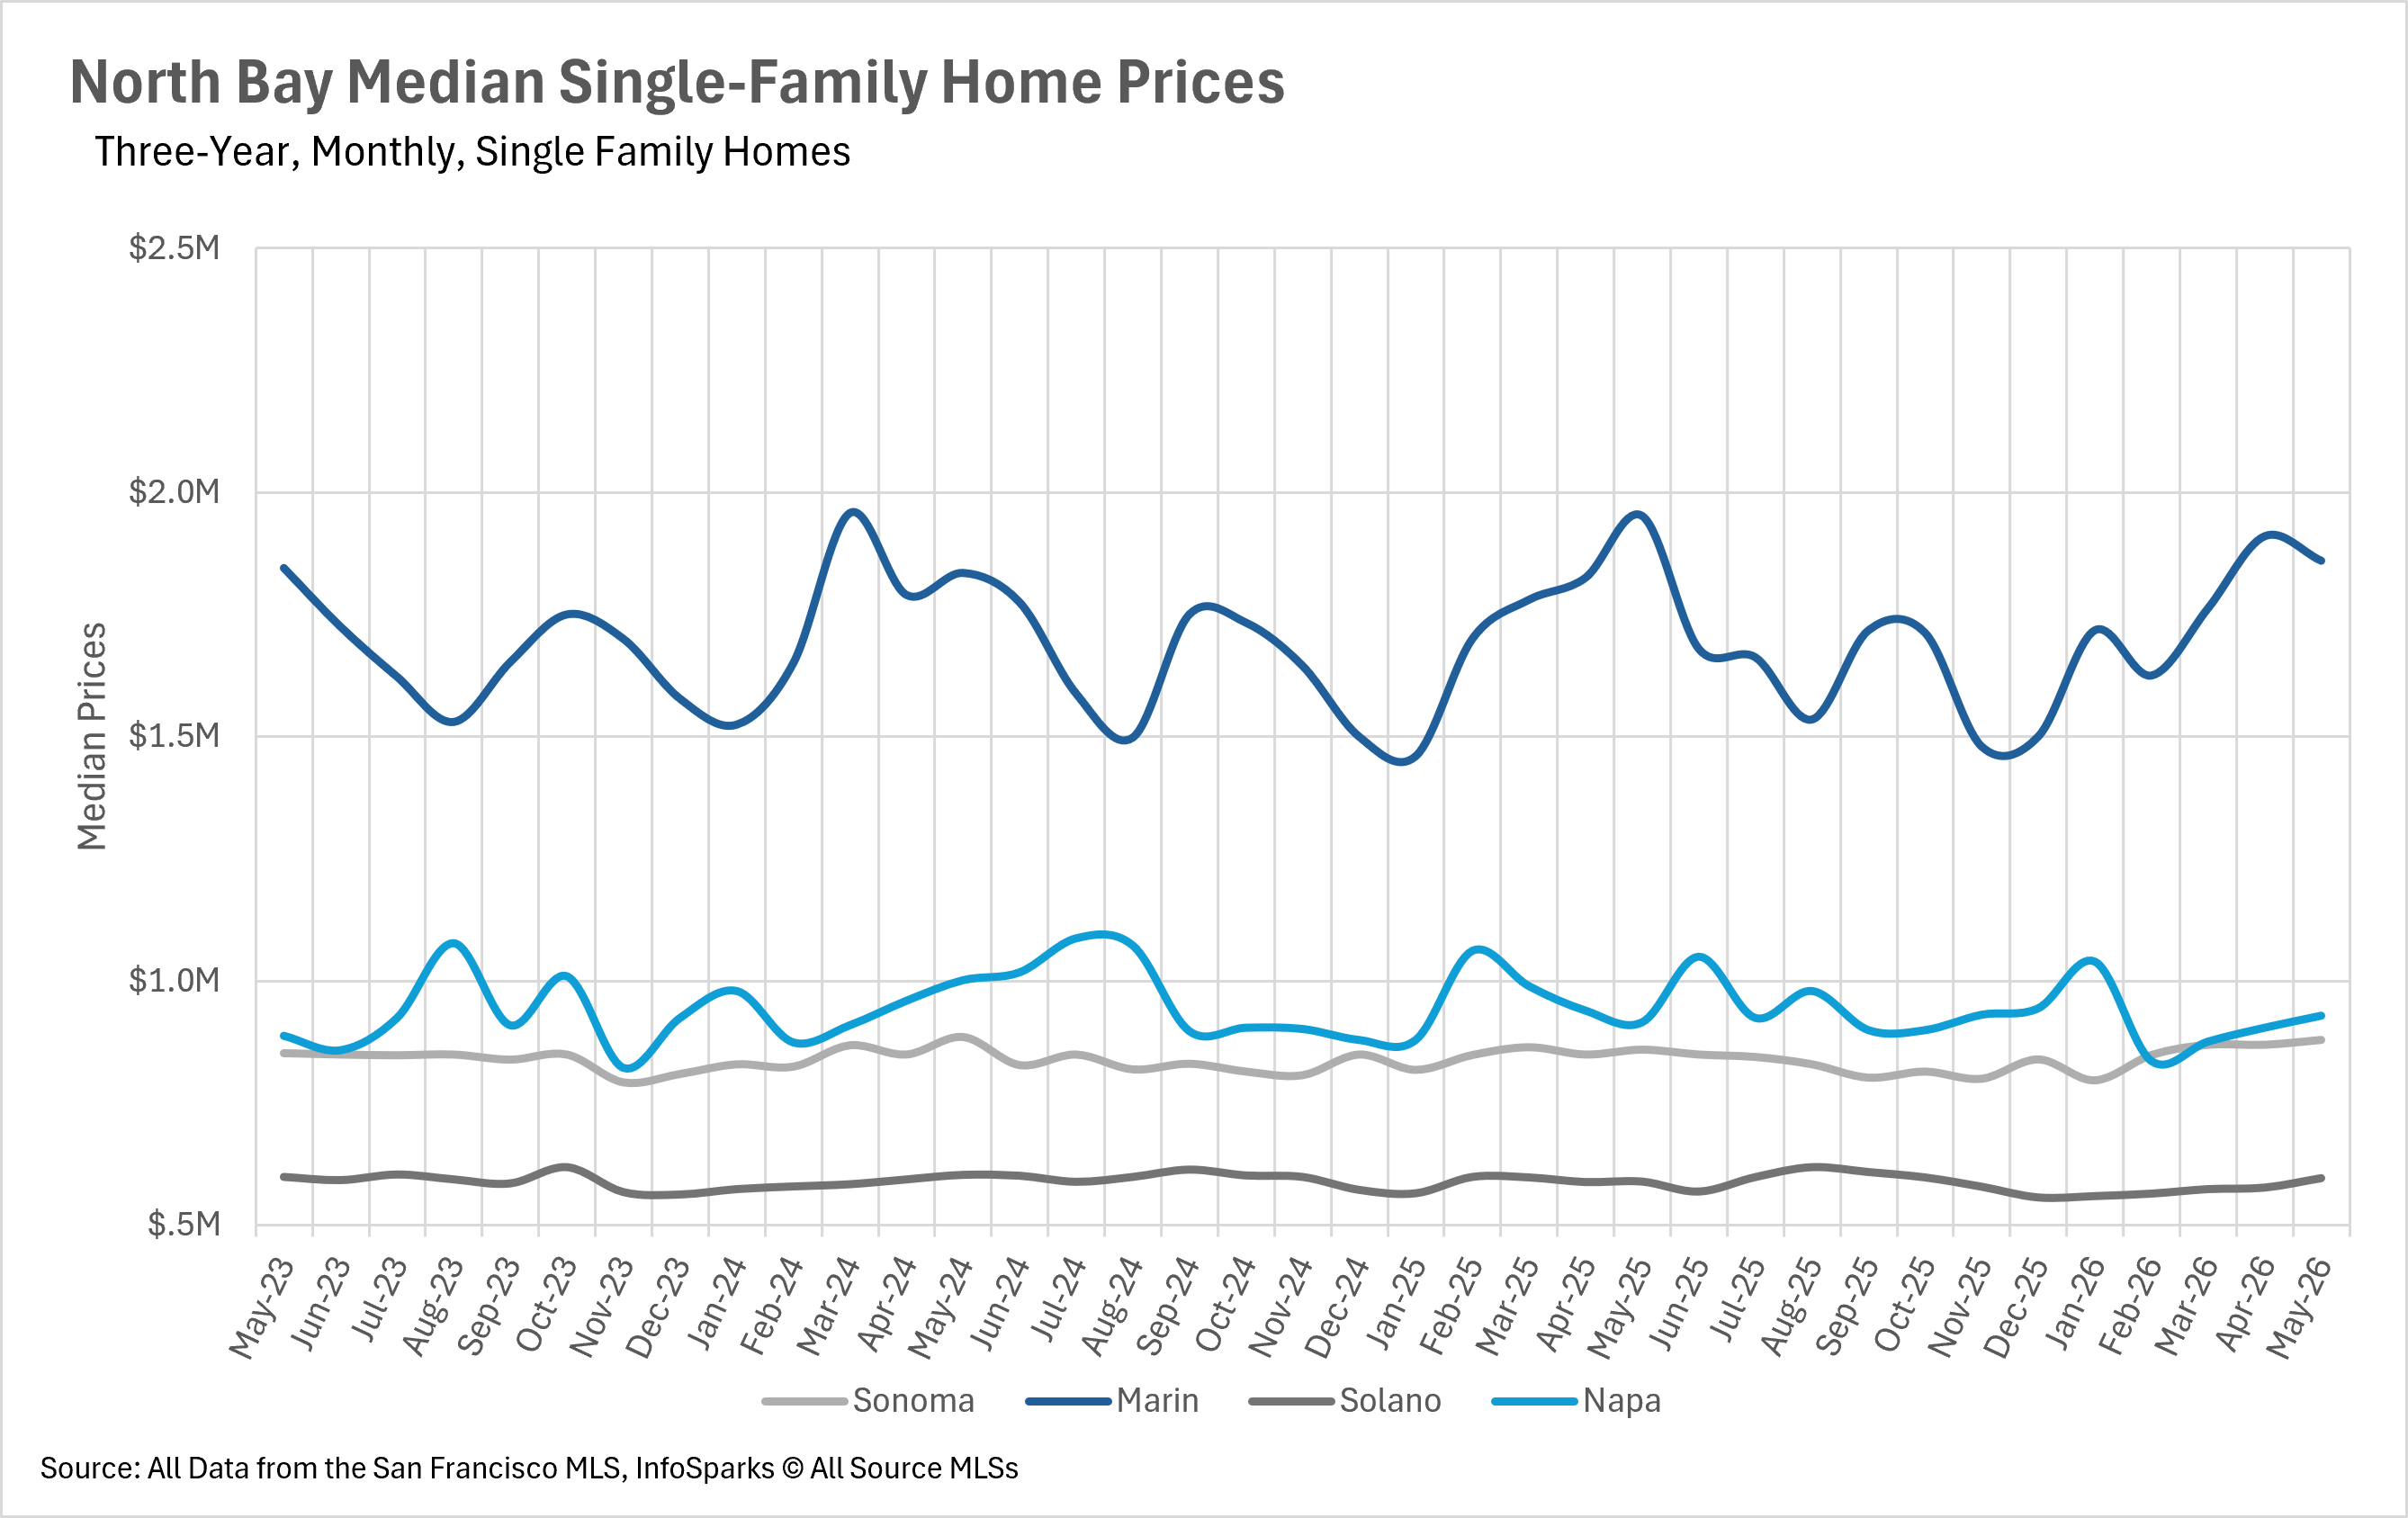
Line chart comparing monthly single-family home prices in Sonoma, Marin, Solano, and Napa counties, May 2023–May 2026.

Chart of year-over-year median condo price changes for four North Bay counties, June 2025 to May 2026.

Chart of year-over-year North Bay single-family home price changes by county, June 2025 to May 2026.

Chart of North Bay condo listings, showing monthly new listings, sold listings, and for-sale inventory from May 2024 to May 2026.

Chart of North Bay single-family home listings and sales, with for-sale totals, from May 2024 to May 2026.

Line chart of monthly condo inventory by North Bay county, May 2024–May 2026; Napa peaks near 9.7 months.

Line chart compares monthly housing inventory across four North Bay counties from May 2024 to May 2026; Napa remains highest.

Line chart comparing monthly condo days on market in Sonoma, Marin, Solano, and Napa counties, May 2024–May 2026.

North Bay days-on-market chart comparing Sonoma, Marin, Solano, and Napa single-family homes from May 2024 to May 2026.

Line chart of monthly East Bay condo prices for Alameda and Contra Costa, May 2023–May 2026.

Line chart comparing monthly median single-family home prices in Alameda and Contra Costa counties, May 2023–May 2026.

Chart comparing year-over-year East Bay condo price changes in Alameda and Contra Costa, June 2025 to May 2026.

Chart of East Bay single-family home price changes, with both Alameda and Contra Costa up in May 2026.

East Bay condo inventory chart comparing monthly new listings, sold listings, and homes for sale from May 2024 to May 2026.

East Bay single-family home inventory chart, tracking monthly new listings, sales, and homes for sale from May 2024 to May 2026.

Line chart comparing monthly condo supply in Alameda and Contra Costa counties from May 2024 to May 2026.

Line chart comparing monthly single-family home supply in Alameda and Contra Costa counties, May 2024 to May 2026.

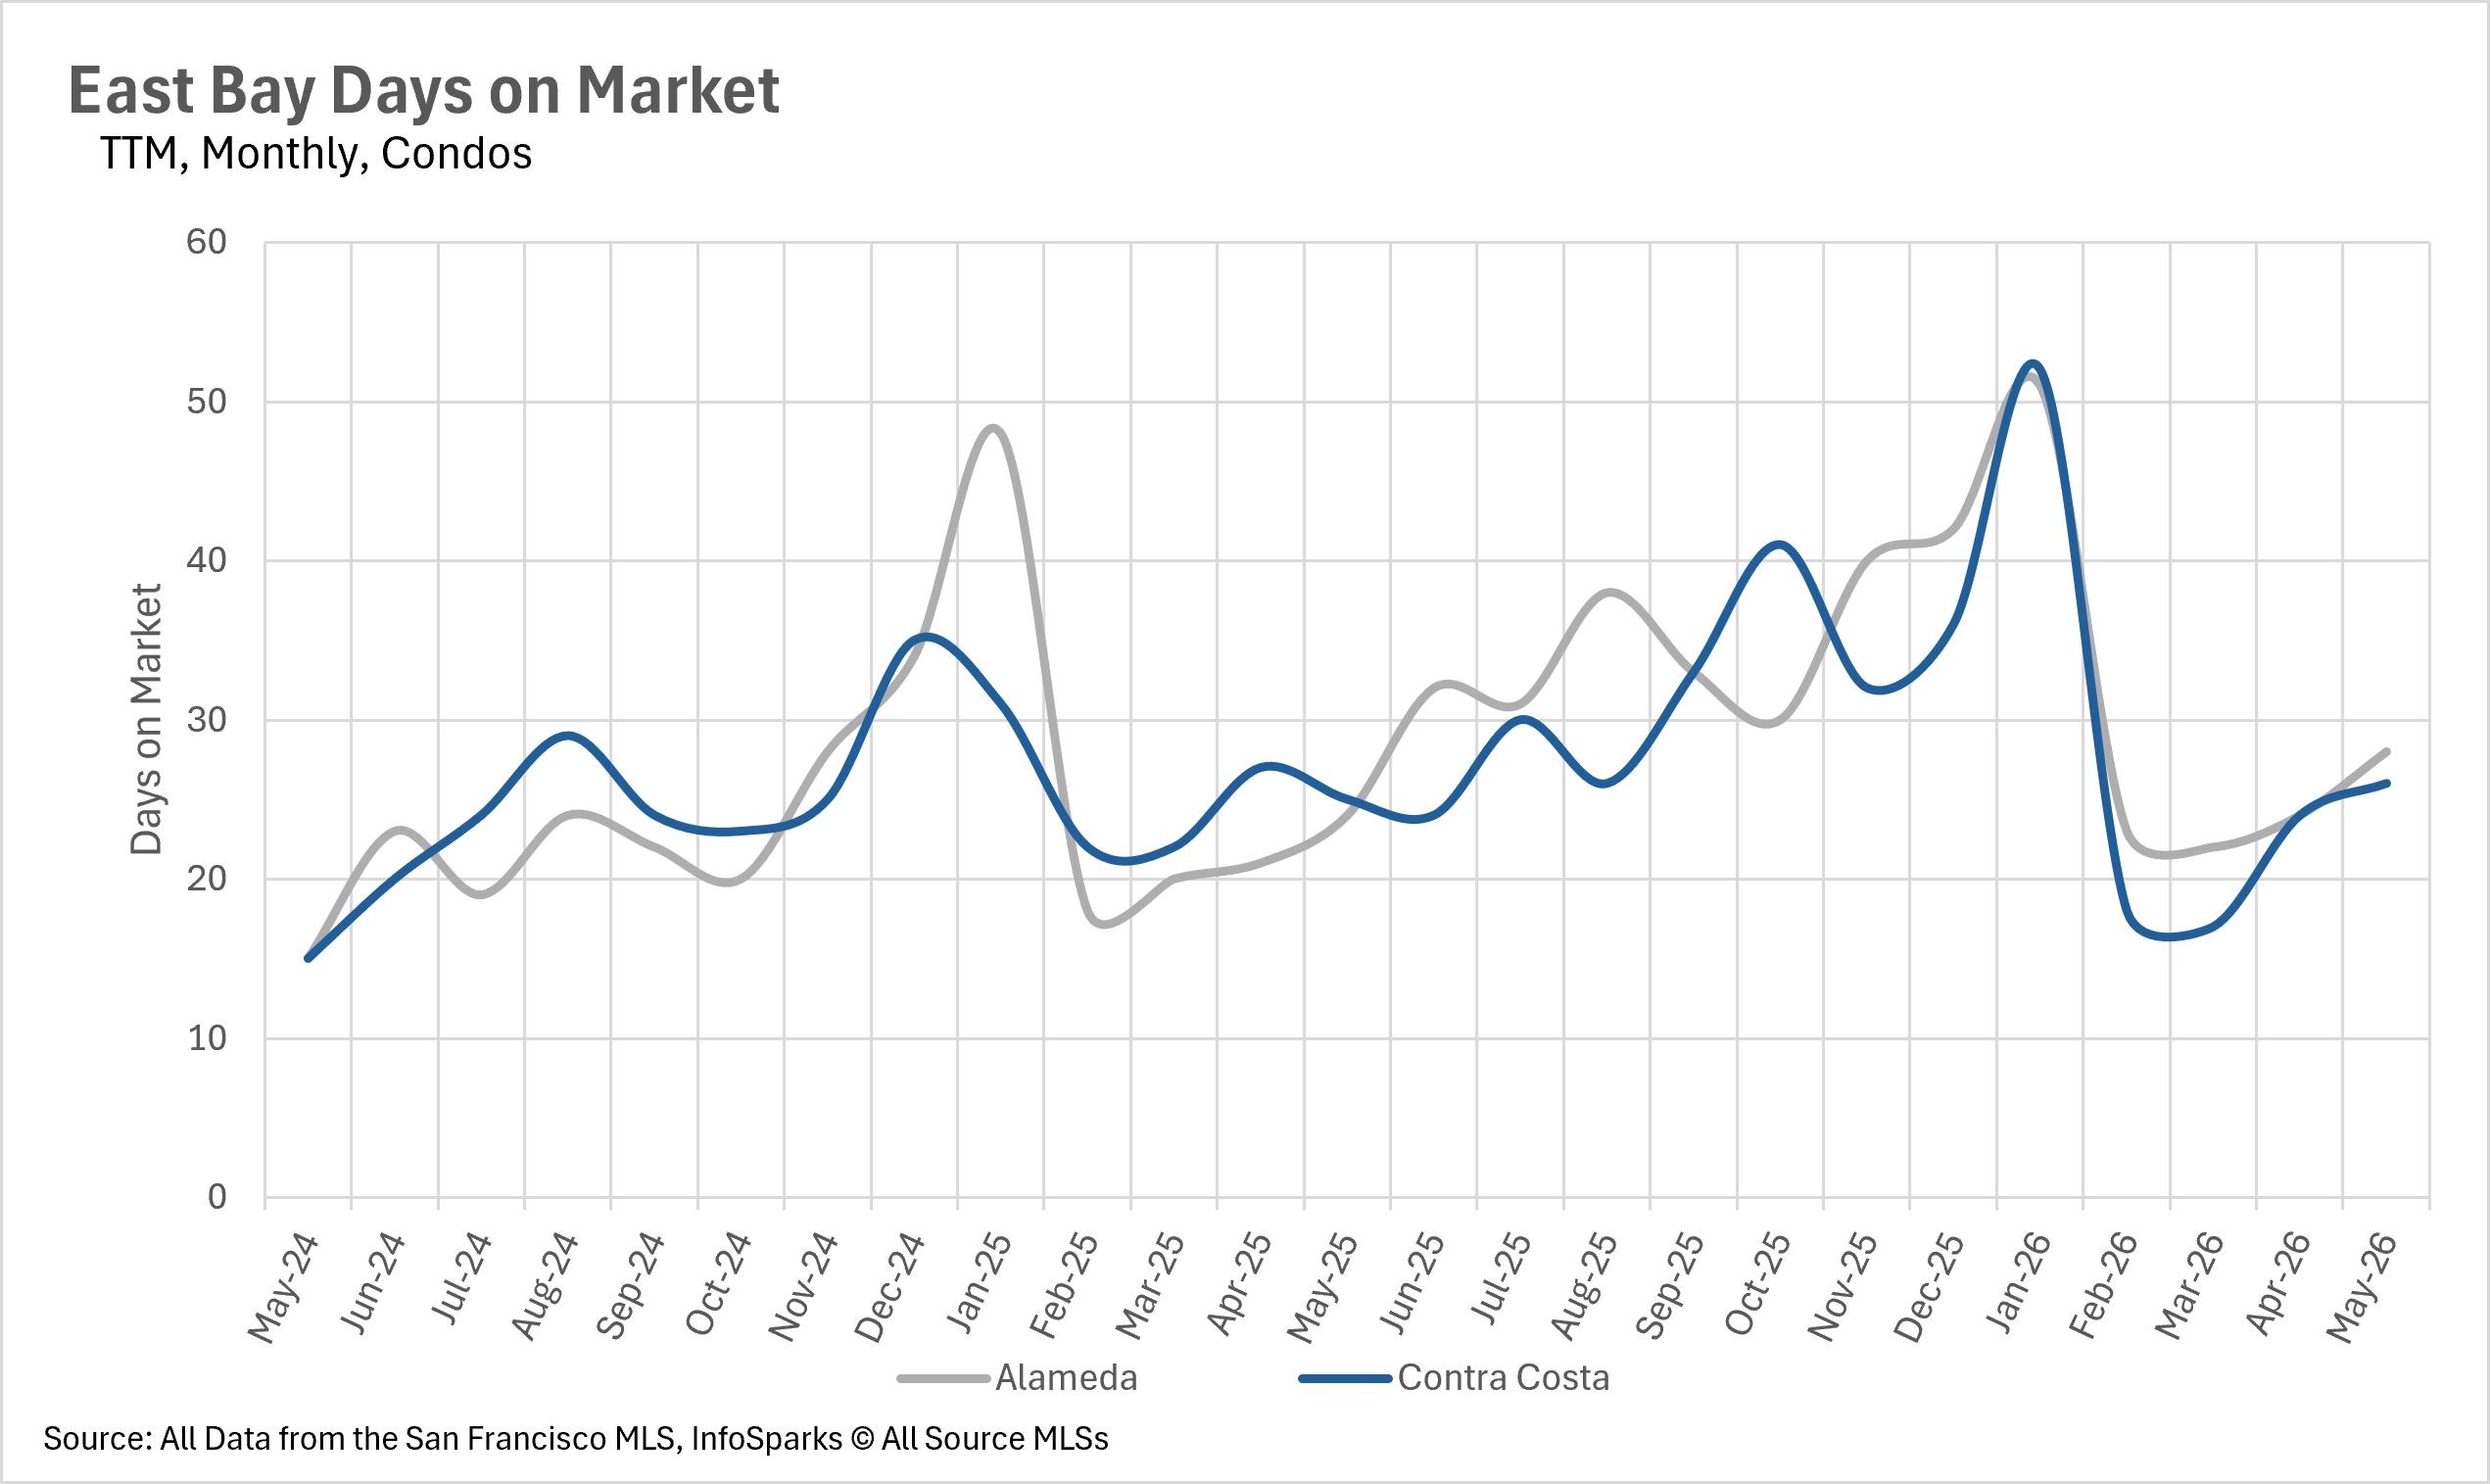
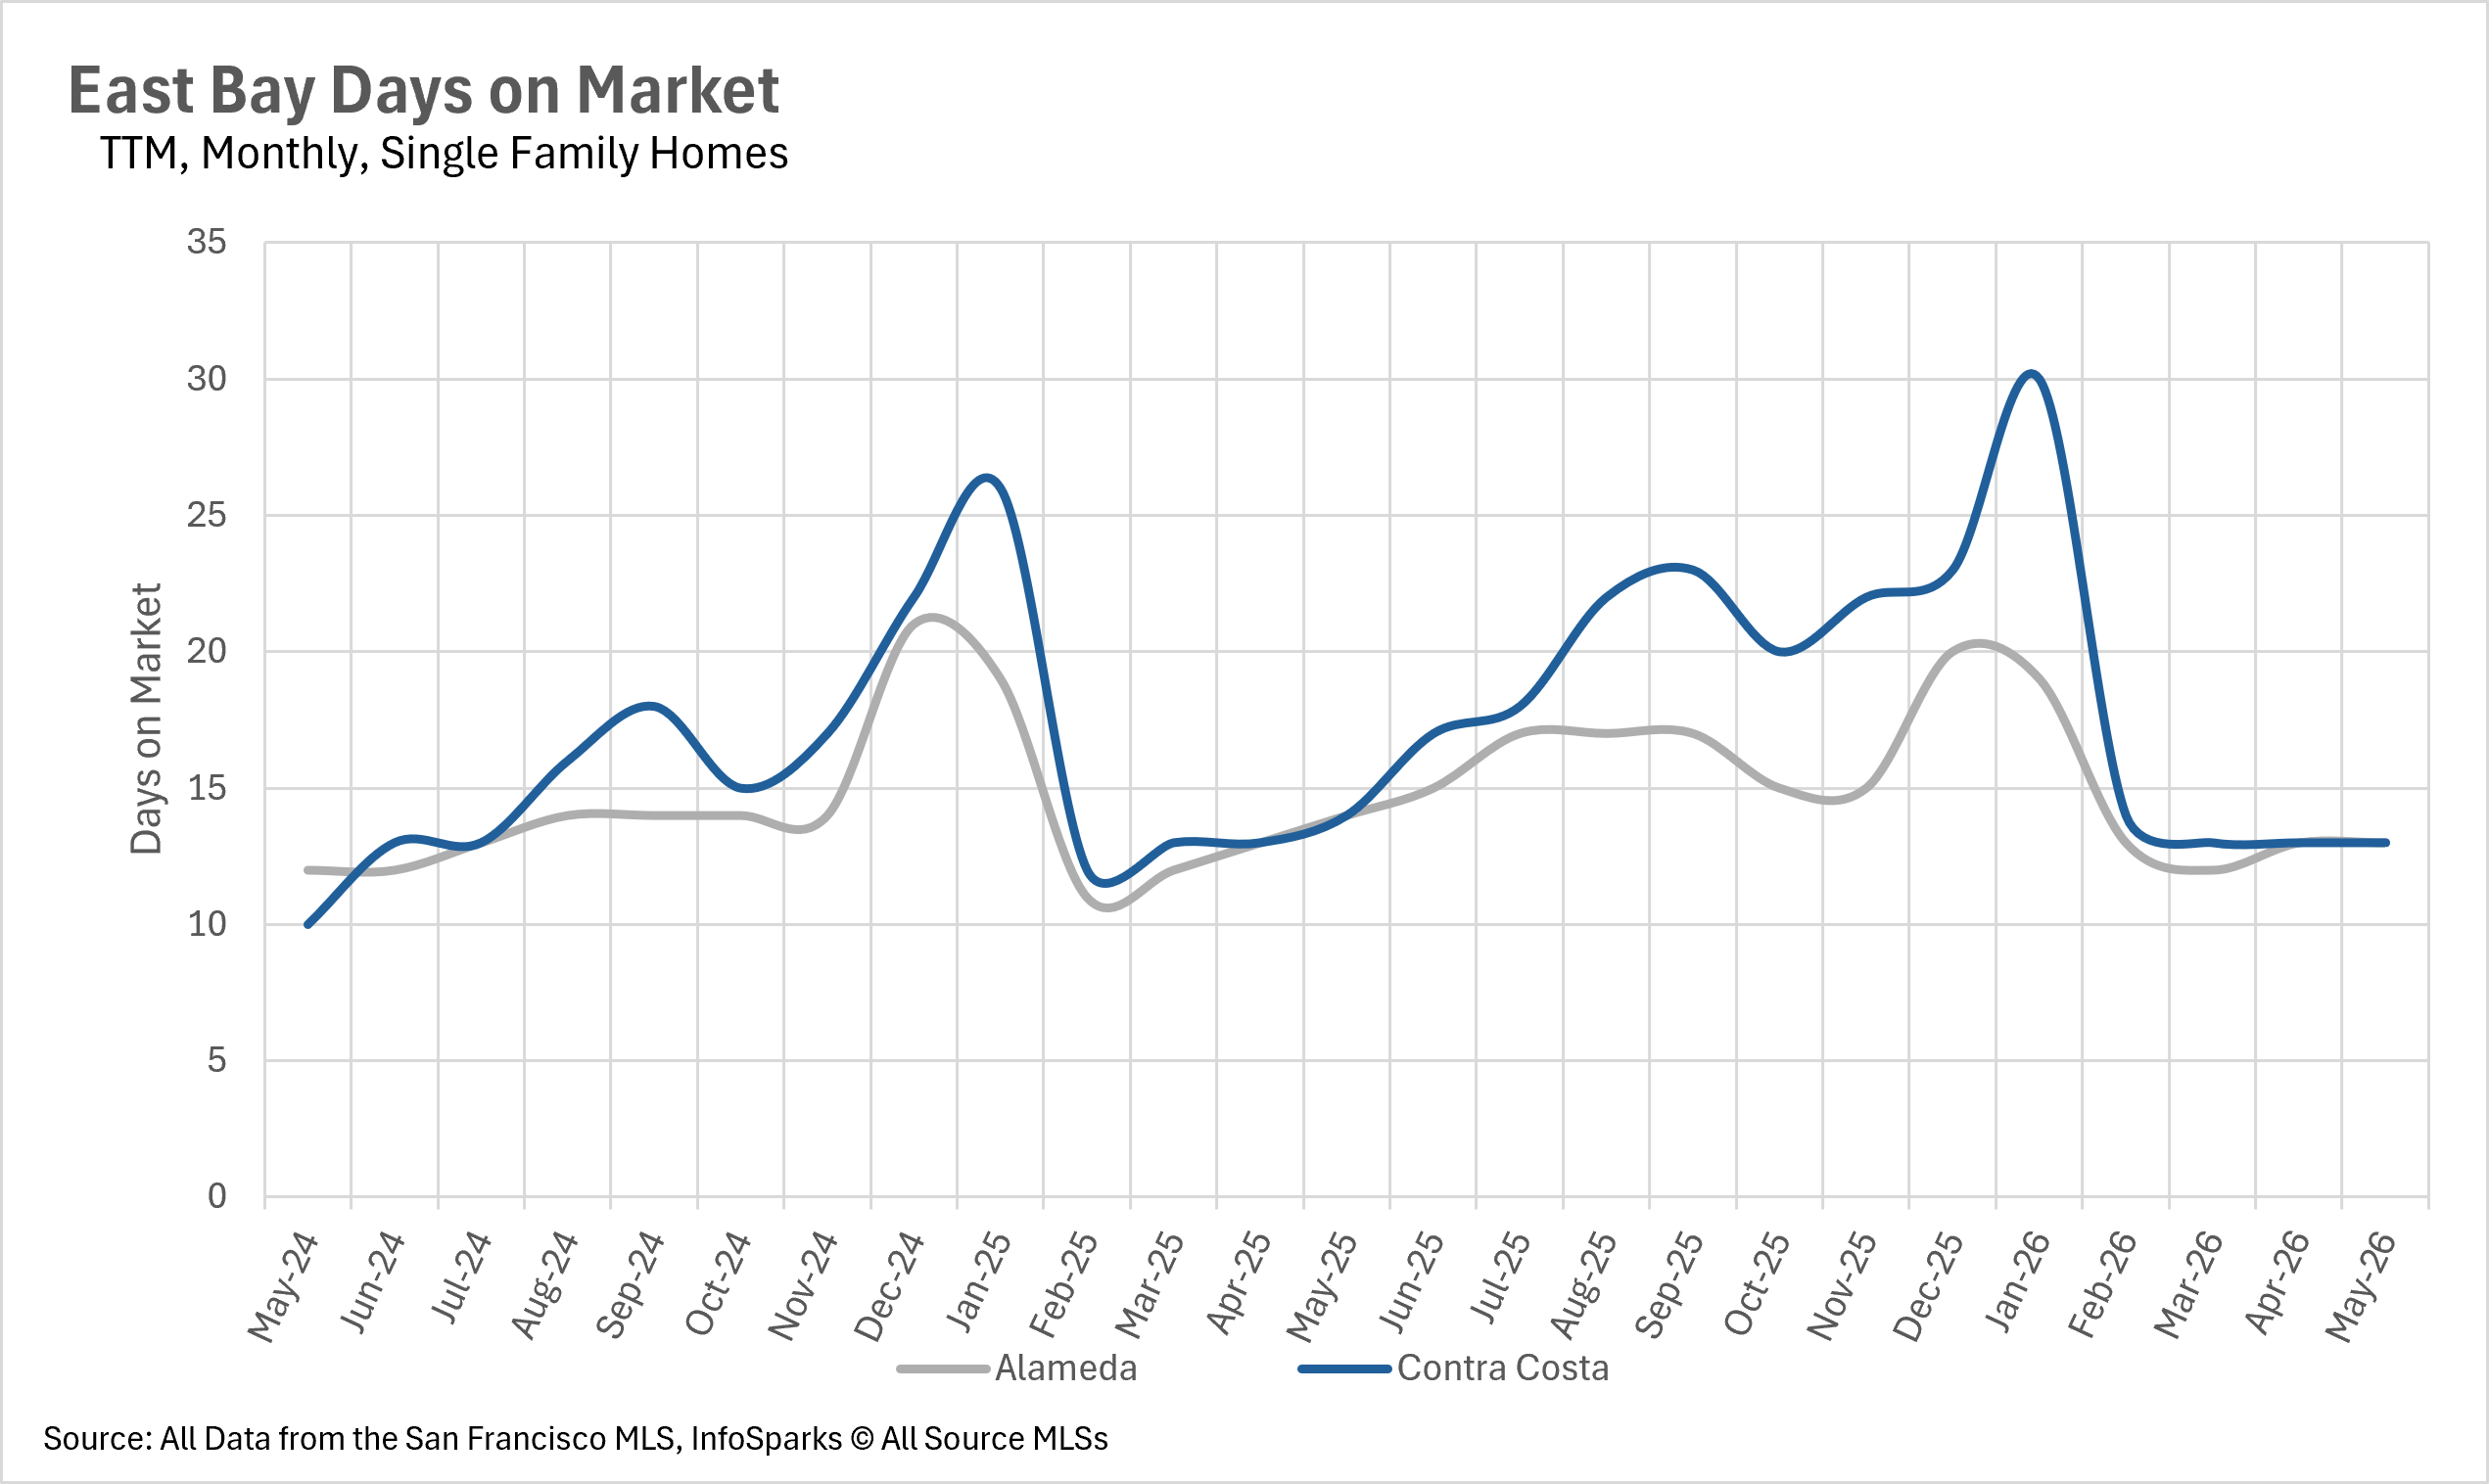
Line chart of monthly condo days on market in Alameda and Contra Costa counties, May 2024–May 2026.

Line chart of East Bay days on market, May 2024–May 2026; Contra Costa generally exceeds Alameda, with peaks in January.

Chart of monthly Silicon Valley median condo prices by county, May 2023–May 2026.

Line chart of monthly Silicon Valley single-family home prices in San Mateo, Santa Clara, and Santa Cruz counties, 2023–2026.

Bar chart comparing year-over-year condo median price changes in San Mateo, Santa Clara, and Santa Cruz counties.

Bar chart comparing year-over-year single-family home median price changes in San Mateo, Santa Clara, and Santa Cruz counties.

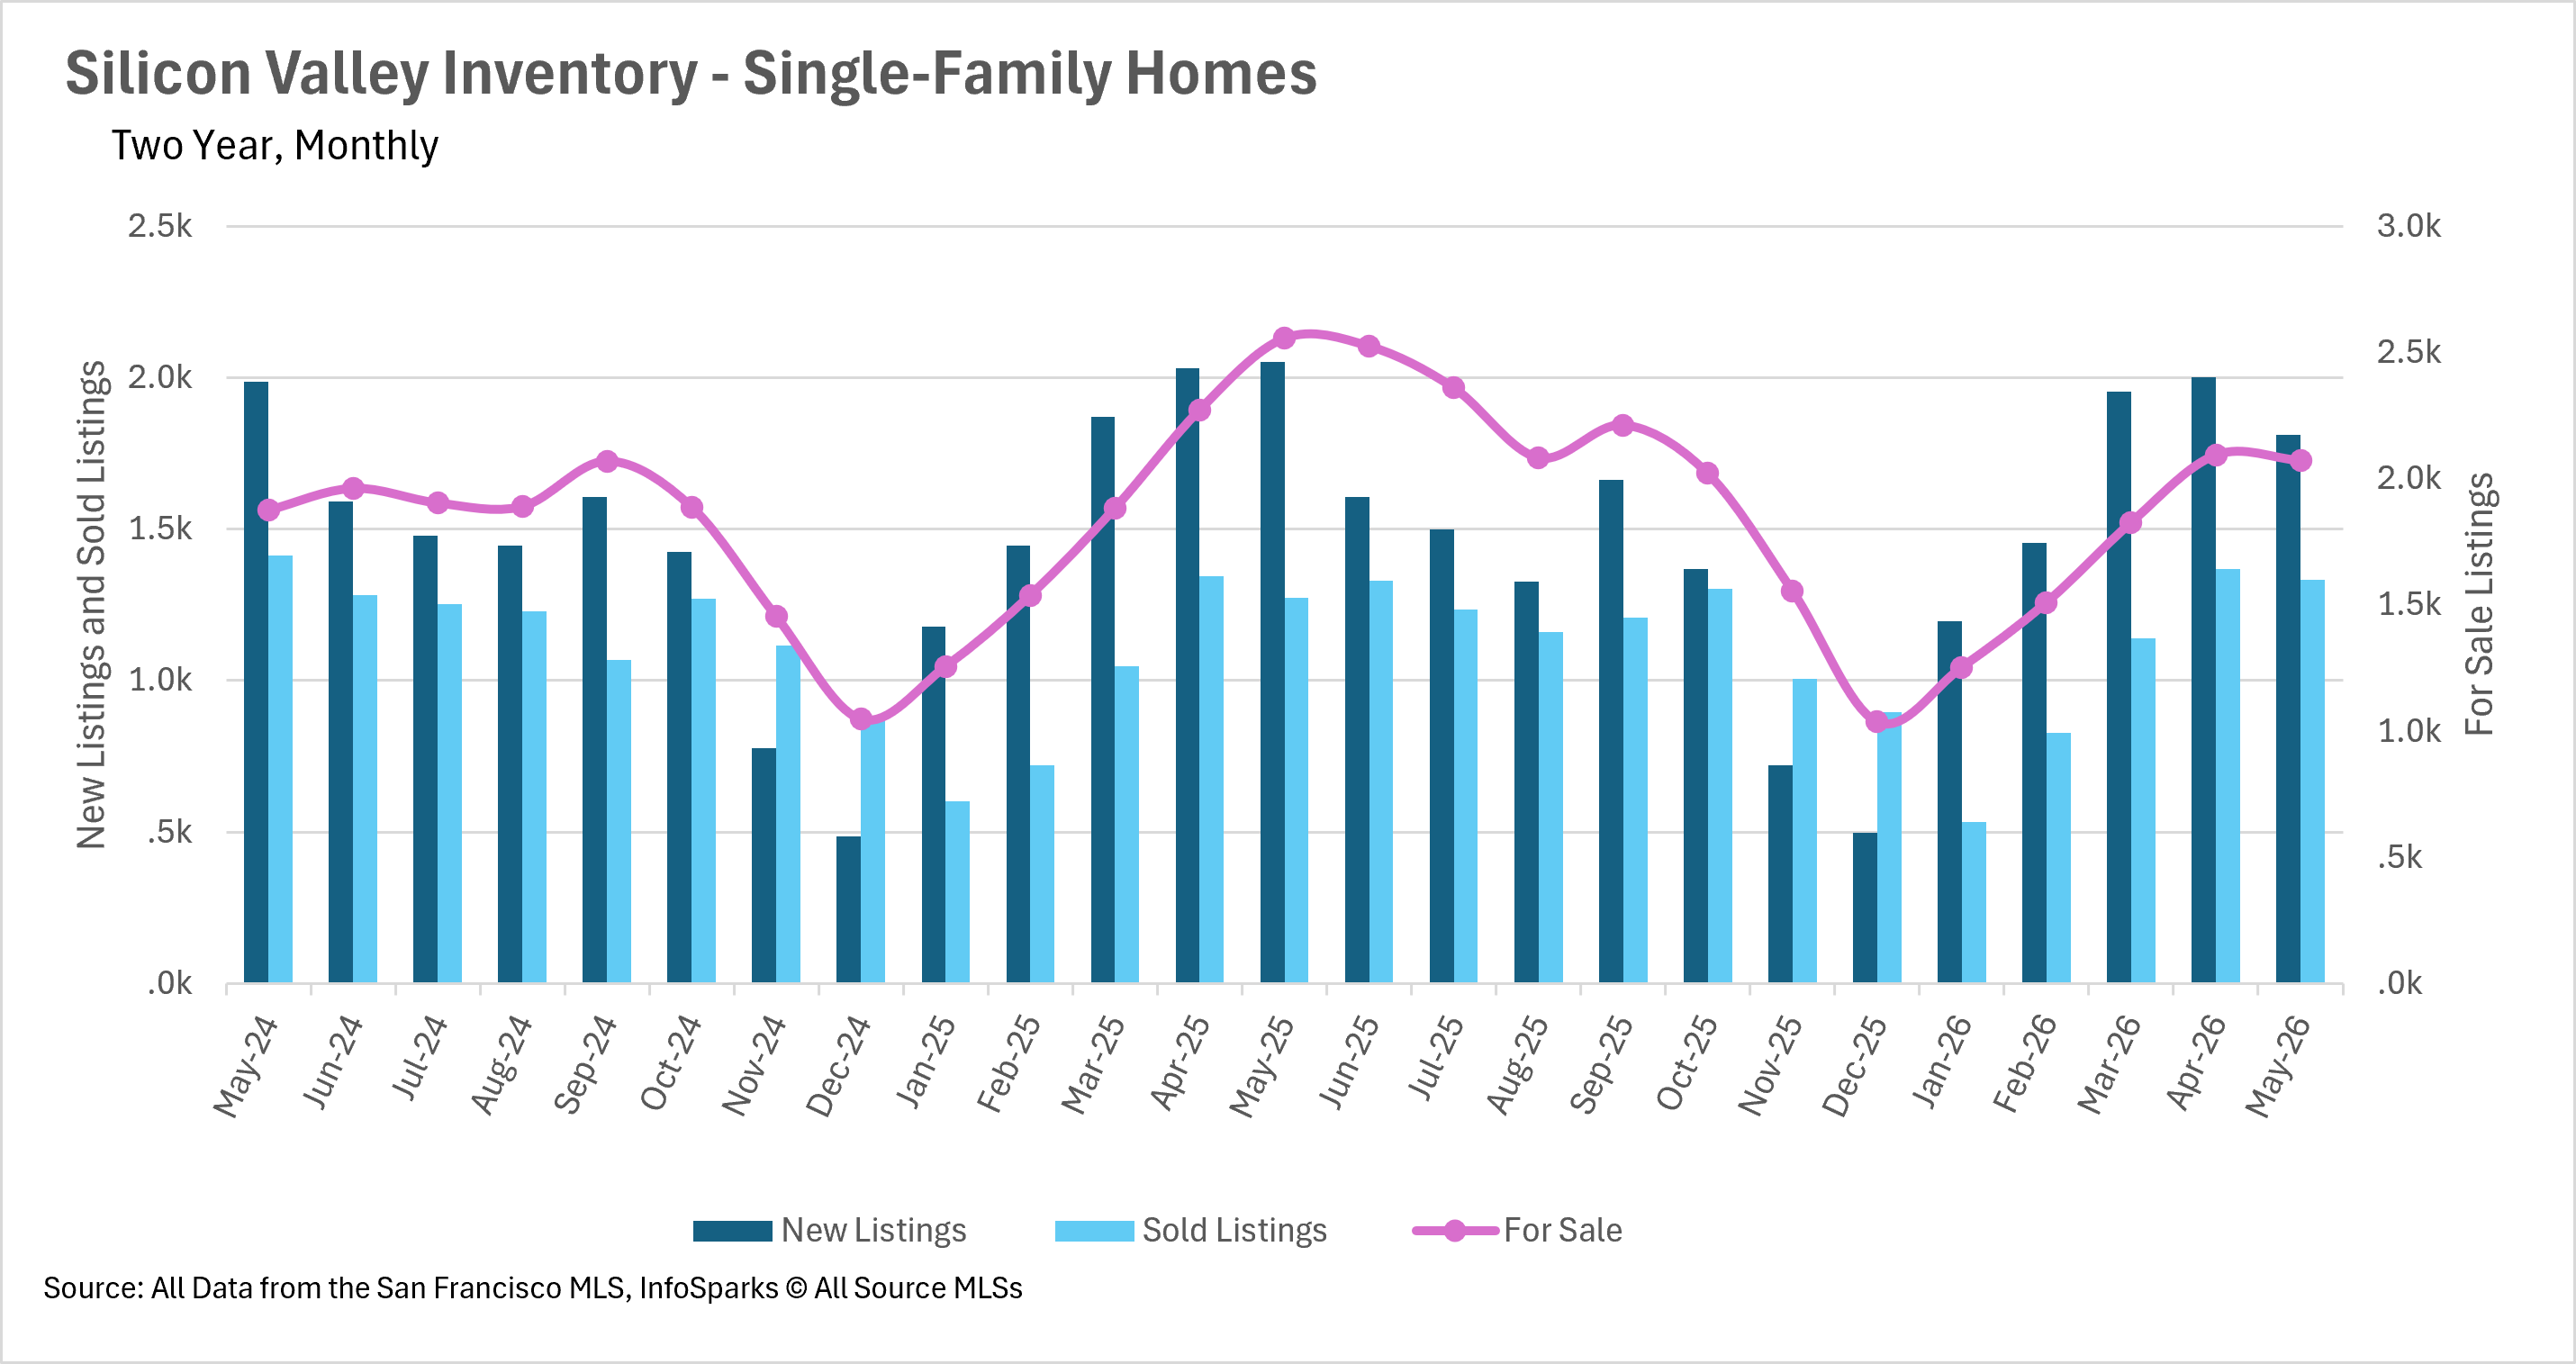
Chart of Silicon Valley single-family home listings, sales, and inventory from May 2024 through May 2026.

Line chart of monthly condo supply in San Mateo, Santa Clara, and Santa Cruz, May 2024–May 2026.

Line chart of Silicon Valley months of supply from May 2024 to May 2026 for San Mateo, Santa Clara, and Santa Cruz.

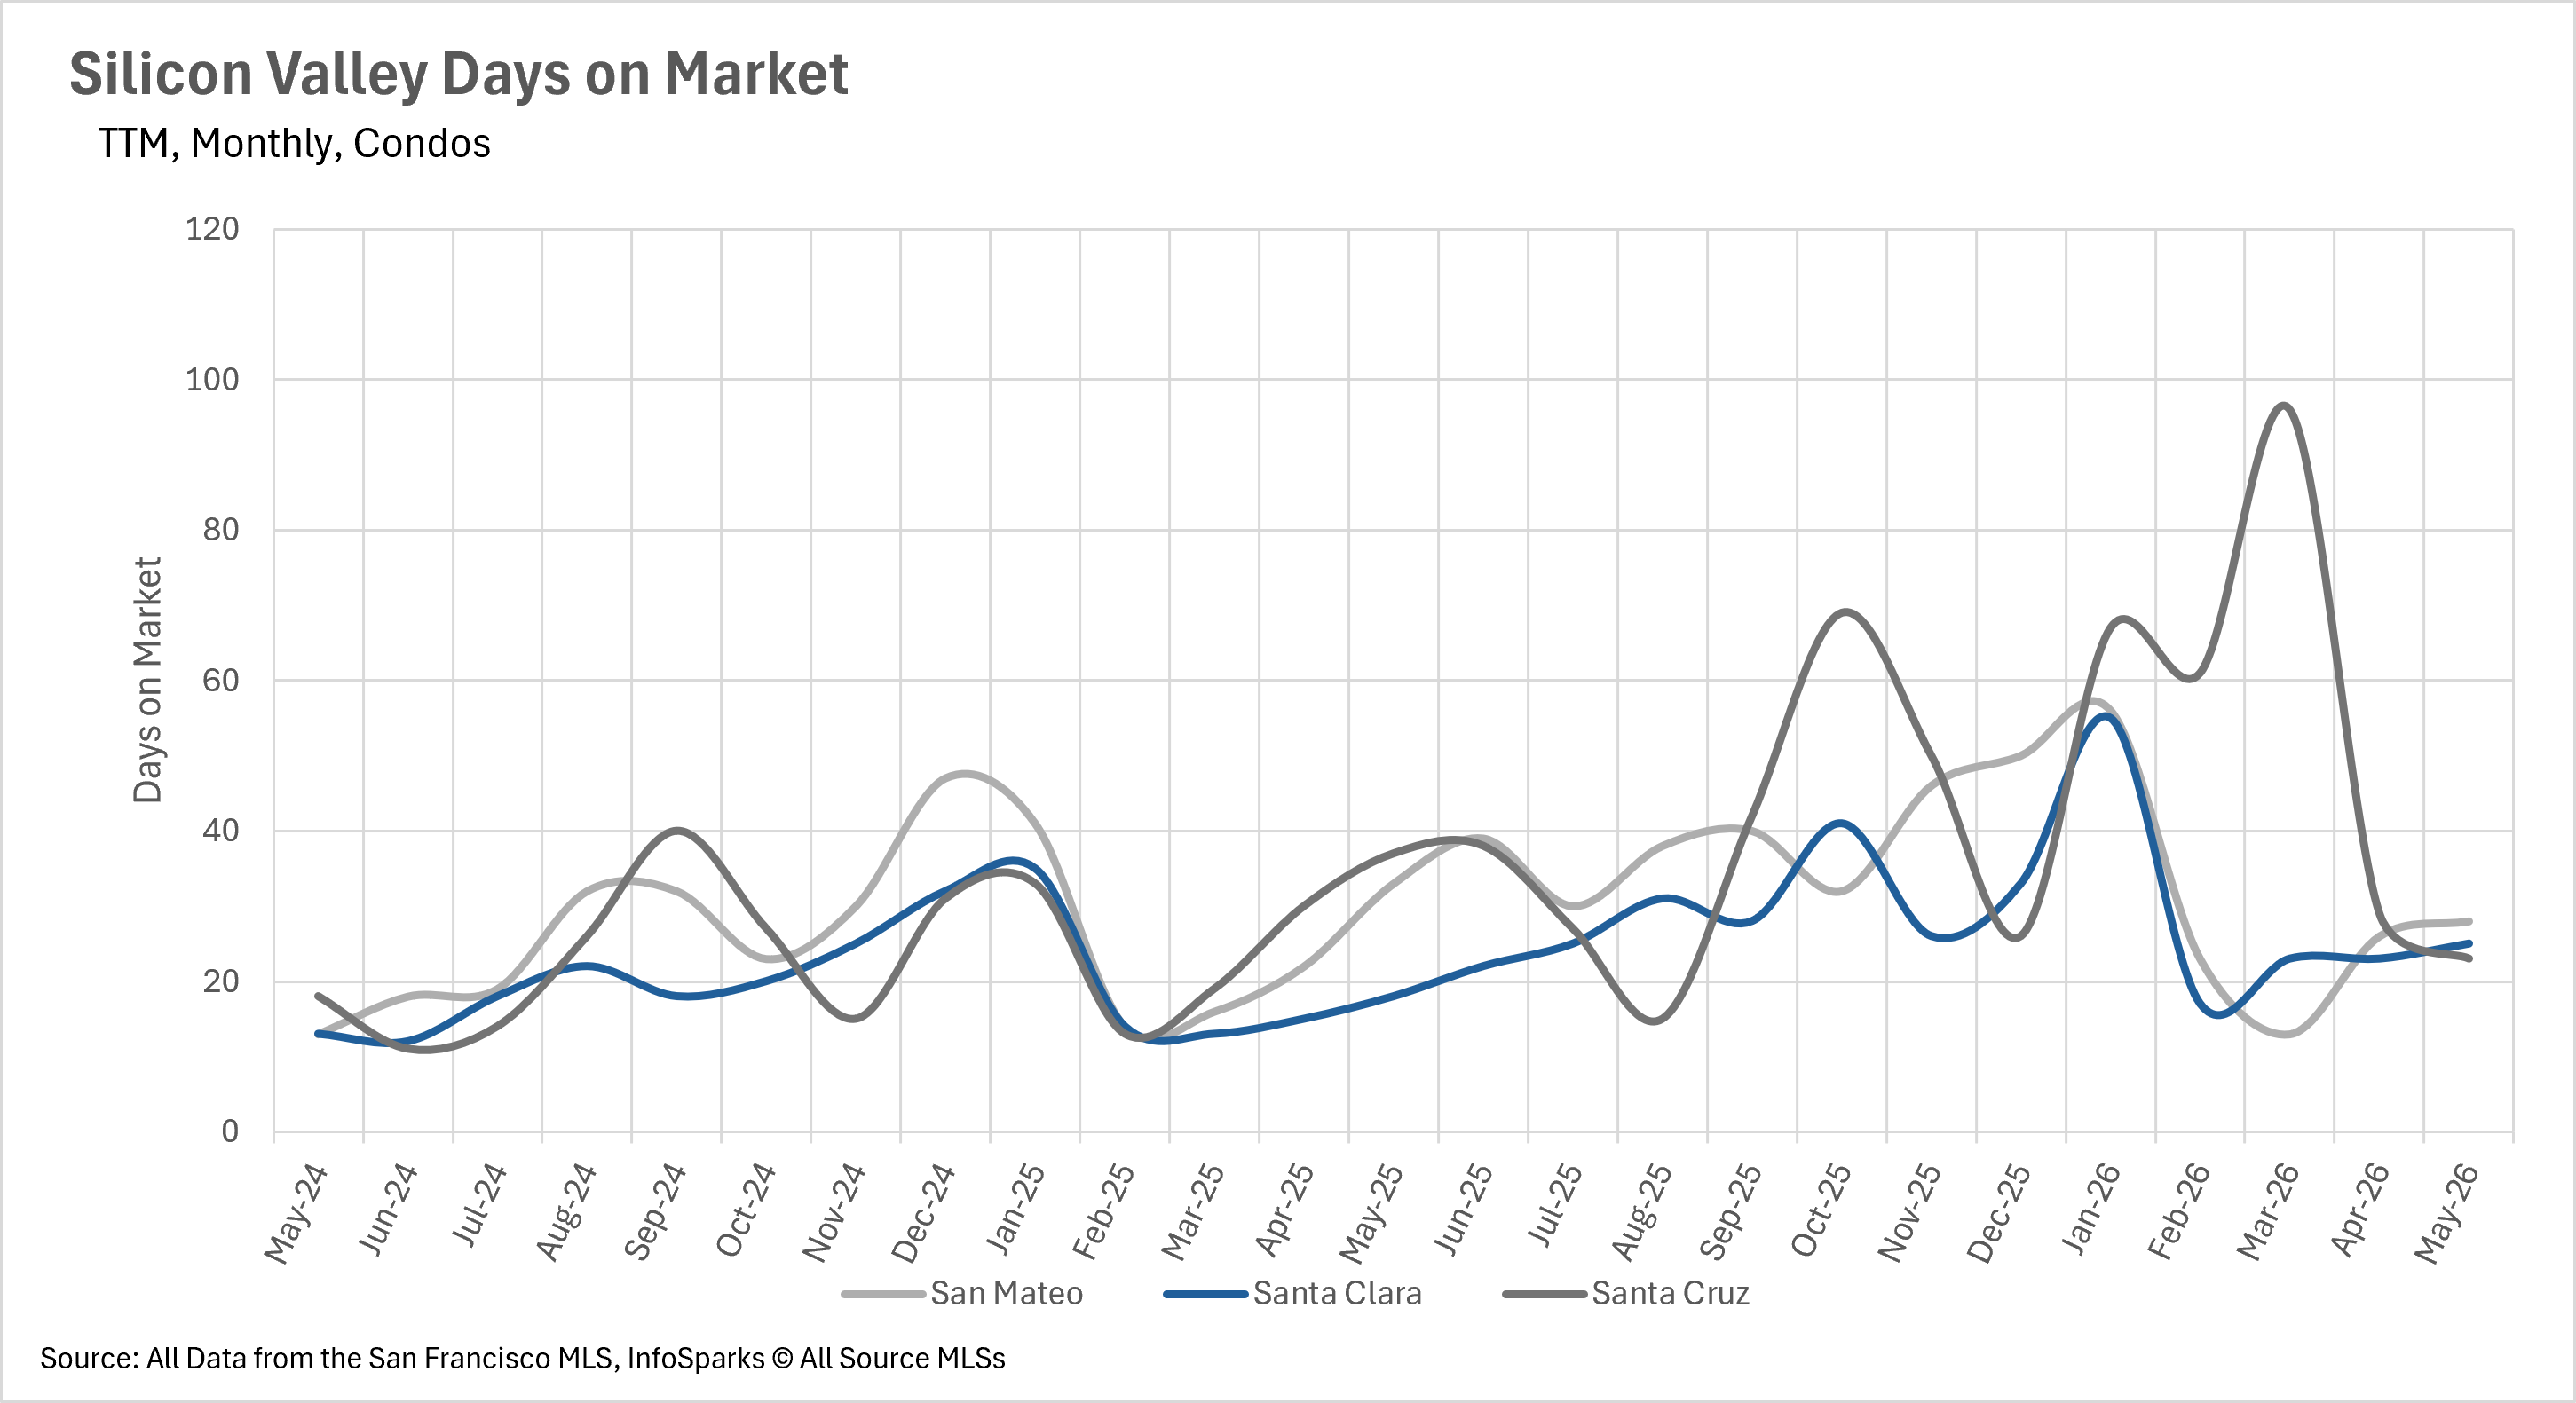
Monthly condo days on market in San Mateo, Santa Clara, and Santa Cruz, May 2024–May 2026.

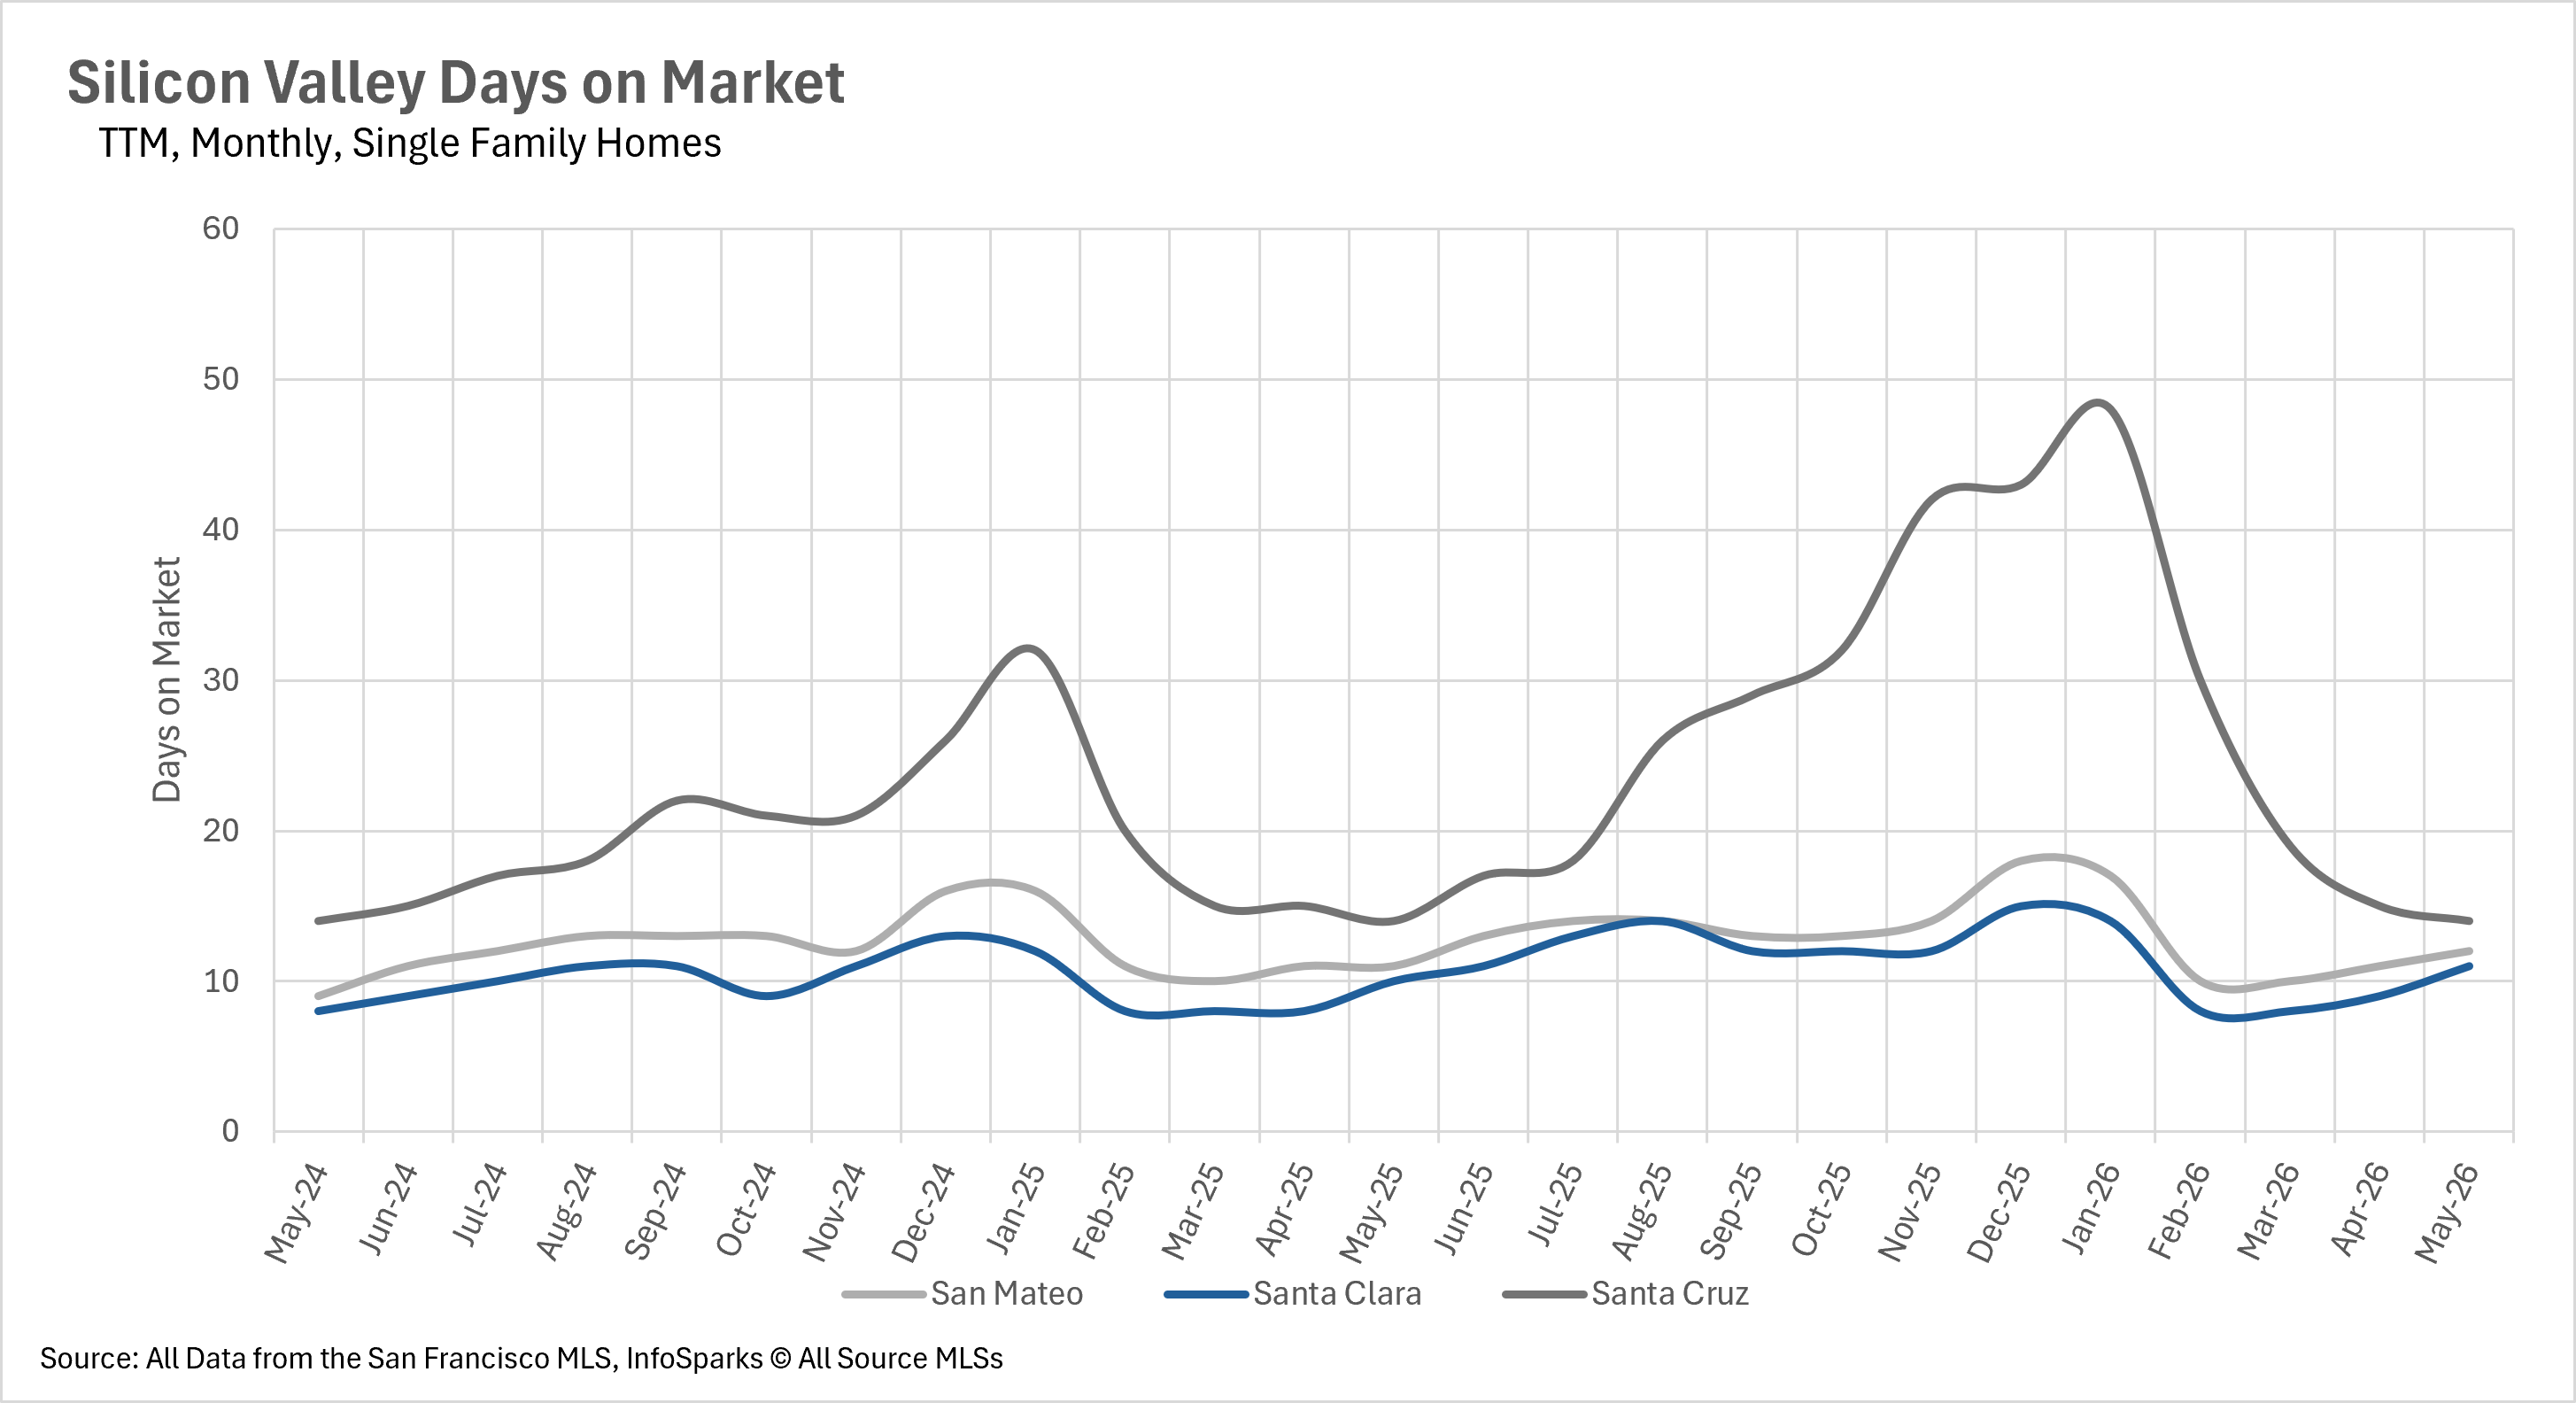
Line chart comparing monthly days on market for single-family homes in three Silicon Valley counties, May 2024–May 2026.

ActivePipe Message ID: 3892340

Let’s Talk

You’ve got questions and we can’t wait to answer them.